
 Japan Mammography Market | 2026-2036
Japan Mammography Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Mammography Market Foresight
Modular service bundling is restructuring how Japanese hospitals procure mammography systems, shifting capital purchases toward managed equipment contracts with maintenance and software upgrades embedded. Fujifilm Corporation leverages its domestic manufacturing footprint to anchor premium digital breast tomosynthesis installations in tier-one medical centers. Siemens Healthineers competes through AI-integrated workflow platforms that reduce radiologist reading times. Konica Minolta specializes in compact screening units designed for mobile breast examination vehicles serving rural Hokkaido and Tohoku.
Mammography denotes X-ray-based breast imaging using low-dose ionizing radiation, typically operating at 25–35 kVp with molybdenum or rhodium target-filter combinations to optimize soft-tissue contrast for detecting microcalcifications and masses. Full-field digital systems now dominate Japanese procurement, displacing residual analog installations as PMDA reimbursement favors higher-resolution screening outputs. Digital breast tomosynthesis represents the fastest-expanding technology segment, capturing margin pools from hospitals seeking differentiation in dense breast evaluation where conventional 2D mammography yields higher false-negative rates. Diagnostic centers constitute the most concentrated end-user channel, aggregating volume through centralized prefectural screening contracts.
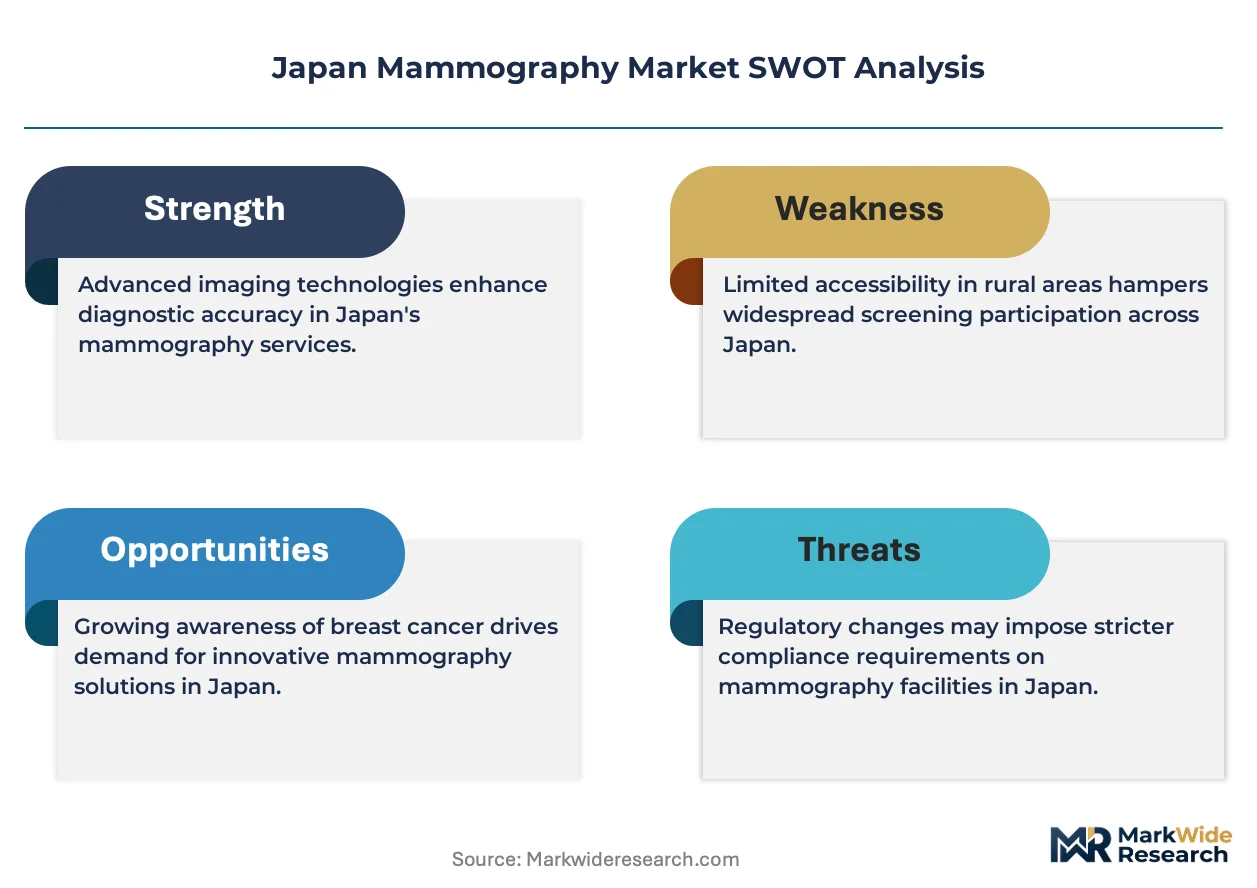
PMDA device approval pathways and Japan's Ministry of Health, Labour and Welfare screening guidelines jointly determine market access timelines and reimbursement levels for new mammography modalities. JIS standards for medical electrical equipment impose specific radiation dose limits and image quality thresholds that manufacturers must satisfy before commercial placement. METI's healthcare technology assessment frameworks increasingly weight cost-effectiveness data in procurement decisions for public hospital systems. Stakeholders must monitor how PMDA's evolving software-as-a-medical-device regulations affect AI diagnostic algorithms bundled with imaging hardware.
Market Dynamics
PMDA's tightening quality benchmarks for diagnostic imaging are compressing approval timelines while elevating technical barriers, forcing equipment vendors to front-load R&D spending and accelerating consolidation among domestic distributors serving metropolitan hospital networks.
Growth Catalysts
- Tokyo-Osaka screening expansion:Metropolitan hospitals are enlarging mammography programs to serve aging prefectural populations, concentrating procurement volume in urban corridors with established radiology infrastructure.
- PMDA reimbursement favoring high-resolution outputs:The regulator's preference for superior screening resolution is channeling capital toward full-field digital systems and away from residual analog installations.
- Digital breast tomosynthesis:This technology addresses false-negative rates in dense breast tissue evaluation, creating clinical differentiation that commands premium placement in tier-one medical centers.
Market Restraints
- Capital intensity of equipment refresh cycles:Municipal hospital systems face constrained budgets that extend replacement timelines beyond optimal technical lifespans, deferring revenue for manufacturers.
- Geographic demand concentration:Procurement aggregates in Tokyo, Osaka, and Aichi prefectures, leaving peripheral regions with limited installed base and sparse service infrastructure.
- Radiologist workforce scarcity:Japan's specialist shortage limits throughput expansion even where equipment capacity exists, capping utilization rates in screening programs.
Strategic Opportunities
- Rural Hokkaido and Tohoku mobile screening:Compact systems designed for examination vehicles can capture underserved populations outside metropolitan corridors where fixed-site infrastructure remains uneconomical.
- AI-integrated workflow platforms:Convergence of machine learning algorithms with imaging hardware offers path to reduce radiologist reading burden and accelerate diagnostic throughput.
- METI healthcare technology assessment frameworks:Cost-effectiveness weighting in public hospital procurement creates opening for vendors with robust health economics documentation.
Industry Challenges
- PMDA software-as-a-medical-device compliance:Evolving regulations for AI diagnostic algorithms bundled with hardware extend certification timelines and require ongoing regulatory surveillance.
- Legacy system integration complexity:Hospital IT environments with heterogeneous PACS architectures demand customized connectivity solutions that strain implementation resources.
- JIS radiation dose limit adherence:Manufacturers must satisfy specific medical electrical equipment thresholds that constrain design flexibility and elevate testing costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Mammography Market |
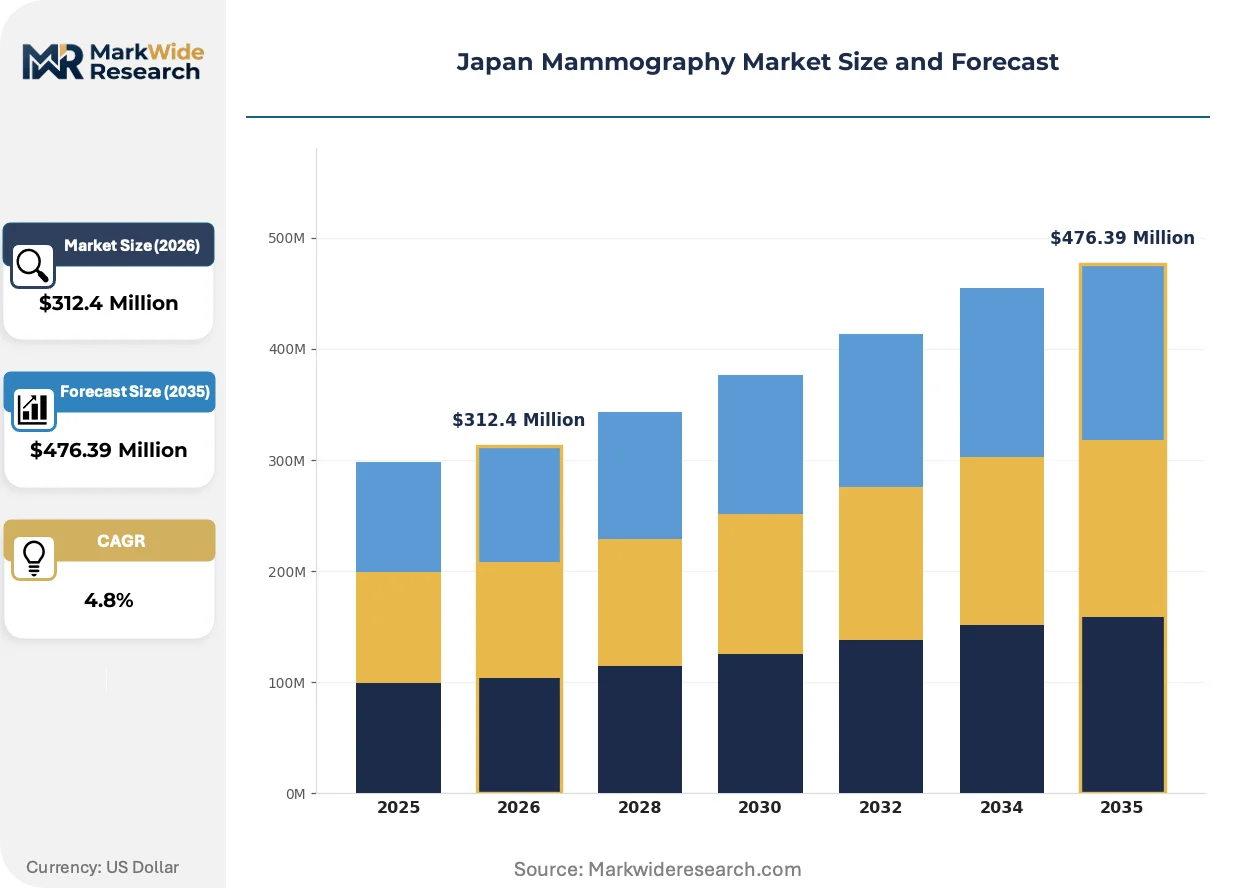
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $476.39 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full-Field Digital, Screen-Film, Digital Breast Tomosynthesis, Analog Technology: X-Ray, MRI, Ultrasound, 3D Imaging End User: Hospitals, Diagnostic Centers, Research Institutions, Private Clinics Application: Screening, Diagnosis, Research, Treatment Planning |
| Companies Covered | Siemens Healthineers, Koninklijke Philips NV, Fujifilm Corporation, Konica Minolta, Toshiba Corporation, Hologic Inc, Canon Medical Systems Corporation, Carestream Health, GE Healthcare, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Mammography Market Shifts & Advancements
Japanese mammography is undergoing modality substitution and procurement restructuring simultaneously, with technology vendors racing to embed intelligent workflows while hospitals reconsider ownership models for capital equipment.
Digital breast tomosynthesis is overtaking conventional 2D mammography in new installations at tier-one medical centers. Diagnostic radiology departments in Tokyo and Osaka are prioritizing three-dimensional tissue acquisition to reduce callback rates from dense breast examinations. This modality shift is compressing margin pools for manufacturers of standard digital systems while elevating service contract values for tomosynthesis-enabled platforms.
PMDA's evolving software-as-a-medical-device regulations are reclassifying AI diagnostic algorithms that previously shipped as hardware accessories. Manufacturers must now submit standalone clinical validation packages for machine learning components integrated into mammography workstations. Tier-one medical centers with established regulatory affairs capabilities are absorbing these compliance costs faster than municipal hospital systems, creating a two-speed adoption pattern across prefectural screening contracts.
Managed equipment contracts with embedded maintenance and software upgrades are displacing traditional capital purchase arrangements in metropolitan hospital networks. Tokyo-based diagnostic centers are negotiating multi-year service agreements that transfer obsolescence risk to vendors while preserving operational budget flexibility. This shift is most pronounced in prefectural screening programs where centralized procurement offices prioritize total cost of ownership over upfront capital expenditure metrics.
Japan Mammography Market Segmentation
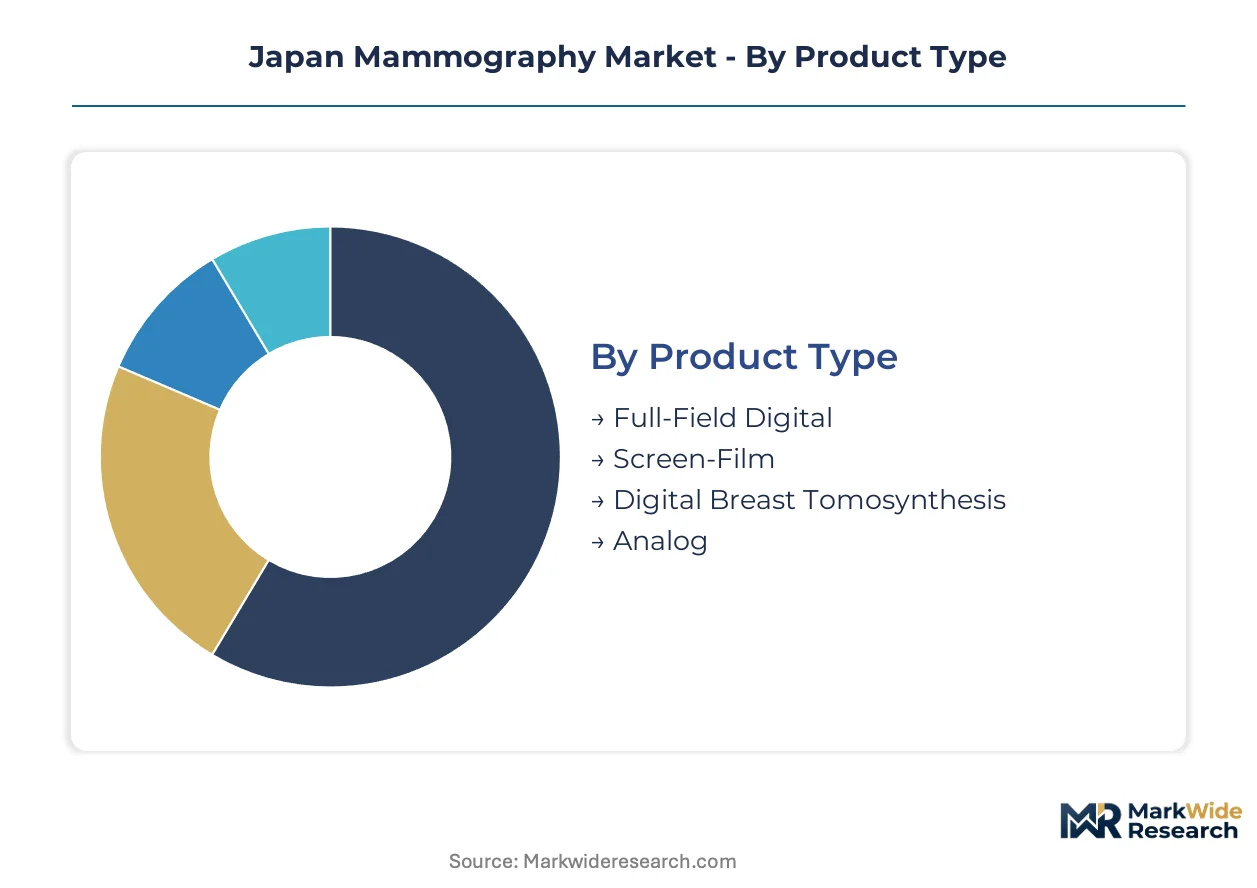
Segmentation in the Japan Mammography Market reveals how procurement priorities diverge between high-throughput urban screening networks and resource-constrained rural facilities. Understanding these divides helps vendors align product configurations with specific prefectural reimbursement structures and clinical workflows.
Product Type:
Standardization dominates at the screening tier while customization concentrates in diagnostic centers seeking differentiation through advanced imaging capabilities.
- Full-Field Digital:These systems capture entire breast volumes in single exposures using flat-panel detectors with 50-100 micron pixel pitch. Tokyo and Osaka prefectural screening contracts prioritize this modality for throughput efficiency in high-volume metropolitan programs.
- Digital Breast Tomosynthesis:Multi-angle X-ray acquisition reconstructs three-dimensional breast architecture to reduce tissue overlap artifacts. Tier-one medical centers in Aichi and Kanagawa prefectures deploy this technology to address callback rates in dense breast populations.
- Screen-Film:Analog chemical processing persists in legacy municipal installations with extended depreciation schedules. Hokkaido and Tohoku rural clinics maintain residual units where capital replacement remains fiscally constrained.
- Analog:Obsolete electromechanical systems with film-screen combinations occupy shrinking installed base. Limited service infrastructure and PMDA reimbursement compression accelerate phase-out timelines.
Most installed capacity flows through Full-Field Digital systems. Expansion is steepest in Digital Breast Tomosynthesis.
Technology:
Cost tier stratification separates premium multi-modality platforms from single-technology screening workhorses across Japanese procurement channels.
- X-Ray:Ionizing radiation at 25-35 kVp with molybdenum-rhodium target-filter combinations delivers optimized soft-tissue contrast for microcalcification detection. Prefectural screening programs standardize on this foundation technology for population-scale deployment.
- 3D Imaging:Tomosynthetic reconstruction algorithms generate depth-resolved slice data at 1mm intervals through compressed breast thickness. Academic medical centers in Kyoto and Fukuoka integrate these platforms with AI-assisted reading workstations.
- Ultrasound:Non-ionizing mechanical wave imaging complements mammography in dense breast evaluation and biopsy guidance. Private breast clinics in urban corridors deploy handheld systems for supplemental diagnostic protocols.
- MRI:Magnetic resonance with dedicated breast coils enables contrast-enhanced lesion characterization for high-risk surveillance. National Cancer Center-designated hospitals reserve this technology for staging and neoadjuvant response monitoring.
X-Ray technology anchors procurement volume across municipal contracts. 3D Imaging commands the steepest expansion trajectory in private hospital networks.
End User:
Customer type determines service contract structure, with centralized prefectural purchasers demanding different support models than dispersed private operators.
- Diagnostic Centers:Specialized breast imaging facilities aggregate screening volume through prefectural government contracts. Tokyo and Osaka metropolitan networks negotiate multi-year managed equipment agreements with embedded maintenance and software upgrade provisions.
- Hospitals:Integrated acute care systems combine mammography with surgical oncology and radiation therapy services. National hospital organizations and university-affiliated medical centers in Nagoya and Sapporo prioritize PACS connectivity and EMR integration capabilities.
- Private Clinics:Independent physician practices serve affluent urban populations with concierge screening models. Minato and Shibuya ward facilities emphasize appointment accessibility and rapid result turnaround.
- Research Institutions:Academic medical centers and national research institutes conduct imaging biomarker validation and AI algorithm development. Tsukuba and Kobe biomedical clusters require research-use licensing and data export flexibility.
Most installed capacity flows through Diagnostic Centers. Expansion is steepest in Hospital networks upgrading to tomosynthesis-enabled platforms.
Application:
Volume concentration in asymptomatic screening creates procurement scale that diagnostic and interventional applications cannot replicate.
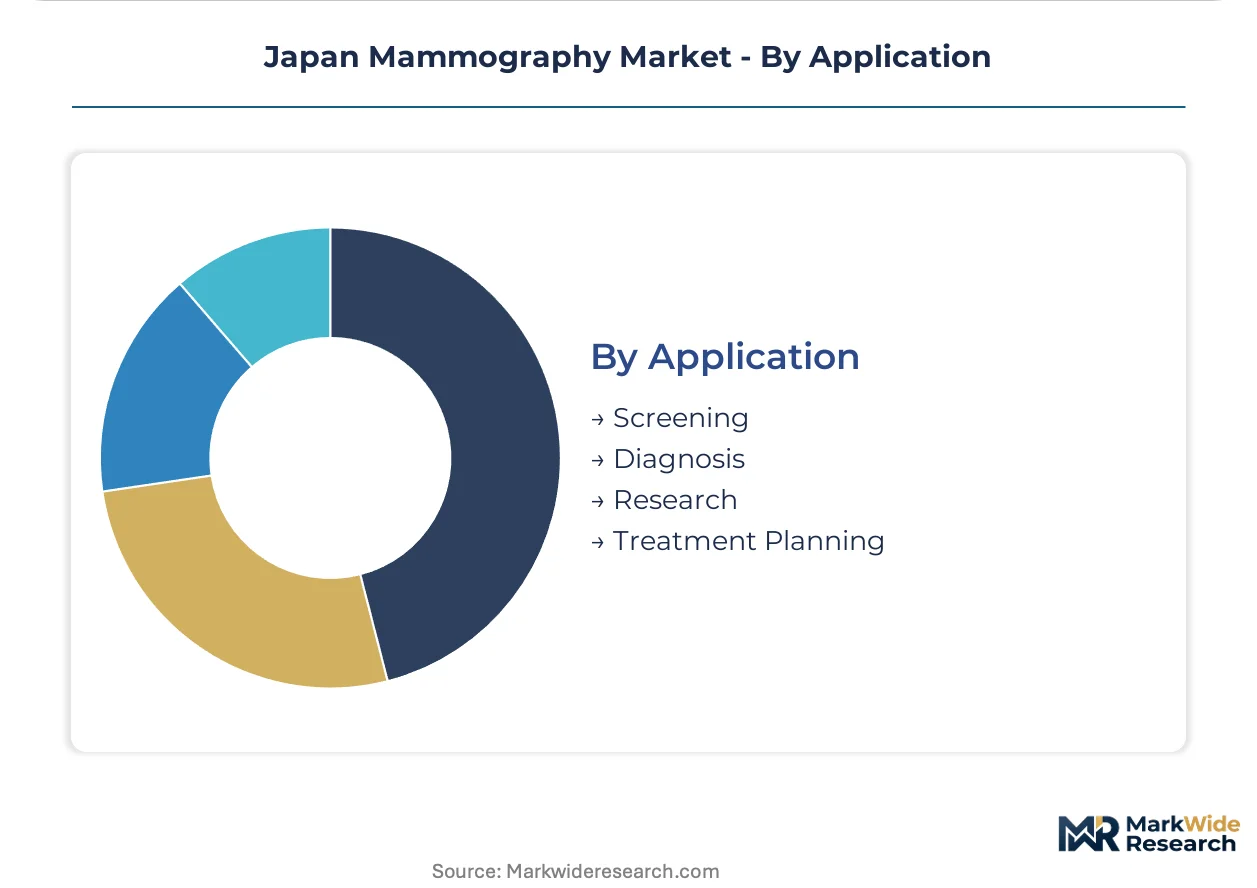
- Screening:Systematic asymptomatic population examination targets women aged 40-74 under Ministry of Health, Labour and Welfare guidelines. Prefectural governments tender centralized contracts covering millions of eligible residents in Tokyo, Kanagawa, and Osaka prefectures.
- Diagnosis:Symptomatic evaluation and callback assessment following abnormal screening results demands higher spatial resolution and biopsy guidance integration. Cancer center hospitals in Fukuoka and Hiroshima configure workstations with stereotactic and vacuum-assisted biopsy capabilities.
- Treatment Planning:Preoperative lesion localization and neoadjuvant chemotherapy response monitoring guides surgical and medical oncology decisions. Breast cancer specialty hospitals coordinate imaging with multidisciplinary tumor boards.
- Research:Imaging biomarker qualification and AI training dataset generation occurs at designated national research hospitals. Regulatory approval pathways for novel algorithms require prospective validation cohorts.
Screening applications dominate procurement volume through prefectural tenders. Treatment Planning exhibits the steepest expansion as neoadjuvant protocols proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's mammography industry traces its modern foundations to postwar radiology equipment manufacturing in Tokyo and Osaka, where domestic imaging technology scaled through Ministry of Health, Labour and Welfare screening program expansions beginning in the 1990s.
Kanto/Tokyo
Metropolitan screening networks in Tokyo and Kanagawa prefectures drive procurement volume through centralized prefectural tenders serving aging populations. PMDA reimbursement structures favor high-resolution digital outputs in these dense urban corridors. The Tokyo Bay medical cluster anchors diagnostic center consolidation with multi-year managed equipment contracts replacing capital purchases.
Kansai/Osaka
Osaka and Kyoto prefectures concentrate tier-one medical center demand for digital breast tomosynthesis systems addressing dense breast evaluation. Japan's Ministry of Health, Labour and Welfare screening guidelines shape procurement specifications across Keihanshin metropolitan networks. Academic medical centers in Suita and Sakai integrate AI-assisted reading workstations with three-dimensional imaging platforms.
Chubu/Nagoya
Aichi prefecture's automotive industry heritage supports precision manufacturing capabilities feeding medical device component supply chains. METI healthcare technology assessment frameworks weight cost-effectiveness data in Nagoya municipal hospital procurement decisions. The Chukyo industrial corridor hosts diagnostic centers negotiating embedded maintenance provisions in equipment service agreements.
Hokkaido
Rural population dispersion across Hokkaido prefecture sustains demand for compact mammography systems deployable in mobile examination vehicles. JIS standards for medical electrical equipment govern radiation dose limits for screening units operating in remote municipalities. Sapporo-based diagnostic networks coordinate centralized reading services for peripheral clinic imaging submissions.
Tohoku
Post-disaster healthcare infrastructure rebuilding in Miyagi and Fukushima prefectures incorporated modernized screening equipment through supplementary budget allocations. PMDA quality benchmarks for diagnostic imaging accelerated replacement of legacy analog installations in Sendai metropolitan hospitals. Regional medical associations coordinate mobile screening routes reaching coastal communities with limited fixed-site radiology capacity.
Japan Mammography Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology integration and service bundling dimensions, with tomosynthesis-enabled platforms commanding pricing separation from standard digital systems. Domestic manufacturers leverage proximity to metropolitan hospital networks for rapid service response, while multinational vendors compete through AI workflow integration and managed equipment contract structures. Three archetypes dominate: integrated imaging conglomerates with captive healthcare IT ecosystems, specialized breast imaging purists with dedicated modality focus, and diversified industrial electronics manufacturers with medical device divisions. Consolidation pressures intensify through distributor network acquisitions and strategic partnerships bundling hardware with cloud-based image storage.
Within the integrated imaging tier, Siemens Healthineers and Koninklijke Philips NV occupy positions anchoring AI-integrated workflow platforms that reduce radiologist reading burden. Fujifilm Corporation exemplifies the domestic manufacturing archetype, leveraging its Japan-based production footprint to anchor premium digital breast tomosynthesis placements in tier-one medical centers. Konica Minolta represents the compact screening specialist segment, with system configurations designed for mobile breast examination vehicles serving rural prefectures where fixed-site infrastructure remains uneconomical.
| Leading Market Players |
|---|
| Siemens Healthineers |
| Koninklijke Philips NV |
| Fujifilm Corporation |
| Konica Minolta |
| Toshiba Corporation |
| Hologic Inc |
| Canon Medical Systems Corporation |
| Carestream Health |
| GE Healthcare |
| Others |
Supply & Pricing Matrix
Tomosynthesis-enabled premium platforms command 40-60% price separation from standard full-field digital systems, with this bifurcation manifesting in both metropolitan hospital procurement budgets and component sourcing strategies that concentrate high-margin detector arrays in domestic Japanese manufacturing while outsourcing commodity flat-panel production to South Korean foundries.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs Japanese mammography procurement, with PMDA reimbursement tiers and JIS certification grades serving as the primary differentiation drivers. Cost compression in standard digital systems is intensifying because municipal hospital budget constraints extend replacement cycles beyond technical obsolescence. Prefectural screening programs exhibit highest price sensitivity, while tier-one academic medical centers prioritize clinical differentiation over acquisition cost.
Supply Chain Analysis
Refurbishment flows for end-of-life systems create secondary revenue streams for domestic service providers, with used equipment redeployed to rural Hokkaido and Tohoku clinics through certified remanufacturing programs. Manufacturing concentration rests on Japan and South Korea for flat-panel detectors, with molybdenum-rhodium target assemblies sourced from German precision metalworkers. Single-source vulnerability in X-ray tube production elevates supply risk. Distribution runs through authorized dealer networks anchored in Tokyo and Osaka medical equipment districts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's mammography market functions as a geographic-arbitrage play where PMDA's software-as-a-medical-device compliance costs deter smaller foreign entrants, creating protected margin pools for domestic manufacturers with established regulatory affairs infrastructure.
For Market Incumbents: Acquire AI algorithm development capabilities to embed diagnostic intelligence within managed equipment contracts. Fujifilm and Siemens Healthineers should deepen backward integration into detector manufacturing to defend against South Korean component suppliers. Consolidate distributor networks in Nagoya and Fukuoka to preempt emerging regional competitors. For New Entrants and Emerging Players: Cloud-based image storage partnerships offer low-capital entry into metropolitan hospital IT procurement cycles. Rural mobile screening contracts in Tohoku present the most penetrable segment, with compact system configurations bypassing fixed-site infrastructure requirements. Target GPO contracts through embedded maintenance pricing rather than capital sale competition. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap AI diagnostic developers holding PMDA software-as-a-medical-device pre-certifications. Five-to-ten year viability hinges on convergence of imaging hardware with algorithmic reading workflows. Monitor PMDA approval timelines for AI-integrated tomosynthesis platforms as inflection indicator for valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Software-as-a-Medical-Device Submission | Accelerates market access for AI-integrated mammography workstations in tier-one centers. |
| Prefectural Screening Contract Partnership | Locks multi-year revenue streams through Tokyo and Osaka government tenders. |
| Mobile Examination Vehicle Fleet Deployment | Captures underserved rural populations in Hokkaido and Tohoku with compact systems. |
| Detector Manufacturing Backward Integration | Reduces dependency on South Korean flat-panel suppliers and protects margin pools. |
| AI-Assisted Reading Workstation Development | Addresses radiologist workforce scarcity limiting throughput expansion nationwide. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital procurement managers, biomedical engineers, PMDA regulatory consultants, and GPO contracts specialists with secondary validation against PMDA device approval databases, Ministry of Health Labour and Welfare screening guidelines, and METI healthcare technology assessment frameworks. Bottom-up equipment installation tracking and top-down market sizing triangulated volume estimates across prefectural tender records and manufacturer shipment disclosures.
Comparable-period anchoring tied projection assumptions to historical replacement cycle patterns and reimbursement trajectory shifts across the analysis window. Segmentation modeling incorporated product type, technology tier, end-user channel, and application purpose dimensions. CAGRs derived from equipment procurement elasticity to screening population growth and PMDA reimbursement rate adjustments, with sensitivity testing for AI algorithm adoption curves and radiologist workforce constraints.
The model assumes a particular technology adoption path; alternative pathways for digital breast tomosynthesis would alter the outlook if PMDA reimbursement structures shift toward 2D mammography preservation. Forecasts reflect assumptions about prefectural budget continuity and JIS standards stability. Practitioners should monitor PMDA software-as-a-medical-device regulatory clarifications and METI cost-effectiveness weighting changes for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
AI-Based Medical Imaging Algorithm Validation Test Platforms Market
Medical Imaging
Teleradiology Services Market
Medical Imaging
North America Digital Radiology Market
Medical Imaging
Whole-Body Imaging Market
Medical Imaging
Healthcare Cloud Picture Archiving and Communications System Market
Medical Imaging
China Nuclear Imaging Market
Medical Imaging
Germany Nuclear Imaging Market
Medical Imaging
Ultrasound-Based Imaging Market
Medical Imaging
Brazil Digital Radiology Market
Medical Imaging
Functional Brain Imaging Systems Market
Medical Imaging
Ultrasound Elastography Systems Market
Medical Imaging
Global AI for Radiology Market
Medical Imaging
Global Automated Breast Ultrasound System (ABUS) Market
Medical Imaging
Middle East and Africa Magnetic Resonance Imaging (MRI) Market
Medical Imaging
Magnetic Resonance Imaging (MRI) Coils Market
Medical Imaging
Angiography Imaging Systems Market