
 Contrast Media Market | 2026-2036
Contrast Media Market Size, Share, and Industry Trends Forecast 2026-2036
Contrast Media Market Intelligence
A shift from single-source iodine supply contracts toward multi-source procurement is restructuring how contrast media manufacturers secure active pharmaceutical ingredients. Bayer AG leverages its backward integration into iodine refining to buffer against raw material volatility. GE HealthCare anchors its position through captive manufacturing of both iodinated and gadolinium-based portfolios. Bracco Imaging S.p.A. differentiates via specialized production of high-concentration iodine formulations for cardiac applications.
Contrast media are pharmacologically active substances administered to enhance the visibility of tissues, vessels, and organs during medical imaging procedures, typically formulated with iodine, gadolinium, barium, or microbubble gas cores at defined osmolality and viscosity thresholds. Their primary purpose is to improve diagnostic accuracy by amplifying differential signal intensity between target anatomical structures and surrounding tissues. Iodinated contrast agents dominate current volume due to entrenched CT protocol standardization, while gadolinium-based agents face structural pressure from macrocyclic substitution trends driven by safety concerns. Microbubble contrast media represent the fastest-growing segment as ultrasound imaging expands into liver and cardiac perfusion assessments where radiation exposure must be eliminated.
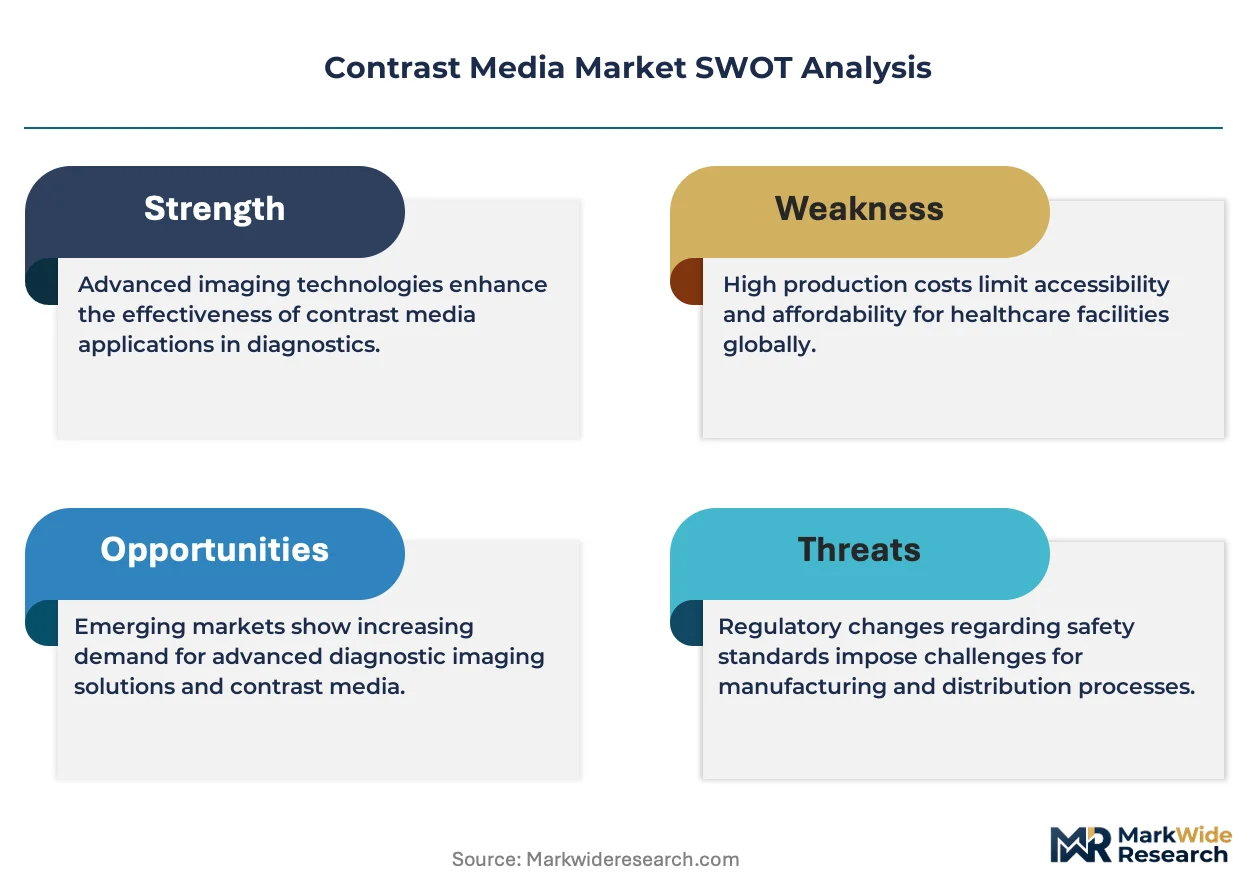
The FDA, EMA, and ISO 10993 collectively govern contrast media through premarket safety evaluation, post-market pharmacovigilance, and biocompatibility testing protocols that directly determine product approval timelines and labeling requirements. The FDA's boxed warning updates on gadolinium retention have forced reformulation investments, while EMA's PRAC restrictions on linear agents have reshaped European product mixes. Stakeholders must monitor evolving renal safety protocols and iodine supply chain diversification requirements as regulatory stringency tightens across major jurisdictions.
Market Dynamics
Macrocyclic gadolinium formulations are displacing linear chelates across major markets, forcing manufacturers to reconfigure production lines and absorb reformulation costs while iodinated agents consolidate their dominance in CT angiography protocols.
Growth Catalysts
- Cardiac CT Protocol Expansion:Hospital cardiology departments are embedding iodinated contrast into routine coronary angiography workflows, creating steady procedural demand.
- FDA Boxed Warning Updates:The agency's strengthened gadolinium retention disclosures have accelerated clinical migration toward macrocyclic alternatives with favorable safety profiles.
- Ultrasound Perfusion Imaging:Microbubble contrast agents are penetrating liver and cardiac assessment protocols where radiation elimination is clinically mandated.
Market Restraints
- Iodine Supply Concentration:Chilean and Japanese iodine refiners control upstream active pharmaceutical ingredient flows, exposing manufacturers to geopolitical and pricing volatility.
- Linear Gadolinium Phase-Out Costs:EMA PRAC restrictions on linear agents have stranded inventory and forced costly manufacturing line conversions.
- Barium Sulfate Substitution Pressure:Oral and rectal barium formulations face displacement by CT and MRI alternatives in gastrointestinal imaging.
Strategic Opportunities
- Outpatient Imaging Center Penetration:Freestanding diagnostic facilities in the United States are expanding contrast-enhanced procedure volumes outside hospital systems.
- ISO 10993 Biocompatibility Certification:Manufacturers achieving enhanced biocompatibility testing credentials can command premium positioning in safety-sensitive applications.
- Artificial Intelligence-Enhanced Dosing:Integration of AI-driven contrast dose optimization with imaging protocols promises reduced adverse event rates and protocol standardization.
Industry Challenges
- Specialized Formulation Chemistry Talent:The field requires rare expertise in chelate stability engineering and osmolality tuning that outpaces educational pipeline output.
- Legacy CT Scanner Compatibility:New high-concentration iodine formulations face integration friction with installed base injector systems and software protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Contrast Media Market |
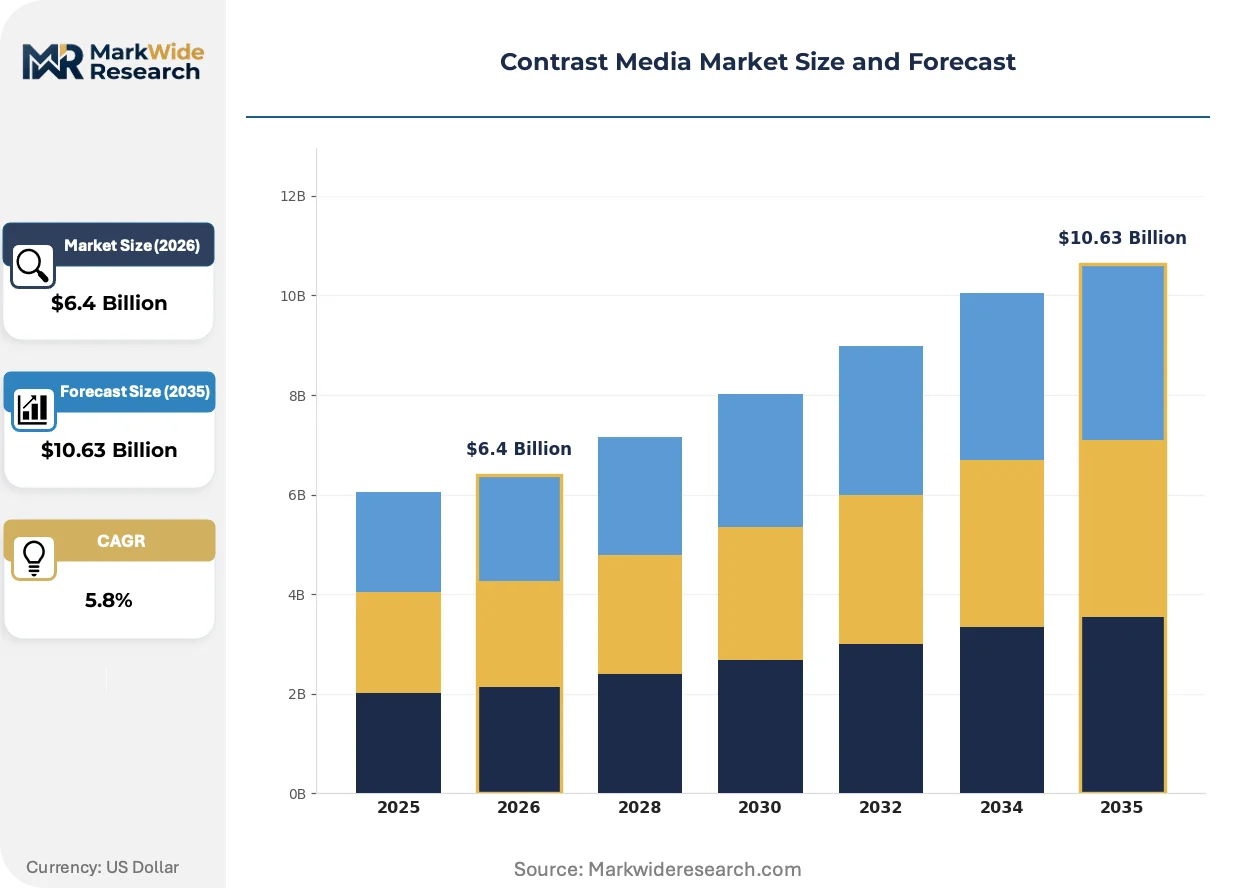
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $10.63 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Iodinated Contrast Agents, Gadolinium-Based Agents, Microbubble Contrast Media, Barium Sulfate Suspensions Application: Magnetic Resonance Imaging, Computed Tomography, Ultrasound Imaging, Fluoroscopy End User: Radiology Clinics, Diagnostic Laboratories, Outpatient Centers, Research Institutes Distribution Channel: Direct Sales, Distributors, E-commerce Platforms, Pharmaceutical Wholesalers |
| Companies Covered | Guerbet, Fujifilm Holdings Corporation, Bayer AG, Beijing Beilu Pharmaceutical Co., Ltd., Daiichi Sankyo Company, Ltd., GE HealthCare, Lantheus Medical Imaging, J.B. Chemicals & Pharmaceuticals Ltd., Bracco Imaging S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Contrast Media Market Strategic Shifts & Innovations
Formulation chemistry, regulatory safety frameworks, and procurement centralization are converging to reshape how contrast agents reach clinical endpoints. These forces favor manufacturers with integrated supply chains and adaptive regulatory capabilities.
Microbubble contrast technology is expanding into functional liver imaging and myocardial perfusion assessment where microvascular flow quantification is clinically essential. Interventional cardiologists and hepatologists are adopting these agents for real-time procedural guidance. This expansion is compressing the addressable market for diagnostic nuclear medicine tracers in hepatobiliary and cardiac stress applications.
EMA's PRAC linear gadolinium agent restrictions have forced wholesale portfolio restructuring across European markets. Manufacturers have withdrawn or reformulated linear chelate products, redirecting R&D investment toward macrocyclic stability optimization. Cardiac MRI centers in Germany, France, and Italy have completed the bulk of this transition, while Southern and Eastern European facilities lag in compliance migration.
Hospital system procurement offices are consolidating contrast media purchasing through centralized therapeutic category management. Group purchasing organizations and integrated delivery networks are displacing individual radiology department buying authority. This concentration is most visible in United States metropolitan markets where three to five health systems control regional imaging capacity.
Contrast Media Market Segmentation
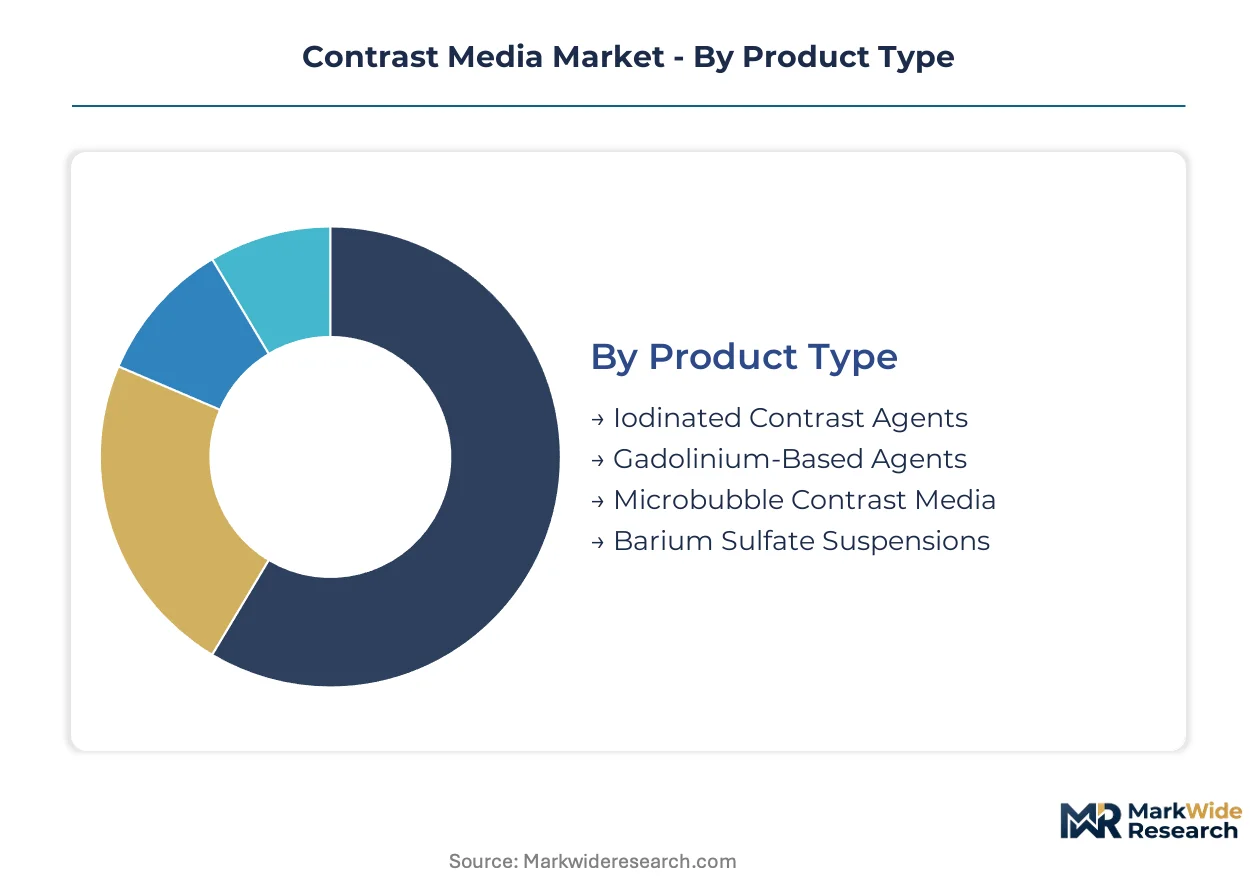
Contrast media segmentation reflects divergent technical requirements across imaging modalities and procurement patterns that vary sharply between hospital systems and decentralized outpatient facilities. Understanding these divides illuminates where formulation investments concentrate versus where distribution economics dominate purchasing decisions.
Product Type:
Iodinated and gadolinium-based agents anchor established hospital protocols, while microbubble formulations embed into specialized functional imaging workflows that demand real-time perfusion assessment.
- Iodinated Contrast Agents:These formulations combine iodine with organic carriers at defined osmolality thresholds to enhance X-ray attenuation in vascular and soft tissue imaging. Demand concentrates in United States cardiac catheterization laboratories where CT angiography protocols have displaced diagnostic catheterization for intermediate-risk patients. Supply contracts increasingly bundle high-concentration formulations with power injector systems.
- Gadolinium-Based Agents:Chelated rare-earth complexes generate paramagnetic contrast in magnetic resonance applications through localized magnetic field distortion. German and French hospital systems have completed macrocyclic conversion following EMA PRAC restrictions, while Southern European facilities retain linear inventory under transition timelines. Reformulation costs have compressed margins for manufacturers with legacy linear portfolios.
- Microbubble Contrast Media:Perfluorocarbon or nitrogen-filled lipid shells oscillate under ultrasound frequency to enable real-time perfusion mapping in hepatobiliary and cardiac assessments.
- Barium Sulfate Suspensions:Insoluble barium preparations coat gastrointestinal mucosa for fluoroscopic examination, facing displacement pressure from cross-sectional alternatives.
Volume placements concentrate in iodinated formulations; the faster expansion belongs to microbubble agents.
Application:
Modalities cluster by radiation exposure tolerance and tissue characterization requirements, with ultrasound gaining ground in populations where cumulative dose limits constrain CT repeatability.
- Computed Tomography:Iodinated enhancement enables vascular, oncologic, and trauma imaging at sub-millimeter resolution through rapid bolus timing. United States emergency departments drive procedural volume through stroke and pulmonary embolism rule-out protocols. Scanner throughput requirements favor high-osmolality formulations with rapid renal clearance profiles.
- Magnetic Resonance Imaging:Gadolinium chelates accentuate blood-brain barrier disruption, tumor neovascularity, and inflammatory tissue changes through T1 shortening effects. German neuroradiology centers have standardized macrocyclic agents for multiple sclerosis surveillance and breast cancer staging. Cardiac MRI stress perfusion protocols are expanding agent consumption in tertiary centers.
- Ultrasound Imaging:Microbubble agents enable quantitative liver stiffness and myocardial perfusion assessment without ionizing radiation exposure.
- Fluoroscopy:Real-time X-ray guidance for interventional procedures relies on iodinated agents for vascular roadmap generation.
CT procedures generate the highest absolute agent consumption; MRI applications show the steepest expansion trajectory in neuro-oncology and cardiac imaging.
End User:
Facility type determines batch sizing, storage infrastructure, and regulatory compliance burden, with outpatient migration reshaping logistics requirements away from central pharmacy models.
- Outpatient Centers:Freestanding diagnostic facilities in United States metropolitan markets perform contrast-enhanced CT and MRI without hospital admission infrastructure. These sites favor single-dose prefilled syringes and abbreviated cold-chain requirements. Group purchasing organization contracts consolidate procurement across regional networks.
- Radiology Clinics:Specialized imaging practices concentrate high-volume CT angiography and breast MRI services with dedicated contrast protocols. German private radiology chains have invested in on-site pharmacy compounding to reduce per-procedure material costs.
- Diagnostic Laboratories:Hospital-affiliated labs process referred imaging with standardized contrast formulary restrictions.
- Research Institutes:Academic medical centers evaluate novel agents under FDA or EMA investigational protocols with specialized pharmacovigilance reporting.
Procurement volume aggregates in radiology clinics; outpatient centers are gaining share fastest as United States reimbursement shifts favor site-neutral payment.
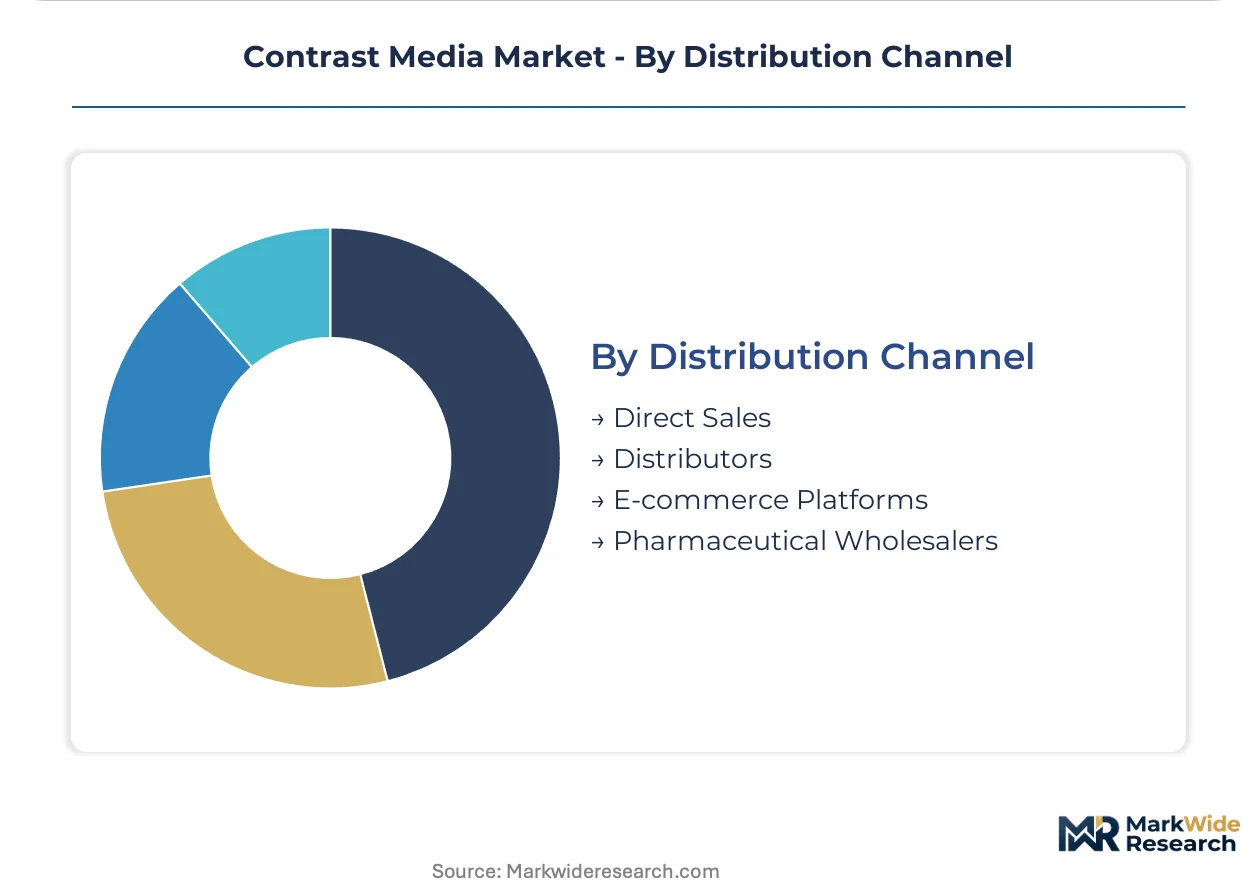
Distribution Channel:
Channel selection tracks order frequency, cold-chain sensitivity, and formulary compliance verification requirements that differ between acute care and elective settings.
- Direct Sales:Manufacturers maintain field inventory at high-volume United States health systems with consignment arrangements and just-in-time replenishment. These partnerships include protocol standardization support and adverse event response training.
- Pharmaceutical Wholesalers:McKesson, AmerisourceBergen, and Cardinal Health distribute temperature-controlled contrast inventory to hospital pharmacies with lot tracking and recall management infrastructure.
- Distributors:Regional medical supply intermediaries service mid-tier imaging centers with consolidated deliveries across multiple therapeutic categories.
- E-commerce Platforms:Limited penetration for contrast agents due to cold-chain requirements and prescription verification protocols.
Direct sales capture the largest contract value; pharmaceutical wholesalers handle the greatest shipment volume across dispersed delivery points.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hospital systems consume the largest share of iodinated contrast volumes, while European regulatory pressure on gadolinium retention is accelerating macrocyclic adoption. Asia-Pacific markets are expanding CT and MRI infrastructure at divergent regulatory paces.
United States
Outpatient imaging centers in Texas, Florida, and California are embedding contrast-enhanced CT angiography into cardiology workflows. FDA boxed warning updates on gadolinium retention have pushed tertiary centers toward macrocyclic formulations. The Mayo Clinic Rochester and Cleveland Clinic anchor high-volume cardiac MRI programs with standardized agent protocols.
Germany
EMA PRAC restrictions on linear gadolinium agents have completed macrocyclic conversion across Bavarian and North Rhine-Westphalian hospital networks. The national pharmaceutical regulator maintains stringent post-market surveillance requirements. Berlin-Brandenburg academic medical centers are piloting AI-enhanced contrast dosing protocols for renal safety optimization.
Japan
PMDA safety reviews have aligned with EMA macrocyclic preferences, compressing linear agent market share. METI industrial policy supports domestic iodine refining capacity expansion. Osaka-Kansai manufacturing clusters produce high-purity active pharmaceutical ingredients for regional CT contrast supply.
China
NMPA regulatory harmonization with ISO 10993 biocompatibility standards is extending approval timelines for imported agents. Yangtze River Delta hospital procurement consortia are consolidating contrast purchasing across Shanghai and Jiangsu province imaging networks. Domestic manufacturers are scaling iodinated formulation capacity for CT protocol standardization.
India
CDSCO import licensing requirements for contrast media are tightening cold-chain verification protocols. Maharashtra and Gujarat radiology chains are expanding MRI gadolinium utilization in Mumbai and Ahmedabad metropolitan markets. Government hospital procurement is concentrating volume through centralized tender mechanisms.
Contrast Media Market Key Industry Players
Backward integration into iodine refining dominates the current landscape as manufacturers seek supply security. The vendor base clusters around three tiers: diversified pharmaceutical conglomerates with captive chemical operations, specialized imaging agent producers with formulation expertise, and regional generic manufacturers serving price-sensitive procurement channels. Strategic archetypes include supply-integrated multinationals, macrocyclic-focused MRI specialists, and microbubble technology developers. Capacity expansion and portfolio diversification represent the dominant competitive moves as firms absorb reformulation costs and rebuild manufacturing lines.
Within the supply-integrated tier, Bayer AG anchors European production networks through in-house iodine refining operations. GE HealthCare occupies a position spanning both iodinated and gadolinium-based portfolios with captive manufacturing infrastructure. Bracco Imaging S.p.A. exemplifies the specialized formulation archetype through concentrated production of high-concentration cardiac applications.
| Leading Market Players |
|---|
| Guerbet |
| Fujifilm Holdings Corporation |
| Bayer AG |
| Beijing Beilu Pharmaceutical Co., Ltd. |
| Daiichi Sankyo Company, Ltd. |
| GE HealthCare |
| Lantheus Medical Imaging |
| J.B. Chemicals & Pharmaceuticals Ltd. |
| Bracco Imaging S.p.A. |
| Others |
Cost & Logistics Intelligence
ISO 10993 biocompatibility certification gates both qualified supply access and premium-tier pricing power for iodinated and gadolinium-based formulations, separating manufacturers with enhanced safety credentials from commodity suppliers serving price-sensitive procurement channels.
Pricing Analysis
Volume placements concentrate in standard-tier iodinated agents for CT protocols, while margins expand in macrocyclic gadolinium and microbubble formulations where safety profiles command premium positioning. Price differentiation hinges on ISO 10993 certification tier and backward integration into iodine refining. Pricing pressure stems from group purchasing organization consolidation in United States metropolitan markets. Outpatient imaging centers exhibit the highest price sensitivity; academic medical centers with research protocols show the least.
Supply Chain Analysis
ISO 10993 biocompatibility certification and FDA premarket approval pathways filter qualified suppliers, concentrating active pharmaceutical ingredient production in Chile, Japan, and China. Iodine extraction, chelate synthesis, and lipid shell formulation for microbubbles constitute critical input dependencies. Single-source vulnerability in Chilean iodine refining exposes manufacturers to geopolitical disruption. Distribution runs through pharmaceutical wholesalers with temperature-controlled logistics and hospital pharmacy consignment models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as EMA PRAC restrictions on linear gadolinium agents and FDA boxed warning updates force smaller manufacturers to absorb unsustainable reformulation costs.
For Market Incumbents: Cement supply security through backward integration into iodine refining or captive chelate manufacturing partnerships. Expand macrocyclic gadolinium capacity ahead of Southern European compliance migration timelines. Defend hospital system contracts by embedding AI-enhanced dosing protocols that reduce adverse event liability exposure.
For New Entrants and Emerging Players: The gap between premium macrocyclic formulations and economy-tier iodinated agents creates white-space opportunity in mid-concentration cardiac-specific products. Target United States outpatient imaging centers with prefilled syringe formats and abbreviated cold-chain requirements. Pursue group purchasing organization vendor qualification as the primary go-to-market pathway.
For Investors and Strategic Acquirers: EMA PRAC withdrawal deadlines for linear agents are the leading indicator that macrocyclic-focused formulation specialists will command scarcity premiums. Position for five-to-ten year horizon consolidation around supply-integrated multinationals. Acquire targets with ISO 10993 enhanced certification and established wholesaler distribution relationships.
| Strategic Initiative | Industry Significance |
|---|---|
| Macrocyclic Gadolinium Conversion | EMA PRAC compliance deadlines force portfolio restructuring and manufacturing line investments. |
| Iodine Refining Backward Integration | Bayer AG's captive supply buffers against Chilean and Japanese refiner pricing volatility. |
| AI-Enhanced Dosing Protocol Development | Mayo Clinic Rochester pilots reduce renal adverse events and standardize cardiac MRI workflows. |
| Outpatient Center Distribution Expansion | Freestanding diagnostic facilities in Texas and Florida bypass hospital pharmacy procurement concentration. |
| Microbubble Perfusion Application Extension | Liver and cardiac ultrasound protocols displace diagnostic nuclear medicine tracer utilization. |
Research Approach
FDA filings, EMA PRAC safety communications, and ISO 10993 biocompatibility databases formed the secondary backbone, supplemented by customs records of iodine active pharmaceutical ingredient trade flows. Primary interviews with radiology department heads, hospital procurement managers, GPO contracts specialists, and contrast media formulation chemists validated demand assumptions and pricing dynamics. Bottom-up procedure volume estimates and top-down manufacturer revenue analysis were triangulated across the analysis window.
Historical trendline analysis of CT and MRI procedure volumes informed the projection framework, with segmentation across product type, application modality, end-user facility category, and distribution channel. CAGRs were derived from fitted growth curves adjusted for regulatory inflection points including EMA PRAC linear agent phase-outs and FDA gadolinium retention warning updates. Modeled inputs incorporated hospital capital expenditure cycles for scanner installations and outpatient imaging center reimbursement policy shifts.
Underlying measurement precision varies by segment; iodinated contrast agent volumes carry tighter precision than microbubble expansion estimates due to established CT protocol standardization. Forecasts reflect assumptions about macrocyclic conversion timelines and iodine supply chain stability that may shift with regulatory or geopolitical developments. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Australia Computed Tomography Market
Medical Imaging
Meningitis Imaging Market
Medical Imaging
South America Fluoroscopy Market
Medical Imaging
Argentina Nuclear Imaging Market
Medical Imaging
United States Digital X-Ray Devices Market
Medical Imaging
Japan Computed Tomography Market
Medical Imaging
North America MRI (Magnetic Resonance Imaging) Market
Medical Imaging
Global Artificial Intelligence in MRI Market
Medical Imaging
Digital X Ray Market
Medical Imaging
Europe Nuclear Imaging Market
Medical Imaging
Medical Imaging Informatics Market
Medical Imaging
Medical Holography Market
Medical Imaging
Middle East and Africa Digital X-Ray Devices Market
Medical Imaging
Germany Nuclear Imaging Market
Medical Imaging
South Korea Mammography Market
Medical Imaging
South Korea Computed Tomography Market