
 Japan Diagnostic Imaging Equipment Market | 2026-2036
Japan Diagnostic Imaging Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Diagnostic Imaging Equipment Market Foresight
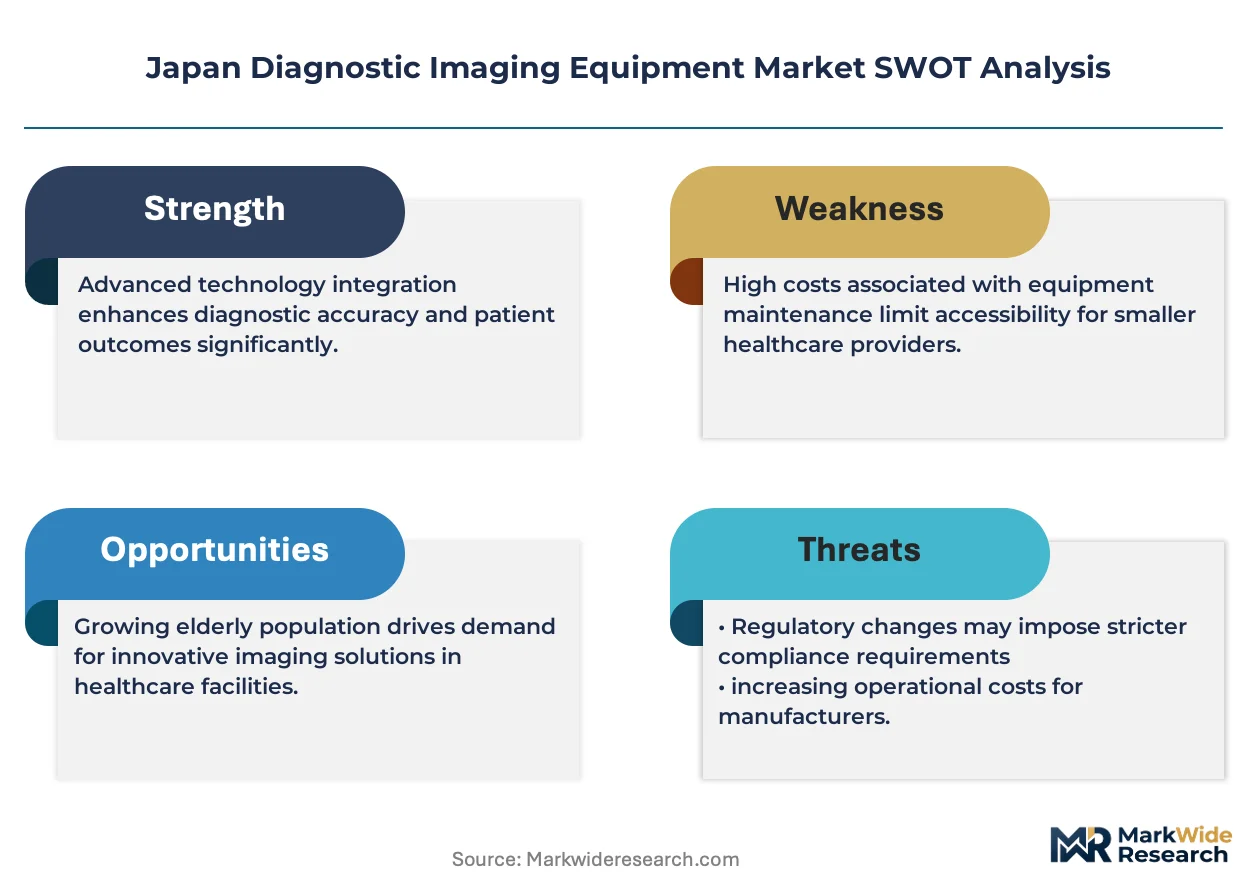
Hospital procurement is rotating toward outpatient imaging centers and specialized clinics as Japan's aging population strains inpatient capacity. Canon Medical Systems Corporation leverages its domestic manufacturing footprint to sustain rapid fulfillment cycles for CT and MRI installations. Siemens Healthineers anchors premium segment positioning through artificial intelligence integration in diagnostic workflows. Fujifilm Holdings Corporation differentiates via concentrated investment in digital X-ray and endoscopic ultrasound platforms.
Diagnostic imaging equipment encompasses electromagnetic, acoustic, and particle-based systems engineered to visualize internal anatomical structures with spatial resolution measured in millimeters or sub-millimeter scales, serving screening, diagnosis, and interventional guidance functions across medical practice. MRI systems command substantial capital allocation from tertiary hospitals due to superior soft-tissue contrast in neurological and oncological applications, while portable digital ultrasound is expanding fastest among clinics and home-care networks seeking point-of-care flexibility. CT scanner demand reflects sustained replacement cycles tied to detector row upgrades and radiation dose optimization protocols.
PMDA governs device safety and efficacy reviews under Japan's Pharmaceutical and Medical Device Act, with METI coordinating industrial policy through medical equipment standardization and export promotion frameworks. JIS standards define performance benchmarks for electromagnetic compatibility and image quality consistency, directly influencing procurement specifications at prefectural hospital consortia. Stakeholders must monitor reimbursement rate adjustments under Japan's universal health coverage system and alignment between AI diagnostic software approvals and hardware platform certifications.
Market Dynamics
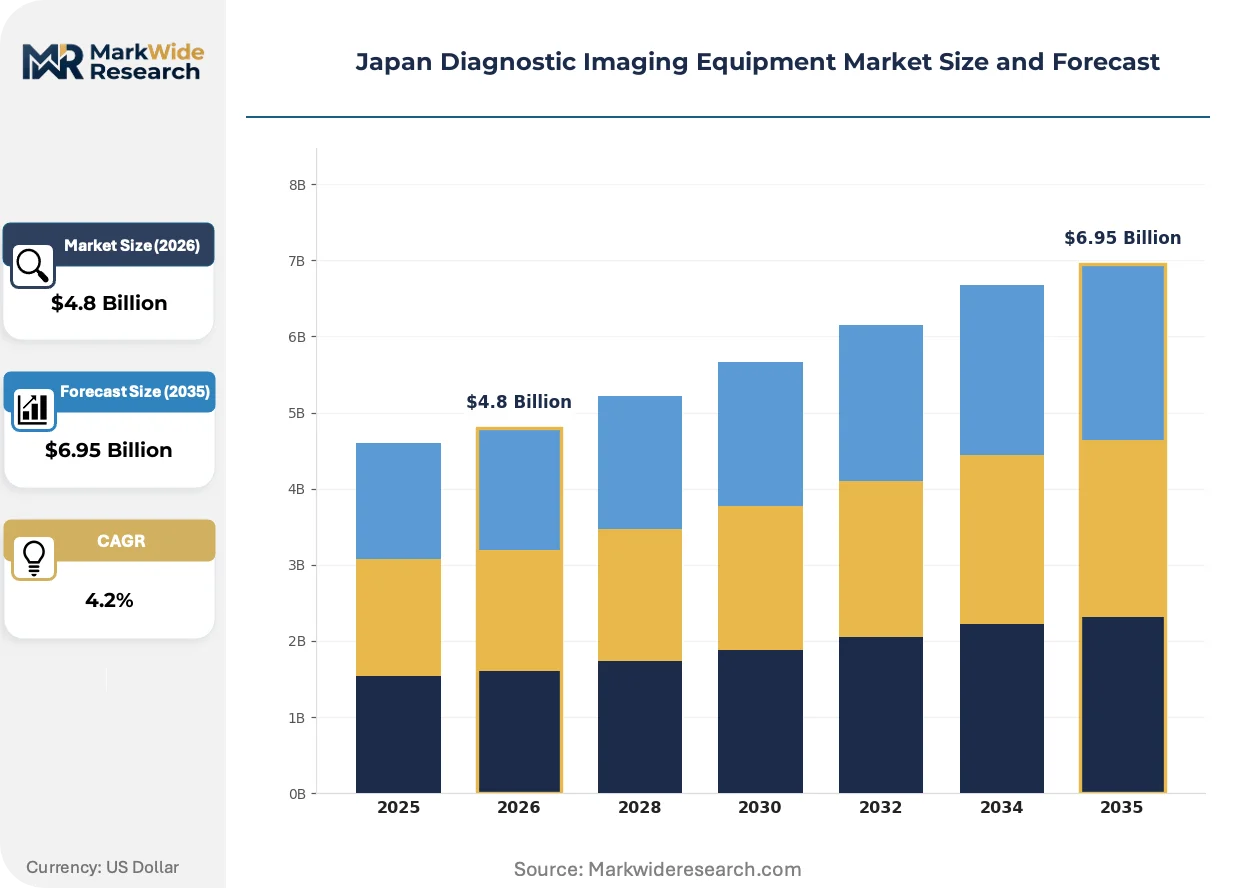
Japan's diagnostic imaging equipment market is undergoing a fundamental reconfiguration as METI's reimbursement reforms and PMDA's AI-assisted imaging approval pathways force vendors to rebuild their commercial models around software-hardware integration rather than standalone hardware sales.
Growth Catalysts
- Regional Healthcare Equity Mandates:Japan's Ministry of Health, Labour and Welfare is directing capital toward rural hospital networks, accelerating procurement of portable ultrasound and digital X-ray systems in prefectures outside Tokyo and Osaka metropolitan clusters.
- PMDA Streamlined AI Pathways:The regulator's accelerated review framework for AI-assisted diagnostic software is compressing time-to-market for vendors integrating machine learning into CT and MRI workflows.
- Aging Population Screening Demand:Japan's demographic shift toward super-aged society status is expanding oncology and neurological imaging volumes at outpatient clinics and specialized diagnostic centers.
Market Restraints
- Capital Intensity of MRI Installations:Superconducting magnet systems and specialized shielding requirements impose substantial upfront costs that constrain replacement cycles at secondary hospitals.
- Domestic Supply Concentration:Heavy reliance on domestic manufacturing footprints for precision components creates vulnerability to localized logistics disruptions affecting just-in-time delivery schedules.
- Radiation Dose Optimization Protocols:Stringent JIS standards for patient safety exposure limits are extending CT detector upgrade timelines and complicating product roadmap planning.
Strategic Opportunities
- Hokkaido and Tohoku Underpenetration:Northern prefectures maintain lower imaging equipment density per capita than national averages, creating expansion potential for mobile diagnostic units and tele-radiology partnerships.
- Home-Care Network Integration:Point-of-care ultrasound platforms are penetrating home healthcare agencies as Japan's government expands community-based long-term care reimbursement categories.
- Endoscopic Ultrasound Convergence:Hybrid imaging-therapeutic systems combining real-time ultrasound guidance with minimally invasive intervention are opening procedural revenue streams at digestive disease specialized clinics.
Industry Challenges
- Clinical Engineering Talent Scarcity:Japan faces acute shortages of biomedical equipment technicians capable of maintaining multi-modality imaging fleets across hybrid digital-analog system generations.
- Legacy PACS Integration Complexity:Hospitals operating decades-old picture archiving infrastructure encounter substantial middleware costs when connecting AI-enabled diagnostic platforms to existing data repositories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Diagnostic Imaging Equipment Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.95 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-ray, MRI, CT Scanner, Ultrasound End User: Hospitals, Imaging Centers, Clinics, Research Labs Technology: Digital, Analog, Hybrid, Portable Application: Cardiology, Oncology, Orthopedics, Neurology |
| Companies Covered | Siemens Healthineers, Koninklijke Philips N.V., Canon Medical Systems Corporation, Carestream Health Inc., Hitachi Ltd., Fujifilm Holdings Corporation, GE HealthCare, Hologic Inc., Shimadzu Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Diagnostic Imaging Equipment Market Shifts & Advancements
Artificial intelligence integration is fragmenting traditional hardware-centric business models across Japan's diagnostic imaging sector, forcing vendors to compete on algorithmic performance and workflow automation rather than raw technical specifications alone.
Photon-counting CT detector technology is fragmenting the conventional energy-integrating detector market by delivering superior spectral resolution and reduced radiation exposure. Tertiary hospitals in Tokyo's metropolitan clusters are piloting these systems for cardiac and pulmonary imaging protocols. The technology is fragmenting procurement evaluation criteria toward software-defined image reconstruction capabilities rather than hardware-centric detector row counts.
METI's medical device reimbursement reform framework is restructuring vendor contracting terms by linking payment rates to demonstrated clinical outcomes and equipment utilization efficiency. Manufacturers must now submit real-world performance data to maintain premium reimbursement tiers for CT and MRI installations. Prefectural hospital consortia are responding by consolidating purchasing authority and demanding outcome-based service level agreements.
Hospital procurement committees are unbundling after-sales service contracts from equipment financing packages, creating standalone competitive bidding for preventive maintenance and software update subscriptions. Independent service organizations are capturing contract opportunities previously held by original equipment manufacturers. This behavioral shift is most pronounced in Osaka's imaging center networks where capital expenditure scrutiny has intensified under regional budget consolidation mandates.
Japan Diagnostic Imaging Equipment Market Segmentation
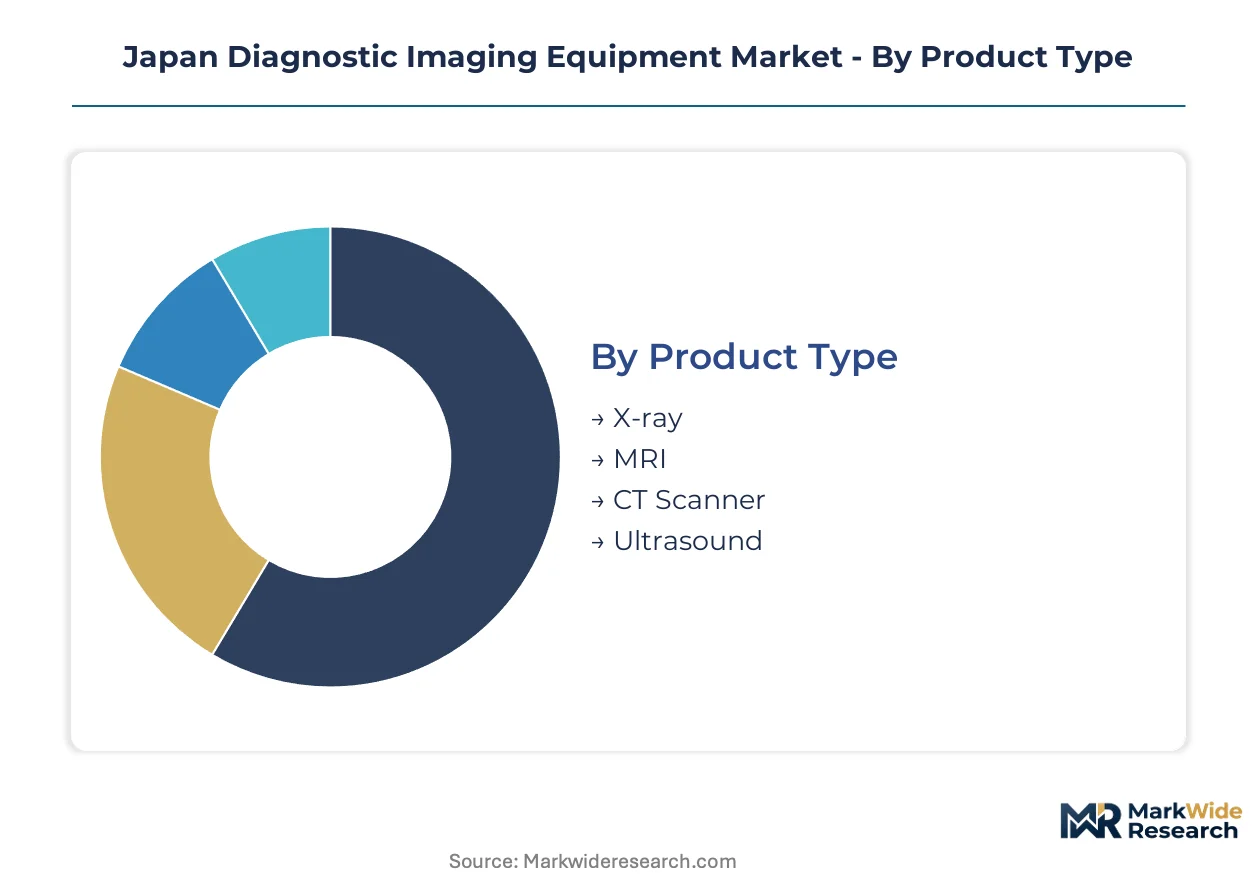
Segmentation reveals how METI reimbursement reforms and PMDA AI pathways are fragmenting procurement patterns across Japan's diagnostic imaging landscape. Understanding these divides exposes where hardware-software integration pressures concentrate and where capital allocation priorities diverge between metropolitan and regional healthcare networks.
Product Type:
Portable ultrasound and digital X-ray systems face intensifying substitution pressure from AI-enhanced platforms, while MRI and CT scanner categories defend position through technical moats in spectral resolution and detector architecture.
- CT Scanner:Multi-detector row systems with photon-counting detector technology deliver superior spectral resolution for cardiac and pulmonary protocols. Tokyo metropolitan tertiary hospitals concentrate procurement around these platforms as METI ties reimbursement rates to demonstrated clinical outcomes and utilization efficiency.
- Ultrasound:Point-of-care portable systems dominate rural hospital procurement under Ministry of Health, Labour and Welfare equity mandates. Prefectural networks outside Osaka and Tokyo metropolitan clusters prioritize these for outpatient and home-care network integration.
- X-ray:Digital radiography platforms with flat-panel detectors serve high-volume screening programs at imaging centers.
- MRI:Superconducting magnet systems with specialized shielding requirements constrain replacement cycles at secondary hospitals due to capital intensity.
CT Scanner retains volume leadership; Ultrasound holds the steepest expansion curve.
End User:
Cost tier stratification separates capital-intensive tertiary installations from efficiency-driven outpatient procurement, with imaging centers and clinics capturing share fastest as Japan's aging population strains inpatient capacity.
- Hospitals:Tertiary institutions concentrate MRI and advanced CT procurement for neurological and oncological applications. Tokyo metropolitan clusters anchor demand for premium spectral imaging and AI-integrated diagnostic workflows.
- Imaging Centers:Specialized diagnostic networks in Osaka prioritize unbundled after-sales service contracts and outcome-based service level agreements under regional budget consolidation mandates.
- Clinics:Outpatient facilities drive portable ultrasound adoption for point-of-care flexibility in community-based long-term care settings.
- Research Labs:Academic medical centers pilot photon-counting CT and AI reconstruction algorithms for protocol development.
Hospitals command the largest installed base; Imaging Centers are climbing the fastest as procurement authority consolidates.
Technology:
Application focus determines technology selection, with cardiology and oncology workflows demanding digital precision while neurology and orthopedics tolerate hybrid transition architectures.
- Digital:Fully integrated PACS-compatible platforms with AI-enabled diagnostic software dominate metropolitan hospital procurement. PMDA's streamlined approval pathways accelerate deployment of machine learning-integrated CT and MRI workflows.
- Portable:Battery-powered ultrasound systems with wireless DICOM transmission penetrate home healthcare agencies as government expands community-based long-term care reimbursement categories.
- Hybrid:Transitional architectures bridge legacy analog infrastructure with digital backbones at secondary hospitals.
- Analog:Remaining installed base concentrates in rural facilities awaiting capital replacement cycles.
Digital platforms anchor revenue concentration; Portable systems gain share fastest among regional expansion strategies.
Application:
Customer type segmentation reflects diverging clinical priorities, with oncology and cardiology demanding premium imaging performance while orthopedics and neurology optimize around throughput and accessibility.
- Oncology:PET-CT and MRI platforms with superior soft-tissue contrast serve screening and staging protocols for Japan's super-aged demographic. Outpatient clinics and specialized diagnostic centers concentrate expansion investment here.
- Cardiology:Photon-counting CT systems with reduced radiation exposure pilot at Tokyo metropolitan tertiary hospitals for coronary imaging protocols.
- Neurology:MRI systems with advanced diffusion and functional sequences address stroke and neurodegenerative disease volumes.
- Orthopedics:Digital X-ray and portable ultrasound serve musculoskeletal intervention guidance at clinics and imaging centers.
Oncology commands the deepest technology investment; Cardiology is expanding most quickly under dose optimization protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision imaging components to Japanese hospital networks, while domestic manufacturers in Tokyo and Osaka dominate final system assembly and regional distribution.
Kanto/Tokyo
Metropolitan tertiary hospitals concentrate demand for photon-counting CT and AI-integrated MRI platforms. METI ties reimbursement rates to demonstrated clinical outcomes, compressing procurement evaluation timelines. Tokyo's hospital clusters anchor premium segment volumes for neurological and oncological imaging protocols.
Kansai/Osaka
Specialized imaging center networks drive unbundled service contract adoption and outcome-based procurement terms. Regional budget consolidation mandates intensify capital expenditure scrutiny. Osaka's diagnostic facilities prioritize efficiency metrics and utilization-based vendor agreements.
Chubu/Nagoya
Manufacturing hub proximity supports rapid fulfillment cycles for precision component delivery. Secondary hospitals balance replacement cycles against superconducting magnet capital intensity. Nagoya's medical device industrial base sustains domestic supply chain resilience for detector and coil production.
Hokkaido
Rural hospital networks accelerate portable ultrasound and digital X-ray procurement under Ministry of Health, Labour and Welfare equity mandates. Lower imaging equipment density per capita creates expansion potential for mobile diagnostic units. Sapporo's regional medical centers pilot tele-radiology partnerships with Tokyo specialists.
Tohoku
Northern prefectures receive targeted capital allocation for point-of-care imaging infrastructure. Community-based long-term care reimbursement expansion drives home healthcare agency adoption of wireless DICOM ultrasound systems. Sendai's hospital consortia consolidate purchasing authority to negotiate outcome-based service level agreements.
Japan Diagnostic Imaging Equipment Market Competitive Landscape
Listed leaders compete with private specialists across software-hardware integration capabilities, reshaping traditional equipment-only contracting models. Market structure tilts toward consolidated premium-tier positioning for multi-modality platforms, with mid-scale specialists capturing regional service contract opportunities. Three archetypes dominate: integrated conglomerates with domestic manufacturing footprints, multinational health technology groups with AI algorithm portfolios, and precision component specialists with captive detector technology. Competitive moves concentrate on strategic partnerships for AI diagnostic software certification and geographic expansion into underpenetrated northern prefectures.
Among diversified Japanese conglomerates, Canon Medical Systems Corporation and Fujifilm Holdings Corporation exemplify domestic manufacturing archetypes with rapid fulfillment capabilities, while Siemens Healthineers anchors multinational positioning through workflow automation integration. Hitachi Ltd. and Shimadzu Corporation occupy mid-tier specialist positions emphasizing precision engineering and regional service density.
| Leading Market Players |
|---|
| Siemens Healthineers |
| Koninklijke Philips N.V. |
| Canon Medical Systems Corporation |
| Carestream Health Inc. |
| Hitachi Ltd. |
| Fujifilm Holdings Corporation |
| GE HealthCare |
| Hologic Inc. |
| Shimadzu Corporation |
| Others |
Supply & Pricing Matrix
Superconducting magnet manufacturing scale economies in Japan's Chubu industrial corridor concentrate precision component production among domestic specialists, compressing cost floors for MRI systems while elevating price discipline for imported CT detector arrays. This concentration pattern forces secondary hospitals to absorb premium tier pricing for advanced modalities or defer replacement cycles entirely.
Pricing Analysis
Photon-counting CT detector technology commands substantial premiums over energy-integrating predecessors, while legacy analog X-ray platforms face accelerating price erosion from digital flat-panel substitution. Three-tier pricing structure across premium spectral imaging, standard multi-detector CT, and economy digital radiography segments reflects divergent JIS certification tiers and after-sales bundling intensity. Cost compression in portable ultrasound intensifies as domestic manufacturers expand Chubu production capacity. Prefectural hospital consortia exhibit highest price sensitivity, whereas Tokyo metropolitan tertiary institutions prioritize clinical outcome metrics over capital expenditure minimization.
Supply Chain Analysis
Inbound logistics costs for superconducting wire and helium cryogen supplies fluctuate with Yokohama port container availability and transpacific shipping lane congestion. Japan draws precision detector components from Germany, South Korea, and domestic Nagoya manufacturing bases. Supply chain risk centers on single-source dependency for liquid helium cooling systems essential to MRI magnet stability. Distribution runs through authorized dealer networks serving prefectural hospital consortia, with direct manufacturer relationships reserved for Tokyo and Osaka metropolitan clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's diagnostic imaging equipment market sits in early-cycle expansion as regional healthcare equity mandates penetrate underpenetrated northern prefectures with point-of-care modalities. METI reimbursement reforms linking payment to clinical outcomes accelerate hardware-software integration demand.
For Market Incumbents: Consolidate service contract density across installed MRI and CT fleets to capture recurring revenue streams before independent service organizations capture regional maintenance markets. Deepen backward integration into photon-counting detector production to defend margin position against German and South Korean component specialists. Prefectural purchasing authority consolidation intensifies price competition for standalone equipment sales.
For New Entrants and Emerging Players: Anchor in Hokkaido and Tohoku mobile diagnostic unit opportunities where imaging equipment density per capita trails national benchmarks by substantial margins. Target home healthcare agency procurement channels as Ministry of Health, Labour and Welfare expands community-based long-term care reimbursement categories for wireless DICOM ultrasound systems. Pursue tele-radiology partnership models with Tokyo metropolitan specialists to overcome local radiologist scarcity.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among independent service organizations with multi-vendor maintenance capabilities and software update subscription models. Long-term viability over the next decade favors acquisition targets with AI diagnostic software certification pathways under PMDA's streamlined approval framework. Watch for inflection signals in prefectural hospital consortia unbundling after-sales contracts from equipment financing packages.
| Strategic Initiative | Industry Significance |
|---|---|
| PMDA AI Software Certification | Accelerated approval pathways compress time-to-market for machine learning-integrated CT and MRI workflows. |
| Prefectural Hospital Consortium Partnership | Consolidated purchasing authority demands outcome-based service level agreements and utilization efficiency guarantees. |
| Photon-Counting Detector Manufacturing Scale-Up | Domestic production expansion in Chubu reduces dependency on German precision component imports. |
| Tele-Radiology Platform Development | Real-time specialist consultation bridges radiologist scarcity gaps in Hokkaido and Tohoku regional networks. |
| Home Healthcare Agency Channel Expansion | Point-of-care ultrasound penetration captures reimbursement expansion under community-based long-term care categories. |
Research Methodology
Initial hypotheses were tested against primary input from hospital purchasing committee members, biomedical engineering directors, GPO contracts managers, and PMDA regulatory affairs specialists and refined through secondary validation against METI medical device standardization filings, prefectural hospital procurement databases, JIS performance benchmark documentation, and universal health coverage reimbursement rate schedules. Bottom-up equipment installation tracking across Tokyo, Osaka, and northern prefecture networks was triangulated with top-down market sizing from domestic manufacturer revenue disclosures.
Variance decomposition across the projection horizon isolates volume drivers by modality type, end-user facility tier, technology generation, and application focus. Segmentation modeling incorporated product type, end user category, technology platform, and clinical application dimensions with regional prefecture clusters as a cross-cutting analytical layer. CAGRs were derived from replacement cycle analysis, demographic screening demand projections, and capital allocation patterns under METI reimbursement reform implementation.
Decision-makers should treat outputs as directional under assumptions of sustained PMDA AI pathway streamlining and continued Ministry of Health, Labour and Welfare equity mandate funding; material deviation in reimbursement rate adjustments or superconducting magnet supply disruption would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Vascular Imaging Systems Market
Medical Imaging
Non-Invasive Coronary Imaging Market
Medical Imaging
Small Animal Imaging (in-Vivo) Market
Medical Imaging
Argentina Diagnostic Imaging Equipment Market
Medical Imaging
Orthopedic Imaging Market
Medical Imaging
Coronary Heart Disease Diagnostic Imaging Market
Medical Imaging
Digital Pathology Market
Medical Imaging
Preclinical Imaging (in-VIVO) Market
Medical Imaging
Medical Videoscope Market
Medical Imaging
United Arab Emirates Diagnostic Imaging Equipment Market
Medical Imaging
Japan Mammography Market
Medical Imaging
Asia Pacific Magnetic Resonance Imaging (MRI) Market
Medical Imaging
Global 3D Laparoscopy Imaging Market
Medical Imaging
Europe Portable X-Ray Devices Market
Medical Imaging
North America MRI (Magnetic Resonance Imaging) Market
Medical Imaging
Brazil Mammography Market