
 US Medical Imaging Market | 2026-2036
US Medical Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
US Medical Imaging Market Insights
CE marking reciprocity under the FDA's Medical Device Single Audit Program is collapsing as a viable fast-track for European entrants, forcing dedicated US regulatory builds. Siemens Healthineers leverages its installed base of MRI and CT platforms to sustain service contract renewal rates above industry norms. GE HealthCare anchors its position through backward integration into helium supply chains for superconducting magnet cooling. Philips Healthcare differentiates via hybrid imaging systems that combine PET and CT modalities in single-suite configurations.
Medical imaging encompasses the non-invasive acquisition of anatomical and physiological visual data through ionizing radiation, magnetic fields, acoustic waves, or radioactive tracers, with spatial resolution thresholds ranging from sub-millimeter CT voxels to whole-body MRI field strengths of 1.5 to 3.0 Tesla. Its primary commercial purpose is to enable diagnostic certainty, treatment planning, and interventional guidance across acute and chronic care pathways. CT scan equipment commands the largest installed base among product types, though AI-enhanced imaging technology captures disproportionate R&D allocation as vendors race for FDA algorithm clearances. Teleradiology delivery mode is expanding fastest among delivery modes, driven by rural hospital outsourcing and overnight coverage contracts.
FDA premarket notification requirements under 510(k) and the more stringent premarket approval pathway govern device commercialization, while HIPAA mandates constrain how imaging data traverses cloud-based teleradiology networks. The Centers for Medicare & Medicaid Services reimbursement schedules for CPT codes directly determine capital recovery timelines for hospital imaging departments. State-level certificate-of-need regulations in approximately three dozen jurisdictions restrict equipment duplication and influence vendor market access. Stakeholders must monitor whether FDA's predetermined change control plans for AI-enabled devices will stabilize or fragment algorithm update economics.
Market Dynamics
Hospital networks are consolidating imaging service lines while FDA's software-as-a-medical-device framework accelerates machine learning algorithm clearances, creating simultaneous pressure on vendor R&D allocation and capital deployment timelines.
Growth Catalysts
- AI-enhanced diagnostic programs:Hospital networks deploy these systems to reduce radiologist workload and compress turnaround times for emergency departments.
- Certificate-of-need regulations:These state-level restrictions in approximately three dozen jurisdictions limit equipment duplication and protect incumbent vendor relationships.
- Teleradiology delivery expansion:Rural hospital outsourcing and overnight coverage contracts drive demand for cloud-based image transmission infrastructure.
Market Restraints
- Helium supply concentration:Superconducting magnet cooling depends on a geographically concentrated helium market, exposing MRI manufacturers to input cost volatility.
- CE marking reciprocity collapse:The FDA's Medical Device Single Audit Program no longer provides viable fast-track pathways for European entrants, forcing dedicated US regulatory builds.
- HIPAA cloud constraints:Federal mandates restrict how imaging data traverses teleradiology networks, adding compliance layers to infrastructure decisions.
Strategic Opportunities
- Texas health system consolidation:Large hospital networks in this state are actively consolidating imaging service lines, creating vendor consolidation opportunities.
- FDA predetermined change control plans:This evolving framework for AI-enabled devices may stabilize algorithm update economics for early adopters.
- Hybrid imaging convergence:PET-CT single-suite configurations offer differentiation potential for vendors with integrated modality capabilities.
Industry Challenges
- Radiologist workforce compression:The specialty faces training pipeline constraints just as AI-assisted workflows demand new human-machine interface competencies.
- Legacy PACS integration friction:Hospital IT departments struggle to embed cloud-native teleradiology platforms into on-premise archival systems.
- 510(k) clearance timeline variability:FDA premarket notification pathways for novel imaging algorithms exhibit unpredictable review durations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Medical Imaging Market |
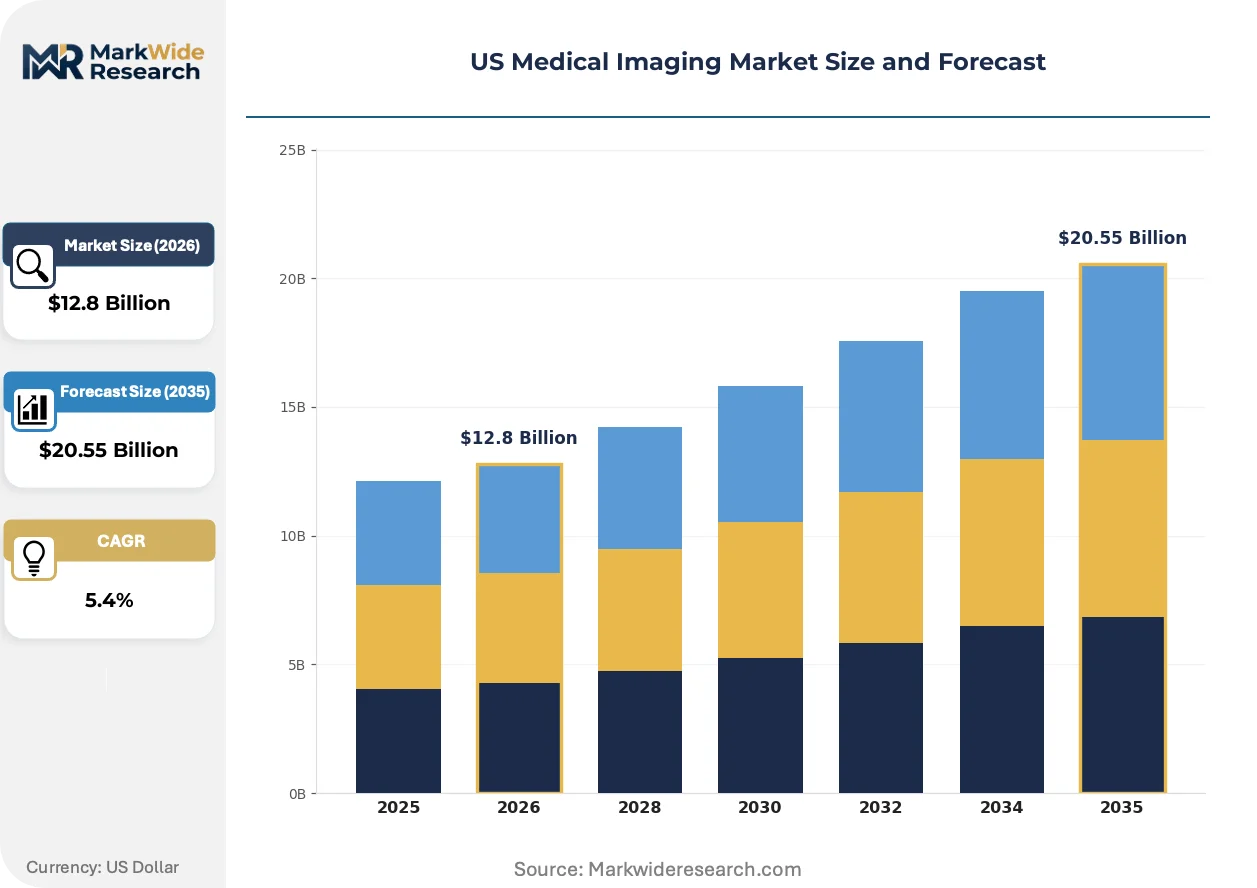
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $20.55 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-ray, MRI, CT Scan, Ultrasound End User: Hospitals, Imaging Centers, Clinics, Research Labs Technology: Digital Imaging, Hybrid Imaging, 3D Imaging, AI-Enhanced Imaging Delivery Mode: Point-of-Care, Teleradiology, In-Hospital, Mobile Services |
| Companies Covered | GE HealthCare, Siemens Healthineers, Philips Healthcare, Canon Medical Systems, FUJIFILM Corporation, Hologic Inc., Shimadzu Corporation, Samsung Electronics, Hitachi Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Medical Imaging Market Trends and Innovations
Machine learning algorithms are reshaping how imaging data converts to diagnostic decisions, while regulatory frameworks race to keep pace with software update velocities and reimbursement models lag technology deployment.
AI-enabled reconstruction algorithms are fragmenting the traditional hardware-software value chain in CT and MRI platforms. Academic medical centers and large integrated delivery networks adopt these tools fastest, demanding subscription-based licensing over perpetual software purchases. The technology is fragmenting vendor competitive advantage away from pure scanner specifications toward algorithm performance benchmarks.
FDA's predetermined change control plans for AI-enabled devices establish a regulated pathway for algorithm updates without full resubmission. This industrial consequence compresses the innovation-to-deployment cycle for imaging software vendors. Radiology AI developers in California and Massachusetts clusters are restructuring quality management systems to exploit this tailwind.
Health system procurement departments now unbundle after-sales service contracts from equipment financing, negotiating radiologist training and AI integration support as separate line items. Equipment vendors face margin pressure as buyers treat software implementation as distinct from hardware acquisition. This pattern concentrates in Florida and Texas health systems with aggressive cost accounting disciplines.
US Medical Imaging Market Segmentation
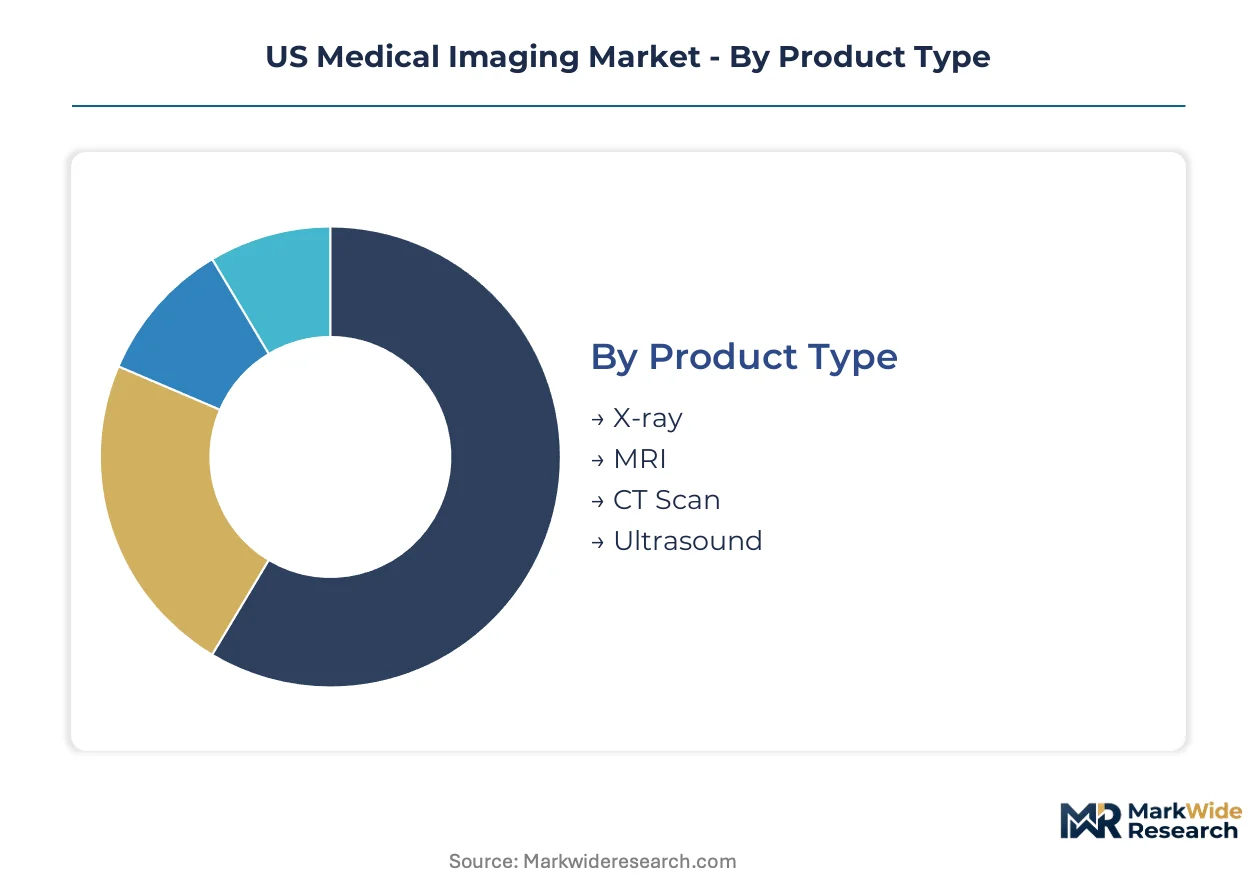
US Medical Imaging Market segmentation reveals how FDA clearance pathways, reimbursement schedules, and state-level certificate-of-need regulations differentially shape capital allocation across product categories and delivery modes. Hospital procurement departments exploit these structural boundaries to negotiate vendor contracts and service unbundling.
Product Type:
FDA premarket notification requirements under 510(k) and premarket approval pathways create distinct regulatory burdens across modalities, with ionizing radiation devices facing additional NRC oversight.
- CT Scan:Ionizing radiation-based tomography generates cross-sectional anatomical datasets with sub-millimeter voxel resolution. Texas and Florida hospital networks concentrate demand for emergency department throughput acceleration, though helium supply volatility for MRI alternatives creates substitution pressure.
- AI-Enhanced Imaging Technology:Machine learning algorithms reconstruct raw scanner data into diagnostic outputs, fragmenting traditional hardware-software value chains. Academic medical centers in California and Massachusetts drive fastest adoption, demanding subscription licensing over perpetual purchases as FDA predetermined change control plans stabilize update economics.
- X-ray:Conventional radiography maintains the largest installed base through low capital cost and rapid image acquisition.
- MRI:Magnetic resonance imaging depends on superconducting magnets cooled by geographically concentrated helium supplies, exposing procurement to input cost volatility.
- Ultrasound:Acoustic wave-based imaging offers portability advantages for point-of-care deployment without ionizing radiation exposure.
Established volume favors CT Scan; emerging adoption favors AI-Enhanced Imaging Technology.
End User:
CMS reimbursement schedules for CPT codes directly determine capital recovery timelines, concentrating purchasing power among entities with favorable cost accounting disciplines.
- Hospitals:Large integrated delivery networks consolidate imaging service lines to extract volume discounts from equipment vendors. Texas, California, and Florida health systems lead this consolidation, unbundling after-sales service contracts from hardware financing to negotiate AI integration support as separate line items.
- Imaging Centers:Freestanding facilities compete on turnaround time and radiologist availability, driving teleradiology outsourcing for overnight coverage. Rural markets in the Mountain West and Great Plains expand fastest as hospital networks shed non-core assets.
- Clinics:Ambulatory settings prioritize portable modalities and point-of-care accessibility over comprehensive diagnostic suites.
- Research Labs:Academic institutions demand hybrid imaging configurations and algorithm development partnerships with equipment manufacturers.
Procurement scale favors Hospitals; margin expansion favors Imaging Centers.
Technology:
Software update velocities now outpace hardware replacement cycles, restructuring vendor competitive advantage toward algorithm performance benchmarks.
- Digital Imaging:Direct detector arrays replace film-screen combinations across radiography and fluoroscopy platforms. General hospital radiology departments in the Northeast and Midwest maintain largest installed base, though replacement demand concentrates in systems exceeding decade-old detector lifecycles.
- Hybrid Imaging:PET-CT single-suite configurations combine functional and anatomical data acquisition in single patient positioning. Florida and Texas cancer centers drive demand for radiation therapy planning integration, with vendors differentiating through isotope supply chain partnerships.
- 3D Imaging:Volumetric reconstruction enables surgical planning and interventional guidance across orthopedic and cardiovascular applications.
- AI-Enhanced Imaging:Deep learning algorithms automate detection tasks and prioritize worklist queues for radiologist efficiency.
Deployment maturity favors Digital Imaging; steepest expansion trajectory favors AI-Enhanced Imaging.
Delivery Mode:
HIPAA mandates constrain how imaging data traverses cloud infrastructure, adding compliance layers to network architecture decisions.
- Teleradiology:Cloud-based image transmission connects rural hospitals to urban radiologist pools for overnight and subspecialty coverage. Certificate-of-need states with restricted equipment duplication drive outsourcing demand, particularly in the Southeast and Southwest where radiologist workforce gaps persist.
- Point-of-Care:Bedside ultrasound and portable X-ray reduce patient transport requirements in emergency and intensive care settings. Texas and California health systems with aggressive throughput metrics lead capital deployment for emergency department workflow compression.
- In-Hospital:Fixed installation suites maintain highest throughput capacity for scheduled diagnostic volumes.
- Mobile Services:Trailer-mounted MRI and CT units serve markets below certificate-of-need thresholds for permanent equipment installation.
Operational scale favors In-Hospital; geographic reach favors Teleradiology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA software-as-a-medical-device frameworks and state-level certificate-of-need regulations create divergent procurement environments across US sub-regions, concentrating vendor activity in jurisdictions with favorable reimbursement schedules and consolidated health system purchasing power.
California
Academic medical centers in Los Angeles and San Francisco drive fastest adoption of AI-enhanced imaging technology, demanding subscription-based licensing over perpetual software purchases. HIPAA mandates constrain how imaging data traverses cloud-based teleradiology networks, adding compliance layers to infrastructure decisions. The Stanford-MIT-Caltech research corridor anchors algorithm development partnerships with equipment manufacturers seeking FDA predetermined change control plan approvals.
Texas
Large hospital networks actively consolidate imaging service lines to extract volume discounts from equipment vendors, unbundling after-sales service contracts from hardware financing. State-level certificate-of-need regulations remain absent, permitting equipment duplication and intensifying vendor competition. The Dallas-Houston-San Antonio triangle concentrates demand for emergency department throughput acceleration and point-of-care portable modalities.
Florida
Cancer centers in Miami and Tampa drive demand for PET-CT single-suite configurations with radiation therapy planning integration. Aggressive cost accounting disciplines lead health system procurement departments to negotiate AI integration support as separate line items from hardware acquisition. Rural markets in the Panhandle expand teleradiology outsourcing for overnight radiologist coverage.
Northeast Corridor
Legacy PACS integration friction constrains hospital IT departments attempting to embed cloud-native teleradiology platforms into on-premise archival systems across New York and Boston metro areas. CMS reimbursement schedules for CPT codes directly determine capital recovery timelines for imaging departments. The Massachusetts biotech corridor supports radiology AI developers restructuring quality management systems for FDA algorithm clearances.
Mountain West
Rural hospital outsourcing drives fastest expansion of teleradiology delivery mode as health systems shed non-core imaging assets in Colorado, Utah, and Arizona. Certificate-of-need states with restricted equipment duplication accelerate mobile services deployment for trailer-mounted MRI and CT units. The Denver-Aurora medical hub concentrates subspecialty radiologist pools serving overnight coverage contracts across underserved territories.
US Medical Imaging Market Competitive Landscape
Player mix skews toward diversified medical technology conglomerates with installed base leverage and dedicated imaging specialists competing on algorithm performance. Market structure exhibits tiered consolidation with three to five dominant vendors controlling modality platforms and a fragmented long tail of AI software developers. Strategic archetypes include hardware-integrated service contract maximizers, algorithm-centric software licensors, and hybrid imaging system differentiators. Dominant competitive moves center on backward integration into critical supply chains and regulatory pathway optimization for machine learning clearances.
Among diversified conglomerates, GE HealthCare, Siemens Healthineers, and Philips Healthcare exemplify the hardware-integrated archetype, each occupying positions shaped by installed base scale and service renewal economics. GE HealthCare represents upstream supply chain control through helium sourcing for superconducting magnet cooling. Siemens Healthineers exemplifies platform leverage sustaining above-norm service contract renewal rates. Philips Healthcare anchors the hybrid imaging convergence strategy through PET-CT single-suite configurations. These three conglomerates sit within a competitive structure where algorithm performance benchmarks increasingly displace pure scanner specifications as differentiation vectors.
| Leading Market Players |
|---|
| GE HealthCare |
| Siemens Healthineers |
| Philips Healthcare |
| Canon Medical Systems |
| FUJIFILM Corporation |
| Hologic Inc. |
| Shimadzu Corporation |
| Samsung Electronics |
| Hitachi Ltd. |
| Others |
Pricing and Supply Chain Analysis
Ninety-day helium inventory cycles at MRI magnet manufacturers anchor pricing power for superconducting systems, compressing margins for vendors without backward integration into cryogenic gas supply chains while amplifying premium capture for those with captive helium sourcing.
Pricing Analysis
FDA clearance tier creates the primary spread between premium and standard equipment valuations, with 510(k) pathway devices commanding subscription-based SaaS pricing for AI-enhanced reconstruction algorithms while premarket approval systems sustain capital-intensive perpetual licensing. Price differentiation stems from algorithm performance benchmarks and service contract bundling, with cost compression in the standard tier intensifying as health systems unbundle after-sales support from hardware financing. Academic medical centers in California exhibit lowest price sensitivity due to research grant funding flexibility, while rural imaging centers in certificate-of-need states face highest budget constraints.
Supply Chain Analysis
Qatar and Algeria helium extraction underwrites global superconducting magnet cooling capacity, with the BLM Federal Helium Reserve in Texas providing strategic buffer stock for domestic MRI manufacturers. Rare earth element processing for CT detector arrays centers on China and Malaysia, while gradient coil copper winding feeds from Chile and Peru. Single-source vulnerability concentrates in isotope supply chains for PET radiotracers, exposing hybrid imaging system vendors to production interruptions. Distribution runs through hospital procurement consortiums and group purchasing organizations with consolidated negotiating leverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Radiologist workforce compression combined with FDA algorithm clearance expertise deficits creates scarcity premiums for vendors bridging human-machine interface competencies, rewarding early investment in predetermined change control plan infrastructure.
For Market Incumbents: Compound installed base leverage through service contract renewal acceleration, embedding AI reconstruction algorithms as mandatory subscription tiers to defend against software-only entrants. Backward integration into helium logistics insulates margin structures from input volatility threatening MRI competitors. Prioritize FDA predetermined change control plan approvals to compress algorithm update cycles below challenger timelines. For New Entrants and Emerging Players: Rural teleradiology infrastructure gaps where incumbent vendors under-serve overnight coverage contracts offer white-space penetration with cloud-native PACS architectures bypassing legacy integration friction. Target imaging centers in certificate-of-need states with restricted equipment duplication, positioning mobile MRI services as compliance-light alternatives to permanent installation. Lead with radiologist workforce augmentation rather than replacement messaging to accelerate hospital pilot adoption. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified conglomerates shedding non-core imaging divisions, particularly service-light hardware units lacking algorithm development pipelines. Long-term viability hinges on software recurring revenue ratios exceeding hardware dependency thresholds. Monitor FDA 510(k) clearance velocity for AI-enabled devices as inflection indicator for sector-wide margin expansion or compression.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Predetermined Change Control Plan Submission | Accelerates algorithm update economics for AI-enhanced imaging vendors seeking competitive separation. |
| Hospital System Partnership | Locks in multi-year service contracts with Texas and Florida networks consolidating imaging service lines. |
| Helium Supply Integration | Secures captive sourcing for superconducting magnet cooling against geographic concentration risks. |
| Software Companion Development | Enables subscription revenue streams from AI reconstruction algorithms unbundled from hardware sales. |
| Reimbursement Strategy | Aligns CMS CPT code coverage with teleradiology delivery mode expansion in rural markets. |
Research Methodology
Desk research of FDA 510(k) and premarket approval filings, CMS reimbursement schedules, and hospital procurement databases preceded structured interviews with radiology department chairs, biomedical equipment procurement managers, GPO contracts specialists, and teleradiology network operators. Secondary validation drew from American College of Radiology practice parameters, state certificate-of-need regulatory filings, and helium market trade data. Bottom-up equipment shipment analysis triangulated against top-down health system capital expenditure surveys.
Variance decomposition across product type, end user, technology, and delivery mode segmentation dimensions structured the analytical framework over the projection horizon. CAGRs derived from logistic diffusion curves for AI-enhanced imaging adoption, constrained by radiologist workforce growth limits and FDA clearance velocity assumptions. Modeled inputs incorporated health system consolidation trajectories in Texas, California, and Florida alongside teleradiology outsourcing elasticity in rural markets.
Underlying assumptions cover stable FDA software-as-a-medical-device framework continuity and helium supply chain resilience, with deviation risk concentrated in radiologist training pipeline constraints and CE marking reciprocity collapse impacts on European entrant competition. Revision becomes warranted when AI algorithm 510(k) clearance timelines exceed historical variance bands or certificate-of-need regulations expand beyond current state coverage.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Mexico Nuclear Imaging Market
Medical Imaging
Automated Contouring Radiotherapy Software Market
Medical Imaging
South America Mammography Market
Medical Imaging
South Africa Nuclear Imaging Market
Medical Imaging
UK Digital Radiology Market
Medical Imaging
Medical X-Ray Films Market
Medical Imaging
Preclinical MRI Equipment Market
Medical Imaging
Argentina Magnetic Resonance Imaging (MRI) Market
Medical Imaging
Smart X-Ray Detectors Market
Medical Imaging
Brazil Digital X-Ray Market
Medical Imaging
Canada Nuclear Imaging Market
Medical Imaging
Canada Magnetic Resonance Imaging (MRI) Market
Medical Imaging
Asia-Pacific Digital X-Ray Devices Market
Medical Imaging
Digital Breast Tomosynthesis Market
Medical Imaging
Orthopedic Radiology Equipment Market
Medical Imaging
Japan Digital Radiology Market