
 OTC Cat Medicines Market | 2026-2036
OTC Cat Medicines Market Size, Share, and Industry Trends Forecast 2026-2036
OTC Cat Medicines Market Analytics
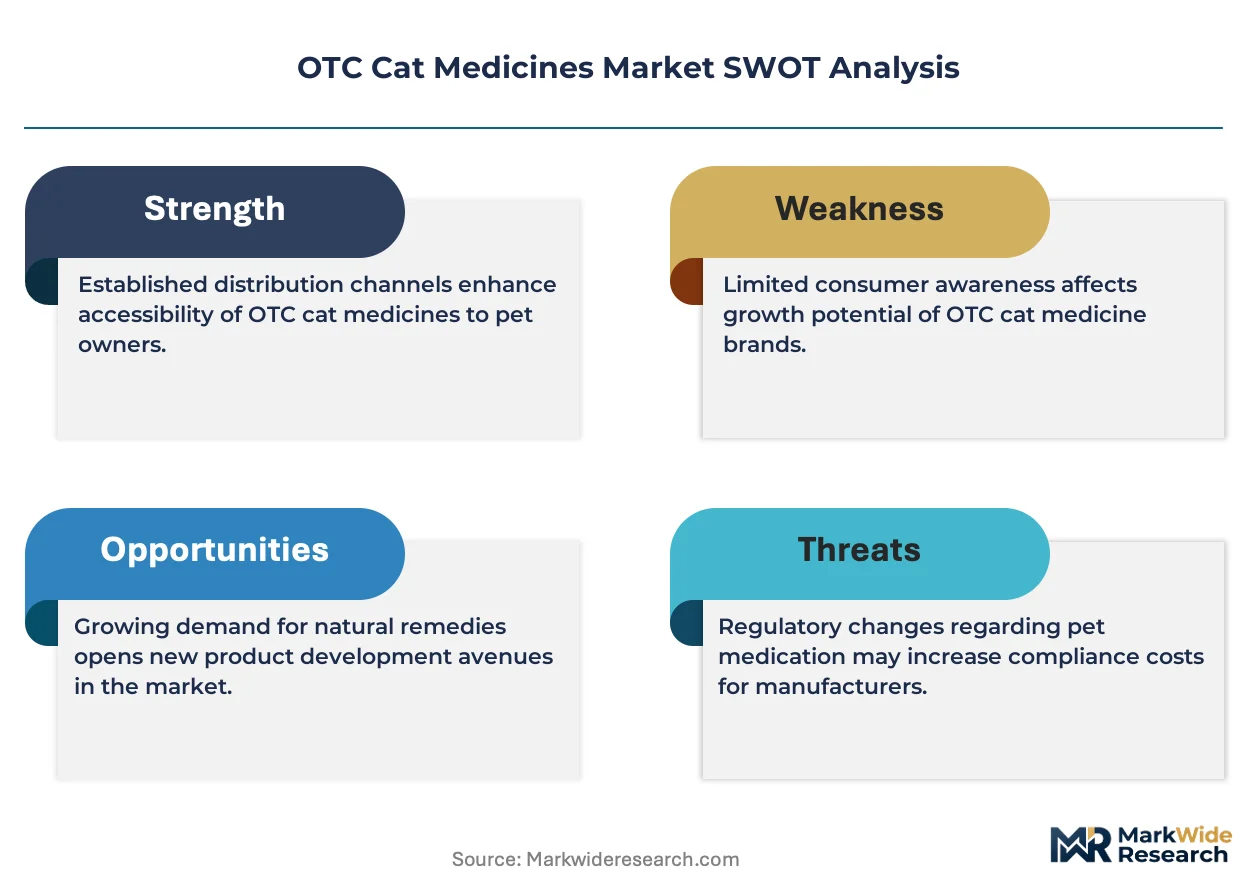
Pet specialty retail is fragmenting as e-commerce platforms and subscription services capture growing share of feline wellness spending. Zoetis leverages its veterinary heritage to sustain premium positioning across antiparasitic and supplement lines. Merck Animal Health anchors its OTC portfolio through broad distribution in veterinary clinics and farm-store networks. Boehringer Ingelheim competes via differentiated chewable formulations that address compliance challenges in cat administration.
OTC cat medicines comprise non-prescription therapeutics and prophylactics formulated for feline physiology, typically dosed by body weight and species-specific metabolism. These products employ palatability enhancers, enteric coatings, or transdermal matrices to overcome feline taste aversion and ensure therapeutic delivery. Antiparasitics and supplements dominate current revenue, with digestive aids representing the fastest-expanding category as microbiome science advances. Topical formulations command margin premiums due to manufacturing complexity and patent-protected delivery systems, while tablets and chews compete on price accessibility.
The FDA's Center for Veterinary Medicine regulates OTC claims and safety labeling, while state pharmacy boards govern retail pharmacy sales of animal health products. ISO standards for veterinary pharmaceutical manufacturing shape supplier qualification and cross-border trade access. Stakeholders must monitor evolving OTC classification boundaries as telehealth platforms and direct-to-consumer channels blur traditional veterinary oversight models.
Market Dynamics
Telehealth platforms and direct-to-consumer veterinary channels are dissolving traditional prescription gatekeeping, forcing incumbent manufacturers to rebuild distribution strategies around self-directed cat owners rather than clinic-dependent sales models.
Growth Catalysts
- Microbiome Science Advancement:Research into feline gut health is expanding the digestive aids category beyond basic fiber supplements toward targeted probiotic formulations with species-specific strains.
- EPA Pesticide Registration Streamlining:Accelerated review pathways for companion animal antiparasitics are compressing time-to-market for novel topical formulations.
- Pet Specialty Retail Expansion:Chewy and independent pet chains are building dedicated feline wellness sections that elevate OTC visibility beyond veterinary clinic shelves.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:China and India supply over 70 percent of veterinary API manufacturing, creating geopolitical and quality-control vulnerabilities for Western formulators.
- Feline Taste Aversion Biology:The Felidae family's bitter receptor sensitivity limits palatability engineering options and drives up R&D costs for oral delivery systems.
- State Pharmacy Board Fragmentation:Inconsistent retail pharmacy licensing for animal health products across US states complicates national distribution planning.
Strategic Opportunities
- Subscription Model Penetration:Auto-ship platforms for chronic-condition supplements (renal support, joint care) are capturing recurring revenue streams previously monopolized by veterinary dispensing.
- Transdermal Delivery Convergence:Combination of polymer science and feline behavioral research is enabling ear-tip absorption systems that bypass oral administration resistance entirely.
- USDA Organic Certification Tailwind:Growing consumer preference for natural inputs is creating premium positioning for plant-based antiparasitics and certified-organic supplements.
Industry Challenges
- Veterinary Pharmacology Talent Scarcity:Specialized expertise in feline metabolism and species-specific dosing remains concentrated among aging specialists with limited training pipeline replacement.
- ISO 17025 Laboratory Accreditation Timelines:Third-party testing facility certification delays are extending quality validation cycles for new product launches by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | OTC Cat Medicines Market |
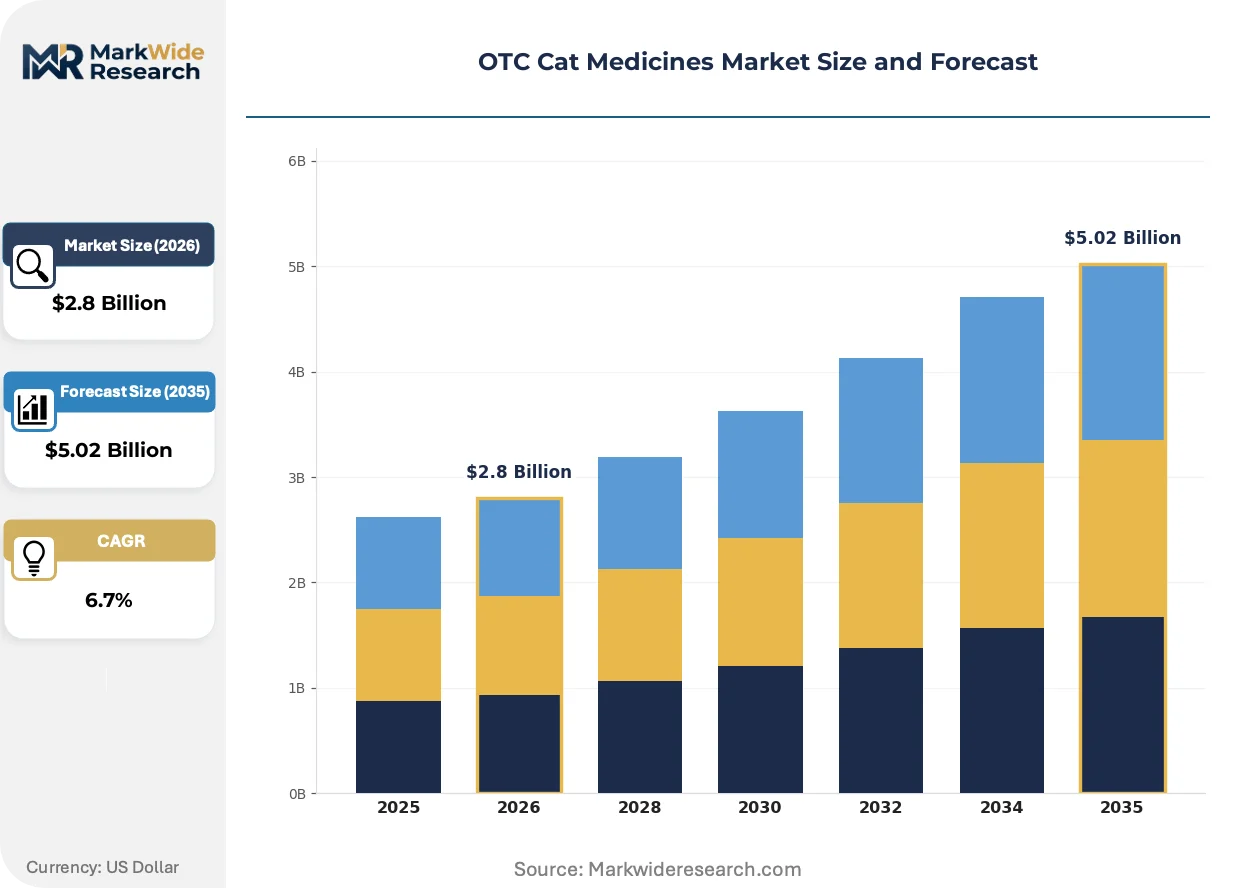
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antiparasitics, Supplements, Digestive Aids, Behavioral Aids Application: Flea Control, Worm Prevention, Joint Health, Stress Management Formulation: Tablets, Liquids, Chews, Topicals Distribution Channel: Veterinary Clinics, Online Retailers, Pet Stores, Pharmacies |
| Companies Covered | Zoetis, Merck Animal Health, Boehringer Ingelheim, Elanco, Ceva Santé Animale, Virbac, Bayer, Vetoquinol, Dechra Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
OTC Cat Medicines Market Evolving Landscape
Digital diagnostic tools and AI-powered symptom checkers are shifting the point of care decision from veterinarians to cat owners, creating demand for products that bridge the gap between self-assessment and professional intervention.
Transdermal gel matrix technology is virtualizing the administration experience for chronically medicated cats. Pet owners managing renal or thyroid conditions are adopting ear-tip applicators at accelerating rates. This virtualization is compressing the veterinary visit frequency for stable chronic cases and redirecting prescription refill economics toward retail channels.
The FDA Center for Veterinary Medicine's expanded enforcement discretion for certain telehealth prescribing relationships is relaxing traditional veterinary-client-patient relationship requirements. This regulatory recalibration enables asynchronous consultation models that pair digital triage with OTC product recommendations. Subscription services and farm-store networks are capturing the resulting prescription-to-OTC conversion volume.
Cat owner purchasing behavior is fragmenting across channel types rather than consolidating around single providers. Buyers now source antiparasitics through veterinary clinics, supplements via direct-to-consumer platforms, and acute symptom relievers through mass retail. This channel diversification is most pronounced in US metropolitan markets where same-day delivery infrastructure supports impulse-driven health purchases.
OTC Cat Medicines Market Segmentation
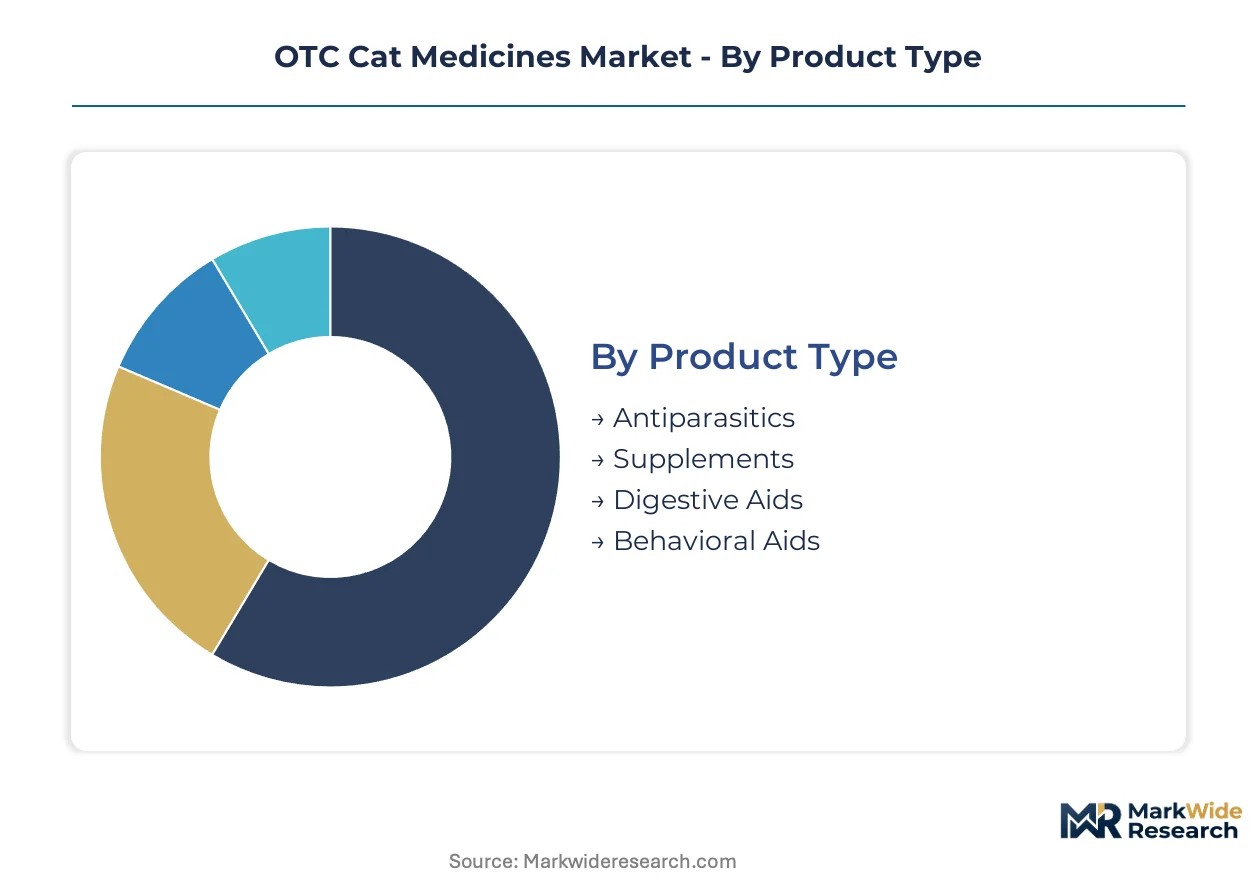
Segmentation in OTC cat medicines reveals divergent margin profiles and channel strategies. Product type determines regulatory pathway complexity, while formulation choice directly impacts compliance rates among feline patients. Understanding these divides enables manufacturers to align R&D investment with purchase behavior patterns.
Product Type:
Antiparasitics turn inventory fastest due to seasonal demand spikes and preventive dosing schedules. Supplements rotate slowest as chronic-condition products build recurring subscription bases.
- Antiparasitics:Formulations targeting fleas, ticks, and heartworm employ isoxazoline compounds or macrocyclic lactones calibrated for feline hepatic metabolism. Demand clusters in southern US states with extended parasite seasons, driven by EPA registration streamlining that accelerates novel topical launches.
- Supplements:Renal support, omega fatty acid, and joint care formulations target aging cat populations with chronic maintenance needs. Expansion concentrates in direct-to-consumer channels where auto-ship models capture recurring revenue previously held by veterinary dispensing.
- Digestive Aids:Probiotic and fiber-based gastrointestinal products leverage advancing microbiome science for species-specific strain formulations.
- Behavioral Aids:Pheromone diffusers and calming supplements address feline stress responses in multi-pet households and urban environments.
Antiparasitics dominate installed base. Digestive aids are where expansion concentrates.
Application:
Cost tier stratification separates premium preventive regimens from economy acute treatments. Flea control commands highest per-dose pricing due to year-round compliance requirements.
- Flea Control:Monthly topical or oral formulations prevent Ctenocephalides felis infestations through insect growth regulators or neurotoxic agents. Metropolitan markets with indoor-outdoor cat populations sustain volume, pressured by generic erosion in mature active ingredients.
- Worm Prevention:Broad-spectrum anthelmintics target Toxocara cati and Ancylostoma species with quarterly or monthly dosing protocols. Rural and suburban geographies with hunting cats drive demand, constrained by API concentration in Asian manufacturing hubs.
- Joint Health:Glucosamine and chondroitin formulations target geriatric feline mobility decline.
- Stress Management:Environmental and nutritional interventions address urinary and behavioral manifestations of feline anxiety.
Flea control dominates installed base. Joint health is climbing the fastest.
Formulation:
Volume concentration favors oral formats, while margin accrues to delivery innovations that overcome species-specific administration barriers.
- Topicals:Transdermal pipettes and spot-on solutions bypass feline taste aversion through sebaceous gland absorption. Premium positioning in veterinary clinics persists, though farm-store and online channels gain share through private-label alternatives.
- Chews:Palatable soft-moist matrices embed actives within hydrolyzed protein bases that mask bitter receptor triggers. Pet specialty retailers prioritize these for compliance advantages in multi-pet households.
- Tablets:Compressed single-entity or layered formulations compete on price accessibility in mass retail.
- Liquids:Suspensions and solutions enable precise weight-based dosing for kittens and geriatric cats with dental compromise.
Tablets dominate installed base. Topicals are gaining share fastest.
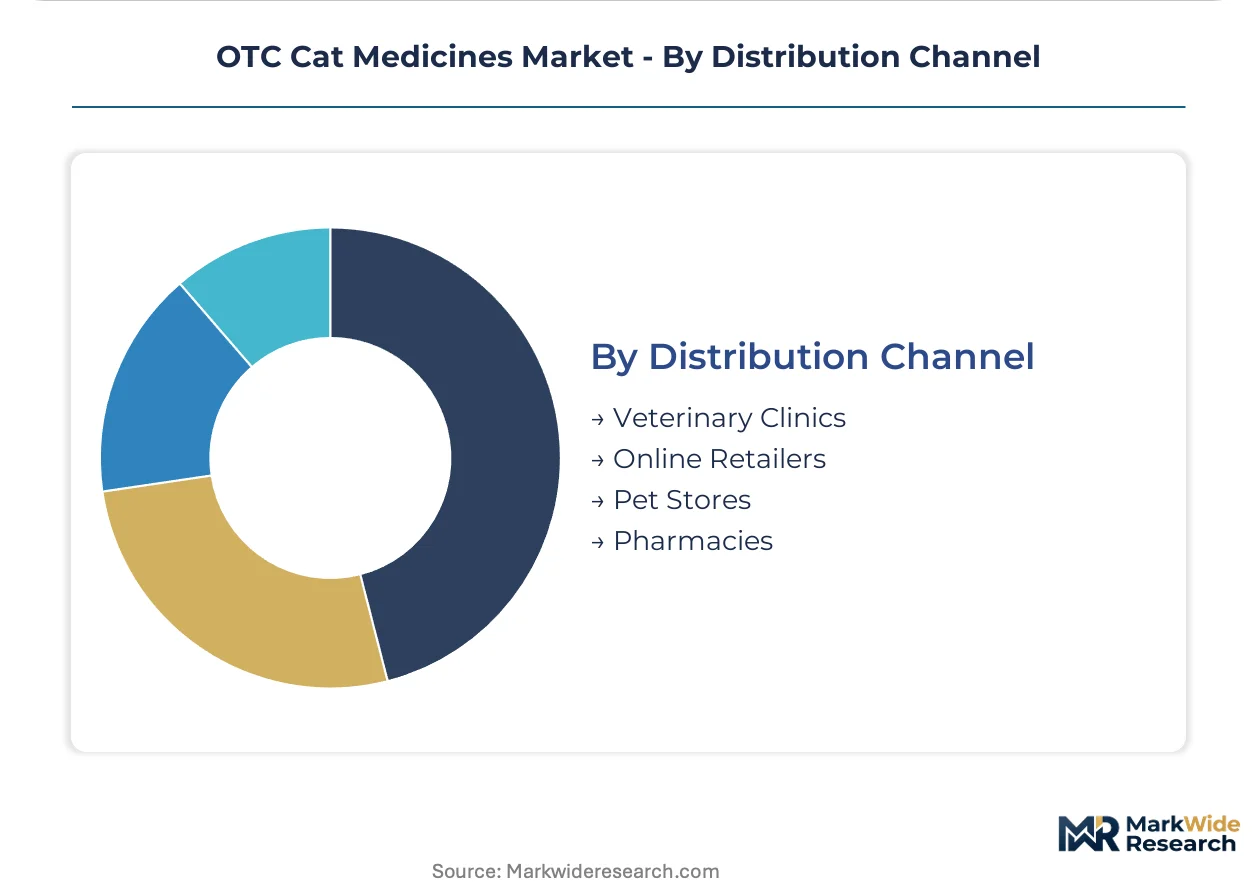
Distribution Channel:
Customer type fragmentation splits procurement between professional-guided and self-directed purchase journeys. Channel choice correlates with condition acuity and owner confidence levels.
- Online Retailers:Chewy and Amazon aggregate subscription auto-ship volumes for chronic-condition products with predictable replenishment cycles. Same-day delivery infrastructure in metropolitan markets supports impulse-driven acute symptom purchases.
- Veterinary Clinics:Professional recommendation anchors antiparasitic and prescription-to-OTC conversion volumes. Clinic dispensing retains premium positioning through VCPR-established trust relationships.
- Pet Stores:Dedicated feline wellness sections in specialty chains elevate supplement visibility beyond veterinary shelves.
- Pharmacies:Human retail pharmacy participation remains fragmented across state-level animal health licensing variations.
Veterinary clinics dominate installed base. Online retailers are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FDA's Center for Veterinary Medicine anchors regulatory oversight in the United States, the dominant geography for OTC cat medicine consumption. Demand concentrates in North America and Western Europe, with emerging expansion in Asia-Pacific metropolitan markets.
United States
High pet ownership rates and premiumization of feline wellness drive demand for antiparasitics and digestive aids. The FDA's Center for Veterinary Medicine oversees OTC approval pathways and labeling requirements for companion animal products. Metropolitan clusters in California and Texas sustain volume through same-day delivery infrastructure supporting impulse-driven health purchases.
Germany
Aging cat populations and veterinary clinic density sustain chronic-condition supplement demand. The Federal Office of Consumer Protection and Food Safety (BVL) coordinates with EMA guidelines for veterinary pharmaceutical distribution. Industrial concentration in Bavaria and North Rhine-Westphalia hosts formulation facilities serving Central European markets.
United Kingdom
Subscription service penetration and direct-to-consumer platform adoption accelerate channel shift away from clinic-dependent models. The Veterinary Medicines Directorate (VMD) governs OTC classification and retail pharmacy licensing for animal health products. Greater London and Southeast England anchor e-commerce fulfillment networks for feline wellness products.
France
Multi-pet household prevalence and urban cat density sustain behavioral aid and stress management product demand. ANSM coordinates veterinary pharmaceutical oversight with EU regulatory frameworks. The Île-de-France region concentrates distribution logistics for domestic and export markets.
Japan
Metropolitan pet humanization trends and geriatric feline care needs expand renal support and joint health categories. PMDA and MAFF jointly regulate veterinary OTC product safety and efficacy claims. The Kanto region around Tokyo hosts specialized retail chains elevating feline wellness visibility.
OTC Cat Medicines Market Competitive Landscape
Veterinary heritage conglomerates and diversified pharmaceutical groups split the market between prescription-to-OTC conversion capabilities and consumer-facing brand equity. The structure concentrates around three archetypes: legacy animal health specialists with clinic channel dominance, human pharmaceutical divisions leveraging manufacturing scale, and independent regional formulators competing on price accessibility. M&A activity targets microbiome science capabilities and transdermal delivery patents, while strategic partnerships with telehealth platforms reshape distribution economics.
Among veterinary heritage specialists, Zoetis and Merck Animal Health exemplify the clinic-anchored archetype with sustained premium positioning across antiparasitic lines. Boehringer Ingelheim occupies a differentiated position through formulation innovation addressing feline administration compliance challenges. These three entities represent distinct strategic vectors: Zoetis anchors subscription and specialty retail penetration, Merck leverages broad veterinary clinic and farm-store networks, while Boehringer Ingelheim competes through palatability engineering and delivery system patents.
| Leading Market Players |
|---|
| Zoetis |
| Merck Animal Health |
| Boehringer Ingelheim |
| Elanco |
| Ceva Santé Animale |
| Virbac |
| Bayer |
| Vetoquinol |
| Dechra Pharmaceuticals |
| Others |
Value Network & Pricing Analysis
Trans-Pacific container freight corridors from Shanghai to Long Beach transmit cost volatility directly into API procurement economics, compressing margin buffers for Western formulators while enabling tiered pricing stratification between premium veterinary-branded and economy private-label offerings.
Pricing Analysis
The customization-premium spread separates standard tablet formulations from species-specific transdermal delivery systems, with the latter commanding substantial markups due to polymer engineering complexity and patent-protected absorption matrices. Three-tier pricing structure across premium, standard, and economy levels reflects brand heritage, FDA registration status, and channel positioning. Price erosion runs through mature antiparasitic categories where generic isoxazoline compounds displace originator products. Mass retail buyers exhibit highest price sensitivity, while veterinary clinic procurement prioritizes compliance guarantees over per-unit cost.
Supply Chain Analysis
Supplier-financing facilities extended by Indian and Chinese API manufacturers allow Western formulators to manage working capital through 90-120 day payment terms, though this dependency concentrates risk. Active pharmaceutical ingredient production draws from China, India, and limited European specialty chemical hubs. Veterinary pharmaceutical manufacturing rests on isoxazoline precursors, macrocyclic lactone intermediates, and enteric coating polymers. Single-source vulnerability in feline-specific probiotic strain cultivation threatens digestive aid expansion timelines. Distribution runs through veterinary clinic networks, farm-store cooperatives, and direct-to-consumer platforms with divergent margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through subscription platform consolidation, with Chewy and Amazon aggregating sufficient chronic-condition supplement volume to extract preferential terms from manufacturers previously anchored to clinic dispensing.
For Market Incumbents: Harden clinic channel control through exclusive formulation partnerships that preempt prescription-to-OTC conversion leakage. Deepen backward integration into transdermal polymer production to defend margin position against generic topical erosion. The telehealth platform threat demands asynchronous consultation bundling with auto-ship logistics. For New Entrants and Emerging Players: Build out USDA Organic certified supplement lines targeting metropolitan markets where pet humanization trends sustain premium positioning. The digestive aids category offers lowest competitive density among established players. Direct-to-consumer microbiome testing integration provides differentiated customer acquisition economics. For Investors and Strategic Acquirers: Transdermal delivery patent portfolios represent the most defensible acquisition target archetype given formulation complexity barriers and chronic-condition virtualization trends. Long-term viability hinges on subscription retention rates rather than transactional volume capture. Watch FDA enforcement discretion expansion as the inflection signal for telehealth-OTC convergence acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Transdermal Delivery Patent Acquisition | Polymer matrix IP from human pharmaceutical spinouts enables feline administration compliance advantages. |
| Subscription Platform Partnership | Chewy auto-ship integration captures recurring revenue streams from renal support and joint care categories. |
| USDA Organic Certification Program | Plant-based antiparasitic positioning aligns with metropolitan consumer preference shifts toward natural inputs. |
| Telehealth Platform Integration | Asynchronous veterinary consultation models pair digital triage with OTC product recommendations. |
| Microbiome Science Capability Buildout | Species-specific probiotic strain development differentiates digestive aid offerings beyond generic fiber supplements. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with veterinary pharmacology specialists, pet specialty retail category managers, FDA regulatory affairs consultants, and telehealth platform product strategists. Secondary validation drew from FDA Center for Veterinary Medicine approval databases, EPA pesticide registration filings, state pharmacy board licensing records, and ISO 17025 laboratory accreditation directories. Bottom-up volume estimates from product-level channel flows were triangulated against top-down category spending aggregates.
Calibration against historical approval timelines and channel shift patterns anchored the analytical framework across the analysis window. Segmentation dimensions modeled include product type, formulation technology, distribution channel architecture, and regional regulatory cluster. CAGRs were derived from regression analysis of category growth trajectories adjusted for demographic pet ownership trends and premiumization indices. Forecast inputs incorporated EPA registration pipeline velocity and telehealth regulatory evolution scenarios.
The forecast holds incumbent behavior within observed patterns; aggressive moves by direct-to-consumer platform entrants or API supply chain reconfigurations would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Veterinary Equipment and Supplies Market
Veterinary
Germany Veterinary Healthcare Market
Veterinary
Clonorchiasis Market
Veterinary
Veterinary Wound Sprays Market
Veterinary
ASEAN Poultry Vaccines Market
Veterinary
Global Veterinary Rapid Test Market
Veterinary
Veterinary Home Diagnostics Market
Veterinary
Asia-Pacific Veterinary Vaccine Market
Veterinary
Global Veterinary Monitoring Equipment Market
Veterinary
Veterinary Antibiotics Market
Veterinary
US Surgical Pet Collar Market
Veterinary
Veterinary Vaccine Adjuvants Market
Veterinary
Animal Antibiotics Market
Veterinary
Global Livestock Vaccines Market
Veterinary
Europe Veterinary Antibiotics Market
Veterinary
Companion Animal Vaccines Market