
 Medical Holography Market | 2026-2036
Medical Holography Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Holography Market Analysis
Modular platform bundling of holographic displays with surgical navigation software is realigning hospital procurement economics. RealView Imaging Ltd. leverages its cardiac imaging specialization to anchor premium pricing in interventional cardiology suites. EchoPixel, Inc. competes through FDA-cleared diagnostic tools that extend into patient-specific anatomical modeling. Holoxica Ltd. differentiates via holographic microscopy systems that occupy research-intensive medical universities in the United Kingdom and Singapore.
Medical holography employs laser interference recording and wavefront reconstruction to generate three-dimensional volumetric visualizations of patient anatomy without specialized eyewear, typically operating at visible wavelengths with spatial resolutions reaching sub-micron scales in microscopy configurations. Holographic imaging and holographic displays command the dominant installed base among technology segments, though holographic microscopy sustains the highest R&D intensity as pathology workflows demand quantitative phase imaging capabilities. Diagnostic tools lead product type revenue, yet surgical planning applications represent the fastest-expanding margin pool as preoperative visualization shifts from two-dimensional imaging to interactive volumetric manipulation.
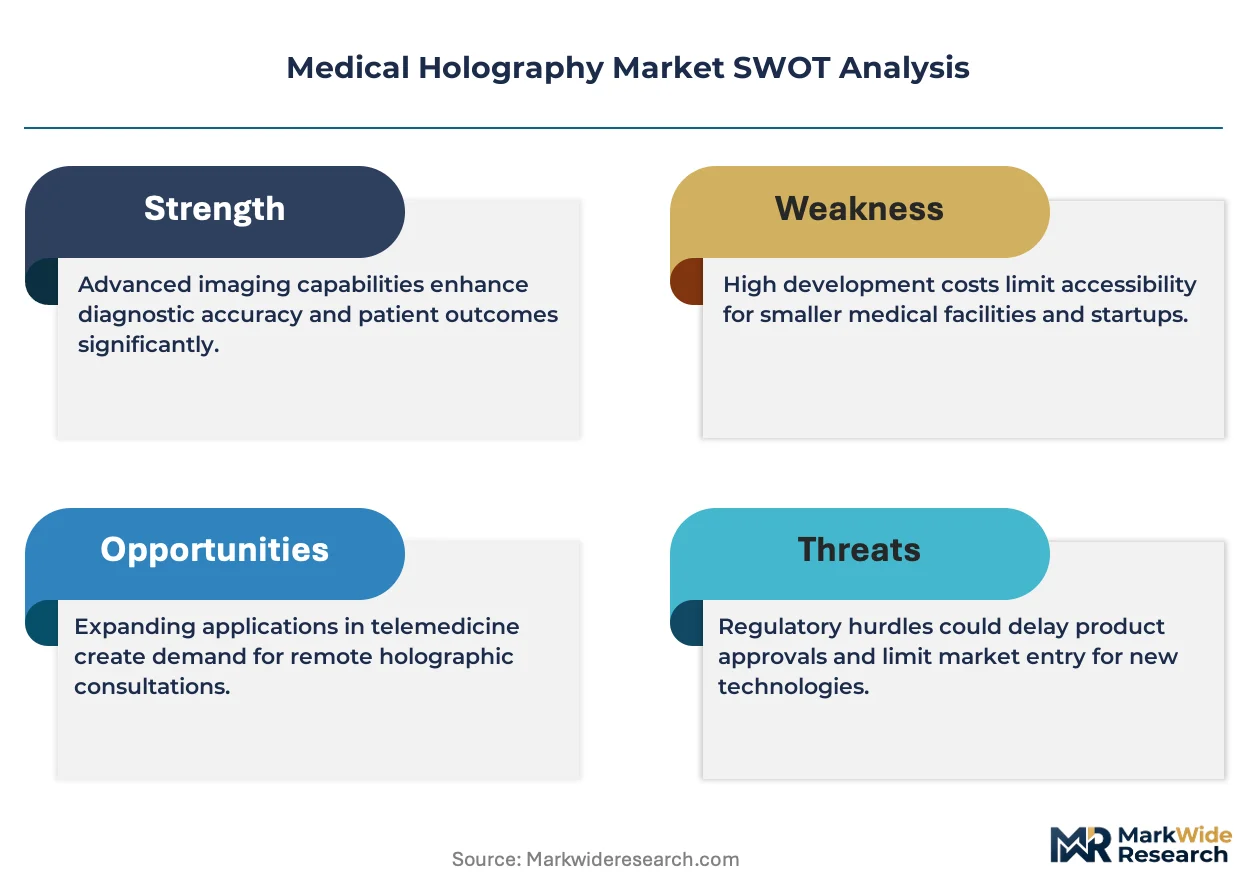
FDA 510(k) and De Novo pathways govern holographic device market access in the United States, while the EU MDR and CE marking requirements impose clinical evidence standards that favor established players with notified body relationships. Japan's PMDA evaluates holographic surgical planning tools under its Sakigake fast-track designation, accelerating approval for systems demonstrating superior spatial accuracy over conventional imaging. Stakeholders must monitor evolving software-as-medical-device classifications across these jurisdictions, as regulatory divergence between FDA predicate-based logic and EU MDR risk-classification rules will determine which product architectures achieve multi-region scalability.
Market Dynamics
Reimbursement frameworks for holographic surgical planning systems are accelerating hospital procurement cycles across North America and Western Europe, compressing the traditional sales timeline from pilot evaluation to enterprise deployment.
Growth Catalysts
- FDA 510(k) Pathway Streamlining:The FDA's predicate-based clearance logic for holographic diagnostic tools reduces regulatory friction for vendors with established device histories, accelerating market entry for software-as-medical-device architectures.
- Interventional Cardiology Suites:Cardiac imaging specialization commands premium pricing power as electrophysiology labs integrate holographic visualization into catheter ablation workflows.
- Japan's Sakigake Fast-Track:PMDA's accelerated approval designation for systems demonstrating superior spatial accuracy over conventional imaging is pulling holographic surgical planning tools into Tokyo's academic medical centers ahead of Western adoption curves.
Market Restraints
- Laser Component Supply Concentration:Specialized visible-wavelength laser sources for holographic display modules concentrate among German and Japanese optical component suppliers, creating input vulnerability.
- EU MDR Clinical Evidence Burden:The Medical Device Regulation's risk-classification rules for software-as-medical-device impose documentation requirements that favor established players with notified body relationships, raising competitive barriers.
- Conventional 3D Visualization Substitution:Stereoscopic displays and VR headsets compete for capital allocation in budget-constrained hospital imaging departments, particularly in secondary care settings.
Strategic Opportunities
- Pathology Workflow Integration:Quantitative phase imaging capabilities in holographic microscopy systems address unmet demand in cancer diagnostics, with research-intensive medical universities in Singapore and the United Kingdom anchoring early reference sites.
- Modular Platform Bundling:Surgical navigation software paired with holographic displays creates new procurement economics, allowing vendors to penetrate interventional suites through software-first contracts.
- IRAs Hospital Infrastructure Provisions:United States federal funding for rural hospital technology modernization creates deployment opportunities outside academic medical center concentrations.
Industry Challenges
- Computational Optics Talent Scarcity:Wavefront reconstruction algorithm development requires specialized expertise at the intersection of physics and biomedical engineering, constraining R&D velocity for mid-tier vendors.
- Legacy PACS Integration Complexity:Hospital picture archiving and communication systems operate on DICOM standards that require custom middleware development for holographic data formats, extending implementation timelines.
- Multi-Jurisdictional Software Classification Divergence:FDA predicate-based logic and EU MDR risk-classification rules produce incompatible product architecture requirements, fragmenting engineering roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Holography Market |
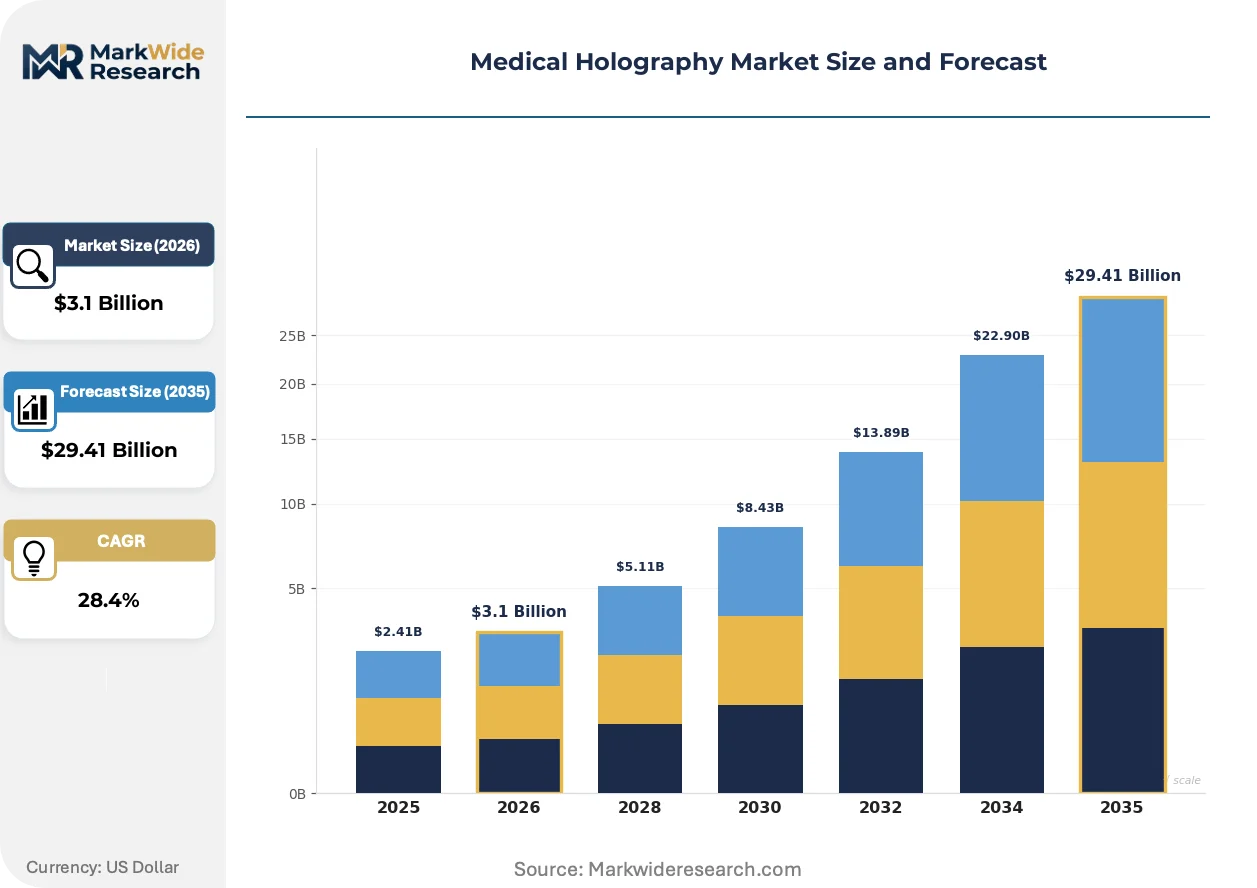
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $29.41 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Holographic Microscopy, Holographic Imaging, Holographic Displays, Portable Holograms Product Type: Diagnostic Tools, Surgical Planning, Patient-Specific Models, Educational Simulators End User: Hospitals, Research Institutions, Medical Universities, Rehabilitation Centers Application: Preoperative Visualization, Medical Training, Patient Consultation, Complex Surgeries |
| Companies Covered | EchoPixel, Inc., RealView Imaging Ltd., Holoxica Ltd., Mach7 Technologies Pte. Ltd., Ovizio Imaging Systems, zSpace, Inc., Zebra Imaging, Lyncée Tec, EON Reality, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Holography Market Emerging Trajectories
Computational holography is migrating from research laboratory environments into clinical workflows, with three distinct vectors reshaping how three-dimensional patient anatomy reaches surgical decision-makers.
Light-field display technology is decentralizing the hardware requirements for holographic visualization. These systems generate volumetric images through micro-lens arrays and directional backlighting, eliminating the laser interference recording apparatus that previously confined deployment to specialized facilities. Community hospitals in Germany and the United States are piloting compact light-field units for preoperative planning, collapsing the capital barrier that historically limited adoption to academic medical centers. The technology is decentralizing surgical planning authority from centralized radiology departments into individual specialty suites.
The EU MDR's software-as-medical-device classification is restructuring vendor commercialization strategies. CE marking requirements now demand clinical evidence standards for holographic diagnostic algorithms that previously operated in regulatory gray zones, forcing architecture redesigns toward locked-down, validated software configurations. European notified bodies are prioritizing holographic microscopy systems for pathology applications, compressing approval timelines for quantitative phase imaging tools while extending scrutiny periods for surgical planning software.
Hospital procurement committees are unbundling after-sales service from hardware acquisition, demanding software subscription models with predictable annual expenditures. This pattern disrupts the traditional capital equipment sales cycle that dominated holographic display vendors, replacing lump-sum transactions with recurring revenue frameworks. Academic medical centers in Japan and the United States are leading this contractual evolution, using their purchasing scale to extract performance-guarantee clauses that tie vendor payments to spatial accuracy benchmarks.
Medical Holography Market Segmentation
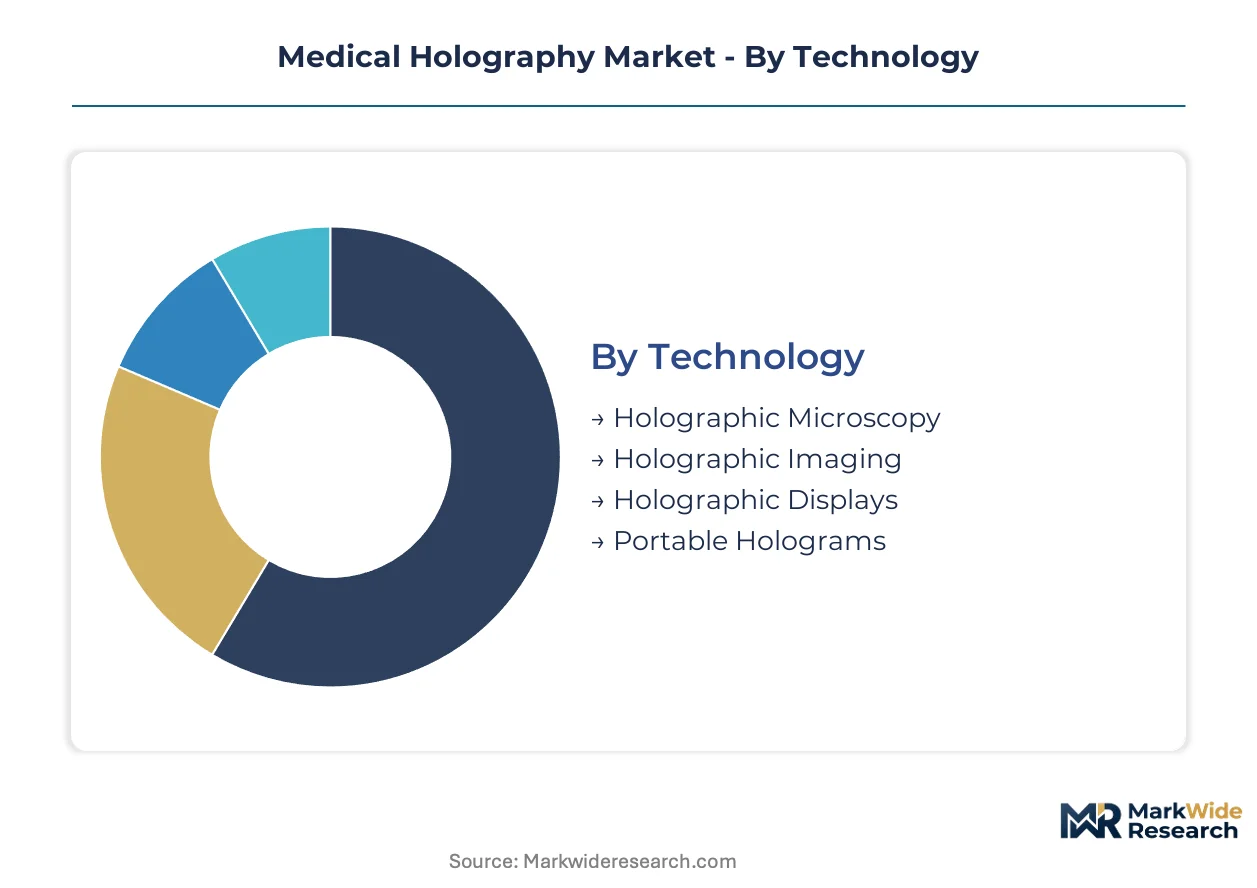
Segmentation in medical holography reveals how technology architecture, clinical workflow integration, and procurement authority distribute across healthcare institutions. Vendors must align product roadmaps with the specific validation requirements and budget cycles governing each segment.
Technology:
Laser interference recording and wavefront reconstruction capabilities differentiate performance tiers across holographic hardware platforms.
- Holographic Microscopy:Quantitative phase imaging enables sub-micron resolution pathology workflows. Research-intensive medical universities in Singapore and the United Kingdom anchor procurement as cancer diagnostics demand advances.
- Holographic Displays:Volumetric visualization without specialized eyewear commands premium positioning in interventional cardiology suites. Electrophysiology labs in Germany and the United States integrate these systems into catheter ablation workflows.
- Holographic Imaging:Laser-based recording systems generate three-dimensional patient anatomy for surgical planning applications.
- Portable Holograms:Compact light-field units using micro-lens arrays reduce capital barriers for community hospital deployment.
Holographic Displays lead on scale; Portable Holograms lead on momentum.
Product Type:
Regulatory pathway complexity and reimbursement status shape margin structures across product categories.
- Diagnostic Tools:FDA 510(k) clearance and EU MDR CE marking govern algorithm validation requirements. European notified bodies prioritize quantitative phase imaging systems, compressing approval timelines for pathology applications.
- Surgical Planning:Interactive volumetric manipulation shifts preoperative visualization from two-dimensional imaging. Japan's PMDA Sakigake fast-track designation accelerates hospital procurement in Tokyo's academic medical centers.
- Patient-Specific Models:Anatomical modeling extends diagnostic utility into personalized surgical preparation.
- Educational Simulators:Training applications operate with reduced regulatory burden compared to clinical tools.
Diagnostic Tools lead on scale; Surgical Planning leads on momentum.
End User:
Purchasing authority and capital allocation timelines fragment demand across institutional types.
- Hospitals:Reimbursement frameworks for holographic surgical planning compress procurement cycles from pilot evaluation to enterprise deployment. North American and Western European facilities accelerate adoption as payment models evolve.
- Research Institutions:R&D funding priorities determine holographic microscopy acquisition. National science foundations in Germany and Japan sustain instrumentation budgets.
- Medical Universities:Educational missions drive simulator procurement alongside research applications.
- Rehabilitation Centers:Patient consultation tools support therapeutic planning with lower capital thresholds.
Hospitals lead on scale; Research Institutions lead on momentum.
Application:
Clinical workflow integration depth determines technology specification requirements and vendor selection criteria.
- Preoperative Visualization:Interactive volumetric manipulation demands high spatial accuracy benchmarks. Academic medical centers in Japan and the United States extract performance-guarantee clauses tying vendor payments to accuracy metrics.
- Complex Surgeries:Real-time holographic guidance integrates with surgical navigation software. Interventional suites bundle displays with planning platforms to realign procurement economics.
- Medical Training:Educational deployment tolerates reduced resolution specifications compared to clinical applications.
- Patient Consultation:Communication-focused visualization prioritizes intuitive interface design over technical performance.
Preoperative Visualization leads on scale; Complex Surgeries leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical holography traces its clinical commercialization to German optical engineering laboratories and Japanese precision manufacturing centers, with both countries maintaining foundational roles in laser interference systems and wavefront reconstruction hardware.
Germany
Electrophysiology labs in Munich and Berlin integrate holographic displays into catheter ablation workflows, driving procurement in interventional cardiology suites. The EU MDR's software-as-medical-device classification imposes clinical evidence standards that favor established players with notified body relationships. Baden-Württemberg's precision optics cluster supplies specialized visible-wavelength laser sources for holographic display modules.
United States
Academic medical centers in Boston and Houston extract performance-guarantee clauses tying vendor payments to spatial accuracy benchmarks. FDA 510(k) and De Novo pathways govern holographic device market access, reducing regulatory friction for vendors with established device histories. Federal funding through IRA hospital infrastructure provisions creates deployment opportunities in rural facilities outside traditional academic concentrations.
Japan
Tokyo's academic medical centers anchor early adoption of holographic surgical planning tools through PMDA's Sakigake fast-track designation. METI instrumentation budgets sustain R&D funding for holographic microscopy at national science foundations. The Kansai region's medical device manufacturing base supports component supply for compact light-field units.
United Kingdom
Research-intensive medical universities in London and Cambridge procure holographic microscopy systems for quantitative phase imaging in cancer diagnostics. The MHRA operates transitional arrangements for EU MDR-aligned devices while establishing independent software-as-medical-device classification rules. Scotland's photonics research corridor contributes algorithm development for wavefront reconstruction.
Singapore
National University Hospital and Singapore General Hospital pilot holographic surgical planning for complex hepatobiliary procedures. The Health Sciences Authority evaluates holographic diagnostic tools under its medical device risk-classification framework. Biopolis research campus hosts pathology workflow integration trials for quantitative phase imaging systems.
Medical Holography Market Vendor Landscape
The competitive structure tilts toward technology specialists with regulatory clearance histories. The vendor base separates into distinct capability tiers: established players with multi-jurisdictional approvals, mid-tier firms with single-market clearances, and research-stage entities lacking commercial deployment. Three archetypes dominate: cardiac imaging specialists commanding premium positioning, diagnostic algorithm developers pursuing software-first contracts, and microscopy innovators targeting academic research funding. Competitive moves concentrate on strategic partnerships with surgical navigation platforms and technology licensing agreements for light-field display modules.
Among Israel-based holographic specialists, RealView Imaging Ltd. exemplifies the cardiac imaging archetype through its interventional cardiology focus. EchoPixel, Inc. occupies a position within the diagnostic tools tier, with its FDA clearance history representing the predicate-based market access pathway. Holoxica Ltd. anchors the microscopy research segment, reflecting the United Kingdom's concentration in holographic pathology applications. These three entities collectively illustrate how geographic origin and regulatory positioning shape competitive differentiation in holographic visualization systems.
| Leading Market Players |
|---|
| EchoPixel, Inc. |
| RealView Imaging Ltd. |
| Holoxica Ltd. |
| Mach7 Technologies Pte. Ltd. |
| Ovizio Imaging Systems |
| zSpace, Inc. |
| Zebra Imaging |
| Lyncée Tec |
| EON Reality |
| Others |
Supply Flow & Price Mechanics
Academic medical centers in Japan and the United States anchor procurement authority through performance-guarantee contracts that tie vendor payments to spatial accuracy benchmarks, compressing traditional capital equipment sales into software subscription models with predictable annual expenditures.
Pricing Analysis
Three-tier pricing structure across premium holographic microscopy, standard surgical planning suites, and economy light-field displays separates vendors by FDA clearance tier and after-sales bundling intensity. Premium cardiac imaging systems command valuation multiples over standard diagnostic tools due to interventional cardiology workflow integration. Cost compression in economy-tier portable units intensifies as micro-lens array manufacturing scales in German and Japanese optical clusters. Community hospitals exhibit highest price sensitivity, while Tokyo's academic medical centers prioritize spatial accuracy over procurement cost.
Supply Chain Analysis
Computational optics talent scarcity in Baden-Württemberg and the Kansai region constrains wavefront reconstruction algorithm development velocity, creating recruitment competition between holographic display vendors and precision instrumentation incumbents. Specialized visible-wavelength laser sources concentrate among German and Japanese optical component suppliers, drawing from precision manufacturing heritage in both geographies. Single-source vulnerability in laser interference recording apparatus creates input risk for holographic imaging system assembly. Distribution runs through surgical navigation platform partnerships that bundle displays with planning software.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medical holography offers margin expansion as light-field display technology collapses hardware capital barriers while software-as-medical-device subscriptions generate recurring revenue streams.
For Market Incumbents: Acquire computational optics talent pools in Scotland's photonics research corridor and Singapore's Biopolis campus to secure wavefront reconstruction algorithm development capacity. Defend against stereoscopic display substitution by locking hospital GPO contracts through multi-year software subscription anchoring. Priority lever: FDA 510(k) predicate stacking to accelerate diagnostic tool clearances ahead of EU MDR clinical evidence requirements. For New Entrants and Emerging Players: The premium-economy price-point gap in holographic surgical planning creates entry space for compact light-field units targeting community hospitals in Germany and United States rural facilities. White-space targets: rehabilitation center patient consultation tools with reduced regulatory burden, and pathology workflow integration at research-intensive medical universities in the United Kingdom. Go-to-market angle: software-first contracts unbundled from hardware acquisition. For Investors and Strategic Acquirers: Surgical navigation platform developers are the most active acquirer in this space, seeking holographic display integration to complete interventional suite bundling. Long-term viability hinges on multi-jurisdictional software classification harmonization between FDA predicate logic and EU MDR risk tiers. Acquisition target archetype: mid-tier firms with single-market clearances and locked-down validated software configurations. Signal to watch: PMDA Sakigake designation expansions beyond Tokyo academic centers.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Stacking | Accelerates diagnostic tool clearances using established device predicates. |
| EU MDR CE Marking Investment | Notified body relationships compress approval timelines for pathology applications. |
| Hospital System Partnership | GPO contracts lock procurement cycles through multi-year software subscriptions. |
| Software Companion Development | Locked-down validated configurations address EU MDR clinical evidence demands. |
| Reimbursement Strategy | Evolving payment models for holographic surgical planning compress sales timelines. |
Methodological Framework
Direct dialogue with hospital purchasing committees, biomedical engineers, interventional cardiologists, and GPO contracts managers grounds qualitative assessment in procurement authority dynamics. Secondary validation draws from FDA 510(k) filings, EU MDR notified body documentation, PMDA Sakigake designations, and hospital procurement databases. Bottom-up and top-down triangulation cross-checks vendor shipment data against academic medical center deployment tracking.
Bottom-up modeling builds from technology segment adoption curves, product type regulatory pathway timelines, and end-user capital allocation patterns across the projection horizon. Segmentation dimensions include holographic microscopy versus display versus imaging technology, diagnostic tools versus surgical planning product type, and hospital versus research institution end-user. CAGRs derive from spatial accuracy benchmark improvements and reimbursement framework evolution. Industry-specific inputs: laser component supply concentration indices and computational optics talent pipeline data.
Caveats apply where FDA software-as-medical-device reclassification or EU MDR risk-tier adjustments could materially shift the outlook. Forecasts reflect assumptions on holographic surgical planning reimbursement expansion and light-field display manufacturing scale. Material deviation in laser source supply stability or multi-jurisdictional software classification divergence warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Middle East and Africa Mammography Market
Medical Imaging
France Nuclear Imaging Market
Medical Imaging
Europe Mobile Tomography Market
Medical Imaging
Magnetic Resonance Imaging Equipment Coils Market
Medical Imaging
AI-Enabled Diagnostic Imaging Market
Medical Imaging
Radiation Dose Management Market
Medical Imaging
Spain Digital X-Ray Market
Medical Imaging
3D Medical and Surgical Imaging Platform Market
Medical Imaging
Africa Nuclear Imaging Market
Medical Imaging
Urology Imaging Systems Market
Medical Imaging
China Computed Tomography Market
Medical Imaging
Diagnostic X-Ray System Market
Medical Imaging
Point of Care (POC) CT Imaging Systems Market
Medical Imaging
Meningitis Imaging Market
Medical Imaging
Global CT Scanners Market
Medical Imaging
Asia-Pacific Digital X-Ray Devices Market