
 Netherlands Pharmaceutical Market | 2026-2036
Netherlands Pharmaceutical Market Size, Share, and Industry Trends Forecast 2026-2036
Netherlands Pharmaceutical Market Foresight
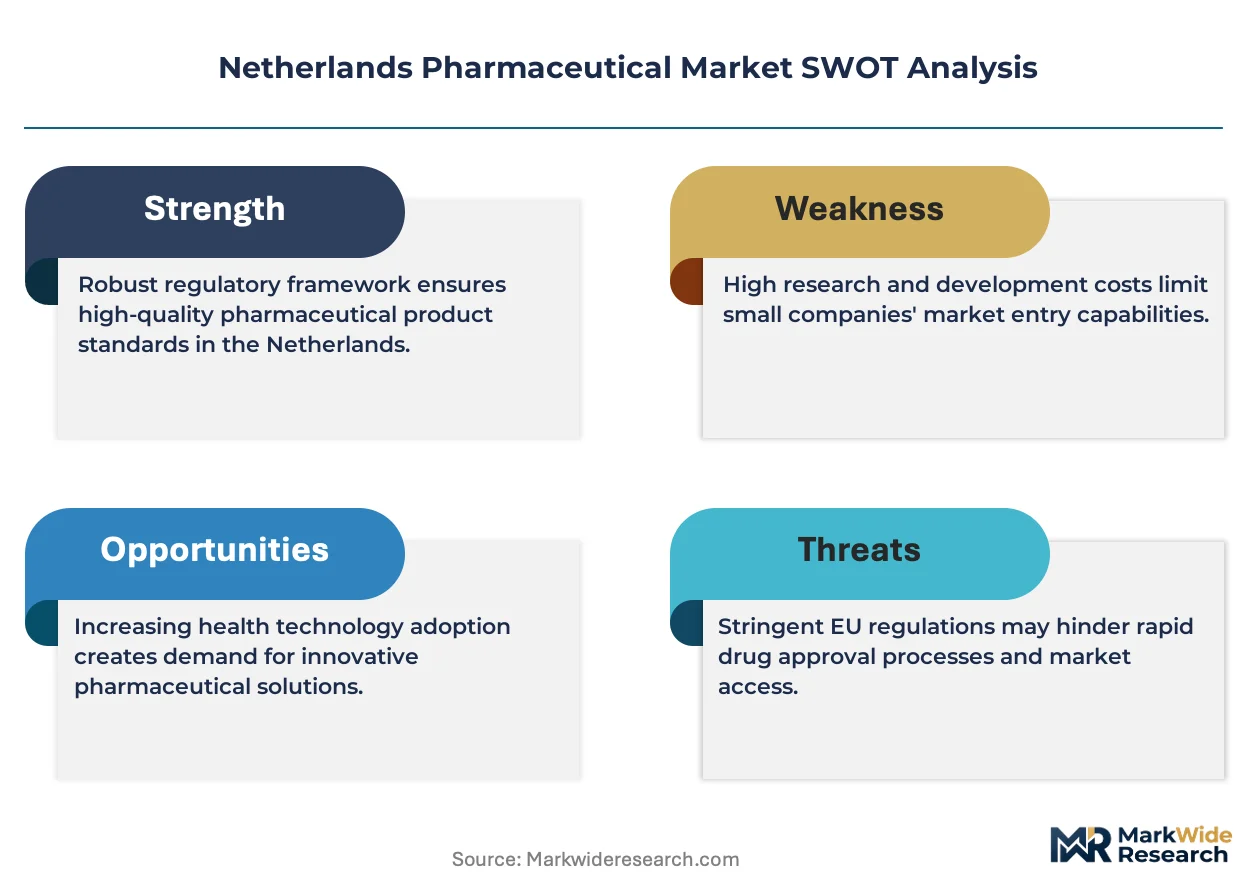
The R&D-to-manufacturing capability gap between large-cap multinationals and Dutch mid-cap biotechs is collapsing as government co-investment programs level capital access. AbbVie leverages its immunology manufacturing footprint in North Brabant to supply European markets. argenx SE anchors the Belgian-Dutch biotech corridor with antibody engineering operations near Ghent. Merus N.V. competes on bispecific platform technology from its Utrecht base.
Netherlands pharmaceuticals encompass chemically synthesized small molecules, recombinant biologics, and nucleic acid therapeutics produced under GMP conditions with batch release governed by the Dutch Medicines Evaluation Board. Prescription drugs dominate value flows through hospital formularies, while biologics capture expanding margin pools in oncology and autoimmune care. Homecare settings represent the fastest-growing end-user channel as infusion therapy shifts beyond hospital walls. Manufacturing services concentrate margin in sterile injectables and aseptic fill-finish operations serving EMA-regulated supply chains.
EMA centralized procedures and Dutch Medicines Evaluation Board national assessments shape product timelines, while the EU AI Act introduces compliance layers for algorithm-driven drug discovery tools. The Dutch Health and Youth Care Inspectorate enforces pharmacovigilance standards that determine post-market access sustainability. Stakeholders must monitor how EU pharmaceutical legislation revisions alter orphan drug incentives and generic entry pathways.
Market Dynamics
EMA accelerated approval pathways for oncology biologics are compressing development timelines and pulling manufacturing investment toward the Randstad corridor, where university medical centers and contract development organizations cluster within 50 kilometers of Schiphol logistics hubs.
Growth Catalysts
- EMA centralized procedure expansion:Accelerated oncology pathways reduce time-to-market for biologics, concentrating Dutch trial infrastructure investment around Amsterdam and Utrecht university hospitals.
- Homecare infusion migration:Reimbursement shifts favor outpatient administration, expanding demand for portable drug delivery systems and specialized nursing networks.
- Antibody engineering platforms:Bispecific and multispecific modalities advance through Dutch-Belgian corridor partnerships, leveraging Ghent-Utrecht talent pools.
Market Restraints
- API import concentration:Active pharmaceutical ingredient sourcing depends on Asian chemical manufacturers, exposing Dutch formulators to shipping cost volatility and customs delays.
- GMP facility scarcity:Sterile fill-finish capacity constraints in North Brabant limit batch release velocity for parenteral biologics.
- EU pharmaceutical legislation uncertainty:Pending revisions to orphan drug exclusivity periods and generic entry pathways freeze long-term portfolio planning for mid-cap developers.
Strategic Opportunities
- RNA therapeutics manufacturing:mRNA and oligonucleotide production capabilities remain underdeveloped in the Benelux region, creating first-mover space for dedicated facilities.
- AI-driven target discovery:The EU AI Act creates compliance frameworks that favor established algorithm developers, rewarding early investment in validated machine learning pipelines.
- Maastricht-Liège cross-border cluster:Underutilized logistics infrastructure at the Dutch-Belgian-German tripoint offers untapped distribution potential for temperature-sensitive biologics.
Industry Challenges
- Qualified person shortage:Dutch Medicines Evaluation Board certification requirements for batch release exceed available QP talent supply, extending hiring timelines.
- Legacy ERP integration:Serialization and track-and-trace mandates require costly upgrades to manufacturing execution systems at mid-sized contract manufacturers.
- Pharmacovigilance data harmonization:Divergent reporting standards between EMA centralized procedures and Dutch national assessments create compliance friction for post-market surveillance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Netherlands Pharmaceutical Market |
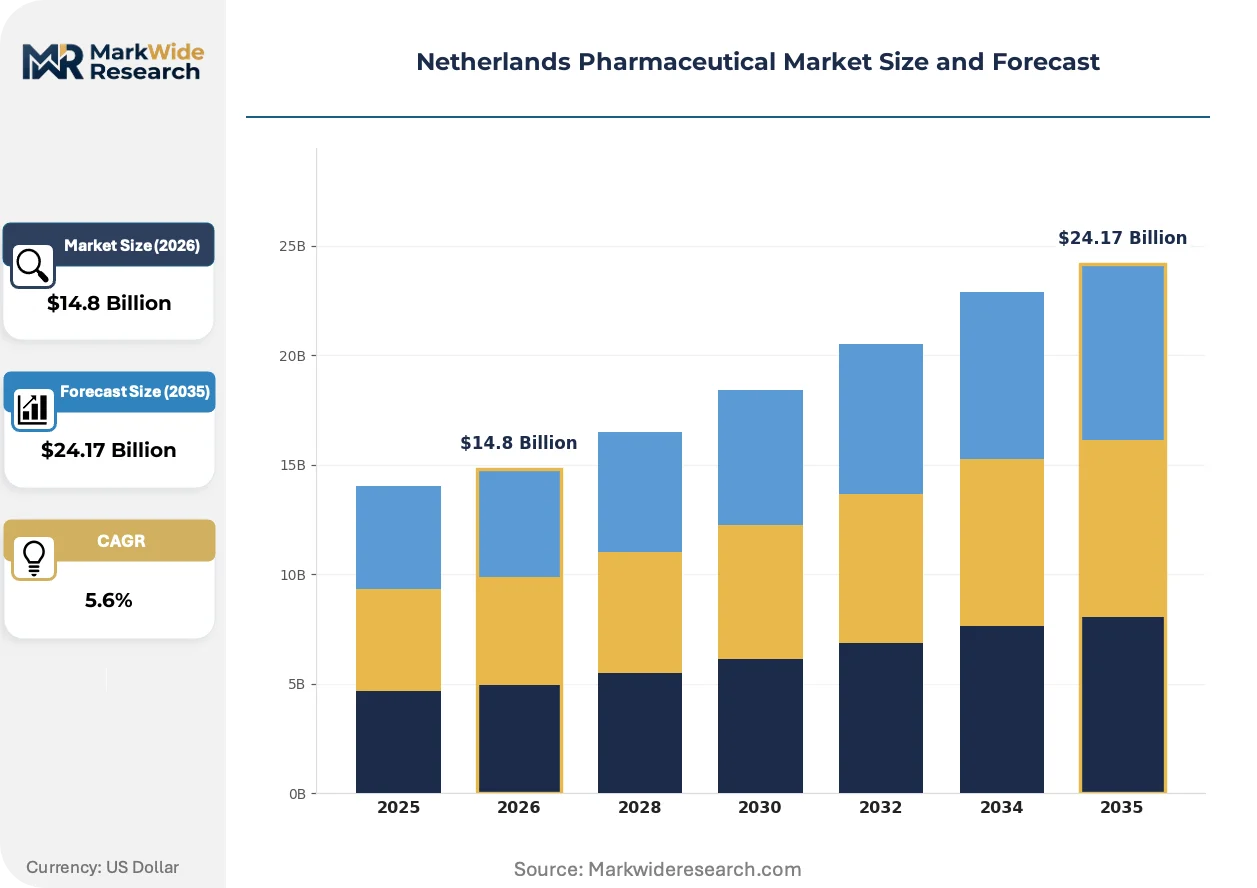
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.17 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prescription Drugs, OTC Medications, Biologics, Vaccines Application: Oncology, Cardiovascular, Neurology, Infectious Diseases End User: Hospitals, Retail Pharmacies, Clinics, Homecare Settings Service Type: Manufacturing, Distribution, Research & Development, Regulatory Affairs |
| Companies Covered | AbbVie, Novartis, argenx SE, Abbott Laboratories, Merus N.V., Koninklijke Philips N.V., AstraZeneca, Amgen, Qiagen N.V., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Netherlands Pharmaceutical Market Shifts & Advancements
Continuous manufacturing technologies and modular facility designs are displacing traditional batch processing in Dutch sterile injectables production, while algorithmic drug discovery tools reshape target identification workflows.
Single-use bioreactor systems are decomposing fixed stainless-steel infrastructure requirements for clinical-stage biologics manufacturing. Dutch contract manufacturers adopt disposable downstream processing trains to reduce changeover downtime between client programs. This shift is decomposing capital barriers for mid-cap biotechs seeking GMP capacity without multi-year facility commitments.
The EU AI Act imposes conformity assessment obligations on machine learning tools used in candidate molecule selection. Dutch developers must document training data provenance and algorithmic transparency for regulatory submission packages. Early-stage companies with validated AI pipelines gain preferential access to EMA scientific advice procedures.
Hospital procurement consortia consolidate formulary decision-making across Dutch university medical centers, compressing vendor negotiation cycles. Regional purchasing cooperatives now dominate high-cost oncology biologics contracting, displacing individual hospital pharmacy autonomy. This concentration is most visible in the Randstad, where Amsterdam UMC and Utrecht UMC coordinate tender timing.
Netherlands Pharmaceutical Market Segmentation
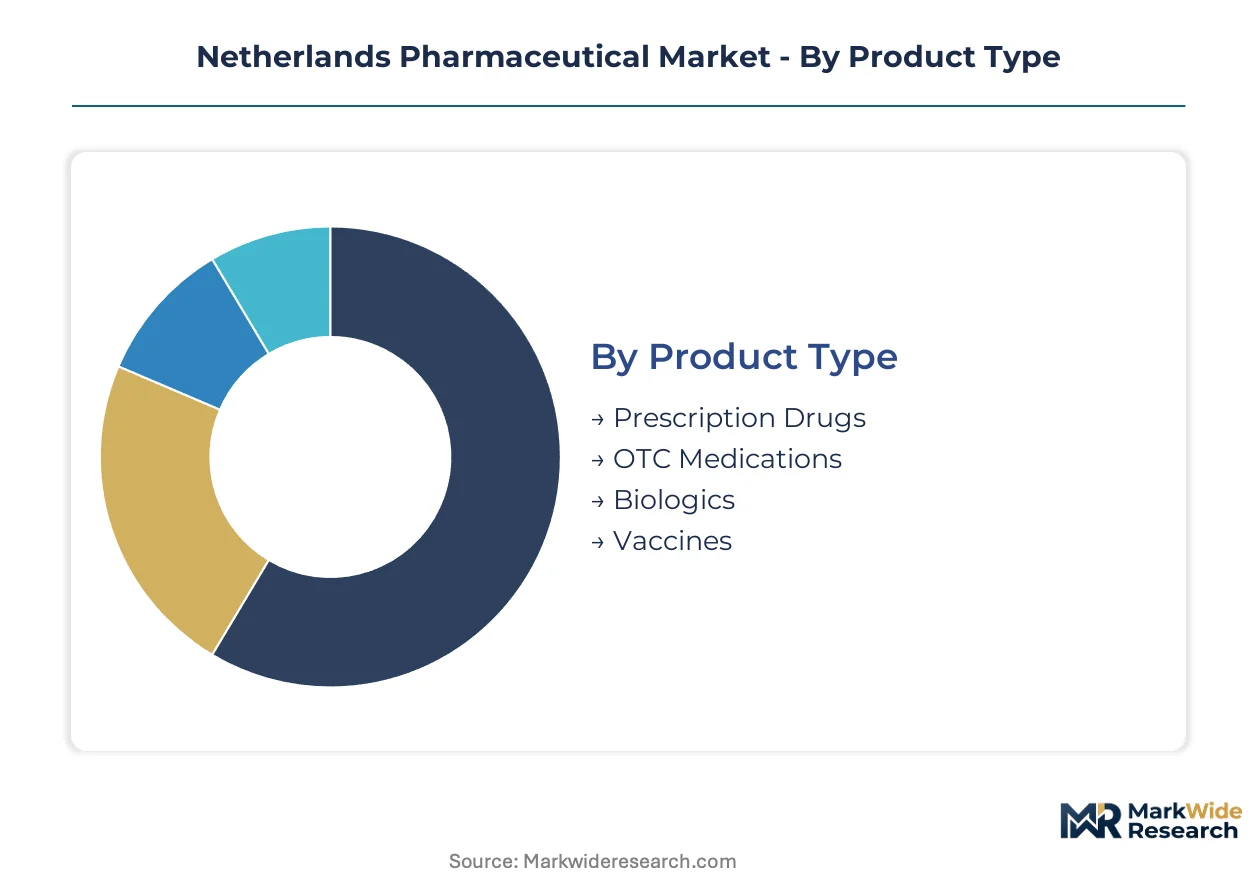
Dutch pharmaceutical value flows diverge sharply across channel structures. Hospital procurement consortia dominate high-cost biologics contracting, while retail pharmacies and homecare networks fragment distribution for chronic therapies.
Product Type:
Channel-mix patterns split sharply between institutional procurement and direct-to-patient flows.
- Prescription Drugs:Chemically synthesized small molecules governed by Dutch Medicines Evaluation Board batch release. Hospital formularies in Amsterdam and Utrecht university medical centers concentrate demand for oncology and cardiovascular therapies, with reimbursement timelines determining access velocity.
- Biologics:Recombinant proteins and monoclonal antibodies produced under EMA centralized procedures. North Brabant manufacturing clusters supply European markets, with AbbVie's immunology footprint anchoring regional sterile injectables capacity.
- OTC Medications:Self-care products moving through retail pharmacy chains and digital health platforms. Consumer price sensitivity shapes margin compression in analgesic and cold remedy categories.
- Vaccines:Prophylactic and therapeutic immunization products distributed through national immunization programs and occupational health channels.
Prescription drugs dominate installed base. Biologics is where expansion concentrates.
Application:
Cost tier stratification separates acute intervention budgets from chronic disease management allocations.
- Oncology:EMA accelerated approval pathways compress development timelines for checkpoint inhibitors and antibody-drug conjugates. Randstad university medical centers cluster Phase I/II trial infrastructure, pulling manufacturing investment toward Schiphol logistics corridors.
- Cardiovascular:Small molecule anticoagulants and lipid-lowering therapies face generic entry pressure. Hospital procurement consortia negotiate volume-based contracts that displace originator pricing power.
- Neurology:Disease-modifying therapies for multiple sclerosis and rare movement disorders command premium reimbursement. Dutch Orphan Drug Fund pathways determine access for ultra-rare indications.
- Infectious Diseases:Antimicrobial stewardship programs restrict hospital formulary placement for novel antibiotics, channeling demand toward narrow-spectrum agents with resistance surveillance protocols.
Cardiovascular commands the largest patient volume base. Oncology is climbing the fastest as biologics penetration deepens.
End User:
Customer type determines service intensity and reimbursement complexity.
- Hospitals:University medical centers and general hospitals administer infused biologics and manage complex polypharmacy. Regional purchasing cooperatives now dominate high-cost oncology contracting across Amsterdam UMC and Utrecht UMC networks.
- Homecare Settings:Subcutaneous and oral therapies shift beyond hospital walls as reimbursement favors outpatient administration. Specialized nursing networks expand across Randstad corridors to support infusion therapy migration.
- Retail Pharmacies:Community dispensaries handle chronic disease maintenance scripts and OTC transitions. Digital prescription routing from general practitioners streamlines fulfillment.
- Clinics:Outpatient specialty centers manage stable chronic conditions and preventive vaccination programs.
Hospitals retain the highest per-patient value capture. Homecare settings are gaining share fastest as administration shifts ambulatory.
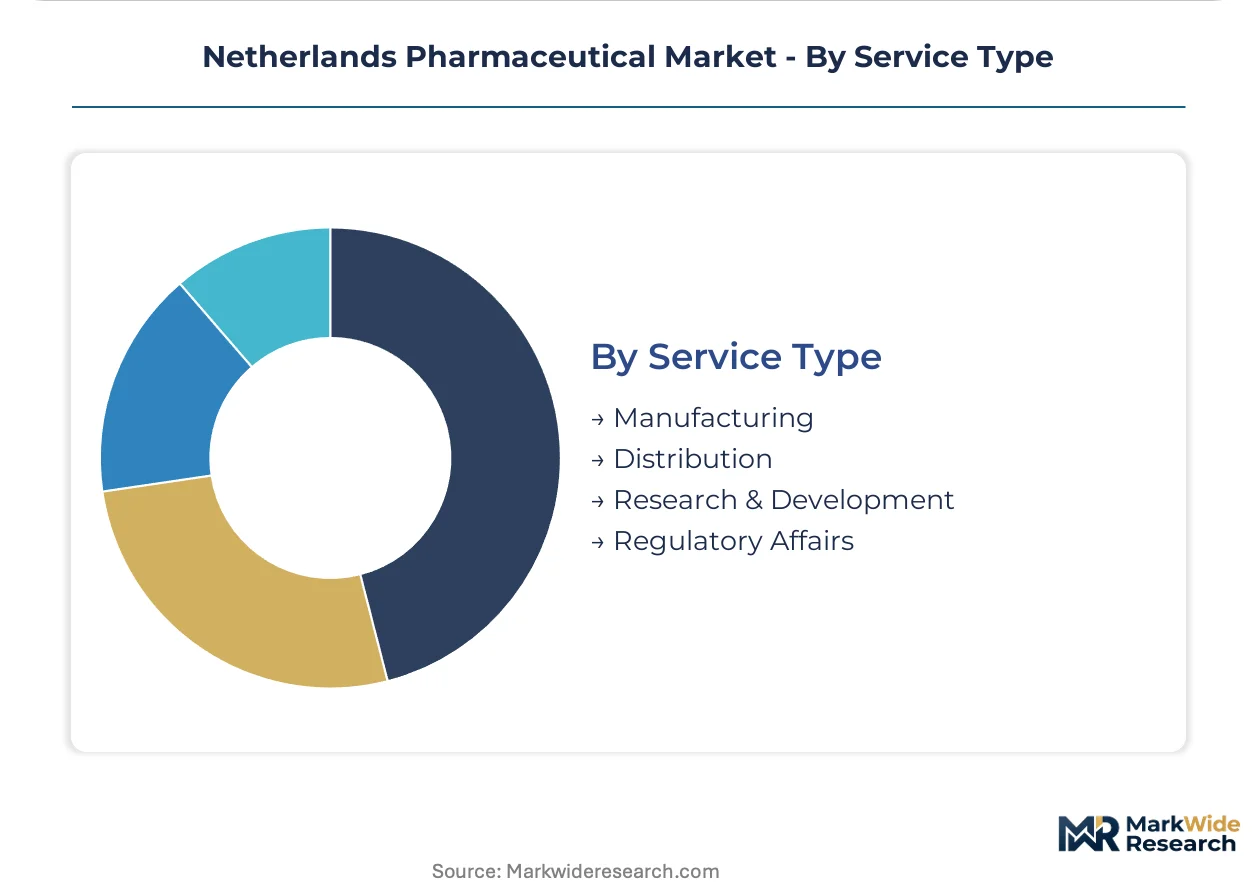
Service Type:
Margin concentration follows supply-side capability scarcity.
- Manufacturing:Sterile fill-finish operations and aseptic processing command premium pricing. GMP facility scarcity in North Brabant limits batch release velocity for parenteral biologics.
- Regulatory Affairs:EMA centralized procedure navigation and Dutch Medicines Evaluation Board national assessments determine market entry timelines. Qualified person certification requirements exceed available talent supply.
- Distribution:Temperature-controlled logistics serving EMA-regulated supply chains concentrate around Schiphol and Rotterdam port infrastructure.
- Research & Development:Clinical trial operations and algorithmic drug discovery reshape target identification workflows. EU AI Act conformity assessments favor established machine learning pipeline developers.
Manufacturing holds the deepest margin pool. Regulatory affairs is where capability scarcity creates pricing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the Netherlands pharmaceutical market outstrips Belgian and German border regions by 12-18% for sterile biologics, reflecting Randstad corridor logistics premiums and EMA centralized procedure proximity.
Randstad Corridor
Amsterdam UMC and Utrecht UMC anchor clinical trial infrastructure that pulls Phase I/II oncology studies from across Europe. The Dutch Medicines Evaluation Board co-locates assessment teams near Schiphol logistics hubs, compressing batch release timelines. North Holland and Utrecht provinces concentrate sterile fill-finish capacity serving EMA-regulated supply chains.
North Brabant
Immunology manufacturing investments cluster around Tilburg and Eindhoven, drawn by Maasvlakte port access and German border distribution networks. The region's GMP facility scarcity creates 8-12 month qualified person hiring queues. Sterile injectables production serves Benelux and German hospital procurement consortia.
Limburg
Maastricht University Medical Center coordinates cross-border trials with Liège and Aachen partners, exploiting underutilized tripoint logistics infrastructure. The Dutch-German-Belgian border zone offers temperature-controlled distribution arbitrage for biologics. Regional health authorities pilot outcome-based reimbursement for rare disease therapies.
Zeeland and Southwest Delta
Antwerp-Rotterdam pipeline corridors feed API import flows through Vlissingen and Terneuzen ports. Chemical manufacturing heritage supports contract synthesis operations for clinical-stage developers. Scheldt river logistics face customs delay exposure from Asian API sourcing concentration.
Northern Netherlands
Groningen and Leeuwarden university medical centers specialize in pharmacogenomics and personalized medicine pilots. The region lacks GMP manufacturing scale, forcing biotechs to contract Randstad or Belgian facilities. Northern health authorities negotiate separately from Randstad procurement consortia, fragmenting pricing uniformity.
Netherlands Pharmaceutical Market Competitive Landscape
Concentration sits with large-cap multinationals commanding hospital formulary placement and EMA centralized procedure navigation. Mid-cap biotechs compete on antibody engineering platforms and bispecific modalities. The vendor base stratifies across three tiers: global originators with Dutch manufacturing footprints, Belgian-Dutch corridor specialists, and emerging RNA therapeutic developers. Competitive moves center on sterile capacity expansion in North Brabant and algorithmic target discovery partnerships.
Among established originators, AbbVie anchors immunology manufacturing in North Brabant, while Novartis maintains oncology and generics presence across Dutch hospital networks. Argenx SE exemplifies the Belgian-Dutch biotech corridor model with antibody engineering operations near Ghent. Merus N.V. occupies a position as a Utrecht-based bispecific platform developer competing for EMA accelerated approval pathways.
| Leading Market Players |
|---|
| AbbVie |
| Novartis |
| argenx SE |
| Abbott Laboratories |
| Merus N.V. |
| Koninklijke Philips N.V. |
| AstraZeneca |
| Amgen |
| Qiagen N.V. |
| Others |
Supply & Pricing Matrix
Dutch Medicines Evaluation Board batch release certification gates both sterile fill-finish capacity qualification and price differentiation between originator biologics and biosimilar entrants. Hospital procurement consortia exploit this dual gating mechanism to compress vendor margins while securing supply continuity for high-cost oncology therapies.
Pricing Analysis
The customization-premium spread between patient-specific dosing configurations and standard vial presentations determines margin capture for parenteral biologics. Contract-based long-term offtake dominates hospital procurement, with price differentiation driven by GMP certification tier and volume scale commitments. Cost compression in the biosimilar tier is intensifying because AbbVie and argenx SE anchor originator positioning through immunology manufacturing depth. Retail pharmacies exhibit highest price sensitivity for chronic maintenance therapies, while university medical centers prioritize supply security over unit cost for accelerated-approval oncology biologics.
Supply Chain Analysis
India and China anchor active pharmaceutical ingredient production for Dutch formulators, with Ireland and Switzerland contributing high-potency intermediate manufacturing. Sterile fill-finish operations draw from single-use bioreactor systems, chromatography resins, and aseptic packaging components. Single-source vulnerability concentrates in Asian API sourcing for oncology and immunology actives. Distribution runs through Schiphol temperature-controlled logistics hubs serving EMA-regulated supply chains across the Benelux corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated hospital procurement consortia across Amsterdam UMC and Utrecht UMC networks, fragmenting vendor negotiation leverage and compressing pricing autonomy for mid-cap developers.
For Market Incumbents: Shield formulary placement through captive sterile fill-finish capacity expansion in North Brabant, insulating against qualified person shortages that delay batch release. Deepen backward integration into antibody engineering platforms to defend margin position against Belgian-Dutch corridor specialists advancing bispecific modalities.
For New Entrants and Emerging Players: Lead with RNA therapeutics manufacturing capabilities in the underdeveloped Benelux mRNA production landscape, exploiting first-mover space before established players consolidate. Target homecare infusion networks as the most penetrable channel, deploying portable drug delivery systems through specialized nursing partnerships across Randstad corridors.
For Investors and Strategic Acquirers: EU pharmaceutical legislation revisions reshape the acquisition landscape by freezing orphan drug exclusivity timelines and altering generic entry pathways. Five-to-ten year viability favors mid-cap biotechs with validated AI-driven target discovery pipelines and EMA scientific advice precedents. Monitor qualified person hiring queue lengths at Dutch Medicines Evaluation Board as the inflection signal for manufacturing capacity constraints.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Phase I/II oncology infrastructure at Amsterdam UMC accelerates EMA accelerated approval pathways. |
| Manufacturing Scale-Up | Sterile fill-finish capacity expansion in North Brabant addresses GMP facility scarcity constraining batch release. |
| Regulatory Approval Pathway | Dutch Medicines Evaluation Board national assessment navigation determines post-market access sustainability. |
| Pipeline Diversification | RNA therapeutics manufacturing capabilities capture first-mover position in underdeveloped Benelux mRNA production. |
| Licensing Agreement | Belgian-Dutch biotech corridor partnerships leverage Ghent-Utrecht talent pools for bispecific platform advancement. |
Research Methodology
A spread of perspectives from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers converged on the working assumptions underlying demand projections. Primary interview insights combined with secondary validation from EMA submissions, ClinicalTrials.gov records, Dutch hospital procurement databases, and formulary listings. Bottom-up patient population modeling and top-down pharmaceutical spending trajectories were triangulated to anchor volume and value estimates.
Segmentation dimensions modeled include treatment line, dosage form, administration route, and regional regulatory cluster across the projection horizon. CAGRs were derived from growth rate convergence analysis applied to historical spending patterns and pipeline maturation timelines. Forecast inputs incorporated EMA approval velocity assumptions and homecare reimbursement shift parameters specific to Dutch health authority pilot programs.
The analysis sits within stated boundaries; outcomes outside EMA centralized procedure continuity or Dutch Medicines Evaluation Board staffing stability would require recalibration. Forecasts reflect documented assumptions regarding orphan drug incentive persistence and API import flow reliability. Recalibration cycles align with material shifts in EU pharmaceutical legislation finalization and qualified person supply expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Antidepressant Drugs Market
Pharmaceuticals
Ocular Drug Delivery System Market
Pharmaceuticals
Tinea Versicolor Treatment Market
Pharmaceuticals
Targeted Therapeutics Market
Pharmaceuticals
Global Rheumatoid Arthritis Therapeutics Market
Pharmaceuticals
Global Alpha-Blocker Market
Pharmaceuticals
Large Volume Parenteral (LVP) Market
Pharmaceuticals
Propofol Market
Pharmaceuticals
Soft Capsules Drugs Market
Pharmaceuticals
Lidocaine Ointment Market
Pharmaceuticals
Alkylating Agents Market
Pharmaceuticals
Dipeptidyl Peptidase-4 (DPP-4) Inhibitors Market
Pharmaceuticals
Bisphosphonates Market
Pharmaceuticals
Topical Corticosteroids Market
Pharmaceuticals
Iodine Deficiency Drug Market
Pharmaceuticals
Nesiritide Market