
 Meniscus Repair Systems Market | 2026-2036
Meniscus Repair Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Meniscus Repair Systems Market Intelligence
A shift from procuring individual components to sourcing integrated, single-use surgical kits from specialized vendors is hardening supply chain relationships. Arthrex, Inc. leverages its strong surgeon relationships to promote its proprietary all-suture repair systems. Smith & Nephew plc differentiates through a broad portfolio including both traditional sutures and advanced implant technologies. Meanwhile, Stryker Corporation anchors its position via extensive hospital distribution networks and a focus on procedural efficiency.
Meniscus repair systems are medical device kits used in orthopedic surgery to suture tears in the knee's meniscal cartilage. They often employ bioabsorbable anchors and ultra-high-molecular-weight polyethylene sutures to preserve joint function and delay total knee arthroplasty. All-suture and anchor-based product types see high utilization in hospitals and orthopedic clinics, the primary end users for these procedures. Within technology segments, bioabsorbable materials are displacing traditional metal instruments due to improved long-term patient outcomes.
Market access requires stringent approvals, such as the FDA's 510(k) pathway in the United States and CE marking under Europe's Medical Device Regulation (MDR). Japan's PMDA similarly enforces rigorous standards for device efficacy and safety, shaping product development strategies. Stakeholders must prioritize generating long-term clinical data on tissue healing and implant resorption to secure favorable reimbursement and surgeon adoption.
Market Dynamics
The central force shaping the market is the procedural shift toward meniscal preservation over removal, driven by a younger, athletic patient demographic demanding less invasive options that delay or prevent knee osteoarthritis. This demand aligns with technological advancements in bioabsorbable materials and all-suture techniques.
Growth Catalysts
- Bioabsorbable Materials:The adoption of advanced polymers that degrade over time eliminates the need for a second surgery for hardware removal, improving long-term patient outcomes and aligning with less invasive surgical goals.
- Sports Medicine Expansion:A rising incidence of sports-related knee injuries among adolescents and young adults is increasing the volume of repair procedures performed in specialized orthopedic clinics and ambulatory surgery centers.
- Reimbursement Frameworks:Favorable reimbursement policies for meniscal repair procedures in developed healthcare systems, such as those in the United States and Germany, incentivize surgeons to choose repair over partial meniscectomy.
Market Restraints
- Procedure Cost:The higher price of sophisticated all-suture or bioabsorbable implant systems compared to traditional, simple meniscectomy can restrict adoption in healthcare facilities with tight budgets or in regions with limited reimbursement.
- Technical Complexity:Meniscus repair is a technically demanding procedure with a significant learning curve for surgeons, which can slow the adoption of newer, more complex devices and techniques, especially for tears in avascular zones.
- Substitution by Meniscectomy:In cases of complex degenerative tears or in older, less active patients, partial meniscectomy remains a viable, faster, and lower-cost alternative, posing a persistent substitution threat to repair procedures.
Strategic Opportunities
- Emerging Market Penetration:Expanding into markets like Brazil and South Korea, where sports participation and access to advanced orthopedic care are increasing, offers significant growth potential for established device manufacturers.
- Regenerative Technologies:Integrating biologic augments, such as scaffolds or growth factors, with repair devices to enhance healing in the avascular zone of the meniscus presents a major opportunity for product differentiation.
- Pediatric Indications:Developing devices and techniques specifically sized and designed for the pediatric population, which has high healing potential, opens a new and underserved patient segment for specialized products.
Industry Challenges
- Long-Term Clinical Data:Manufacturers face the challenge of funding and executing multi-year clinical studies to definitively prove the long-term durability and cost-effectiveness of new repair technologies to satisfy regulators like the FDA and payers.
- Surgeon Training Scalability:Providing consistent, high-quality hands-on training and education to a global network of orthopedic surgeons on the use of novel repair systems is a significant logistical and financial hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Meniscus Repair Systems Market |
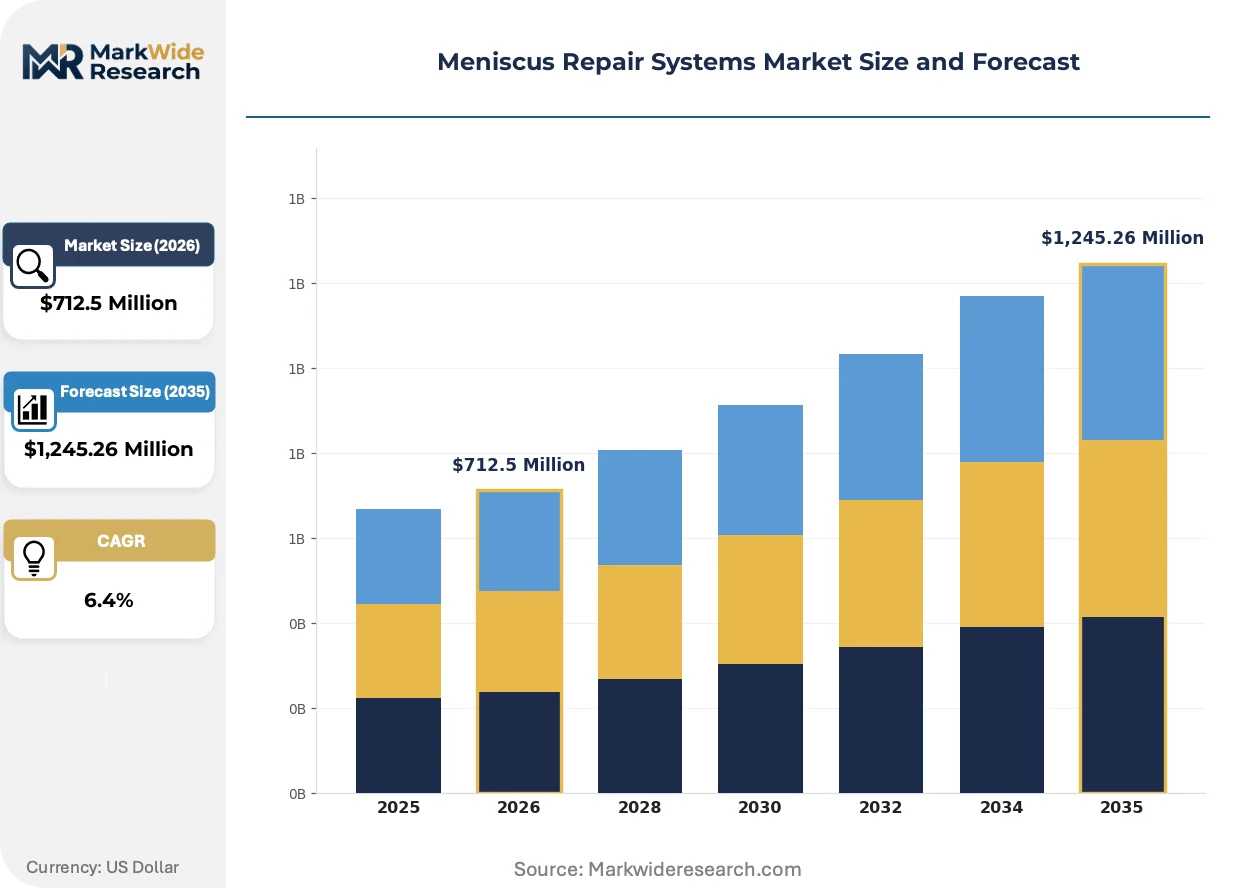
| Market Size in 2026 | $712.5 Million |
| Market Size in 2035 | $1,245.26 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Arthroscopic Devices, Sutures, Anchors, Grafts Delivery Mode: Open Surgery, Minimally Invasive Surgery, Non-Invasive Techniques, Arthroscopic Surgery End User: Hospitals, Orthopedic Clinics, Rehabilitation Centers, Sports Medicine Facilities Technology: Bioabsorbable Materials, Metal Instruments, Robotic Assistance, Imaging Systems |
| Companies Covered | Stryker Corporation, Zimmer Biomet Holdings, Inc, Arthrex, Inc, Johnson & Johnson, Smith & Nephew plc, CONMED Corporation, Medtronic plc, DePuy Synthes, Arcuro Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Meniscus Repair Systems Market Strategic Shifts & Innovations
A convergence of material science and surgical instrumentation is redefining the market's trajectory. The focus is shifting from simple mechanical fixation to creating an environment that promotes biological healing, fundamentally changing product design and clinical expectations for patient recovery.
Bioresorbable polymers, primarily polylactic acid (PLLA) and polyglycolic acid (PGA), form the basis of modern meniscal implants, providing temporary structural support during the healing phase. Orthopedic hospitals and sports medicine facilities are rapidly adopting these materials for younger patients undergoing arthroscopic surgery. This technological evolution is absorbing the market share of older, permanent implants, thereby reducing risks associated with long-term hardware presence in the knee joint.
Europe's Medical Device Regulation (MDR) has introduced more stringent requirements for clinical evidence and post-market surveillance for all medical devices. This places a greater burden on manufacturers to prove safety and performance, often delaying market access for new meniscus repair systems. In response, companies are integrating long-term data collection strategies into their initial product development plans to meet the rigorous demands of notified bodies and maintain CE marking.
Hospitals are altering procurement patterns by favoring integrated, single-use surgical kits over purchasing individual components separately. This trend disrupts the traditional supply chain, benefiting vendors capable of offering a complete procedural solution that includes sutures, anchors, and delivery instruments in one sterile package. The shift is most visible in large healthcare networks across the United States, driven by institutional pressures to standardize procedures and enhance inventory management efficiency.
Meniscus Repair Systems Market Segmentation
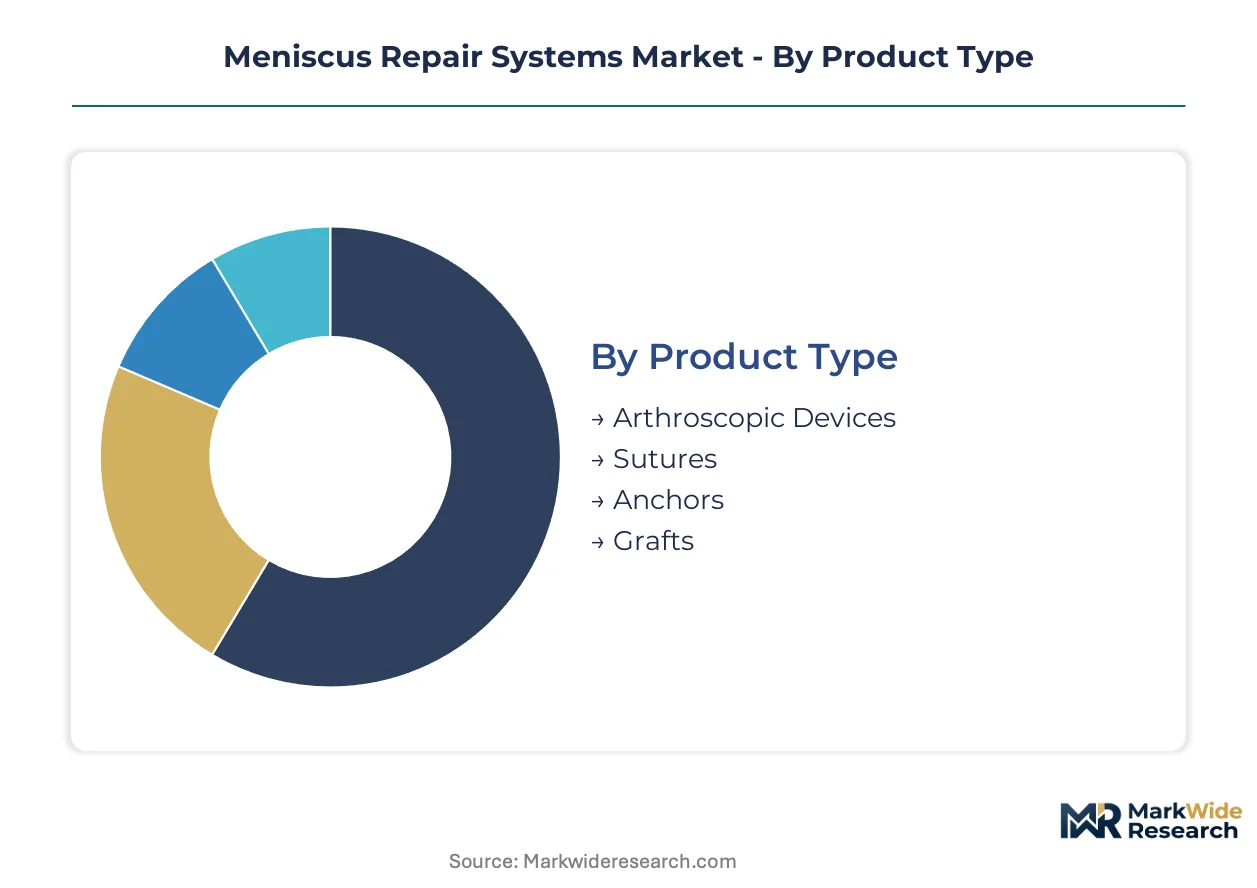
Meniscus repair systems segmentation illuminates distinct product requirements and adoption patterns. Understanding these categories is crucial for manufacturers to align product development with clinical needs and regulatory pathways. The market's diverse end-users and technological preferences shape demand for specialized surgical tools.
Product Type:
The regulatory landscape significantly influences product type development, with different components facing distinct certification burdens from bodies like the FDA or Europe's MDR.
- Sutures:Ultra-high-molecular-weight polyethylene sutures provide mechanical strength for meniscal tissue approximation during healing. Demand concentrates in sports medicine facilities across the United States, driven by the need for robust, long-lasting repairs in athletic patients.
- Anchors:Bioabsorbable anchors secure meniscal tissue to the joint capsule, offering a fixation point without permanent hardware. Orthopedic clinics in Germany show high demand for these devices, favoring less invasive options that promote natural healing.
- Arthroscopic Devices:These include specialized instruments like shavers, resectors, and cannulas used to prepare the joint space and facilitate repair.
- Grafts:Meniscal allografts or synthetic scaffolds are employed for larger meniscal defects or irreparable tears, requiring rigorous tissue bank regulation.
Sutures sit at the top of the volume ranking, with Grafts climbing the fastest.
Delivery Mode:
Delivery modes define the surgical approach, influencing patient recovery times and the complexity of the required instrumentation.
- Minimally Invasive Surgery:This approach utilizes small incisions and specialized tools to reduce tissue trauma and accelerate patient recovery. Demand for these techniques is strong in specialized orthopedic centers globally, driven by patient preference for less pain and quicker return to activity.
- Arthroscopic Surgery:This technique employs an arthroscope to visualize the joint interior through small portals, enabling precise meniscal repair. Hospitals in Japan increasingly adopt arthroscopic methods for their diagnostic accuracy and reduced surgical footprint.
- Open Surgery:This traditional method involves a larger incision to directly access the knee joint, typically reserved for complex cases.
- Non-Invasive Techniques:These include physical therapy and medication, often used as first-line treatments before surgical intervention is considered.
The market is shifting decisively towards less invasive options, with Arthroscopic Surgery dominating procedural volumes.
End User:
End-user segments dictate procurement patterns and the scale of device utilization, reflecting varied patient populations and care models.
- Hospitals:These institutions serve a broad patient demographic, performing a high volume of both elective and emergency meniscal repair procedures. Procurement decisions in large US hospital networks often prioritize integrated surgical kits for efficiency and cost control.
- Sports Medicine Facilities:Specializing in athletic injuries, these centers cater to younger, active patients seeking rapid recovery and return to sport. Demand here is concentrated on advanced bioabsorbable systems that support aggressive rehabilitation protocols.
- Orthopedic Clinics:These outpatient facilities focus on specialized musculoskeletal care, offering diagnostic, treatment, and follow-up services for meniscal injuries.
- Rehabilitation Centers:These facilities provide post-operative physical therapy and recovery programs, supporting patients after meniscal repair surgery.
Sports Medicine Facilities are demonstrating the steepest expansion trajectory, driven by a focused patient demographic.
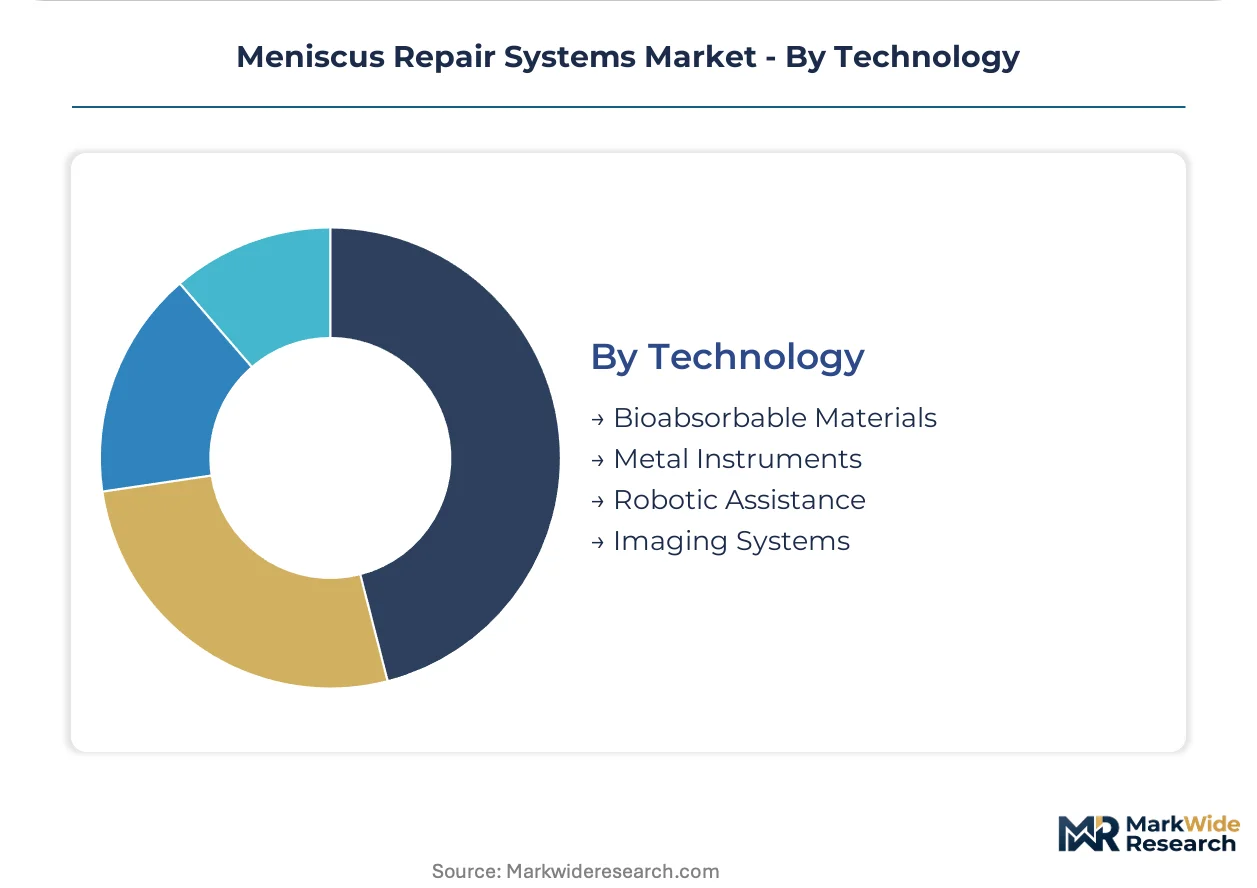
Technology:
Technological advancements are driving innovation within meniscus repair, with novel materials and digital solutions reshaping surgical practices.
- Bioabsorbable Materials:Polymers such as PLLA and PGA provide temporary structural support, degrading harmlessly as the meniscus heals, eliminating the need for hardware removal. These materials are gaining share fastest in Germany, where patient preference for less invasive, long-term solutions is strong.
- Robotic Assistance:Robotic platforms enhance surgical precision and repeatability, potentially reducing complications and improving outcomes in complex meniscal repairs. Early adoption of these systems is observed in advanced orthopedic centers in the United States, focusing on improved procedural efficiency.
- Metal Instruments:Traditional stainless steel or titanium tools are used for various surgical steps, providing durability and established performance.
- Imaging Systems:Intraoperative imaging, including fluoroscopy and ultrasound, aids in precise device placement and real-time visualization during meniscal repair procedures.
Bioabsorbable Materials are displacing traditional options, while Robotic Assistance is gaining significant market share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The regulatory landscape significantly influences regional market dynamics, with production often gravitating towards areas offering more streamlined approval processes or established regulatory frameworks. Manufacturers strategically navigate the varied requirements of bodies like the FDA and Europe's MDR to optimize market entry and product distribution. This careful consideration of regulatory environments shapes investment patterns and technology adoption across major economies.
United States
A high incidence of sports-related knee injuries drives significant demand for advanced meniscal repair systems, particularly among younger, active patients. The FDA's 510(k) pathway provides a clear, though rigorous, approval route for medical devices, influencing product development cycles. Major orthopedic research and development clusters in Boston and the San Francisco Bay Area continuously push innovation in surgical techniques and biomaterials.
Germany
Germany's sophisticated healthcare infrastructure and patient preference for less invasive procedures fuel strong demand for bioabsorbable anchors and all-suture systems. CE marking under Europe's Medical Device Regulation (MDR) sets stringent clinical evidence requirements for market access. Orthopedic device manufacturing and research hubs in Bavaria and North Rhine-Westphalia are central to European product development.
Japan
Increasing adoption of arthroscopic methods and a growing awareness of meniscal preservation techniques contribute to market expansion in Japan. The PMDA enforces rigorous standards for device efficacy and safety, shaping product development strategies for local and international manufacturers. Major medical technology innovation and adoption occur in metropolitan areas like Tokyo and Osaka.
South Korea
Rising sports participation among adolescents and young adults, coupled with increasing access to advanced orthopedic care, drives demand for repair systems. The MFDS (Ministry of Food and Drug Safety) maintains strict approval processes for medical devices, impacting market entry for new technologies. The Seoul Capital Area and Busan-Ulsan region are emerging as key centers for orthopedic surgical innovation.
Brazil
Expanding healthcare access and a growing middle class capable of affording advanced medical treatments contribute to the market's growth potential in Brazil. ANVISA, the national health surveillance agency, regulates medical device registration and approval, influencing product availability. Major medical device distribution and surgical activity concentrate in large urban centers such as São Paulo and Rio de Janeiro.
Meniscus Repair Systems Market Key Industry Players
Established producers occupy the standard tier, offering a broad portfolio of traditional and advanced repair systems, while emerging entrants pursue niche opportunities in regenerative technologies. The market structure exhibits a tiered consolidation, with a few large players dominating market share through extensive distribution networks. Strategic partnerships and targeted acquisitions are common competitive moves, enabling companies to expand product lines and geographic reach.
Specialists in advanced repair systems include Arthrex, Inc., which leverages strong surgeon relationships to promote its proprietary all-suture systems, exemplifying a focus on technique-driven innovation. Smith & Nephew plc, a UK-based public limited company, differentiates through a broad portfolio spanning both traditional sutures and advanced implant technologies, representing diversification across product types. Stryker Corporation, an American multinational medical technologies corporation, anchors its position via extensive hospital distribution networks and a focus on procedural efficiency, reflecting a strategy centered on market access and operational integration.
| Leading Market Players |
|---|
| Stryker Corporation |
| Zimmer Biomet Holdings, Inc |
| Arthrex, Inc |
| Johnson & Johnson |
| Smith & Nephew plc |
| CONMED Corporation |
| Medtronic plc |
| DePuy Synthes |
| Arcuro Medical |
| Others |
Cost & Logistics Intelligence
A clear performance gap between traditional and advanced meniscus repair systems creates distinct pricing and supply chain configurations. Bioabsorbable materials command higher pricing due to enhanced patient outcomes, influencing procurement strategies for integrated surgical kits.
Pricing Analysis
Distributor margin layers significantly influence the final cost of meniscus repair systems for healthcare providers. The dominant pricing model remains value-based, reflecting the clinical benefits of joint preservation and delayed arthroplasty. Price differentiation stems from advanced bioabsorbable material composition and robust long-term clinical evidence. Pricing pressure stems from the higher cost of these sophisticated systems compared to traditional meniscectomy alternatives. Hospitals with tight budgets exhibit greater price sensitivity, while specialized sports medicine facilities prioritize advanced technology for athletic patients.
Supply Chain Analysis
Dual-sourcing requirements for critical components are becoming standard practice, especially for bioabsorbable polymers. Supply concentration for advanced materials like PLLA and PGA primarily centers in the United States and Germany. Raw material dependencies include ultra-high-molecular-weight polyethylene for sutures and specialized polymers for anchors. A key structural risk is regulatory restriction, particularly under Europe's MDR, which can delay market access for new devices. Distribution runs through a combination of direct sales forces and specialized medical device distributors to hospitals and orthopedic clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The meniscus repair systems market is currently a late-cycle quality story, driven by a pronounced demand-shift towards bioabsorbable materials for improved patient recovery.
For Market Incumbents: Acquire specialized R&D capabilities in regenerative technologies to enhance existing product portfolios. Companies must secure long-term clinical data on implant resorption and tissue healing to satisfy regulators and payers. This strategy helps mitigate the threat of emerging regenerative solutions and strengthens market positioning against less invasive alternatives. Deepening surgeon relationships through extensive training programs reinforces adoption of advanced repair techniques.
For New Entrants and Emerging Players: Launch novel bioabsorbable systems via targeted partnerships with specialized orthopedic clinics. Focus on white-space opportunities in pediatric indications, where high healing potential offers a strong value proposition. The most penetrable segment remains young, active patients seeking rapid return to sport. A go-to-market angle emphasizing superior long-term outcomes and reduced re-intervention rates will resonate with clinicians and patients.
For Investors and Strategic Acquirers: Consolidation pressure builds where specialized regenerative technologies demonstrate superior clinical efficacy. The market offers long-term viability over a 5-10 year window, driven by meniscal preservation trends. Acquisition targets should be companies with proprietary bioabsorbable materials or proven regenerative augments. A key signal to watch is favorable reimbursement policy expansion for advanced repair procedures in major healthcare systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Regenerative Biologics | Enhances healing potential in avascular zones, offering significant product differentiation for advanced repairs. |
| Expand Surgeon Training Programs | Accelerates adoption of technically complex repair systems by improving surgical proficiency and confidence. |
| Secure Long-Term Clinical Data | Provides robust evidence for regulatory approvals and favorable reimbursement, crucial for market access. |
| Develop Pediatric-Specific Devices | Addresses an underserved patient segment with unique anatomical needs and high healing potential. |
| Target Emerging Market Penetration | Unlocks new growth avenues by expanding access to advanced orthopedic care in growing economies. |
Research Approach
Direct dialogue with orthopedic surgeons, hospital purchasing committees, biomedical engineers, and GPO contracts managers provided qualitative insights. This primary research was triangulated with extensive secondary validation from FDA filings, CE marking documentation, clinical trial registries, and healthcare expenditure reports. A combination of bottom-up and top-down approaches ensured comprehensive market sizing and forecast accuracy.
The analytical lens applied a bottom-up approach, building market estimates from procedure volumes and average selling prices for each product type. Segmentation dimensions modeled included product type, delivery mode, end user, technology, and regional adoption patterns across the analysis window. Compound annual growth rates were derived from historical trends and projected technological advancements. Key forecast inputs included sports injury incidence rates and evolving reimbursement policies.
Forecast precision tightens around the base case; tail outcomes carry wider variance under conditions of unexpected regulatory changes or clinical trial setbacks. Forecasts reflect assumptions regarding technological adoption and healthcare infrastructure development. Deviation in major regulatory body approvals would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Wearable Injector Devices Market
Medical Devices
Invasive SEEG Depth Electrodes Market
Medical Devices
Global Cerebrospinal Fluid Drainage Catheter Market
Medical Devices
Global Non-Surgical Skin Tightening Devices Market
Medical Devices
Stethoscope Hygiene Devices Market
Medical Devices
Global Intravenous (IV) Equipment Market
Medical Devices
Snare Devices Market
Medical Devices
Indian Laparoscopy Devices Market
Medical Devices
South America C-Arms Market
Medical Devices
Balloon Inflation Devices Market
Medical Devices
Chile Artificial Organs and Bionic Implants Market
Medical Devices
Europe Breast Implant Market
Medical Devices
Global Intra-Cranial Pressure (ICP) Monitor Market
Medical Devices
Colposcopes Market
Medical Devices
Respiratory Oxygen Delivery Devices Market
Medical Devices
Global Artificial Tendons and Ligaments Market