
 Orbital Tissue Expander Market | 2026-2036
Orbital Tissue Expander Market Size, Share, and Industry Trends Forecast 2026-2036
Orbital Tissue Expander Market Analytics
Premium-grade silicone construction is bifurcating the competitive landscape into specification-differentiated tiers. Mentor leverages vertically integrated polymer supply chains to sustain cost advantages across North American hospital networks. Allergan competes through specialized oculoplastic portfolios that anchor its position in reconstructive surgery channels. Silimed differentiates via European regulatory depth and ISO-certified manufacturing protocols.
Orbital tissue expanders are biocompatible, inflatable prosthetic devices—typically fabricated from medical-grade silicone elastomer with integrated injection ports—that enable serial volume augmentation of the anophthalmic socket prior to permanent implant placement. Their primary purpose is to stimulate tissue growth and maintain orbital cavity architecture in patients with congenital anophthalmos, acquired socket defects, or post-enucleation volume loss. Silicone expanders dominate current procurement flows due to established biocompatibility profiles and predictable inflation mechanics, while dual-plane expanders represent the fastest-growing configuration as surgeons seek simultaneous anterior and posterior segment expansion. The reconstructive surgery application segment commands the deepest margin pools, though aesthetic procedures exhibit the steepest volume trajectory among ambulatory settings.
FDA 510(k) premarket notification requirements and the EU Medical Device Regulation (MDR) establish divergent compliance thresholds that shape regional product portfolios and market access timelines. ISO 10993 biocompatibility testing protocols and ASTM F749 implant material standards further constrain formulation choices and supplier qualification processes. Stakeholders must monitor evolving notified body capacity constraints under MDR implementation and assess whether dual regulatory filings or region-specific SKUs yield superior capital efficiency.
Market Dynamics
Dual-plane expander configurations are compressing traditional single-chamber designs as oculoplastic surgeons demand simultaneous anterior and posterior segment control, forcing manufacturers to retool polymer fabrication lines and recalibrate injection port geometries.
Growth Catalysts
- EU MDR streamlining:Harmonized conformity assessment pathways under the Medical Device Regulation are accelerating notified body clearances for silicone-based orbital implants across German and French hospital procurement networks.
- Ambulatory surgical center expansion:Freestanding ASCs in Texas and Florida are building dedicated oculoplastic suites, creating dedicated demand channels for disposable expander kits with integrated inflation systems.
- Congenital anophthalmos protocols:Pediatric ophthalmology departments at Boston Children's Hospital and Cincinnati Children's are standardizing early socket intervention, driving serial expansion procedures before age five.
Market Restraints
- Medical-grade silicone volatility:Silicone elastomer feedstock prices fluctuate with semiconductor and automotive sector demand, squeezing margin stability for implant manufacturers dependent on spot-market polymer purchases.
- Notified body bottlenecks:EU MDR implementation has thinned accredited conformity assessment organizations, extending time-to-market for new expander geometries by fourteen to eighteen months.
- Autologous dermis substitutes:Fat grafting and fascia lata harvesting techniques in select Asian surgical centers present functional alternatives for socket volume restoration without permanent implant commitment.
Strategic Opportunities
- Brazilian regulatory arbitrage:ANVISA's accelerated pathway for Class III devices with prior FDA clearance creates a two-year market lead window before full EU MDR certification completes.
- Remote inflation monitoring:Bluetooth-enabled pressure sensors embedded in expander ports enable telemedicine follow-up, opening rural and exurban patient populations previously excluded from specialized oculoplastic care.
- Aesthetic orbital contouring:Cosmetic practices in Beverly Hills and Miami are adopting expanders for non-anophthalmic patients seeking superior sulcus definition, expanding addressable volume beyond reconstructive indications.
Industry Challenges
- Microsurgical training deficits:Residency programs have reduced dedicated oculoplastic rotations, narrowing the specialist pipeline capable of executing complex socket reconstruction with serial expander protocols.
- Biocompatibility testing backlogs:ISO 10993 cytotoxicity and sensitization studies face six-month queues at contract research organizations, delaying 510(k) submission timelines.
- Legacy inventory reconciliation:Hospitals must segregate pre-MDR and post-MDR device lots, complicating supply chain traceability and recall readiness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Orbital Tissue Expander Market |
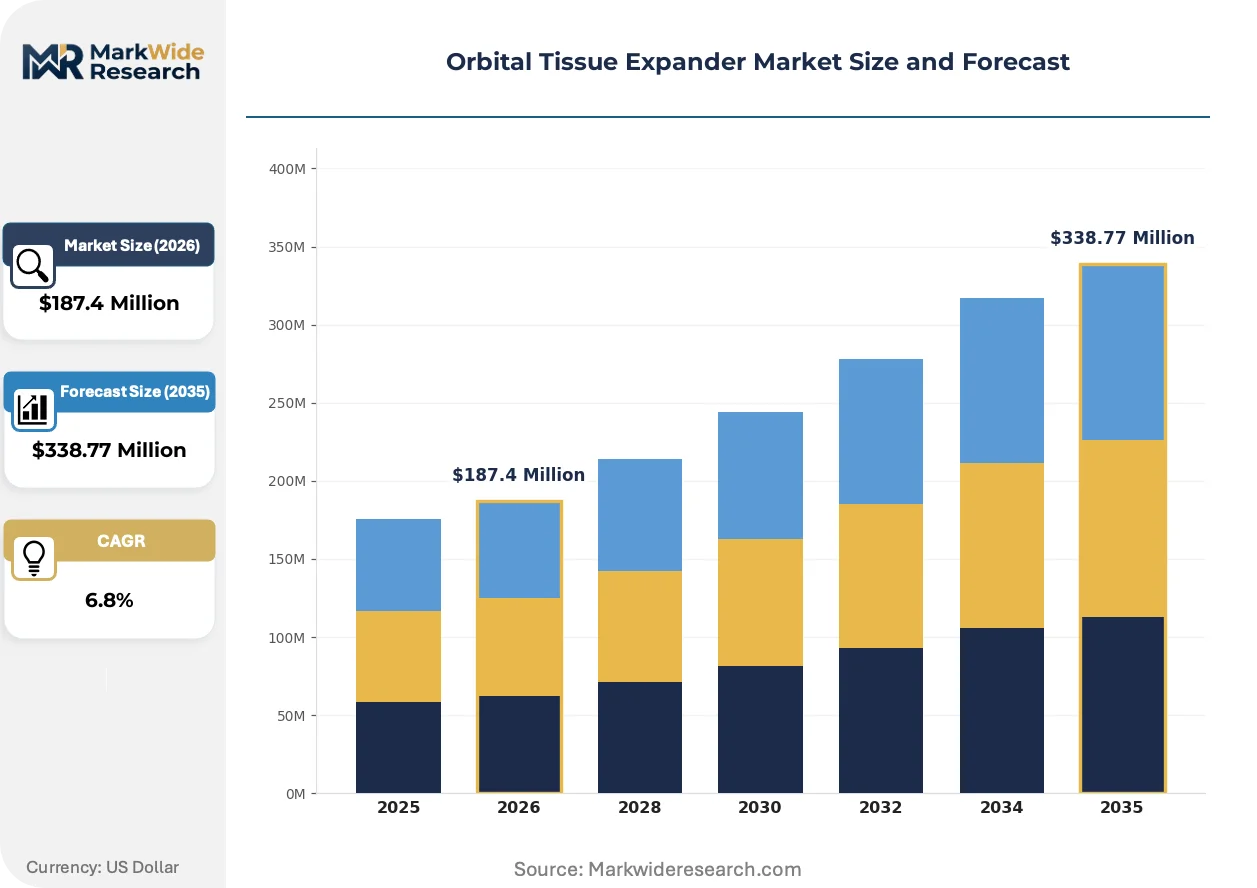
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone Expanders, Saline Expanders, Dual-Plane Expanders, Radiopaque Expanders Application: Reconstructive Surgery, Oculoplastic Surgery, Aesthetic Procedures, Trauma Repair End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutions Distribution Channel: Direct Sales, Online Sales, Distributors, Medical Device Dealers |
| Companies Covered | Silimed, Network Medical Products Ltd., Innovia LLC, Mentor (Johnson & Johnson), Allergan (AbbVie Inc.), IOP Ophthalmics, Bio-Eye Orbital Implants, Sientra, Inc., FCI Ophthalmics, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Orbital Tissue Expander Market Evolving Landscape
Orbital tissue expander technology is converging with digital surgical planning and connected health infrastructure, compressing the traditional gap between implantation and final prosthetic fitting while raising new data governance requirements.
Miniaturized valve mechanisms are miniaturizing. Next-generation expanders incorporate sub-millimeter pressure-relief valves that prevent overinflation trauma during patient self-management. Pediatric ophthalmology departments at SickKids Toronto and Children's Hospital Los Angeles are piloting these devices for home-based expansion protocols. The technology is miniaturizing the footprint of required clinical visits and compressing total treatment duration by thirty to forty percent.
EU MDR Article 10 post-market surveillance requirements are mandating systematic implant registries. Manufacturers must now collect real-world performance data across fifteen-year device lifespans, forcing investment in cloud-based traceability infrastructure. Reconstructive surgery applications face the steepest compliance burden due to higher patient mobility and multi-country follow-up complexity.
Hospital purchasing committees are consolidating supplier relationships around full-procedure bundles. Rather than negotiating expander hardware separately, materials managers at Cleveland Clinic and Mayo Clinic are sourcing complete socket reconstruction kits encompassing expanders, permanent implants, and postoperative care supplies. This bundling is visible most acutely in United States academic medical centers with centralized value analysis committees.
Orbital Tissue Expander Market Segmentation
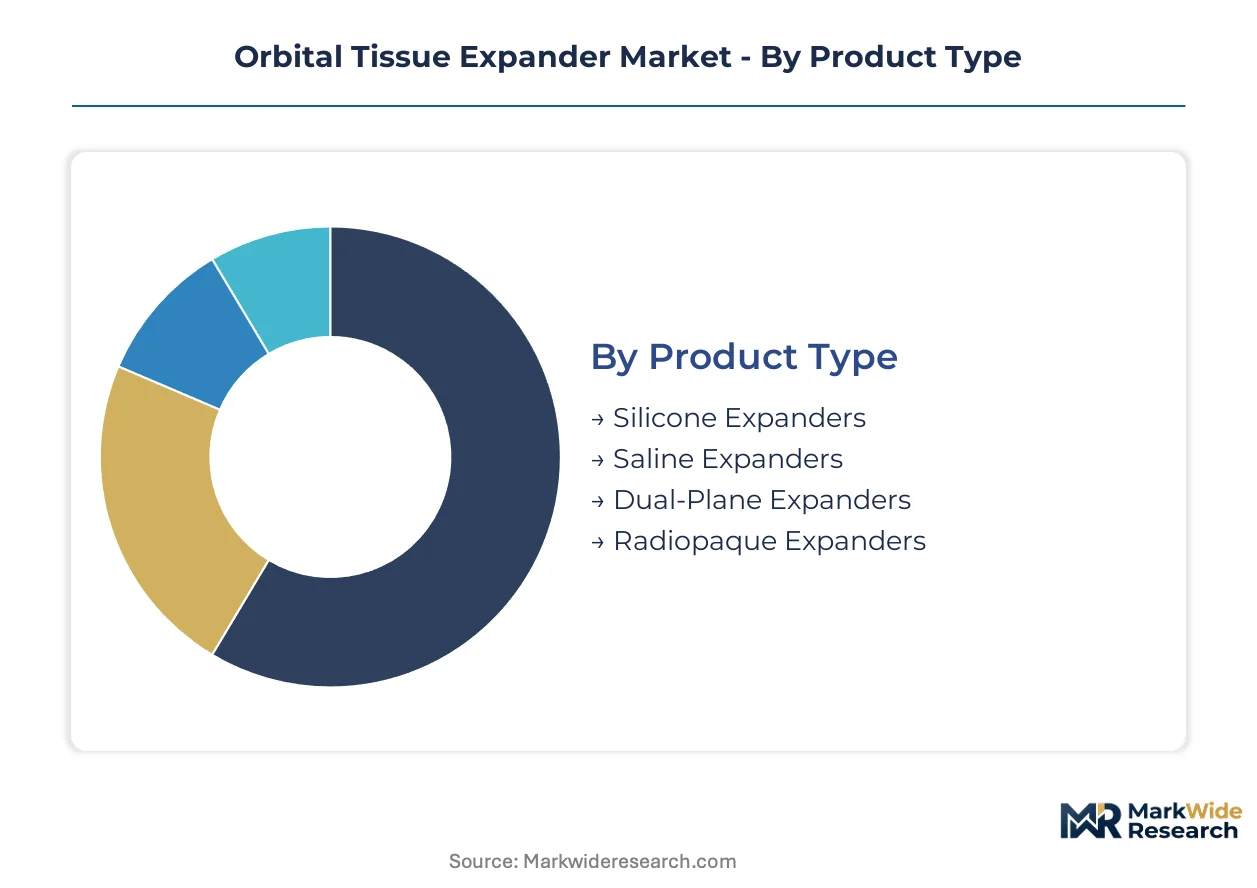
Orbital tissue expander procurement patterns diverge sharply across clinical settings, with product specifications, application urgency, and reimbursement pathways creating distinct demand clusters. Manufacturers must align formulation choices and channel strategies to these segment-specific requirements.
Product Type:
Silicone-based configurations face intensifying substitution pressure from dual-plane alternatives as surgeons seek more anatomically precise expansion control.
- Silicone Expanders:Medical-grade silicone elastomer construction with integrated injection ports delivers predictable inflation mechanics and established biocompatibility profiles. Demand concentrates in United States academic medical centers with standardized procurement protocols for congenital anophthalmos cases, though margin pressure from polymer feedstock volatility constrains manufacturer flexibility.
- Dual-Plane Expanders:Separate anterior and posterior chambers enable simultaneous multi-vector tissue expansion through independent port systems. Adoption is accelerating fastest among oculoplastic surgery clusters in Texas and Florida ambulatory centers seeking reduced procedure counts for socket reconstruction.
- Saline Expanders:Biocompatible saline inflation medium with simpler valve architectures targets cost-sensitive pediatric programs.
- Radiopaque Expanders:Barium-impregnated silicone enables postoperative imaging verification of expander position and inflation status.
Silicone Expanders anchor the volume base while Dual-Plane Expanders gain share at the steepest rate.
Application:
Margin structures vary dramatically across clinical indications, with reconstructive procedures commanding premium pricing and aesthetic applications exhibiting the most volatile demand elasticity.
- Reconstructive Surgery:Post-enucleation and congenital defect restoration requires serial expansion protocols with high procedural complexity. Boston Children's Hospital and Cincinnati Children's pediatric ophthalmology departments drive concentrated demand through early-intervention standardization, with bundled reimbursement creating stable revenue visibility for manufacturers.
- Aesthetic Procedures:Superior sulcus contouring in non-anophthalmic patients represents an off-label expansion of addressable volume. Beverly Hills and Miami cosmetic practices are piloting expander protocols for orbital rejuvenation, though regulatory ambiguity and cash-pay economics limit scalability.
- Oculoplastic Surgery:Specialist-driven socket reconstruction encompasses both functional and cosmetic objectives with intermediate reimbursement profiles.
- Trauma Repair:Acquired orbital defects from facial trauma require rapid intervention with less predictable expansion sequencing.
Reconstructive Surgery generates the deepest margin pools while Aesthetic Procedures expand most quickly among cash-pay channels.
End User:
Facility type determines kit configuration preferences, with ambulatory settings demanding streamlined disposable systems and hospitals prioritizing inventory flexibility.
- Hospitals:Centralized value analysis committees at Cleveland Clinic and Mayo Clinic negotiate full-procedure bundles encompassing expanders, permanent implants, and postoperative supplies. These academic medical centers require extensive documentation support for 510(k) cleared devices and maintain dual inventory tracks for pre-MDR and post-MDR device lots.
- Ambulatory Surgical Centers:Freestanding facilities in Texas and Florida are constructing dedicated oculoplastic suites with preference for disposable expander kits featuring integrated inflation systems. Limited storage capacity and rapid turnover economics favor single-use configurations over reusable hardware.
- Specialty Clinics:Concentrated oculoplastic practices balance procedure volume with personalized patient management protocols.
- Research Institutions:Pediatric ophthalmology departments at SickKids Toronto and Children's Hospital Los Angeles pilot miniaturized valve technologies for home-based expansion protocols.
Hospitals dominate absolute procurement volume while Ambulatory Surgical Centers climb the fastest as site-of-service migration accelerates.
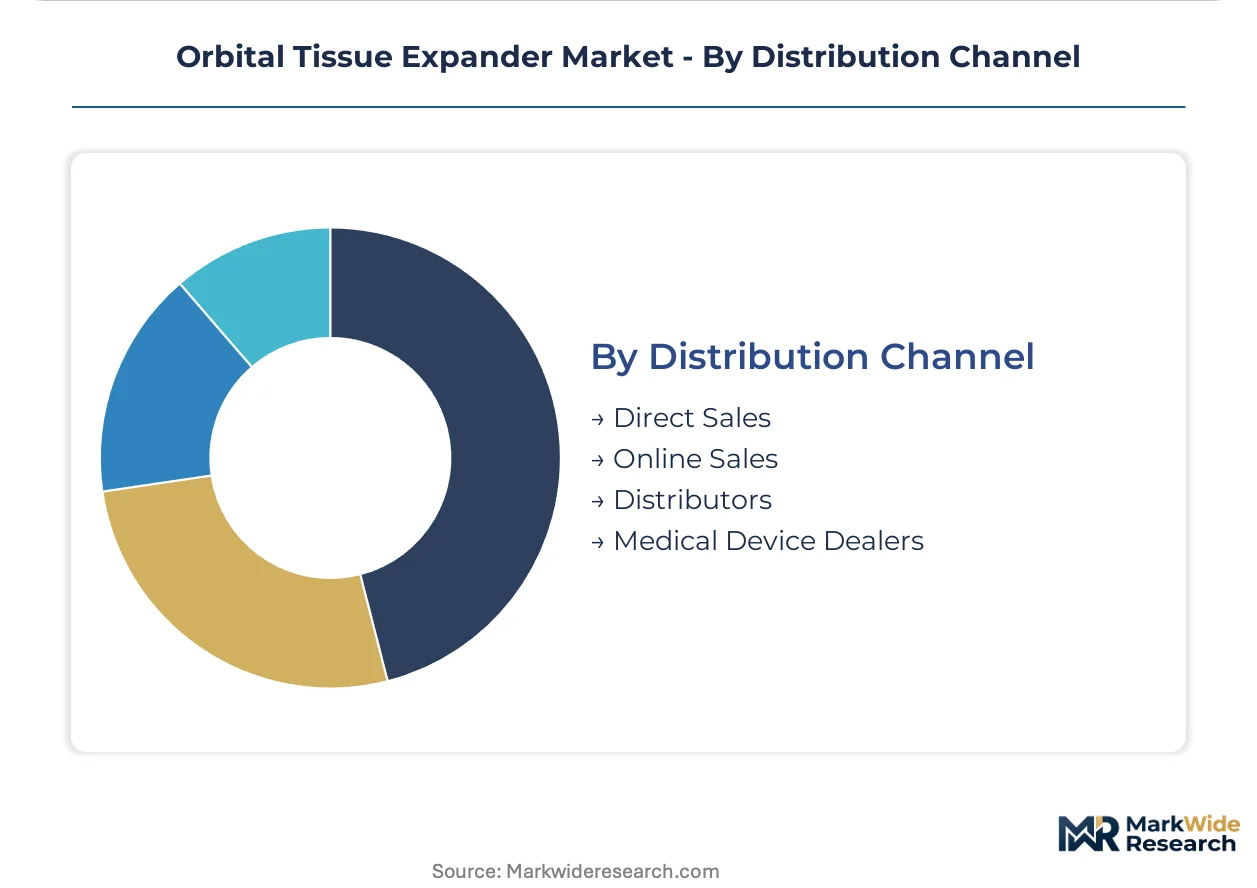
Distribution Channel:
Channel economics reflect customer scale and technical support requirements, with direct relationships consolidating around high-volume hospital networks.
- Direct Sales:Manufacturer field organizations maintain dedicated oculoplastic specialists for academic medical center and large ASC chain accounts. Cleveland Clinic and Mayo Clinic purchasing committees leverage direct relationships to negotiate procedure bundles spanning expanders through permanent implants.
- Distributors:Regional medical device distributors serve mid-tier hospitals and specialty clinics with localized inventory and technical training support.
- Online Sales:Limited to replacement inflation accessories and consumable components rather than implantable devices.
- Medical Device Dealers:Independent representatives address fragmented geographic markets with lower procedure density.
Direct Sales captures the largest revenue concentration while Distributors extend geographic reach most efficiently.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicone polymer supply chains concentrate in Germany and the United States, while demand clusters around specialized oculoplastic surgery centers in major metropolitan hospital systems. Regulatory divergence between FDA 510(k) pathways and EU MDR implementation timelines creates distinct regional market access conditions. Procurement patterns favor bundled procedure kits in academic medical centers and disposable configurations in ambulatory settings.
United States
Pediatric ophthalmology departments at Boston Children's Hospital and Cincinnati Children's Hospital Medical Center drive congenital anophthalmos intervention protocols requiring serial expansion procedures. FDA 510(k) premarket notification pathways streamline silicone implant clearances for manufacturers with established biocompatibility profiles. Texas and Florida ambulatory surgical centers are constructing dedicated oculoplastic suites with preference for disposable expander kits featuring integrated inflation systems.
Germany
Notified body capacity under EU MDR implementation has concentrated conformity assessment activity around TÜV SÜD and BSI Group, extending time-to-market for new expander geometries. Harmonized assessment pathways are accelerating clearances for silicone-based orbital implants across German hospital procurement networks. University hospitals in Heidelberg and Munich anchor reconstructive surgery demand through standardized early-intervention protocols for pediatric socket defects.
Brazil
ANVISA's accelerated pathway for Class III devices with prior FDA clearance creates a two-year market lead window before full EU MDR certification completes. São Paulo's concentrated private hospital networks generate demand for premium-grade silicone expanders in post-enucleation reconstruction. The regulatory arbitrage opportunity attracts manufacturers seeking South American market establishment ahead of European certification finalization.
United Kingdom
Manchester Royal Eye Hospital and Moorfields Eye Hospital maintain specialized oculoplastic units with standardized procurement for congenital and acquired socket defects. MHRA recognition of EU MDR certificates post-Brexit creates parallel regulatory tracking requirements for manufacturers serving both markets. NHS England value analysis committees are consolidating supplier relationships around full-procedure bundles encompassing expanders through permanent implants.
Japan
PMDA marketing authorization requirements for silicone-based implants emphasize extended biocompatibility testing protocols beyond ISO 10993 baselines. University hospitals in Tokyo and Osaka concentrate demand for precision-manufactured dual-plane expander configurations. The aging population trajectory is expanding acquired socket defect cases requiring reconstructive intervention, though reimbursement pathways for pediatric congenital cases remain more established.
Orbital Tissue Expander Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the market structure. Vertically integrated polymer suppliers with captive silicone production anchor the cost-efficient tier, while specialized oculoplastic portfolios with regulatory depth occupy premium positioning. Three strategic archetypes dominate: diversified medical device conglomerates with reconstructive surgery divisions, pure-play orbital implant specialists with ISO-certified manufacturing protocols, and contract manufacturers serving private-label distributors. Competitive moves center on M&A activity to acquire polymer fabrication capabilities and strategic partnerships with academic medical centers for clinical validation data.
Among diversified conglomerates, Mentor and Allergan exemplify the integrated medical device archetype with reconstructive surgery channel presence. Silimed occupies a distinct position within the European regulatory specialization tier, leveraging notified body relationships and ISO-certified manufacturing depth. These three companies represent the primary competitive anchors across cost leadership, premium portfolio, and regulatory arbitrage strategies respectively.
| Leading Market Players |
|---|
| Silimed |
| Network Medical Products Ltd. |
| Innovia LLC |
| Mentor (Johnson & Johnson) |
| Allergan (AbbVie Inc.) |
| IOP Ophthalmics |
| Bio-Eye Orbital Implants |
| Sientra, Inc. |
| FCI Ophthalmics, Inc. |
| Others |
Value Network & Pricing Analysis
Dual-plane expander adoption replacing single-chamber silicone configurations is redrawing procurement geography and compressing margin structures across manufacturer tiers. This substitution dynamic pulls polymer fabrication toward specialized oculoplastic clusters in Texas and Florida while forcing price realignment between established silicone suppliers and next-generation dual-plane specialists.
Pricing Analysis
FDA 510(k) clearance tiers dictate the pricing structure across implant categories, separating premium dual-plane configurations from standard silicone single-chamber devices. Price differentiation rests on ISO 10993 certification depth and injection port complexity, with academic medical centers absorbing premium markups for bundled procedure kits. Cost compression in the standard silicone tier is intensifying because of polymer feedstock volatility linked to automotive and semiconductor sector demand. Ambulatory surgical centers exhibit the sharpest price sensitivity, while pediatric ophthalmology departments at major children's hospitals prioritize clinical outcomes over unit cost.
Supply Chain Analysis
Inventory segregation requirements for pre-MDR and post-MDR device lots have extended lead times for European hospital procurement committees. Medical-grade silicone elastomer production concentrates in Germany and the United States, with dual-plane expander assembly increasingly tethered to specialized oculoplastic manufacturing facilities in Texas and Florida. Raw material dependencies center on platinum-cured silicone polymers, barium sulfate radiopaque additives, and sub-millimeter valve components sourced from precision medical device suppliers. Single-source vulnerability in notified body certification capacity under EU MDR implementation creates regulatory chokepoints. Distribution runs through direct manufacturer field organizations for high-volume hospital networks and regional medical device distributors for mid-tier facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The orbital tissue expander market sits in a post-regulatory-shock recovery phase, with EU MDR implementation delays creating temporary supply constraints that favor manufacturers with dual FDA-ANVISA clearance strategies.
For Market Incumbents: Fortify polymer supply chain control through backward integration into medical-grade silicone production or long-term offtake agreements with German and US feedstock suppliers. Deepen regulatory arbitrage capabilities by accelerating ANVISA submissions ahead of full EU MDR certification, while investing in cloud-based traceability infrastructure to satisfy Article 10 post-market surveillance requirements. For New Entrants and Emerging Players: Differentiate on remote patient monitoring integration, embedding Bluetooth-enabled pressure sensors in expander ports to capture rural and exurban populations excluded from specialized oculoplastic care. Target aesthetic orbital contouring applications in Beverly Hills and Miami cosmetic practices as the most penetrable white-space segment, deploying cash-pay pricing models and direct-to-physician educational programs. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated polymer specialists with captive silicone production and established notified body relationships. Acquisition targets should demonstrate ISO 13485 manufacturing protocols and dual regulatory filing experience across FDA and EU MDR pathways. The signal to watch is notified body capacity expansion announcements, which would compress certification timelines and revalue regulatory arbitrage strategies.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Optimization | Streamlined premarket notification accelerates silicone implant clearances for manufacturers with established biocompatibility profiles. |
| EU MDR Certification Investment | Notified body relationship depth determines market access sequencing across German and French hospital procurement networks. |
| Hospital System Partnership | Cleveland Clinic and Mayo Clinic value analysis committees consolidate supplier relationships around full-procedure bundles. |
| Software Companion Development | Bluetooth-enabled pressure sensors enable telemedicine follow-up and expand addressable geography beyond metropolitan oculoplastic clusters. |
| Reimbursement Strategy | Pediatric congenital anophthalmos protocols at Boston Children's Hospital and Cincinnati Children's drive stable bundled reimbursement visibility. |
Research Methodology
Operator-level perspectives from oculoplastic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation across FDA 510(k) filings, EU MDR notified body documentation, hospital procurement databases, and CMS Medicare reimbursement schedules. Bottom-up demand modeling triangulated against top-down market sizing across product type, application, end user, and distribution channel dimensions.
Sensitivity analysis informed the analytical framework across the projection horizon, with segmentation modeling spanning silicone versus dual-plane configurations, reconstructive versus aesthetic applications, and hospital versus ambulatory surgical center end users. CAGRs derived from procedure volume trajectories, reimbursement pathway stability, and regulatory clearance velocity. Industry-specific forecast inputs incorporated pediatric ophthalmology department expansion plans and ambulatory oculoplastic suite construction pipelines.
The analysis sits within stated boundaries; outcomes outside stable FDA 510(k) clearance timelines and resolved EU MDR notified body capacity constraints would require recalibration. Forecasts reflect documented assumptions regarding polymer feedstock price stability and specialist surgeon training pipeline adequacy. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Australia General Surgical Devices Market
Medical Devices
Novel Vaccine Delivery Systems Market
Medical Devices
Digital Impression System Market
Medical Devices
Ablation Devices Market
Medical Devices
South Africa Digital X-Ray Devices Market
Medical Devices
Leadless Pacemakers Market
Medical Devices
Europe Micro Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Endoscopic Mucosal Resection Device Market
Medical Devices
South Korea Respiratory Devices Market
Medical Devices
Global Portable Ultrasound Equipment Market
Medical Devices
Injectable Bulking Agents Market
Medical Devices
Electroencephalography (EEG) Systems Market
Medical Devices
Smart Medical Devices Market
Medical Devices
Global Digital Therapeutic Devices Market
Medical Devices
Laryngeal Airway Mask Market
Medical Devices
Global Ileostomy Market