
 Acne Treatment Devices Market | 2026-2036
Acne Treatment Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Acne Treatment Devices Market Analytics
Korean aesthetic device manufacturing is broadening its export footprint across Southeast Asia and the Middle East. Lumenis Ltd anchors its position through deep vertical integration in laser source production. Candela Corporation competes on R&D intensity with sustained patent filings in fractional radiofrequency technology.
Acne treatment devices encompass electrically or optically powered instruments engineered to reduce sebum output, bacterial colonization, or follicular inflammation through controlled energy delivery, typically operating at wavelengths between 400 nm and 1,064 nm or frequencies below 6 MHz. These systems serve dermatology practices, hospital outpatient departments, and direct-to-consumer channels seeking alternatives to pharmaceutical regimens. Light therapy devices occupy the largest installed base due to lower capital requirements and gentler patient recovery profiles, while laser treatment systems capture premium margin pools from scar revision and cystic acne protocols. Home user penetration is accelerating fastest through online retail channels, though dermatology centers retain the highest revenue per procedure.
FDA 510(k) clearances and CE marking under the EU MDR govern device safety and clinical claim substantiation, with FDA scrutiny intensifying for at-home light therapy systems marketed with drug-like efficacy language. The EU AI Act introduces emerging compliance obligations for devices incorporating automated skin assessment algorithms. Stakeholders must monitor regulatory divergence between US and European evidentiary standards for combination therapy platforms.
Market Dynamics
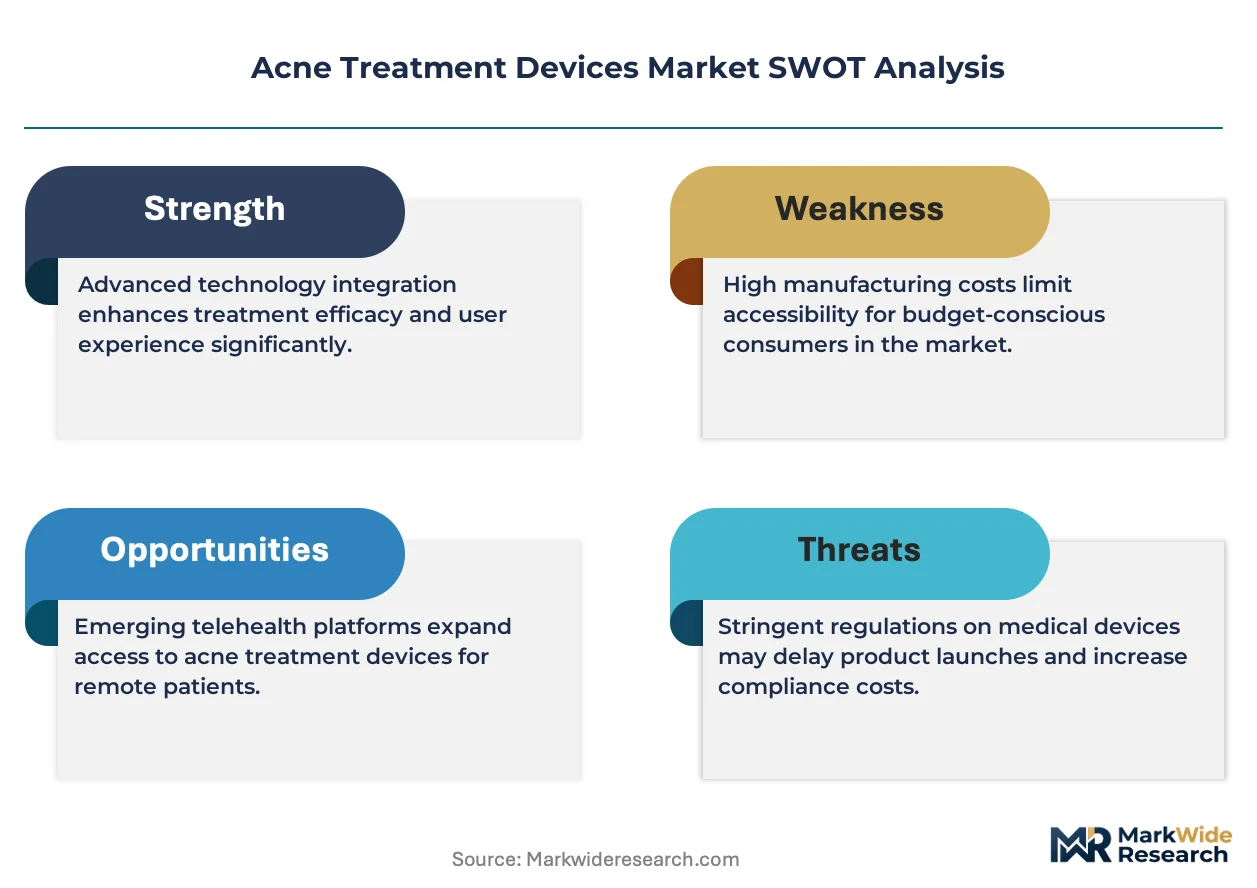
FDA documentation tightening for light-based efficacy claims is compressing product development timelines while forcing manufacturers to front-load clinical validation costs, reshaping competitive entry barriers across the acne treatment device landscape.
Growth Catalysts
- EU AI Act compliance pathways:Automated skin assessment algorithms embedded in combination therapy platforms gain commercial legitimacy through structured conformity assessment, accelerating dermatology center procurement of intelligent diagnostic-therapeutic systems.
- Home-use channel expansion:Direct-to-consumer online retail penetration for LED mask devices intensifies as Korean manufacturing clusters scale output for Southeast Asian e-commerce platforms, bypassing traditional clinic distribution.
- Combination therapy standardization:Aesthetic clinic chains in Seoul and Busan consolidate protocols around multi-modality platforms integrating blue light, fractional radiofrequency, and topical delivery, creating template demand for integrated systems.
Market Restraints
- Clinical validation cost inflation:FDA 510(k) pathway documentation requirements for at-home light therapy systems demand expanded photobiological safety and efficacy datasets, extending time-to-market by 12-18 months for novel wavelength configurations.
- Optical component supply concentration:High-power diode laser sources for 1,064 nm acne scar protocols depend on German and Japanese precision optics suppliers, exposing device manufacturers to allocation risk during semiconductor substrate shortages.
- Pharmaceutical substitution persistence:Oral isotretinoin and topical retinoid regimens retain insurer reimbursement advantages over capital equipment purchases, constraining hospital outpatient department budget reallocation toward device acquisition.
Strategic Opportunities
- Middle East aesthetic clinic buildout:Dubai and Riyadh dermatology center expansion creates unserved demand for mid-power LED systems positioned between home-use masks and premium laser platforms, with MOHAP and SFDA import frameworks streamlining device registration.
- EU MDR Article 120 transition:Legacy device recertification deadlines compress competitor pipelines, opening market share capture windows for manufacturers with proactive clinical evidence packages and notified body relationships.
- Telemedicine-integrated home monitoring:Smartphone-connected treatment adherence tracking and remote dermatologist consultation bundling with direct-ship device sales creates recurring revenue attachment opportunities beyond hardware margins.
Industry Challenges
- Photobiology specialist scarcity:Device manufacturers face recruitment competition for laser safety officers and clinical study directors capable of designing ISO 10993-compliant biocompatibility protocols for novel optical delivery systems.
- Legacy system interoperability:Dermatology centers with installed base fractional CO2 platforms encounter integration friction when layering radiofrequency modules, requiring custom interface development and extended field service deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acne Treatment Devices Market |
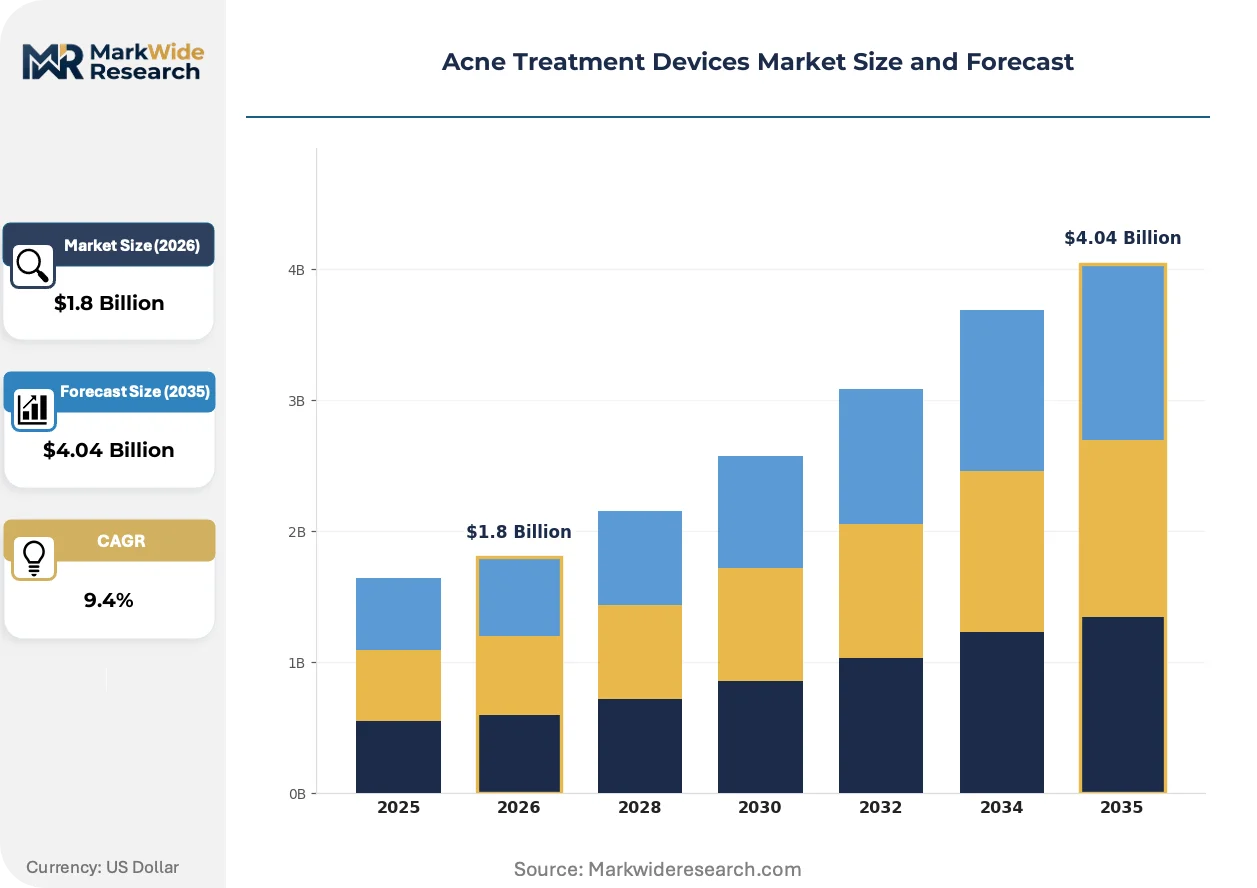
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Light Therapy, Laser Treatment, Microdermabrasion, Radiofrequency End User: Clinics, Hospitals, Home Users, Dermatology Centers Treatment Modality: Electrical, Chemical Peel, Extractions, Combination Therapy Distribution Channel: Online Retail, Direct Sales, Medical Supply Stores, Distributors |
| Companies Covered | Lumenis Ltd, Candela Corporation, Alma Lasers Ltd, Cutera Inc, Sciton Inc, EL.EN. S.p.A., Fotona d.o.o., Venus Concept Inc, Erchonia Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acne Treatment Devices Market Evolving Landscape
Convergence between diagnostic imaging and therapeutic energy delivery is compressing the traditional separation between assessment and treatment phases, while regulatory frameworks for algorithmic devices mature in parallel with hardware innovation cycles.
Multi-wavelength LED arrays with integrated melanin density sensors are unifying real-time skin-type calibration with automated fluence adjustment, eliminating operator-dependent parameter selection. Korean device OEMs deploy these systems across franchised clinic networks in Vietnam and Thailand, compressing training requirements and reducing treatment variability. The technology is unifying hardware and software revenue streams through mandatory cloud connectivity for algorithm updates, shifting margin capture toward recurring licensing.
FDA enforcement discretion letters targeting at-home light therapy manufacturers using drug-like efficacy language are compelling marketing vocabulary standardization and substantiation documentation restructuring. Device firms with existing pharmaceutical partnerships leverage clinical affairs infrastructure to accelerate compliant claim development, while pure-play hardware entrants face compliance capability gaps. Direct-to-consumer brands with US market exposure are responding by establishing medical advisory boards and restructuring influencer content review protocols.
Subscription-based device access programs for cystic acne patients are displacing outright purchase models in urban US dermatology practices, with monthly fees bundling hardware, consumables, and telemedicine follow-up. This restructuring concentrates patient lifetime value calculation and retention risk with device manufacturers rather than clinics. California and New York metropolitan areas exhibit highest penetration of these arrangements, where high commercial real estate costs incentivize practices to minimize capital equipment inventory.
Acne Treatment Devices Market Segmentation
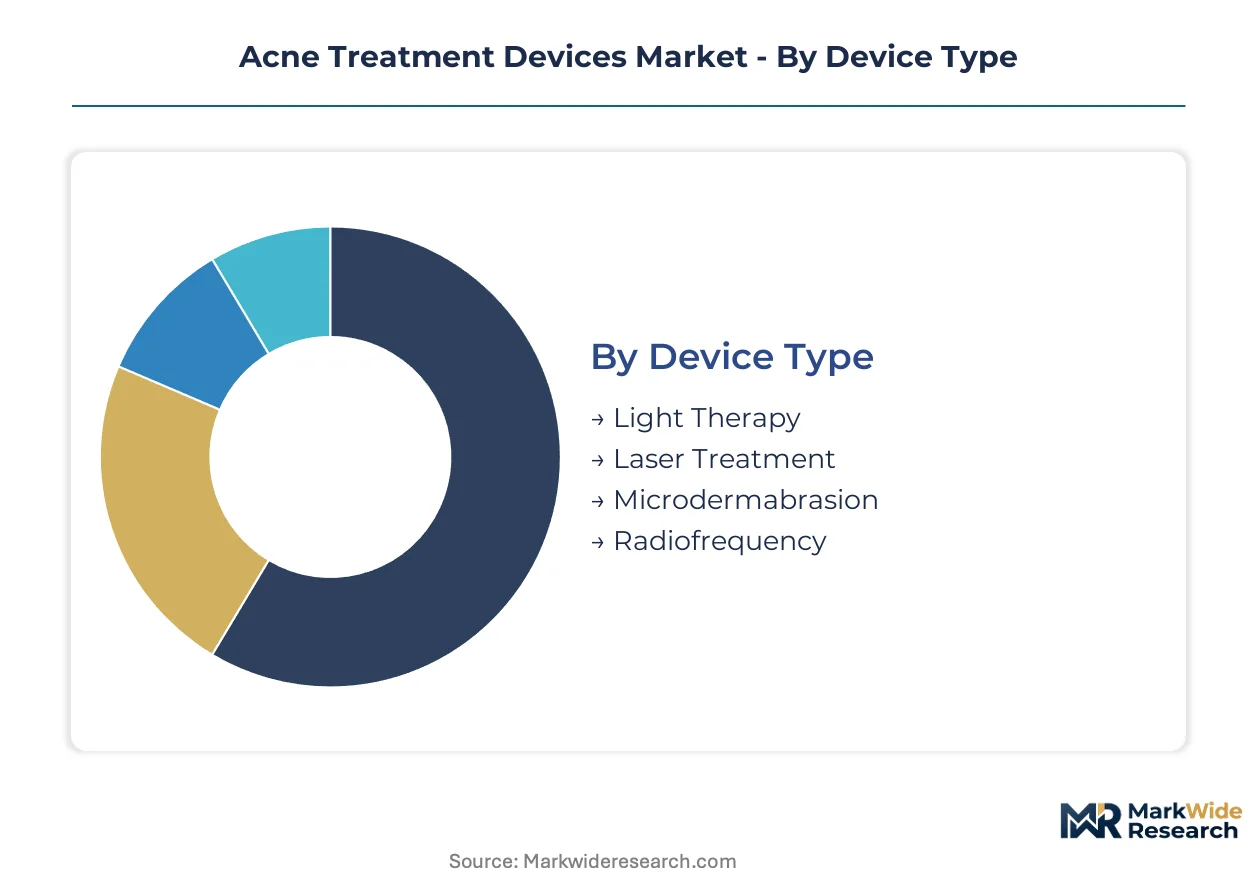
Acne treatment device purchasing decisions diverge sharply across clinical versus home-use contexts, with upgrade cycles and replacement timelines varying by an order of magnitude between hospital procurement departments and direct-to-consumer channels. Understanding these segment-specific rhythms illuminates where manufacturers must front-load service infrastructure versus where subscription bundling captures recurring revenue.
Device Type:
Replacement cycles stretch from 3-5 years for capital laser platforms to 12-18 months for home-use LED masks, compressing upgrade revenue recognition windows for lower-tier modalities.
- Light Therapy:Blue and red LED arrays operating between 415 nm and 633 nm dominate installed base metrics through lower capital thresholds and minimal training requirements. Dermatology centers in Seoul and Busan standardize these systems for maintenance protocols between aggressive laser sessions, while Southeast Asian e-commerce channels move mask-format devices direct to consumers.
- Laser Treatment:Fractional and pulsed dye systems at 585 nm and 1,064 nm wavelengths command premium positioning for cystic acne and scar revision. Demand concentrates in Dubai and Riyadh aesthetic clinic buildouts where MOHAP registration pathways favor established 510(k) cleared platforms over novel entrants.
- Microdermabrasion:Crystal and diamond-tip abrasion systems serve as entry-level clinic offerings with consumable-driven revenue models.
- Radiofrequency:Fractional RF modules integrate with existing CO2 platforms, requiring custom interface development for legacy system compatibility.
Volume placements concentrate in Light Therapy; the faster expansion belongs to Laser Treatment.
End User:
Procurement authority and budget allocation mechanisms fragment across institutional purchasing committees, individual physician practices, and direct-to-consumer decision-making.
- Clinics:Independent aesthetic practices and franchise chains drive combination therapy platform adoption, with Korean clinic networks in Vietnam and Thailand creating template demand for standardized protocols.
- Hospitals:Outpatient dermatology departments face capital equipment budget competition from pharmaceutical reimbursement advantages for oral isotretinoin regimens.
- Home Users:Smartphone-connected LED masks with treatment adherence tracking represent the steepest expansion trajectory, with California and New York metropolitan areas showing highest subscription program penetration.
- Dermatology Centers:Academic and high-volume private centers retain the highest revenue per procedure through premium laser scar revision protocols.
Capital commitment intensity peaks at Dermatology Centers; Home Users are gaining share fastest through channel bypass strategies.
Treatment Modality:
Margin capture shifts from hardware-only sales toward consumable attachment and software licensing as modalities integrate diagnostic and therapeutic phases.
- Electrical:High-frequency and galvanic current devices serve professional extraction preparation with minimal consumable requirements.
- Chemical Peel:Device-assisted acid delivery systems concentrate in European aesthetic practices navigating EU MDR Article 120 recertification deadlines.
- Extractions:Vacuum and ultrasonic extraction tools occupy mid-tier clinic positioning with 24-36 month replacement cycles.
- Combination Therapy:Multi-modality platforms integrating blue light, fractional radiofrequency, and topical delivery command the fastest adoption velocity among Seoul clinic chains seeking protocol standardization.
Recurring revenue attachment concentrates in Combination Therapy; Chemical Peel device placements face regulatory compression.
Distribution Channel:
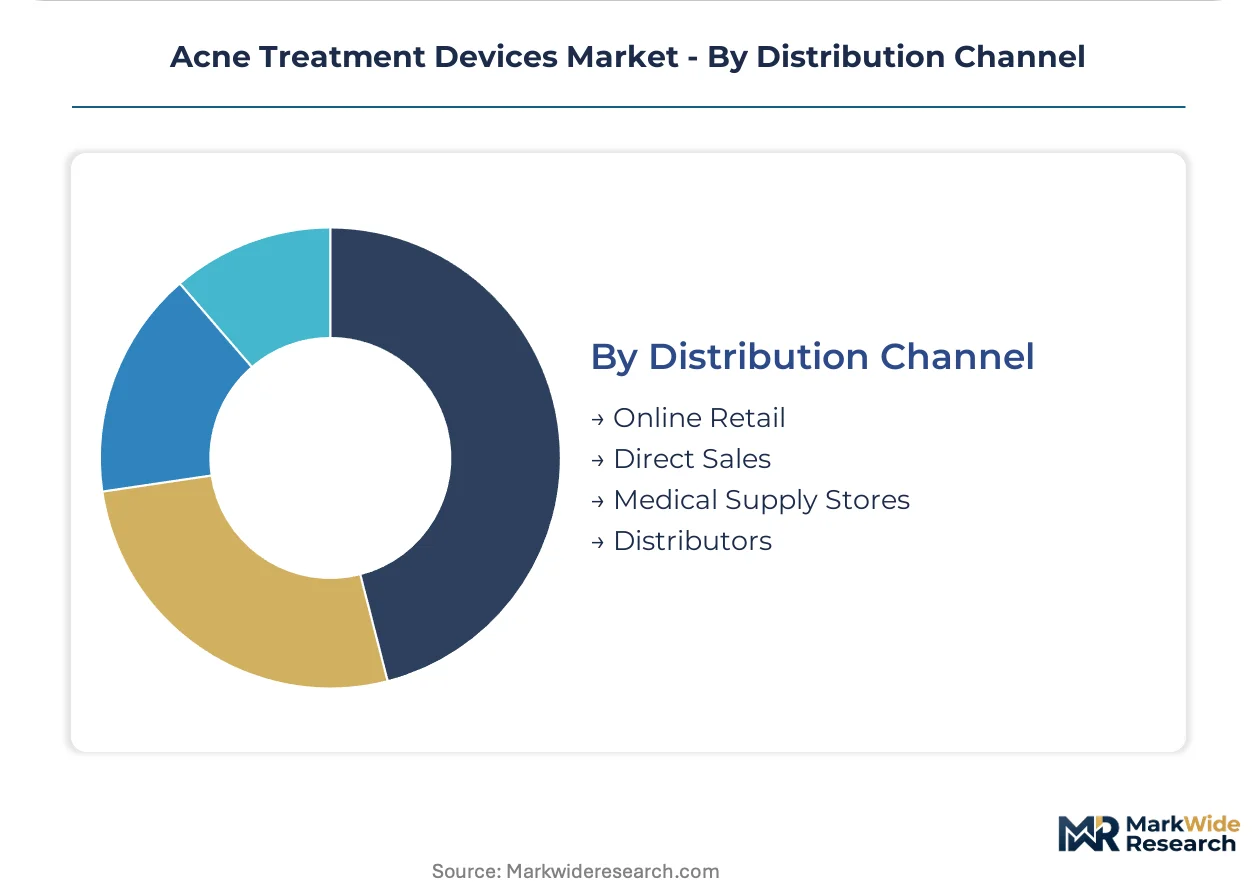
Channel selection determines compliance burden intensity, with medical device registration requirements varying sharply across direct clinical sales versus consumer retail pathways.
- Online Retail:Korean manufacturing clusters scale LED mask output for Southeast Asian e-commerce platforms, bypassing traditional clinic distribution entirely.
- Direct Sales:Capital laser platforms require field service deployment and clinical training infrastructure, favoring manufacturer-controlled relationships with dermatology centers.
- Medical Supply Stores:Regional distributors stock mid-tier microdermabrasion and extraction devices for independent clinic procurement.
- Distributors:Third-party logistics networks manage SFDA and MOHAP import framework navigation for Middle East clinic buildouts.
Transaction volume concentrates in Online Retail; Direct Sales retains the highest margin per unit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-power diode laser sources for 1,064 nm acne scar protocols concentrate in German and Japanese precision optics clusters, anchoring device manufacturing geography to these supplier bases.
United States
Dermatology centers across California and New York metropolitan areas are expanding device fleets as patient volumes climb. FDA 510(k) clearances govern device safety and clinical claim substantiation, with scrutiny intensifying for at-home light therapy systems. Academic medical centers in Boston and Stanford retain the highest revenue per procedure through premium laser scar revision protocols.
South Korea
Aesthetic clinic chains in Seoul and Busan are standardizing acne protocols around combination therapy platforms. MFDS regulates medical device registration with pathways that favor established clinical evidence packages. Manufacturing clusters in the Seoul Capital Area scale LED mask output for Southeast Asian e-commerce platforms, bypassing traditional clinic distribution.
Germany
Precision optics suppliers in Baden-Württemberg and Bavaria dominate high-power diode laser source production for 1,064 nm protocols. EU MDR Article 120 recertification deadlines compress competitor pipelines, opening market share capture windows. Frankfurt and Munich dermatology centers drive demand for mid-power LED systems positioned between home-use masks and premium laser platforms.
United Arab Emirates
Dubai and Riyadh dermatology center expansion creates unserved demand for mid-power LED systems. MOHAP import frameworks streamline device registration for manufacturers with existing 510(k) clearances. Aesthetic clinic buildouts in Dubai Healthcare City concentrate procurement authority among franchise chains seeking standardized protocols.
Japan
PMDA governs medical device approval with evidentiary standards that diverge from US and European requirements. Precision optics suppliers in the Chubu region around Nagoya anchor semiconductor substrate supply for laser source manufacturers. Tokyo and Osaka dermatology centers retain premium positioning for fractional radiofrequency scar revision systems.
Acne Treatment Devices Market Competitive Landscape
Global majors compete with regional champions across regulatory compliance capabilities and clinical validation infrastructure. The vendor base stratifies into three tiers: integrated laser source manufacturers with captive optics supply, assembly specialists dependent on third-party diodes, and direct-to-consumer brands leveraging Korean OEM manufacturing. Strategic moves concentrate on M&A for clinical affairs capabilities and geographic expansion through distributor relationships in Middle East markets.
Within the integrated manufacturing tier, Lumenis Ltd and Candela Corporation exemplify archetypes of vertical control over laser source production. Alma Lasers Ltd occupies a position bridging professional clinic systems and emerging home-use modalities. These three anchors represent divergent bets on whether margin capture shifts toward hardware-only sales or recurring software licensing and consumable attachment.
| Leading Market Players |
|---|
| Lumenis Ltd |
| Candela Corporation |
| Alma Lasers Ltd |
| Cutera Inc |
| Sciton Inc |
| EL.EN. S.p.A. |
| Fotona d.o.o. |
| Venus Concept Inc |
| Erchonia Corporation |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up device specialists have consolidated manufacturing footprints across Baden-Württemberg and Seoul Capital Area, compressing supplier bargaining power while enforcing three-year service contract bundling that locks clinic procurement committees into predictable spend profiles. This ownership concentration translates directly into pricing discipline, as portfolio companies cross-subsidize R&D amortization across multiple brand portfolios while maintaining premium positioning through FDA 510(k) clearance moats.
Pricing Analysis
Warranty and field service bundling separates premium laser platforms from unbundled home-use LED masks, with dermatology centers paying 18-24% attach rates for multi-year coverage while direct-to-consumer channels absorb replacement risk. Three-tier pricing structure across premium, standard, and economy levels stratifies by optical power output and algorithmic diagnostic capability, with FDA-cleared scar revision systems commanding the widest spreads. Cost compression in mid-power LED segments is intensifying because Korean manufacturing clusters are scaling output for Southeast Asian e-commerce platforms. Hospital outpatient departments exhibit the highest price sensitivity due to pharmaceutical reimbursement competition, while Dubai franchise chains show lowest sensitivity when protocols standardize around combination therapy platforms.
Supply Chain Analysis
Domestic-content mandates in China's NMPA registration pathway and India's PLI scheme for medical electronics are reshaping sourcing decisions, pressuring device assemblers to qualify alternative diode suppliers outside traditional German and Japanese precision optics clusters. High-power laser sources for 1,064 nm protocols draw from Baden-Württemberg and Bavaria, while LED array manufacturing concentrates in Seoul Capital Area and Shenzhen. Single-source vulnerability runs through Japanese semiconductor substrate suppliers for fractional radiofrequency modules. Distribution runs through third-party logistics networks navigating SFDA and MOHAP import frameworks for Middle East clinic buildouts, bypassing traditional medical supply store channels for capital equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multi-wavelength LED arrays with integrated melanin density sensors are displacing operator-dependent parameter selection across Korean franchise networks, compressing the traditional separation between diagnostic assessment and therapeutic delivery. This technology transition phase rewards manufacturers who unify hardware and software revenue streams through mandatory cloud connectivity.
For Market Incumbents: Lock in captive supply of high-power diode laser sources through backward integration into German precision optics partnerships, insulating against allocation risk during semiconductor substrate shortages. Prioritize clinical affairs infrastructure investment to accelerate FDA 510(k) documentation for at-home light therapy systems facing tightened efficacy claim scrutiny, defending against pure-play hardware entrants with compliance capability gaps. For New Entrants and Emerging Players: The price-point gap between premium laser scar revision systems and economy home-use LED masks creates white-space opportunity for mid-power systems in Dubai and Riyadh dermatology center buildouts. Target MOHAP-registered platforms positioned between mask-format devices and capital equipment, leveraging third-party logistics networks for SFDA import navigation rather than building direct sales infrastructure. For Investors and Strategic Acquirers: EU MDR Article 120 recertification deadline compression is the leading indicator that legacy device pipelines will create market share capture windows for manufacturers with proactive clinical evidence packages. The acquisition target archetype combines notified body relationships with algorithmic diagnostic-therapeutic platforms. Watch MFDS registration velocity for Korean OEMs exporting to Southeast Asian e-commerce channels as the signal for home-use channel expansion sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Article 120 recertification deadlines compress competitor pipelines for combination therapy platforms. |
| Software Companion Development | Smartphone-connected treatment adherence tracking creates recurring revenue attachment beyond hardware margins. |
| Hospital System Partnership | Subscription-based device access programs concentrate patient lifetime value with manufacturers rather than clinics. |
| FDA Submission | 510(k) clearance documentation tightening forces front-loaded clinical validation costs for light-based efficacy claims. |
| Reimbursement Strategy | Pharmaceutical substitution persistence for oral isotretinoin constrains hospital outpatient department capital reallocation. |
Research Methodology
Multi-period observation of FDA 510(k) clearance timelines, EU MDR notified body assignment rates, and Korean MFDS export certification volumes anchored the trend analysis, supplemented by interviews with dermatology center procurement directors, biomedical engineers designing optical delivery systems, GPO contracts managers, and regulatory affairs leads at device manufacturers. Secondary validation drew from FDA 510(k) database filings, EU MDR Article 120 transition notices, MFDS medical device registration statistics, and customs records for precision optics trade flows. Bottom-up installed base modeling triangulated against top-down procedure volume estimates from hospital procurement databases.
Segment-weighting approaches applied differential growth assumptions across device type, end user, treatment modality, and distribution channel dimensions, with combination therapy platforms receiving distinct algorithmic capability premiums. CAGRs were derived from fitted growth curves calibrated to historical adoption S-cycles for light-based dermatological modalities. Forecast inputs incorporated photobiological safety dataset completion timelines and semiconductor substrate allocation forecasts from precision optics suppliers.
Inputs from FDA enforcement discretion letters and EU MDR notified body capacity reports were available through the study window; gaps in real-time Middle East MOHAP registration processing times introduce uncertainty bands around Dubai and Riyadh market penetration assumptions. Forecasts reflect documented assumptions regarding regulatory pathway efficiency and clinic procurement committee budget reallocation willingness. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Prefilled Syringe Small Molecule Market
Medical Devices
North America Refractive Surgery Devices Market
Medical Devices
Japan Anesthesia Devices Market
Medical Devices
GCC Biopsy Devices Market
Medical Devices
South Africa General Surgical Devices Market
Medical Devices
Bone Power Tools Market
Medical Devices
Organ Care Systems (OCS) Market
Medical Devices
Medical Device Cros Market
Medical Devices
Global Orthopedic Power Tools Market
Medical Devices
Respiratory Inhaler Devices Market
Medical Devices
Continuous Positive Airway Pressure (CPAP) Interface Devices Market
Medical Devices
Vein Illumination Devices Market
Medical Devices
I.V. Fluid Warmer Market
Medical Devices
Global Medical Radiation Shielding Market
Medical Devices
3D Printed Prosthetics Market
Medical Devices
China General Surgical Devices Market