
 Netherlands Artificial Organs and Bionic Implants Market | 2026-2036
Netherlands Artificial Organs and Bionic Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Netherlands Artificial Organs and Bionic Implants Market Foresight
A shortage of specialized biomedical engineers is collapsing development timelines for next-generation neuroprosthetics. Medtronic plc leverages its Galway manufacturing footprint to sustain European supply chain continuity for cardiac rhythm devices. Reboocon Bionics B V anchors its competitive stance through deep specialization in motorized prosthetic knee systems for above-amputation patients.
Artificial organs and bionic implants comprise electromechanical and biological systems designed to replace or augment native physiological functions, typically incorporating biocompatible alloys, polymers, and sensor arrays that interface with neural or muscular tissue. These devices restore motor, sensory, or organ-level performance in patients with congenital defects, traumatic injury, or degenerative disease. Cochlear implants and bionic limbs currently occupy the largest addressable segments, while artificial kidney development attracts the most intensive R&D investment due to chronic dialysis population expansion. Hospitals dominate end-user procurement volume, though home care channels are gaining traction as remote monitoring capabilities mature.
The EU Medical Device Regulation and Dutch Health and Youth Care Inspectorate (IGJ) jointly govern market access, with MDR's enhanced clinical evaluation requirements extending certification cycles for novel implantable devices. ISO 14155 standards for clinical investigation of medical devices further constrain trial design flexibility for manufacturers seeking CE marking. Stakeholders must monitor evolving HTA reimbursement decisions by the National Health Care Institute (ZIN) to anticipate which bionic categories will secure statutory insurance coverage.
Market Dynamics
The EU Medical Device Regulation's enhanced clinical evidence requirements are compressing certification timelines and forcing Dutch manufacturers to restructure premarket validation workflows around ISO 14155 standards.
Growth Catalysts
- Reimbursement Expansion:Dutch insurers are broadening statutory coverage for sensory and mobility restoration devices, directly expanding hospital procurement budgets for cochlear implants and bionic limbs.
- EU MDR Harmonization:The Medical Device Regulation's unified CE marking framework reduces fragmentation across member states, streamlining market access for Dutch manufacturers exporting to Germany and Belgium.
- Randstad Cluster Density:Amsterdam and Rotterdam's concentration of university medical centers creates concentrated demand pools and accelerates clinical feedback loops for device developers.
Market Restraints
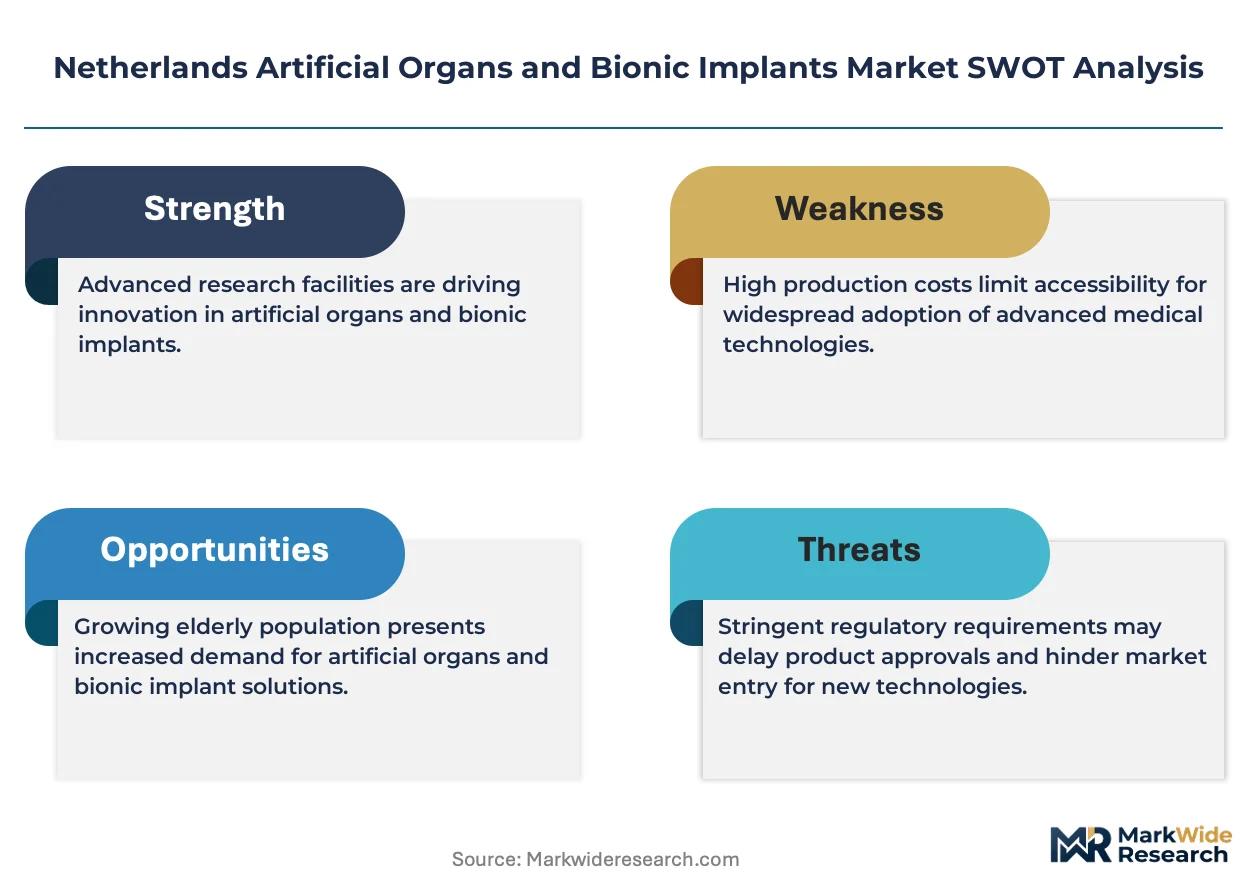
- Titanium Alloy Price Volatility:Input cost swings for biocompatible metals squeeze margin structures for implantable device producers dependent on aerospace-grade titanium supply chains.
- Biomedical Engineer Scarcity:The Netherlands faces acute shortages of specialized neuroprosthetics talent, collapsing development timelines for next-generation electromechanical systems.
- MDR Certification Friction:Extended clinical evaluation cycles under the EU Medical Device Regulation delay product launches by 18-36 months compared to the previous directive.
Strategic Opportunities
- Home Care Channel Expansion:Remote monitoring capabilities are maturing, enabling device manufacturers to bypass hospital procurement and capture recurring revenue from direct patient relationships.
- Artificial Kidney R&D:Chronic dialysis population expansion is redirecting venture capital toward implantable renal replacement systems, creating first-mover advantages for Dutch research consortia.
- ZIN HTA Alignment:Proactive engagement with the National Health Care Institute's health technology assessment processes can secure preferential reimbursement positioning ahead of competitive submissions.
Industry Challenges
- Neural Interface Integration Complexity:Engineering teams struggle to achieve stable long-term signal transduction between sensor arrays and peripheral nervous tissue in above-amputation patients.
- IGJ Inspection Backlogs:The Dutch Health and Youth Care Inspectorate's limited technical staff capacity creates bottlenecks in post-market surveillance audits and adverse event investigations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Netherlands Artificial Organs and Bionic Implants Market |
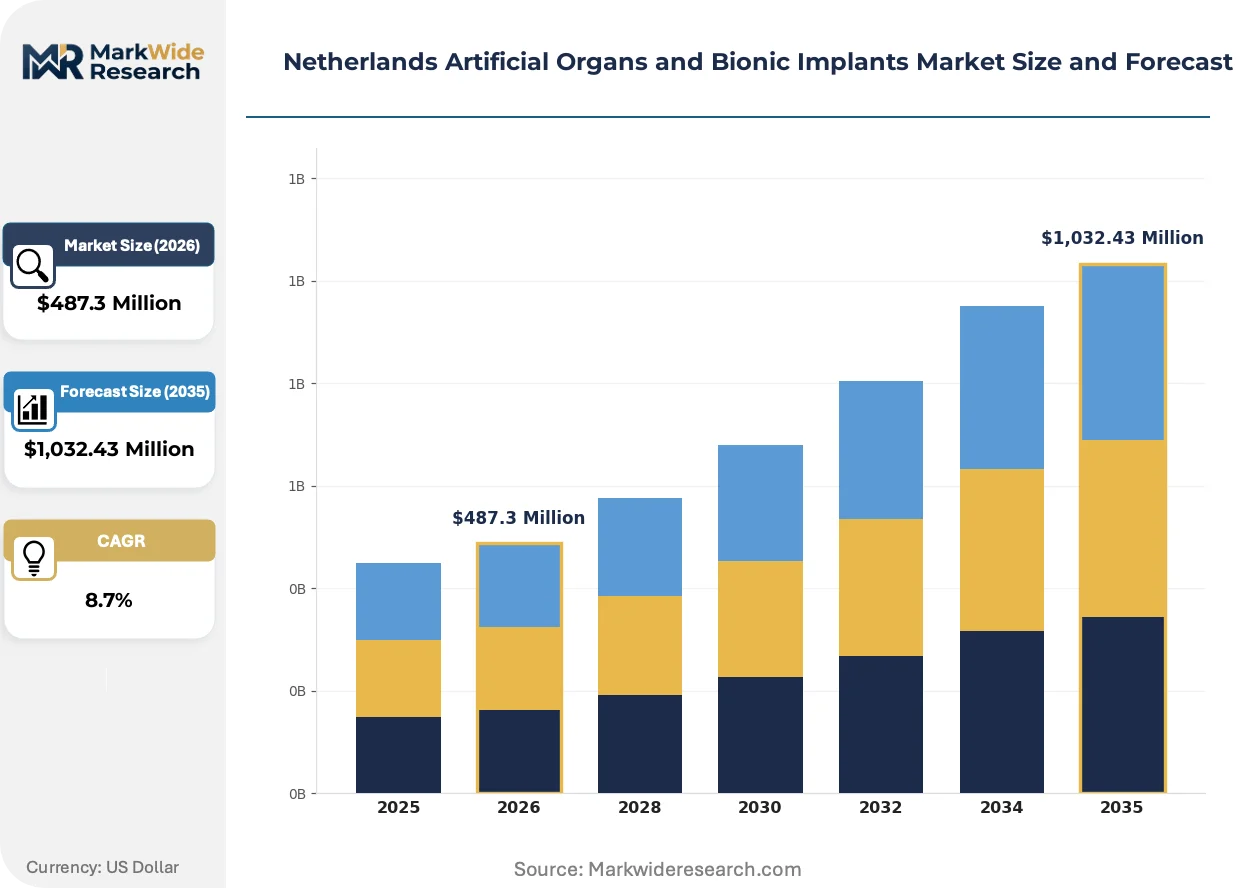
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Artificial Heart, Bionic Limb, Cochlear Implant, Artificial Kidney End User: Hospitals, Rehabilitation Centers, Ambulatory Surgical Centers, Home Care Technology: Mechanical, Electrical, Biochemical, Cybernetic Application: Transplantation, Cosmetic Surgery, Injury Rehabilitation, Deafness Treatment |
| Companies Covered | Ossur, Otto Bock Holding GmbH & Co KG, Medtronic plc, Abbott Laboratories, Reboocon Bionics B V, Boston Scientific Corporation, Sonova Holding AG, Edwards Lifesciences Corporation, Zimmer Biomet, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Netherlands Artificial Organs and Bionic Implants Market Shifts & Advancements
Sensor-embedded prosthetics and closed-loop neurostimulation systems are actively restructuring competitive advantage in Dutch bionic implant development, compressing the gap between laboratory demonstration and clinical deployment.
Motorized microprocessor-controlled knee systems are supplanting passive mechanical prosthetics in above-amputation rehabilitation protocols. Dutch rehabilitation centers are adopting these electromechanical platforms at accelerating pace for traumatic injury patients. The technology is supplanting legacy pneumatic systems and forcing component suppliers to retool around servo motor and lithium polymer battery supply chains.
The EU Medical Device Regulation's post-market clinical follow-up requirements are mandating systematic device performance surveillance across implant lifecycles. Dutch notified bodies are demanding real-world evidence registries that track patient outcomes for minimum five-year horizons. Cardiac rhythm and neurostimulation device categories face the steepest compliance burdens, with manufacturers restructuring quality management systems around MDR Annex XIV clinical evaluation reporting standards.
Hospital procurement committees are consolidating vendor relationships around full-lifecycle service agreements rather than transactional device purchases. Academic medical centers in the Randstad are negotiating multi-year partnerships that bundle implant provision with rehabilitation therapy and remote monitoring subscriptions. This restructuring is most visible in Rotterdam's Erasmus MC and Amsterdam UMC procurement patterns, where value-based contracting frameworks now dominate bionic limb acquisition decisions.
Netherlands Artificial Organs and Bionic Implants Market Segmentation
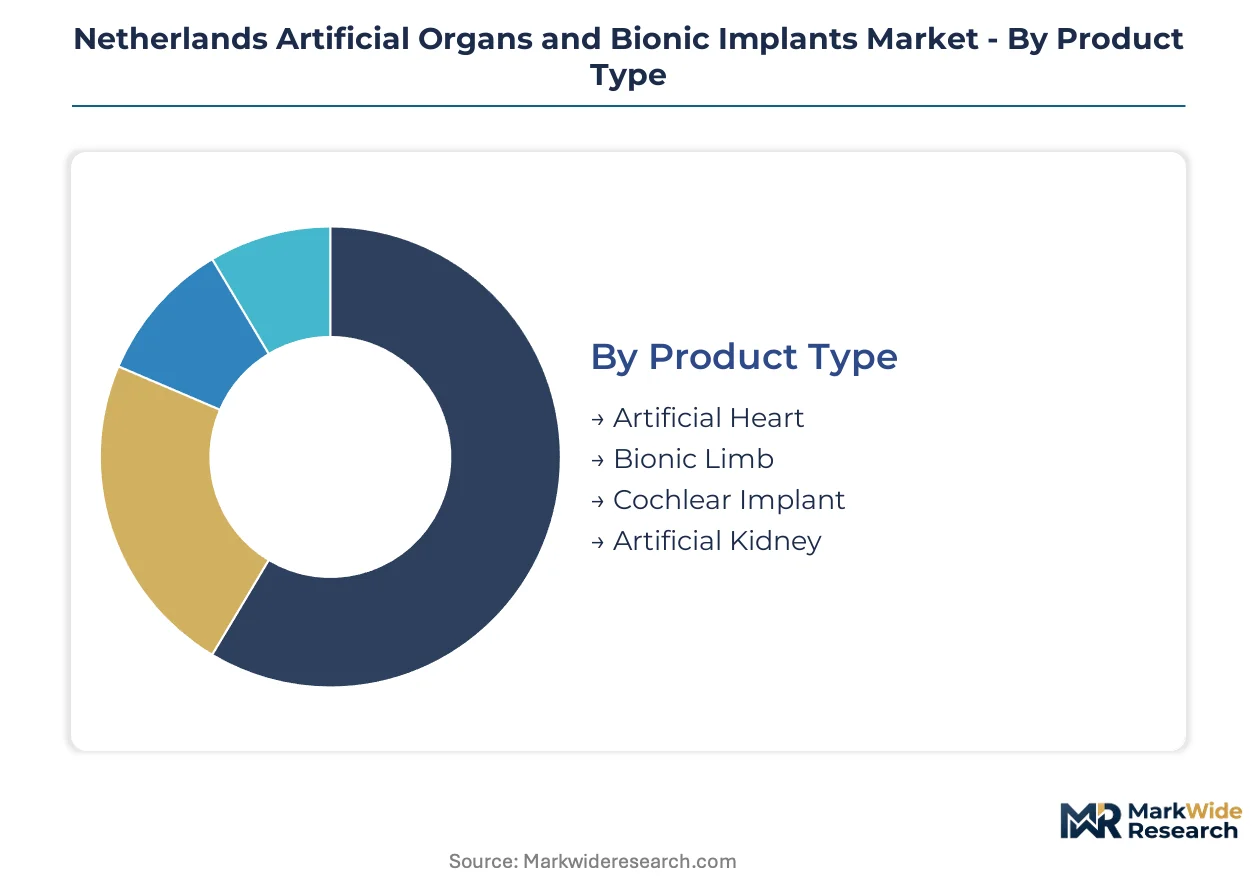
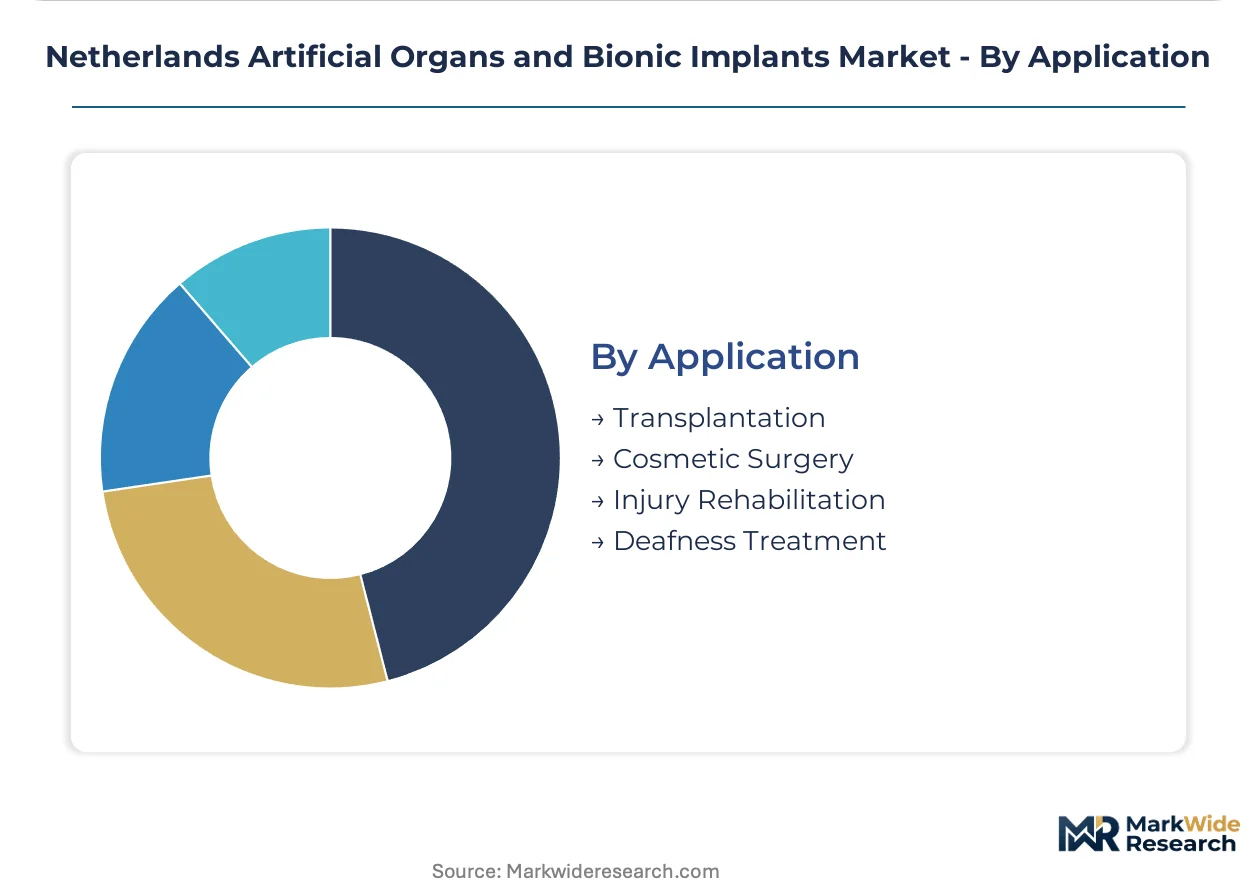
Segmentation in the Dutch artificial organs and bionic implants market reveals how regulatory pathways, reimbursement tiers, and clinical settings reshape procurement priorities across distinct device categories. Understanding these divisions exposes where MDR compliance costs concentrate and which patient populations unlock statutory insurance coverage.
Product Type:
MDR's clinical evidence tiers split product categories into divergent certification timelines, with Class III implantables facing the steepest Annex XIV reporting burdens.
- Artificial Heart:These electromechanical circulatory support systems incorporate ventricular assist devices and total artificial hearts constructed from biocompatible polymers and titanium alloys. Demand concentrates in Rotterdam's Erasmus MC and Amsterdam UMC thoracic surgery departments, where heart failure patient volumes and transplant waiting list pressures drive procurement. MDR's enhanced clinical evaluation requirements extend certification cycles for these Class III devices.
- Cochlear Implant:Multi-channel electrode arrays surgically embedded in the cochlea restore auditory signal transduction for severe-to-profound sensorineural hearing loss. Dutch insurers have broadened ZIN reimbursement for pediatric and adult candidates, expanding hospital procurement budgets at Radboudumc and Leiden University Medical Center otolaryngology units.
- Bionic Limb:Myoelectric and motorized prosthetic systems replace or augment motor function following traumatic amputation or congenital deficiency. Rehabilitation centers in the Randstad cluster are consolidating vendor relationships around full-lifecycle service agreements for these devices.
- Artificial Kidney:Implantable renal replacement systems and wearable dialysis platforms target chronic kidney disease populations dependent on thrice-weekly hemodialysis. Dutch research consortia are redirecting venture capital toward this category amid dialysis patient expansion.
Established volume favors Cochlear Implant; emerging adoption favors Artificial Kidney.
End User:
Procurement authority and reimbursement pathways fragment across institutional settings, with academic medical centers commanding premium device selection and home care channels bypassing traditional hospital purchasing committees.
- Hospitals:University medical centers in Amsterdam, Rotterdam, and Utrecht dominate implantable device procurement through centralized purchasing committees that negotiate multi-year vendor partnerships. These institutions absorb the steepest MDR compliance costs through dedicated regulatory affairs departments.
- Rehabilitation Centers:Specialized facilities in the Randstad metropolitan cluster prescribe and fit bionic limbs, cochlear implants, and neuroprosthetics during post-surgical recovery protocols. IGJ inspection requirements govern their device handling and patient outcome reporting obligations.
- Ambulatory Surgical Centers:These facilities concentrate same-day implant procedures for cochlear and select bionic devices, competing on throughput and cost efficiency rather than research prestige.
- Home Care:Remote monitoring capabilities are maturing for cardiac rhythm and neurostimulation devices, enabling direct manufacturer-patient relationships outside hospital procurement channels. This segment climbs the fastest as telemedicine infrastructure penetrates Dutch healthcare delivery.
Procurement volume concentrates in Hospitals; regulatory flexibility expands fastest in Home Care.
Technology:
Technical sophistication determines manufacturing complexity, supply chain dependencies, and the depth of specialized biomedical engineering talent required for development.
- Electrical:Microprocessor-controlled systems with sensor arrays and closed-loop feedback dominate cochlear implants, cardiac rhythm devices, and motorized prosthetic knees. These platforms require lithium polymer batteries and servo motor supply chains that Dutch manufacturers source through Medtronic's Galway operations.
- Cybernetic:Neural interface systems attempting direct nervous tissue signal transduction represent the frontier of above-amputation prosthetic control. Reboocon Bionics anchors its competitive stance in motorized knee systems that approach this integration threshold.
- Mechanical:Passive pneumatic and hydraulic prosthetic components retain cost advantages in standard care pathways but are losing share to electromechanical alternatives.
- Biochemical:Bioartificial organs incorporating living cells within synthetic scaffolds remain preclinical for renal and hepatic applications, constrained by vascularization and immune rejection challenges.
Reimbursement security favors Electrical; R&D investment intensity favors Cybernetic.
Application:
Clinical indication determines patient eligibility criteria, rehabilitation protocol duration, and the strength of health technology assessment evidence required for ZIN coverage decisions.
- Deafness Treatment:Cochlear implantation for congenital pediatric and acquired adult sensorineural hearing loss carries established ZIN reimbursement codes and predictable clinical outcome metrics. Dutch audiology centers report standardized speech perception scores that satisfy HTA evidentiary requirements.
- Injury Rehabilitation:Traumatic amputation and spinal cord injury populations drive demand for bionic limbs and neuroprosthetics with customized fitting protocols. Randstad rehabilitation facilities are adopting motorized microprocessor knee systems at accelerating pace for these patients.
- Transplantation:Mechanical circulatory support as bridge-to-transplant or destination therapy for end-stage heart failure faces stringent MDR clinical investigation standards under ISO 14155 protocols.
- Cosmetic Surgery:Aesthetic prosthetics and elective implantable devices fall outside statutory insurance coverage, constraining market size to private payment capacity.
Reimbursement stability favors Deafness Treatment; technology innovation potential favors Injury Rehabilitation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Medical Device Regulation anchors regulatory harmonization across European markets, compressing certification timelines for Dutch manufacturers while creating divergent competitive conditions in neighboring jurisdictions. This framework shapes procurement patterns and investment flows across the continent's major medical technology clusters.
Germany
Federal Institute for Drugs and Medical Devices oversight enforces stringent clinical evaluation standards for Class III implantables entering the German market. The KBA maintains separate technical documentation requirements for motorized prosthetic components, creating dual compliance burdens for cross-border suppliers. Berlin and Munich host the largest rehabilitation engineering research consortia, where university hospitals pilot next-generation neuroprosthetic interfaces.
Belgium
Federal Agency for Medicines and Health Products operates mutual recognition agreements with Dutch notified bodies, accelerating CE marking reciprocity for cochlear and cardiac rhythm devices. Brussels-Antwerp corridor concentration of university hospitals creates demand density comparable to the Randstad cluster. Leuven's biomedical engineering faculties supply specialized talent to regional device manufacturers.
France
ANSM post-market surveillance requirements exceed baseline MDR mandates, extending adverse event reporting obligations for implantable cardiac and neural devices. The Île-de-France region concentrates procurement authority through AP-HP central purchasing, negotiating multi-year bionic limb contracts that Dutch exporters target. Lyon and Grenoble host competing rehabilitation technology clusters with overlapping patient catchment areas.
United Kingdom
MHRA operates independent device registration post-Brexit, fragmenting previously unified EU certification pathways for Dutch exporters. NHS England's specialized commissioning frameworks govern access to advanced bionic systems, creating reimbursement uncertainty for continental suppliers. Oxford-Cambridge life sciences corridor attracts Dutch research partnerships seeking alternative clinical trial sites outside EU regulatory jurisdiction.
Switzerland
Swissmedic maintains bilateral recognition agreements with EU notified bodies, preserving market access continuity despite non-member status. Zurich and Basel university hospitals command premium procurement budgets for experimental implantable systems, offering Dutch developers early clinical validation opportunities. The country's private insurance model creates parallel reimbursement channels distinct from statutory European schemes.
Netherlands Artificial Organs and Bionic Implants Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with multinational device conglomerates controlling cardiac rhythm and cochlear implant categories while regional engineering houses dominate motorized prosthetic niches. Market structure reflects divergent capital intensity requirements: electromechanical platforms demand semiconductor supply chain integration, while passive mechanical alternatives tolerate fragmented component sourcing. Three archetypes populate the competitive terrain: diversified medical technology conglomerates with European manufacturing footprints; specialized prosthetic engineering firms with deep orthopedic rehabilitation expertise; and emerging cybernetic interface developers targeting neural signal transduction. Consolidation pressure concentrates in the cardiac and auditory segments, whereas limb prosthetics retain specialist fragmentation due to customization intensity.
Among diversified medical technology conglomerates, Medtronic plc and Abbott Laboratories exemplify the integrated archetype through their European operational scale. Reboocon Bionics B V occupies a distinct position within the specialized tier, representing the motorized prosthetic engineering model anchored in Dutch technical development. These three entities collectively illustrate the competitive spectrum spanning multinational supply chain leverage versus focused biomechanical innovation.
| Leading Market Players |
|---|
| Ossur |
| Otto Bock Holding GmbH & Co KG |
| Medtronic plc |
| Abbott Laboratories |
| Reboocon Bionics B V |
| Boston Scientific Corporation |
| Sonova Holding AG |
| Edwards Lifesciences Corporation |
| Zimmer Biomet |
| Others |
Supply & Pricing Matrix
Medtronic's Galway manufacturing footprint generates scale economies that compress unit costs for cardiac rhythm devices while establishing price floors Dutch competitors cannot undercut without sacrificing MDR compliance investment. This concentration of Class III device production in Ireland shapes procurement negotiations across Amsterdam UMC and Rotterdam's Erasmus MC, where hospital purchasing committees face limited vendor alternatives for ISO 14155-certified supply.
Pricing Analysis
Long-term service agreements dominate bionic limb procurement, with Randstad rehabilitation centers negotiating multi-year contracts that bundle device provision with fitting protocols and remote monitoring subscriptions. Price differentiation separates MDR-certified premium tiers from economy mechanical alternatives, with titanium alloy grade and neural interface sophistication as primary drivers. Cost compression in motorized knee systems intensifies as Reboocon Bionics and Otto Bock compete for above-amputation market share. Academic medical centers exhibit lowest price sensitivity due to research prestige requirements, while ambulatory surgical centers prioritize throughput economics.
Supply Chain Analysis
Strategic stockpiling of aerospace-grade titanium and lithium polymer batteries prevails over just-in-time approaches, given MDR-mandated batch traceability and IGJ inspection readiness requirements. Dutch manufacturers draw from German precision machining, Irish Medtronic assembly operations, and Chinese rare-earth magnet suppliers for servo motor components. Single-source vulnerability concentrates in neural signal processing chips sourced through constrained semiconductor foundry capacity. Distribution runs through hospital procurement committees and GPO frameworks, with home care channels emerging as direct-to-patient alternatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from remote monitoring subscriptions and rehabilitation therapy bundling expands faster than hardware sales, transforming artificial organ vendors into recurring-revenue platforms. This shift rewards manufacturers that integrate software companion development with implant provision.
For Market Incumbents: Shield market position by deepening backward integration into titanium alloy supply through captive relationships with German precision forges, and accelerate MDR Annex XIV clinical evaluation investment to extend certification lead times beyond emerging competitor reach. Neural interface patent thickets and IGJ-established quality management systems serve as defensive moats against low-cost mechanical alternatives. For New Entrants and Emerging Players: CE marking fast-track through Dutch notified bodies with pre-submission engagement on ISO 14155 protocols offers the most penetrable regulatory pathway for artificial kidney and bioartificial organ categories. Target home care channel bypass of hospital procurement committees, where remote monitoring capabilities enable direct patient relationships outside GPO frameworks. White-space concentration in pediatric bionic limb customization and chronic dialysis wearable platforms remains underdeveloped. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cybernetic interface developers with software-defined device architectures, positioning these archetypes for premium valuation multiples. Long-term viability across the analysis window favors platforms with ZIN reimbursement pre-negotiation and MDR technical documentation depth. Monitor IGJ post-market surveillance audit frequency as inflection indicator for regulatory compliance cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical Documentation Investment | Annex XIV clinical evaluation reporting satisfies Dutch Health and Youth Care Inspectorate audit requirements. |
| ZIN Reimbursement Pre-Negotiation | Proactive National Health Care Institute engagement secures statutory insurance coverage ahead of competitive submissions. |
| Remote Monitoring Platform Development | Software companion capabilities enable home care channel bypass of hospital procurement committees. |
| Neural Interface Patent Portfolio Expansion | Signal transduction IP thickets defend against motorized prosthetic commoditization in above-amputation segments. |
| Randstad Academic Medical Center Partnership | Erasmus MC and Amsterdam UMC collaborations accelerate clinical feedback loops for device iteration. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with biomedical engineers, hospital purchasing committee members, rehabilitation center procurement leads, and IGJ regulatory affairs specialists. Secondary validation drew from EU MDR technical documentation databases, ZIN health technology assessment rulings, GPO contract repositories, and ISO 14155 clinical investigation registries. Bottom-up patient population modeling and top-down medical device expenditure triangulation anchored market size estimation.
Across the analysis window, the forecasting framework segmented volume and value by product type, end-user institution, technology sophistication, and clinical application indication. CAGRs derived from regression analysis against chronic dialysis population expansion, reimbursement policy trajectory, and MDR implementation phase-in schedules. Neural interface adoption curves and titanium alloy price volatility indices served as industry-specific sensitivity inputs.
Underlying assumptions cover MDR compliance cost absorption, ZIN coverage expansion continuity, and biomedical engineer supply recovery, with deviation risk concentrated in IGJ inspection capacity constraints and semiconductor foundry allocation. Revision becomes warranted when EU MDR enforcement intensity or rare-earth magnet export restrictions cross materiality thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Asia Pacific Portable X-Ray Devices Market
Medical Devices
North America Ultrasound Probe Disinfection Market
Medical Devices
Global Non-Surgical Skin Tightening Devices Market
Medical Devices
Global Nerve Monitoring System Market
Medical Devices
Aerosol Drug Delivery Devices Market
Medical Devices
Facial Implant Market
Medical Devices
Pressure Ulcer Detection Devices Market
Medical Devices
Electrocautery Devices Market
Medical Devices
Stool Management Systems Market
Medical Devices
Saliva Collection Devices Market
Medical Devices
Digital Migraine Treatment Device Market
Medical Devices
DLIF and XLIF Implants Market
Medical Devices
Global Brachytherapy Devices Market
Medical Devices
IoT Medical Devices Market
Medical Devices
Radiotherapy Positioning Devices Market
Medical Devices
Global Angioplasty Balloons Market