
 Bladder Liners Market | 2026-2036
Bladder Liners Market Size, Share, and Industry Trends Forecast 2026-2036
Bladder Liners Market Outlook
Pharmacy-to-homecare channel flow is tilting as insurers favor direct-to-patient reimbursement models. Kimberly-Clark Corporation leverages its institutional contracts to sustain shelf presence across major retail pharmacy networks. Essity Aktiebolag anchors European distribution through specialized medical supply partnerships, while Cardinal Health competes on logistics scale for hospital system consolidation contracts.
Bladder liners are thin, absorbent hygiene products engineered with polymer cores and non-woven top sheets to capture light-to-moderate urinary leakage while maintaining skin dryness and odor control. Manufacturing employs hot-melt adhesive lamination and fluff pulp compression to achieve targeted absorbency capacities measured in milliliters retained per gram of core material. Disposable liners lead volume due to infection control protocols in clinical settings, though biodegradable material formulations are gaining fastest as environmental compliance hardens across European and North American procurement rules. Custom liners command premium positioning where anatomical fit specifications drive repeat purchasing among post-operative patient segments.
The FDA regulates bladder liners as Class I medical devices under 21 CFR 876.5900, requiring biocompatibility testing and adverse event reporting that shapes product development timelines for US market entrants. The EU MDR and REACH chemical restrictions jointly pressure manufacturers to reformulate super absorbent polymers and validate new material compositions through notified body review. Stakeholders must monitor how CMS reimbursement coding for continence supplies intersects with state-level Medicaid expansion decisions to determine which distribution channels capture incremental patient volume.
Market Dynamics
EU MDR absorbency labeling mandates and REACH chemical restrictions are forcing manufacturers to reformulate super absorbent polymers and validate new material compositions through notified body review, compressing product development timelines and raising compliance costs across European supply chains.
Growth Catalysts
- Post-acute patient volume expansion:North American home healthcare channels are capturing rising discharge volumes as insurers favor direct-to-patient reimbursement models over institutional billing.
- REACH chemical compliance:European environmental regulations are accelerating biodegradable material adoption as procurement rules harden across medical supply contracts.
- Geriatric care facility procurement:Japan and Germany are expanding super absorbent liner purchasing amid accelerating aging demographics and institutional capacity expansion.
Market Restraints
- Fluff pulp input volatility:Raw material cost swings constrain margin predictability for manufacturers dependent on softwood pulp supply chains.
- Notified body capacity bottleneck:EU MDR certification queues extend product launch timelines by 12-18 months for new polymer formulations.
- Reusable garment substitution:Washable incontinence underwear is capturing price-sensitive home care segments in Nordic markets.
Strategic Opportunities
- Custom anatomical fit segments:Post-operative patient populations are driving repeat purchasing for specification-matched liners with premium positioning.
- Biodegradable polymer convergence:Bio-based super absorbent materials combined with compostable non-woven substrates are opening green procurement channels.
- Direct-to-patient channel innovation:Subscription fulfillment models are bypassing traditional pharmacy distribution for chronic condition management.
Industry Challenges
- Polymer chemistry talent scarcity:Formulation expertise for skin-compatible super absorbent materials is concentrated among a narrow specialist workforce.
- Adhesive lamination capex requirements:Hot-melt coating equipment upgrades demand significant capital outlays for compliance with evolving biocompatibility standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bladder Liners Market |
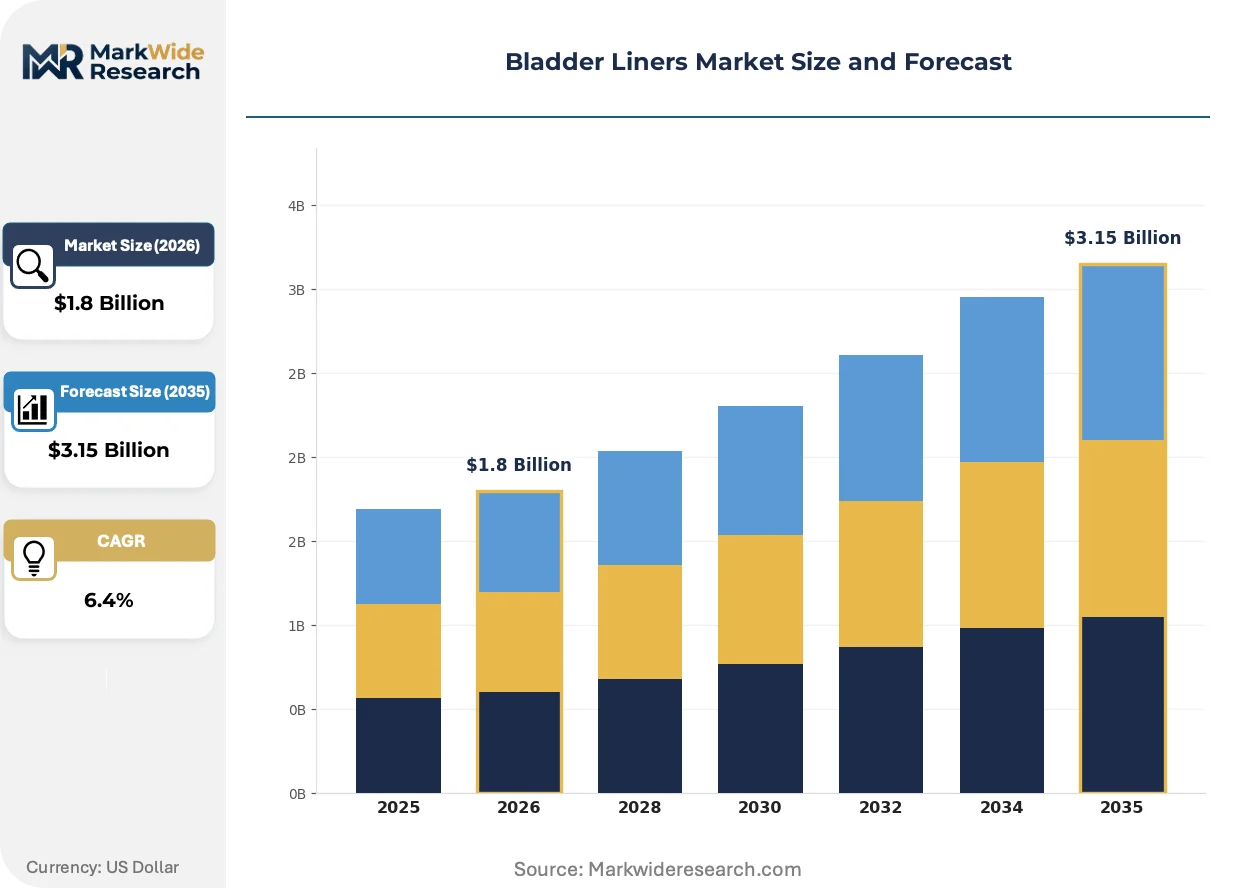
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable Liners, Reusable Liners, Super Absorbent Liners, Custom Liners Material: Polymer, Cotton, Biodegradable Material, Non-woven Fabric Target Audience: Seniors, Pediatric Patients, Post-operative Patients, Athletes Distribution Channel: Pharmacies, Online Retail, Hospitals, Medical Supply Stores |
| Companies Covered | Kimberly-Clark Corporation, Essity Aktiebolag, Cardinal Health, Medline Industries, Ontex, Coloplast, Domtar Corporation, Procter & Gamble Company, Attends Healthcare Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bladder Liners Market Strategic Shifts
Material science advances and regulatory chemistry restrictions are actively reshaping bladder liner composition and manufacturing processes. Three developments are restructuring competitive positioning and procurement patterns.
Plant-derived super absorbent polymers are migrating from petroleum-based sodium polyacrylate cores in premium product tiers. Post-operative patient segments in German and Japanese geriatric facilities are adopting bio-based liners at accelerating pace as institutional sustainability mandates harden. This migration is compressing conventional polymer demand in contract channels where environmental scoring determines award criteria.
EU MDR absorbency labeling requirements are tightening disclosure standards for milliliter retention capacity per gram of core material. Manufacturers must now validate claims through notified body testing, extending development cycles and raising documentation burdens. European medical supply distributors are consolidating supplier bases to reduce compliance complexity, favoring partners with established notified body relationships.
Home care buyers are consolidating purchasing through specialized medical supply partnerships rather than retail pharmacy networks. Hospital system discharge planners are directing patients to contracted durable medical equipment channels that bundle liners with other continence products. This concentration is most visible in US Medicare Advantage markets where plan-specific preferred provider arrangements lock in volume.
Bladder Liners Market Segmentation
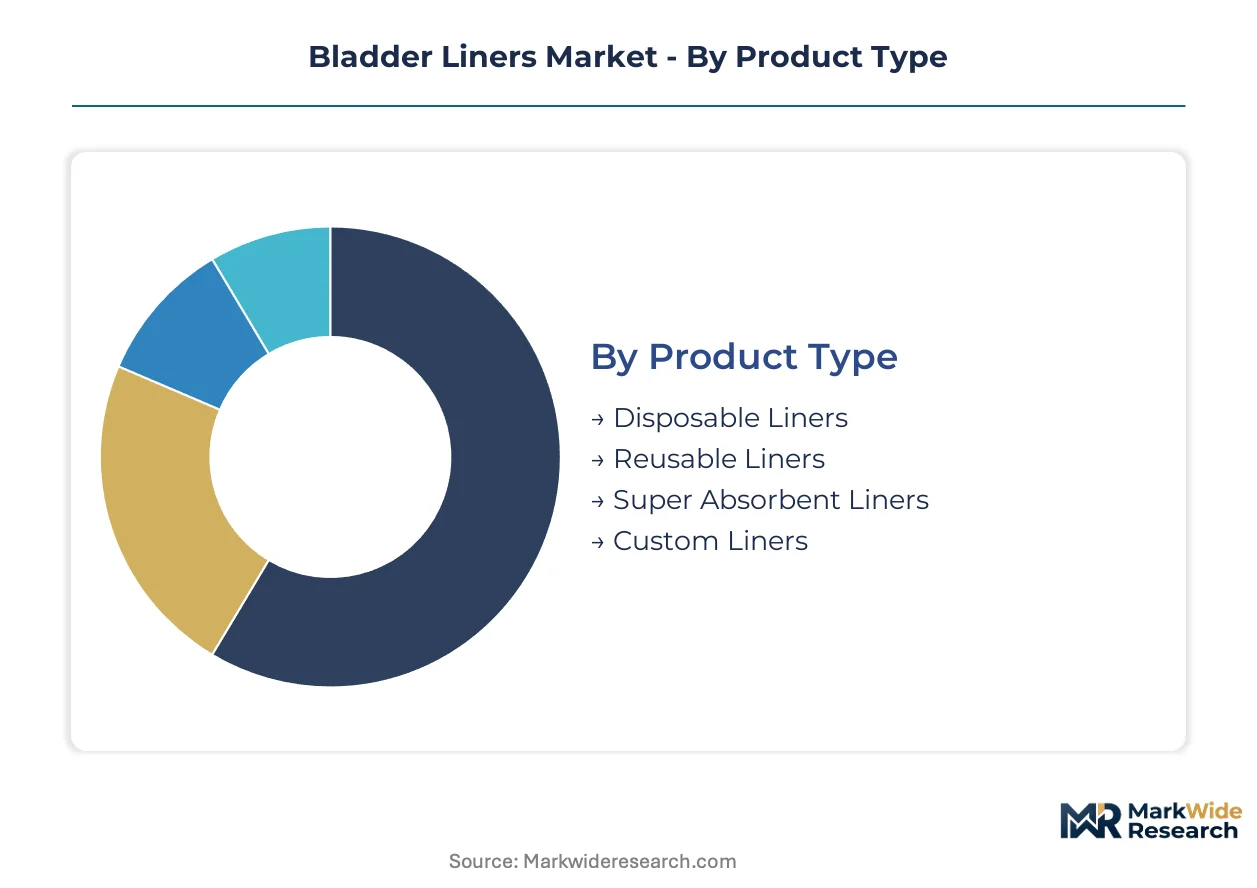
Segmentation in bladder liners reveals how material science, patient anatomy, and procurement channel economics create distinct competitive battlegrounds. Manufacturers must align formulation capabilities with specific end-use requirements rather than pursuing universal product architectures.
Product Type:
Mature disposable formats dominate hospital procurement contracts while emerging biodegradable and custom-fit alternatives reshape premium positioning.
- Disposable Liners:Single-use polymer-core products with hot-melt adhesive lamination and fluff pulp compression achieve standardized absorbency for infection control protocols. Acute care facilities in Japan and Germany specify these for geriatric wards under institutional purchasing agreements. Clinical throughput requirements lock in volume concentration here.
- Super Absorbent Liners:Advanced sodium polyacrylate cores retain higher milliliter volumes per gram of material, serving moderate-to-heavy leakage patients. Post-acute discharge planners in North American home healthcare channels are steering patients toward these higher-performance formats as direct-to-patient reimbursement models expand.
- Reusable Liners:Washable fabric-based designs with moisture-wicking layers target cost-conscious home care segments in Nordic markets where environmental compliance hardens procurement rules.
- Custom Liners:Anatomically specification-matched products command premium positioning through repeat purchasing loyalty among post-operative recovery populations.
Disposable liners handle the majority of throughput; custom liners are expanding most quickly on share.
Material:
Cost tier stratification separates petroleum-derived polymers from premium bio-based alternatives as REACH chemical restrictions tighten across European supply chains.
- Polymer:Petroleum-based sodium polyacrylate super absorbent polymers deliver cost-efficient absorbency at scale. FDA biocompatibility testing requirements under 21 CFR 876.5900 shape development timelines for US market entrants using these conventional cores.
- Biodegradable Material:Plant-derived super absorbent polymers combined with compostable non-woven substrates open green procurement channels. German and Japanese geriatric facilities are accelerating adoption as institutional sustainability mandates harden.
- Cotton:Natural fiber top sheets appeal to skin-sensitive patient populations seeking reduced chemical exposure.
- Non-woven Fabric:Synthetic substrate layers provide structural integrity and fluid distribution across product architectures.
Polymer formulations anchor current volume; biodegradable materials are climbing the fastest.
Target Audience:
Volume concentrates in aging demographics while margin accrues to specialized post-surgical and athletic segments requiring performance-tuned specifications.
- Seniors:Aging demographic expansion in Japan and Germany drives institutional procurement of super absorbent formats for geriatric care facility capacity.
- Post-operative Patients:Specification-matched liners with anatomical customization capture premium positioning through repeat purchasing in recovery protocols.
- Pediatric Patients:Smaller-format designs with gentler adhesive systems address specific sizing and skin sensitivity requirements.
- Athletes:Low-profile, high-mobility designs target leakage management during physical activity with discrete fit characteristics.
Seniors represent the largest addressable population; post-operative patients generate the steepest margin expansion.
Distribution Channel:
Channel flow is tilting from retail pharmacy networks toward specialized medical supply partnerships as insurer reimbursement models restructure patient access pathways.
- Medical Supply Stores:Durable medical equipment channels bundle liners with continence products under contracted preferred provider arrangements in US Medicare Advantage markets.
- Online Retail:Subscription fulfillment models bypass traditional distribution for chronic condition management, capturing direct-to-patient volume.
- Pharmacies:Retail pharmacy networks retain shelf presence through institutional contracts though volume is shifting toward homecare channels.
- Hospitals:Discharge planners direct patients to contracted channels rather than maintaining inpatient product continuity.
Medical supply stores concentrate institutional volume; online retail is gaining share fastest through subscription mechanics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Japanese institutional channels while German procurement faces margin compression from REACH compliance costs. This asymmetry reflects divergent regulatory environments and demographic urgency across developed markets.
United States
Post-acute discharge volumes are expanding through Medicare Advantage preferred provider arrangements that bundle continence products. FDA Class I device regulations under 21 CFR 876.5900 require biocompatibility testing that extends development timelines for new entrants. Hospital systems in the Midwest and Southeast are consolidating purchasing through durable medical equipment channels.
Germany
Geriatric care facilities are accelerating super absorbent liner procurement amid institutional capacity expansion for aging populations. EU MDR absorbency labeling mandates and REACH chemical restrictions are forcing polymer reformulation and notified body validation. Manufacturing clusters in North Rhine-Westphalia are adapting production lines to meet tightened documentation standards.
Japan
Long-term care insurance reimbursement is sustaining premium pricing for institutional-grade liners in rapidly aging metropolitan markets. METI sustainability guidelines are pressuring suppliers to validate bio-based material alternatives. Production facilities in the Kanto region are scaling output to serve expanding geriatric ward contracts.
United Kingdom
NHS supply chain consolidation is concentrating procurement through fewer contracted medical distributors with full continence product portfolios. MHRA alignment with EU MDR post-Brexit maintains parallel compliance burdens for market access. Distribution hubs in the Midlands are capturing consolidated volume from fragmented pharmacy networks.
Canada
Provincial health authority tendering is standardizing absorbency specifications across long-term care procurement. Health Canada medical device regulations require adverse event reporting systems that shape product development priorities. Ontario-based distributors are building logistics capacity to serve remote northern territories.
Bladder Liners Market Competitive Environment
Institutional contract holders and specialized medical supply platforms split the market between scale-driven logistics and relationship-based procurement channels. Consolidation pressure is mounting as hospital system purchasing alliances reduce vendor counts. Three archetypes dominate: multinational hygiene conglomerates with retail pharmacy shelf presence, medical supply specialists with durable equipment distribution networks, and private-label manufacturers serving cost-focused institutional buyers. Competitive moves center on backward integration into polymer formulation and strategic partnerships with geriatric care facility chains.
Within the institutional contract tier, Kimberly-Clark Corporation and Essity Aktiebolag exemplify divergent geographic anchoring strategies. Cardinal Health occupies a position at the logistics-scale end of the competitive spectrum. These three entities represent the primary competitive anchors against which mid-cap specialists and private-label alternatives position their offerings.
| Leading Market Players |
|---|
| Kimberly-Clark Corporation |
| Essity Aktiebolag |
| Cardinal Health |
| Medline Industries |
| Ontex |
| Coloplast |
| Domtar Corporation |
| Procter & Gamble Company |
| Attends Healthcare Group |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Southeast Asian fluff pulp processing facilities is compressing input costs for polymer-core manufacturers while simultaneously eroding bargaining power for regional converters, creating divergent margin trajectories across the value chain.
Pricing Analysis
The customization-premium spread separates specification-matched post-operative liners from standard institutional formats by a substantial margin tier. Three-tier pricing structure across premium, standard, and economy levels reflects absorbency certification grade and anatomical fit precision. Price differentiation hinges on notified body validation status and volume commitment scale. Cost compression in economy tiers is intensifying because REACH-compliant polymer reformulation is raising production expenses, while post-operative patient segments show lowest price sensitivity due to reimbursement coverage.
Supply Chain Analysis
Extended payment terms from Japanese geriatric care facility chains are squeezing working capital for European polymer suppliers serving the Asia-Pacific corridor. Manufacturing concentrates in Germany, Japan, and the United States for finished goods, while fluff pulp feeds from Scandinavian and North American softwood forests. Raw material dependencies rest on sodium polyacrylate resin, hot-melt adhesive formulations, and compostable non-woven substrates. Single-source vulnerability in super absorbent polymer formulation expertise threatens supply continuity. Distribution runs through durable medical equipment channels that bundle continence products under contracted preferred provider arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemistry expertise for skin-compatible super absorbent materials is concentrated among a narrow specialist workforce, creating persistent bottlenecks that favor incumbents with established R&D pipelines and long-tenured technical teams.
For Market Incumbents: Entrench institutional procurement relationships by securing exclusive supply agreements with expanding geriatric care facility chains in Japan and Germany. Deepen backward integration into bio-based polymer formulation to preempt REACH-driven material substitution. Lock in notified body partnerships to compress certification timelines for next-generation absorbent cores. For New Entrants and Emerging Players: Build out direct-to-patient subscription capabilities targeting North American home healthcare channels where insurer reimbursement models are bypassing traditional pharmacy networks. Focus initial penetration on custom anatomical fit segments where specification-matched products command premium positioning and repeat purchasing loyalty. Leverage compounding pharmacy partnerships for clinical credibility. For Investors and Strategic Acquirers: Long-term, this sits as a demographic-utility play because aging population trajectories in developed markets guarantee sustained institutional demand regardless of cyclical fluctuations. Target acquisition candidates with established EU MDR notified body relationships and validated bio-based material formulations. Monitor CMS reimbursement coding revisions for continence supplies as the critical inflection signal for channel profitability shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Notified Body Partnership Development | Accelerates EU MDR certification timelines for reformulated super absorbent polymers by 12-18 months. |
| Bio-Based Polymer Backward Integration | Captures margin from REACH-compliant material substitution while satisfying German institutional sustainability mandates. |
| Direct-to-Patient Subscription Launch | Bypasses pharmacy distribution concentration in US Medicare Advantage markets with bundled fulfillment models. |
| Geriatric Care Facility Chain Exclusivity | Locks in volume concentration amid Japanese long-term care insurance reimbursement expansion. |
| Custom Anatomical Fit Specification Development | Captures premium positioning through repeat purchasing loyalty in post-operative recovery protocols. |
Study Parameters
A spread of perspectives from polymer formulation chemists, geriatric care facility procurement directors, hospital discharge planners, durable medical equipment distributors, and notified body auditors converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, CMS reimbursement coding updates, and hospital procurement contract registries. Bottom-up volume modeling triangulated against top-down macroeconomic demand projections.
Demand-supply balance dynamics across absorbent hygiene manufacturing capacity and geriatric care facility expansion schedules anchored the analytical framework. Segmentation dimensions modeled include product type hierarchy, material composition tier, target patient population, and distribution channel structure. CAGRs were derived through regression analysis of historical procurement volumes against demographic projections. Forecast inputs incorporated REACH chemical restriction implementation timelines and long-term care insurance reimbursement policy trajectories.
Practitioners should monitor EU MDR notified body capacity utilization and CMS reimbursement coding revisions for early signals of timeline compression or channel profitability shifts. Forecasts reflect assumptions regarding polymer formulation technology maturation and institutional sustainability mandate adoption rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Finger Splint Market
Medical Supplies
Plastic Medicine Spoons Market
Medical Supplies
Custom Procedure Packs (CPT) Market
Medical Supplies
North America Ostomy Drainage Bags Market
Medical Supplies
Physiological Saline Market
Medical Supplies
Single Use Safety Lancet Market
Medical Supplies
Menthol Patches Market
Medical Supplies
Middle East and North Africa Disposable Gloves Market
Medical Supplies
Disposable Medical Gowns Market
Medical Supplies
Compression Socks Market
Medical Supplies
Thermal Printable Wristband Market
Medical Supplies
Medical Shoe Covers Market
Medical Supplies
Medical and Industrial Gloves Market
Medical Supplies
Safety Lancet Market
Medical Supplies
Plastic Syringes Market
Medical Supplies
Tissue Glue and Bio-Adhesive Sealants Market