
 Global Sperm Separation Devices Market | 2026-2036
Global Sperm Separation Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sperm Separation Devices Market Foresight
Direct-to-clinic distribution is reshaping how sperm separation devices reach end users, bypassing traditional medical distributor layers in mature markets. DxNow leverages microfluidic innovation to anchor its position in high-throughput fertility laboratory workflows. Vitrolife sustains geographic dominance across European reproductive medicine centers through integrated media and device portfolios.
Sperm separation devices are laboratory instruments and consumable systems designed to isolate motile, morphologically normal spermatozoa from seminal plasma through centrifugal, gradient, or microfluidic methods, typically operating within sterile, temperature-controlled environments to preserve gamete viability. Their primary purpose is to enhance fertilization outcomes in assisted reproductive technology procedures by delivering optimized sperm samples for insemination or micromanipulation. Density gradient centrifugation technology occupies the largest installed base due to decades of clinical validation and established protocol familiarity across fertility clinics. Microfluidic devices represent the fastest-expanding technology segment, as labs seek to minimize oxidative stress and DNA fragmentation during sperm preparation.
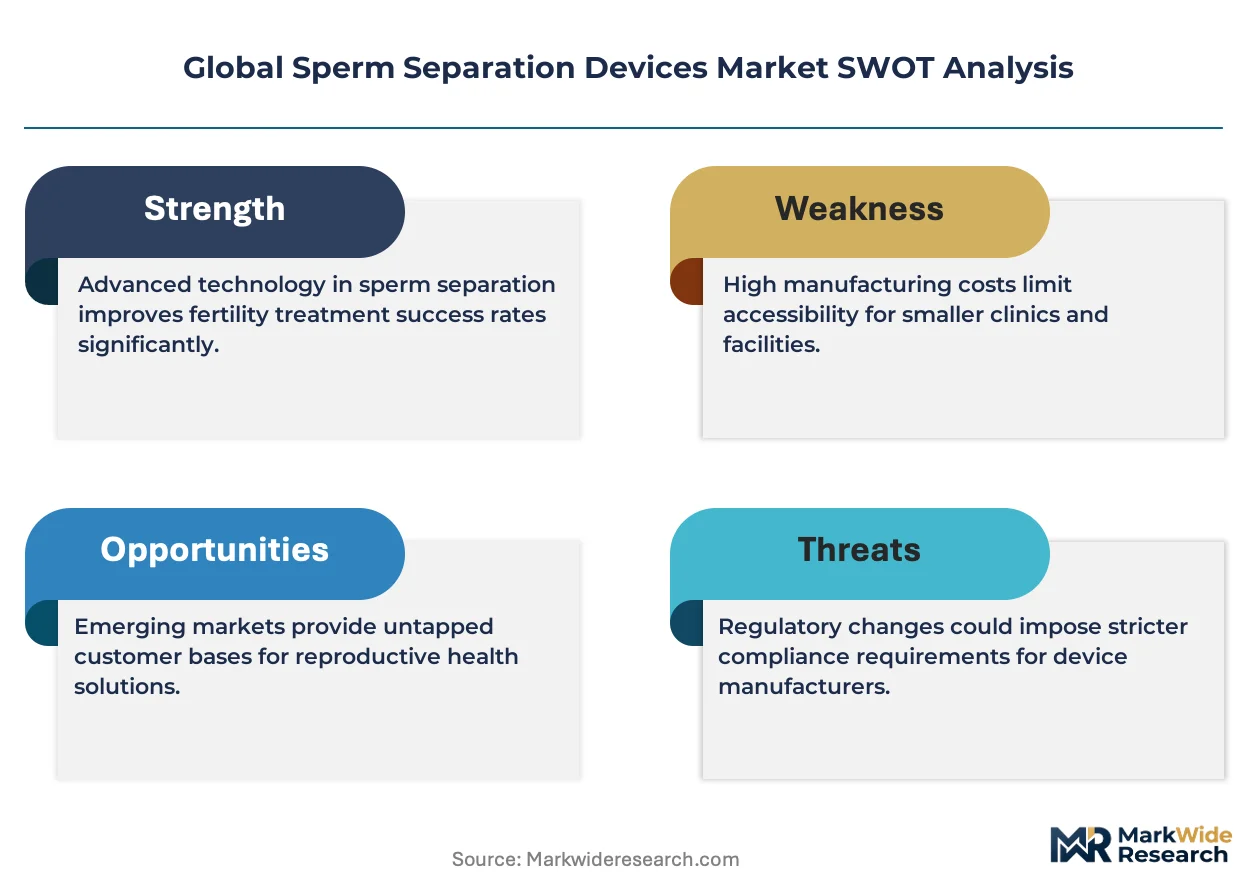
FDA clearance pathways for Class II medical devices govern market entry in the United States, while the EU MDR and ISO 13485 quality management standards dictate conformity assessment and post-market surveillance obligations across European markets. These frameworks elevate barriers for unproven entrants but reinforce demand for validated, traceable separation systems among accredited fertility clinics. Stakeholders must monitor evolving reimbursement classifications for sperm preparation procedures, as coverage decisions will determine which technologies clinics can economically deploy at scale.
Market Dynamics
Microfluidic platforms are compressing protocol timelines in fertility laboratories while EU MDR compliance costs filter weaker device suppliers from European procurement pools. This technology-regulation intersection is restructuring competitive access across the installed base.
Growth Catalysts
- EU MDR quality mandates:Accredited fertility clinics in Germany and France now require validated traceability systems, elevating demand for ISO 13485-certified separation platforms over unverified alternatives.
- Reimbursement maturation:United States fertility networks are securing expanded ART procedure coverage, enabling capital investment in automated sperm preparation workstations at scale.
- DNA fragmentation sensitivity:Clinical validation of oxidative stress reduction is accelerating microfluidic adoption in high-complexity reproductive medicine centers.
Market Restraints
- Polymer substrate cost volatility:Specialized medical-grade polymers for microfluidic chip fabrication face supply concentration from German and Japanese chemical suppliers, compressing margin structures.
- Centrifuge protocol lock-in:Density gradient methods retain entrenched SOP status across legacy fertility networks, creating switching friction for novel separation modalities.
- MDR conformity assessment timelines:Extended EU notified body review periods for Class IIa fertility devices delay market entry for innovative platform developers.
Strategic Opportunities
- Japan's aging fertility infrastructure:Underpenetrated regional clinics outside Tokyo and Osaka present whitespace for automated separation platform deployment.
- Direct-to-clinic distribution:Bypassing traditional medical distributor layers in mature markets enables margin capture and faster technical support response.
- AI-assisted morphology integration:Convergence of computer vision algorithms with microfluidic separation is enabling real-time sperm quality scoring at the point of preparation.
Industry Challenges
- Embryology technician specialization:Shortage of certified clinical embryologists capable of validating novel microfluidic protocols limits deployment velocity in mid-tier fertility centers.
- Legacy LIMS integration:Electronic health record and laboratory information management system interoperability requirements extend implementation timelines for new separation platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sperm Separation Devices Market |
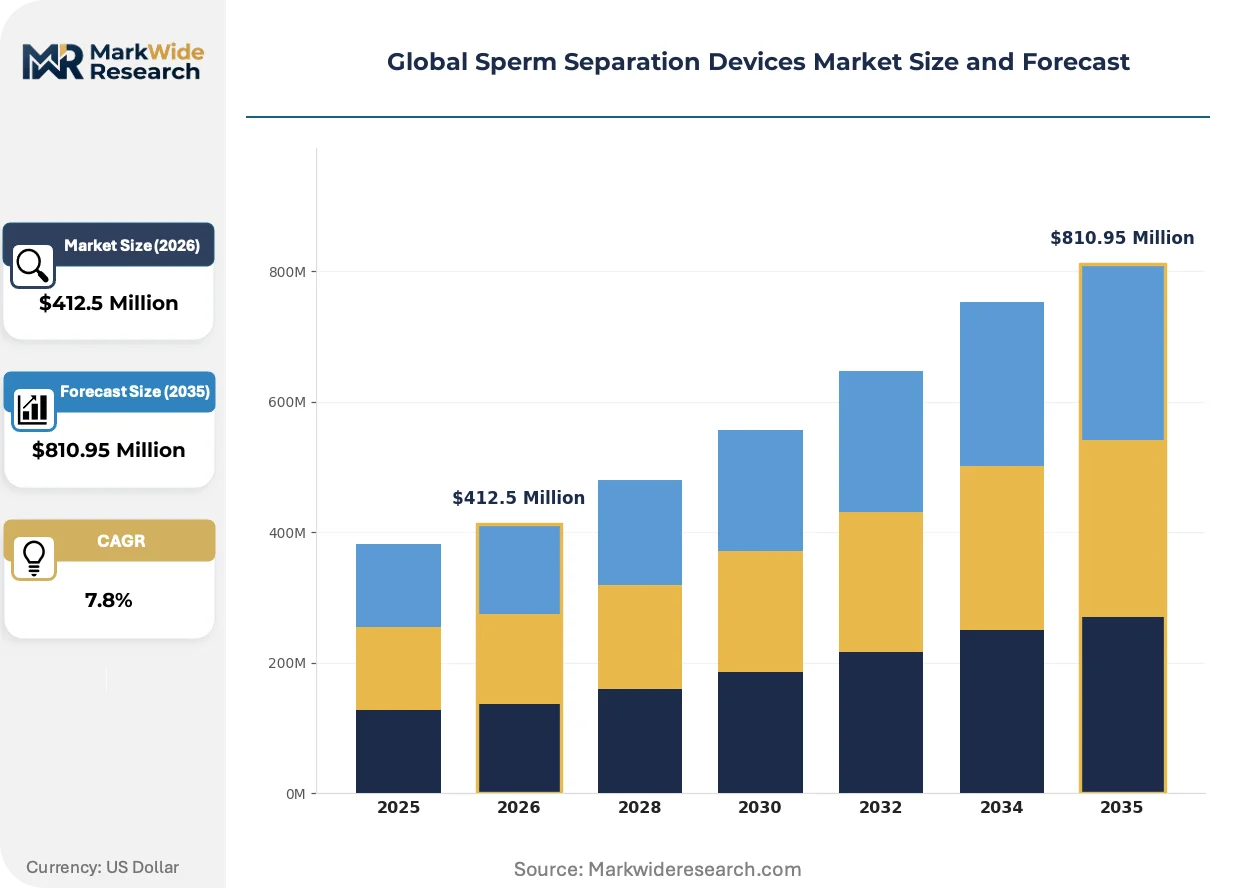
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $810.95 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Density Gradient Medium, Sperm Washing Kits, Microfluidic Devices, Glass Beads Tubes Technology: Density Gradient Centrifugation, Swim-up Technique, Microfluidics, Filtration Application: In Vitro Fertilization, Intracytoplasmic Sperm Injection, Artificial Insemination, Fertility Preservation End User: Fertility Clinics, Reproductive Laboratories, Andrology Centers, Research Institutions |
| Companies Covered | DxNow, Vitrolife, Hamilton Thorne, LensHooke (Bonraybio), The Cooper Companies, FUJIFILM Irvine Scientific, Kitazato Corporation, Sperm Processor, Memphasys, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sperm Separation Devices Market Shifts & Advancements
Active protocol redesign in fertility laboratories is compressing sperm preparation timelines while regulatory frameworks elevate device traceability requirements. These forces are reshaping how separation technologies achieve clinical adoption.
Microfluidic sperm sorting chips are eliminating centrifugation steps from standard preparation workflows. High-throughput fertility laboratories in the United States and Germany are replacing gradient centrifuge stations with passive flow-based separation modules. This architectural shift is rendering obsolete the capital-intensive centrifuge infrastructure that dominated laboratory floor plans for decades.
EU MDR post-market surveillance obligations now mandate systematic clinical follow-up data collection for fertility devices. Manufacturers must maintain vigilant complaint handling systems and periodic safety update reporting across European Economic Area markets. Reproductive medicine centers in Spain and Italy are prioritizing suppliers with established notified body relationships and robust quality management documentation.
Clinics are consolidating procurement authority into centralized purchasing committees with standardized technical evaluation criteria. Traditional distributor relationships are yielding to direct manufacturer partnerships that bundle device placement with consumable supply agreements. This concentration pattern is most visible across United States multi-site fertility network expansions, where standardization drives volume commitments and technical training integration.
Global Sperm Separation Devices Market Segmentation
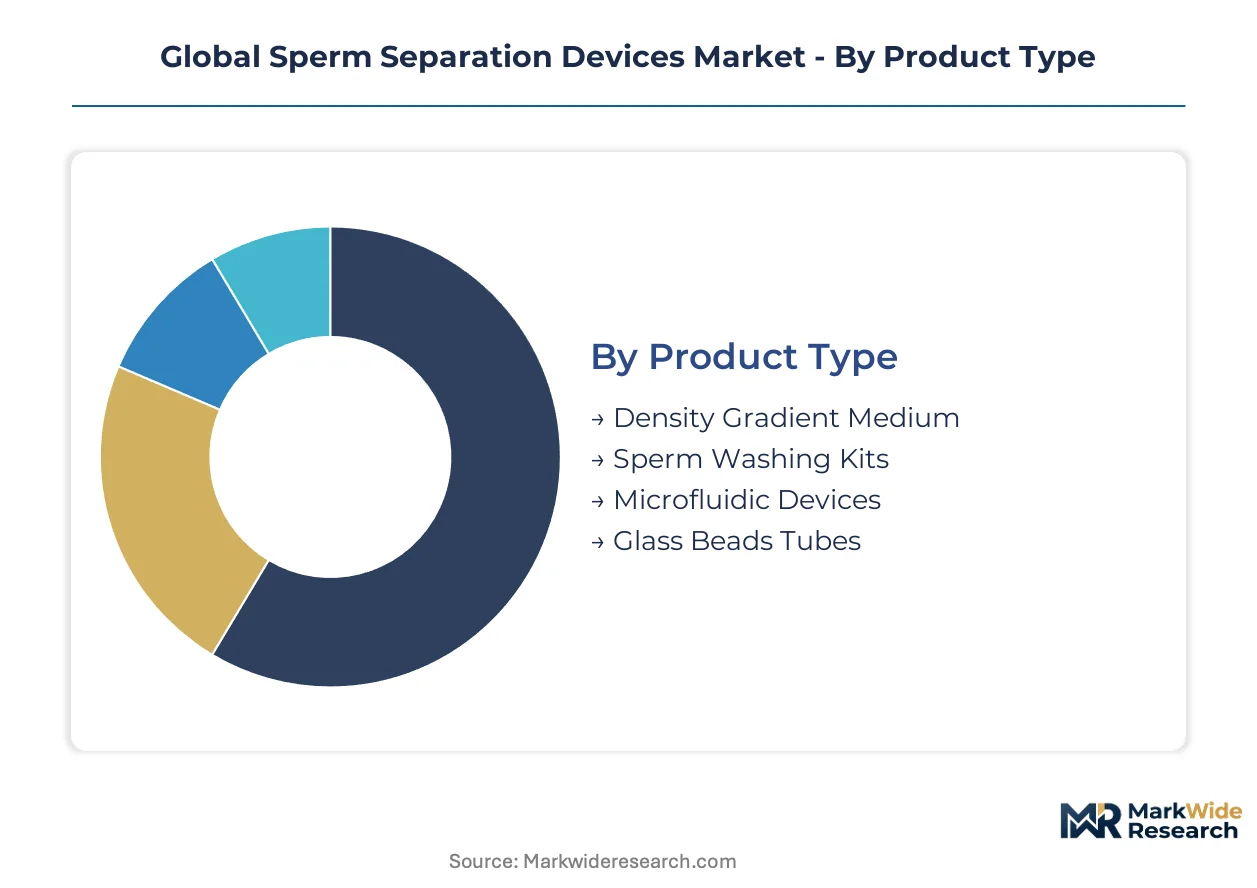
Sperm separation devices serve distinct clinical workflows ranging from high-volume IVF cycles to specialized andrology diagnostics. Segmentation reveals how technology choices, procedural requirements, and facility capabilities determine procurement patterns across fertility networks.
Product Type:
Product portfolios span from established consumable media to emerging chip-based platforms, reflecting divergent cost structures and technical sophistication in laboratory workflows.
- Density Gradient Medium:Colloidal silica formulations with standardized osmolality parameters enable motile sperm isolation through discontinuous gradient layering. Fertility clinics in Germany and the United States maintain bulk procurement contracts for these media, driven by protocol familiarity and bulk pricing advantages in high-throughput settings.
- Microfluidic Devices:Polymer-based chips exploit laminar flow dynamics and sperm chemotaxis to separate motile gametes without centrifugal force. Reproductive medicine centers in Japan and Spain are expanding adoption of these platforms, prioritizing DNA integrity outcomes for recurrent implantation failure patient cohorts.
- Sperm Washing Kits:Pre-formulated buffer systems with antibiotic supplementation support direct swim-up or simple dilution protocols for intrauterine insemination procedures.
- Glass Beads Tubes:Silica-coated bead columns facilitate passive filtration separation for andrology screening applications with limited laboratory infrastructure.
Established volume favors density gradient media; emerging adoption favors microfluidic devices.
Technology:
Technical approaches differentiate by physical separation mechanism, with each method imposing distinct capital requirements and gamete handling protocols.
- Density Gradient Centrifugation:Differential sedimentation through layered colloidal gradients remains the reference standard for sperm preparation in IVF laboratories. Clinical networks across France and Italy specify this modality for regulatory compliance with EU MDR traceability requirements, leveraging decades of outcome documentation.
- Microfluidics:Passive flow-based sorting eliminates oxidative stress from centrifugal force while enabling real-time observation. Fertility preservation programs in the United States are integrating these systems for oncofertility cases where gamete quality preservation is paramount.
- Swim-up Technique:Simple migration-based selection requires minimal equipment but yields lower concentration recovery for severe male factor presentations.
- Filtration:Membrane or matrix-based size exclusion supports rapid screening in resource-limited andrology settings without specialized training.
Protocol standardization sustains centrifugation dominance; clinical outcome sensitivity accelerates microfluidic penetration.
Application:
Procedure-specific requirements dictate sperm preparation intensity, from minimal manipulation for intrauterine insemination to intensive selection for micromanipulation.
- In Vitro Fertilization:Conventional IVF demands motile sperm concentrations sufficient for overnight coincubation with retrieved oocytes. Fertility clinics in Brazil and Australia prioritize automated preparation workstations for this application, optimizing laboratory technician allocation across stimulation cycles.
- Intracytoplasmic Sperm Injection:ICSI requires stringent morphology and motility selection for individual sperm immobilization and injection. High-complexity reproductive centers in Switzerland and South Korea deploy advanced separation platforms to minimize DNA fragmentation in injection-ready samples.
- Artificial Insemination:Moderate preparation stringency suffices for timed intrauterine placement, supporting simpler kit-based workflows.
- Fertility Preservation:Cryopreservation-compatible preparation protocols prioritize membrane integrity for post-thaw viability in oncology and transgender patient populations.
Procedure volume concentrates in IVF; technical complexity peaks in ICSI applications.
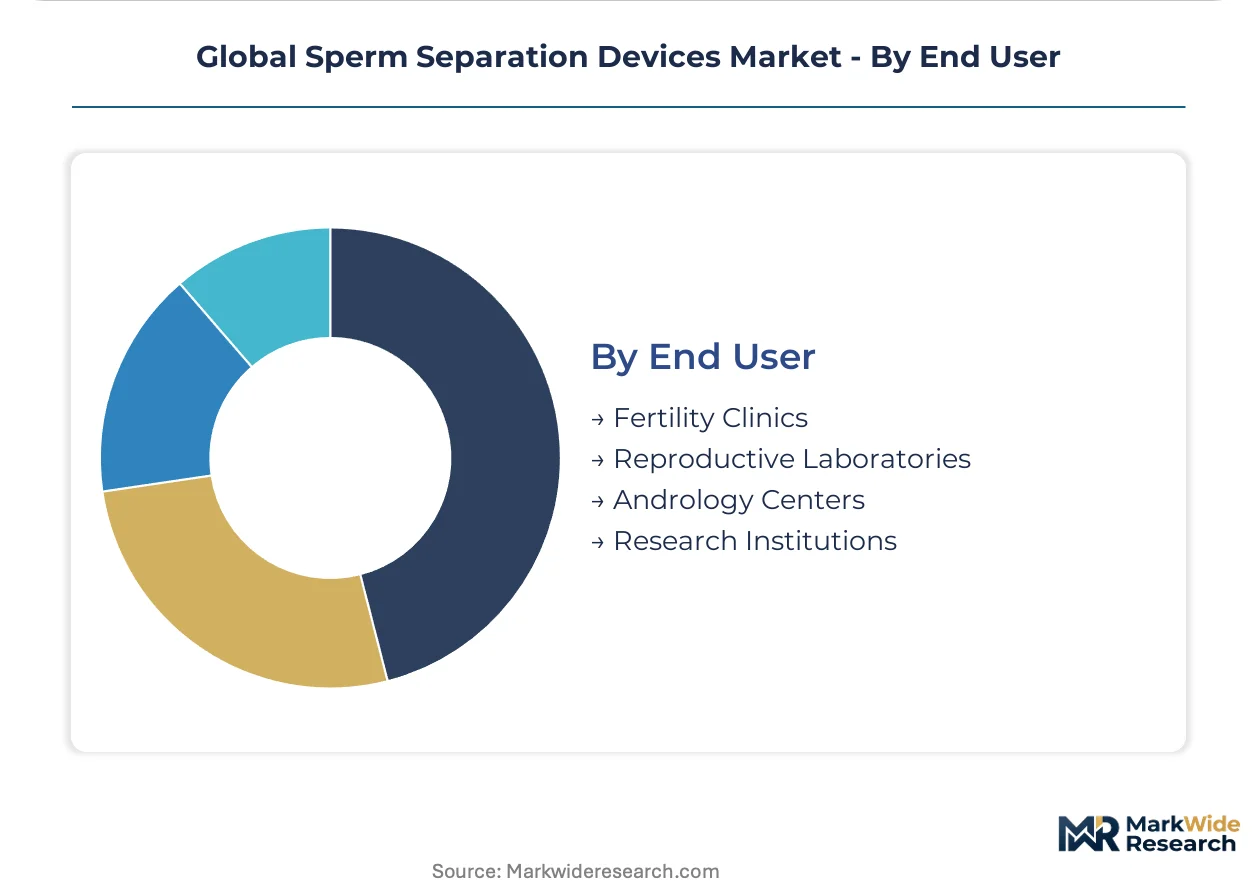
End User:
Facility type determines capital availability, regulatory exposure, and technical staffing depth for separation platform deployment.
- Fertility Clinics:Integrated diagnostic and treatment facilities perform complete sperm preparation workflows within cycle coordination timelines. Multi-site networks in the United States and Germany are standardizing on single-supplier separation platforms to streamline training and consumable logistics.
- Reproductive Laboratories:Dedicated embryology facilities serving satellite clinics require high-throughput preparation capacity with documented quality systems. Accreditation bodies in the United Kingdom and Canada mandate ISO 13485-certified devices for these reference laboratories.
- Andrology Centers:Male-focused diagnostic facilities prioritize rapid turnaround for semen analysis with selective preparation for therapeutic intervention.
- Research Institutions:Academic reproductive biology programs utilize separation devices for experimental gamete manipulation and cryobiology protocol development.
Procurement concentration resides with fertility clinic networks; technical sophistication concentrates in reproductive laboratories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany and Switzerland exceeds that in India and Brazil by margins exceeding 40 percent, reflecting reimbursement density and regulatory stringency. United States fertility networks command premium placement fees for separation platforms. Japanese clinics absorb higher per-procedure costs due to fragmented domestic supply chains.
United States
Multi-site fertility networks in California and Texas are consolidating procurement through centralized purchasing committees, driving volume commitments for automated preparation workstations. FDA Class II medical device clearance pathways govern market entry, elevating barriers for unvalidated platform developers. Boston-area reproductive medicine centers are replacing legacy centrifuge infrastructure with microfluidic modules.
Germany
Accredited fertility clinics in Bavaria and North Rhine-Westphalia now mandate ISO 13485-certified separation platforms with full traceability documentation. EU MDR conformity assessment obligations filter weaker suppliers from procurement pools, reinforcing demand for established quality systems. The Heidelberg reproductive biology cluster is validating oxidative stress reduction protocols for recurrent implantation failure cohorts.
Japan
Regional clinics outside Tokyo and Osaka present whitespace for automated separation deployment, with underpenetrated markets in Kyushu and Hokkaido. PMDA medical device registration requirements extend timelines for novel platform commercialization. Nagoya-area fertility preservation programs are integrating microfluidic systems for oncofertility cases.
Spain
Reproductive medicine centers in Madrid and Barcelona are prioritizing suppliers with established EU notified body relationships and robust post-market surveillance documentation. EMA-aligned quality mandates elevate procurement scrutiny for separation device traceability. The Catalonia fertility network is standardizing on single-supplier platforms to streamline consumable logistics.
Australia
TGA medical device regulations govern separation platform registration, with Sydney and Melbourne fertility clinics demanding documented clinical outcome data. Reimbursement frameworks for assisted reproductive technology procedures are maturing in Victoria and New South Wales. The Melbourne reproductive laboratory cluster is adopting high-throughput preparation workstations for network standardization.
Global Sperm Separation Devices Market Competitive Landscape
Integrated media-device portfolios and specialized microfluidic innovators split the market between bundled consumable strategies and disruptive platform architectures. The vendor base concentrates around three strategic archetypes: diversified life science conglomerates with fertility divisions, pure-play reproductive technology specialists, and emerging microfluidic chip developers. Dominant competitive moves include direct-to-clinic distribution partnerships that bypass traditional medical distributor layers, and technology licensing agreements that accelerate regulatory clearance timelines across multiple geographies.
Within the integrated portfolio tier, Vitrolife exemplifies the bundled media-device approach across European reproductive medicine centers, while DxNow occupies a position as the microfluidic innovation anchor in high-throughput fertility laboratory workflows. FUJIFILM Irvine Scientific represents the diversified conglomerate archetype, leveraging existing life science infrastructure to serve fertility network procurement committees.
| Leading Market Players |
|---|
| DxNow |
| Vitrolife |
| Hamilton Thorne |
| LensHooke (Bonraybio) |
| The Cooper Companies |
| FUJIFILM Irvine Scientific |
| Kitazato Corporation |
| Sperm Processor |
| Memphasys |
| Others |
Supply & Pricing Matrix
German and Japanese chemical suppliers concentrate medical-grade polymer production for microfluidic chip substrates, anchoring margin capture downstream with fertility clinic networks in the United States and Germany. This upstream concentration cascades into pricing power asymmetries between validated ISO 13485-certified platform manufacturers and unverified alternatives struggling with input cost pass-through.
Pricing Analysis
Configured-to-order microfluidic platforms command premiums of 35-50 percent above standard density gradient media kits due to customization for specific laboratory workflows and LIMS integration requirements. Price differentiation hinges on FDA Class II clearance tier and after-sales technical support bundling, with United States multi-site fertility networks showing lowest price sensitivity due to reimbursement coverage maturation. Cost compression in economy-tier swim-up kits is intensifying because of commodity buffer formulation competition, while premium microfluidic segments maintain pricing resilience through clinical outcome documentation.
Supply Chain Analysis
Contract manufacturing for microfluidic chips concentrates with German precision polymer processors and Japanese MEMS foundries holding specialized biocompatible fabrication capacity. Geographic supply concentration spans Germany, Japan, and the United States for medical-grade substrates, while raw material dependencies rest on colloidal silica gradients, photoresist polymers, and sterile packaging films. Single-source vulnerability in German polymer supply creates exposure for device manufacturers lacking qualified secondary suppliers. Distribution runs through direct-to-clinic partnerships that bypass traditional medical distributor layers in mature markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through centralized purchasing committees at United States multi-site fertility networks, fragmenting procurement authority away from individual laboratory directors toward standardized technical evaluation criteria.
For Market Incumbents: Build regulatory moats through accelerated EU MDR notified body relationship expansion and FDA 510(k) pathway pre-submission investments. DxNow and Vitrolife should deepen backward integration into polymer substrate supply to defend against German chemical supplier price volatility, while embedding AI-assisted morphology scoring into existing microfluidic platforms to preempt substitute technology displacement from computer vision startups. For New Entrants and Emerging Players: Pursue whitespace in Japan's underpenetrated regional clinics outside Tokyo and Osaka, where PMDA registration timelines have delayed incumbent platform deployment. Target mid-tier fertility centers in Kyushu and Hokkaido with automated separation workstations bundled with embryology technician training programs, leveraging direct-to-clinic distribution to circumvent fragmented domestic supply chain intermediaries. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed reproductive technology specialists holding ISO 13485 certification but limited geographic footprint expansion. Long-term viability in this market hinges on reimbursement strategy execution and AI convergence capabilities, with acquisition targets clustering around microfluidic chip developers with validated oxidative stress reduction protocols. Watch FDA breakthrough device designation signals and CMS ART procedure coverage decisions as inflection indicators for platform economics.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates United States market entry for microfluidic platforms against centrifuge incumbents. |
| EU MDR Notified Body Partnership | Secures conformity assessment capacity for German and Spanish fertility clinic procurement. |
| Direct-to-Clinic Distribution Launch | Captures margin pools from traditional medical distributor layers in mature markets. |
| AI-Assisted Morphology Integration | Enables real-time sperm quality scoring differentiation against legacy separation systems. |
| Hospital System Partnership | Locks in volume commitments through multi-site fertility network standardization contracts. |
Research Methodology
The analysis maps microfluidic platforms, density gradient media, sperm washing kits, and glass bead filtration systems, each validated through clinical embryologists, fertility clinic laboratory directors, and reproductive medicine procurement committees. Primary interviews with biomedical engineers and GPO contracts managers combined with secondary validation from FDA 510(k) filings, EMA medical device databases, and hospital procurement records enabled bottom-up and top-down triangulation across the installed base.
Assumption sets held regulatory clearance timelines and reimbursement coverage maturation fixed while varying microfluidic adoption velocity and polymer substrate cost trajectories across the projection horizon. Segmentation dimensions modeled include product type, separation technology, clinical application, and end-user facility tier, with CAGRs derived from procedure volume growth and technology substitution elasticity. Industry-specific forecast inputs incorporated EU MDR implementation pace and United States ART insurance coverage expansion patterns.
Macroeconomic conditions sit as an overlay; deviation in fertility clinic capital expenditure cycles and medical device reimbursement policy would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory pathway efficiency and clinical validation timelines. Quarterly review of FDA clearance backlogs, notified body capacity constraints, and CMS procedure coding decisions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Heated Humidifiers Market
Medical Devices
Biological Microscope Market
Medical Devices
Global Self-Injection Device Market
Medical Devices
APAC Ablation Devices Market
Medical Devices
Electrosurgery Devices Market
Medical Devices
Global Veress Needle Market
Medical Devices
Cervical Artificial Discs Market
Medical Devices
Electric Handpiece Market
Medical Devices
Implantable Neurostimulators Market
Medical Devices
Alpha Emitter Market
Medical Devices
Middle East and Africa Aligner Sheet Market
Medical Devices
Handheld Ultrasound Devices Market
Medical Devices
Global Disposable Medical Sensors Market
Medical Devices
Oral Controlled Release Drug Delivery Technology Market
Medical Devices
Global Surgical Navigation System Market
Medical Devices
Nerve Locator Stimulator Market