
 Dry Eye Treatment Devices Market | 2026-2036
Dry Eye Treatment Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Dry Eye Treatment Devices Market Intelligence
Direct-to-clinic sales channels are rewriting how device manufacturers reach end-users in the dry eye treatment landscape. Sight Sciences leverages its specialized commercial team to target ophthalmology practices with thermal pulsation platforms. Lumenis anchors its position through intense pulsed light systems deployed across premium clinic networks. Alcon competes by extending its established eye care distribution infrastructure into device-centric therapeutic protocols.
Dry eye treatment devices encompass electromechanical and optical systems engineered to restore tear film stability, with thermal pulsation units typically operating at controlled temperatures between 40°C and 45°C to liquefy meibum and clear obstructed glands. These instruments serve the clinical purpose of addressing evaporative dry eye and meibomian gland dysfunction without pharmaceutical dependency. Thermal pulsation devices and intense pulsed light systems capture disproportionate margin pools as clinicians shift toward in-office procedural revenue models. Homecare settings represent the fastest-growing end-user segment as manufacturers miniaturize previously clinic-bound technologies for patient-managed therapy.
FDA 510(k) pathways govern market access for thermal and light-based devices in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements on manufacturers seeking CE marking for ophthalmic equipment. Japan's PMDA maintains distinct technical standards for electrical medical devices that influence product adaptation cycles for Asian market entry. Stakeholders must monitor evolving reimbursement codes for in-office dry eye procedures across Medicare and private payer systems.
Market Dynamics
Clinic-bound thermal pulsation systems are migrating into homecare environments, compressing the traditional equipment procurement cycle and forcing manufacturers to recalibrate service revenue models around patient-managed therapy protocols.
Growth Catalysts
- FDA 510(k) clearance:Streamlined premarket pathways for meibomian gland dysfunction devices accelerate commercial timelines for thermal and light-based platforms entering the United States.
- Homecare settings:Patient-managed therapy segments expand as miniaturized electromechanical systems replace clinic-dependent treatment protocols.
- EU MDR compliance:Stricter clinical evidence requirements for ophthalmic equipment CE marking raise competitive barriers, favoring well-capitalized manufacturers with robust trial infrastructure.
Market Restraints
- Optical component supply:Precision light-delivery systems depend on concentrated Asian manufacturing clusters, exposing procurement to logistics volatility.
- Reimbursement code fragmentation:Medicare and private payer systems maintain inconsistent coverage for in-office dry eye procedures, creating revenue uncertainty for clinic adopters.
- Pharmaceutical substitution:Topical immunomodulators and artificial tear formulations retain first-line therapy status in mild-to-moderate cases, limiting device penetration.
Strategic Opportunities
- Japan PMDA alignment:Electrical medical device standards in Asian markets create adaptation requirements that, once satisfied, open premium-priced distribution channels.
- Intense pulsed light convergence:Combination platforms integrating thermal pulsation with optical energy delivery capture expanded procedural revenue per patient encounter.
- Direct-to-clinic channels:Specialized commercial teams bypass traditional distributor markups, improving margin capture in ophthalmology practice networks.
Industry Challenges
- Biocompatibility certification:Ocular surface contact materials require extended ISO 10993 testing timelines, delaying product launches.
- Field service engineering:Thermal calibration and optical alignment demand scarce technician expertise, constraining geographic expansion.
- Legacy EHR integration:Device data outputs require custom API development to interface with dominant electronic health record platforms in ophthalmology.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dry Eye Treatment Devices Market |
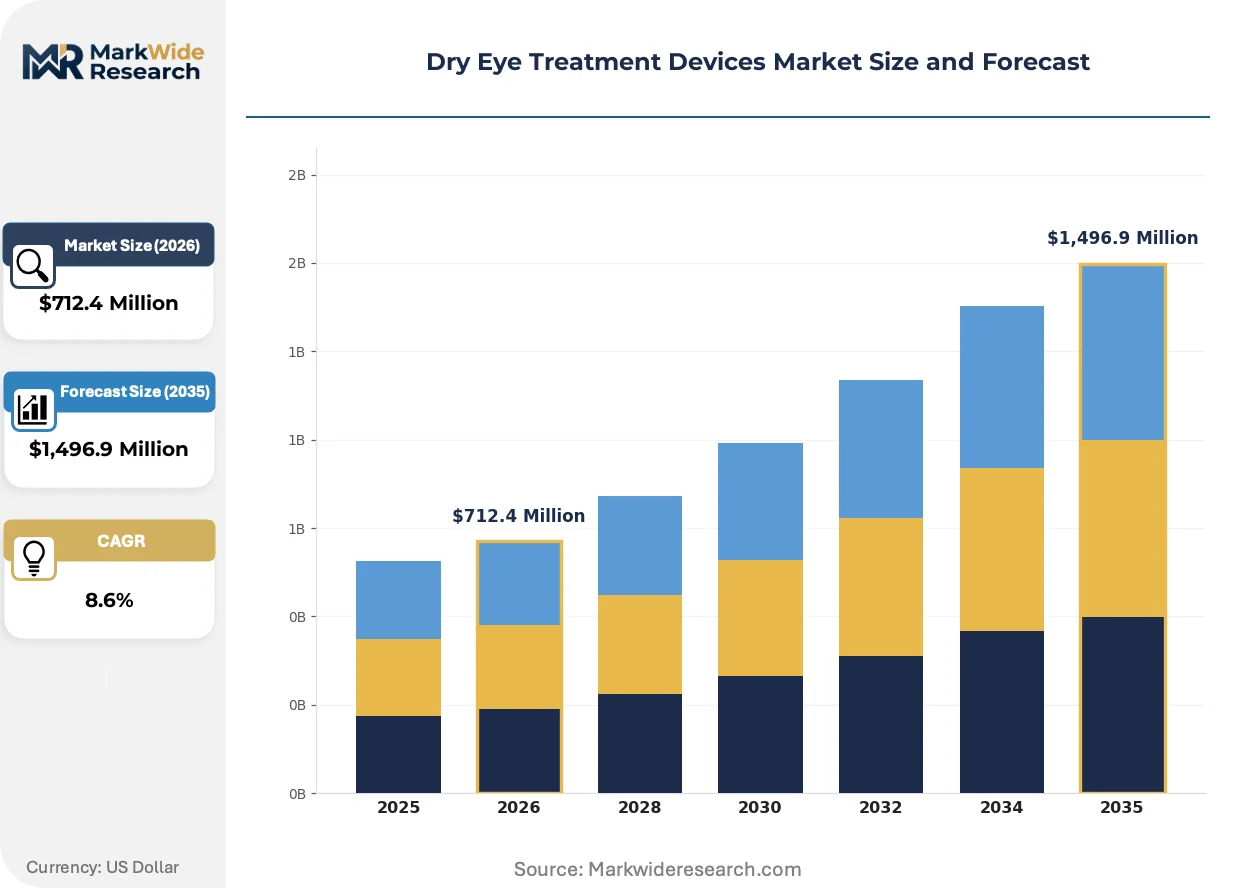
| Market Size in 2026 | $712.4 Million |
| Market Size in 2035 | $1,496.9 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Thermal Pulsation Devices, Punctal Plugs, LipiFlow, Intense Pulsed Light Devices Treatment Method: Medication, Light Therapy, Surgery, Home Remedies End User: Hospitals, Ophthalmology Clinics, Ambulatory Surgical Centers, Homecare Settings Distribution Channel: Online Retail, Direct Sales, Distributors, Specialty Clinics |
| Companies Covered | Sight Sciences, Lumenis, MiBo Medical Group, ESW Vision, Alcon, Johnson & Johnson Vision, BlephEx LLC, BioTissue, NuSight Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dry Eye Treatment Devices Market Strategic Shifts & Innovations
Device architecture is fragmenting into modular, connectivity-enabled platforms that separate the therapeutic mechanism from data capture and patient monitoring functions, enabling subscription-based revenue models.
Thermal pulsation technology is hybridizing with real-time temperature feedback systems and connected health infrastructure. Ophthalmology clinics in the United States and Germany are deploying these platforms at accelerated replacement cycles. This convergence is compressing capital equipment refresh periods while opening recurring software and monitoring revenue streams previously unavailable to hardware manufacturers.
Japan's PMDA electrical medical device standards are tightening documentation requirements for thermal-based ophthalmic equipment. Manufacturers must submit expanded electromagnetic compatibility and thermal safety data for market authorization. Asian-market product adaptation cycles now extend competitive timelines for firms lacking established regulatory affairs capabilities in Tokyo.
Patient acquisition patterns are rotating toward specialist referral networks rather than primary care gatekeepers. Ophthalmology clinics in premium metropolitan markets are consolidating device procurement decisions into centralized purchasing committees. This concentration is most visible in Germany's university hospital networks and Japan's JIS-certified specialty centers.
Dry Eye Treatment Devices Market Segmentation
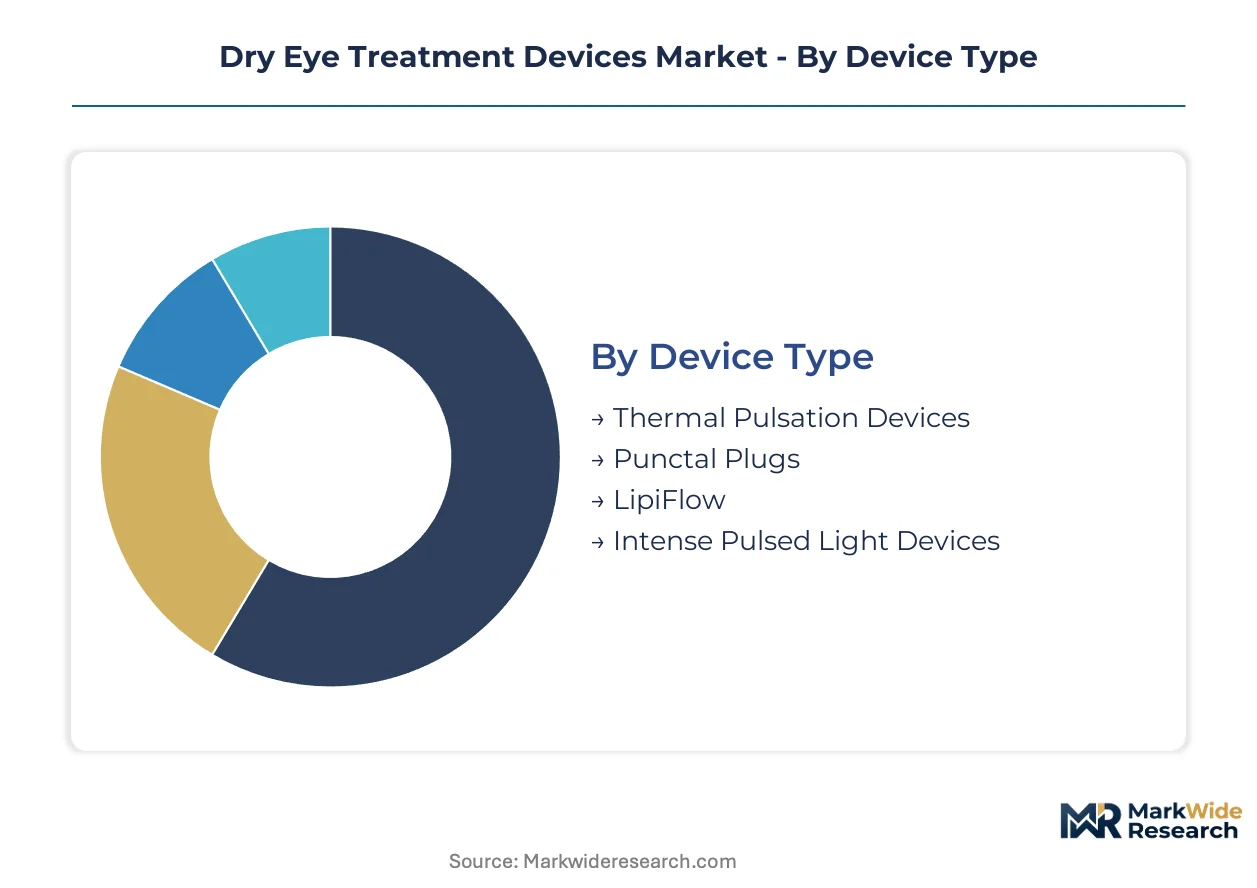
Segmentation in dry eye treatment devices reveals divergent capital cycles across hardware categories. Thermal platforms demand multi-year depreciation schedules while disposable components turn inventory faster. Understanding these velocity mismatches shapes portfolio construction for manufacturers balancing recurring revenue against upfront equipment sales.
Device Type:
Replacement cycles stretch from single-use disposables to decade-long capital equipment, creating tiered aftermarket revenue profiles.
- Thermal Pulsation Devices:Electromechanical systems applying controlled heat between 40°C and 45°C to liquefy meibum and restore gland function. Demand concentrates in ophthalmology clinics across the United States and Germany as clinicians build procedural revenue streams independent of pharmaceutical dispensing. FDA 510(k) pathways govern clearance timelines for these platforms.
- Intense Pulsed Light Devices:Optical energy delivery systems targeting inflammatory mediators and abnormal vasculature on the periocular surface. Adoption clusters in premium metropolitan clinic networks where combination therapy protocols command elevated reimbursement positioning.
- Punctal Plugs:Silicone or collagen inserts blocking tear drainage channels to prolong ocular surface moisture retention.
- LipiFlow:Integrated thermal-mechanical platforms combining heat application with automated gland expression in single-session protocols.
Thermal Pulsation Devices dominate installed base. Intense Pulsed Light Devices are where expansion concentrates.
Treatment Method:
Reimbursement codes and clinical guidelines stratify treatment approaches into distinct economic tiers with varying margin profiles.
- Light Therapy:In-office optical energy protocols generating procedural fee structures separate from product sales. Concentration in ophthalmology clinics seeking to offset declining pharmaceutical margin compression through device-centric revenue models.
- Medication:Topical immunomodulators and anti-inflammatory formulations retaining first-line therapy status in mild-to-moderate presentations per standard-of-care protocols.
- Surgery:Punctal occlusion and tarsorrhaphy procedures for refractory cases unresponsive to conservative management.
- Home Remedies:Patient-managed warm compress regimens and artificial tear supplementation preceding clinical intervention.
Medication commands patient volume. Light Therapy is climbing the fastest as clinics restructure toward procedural economics.
End User:
Procurement authority and capital allocation discipline vary sharply across institutional settings, shaping sales cycle duration and contract complexity.
- Ophthalmology Clinics:Specialized practices with concentrated purchasing committees driving centralized equipment decisions. Germany's university hospital networks and Japan's JIS-certified specialty centers exhibit pronounced consolidation in procurement authority.
- Homecare Settings:Patient-managed therapy environments expanding as manufacturers miniaturize previously clinic-bound thermal technologies. This segment is gaining share fastest as direct-to-consumer channels bypass traditional clinical gatekeeping.
- Hospitals:Integrated delivery networks with formal capital budgeting processes and extended vendor qualification requirements.
- Ambulatory Surgical Centers:Freestanding procedural facilities prioritizing throughput-optimized equipment footprints.
Ophthalmology Clinics anchor equipment revenue. Homecare Settings represent the steepest expansion trajectory as miniaturization accelerates.
Distribution Channel:
Margin capture and customer relationship depth shift dramatically across channel architectures, with direct engagement displacing legacy intermediaries.
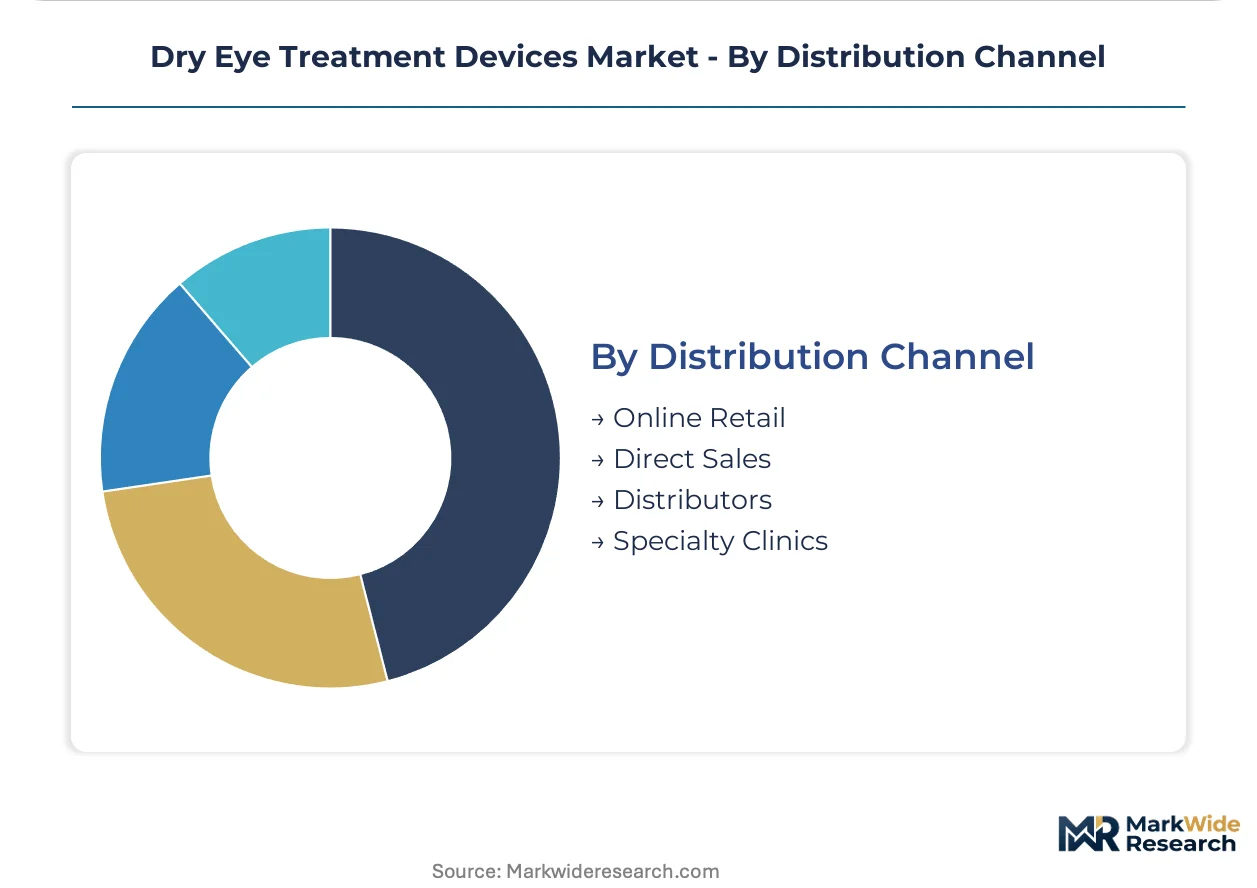
- Direct Sales:Manufacturer-employed specialized commercial teams targeting ophthalmology practices with thermal pulsation platforms. This channel improves margin retention by eliminating distributor markups while enabling clinical training and service integration.
- Specialty Clinics:Captive distribution through vertically integrated practice networks controlling both device procurement and patient access. Concentrated in premium US metropolitan markets and Germany's consolidated hospital systems.
- Distributors:Third-party logistics and sales intermediaries serving geographic markets lacking direct manufacturer presence.
- Online Retail:E-commerce platforms facilitating patient-managed device acquisition for homecare-compatible technologies.
Direct Sales commands premium pricing power. Specialty Clinics concentrate volume in consolidated health systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Los Angeles anchors trans-Pacific medical device logistics, channeling thermal pulsation platforms into ophthalmology networks across the western United States. This infrastructure underwrites distribution velocity for manufacturers targeting clinic procurement cycles.
United States
Ophthalmology practices in metropolitan corridors deploy thermal pulsation systems at accelerated replacement cycles. FDA 510(k) pathways streamline premarket authorization for meibomian gland dysfunction platforms. Boston's medical device cluster concentrates regulatory affairs expertise and clinical trial infrastructure.
Germany
University hospital networks consolidate equipment procurement through centralized purchasing committees. EU Medical Device Regulation imposes stricter clinical evidence requirements for CE marking of ophthalmic equipment. Baden-Württemberg's precision engineering corridor supplies optical component fabrication.
Japan
JIS-certified specialty centers drive premium-tier adoption of thermal-based therapeutic platforms. PMDA electrical medical device standards require expanded electromagnetic compatibility documentation for market authorization. Tokyo's ophthalmology corridor concentrates purchasing authority and service engineering capacity.
United Kingdom
NHS commissioning frameworks shape reimbursement positioning for in-office procedural devices. MHRA post-Brexit regulatory autonomy creates distinct conformity assessment pathways from EU MDR. London's private ophthalmology networks import premium thermal platforms ahead of national health system adoption.
South Korea
MFDS medical device registration timelines compress for thermal ophthalmic equipment with predicate device references. Seoul Capital Area's ophthalmology chains standardize on combination therapy protocols integrating thermal and optical modalities. Busan-Ulsan's precision manufacturing base supplies miniaturized electromechanical components.
Dry Eye Treatment Devices Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream supplying precision thermal and optical subsystems to finished device assemblers. The vendor base organizes into three tiers: multinational eye care conglomerates with established distribution infrastructure, mid-scale device specialists with concentrated commercial teams, and regional fabricators serving geographic niches. Dominant competitive moves include direct-to-clinic channel establishment bypassing traditional distributor markups, and portfolio diversification into homecare-compatible miniaturized formats.
Among the named participants, Sight Sciences and Lumenis exemplify the device-specialist archetype with concentrated commercial organizations targeting ophthalmology practices, while Alcon occupies a position representing the integrated eye care conglomerate tier with extended distribution infrastructure. These three anchors illustrate the competitive spectrum from pure-play thermal platform developers to diversified manufacturers cross-leveraging pharmaceutical and device portfolios.
| Leading Market Players |
|---|
| Sight Sciences |
| Lumenis |
| MiBo Medical Group |
| ESW Vision |
| Alcon |
| Johnson & Johnson Vision |
| BlephEx LLC |
| BioTissue |
| NuSight Medical |
| Others |
Cost & Logistics Intelligence
Baden-Württemberg's precision engineering corridor concentrates optical component fabrication capacity, creating asymmetric pricing power for thermal pulsation device manufacturers who source electromechanical subsystems from this German cluster. Clinics in the United States and Japan absorb premium pricing for FDA 510(k) cleared and PMDA authorized platforms, while procurement committees in consolidated health systems extract volume concessions from suppliers lacking geographic diversification.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies the installed base, with premium tiers commanding elevated positioning through FDA 510(k) clearance status and bundled clinical training protocols. Price differentiation hinges on certification tier and after-sales service intensity, with EU MDR CE marking and ISO 13485 quality management certification separating premium from standard offerings. Cost compression in the economy tier is intensifying because Asian manufacturers are miniaturizing thermal pulsation technology for direct-to-consumer channels. Hospital purchasing committees exhibit highest price sensitivity, while specialized ophthalmology clinics in premium metropolitan markets demonstrate lowest sensitivity due to procedural revenue offset.
Supply Chain Analysis
Export control regimes on precision optical components and semiconductor-grade temperature sensors constrain flows from select Asian manufacturing clusters, forcing device assemblers to qualify alternative suppliers. Supply concentrates in Germany for electromechanical subsystems, South Korea for miniaturized thermal control modules, and Japan for biocompatible ocular surface contact materials. Raw material dependencies center on medical-grade silicone, rare-earth doped optical fibers, and platinum resistance temperature detectors. Single-source vulnerability in precision light-delivery systems exposes procurement to logistics volatility. Distribution runs through direct sales teams for clinic-bound equipment and e-commerce platforms for homecare-compatible devices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from pharmaceutical-first therapy protocols as clinicians rebuild procedural revenue models around device-centric protocols. The cyclical driver is reimbursement code consolidation for in-office dry eye procedures across Medicare and private payer systems.
For Market Incumbents: Harden regulatory moats by accelerating EU MDR technical documentation completion for existing thermal pulsation platforms before stricter clinical evidence requirements fully phase in. Deepen backward integration into precision optical component supply by acquiring Baden-Württemberg fabrication specialists, reducing exposure to Asian logistics volatility. Channel control through specialized commercial teams remains essential as distributor markups compress margins in competitive ophthalmology networks.
For New Entrants and Emerging Players: Establish a beachhead in homecare settings where miniaturization trends and direct-to-consumer channels bypass entrenched clinic procurement gatekeepers. Target patient-managed therapy segments with portable thermal pulsation devices priced below clinic-bound capital equipment thresholds. Pursue software companion development as the primary go-to-market angle, enabling subscription revenue models that incumbent hardware manufacturers have been slow to adopt.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among device specialists with integrated data platforms and patient monitoring subscriptions rather than pure hardware vendors. Long-term viability over the coming decade favors manufacturers with regulatory affairs capabilities spanning FDA, EU MDR, and PMDA jurisdictions. The acquisition target archetype is mid-scale thermal platform developers with cleared 510(k) predicates but underdeveloped commercial infrastructure. Watch reimbursement code finalization for combination thermal-optical therapies as the inflection signal indicating procedural revenue sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy | CMS code alignment for thermal pulsation procedures secures clinic adoption economics in the United States. |
| CE Marking Pathway | EU MDR technical documentation investment raises competitive barriers against undercapitalized rivals seeking European market entry. |
| Hospital System Partnership | Centralized purchasing committee relationships in Germany's university hospital networks consolidate procurement volume. |
| Software Companion Development | Connected health infrastructure enables recurring subscription revenue from previously transactional hardware sales. |
| Backward Integration | In-house production of precision optical subsystems reduces dependency on concentrated Asian manufacturing clusters. |
Research Approach
Cross-validation between primary interviews with ophthalmology practice administrators, biomedical engineers, GPO contracts managers, and regulatory affairs specialists anchors the qualitative findings against secondary validation from FDA 510(k) filings, PMDA submission databases, CMS Medicare reimbursement schedules, and EU MDR notified body documentation. Bottom-up demand modeling from clinic procurement cycles and top-down market sizing from equipment manufacturer revenue disclosures were reconciled through iterative triangulation.
Calibration against historical replacement cycles for thermal pulsation platforms and intense pulsed light systems informed the analytical framework across the projection horizon. Segmentation dimensions modeled include device type, treatment method, end user setting, and distribution channel complexity. CAGRs were derived from equipment shipment velocities and procedural volume trajectories, with inputs from miniaturization cost curves and regulatory authorization timelines shaping the forecast envelope.
Stress conditions across reimbursement code fragmentation, optical component supply disruption, and pharmaceutical substitution pressure were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding clinician adoption curves and patient compliance rates for homecare protocols. Material shifts in FDA clearance timelines or EU MDR enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Canes and Crutches Market
Medical Devices
Carotid Stenting Systems Market
Medical Devices
Gamma Knife Market
Medical Devices
South Korea Massage Equipment Market
Medical Devices
Disposable Medicine Measuring Cups Market
Medical Devices
Sterile Filtration Module Market
Medical Devices
Walkers and Rollators Market
Medical Devices
Germanium-68/Gallium-68 Generators Market
Medical Devices
Global Electronic Drug Delivery Systems Market
Medical Devices
Neuroendoscopy Devices Market
Medical Devices
Global Stent Graft Balloon Catheter Market
Medical Devices
Surgical Smart Glasses Market
Medical Devices
Global Robotic Wheelchairs Market
Medical Devices
Global Surgical Visualization Products Market
Medical Devices
Latin America Biomedical Sensors Market
Medical Devices
Cochlear Implant Systems Market