
 Electrophysiology Market | 2026-2036
Electrophysiology Market Size, Share, and Industry Trends Forecast 2026-2036
Electrophysiology Market Analysis
Project finance and equipment leasing for catheter labs is tilting competitive dynamics toward hospital networks that can deploy advanced mapping systems without full capital ownership. Medtronic leverages its integrated hardware-software ecosystem to sustain recurring revenue from consumable catheters. Abbott differentiates through contact force-sensing ablation technology that commands premium positioning in atrial fibrillation procedures. Johnson & Johnson Services, Inc. anchors its electrophysiology presence through Biosense Webster's three-dimensional mapping platforms that dominate complex ablation workflows.
Electrophysiology encompasses the diagnostic and therapeutic manipulation of cardiac electrical activity using electrode-tipped catheters, mapping systems, and energy-delivery platforms operating at frequencies from 300 to 750 kHz for radiofrequency ablation. The field serves the industrial purpose of restoring normal heart rhythm in patients with supraventricular and ventricular tachyarrhythmias. Diagnostic devices and mapping systems capture the largest margin pools as hospitals prioritize precision localization of arrhythmic substrates before energy delivery. Catheters represent the highest-volume recurring segment, with cryoablation and radiofrequency technologies splitting the ablation technology landscape based on lesion durability and procedural speed trade-offs.
The FDA's breakthrough device program and the EU MDR's clinical evidence requirements shape product development timelines and market access trajectories for electrophysiology manufacturers. Japan's PMDA and China's NMPA impose additional localization and clinical trial obligations that filter which multinationals compete in Asia-Pacific. Stakeholders must monitor reimbursement shifts for ambulatory cardiac ablation and the evolving clinical evidence linking specific catheter technologies to long-term arrhythmia-free survival.
Market Dynamics
Catheter-based ablation is displacing pharmacological rhythm management as first-line therapy for paroxysmal atrial fibrillation, compressing the addressable patient pool for antiarrhythmic drugs and elevating hospital capital allocation toward electrophysiology lab infrastructure.
Growth Catalysts
- FDA Breakthrough Device Designation:Expedited review pathways compress time-to-market for novel mapping catheters and pulsed field ablation systems, accelerating commercialization timelines for manufacturers targeting complex ventricular tachycardia substrates.
- Aging demographics in Japan and Germany:Elevated prevalence of atrial fibrillation in populations over 65 years is expanding procedure volumes in tertiary cardiac centers with established reimbursement frameworks.
- Radiofrequency energy delivery at 300-750 kHz:Lesion durability and procedural efficiency advantages over cryoablation in pulmonary vein isolation are sustaining physician preference and repeat procedure economics.
Market Restraints
- Platinum-iridium electrode tip supply concentration:Dependence on specialized precious metal suppliers in South Africa and Russia creates input cost volatility and geopolitical exposure for catheter manufacturers.
- EU MDR clinical evidence requirements:Expanded post-market surveillance obligations and notified body capacity constraints are extending recertification timelines and elevating compliance expenditures for CE-marked devices.
- Pharmacological rhythm control:Direct oral anticoagulants and upstream antiarrhythmic therapy retain first-line status in certain European markets, limiting ablation penetration in cost-constrained health systems.
Strategic Opportunities
- India's underserved electrophysiology infrastructure:Concentration of ablation capacity in Delhi, Mumbai, and Chennai metropolitan clusters leaves tier-2 cities with catheterization labs but without dedicated electrophysiology programs.
- Pulsed field ablation convergence with high-density mapping:Integration of irreversible electroporation with three-dimensional anatomical reconstruction enables single-shot pulmonary vein isolation with reduced esophageal injury risk.
- Japan PMDA Sakigake designation:Priority review and early reimbursement consultation for innovative cardiac devices accelerates market access for novel ablation technologies in the Asia-Pacific's highest-value electrophysiology market.
Industry Challenges
- Electrophysiologist training pipeline:Fellowship positions and proctoring capacity are constraining expansion of ablation programs in health systems seeking to add catheter lab services.
- Capital equipment integration complexity:Mapping system hardware, ablation generator platforms, and electronic health record networks require specialized biomedical engineering support that exceeds rural hospital staffing models.
- Patent thickets around contact force sensing:Licensing negotiations and infringement disputes surrounding pressure-sensitive catheter tip technology are elevating R&D legal expenditures and delaying product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrophysiology Market |
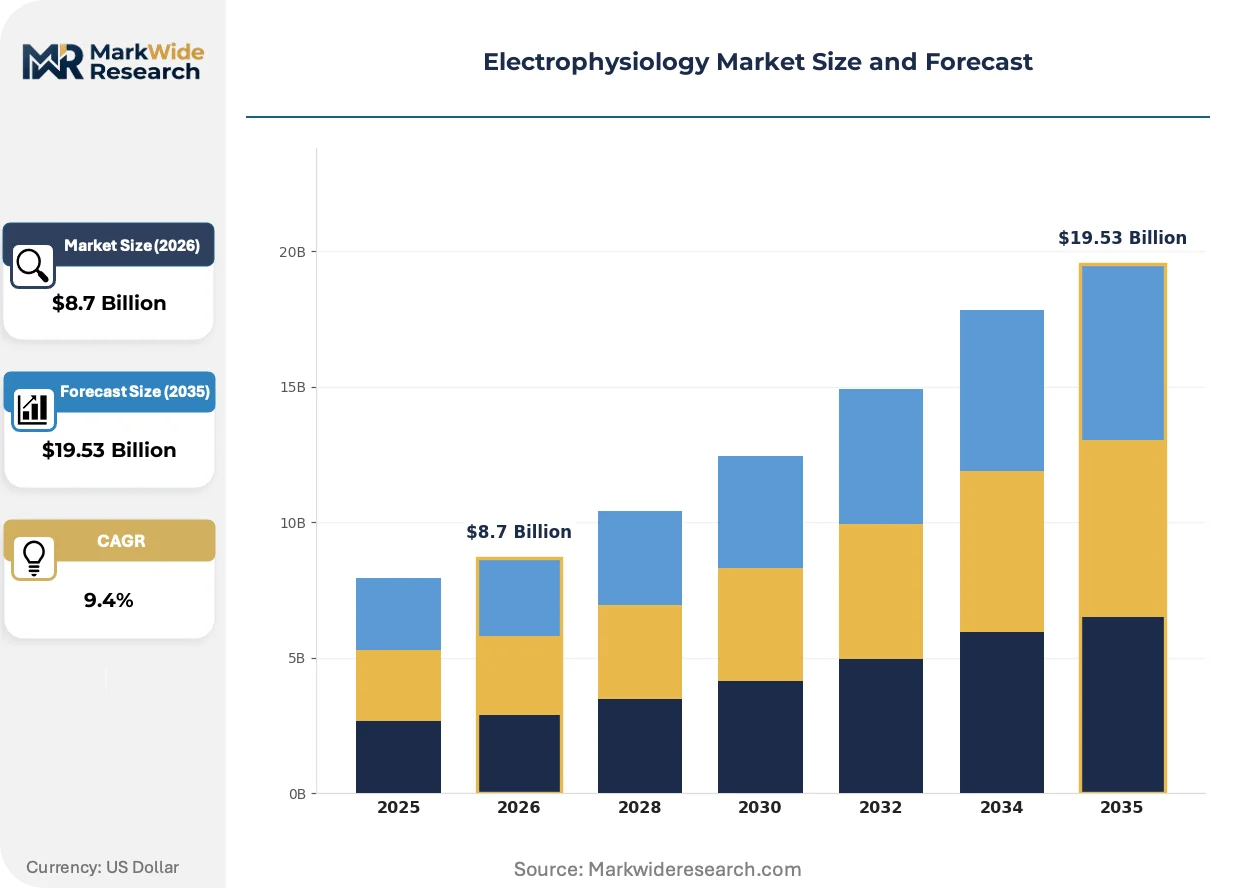
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Devices, Catheters, Electrophysiology Ablation Systems, Mapping Systems End User: Cardiology Centers, Hospitals, Clinics, Research Laboratories Technology: Radiofrequency, Cryoablation, Laser, Ultrasound Application: Atrial Fibrillation, Ventricular Tachycardia, Atrioventricular Nodal Reentry, Others |
| Companies Covered | Boston Scientific Corporation, Medtronic, Abbott, Johnson & Johnson Services, Inc., BIOTRONIK, GE Healthcare, Koninklijke Philips N.V., Microport Scientific Corporation, AtriCure, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrophysiology Market Emerging Trajectories
Real-time computational integration is compressing the diagnostic-to-therapeutic interval in cardiac ablation workflows, enabling substrate characterization and energy delivery within unified procedural sessions rather than staged interventions.
High-density multielectrode mapping catheters with automated signal processing are rendering obsolete point-by-point manual annotation systems that required extended fluoroscopy exposure and prolonged procedure times. Tertiary cardiac centers in the United States and Germany are adopting these platforms for complex atrial and ventricular arrhythmia cases, compressing average procedure duration and elevating throughput capacity in high-volume electrophysiology labs.
EU MDR Article 117 and associated clinical evaluation report requirements are elevating post-market clinical follow-up obligations for legacy ablation catheters previously approved under the Medical Device Directive. Manufacturers must generate prospective safety and performance data for grandfathered products, compressing profit margins on mature product lines and accelerating portfolio rationalization toward next-generation platforms with embedded clinical evidence generation capabilities.
Hospital procurement departments are unbundling capital equipment acquisition from disposable catheter supply agreements, fragmenting vendor lock-in strategies that historically tied mapping system purchases to multi-year exclusive catheter contracts. This pattern is most visible in United States hospital networks with centralized supply chain governance, where value analysis committees now evaluate catheter technologies on standalone clinical and economic merit rather than ecosystem integration.
Electrophysiology Market Segmentation
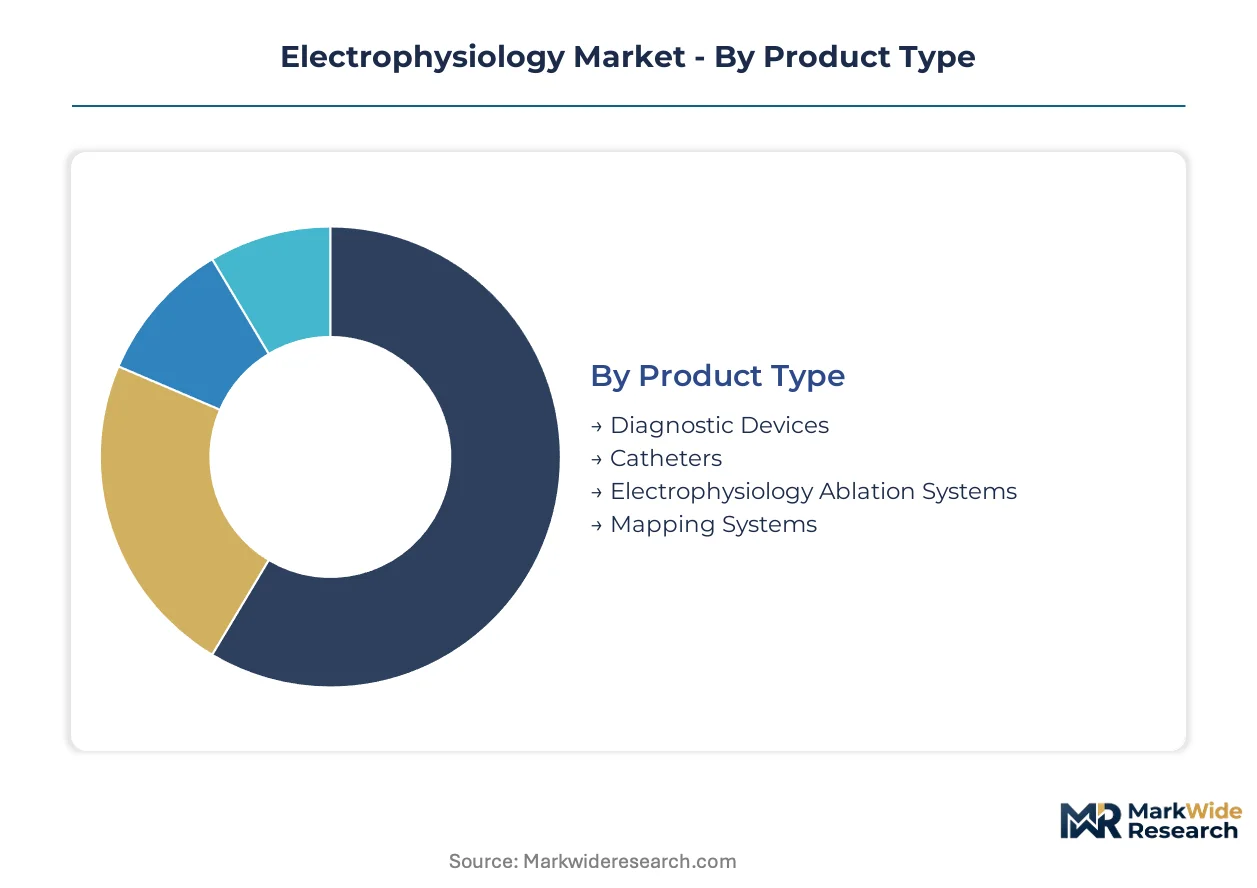
Segmentation in electrophysiology reveals how capital equipment, consumable catheters, and energy-delivery platforms command distinct margin profiles and replacement cycles. Hospital procurement teams evaluate each category through separate value-analysis frameworks, with mapping systems requiring long-term infrastructure commitments while catheter selections rotate more frequently based on physician preference.
Product Type:
Cost tier stratification separates capital-intensive fixed assets from high-velocity disposable revenue streams in manufacturer portfolios.
- Diagnostic Devices:Electrode-tipped catheters and recording systems capture intracardiac electrical signals during electrophysiology studies. Demand concentrates in German tertiary cardiac centers where reimbursement clarity supports upfront diagnostic workup before ablation commitment.
- Catheters:Steerable, multi-electrode disposable devices constitute the highest-volume recurring revenue segment in manufacturer portfolios. United States hospital networks with centralized supply chain governance are unbundling catheter procurement from mapping system contracts, fragmenting historical vendor lock-in strategies.
- Electrophysiology Ablation Systems:Energy-delivery platforms operating at radiofrequency or cryothermal parameters generate lesions to interrupt arrhythmic circuits. Japanese PMDA priority review pathways accelerate commercialization timelines for novel ablation generators.
- Mapping Systems:Three-dimensional electroanatomical reconstruction platforms with integrated magnetic or impedance-based localization enable substrate visualization without fluoroscopy. These systems anchor hospital capital budgets and require specialized biomedical engineering support.
Mapping systems hold installed capacity. Catheters are rotating up the share rankings.
End User:
Customer type determines purchasing authority complexity and clinical volume thresholds across the care continuum.
- Cardiology Centers:Dedicated electrophysiology facilities with fellowship-trained staff perform high-complexity ablation procedures. Concentration of ablation capacity in Delhi, Mumbai, and Chennai metropolitan clusters leaves tier-2 Indian cities with catheterization labs but without dedicated electrophysiology programs.
- Hospitals:General acute-care institutions with cardiac service lines balance electrophysiology investment against competing capital priorities. United States hospital networks expanding catheter-based arrhythmia treatment capacity are deploying advanced mapping systems through equipment leasing rather than full capital ownership.
- Clinics:Outpatient diagnostic facilities conduct initial rhythm assessment and patient triage for referral to ablation centers. Ambulatory cardiac ablation reimbursement shifts are elevating interest in office-based electrophysiology services.
- Research Laboratories:Academic and translational research settings investigate novel energy modalities and arrhythmia mechanisms. These sites generate clinical evidence supporting regulatory submissions to FDA and EMA.
Hospitals anchor procedure volume. Cardiology centers are climbing the fastest in throughput expansion.
Technology:
Energy-delivery modality shapes lesion characteristics, procedural efficiency, and complication risk profiles in pulmonary vein isolation.
- Radiofrequency:Thermal energy delivery at 300-750 kHz creates transmural lesions through resistive heating of myocardial tissue. Lesion durability and procedural efficiency advantages over cryoablation sustain physician preference in United States electrophysiology labs.
- Cryoablation:Balloon-based nitrous oxide delivery achieves circumferential pulmonary vein isolation through tissue freezing. Single-shot anatomical coverage reduces procedure duration in paroxysmal atrial fibrillation cases.
- Laser:Optical energy delivery enables precise lesion geometry with adjustable penetration depth. Limited commercial penetration reflects capital equipment requirements and training infrastructure needs.
- Ultrasound:High-intensity focused acoustic energy generates thermal lesions without electrode-tissue contact. Experimental applications in ventricular tachycardia substrate ablation remain investigational.
Radiofrequency holds installed capacity. Pulsed field systems are gaining share fastest as next-generation entrants.
Application:
Arrhythmia substrate complexity determines mapping system requirements, catheter selection, and reimbursement intensity per procedure.
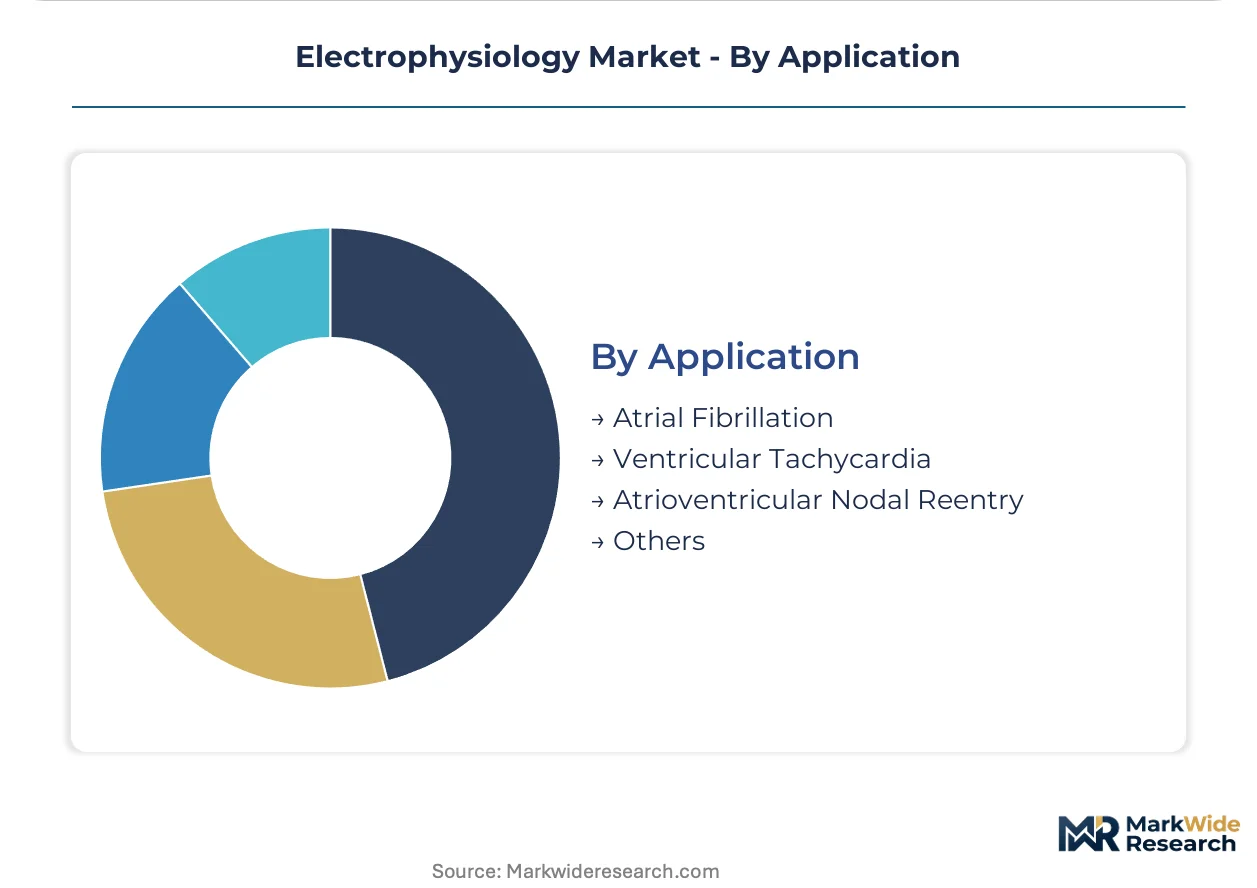
- Atrial Fibrillation:The most common sustained arrhythmia requiring pulmonary vein isolation or substrate modification. Aging demographics in Japan and Germany elevate procedure volumes in tertiary cardiac centers with established reimbursement frameworks.
- Ventricular Tachycardia:Life-threatening arrhythmia arising from scar-related reentry circuits in post-infarction or cardiomyopathy substrates. FDA breakthrough device designations accelerate commercialization for novel mapping catheters targeting complex ventricular tachycardia.
- Atrioventricular Nodal Reentry:Supraventricular tachycardia mechanism involving dual atrioventricular nodal pathways. Cryoablation preference in pediatric populations reflects reduced permanent conduction block risk.
- Others:Accessory pathway-mediated tachycardias, atrial flutter, and idiopathic ventricular arrhythmias comprise residual procedure volume. EU MDR clinical evidence requirements extend recertification timelines for legacy ablation catheters across all arrhythmia indications.
Atrial fibrillation holds installed capacity. Ventricular tachycardia is expanding most quickly in academic center case mix.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA breakthrough device designations and Japan's PMDA Sakigake pathway are compressing commercialization timelines for novel ablation technologies. Reimbursement clarity in Germany and aging demographics across developed markets are expanding procedure volumes in tertiary cardiac centers.
United States
Hospital networks in the United States are expanding catheter-based arrhythmia treatment capacity through equipment leasing rather than full capital ownership. The FDA's breakthrough device program expedites review pathways for pulsed field ablation systems and novel mapping catheters. Tertiary cardiac centers in Boston and Cleveland anchor complex ablation case volumes with established electrophysiology fellowship programs.
Germany
German tertiary cardiac centers prioritize precision localization of arrhythmic substrates before energy delivery, capturing the largest margin pools in diagnostic devices and mapping systems. EU MDR Article 117 elevates post-market clinical follow-up obligations for legacy ablation catheters, compressing profit margins on mature product lines. The Rhine-Ruhr metropolitan cluster concentrates ablation capacity with established reimbursement frameworks supporting procedure volume expansion.
Japan
Aging demographics in Japan are elevating atrial fibrillation prevalence in populations over 65 years, expanding procedure volumes in tertiary cardiac centers. The PMDA Sakigake designation provides priority review and early reimbursement consultation for innovative cardiac devices, accelerating market access for novel ablation technologies. Tokyo and Osaka metropolitan areas anchor electrophysiology infrastructure with the highest-value procedure economics in Asia-Pacific.
India
Ablation capacity in India concentrates in Delhi, Mumbai, and Chennai metropolitan clusters, leaving tier-2 cities with catheterization labs but without dedicated electrophysiology programs. The country's national medical device regulator imposes localization and clinical trial obligations that filter which multinationals compete in this market. Hyderabad and Bangalore are emerging as destinations for medical technology manufacturing partnerships targeting domestic supply chain development.
China
China's national medical products administration requires additional localization and clinical trial obligations for electrophysiology manufacturers seeking market access. Shanghai and Beijing anchor high-complexity ablation programs with growing adoption of three-dimensional mapping platforms. Provincial hospital networks are expanding electrophysiology lab infrastructure through public-private partnership financing models.
Electrophysiology Market Vendor Landscape
On the supply side, the industry is consolidating around integrated hardware-software ecosystems that generate recurring revenue from consumable catheters. Large diversified medical technology conglomerates compete against specialized cardiac rhythm management pure-plays, creating a tiered competitive structure. Two strategic archetypes dominate: mapping system platform holders with captive catheter supply agreements, and contact force-sensing catheter specialists commanding premium positioning. M&A activity concentrates on pulsed field ablation technology acquisitions, while strategic partnerships target high-density mapping integration.
Among diversified medical technology conglomerates, Medtronic, Abbott, and Johnson & Johnson Services, Inc. represent the integrated platform archetype, each anchoring competitive positioning through distinct hardware-software ecosystems. These companies exemplify the capital equipment-to-consumables business model that sustains recurring revenue streams in hospital electrophysiology labs. Their geographic footprints span United States, European, and Asia-Pacific markets with established regulatory clearance portfolios.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Medtronic |
| Abbott |
| Johnson & Johnson Services, Inc. |
| BIOTRONIK |
| GE Healthcare |
| Koninklijke Philips N.V. |
| Microport Scientific Corporation |
| AtriCure, Inc. |
| Others |
Supply Flow & Price Mechanics
Platinum-iridium electrode tip suppliers in South Africa and Russia anchor input cost volatility for catheter manufacturers, concentrating margin pressure on the consumable tier while diagnostic devices and mapping systems retain pricing power through regulatory certification barriers. This upstream precious metal dependence feeds directly into hospital procurement negotiations, where unbundled catheter contracts face steeper price compression than integrated capital equipment ecosystems.
Pricing Analysis
Certification level (FDA breakthrough/CE MDR/Sakigake-grade) creates the primary spread between premium mapping platforms and standard diagnostic catheters. Three-tier pricing structure across premium, standard, and economy levels reflects after-sales service bundling and software companion integration. Cost compression in the catheter tier is intensifying because hospital supply chain governance is fragmenting historical vendor lock-in agreements. Ambulatory clinics exhibit highest price sensitivity; tertiary cardiac centers with fellowship programs show lowest sensitivity due to throughput economics.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from specialized precious metal traders in South Africa and Russia shape working capital requirements for electrode tip manufacturers. Component sourcing draws from Germany for precision mapping sensors, Japan for ablation generator electronics, and the United States for software platforms. Single-source vulnerability in platinum-iridium supply creates geopolitical exposure. Distribution runs through hospital procurement committees and GPO contracts in developed markets, with direct manufacturer-to-hospital relationships dominating capital equipment sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pulsed field ablation convergence with high-density mapping is compressing the diagnostic-to-therapeutic interval, creating a regulatory and technological inflection that rewards first-movers with integrated platform capabilities.
For Market Incumbents: Insulate installed base economics by deepening software companion integration and securing multi-year catheter supply agreements before procurement unbundling accelerates. Expand biomedical engineering service contracts to lock in mapping system loyalty against emerging pulsed field entrants. Priority lever: exclusive hospital system partnerships in Germany and Japan where reimbursement clarity supports long-term commitments.
For New Entrants and Emerging Players: Pursue tier-2 Indian cities with catheterization labs but lacking dedicated electrophysiology programs, where capital equipment leasing models lower entry barriers. Target contact force-sensing catheter niches where patent thickets are expiring. Go-to-market angle: pulsed field ablation systems with reduced esophageal injury risk, pitched to safety-focused procurement committees.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across pulsed field ablation sub-segments as single-shot platforms reduce procedure duration and elevate throughput. Long-term viability favors manufacturers with embedded clinical evidence generation capabilities for EU MDR compliance. Acquisition target archetype: high-density mapping specialists with FDA breakthrough designations. Signal to watch: PMDA Sakigake approvals as leading indicator of Asia-Pacific premium pricing power.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Expedited review compresses time-to-market for pulsed field ablation in ventricular tachycardia. |
| CE Marking Pathway under EU MDR | Article 117 compliance elevates post-market surveillance obligations for legacy catheter portfolios. |
| Hospital System Partnership | Equipment leasing agreements with United States networks reduce capital ownership barriers. |
| Software Companion Development | Real-time computational integration unifies diagnostic and therapeutic workflows in mapping platforms. |
| Reimbursement Strategy | Ambulatory ablation coding shifts in Germany and Japan determine procedure volume economics. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across electrophysiology labs, hospital procurement committees, biomedical engineering departments, and GPO contracts managers. Primary interviews triangulated with secondary validation from FDA 510(k) filings, PMDA approval databases, EU MDR notified body certificates, and hospital procurement records. Bottom-up catheter volume modeling and top-down mapping system revenue analysis were cross-checked against CMS Medicare procedure data and German DRG reimbursement schedules.
Calibration against historical procedure volume trajectories in the United States, Germany, and Japan anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type (capital equipment versus consumables), energy delivery modality, arrhythmia substrate complexity, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to hospital capital budget cycles and catheter replacement rates. Forecast inputs incorporated electrophysiologist fellowship pipeline constraints and EU MDR recertification timelines.
Macroeconomic conditions sit as an overlay; deviation in hospital capital expenditure cycles, precious metal commodity prices, or reimbursement policy would shift the trajectory. Forecasts reflect documented assumptions about procedure volume expansion, regulatory pathway durations, and competitive platform adoption. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Ultrasound Biometry Devices Market
Medical Devices
Nasogastric Tube Market
Medical Devices
Illuminating Eye Massagers Market
Medical Devices
Global Surgical/Operating Microscopes Market
Medical Devices
Global Thoracic Drainage Devices Market
Medical Devices
Global Augmentative and Alternative Communication (AAC) Devices Market
Medical Devices
Europe Organ Preservation Market
Medical Devices
US Medical Device Outsourcing Market
Medical Devices
Americas Wearable Medical Device Market
Medical Devices
Japan Contraceptive Devices Market
Medical Devices
Struts Implants Market
Medical Devices
Global Infusion Pumps and Accessories Market
Medical Devices
Cranial Perforator Market
Medical Devices
Global Spirometers Market
Medical Devices
Vaginal Pessary Market
Medical Devices
Hemodialysis Catheters Market