
 China Electrocardiograph (ECG) Market | 2026-2036
China Electrocardiograph (ECG) Market Size, Share, and Industry Trends Forecast 2026-2036
China Electrocardiograph (ECG) Market Insights
AI-enhanced signal processing is fragmenting the traditional ECG technology stack into modular hardware-software layers. Shenzhen Mindray Bio-Medical Electronics Co., Ltd. leverages its domestic manufacturing scale to control cost structures across portable and traditional device lines. Lepu Medical Technology (Beijing) Co., Ltd. anchors its position through backward integration into electrode and sensor production. EDAN Instruments, Inc. specializes in compact Holter systems for clinic and home care deployment.
An electrocardiograph records the heart's electrical activity through surface electrodes, typically sampling at 500–1000 Hz with 12-lead configurations to detect arrhythmias, ischemia, and structural abnormalities. Portable ECG devices are capturing margin pools as home care and clinic channels expand beyond hospital-centric procurement. AI-Enhanced ECG technology leads growth trajectories by embedding real-time diagnostic algorithms that reduce specialist interpretation burdens. Wireless ECG competes on patient mobility but faces reimbursement friction in diagnostic center workflows.
NMPA's Class II device registration requirements and GB 9706 medical electrical safety standards shape product development timelines and market access for domestic and imported systems. China's dual carbon goals are pushing manufacturers toward lower-power device architectures and sustainable packaging compliance. Stakeholders must monitor how provincial procurement consortia reshape pricing dynamics and channel control across tiered city networks.
Market Dynamics
AI-enhanced signal processing is fragmenting the traditional ECG technology stack into modular hardware-software layers, forcing manufacturers to recalibrate R&D allocation between embedded algorithms and device hardware.
Growth Catalysts
- Healthy China 2030 Framework:Rural hospital networks are expanding ECG procurement quotas under national cardiovascular screening mandates, creating pull-through demand for portable and wireless device categories.
- NMPA Streamlined Class II Pathway:Accelerated medical device approval timelines compress domestic innovation cycles from 18-24 months to 12-16 months for algorithm-embedded systems.
- Tier-Two City Screening Programs:Provincial health commissions in Sichuan, Hubei, and Shandong are scaling community-based arrhythmia detection networks faster than tier-one saturation permits.
Market Restraints
- Electrode Raw Material Concentration:Silver-silver chloride sensor supply chains concentrate in Jiangsu and Zhejiang manufacturing clusters, exposing producers to input cost volatility and single-source risk.
- Reimbursement Friction for Wireless ECG:Diagnostic center workflows face delayed provincial reimbursement code adoption for ambulatory monitoring, constraining patient mobility value capture.
- AI Algorithm Validation Burden:NMPA's clinical evidence requirements for machine-learning diagnostic outputs extend registration timelines and inflate validation costs for software-heavy submissions.
Strategic Opportunities
- Home Care Channel Expansion:Pharmacy retail chains and telemedicine platforms are creating direct-to-patient distribution pathways that bypass traditional hospital procurement committees.
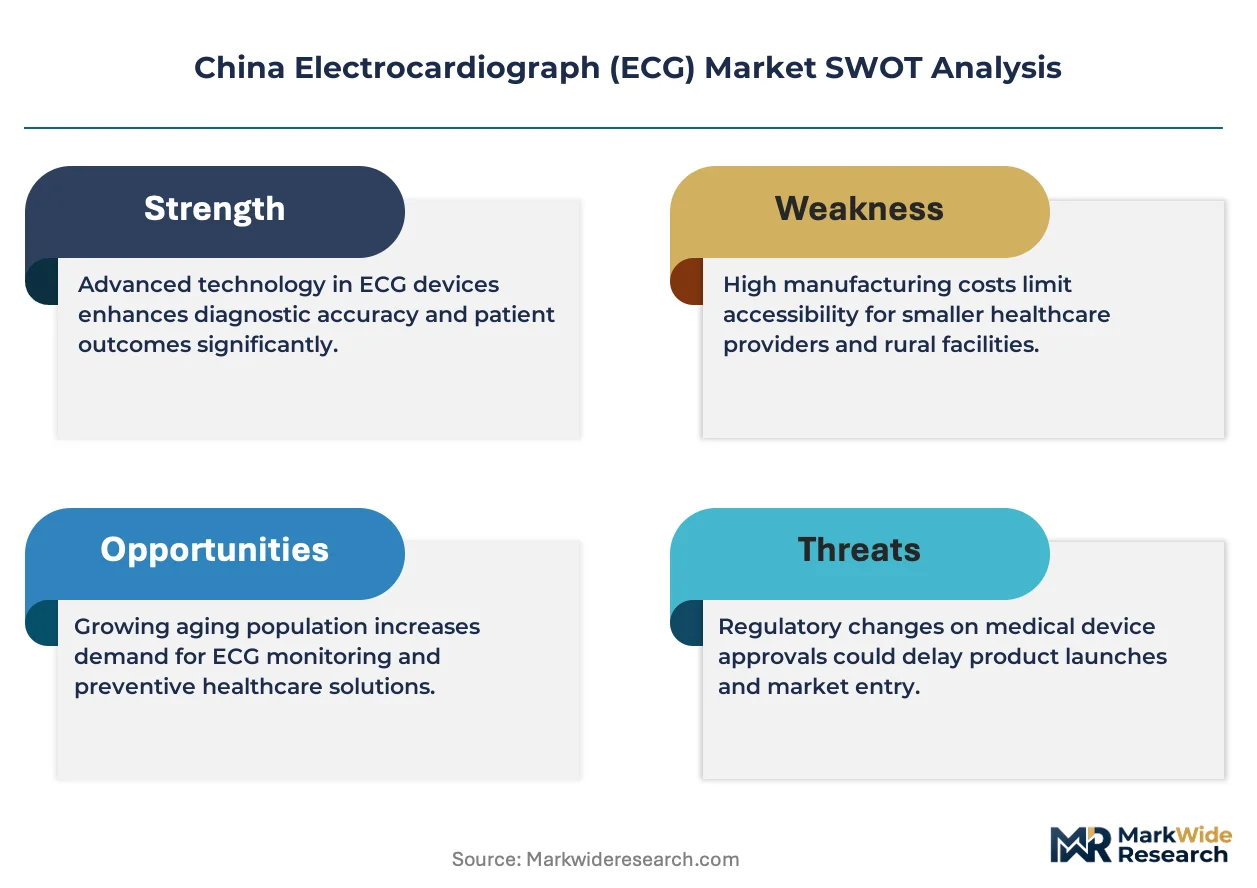
- Dual Carbon Compliance Differentiation:Lower-power device architectures and sustainable packaging align with MEE enforcement trajectories, opening preferential tender scoring for green-certified manufacturers.
- AI-ECG Convergence with Wearables:Integration of real-time arrhythmia detection into consumer health bands creates data pipeline opportunities for clinic-validated diagnostic services.
Industry Challenges
- Embedded Systems Talent Scarcity:Firmware engineers with medical signal processing expertise command 40-60% salary premiums, constraining domestic R&D team scaling.
- Legacy Hospital IT Integration:Provincial hospital networks operate fragmented EMR systems requiring custom HL7/FHIR middleware development for AI-ECG data ingestion.
- GB 9706 Electrical Safety Recertification:Updated medical electrical safety standards force hardware redesign cycles for existing product lines awaiting renewal.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Electrocardiograph (ECG) Market |
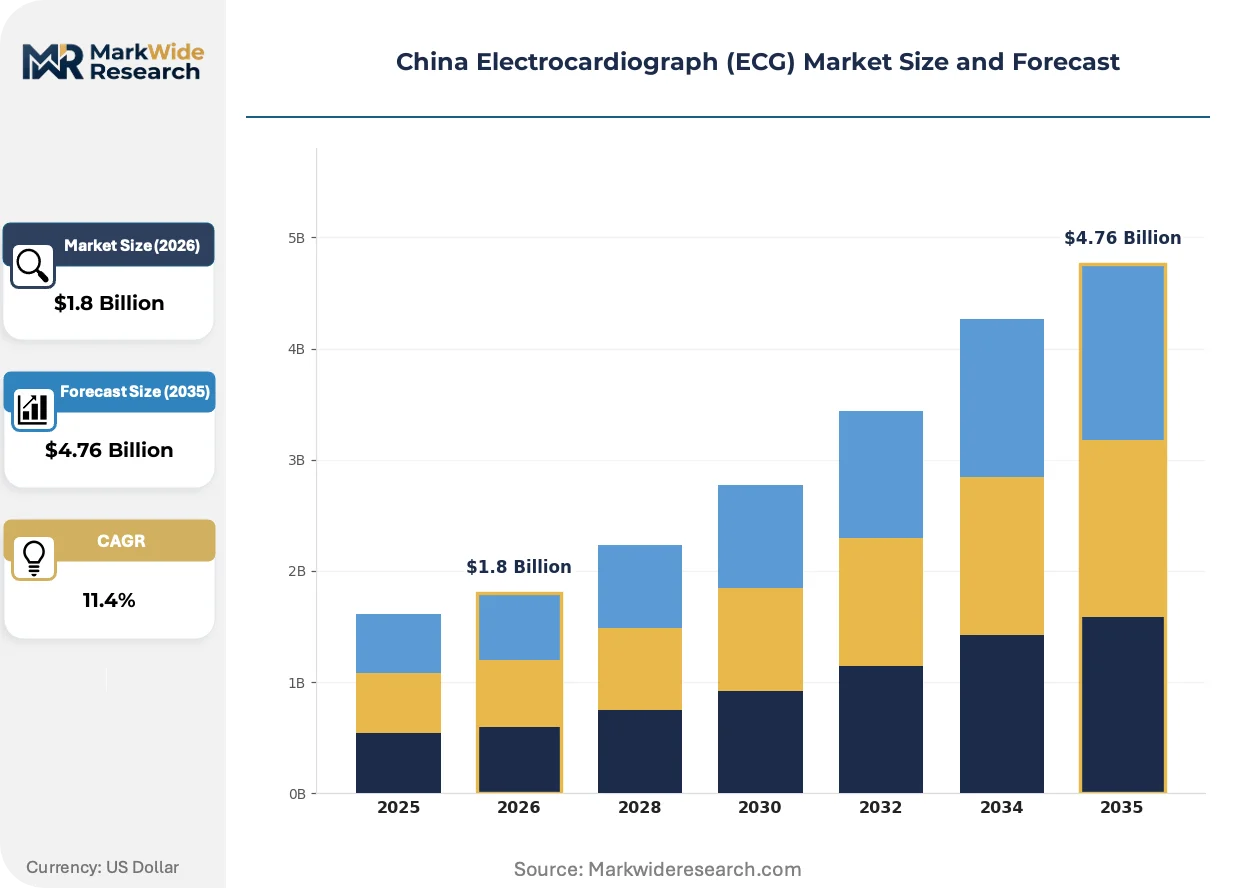
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable ECG, Holter Monitor, Stress ECG, Traditional ECG End User: Hospitals, Clinics, Home Care, Diagnostic Centers Technology: Analog ECG, Digital ECG, Wireless ECG, AI-Enhanced ECG Application: Cardiac Monitoring, Arrhythmia Detection, Stress Testing, Healthcare Research |
| Companies Covered | Lepu Medical Technology (Beijing) Co., Ltd., EDAN Instruments, Inc., Shenzhen Mindray Bio-Medical Electronics Co., Ltd., Nihon Kohden Corporation, Koninklijke Philips N.V., SCHILLER, GE HealthCare, MicroPort Scientific Corporation, Fukuda Denshi, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Electrocardiograph (ECG) Market Trends and Innovations
Signal processing architectures are bifurcating between cloud-dependent AI inference and edge-computing embedded diagnostics, reshaping how manufacturers define core competencies.
Deep learning-based ECG interpretation is hybridizing traditional 12-lead diagnostic workflows. Cardiology departments in tier-two municipal hospitals are piloting real-time algorithmic pre-screening that flags critical arrhythmias before specialist review. This compression of interpretation latency is enabling same-day diagnostic closure for outpatient screening programs.
NMPA's 2023 guidance on AI-enabled medical devices mandates clinical validation datasets reflecting China's demographic diversity. Domestic manufacturers must now submit algorithm performance stratified by age, region, and comorbidity prevalence. Software-centric submissions face extended review queues as regulator technical capacity scales to match submission volume.
Provincial procurement consortia are consolidating purchasing authority across county-level hospital networks. Device vendors now negotiate with centralized tender platforms in Sichuan and Guangdong rather than individual facility procurement departments. This buyer concentration is compressing price negotiation cycles and favoring suppliers with multi-product portfolio breadth.
China Electrocardiograph (ECG) Market Segmentation
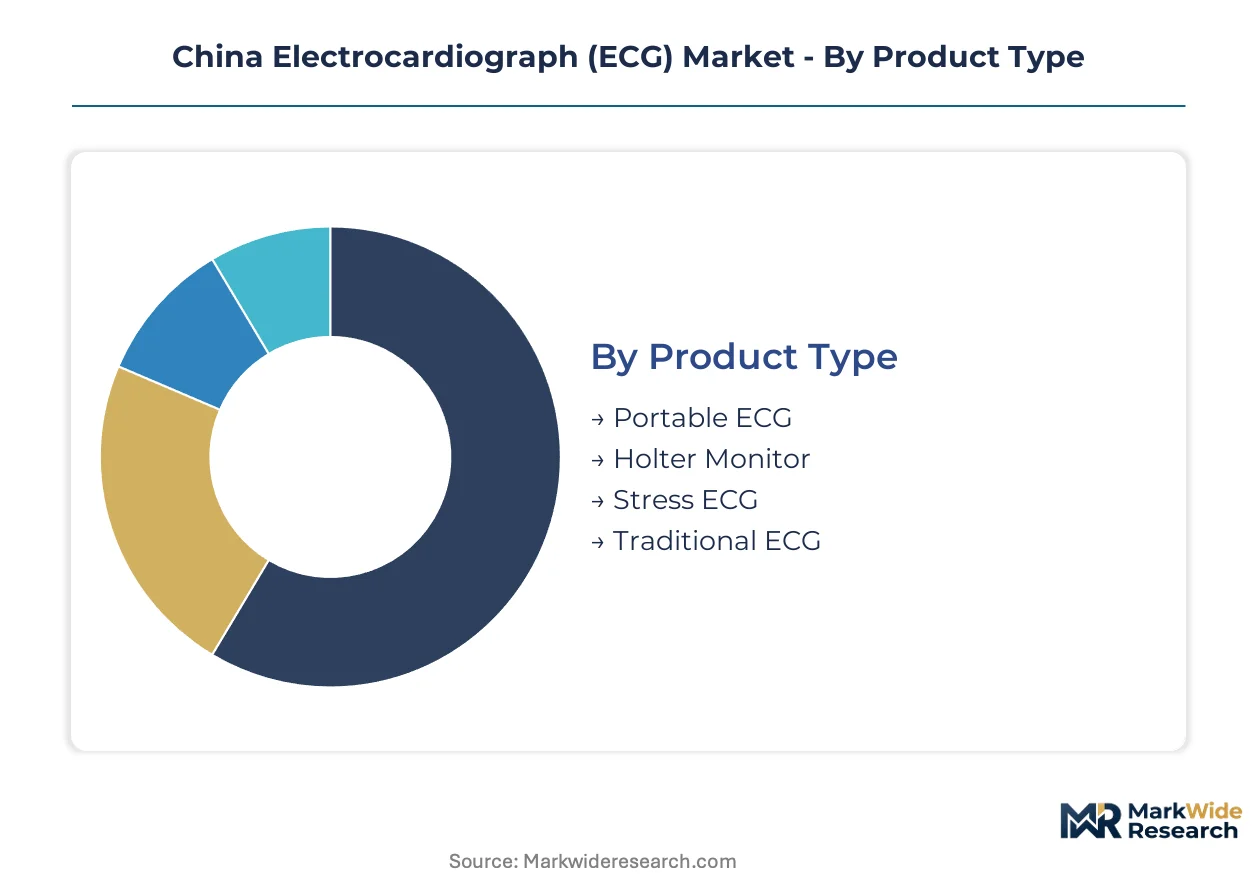
ECG procurement patterns in China diverge sharply across clinical settings and technology tiers. Device specifications, connectivity protocols, and reimbursement pathways reshape vendor priorities within each segment boundary.
Product Type:
After-sales service intensity varies dramatically across form factors, with portable units demanding remote calibration support and traditional systems requiring on-site preventive maintenance contracts.
- Portable ECG:Compact battery-powered units sample at 500–1000 Hz with 12-lead capability. Rural hospital networks in Sichuan and Shandong are scaling procurement for village clinic deployment under Healthy China 2030 cardiovascular screening mandates.
- Holter Monitor:Ambulatory systems record 24–48 hour continuous traces via 3–12 lead configurations. Diagnostic centers in tier-two cities face reimbursement friction for ambulatory monitoring codes, constraining patient mobility value capture.
- Stress ECG:Treadmill-integrated systems with real-time ST-segment analysis. Tertiary hospital cardiology departments anchor demand.
- Traditional ECG:Cart-based stationary units with thermal printing and EMR integration. Legacy hospital IT fragmentation drives middleware customization costs.
Traditional ECG holds the largest share; momentum sits with portable ECG.
End User:
Procurement authority concentrates differently across settings, with provincial consortia dominating hospital purchasing while home care channels bypass tender platforms entirely.
- Hospitals:Acute care settings demand 12-lead diagnostic-grade systems with HL7/FHIR EMR integration. County-level networks in Hubei consolidate purchasing through centralized tender platforms.
- Clinics:Community health centers prioritize compact units with simplified interpretation aids. Tier-two municipal arrhythmia screening programs are expanding fastest here.
- Home Care:Direct-to-patient devices connect via cellular or Wi-Fi to telemedicine platforms. Pharmacy retail chains are creating bypass distribution pathways.
- Diagnostic Centers:Specialized facilities require high-throughput systems with centralized reading workflows. NMPA's AI validation requirements extend software-heavy registration timelines.
Hospitals command the dominant procurement volume; home care is climbing the fastest.
Technology:
Margin structures bifurcate between hardware-centric analog systems and software-heavy AI-embedded platforms with recurring algorithm licensing revenue.
- AI-Enhanced ECG:Real-time deep learning algorithms flag arrhythmias before specialist review. NMPA's 2023 guidance mandates clinical validation datasets reflecting China's demographic diversity, stratifying performance by age and region.
- Wireless ECG:Bluetooth and cellular-connected devices enable patient mobility. Diagnostic center workflows face delayed provincial reimbursement code adoption.
- Digital ECG:DSP-based signal processing with digital storage and transmission. Standard for mid-tier hospital procurement.
- Analog ECG:Legacy amplifier-based systems with thermal chart output. Concentrated in budget-constrained county facilities.
Digital ECG maintains installed base dominance; AI-Enhanced ECG shows steepest expansion trajectory.
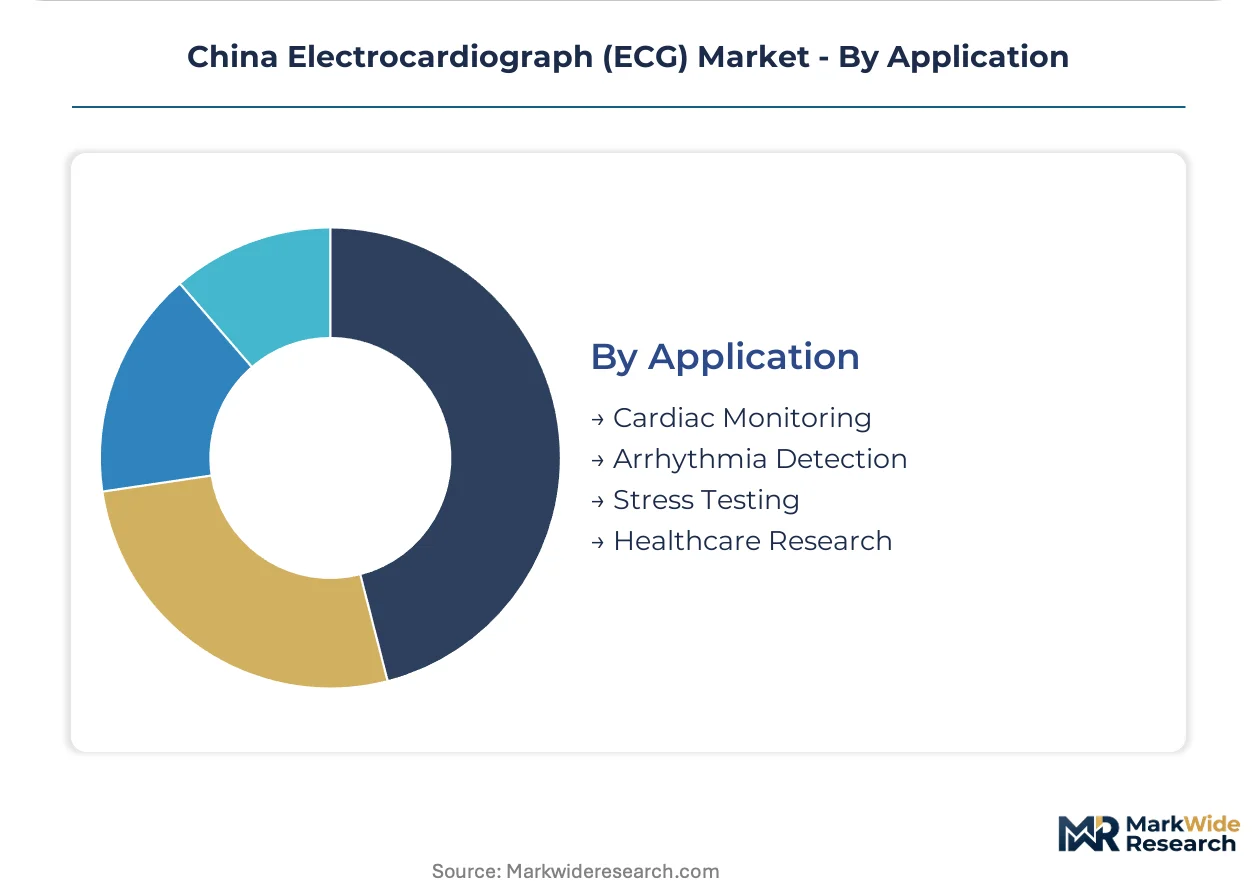
Application:
Reimbursement coding and clinical evidence requirements vary by diagnostic purpose, shaping manufacturer clinical trial investment priorities.
- Cardiac Monitoring:Continuous or episodic electrical activity surveillance for post-surgical and chronic heart failure patients. Tertiary hospital step-down units drive premium system demand.
- Arrhythmia Detection:Algorithmic identification of atrial fibrillation, ventricular tachycardia, and conduction abnormalities. Community screening networks in Guangdong are scaling fastest.
- Stress Testing:Exercise-induced ischemia evaluation via treadmill protocols. Cardiology department capital budgets concentrate this demand.
- Healthcare Research:High-fidelity signal acquisition for clinical trials and epidemiological studies. Academic medical centers anchor this niche.
Cardiac Monitoring represents the largest application segment; Arrhythmia Detection is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Provincial procurement consortia concentrate purchasing authority across county-level hospital networks. Tier-two municipal governments drive cardiovascular screening program expansion. Manufacturing clusters in Jiangsu and Zhejiang anchor electrode supply chains.
Beijing-Tianjin-Hebei
Tertiary hospital cardiology departments anchor demand for AI-enhanced diagnostic systems. NMPA's headquarters proximity accelerates regulatory consultation cycles for domestic manufacturers. Zhongguancun technology corridor hosts firmware engineering talent pools for embedded signal processing development.
Yangtze River Delta
Shanghai municipal health commissions pilot community-based arrhythmia detection networks at scale. GB 9706 medical electrical safety standards enforcement concentrates testing laboratory capacity here. Suzhou and Hangzhou manufacturing zones supply silver-silver chloride sensor components to device assemblers nationwide.
Pearl River Delta
Shenzhen's electronics manufacturing ecosystem controls cost structures for portable device production. Dual carbon goals from MEE push lower-power architecture adoption among local producers. Dongguan assembly plants handle contract manufacturing for domestic and export-bound ECG systems.
Sichuan-Chongqing
Rural hospital networks in Sichuan province expand ECG procurement quotas under Healthy China 2030 mandates. Provincial procurement consortia consolidate county-level purchasing through centralized tender platforms. Chengdu medical device industrial parks attract assembly operations seeking western China market access.
Shandong Peninsula
Village clinic deployment programs drive portable ECG device demand across prefecture-level networks. Local health commissions scale cardiovascular screening faster than tier-one saturation permits. Qingdao port infrastructure supports component import and finished device export logistics.
China Electrocardiograph (ECG) Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement authority. Domestic manufacturers leverage NMPA streamlined pathways against multinational installed-base advantages. Three archetypes dominate: integrated electronics conglomerates, medical device pure-plays, and diversified health technology groups. Competitive moves concentrate on backward integration into sensor production and AI algorithm licensing partnerships.
Among Beijing-based medical technology groups, Lepu Medical Technology (Beijing) Co., Ltd. exemplifies backward integration strategies through captive electrode manufacturing. Shenzhen Mindray Bio-Medical Electronics Co., Ltd. anchors the scale-driven tier with domestic manufacturing breadth across form factors. EDAN Instruments, Inc. occupies a position within the compact-system specialist archetype, with Shenzhen headquarters proximity to component supply clusters.
| Leading Market Players |
|---|
| Lepu Medical Technology (Beijing) Co., Ltd. |
| EDAN Instruments, Inc. |
| Shenzhen Mindray Bio-Medical Electronics Co., Ltd. |
| Nihon Kohden Corporation |
| Koninklijke Philips N.V. |
| SCHILLER |
| GE HealthCare |
| MicroPort Scientific Corporation |
| Fukuda Denshi |
| Others |
Pricing and Supply Chain Analysis
Jiangsu and Zhejiang manufacturing clusters anchor silver-silver chloride electrode production, concentrating input cost leverage among a handful of domestic suppliers and compressing margin buffers for device assemblers downstream.
Pricing Analysis
Cost-plus contracts with silver price indexation dominate raw material procurement for electrode-dependent device tiers. Three-tier pricing structure across premium, standard, and economy levels reflects NMPA certification grade and after-sales service bundling rather than hardware performance alone. Cost compression in economy-tier portable units is intensifying because provincial procurement consortia consolidate county-level purchasing authority. County hospital networks exhibit highest price sensitivity; tertiary cardiology departments accept premium positioning for AI-embedded diagnostic systems.
Supply Chain Analysis
Export-control regimes on advanced DSP and AI accelerator chips constrain component flows from US and Taiwanese suppliers into domestic manufacturing lines. Device assembly draws from South Korean memory modules, Japanese precision analog components, and local Shenzhen PCB fabrication. Single-source vulnerability concentrates in high-resolution ADC suppliers for diagnostic-grade systems. Distribution runs through provincial tender platforms for hospital procurement and pharmacy retail chains for home care channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Firmware engineers with medical signal processing expertise command 40-60% salary premiums, creating a persistent talent bottleneck that constrains domestic R&D scaling and favors players with captive technical pipelines.
For Market Incumbents: Pre-empt algorithm-embedded portable device commoditization by locking exclusive electrode supply contracts with Jiangsu manufacturers and accelerating NMPA Class II registration for AI-diagnostic software modules. Channel control through provincial tender platform relationships offers defensive leverage against emerging compact-system specialists. For New Entrants and Emerging Players: Build out telemedicine-integrated home care distribution through pharmacy retail chain partnerships, bypassing hospital procurement committee gatekeeping. Village clinic deployment programs under Healthy China 2030 represent the most penetrable geography; direct-to-patient cellular-connected devices with simplified interpretation aids offer the clearest go-to-market angle. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors medical device pure-plays with backward integration into sensor production and established NMPA regulatory navigation capabilities. Long-term viability rests on algorithm licensing revenue streams and wearable data pipeline monetization. Watch NMPA AI validation queue clearance rates as the inflection indicator for software-heavy submission viability.| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Class II Registration Acceleration | Compresses domestic innovation cycles from 18-24 months to 12-16 months for algorithm-embedded systems. |
| Backward Integration into Electrode Manufacturing | Captive silver-silver chloride sensor production insulates margin structures from Jiangsu-Zhejiang supply concentration. |
| Telemedicine Platform Partnership | Pharmacy retail chain distribution creates direct-to-patient pathways beyond hospital-centric procurement. |
| AI Algorithm Licensing Model | Recurring software revenue displaces transactional hardware margins in diagnostic-grade system portfolios. |
| Dual Carbon Compliance Certification | MEE-aligned lower-power architectures unlock preferential tender scoring in provincial procurement consortia. |
Research Methodology
A standing panel of hospital purchasing committee members, biomedical engineers, GPO contracts managers, and NMPA regulatory consultants provided ongoing calibration across primary interview cycles. Secondary validation drew from hospital procurement databases, GPO contract filings, NMPA device registration records, and provincial tender platform disclosures. Bottom-up device shipment modeling and top-down healthcare expenditure allocation were triangulated to cross-verify segment-level outputs.
Scenario-bracketing around NMPA approval timeline variations and provincial reimbursement code adoption rates bounded forecast uncertainty across the analysis window. Segmentation modeling incorporated product form factor, end-user setting, technology tier, and application purpose dimensions. CAGRs were derived from installed base replacement cycles and expansionary procurement under national cardiovascular screening mandates.
Stress conditions across silver price volatility, NMPA AI validation queue depth, and provincial procurement consolidation pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding Healthy China 2030 implementation continuity and tier-two city screening program scaling. Material shifts in NMPA software-as-medical-device guidance or MEE dual carbon enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Germanium-68/Gallium-68 Generators Market
Medical Devices
United States Organ Preservation Market
Medical Devices
North America Renal Denervation Devices Market
Medical Devices
Spinal Access Systems Market
Medical Devices
Global Tracheostomy Products Market
Medical Devices
Canada Ultrasound Devices Market
Medical Devices
Spherical IOL Market
Medical Devices
Global Bone Cement Market
Medical Devices
Indonesia Devices Market
Medical Devices
Wearable Breast Pumps Market
Medical Devices
Spain Contraceptive Devices Market
Medical Devices
Otorhinolaryngology Devices Market
Medical Devices
Mediastinoscope Market
Medical Devices
Arteriovenous Fistula Devices Market
Medical Devices
US Medical Device Manufacturers Market
Medical Devices
Digital Respiratory Devices Market