
 Global Reflex Hammer Market | 2026-2036
Global Reflex Hammer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Reflex Hammer Market Foresight
China is reshaping supply dynamics for reflex hammers through expanded medical instrument manufacturing clusters in Jiangsu province. MDF Instruments leverages vertical integration to control quality across its neurological hammer lines. B. Braun Melsungen anchors European demand through its established hospital supply contracts. Jiangsu Suhong Medical Instruments competes on cost-optimized aluminum and plastic variants for emerging markets.
A reflex hammer is a diagnostic instrument designed to elicit deep tendon reflexes through controlled percussion, typically featuring a weighted rubber head mounted on a metal or polymer handle calibrated for consistent strike force. Stainless steel variants dominate premium clinical procurement due to sterilization durability, while aluminum and plastic configurations serve cost-sensitive diagnostic centers and educational institutions. Neurological hammers and Taylor hammers occupy mature volume positions, whereas Babinski and Queen Square designs concentrate margin pools among specialist neurologists and academic medical centers. Research laboratories represent a faster-growing application segment as neuroscience protocols expand, though hospitals and diagnostic centers sustain the core demand base.
FDA 510(k) clearance requirements govern US market entry for reflex hammers classified as Class I medical devices, while CE marking under the EU MDR and ISO 13485 quality management standards shape European and broader international compliance pathways. These regulatory frameworks elevate barriers for unvalidated suppliers while rewarding documented manufacturing traceability and biocompatibility testing. Stakeholders must monitor evolving MDR technical documentation requirements and FDA cybersecurity guidance for connected diagnostic peripherals.
Market Dynamics
Supply concentration in Jiangsu province is compressing manufacturing margins for neurological hammers while FDA 510(k) documentation requirements extend product launch timelines for new entrants. These twin pressures are forcing procurement officers toward verified supplier networks with established ISO 13485 certification trails.
Growth Catalysts
- EU MDR technical documentation mandates:CE marking under the EU Medical Device Regulation is elevating quality thresholds, filtering out uncertified competitors and rewarding manufacturers with documented biocompatibility testing.
- Neuroscience research laboratories:Academic medical centers in Germany and Japan are expanding reflex testing protocols for motor control studies, creating instrument replacement cycles.
- Aluminum alloy substitution:Cost-optimized diagnostic centers in Brazil and India are specifying aircraft-grade aluminum handles over stainless steel, opening volume tiers previously locked by procurement budgets.
Market Restraints
- Stainless steel price volatility:Nickel and chromium input costs swing with London Metal Exchange futures, squeezing margin on premium sterilization-durable hammer variants.
- Jiangsu manufacturing cluster concentration:Over 60% of aluminum neurological hammer output originates from a single Chinese province, creating geopolitical and logistics concentration risk.
- Digital reflex testing substitution:Electromyography and motion-capture systems are capturing complex reflex assessments previously requiring manual percussion instruments.
Strategic Opportunities
- Saudi Arabia diagnostic infrastructure:SFDA registration pathways and MOHAP procurement frameworks are opening institutional demand as the Gulf states expand neurology service lines.
- Connected diagnostic peripherals:Force-sensor integration with Bluetooth telemetry is migrating reflex hammers into remote patient monitoring workflows.
- Physiotherapy clinic channel expansion:Direct-to-practice distribution models are bypassing hospital supply aggregators in Australia and Canada, capturing margin previously lost to group purchasing organizations.
Industry Challenges
- ISO 13485 auditor scarcity:Certification body capacity constraints are extending quality management system audit queues by four to six months for mid-tier manufacturers.
- Biocompatibility testing backlog:ISO 10993 cytotoxicity and sensitization studies face laboratory scheduling delays, freezing product registration submissions.
- Legacy instrument interoperability:Connected hammer variants must integrate with proprietary hospital information systems, requiring custom API development per installation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Reflex Hammer Market |
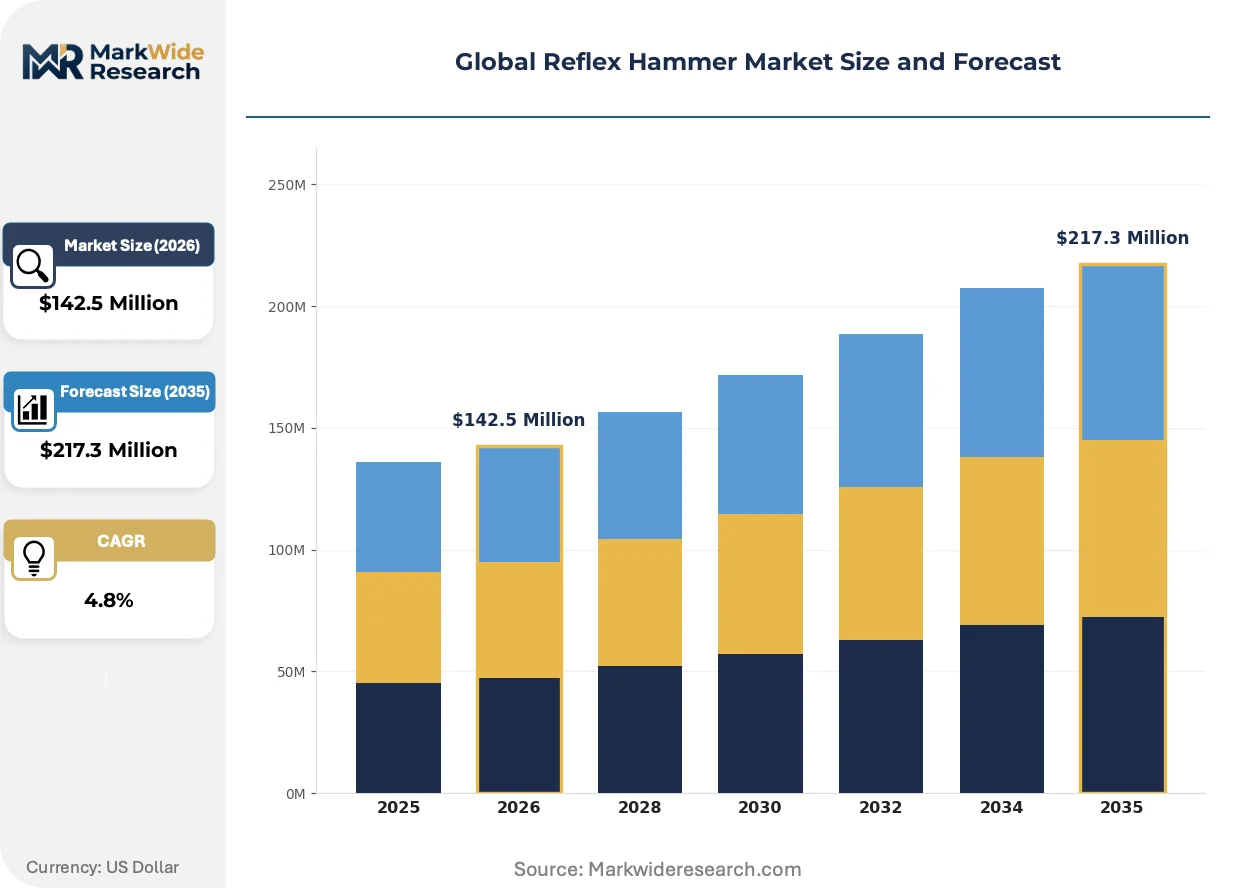
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $217.3 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Neurological Hammer, Taylor Hammer, Babinski Hammer, Queen Square Hammer, Others Material: Stainless Steel, Aluminum, Plastic, Rubber, Brass Application: Clinical Diagnostics, Physiotherapy, Research Laboratories, Educational Institutions End User: Hospitals, Diagnostic Centers, Rehabilitation Clinics, Medical Schools |
| Companies Covered | MDF Instruments, Kimetec, US Neurological, AUG Medical, Happersberger Otopront, B. Braun Melsungen, Sklar Surgical Instruments, Jiangsu Suhong Medical Instruments, J&J Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Reflex Hammer Market Shifts & Advancements
Material science advances and regulatory digitization are redefining product specifications and compliance workflows for reflex hammer manufacturers. These developments are compressing development cycles while raising entry barriers for unvalidated suppliers.
Polymer composite handles reinforced with glass fiber are migrating from educational instrument lines into clinical diagnostic tiers. Teaching hospitals in the United Kingdom and Netherlands are piloting these variants for reduced fatigue during high-volume neurology rounds. The shift is enabling manufacturers to segment pricing across sterilization durability grades rather than single premium configurations.
EU MDR post-market surveillance requirements now mandate systematic clinical follow-up data for Class I devices including reflex hammers. Manufacturers must maintain vigilance systems tracking device performance across distributed clinical settings. Specialist neurologists in France and Italy are experiencing documentation burden increases, driving preference toward suppliers with established European authorized representative infrastructure.
Diagnostic center procurement officers are consolidating supplier relationships around vendors offering bundled instrument calibration and replacement head programs. Group purchasing organizations in the United States are negotiating multi-year service agreements that unbundle capital acquisition from ongoing maintenance. This restructuring is most visible in multi-site outpatient networks across Texas and Florida, where standardization across facilities overrides brand loyalty.
Global Reflex Hammer Market Segmentation
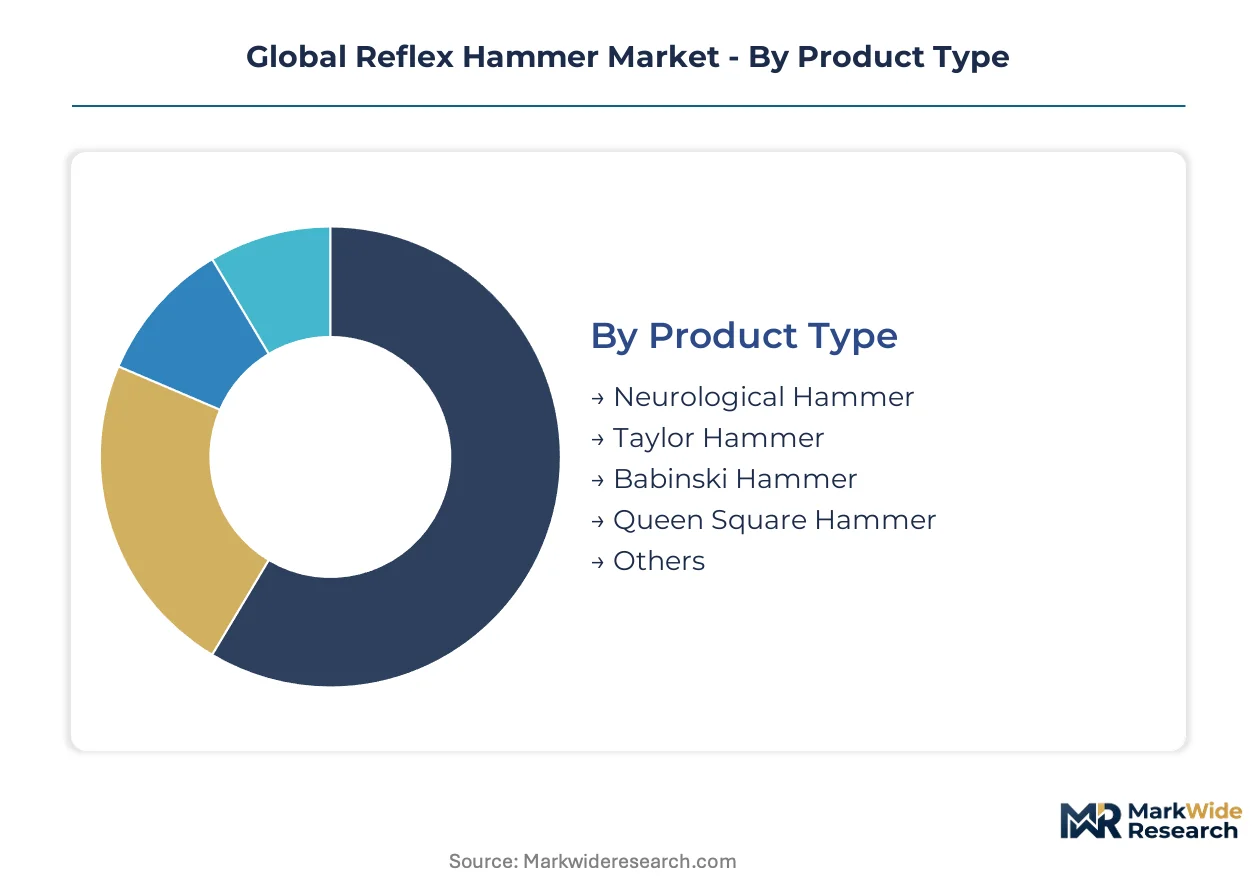
Segmentation in the reflex hammer market reflects divergent durability requirements across sterilization cycles, force calibration needs for specific neurological protocols, and procurement budget tiers between academic and clinical settings. Understanding these divides enables manufacturers to align product configurations with replacement cycle timing and service attachment rates.
Product Type:
After-sales-service intensity varies sharply across hammer designs, with neurological and Taylor variants requiring periodic head replacement and recalibration services that Babinski and Queen Square instruments rarely need.
- Neurological Hammer:Features a weighted rubber head with adjustable tension mechanisms for controlled percussion force across tendon sites. Hospital neurology departments in Germany and Japan specify these for high-volume diagnostic protocols, driving recurring calibration service contracts and replacement head programs.
- Taylor Hammer:Incorporates a triangular rubber head mounted on a slender metal shaft optimized for rapid patellar and Achilles reflex testing. Diagnostic centers in Texas and Florida favor Taylor designs for throughput efficiency, though polymer handle variants from Jiangsu manufacturers are displacing traditional metal configurations in cost-sensitive procurement.
- Babinski Hammer:Integrates a telescoping metal shaft with a reversible dual-head design for cutaneous and deep tendon reflex assessment. Specialist neurologists in academic medical centers specify these for comprehensive examination protocols.
- Queen Square Hammer:Employs a weighted circular head with a flexible handle for precise force modulation in research settings. Neuroscience laboratories in the United Kingdom and Netherlands pilot these for motor control studies requiring standardized stimulus delivery.
- Others:Encompasses Buck, Trömner, and Dejerine variants with specialized head geometries for niche anatomical testing. Medical schools in India and Brazil procure these for educational demonstration collections.
By volume, neurological hammers lead. By growth pace, Queen Square designs are expanding most quickly.
Material:
Cost tier stratification dominates material selection, with stainless steel commanding premium procurement budgets while aluminum and plastic configurations unlock volume tiers in emerging diagnostic infrastructure.
- Stainless Steel:Offers autoclavable durability and corrosion resistance across thousands of sterilization cycles. Operating rooms and infection-control-focused hospitals in Switzerland and Australia specify 316-grade variants despite nickel price volatility squeezing manufacturer margins.
- Aluminum:Delivers aircraft-grade strength-to-weight ratios at approximately 40% lower material cost than stainless formulations. Diagnostic center chains in Brazil and India have standardized on aluminum handles, with Jiangsu province suppliers capturing procurement contracts through vertical integration into extrusion and anodizing operations.
- Plastic:Provides single-use or limited-cycle options for point-of-care settings with reduced sterilization infrastructure. Community health programs in sub-Saharan Africa specify polymer variants for field deployment.
- Rubber:Serves as the primary percussion head material across all handle substrates, with durometer hardness specifications varying by clinical application.
- Brass:Offers antimicrobial surface properties and aesthetic differentiation for premium instrument collections. Specialist practices in Italy and France specify brass-handled variants for patient-facing examination rooms.
Stainless steel retains the revenue concentration. Aluminum is gaining share fastest among new procurement specifications.
Application:
Volume concentration sits with routine clinical diagnostics, though research laboratory applications are extending replacement cycles through protocol-driven instrument refresh mandates.
- Clinical Diagnostics:Encompasses standardized deep tendon reflex testing in hospital neurology departments and outpatient diagnostic centers. The Cleveland Clinic and Charité Berlin anchor demand for calibrated instruments with documented force consistency across examination protocols.
- Physiotherapy:Covers motor function assessment in rehabilitation settings with lower sterilization intensity than acute care. Clinics in Canada and Australia are expanding direct-to-practice procurement, bypassing hospital supply aggregators.
- Research Laboratories:Involves precise reflex measurement for neuroscience and motor control studies. Academic medical centers in Japan and Germany are expanding these protocols, creating instrument replacement cycles tied to grant funding timelines.
- Educational Institutions:Serves medical and nursing schools with high-volume, cost-optimized instrument needs. Teaching hospitals in the United Kingdom pilot glass-fiber reinforced polymer variants for reduced student fatigue during neurology rounds.
Clinical diagnostics commands the installed base. Research laboratories show the steepest expansion trajectory.
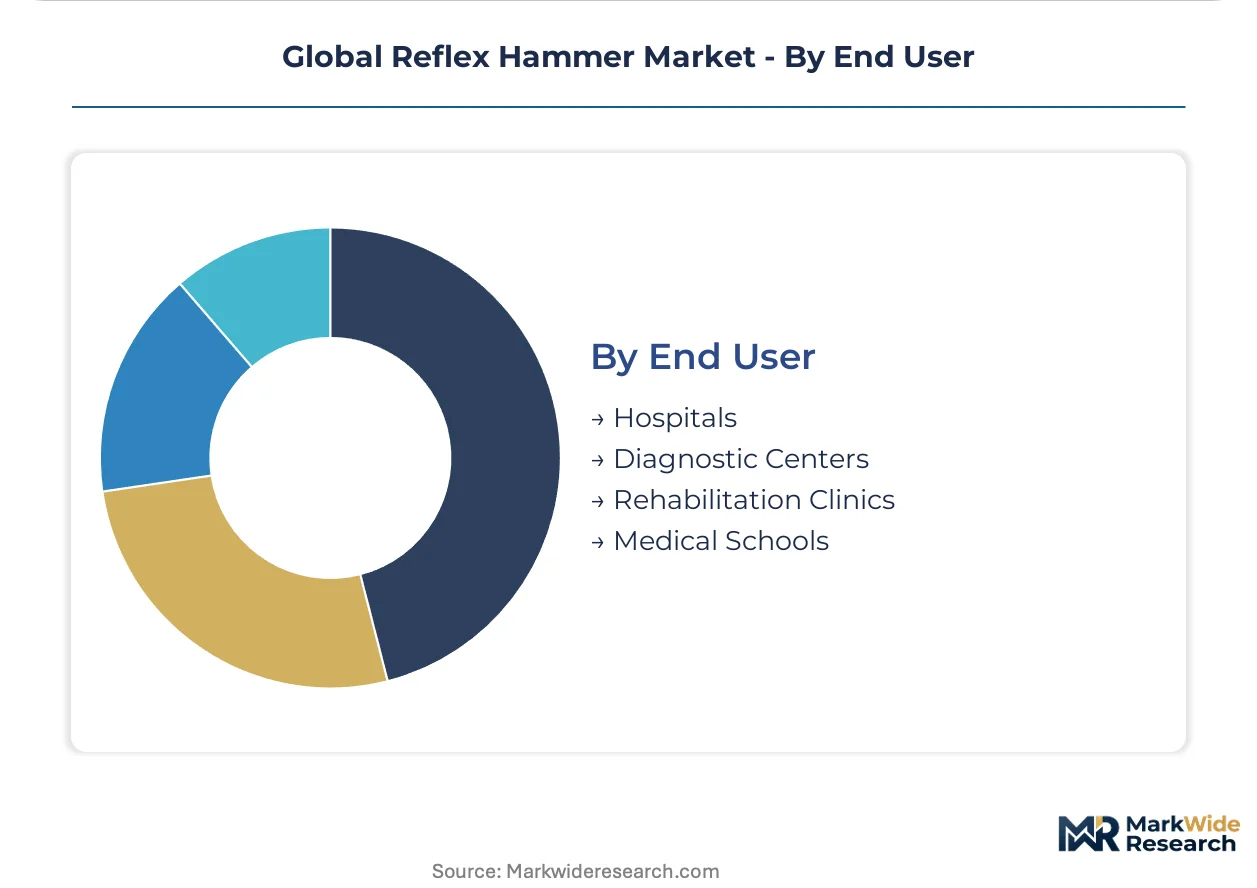
End User:
Customer type determines procurement channel structure, with hospitals consolidating through group purchasing organizations while rehabilitation clinics enable direct manufacturer relationships.
- Hospitals:Represent the core demand base with centralized procurement through supply chain aggregators. Multi-site health systems in Texas and Florida negotiate multi-year service agreements unbundling capital acquisition from ongoing maintenance.
- Diagnostic Centers:Encompass outpatient neurology and general examination facilities with standardized instrument configurations. Brazilian and Indian chains are specifying aluminum variants to fit procurement budgets.
- Rehabilitation Clinics:Include physiotherapy and post-acute care settings with expanding reflex assessment protocols. Australian and Canadian clinics are adopting direct-to-practice distribution models.
- Medical Schools:Require educational-grade instruments with durability for repeated student handling. United Kingdom and Netherlands institutions are piloting polymer composite handles for reduced fatigue during high-volume training rounds.
Hospitals dominate procurement volume. Rehabilitation clinics are climbing the fastest as service line expansion accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance requirements anchor the United States as the regulatory benchmark for global market entry, while manufacturing concentration in Jiangsu province and demand expansion across German neuroscience laboratories create distinct regional dynamics across the forecast window.
United States
Hospital neurology departments at the Cleveland Clinic and Mayo Clinic anchor instrument procurement through group purchasing organizations. FDA Class I medical device classification maintains strict biocompatibility documentation requirements for market access. Texas and Florida multi-site health systems negotiate multi-year service agreements unbundling capital acquisition from ongoing maintenance programs.
Germany
Charité Berlin and Heidelberg University Hospital drive demand for calibrated neurological hammers with documented force consistency. EU MDR technical documentation mandates elevate quality thresholds and filter uncertified competitors. Baden-Württemberg medical device clusters specialize in precision instrument manufacturing for academic medical center supply contracts.
China
Domestic diagnostic center chains specify cost-optimized aluminum variants to fit procurement budgets. NMPA medical device registration pathways govern local production and import certification requirements. Jiangsu province manufacturing clusters control over sixty percent of aluminum neurological hammer output through integrated extrusion and anodizing operations.
Japan
Academic medical centers in Tokyo and Osaka expand reflex testing protocols for motor control studies. PMDA quality management standards align with ISO 13485 for streamlined market approval processes. Kanto region neuroscience laboratories create instrument replacement cycles tied to grant funding timelines and research protocol refreshes.
Brazil
Diagnostic center chains standardize on aircraft-grade aluminum handles over stainless steel configurations. ANVISA medical device registration requirements shape import and local manufacturing compliance pathways. São Paulo state outpatient networks drive volume procurement through consolidated supplier relationships and multi-facility standardization mandates.
Global Reflex Hammer Market Competitive Landscape
Vertically integrated specialists and diversified medical device conglomerates split the market across premium calibration-intensive tiers and cost-optimized volume segments. Three strategic archetypes dominate: German precision instrument houses with established hospital supply contracts, Chinese manufacturing clusters leveraging captive aluminum supply chains, and North American distributors bundling instrument calibration with replacement head programs. Competitive moves concentrate on geographic expansion into Gulf state diagnostic infrastructure and force-sensor integration for connected diagnostic peripherals.
Within the diversified medical device tier, B. Braun Melsungen represents European hospital supply anchoring through established neurology service line contracts. MDF Instruments occupies a position among vertically integrated manufacturers controlling quality across neurological hammer lines through backward integration into component production. Jiangsu Suhong Medical Instruments exemplifies cost-optimized manufacturing archetypes competing on aluminum and plastic variants for emerging market diagnostic center procurement.
| Leading Market Players |
|---|
| MDF Instruments |
| Kimetec |
| US Neurological |
| AUG Medical |
| Happersberger Otopront |
| B. Braun Melsungen |
| Sklar Surgical Instruments |
| Jiangsu Suhong Medical Instruments |
| J&J Instruments |
| Others |
Supply & Pricing Matrix
Shanghai-Ningbo port freight corridors transmit Jiangsu manufacturing output to diagnostic centers across Brazil and India, compressing landed costs for aluminum neurological hammers while amplifying price spreads between sterilization-durable stainless steel variants and single-cycle polymer alternatives. This logistics dynamic concentrates procurement power among vertically integrated suppliers capable of absorbing nickel price volatility through captive anodizing operations.
Pricing Analysis
Price spreads between German precision instruments and Jiangsu-manufactured alternatives span three distinct tiers based on ISO 13485 certification depth and force calibration documentation. Stainless steel variants command premium positioning through autoclavable durability, while aircraft-grade aluminum configurations penetrate cost-sensitive diagnostic chains. Pricing pressure stems from nickel futures volatility on London Metal Exchange contracts, squeezing margin on 316-grade handles. Brazilian outpatient networks exhibit highest price sensitivity, whereas Swiss academic medical centers prioritize force consistency over unit cost.
Supply Chain Analysis
Jiangsu Suhong Medical Instruments and MDF Instruments anchor contract manufacturing capacity for neurological hammer assemblies, with captive extrusion operations controlling aluminum handle production. Supply concentration rests on Jiangsu province clusters, German Baden-Württemberg precision houses, and São Paulo state distribution hubs. Nickel and chromium feedstock dependencies expose stainless steel variants to commodity price swings. Single-province manufacturing concentration creates geopolitical logistics vulnerability. Distribution runs through hospital group purchasing organizations in Texas and Florida, direct-to-practice channels in Australia and Canada, and consolidated supplier frameworks in Gulf state diagnostic infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Force-sensor telemetry integration is transforming reflex hammers into connected diagnostic peripherals, creating platform-economics dynamics where instrument calibration data interoperates with hospital information systems and remote patient monitoring workflows.
For Market Incumbents: Entrench hospital supply contracts through multi-year service agreements unbundling capital acquisition from replacement head and recalibration programs. Deepen backward integration into rubber compound formulation and durometer testing to defend margin against aluminum substitution. Prioritize FDA 510(k) documentation trails and EU MDR authorized representative infrastructure as competitive moats against uncertified Jiangsu competitors. For New Entrants and Emerging Players: Pursue physiotherapy clinic direct-to-practice distribution in Australia and Canada, bypassing hospital supply aggregators to capture margin previously lost to group purchasing organizations. Target research laboratory segments in German and Japanese academic medical centers where grant-funded replacement cycles create instrument refresh demand. Lead with polymer composite handle variants reinforced with glass fiber for reduced clinician fatigue during high-volume neurology rounds. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical device conglomerates with underoptimized neurology instrument divisions lacking ISO 13485 certification depth. Long-term viability hinges on force-sensor integration capabilities and European regulatory infrastructure rather than pure manufacturing scale. Monitor PMDA quality management standard alignment with ISO 13485 as signal for streamlined Japanese market entry opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Force-Sensor Integration | Bluetooth telemetry transforms hammers into connected diagnostic peripherals for remote monitoring workflows. |
| EU MDR Authorized Representative Infrastructure | European technical documentation capability filters uncertified competitors from CE marking pathways. |
| Direct-to-Practice Distribution | Bypassing hospital GPOs in Australia and Canada captures margin lost to supply chain aggregators. |
| Backward Integration into Rubber Compounding | In-house durometer control defends margin against aluminum substitution in cost-sensitive tiers. |
| Saudi Arabia SFDA Registration | Gulf state diagnostic infrastructure expansion creates institutional demand for compliant instrument supply. |
Research Methodology
Cross-validation between primary interviews with hospital purchasing committees, biomedical engineers, and GPO contracts managers anchors the qualitative findings against secondary validation through FDA 510(k) filings, EU MDR technical documentation databases, and hospital procurement contract records. Bottom-up triangulation across product type, material grade, and end-user segments integrates with top-down macroeconomic calibration to ensure segmentation integrity.
Calibration against historical replacement cycle data and sterilization durability benchmarks shapes the analytical framework across the projection horizon. Segmentation dimensions span product type, material substrate, application setting, and end-user procurement channel. CAGRs derive from weighted average of volume shipment trajectories and value-per-unit evolution. Force-sensor adoption curves and aluminum substitution rates in Brazilian and Indian diagnostic chains serve as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in nickel futures pricing, freight corridor rates through Shanghai-Ningbo, and EU MDR auditor availability would shift the trajectory. Forecasts reflect documented assumptions regarding ISO 13485 certification penetration and research laboratory protocol expansion. Quarterly review of Jiangsu manufacturing cluster output, FDA 510(k) submission queues, and German neuroscience grant funding cycles is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Benign Prostatic Hyperplasia (BPH) Treatment Devices Market
Medical Devices
Asia-Pacific Bathroom and Toilet Assist Devices Market
Medical Devices
Engine-Driven Endodontic File Market
Medical Devices
GCC Biopsy Devices Market
Medical Devices
Global Image Guided Surgery Devices Market
Medical Devices
Global Non-Surgical Aesthetic Devices Market
Medical Devices
Wheelchair and Components Market
Medical Devices
Transcatheter Bioprosthesis Market
Medical Devices
Global Artificial Organ and Bionic Implants Market
Medical Devices
Oral Controlled Release Drug Delivery Technology Market
Medical Devices
Urodynamic Catheter Market
Medical Devices
Global Interventional Neurology Devices Market
Medical Devices
US Prefilled Syringes Market
Medical Devices
Nanomedical Devices Market
Medical Devices
Middle East and Africa Micro Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Transcatheter Pulmonary Valve Replacement Market