
 Anti-Snore Device Market | 2026-2036
Anti-Snore Device Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Snore Device Market Analytics
EU MDR biocompatibility requirements for oral appliances is shifting procurement standards across European sleep therapy channels. ResMed leverages integrated digital health ecosystems to sustain recurring revenue from connected airflow devices. SomnoMed anchors its position through specialized dental partnerships that control clinician training and fitting protocols. ProSomnus Sleep Technologies differentiates via precision-manufactured, 3D-printed oral devices that occupy the premium customization tier.
An anti-snore device is a mechanical or electromechanical apparatus designed to maintain patent upper airway patency during sleep, typically constructed from medical-grade polymers, silicone elastomers, or thermoplastic materials and engineered to deliver mandibular protrusion, nasal dilation, or positional feedback with pressure thresholds calibrated to individual airway anatomy. Its primary commercial purpose is to reduce pharyngeal collapse and associated nocturnal airway obstruction in patients diagnosed with primary snoring or mild-to-moderate obstructive sleep apnea. Mandibular advancement devices lead volume due to established reimbursement codes and dental fitting infrastructure, while smart sensor-enabled wearables represent the fastest-expanding margin pool as sleep data integration commands subscription pricing. Nasal devices remain mature with compressed margins, though portable continuous positive airway pressure units are gaining traction among travel-focused patient segments.
FDA 510(k) clearance processes govern device safety and efficacy claims in the United States, while EU MDR and CE marking requirements enforce clinical evidence standards for European market access. Japan's PMDA maintains distinct material testing protocols that extend registration timelines for foreign manufacturers. Stakeholders must monitor evolving home sleep test reimbursement policies and digital therapeutics classification decisions that will determine channel economics and competitive moats.
Market Dynamics
FDA tightening of 510(k) biocompatibility requirements for mandibular advancement devices is compressing supplier qualification timelines while simultaneously elevating material science capabilities as the decisive competitive filter.
Growth Catalysts
- Home Sleep Testing Reimbursement:CMS and private payers in the United States have expanded coverage for unattended polysomnography. This removes the diagnostic bottleneck that previously constrained device prescriptions.
- EU MDR Clinical Evidence Standards:Stricter biocompatibility documentation for oral appliances under the Medical Device Regulation is professionalizing procurement channels across German and French sleep therapy networks.
- 3D Printing Precision Manufacturing:Direct metal laser sintering and photopolymer vat polymerization now enable patient-specific mandibular advancement devices with sub-millimeter fitting tolerances.
Market Restraints
- Medical-Grade Silicone Volatility:Raw material supply for oral appliance elastomers concentrates among specialty chemical producers in Germany and Japan, exposing device manufacturers to input cost swings.
- PMDA Registration Timelines:Japan's Pharmaceuticals and Medical Devices Agency maintains extended material testing protocols that delay foreign manufacturer market entry by 18-24 months relative to FDA clearance.
- CPAP Device Substitution:Portable continuous positive airway pressure units are capturing travel-focused patient segments that oral appliance makers previously dominated.
Strategic Opportunities
- India Diagnostic Infrastructure:Sleep disorder awareness campaigns by the Indian Society of Sleep Medicine are creating first-mover advantages for mandibular advancement device training programs in Mumbai and Delhi.
- Digital Therapeutics Classification:FDA draft guidance on software-as-medical-device pathways creates regulatory clarity for sensor-enabled wearables with integrated sleep coaching subscriptions.
- Tele-Dentistry Distribution:Remote intraoral scanning and direct-to-patient shipping models are bypassing traditional dental office fitting bottlenecks in Australian and Canadian markets.
Industry Challenges
- Dental Sleep Medicine Training Scarcity:Qualified clinicians capable of mandibular advancement device fitting remain concentrated in major metropolitan clusters, limiting rural penetration.
- Cross-Border Data Compliance:GDPR in Europe and HIPAA in the United States impose conflicting requirements on cloud-based sleep data platforms serving international patient populations.
- Legacy Device Recall Liability:Historical oral appliances with now-banned phthalate plasticizers expose manufacturers to retrospective litigation and reputational damage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Snore Device Market |
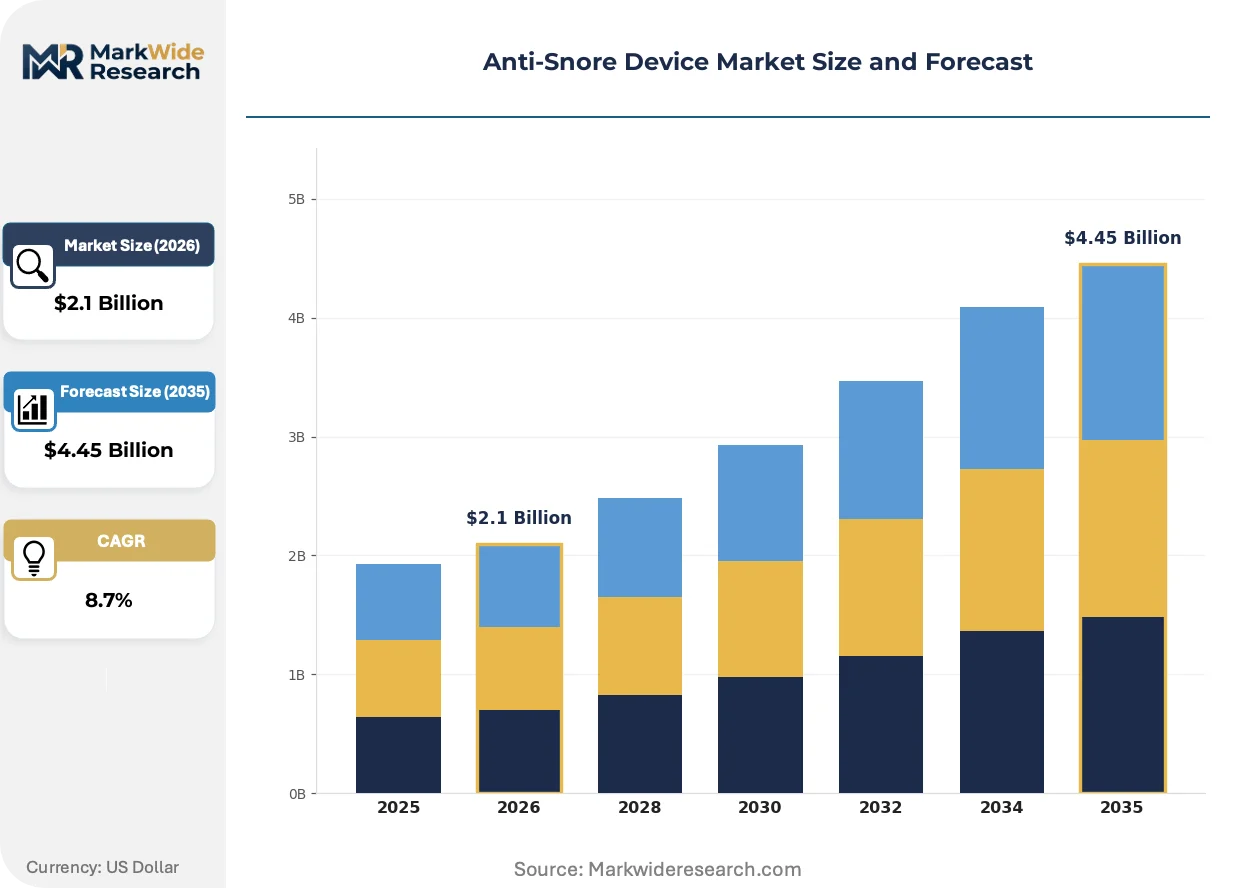
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Mandibular Advancement Devices, Nasal Devices, Continuous Positive Airway Pressure, Positioning Devices Technology: Vibration, Smart Sensors, Feedback Mechanisms, Adjustable Pressure Systems End User: Adults, Adolescents, Pediatric Patients, Seniors Distribution Channel: Retail Stores, Online Platforms, Hospitals, Specialty Clinics |
| Companies Covered | ResMed, SomnoMed, ProSomnus Sleep Technologies, Fisher & Paykel Healthcare Limited, Apnea Sciences Corporation, Tomed GmbH, GlaxoSmithKline plc, Airway Management, Sleeping Well LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Snore Device Market Evolving Landscape
Sensor miniaturization and machine learning inference at the edge are transforming passive mechanical devices into active airway management systems. The convergence of materials science, regulatory science, and behavioral economics is rewriting competitive boundaries.
Photopolymer vat polymerization with biocompatible resins certified to ISO 10993 standards is rewriting the economics of custom oral appliance production. Sleep clinics in the United States and Germany are adopting chairside intraoral scanning workflows that compress fitting from three visits to one. This compression is eliminating inventory-carrying distributors and transferring margin capture to precision-manufacturing device specialists.
EU MDR Annex I general safety and performance requirements now mandate clinical evidence for all Class IIa oral appliances, including legacy devices previously grandfathered under the Medical Device Directive. German notified bodies are rejecting substantial equivalence arguments for mandibular advancement devices without prospective patient cohort data. Manufacturers are responding by sponsoring registry studies through European sleep medicine societies to secure CE marking renewal.
Subscription pricing for connected airflow devices is displacing outright purchase models in United States home-care channels. Patients receive hardware at nominal cost while providers capture recurring revenue from sleep data analytics and remote monitoring services. This shift is most visible in Medicare Advantage plans seeking to reduce polysomnography facility utilization through longitudinal airway management.
Anti-Snore Device Market Segmentation
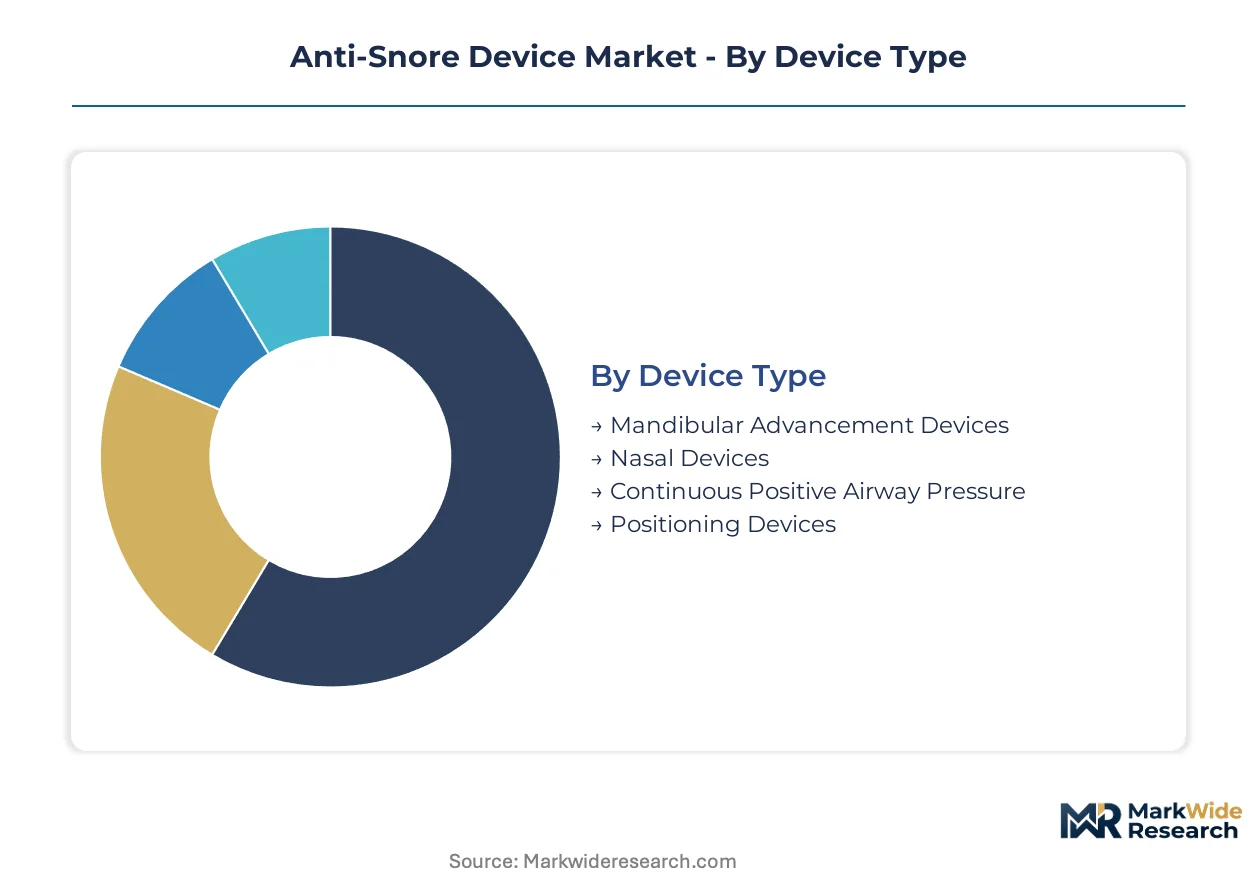
Segmentation in the anti-snore device market separates volume-driven mechanical appliances from premium digital health platforms. Device type and technology tiers determine reimbursement eligibility, manufacturing complexity, and margin capture potential.
Device Type:
Mandibular advancement devices dominate unit volume through established dental fitting infrastructure, while smart-enabled alternatives command subscription pricing premiums.
- Mandibular Advancement Devices:Thermoplastic or acrylic oral appliances mechanically protrude the mandible to maintain pharyngeal patency. Demand concentrates in United States sleep clinics and German dental sleep medicine networks where reimbursement codes and clinician training infrastructure are mature.
- Continuous Positive Airway Pressure:Portable airflow generators deliver calibrated positive pressure via nasal or oronasal interfaces. United States Medicare Advantage plans and Japanese home-care channels are expanding coverage for travel-focused miniaturized units, displacing oral appliance prescriptions in moderate-to-severe apnea cases.
- Nasal Devices:External dilators and internal stents constructed from medical-grade silicone elastomers mechanically expand the nasal valve. Retail pharmacy chains in Germany and over-the-counter channels in the United States carry standardized sizing inventories with compressed margins.
- Positioning Devices:Vibration-based wearables and positional trainers prevent supine sleep through haptic feedback. Australian direct-to-consumer platforms and Canadian tele-dentistry networks are piloting remote calibration protocols for these sensor-integrated systems.
Mature deployment sits with mandibular advancement devices. Newer deployment is concentrated in continuous positive airway pressure miniaturization and positional feedback systems.
Technology:
Technology tiers separate passive mechanical solutions from active, data-generating platforms that enable recurring revenue models.
- Smart Sensors:Miniaturized accelerometers, microphones, and pulse oximeters embedded in wearable form factors capture sleep architecture data. United States digital health startups and German medical device manufacturers are integrating these into subscription-based airway management platforms with FDA 510(k) and CE marking pathways.
- Adjustable Pressure Systems:Microprocessor-controlled pneumatic or mechanical actuators enable real-time titration of mandibular protrusion or airflow delivery. Japanese PMDA-registered devices and United States sleep clinic inventories emphasize precision calibration for individual airway anatomy.
- Vibration:Piezoelectric or eccentric rotating mass actuators deliver haptic stimuli to alter sleep position or suppress snoring amplitude. Direct-to-consumer manufacturers in Australia and retail distributors in Germany source these from standardized component suppliers with minimal regulatory burden.
- Feedback Mechanisms:Audio or tactile response systems conditioned on detected airway vibration patterns. Indian diagnostic infrastructure pilots and Canadian tele-dentistry platforms are evaluating these for remote patient monitoring integration.
Reimbursement eligibility favors adjustable pressure systems. Steepest expansion trajectory belongs to smart sensors with cloud analytics integration.
End User:
Demographic targeting determines device sizing protocols, regulatory classification, and marketing channel selection.
- Adults:Primary commercial segment encompassing working-age patients with primary snoring or mild-to-moderate obstructive sleep apnea. United States employer wellness programs and German statutory health insurance funds cover diagnostic and device costs for this cohort.
- Seniors:Patients over 65 with elevated comorbidity burden and polypharmacy considerations. Japanese long-term care insurance and United States Medicare Advantage plans are expanding home sleep testing and device coverage for this rapidly expanding demographic.
- Adolescents:Developing patients with craniofacial growth considerations requiring orthodontic-compatible designs. Specialized sleep medicine centers in Germany and pediatric dental networks in the United States maintain limited fitting capacity for this niche.
- Pediatric Patients:Children under 12 with congenital or acquired airway obstruction. Tertiary referral centers in the United States and academic medical centers in Germany handle these cases through multidisciplinary craniofacial teams with restricted device availability.
Prescription volume concentrates in adults. Fastest-growing addressable base is seniors with age-related pharyngeal collapse.
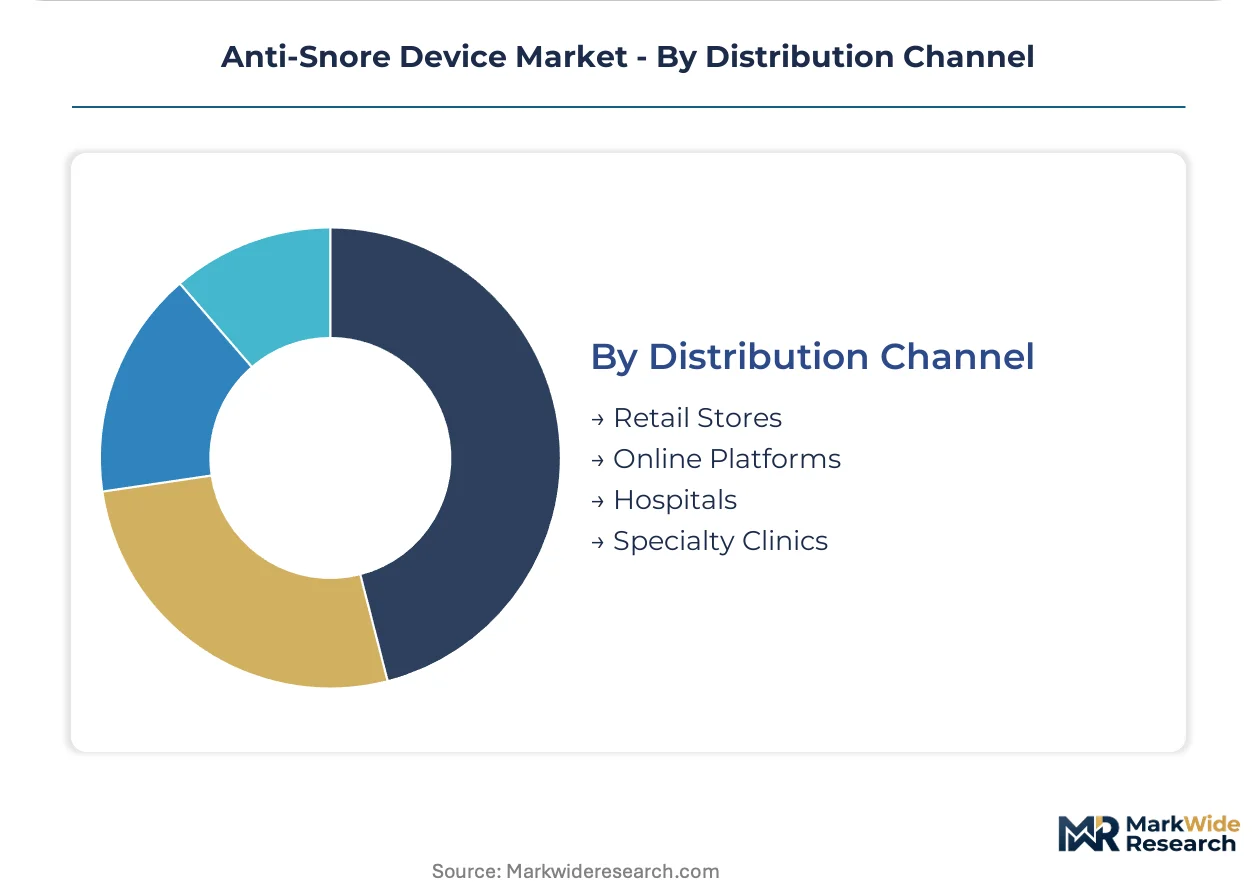
Distribution Channel:
Channel selection determines margin retention, patient education burden, and regulatory compliance obligations.
- Specialty Clinics:Dental sleep medicine practices and hospital-affiliated sleep centers with polysomnography capabilities. German sleep therapy networks and United States academic medical centers maintain exclusive fitting relationships with mandibular advancement device manufacturers.
- Online Platforms:Direct-to-consumer websites and tele-dentistry portals enabling remote intraoral scanning and home delivery. Australian and Canadian markets are expanding these channels to bypass traditional dental office bottlenecks.
- Hospitals:Inpatient and outpatient facilities with integrated sleep medicine departments. Japanese general hospitals and United States health systems are consolidating device procurement through group purchasing organizations.
- Retail Stores:Pharmacies, big-box retailers, and consumer health stores carrying over-the-counter nasal dilators and basic positioning aids. German pharmacy chains and United States drugstore networks stock standardized products with minimal fitting requirements.
Margin capture is strongest in specialty clinics. Channel expansion is accelerating through online platforms with remote diagnostic integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device production clusters in Germany and the United States while consumption concentrates in aging societies with established sleep medicine infrastructure. Manufacturing capabilities for precision-molded oral appliances and sensor-integrated systems concentrate in industrial regions with medical-grade polymer supply chains.
United States
Employer wellness programs and Medicare Advantage plans drive diagnostic volume for mandibular advancement devices. FDA 510(k) clearance pathways enforce biocompatibility documentation that elevates material science capabilities as a competitive filter. Sleep clinics in Boston and Minneapolis maintain exclusive fitting relationships with precision-manufacturing specialists.
Germany
Statutory health insurance funds cover dental sleep medicine procedures, creating stable reimbursement for oral appliance prescriptions. EU MDR Annex I clinical evidence requirements now mandate prospective patient cohort data for CE marking renewal. Notified bodies in Munich and Stuttgart are rejecting substantial equivalence arguments without registry study sponsorship.
Japan
Long-term care insurance expansion targets seniors with age-related pharyngeal collapse, the fastest-growing addressable demographic. PMDA material testing protocols extend registration timelines by 18-24 months relative to FDA clearance. Home-care channels in Osaka and Tokyo are consolidating procurement through regional medical device distributors.
Australia
Tele-dentistry platforms pilot remote intraoral scanning workflows that compress fitting from three visits to one. TGA registration requirements for software-as-medical-device pathways create regulatory clarity for sensor-enabled wearables. Direct-to-consumer channels in Sydney and Melbourne bypass traditional dental office bottlenecks through home delivery models.
India
Sleep disorder awareness campaigns by the Indian Society of Sleep Medicine create first-mover advantages for mandibular advancement device training programs. CDSCO medical device rules classify oral appliances as Class A or B based on duration of use, streamlining import registration. Diagnostic infrastructure investments in Mumbai and Delhi expand addressable patient bases beyond metropolitan clusters.
Anti-Snore Device Market Competitive Landscape
The competitive structure tilts toward precision-manufacturing specialists with dental network control and integrated digital health platforms with recurring revenue models. Consolidation pressures favor players with in-house production of medical-grade polymers and direct clinician training relationships. Three archetypes dominate: dental partnership specialists, connected device platforms, and precision-manufacturing boutiques. Competitive moves concentrate on strategic partnerships for distribution access and technology licensing for sensor integration.
Among dental partnership specialists, SomnoMed anchors clinician training and fitting protocol control. ResMed exemplifies the connected device platform archetype with integrated digital health ecosystems. ProSomnus Sleep Technologies occupies the precision-manufacturing boutique tier through 3D-printed oral devices with sub-millimeter fitting tolerances. These three players represent distinct competitive vectors rather than direct substitution threats.
| Leading Market Players |
|---|
| ResMed |
| SomnoMed |
| ProSomnus Sleep Technologies |
| Fisher & Paykel Healthcare Limited |
| Apnea Sciences Corporation |
| Tomed GmbH |
| GlaxoSmithKline plc |
| Airway Management |
| Sleeping Well LLC |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between FDA 510(k)-cleared mandibular advancement devices and unregulated over-the-counter nasal dilators manifests in both pricing power and supply chain configuration. Premium precision-manufactured oral appliances command three-to-five-fold unit economics over commodity nasal stents, reflecting biocompatible resin certification costs and dental fitting infrastructure requirements that reshape procurement channel economics.
Pricing Analysis
Cost-down pressure on standardized nasal devices accelerates because retail pharmacy chains in Germany and the United States are consolidating SKU portfolios toward private-label sourcing. Three-tier pricing structure across premium customization, standard thermoplastic, and economy nasal dilators separates patient-specific 3D-printed mandibular devices from mass-molded alternatives. Price differentiation traces to ISO 10993 biocompatibility certification tier and dental sleep medicine fitting protocol complexity. Subscription pricing for connected sensor platforms in United States Medicare Advantage plans exhibits lowest price sensitivity, while over-the-counter nasal dilator buyers in German pharmacy chains demonstrate highest elasticity.
Supply Chain Analysis
Medical-grade silicone elastomer supply rests on specialty chemical producers in Germany and Japan, exposing device manufacturers to input cost volatility. Photopolymer resin for vat polymerization draws from certified suppliers in the United States and Germany maintaining ISO 10993 documentation. Precision-machined titanium components for adjustable mandibular devices source from Swiss and Japanese metalworking clusters. Single-source vulnerability concentrates in biocompatible resin certification capacity, where notified body backlogs extend qualification timelines. Distribution runs through dental sleep medicine practices in the United States and Germany, with direct-to-consumer platforms in Australia and Canada bypassing traditional clinic inventory models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EU MDR Annex I clinical evidence requirements for Class IIa oral appliances create a barrier-to-entry moat for manufacturers with prospective registry study capabilities.
For Market Incumbents: Acquire dental sleep medicine training infrastructure to lock in clinician fitting protocol control. Portable CPAP miniaturization threatens oral appliance prescriptions in moderate-to-severe apnea segments; defend share by sponsoring chairside intraoral scanning workflows that compress patient visits from three to one. Backward integration into medical-grade polymer compounding secures supply continuity against German and Japanese specialty chemical volatility. For New Entrants and Emerging Players: The premium-to-economy price-point gap in mandibular advancement devices offers white-space capture for mid-tier precision-manufactured alternatives. Indian diagnostic infrastructure expansion in Mumbai and Delhi presents the most penetrable geography, with CDSCO Class A/B classification streamlining import registration. Tele-dentistry distribution with remote scanning and direct-to-patient shipping bypasses incumbent dental office relationships in Australian and Canadian markets. For Investors and Strategic Acquirers: Re-rating potential sits with precision-manufacturing boutiques given EU MDR registry study sponsorship requirements that professionalize procurement channels. Long-term viability across the analysis window favors players with in-house 3D printing workflows and direct clinician training relationships. Watch FDA draft guidance finalization on software-as-medical-device classification as the inflection signal for connected wearable platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Registry Study Sponsorship | CE marking renewal for Class IIa oral appliances now demands prospective patient cohort data from German notified bodies. |
| Chairside Intraoral Scanning Deployment | Compresses mandibular device fitting from three visits to one, eliminating distributor margin capture in United States sleep clinics. |
| Tele-Dentistry Platform Integration | Remote scanning and direct-to-patient shipping bypass traditional dental office bottlenecks in Australian markets. |
| Biocompatible Resin Backward Integration | In-house ISO 10993-certified photopolymer production insulates against German specialty chemical supply volatility. |
| Software-as-Medical-Device Pathway Navigation | FDA draft guidance clarity enables subscription pricing for sensor-enabled wearables with integrated sleep coaching. |
Research Methodology
Document review covered FDA 510(k) filings, EU MDR notified body guidance documents, and PMDA registration protocols, complemented by interviews with dental sleep medicine practitioners, biomedical engineers at precision-manufacturing facilities, and procurement managers at United States group purchasing organizations. Secondary validation drew from CMS reimbursement bulletins, German statutory health insurance fund coverage directives, and Japanese long-term care insurance expansion notices. Bottom-up demand modeling for mandibular advancement device prescriptions was cross-referenced against top-down sleep clinic capacity estimates across the analysis window.
Historical prescription volume trajectories were cross-referenced against panel input from sleep medicine society registry sponsors. The analytical framework segmented by device type, technology tier, end-user demographic, and distribution channel throughout the forecast period. CAGRs were derived from fitted growth curves calibrated to home sleep testing reimbursement expansion and diagnostic infrastructure investment patterns. Industry-specific inputs included dental sleep medicine training program graduation rates and EU MDR notified body processing backlogs.
Inputs from FDA 510(k) clearance databases and EU MDR notified body decision logs were available through the study window; gaps in real-time PMDA registration timeline data introduce uncertainty bands around Japanese market entry assumptions. Forecasts reflect documented regulatory pathway assumptions and reimbursement policy trajectories. Supply disruption in medical-grade silicone elastomers, abrupt shifts in CMS home sleep testing coverage, and EU MDR grandfathering deadline extensions warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Gastric Space-Occupying Devices Market
Medical Devices
Brazil Contraceptive Devices Market
Medical Devices
Global Radiofrequency Ablation Devices Market
Medical Devices
Medical Device Regulatory Affairs Market
Medical Devices
Global Digital Pathology Systems Market
Medical Devices
Fixed and Mobile C-Arms Market
Medical Devices
US Orthopedic Spine Navigation Systems Market
Medical Devices
Capsule Endoscope Systems Market
Medical Devices
Breast Pump Flange Market
Medical Devices
High Pressure Contrast Media Injectors Market
Medical Devices
France Spinal Surgery Devices Market
Medical Devices
Italy Medical Device Regulatory Affairs Market
Medical Devices
Medical Laser Cutting Device Market
Medical Devices
Intravascular Temperature Management Systems Market
Medical Devices
Americas Wearable Medical Device Market
Medical Devices
Brazil Artificial Organs and Bionic Implants Market