
 Esophagoscopes and Gastroscopes Market | 2026-2036
Esophagoscopes and Gastroscopes Market Size, Share, and Industry Trends Forecast 2026-2036
Esophagoscopes and Gastroscopes Market Analysis
Equipment leasing and managed service contracts are reconfiguring capital deployment across endoscopy suites, allowing mid-sized hospitals to access advanced visualization platforms without upfront purchase. Olympus Corporation leverages its installed base of processor units to sustain recurring revenue from proprietary consumables and accessories. Boston Scientific Corporation competes through single-use gastroscope portfolios that eliminate reprocessing liability for outpatient facilities. Fujifilm Holdings Corporation anchors its position with 4K and 3D imaging platforms that integrate with AI-assisted polyp detection software.
Esophagoscopes and gastroscopes are flexible or rigid tubular instruments equipped with fiber optic or digital imaging channels, designed for direct visualization, tissue sampling, and therapeutic intervention within the upper gastrointestinal tract. The devices incorporate working channels ranging from 2.0 to 3.7 millimeters to accommodate biopsy forceps, injection needles, and electrocautery accessories for polypectomy and hemostasis. Video endoscope systems with HD imaging and 3D visualization capabilities command the premium tier of the product landscape, while single-use devices represent the fastest-expanding segment as infection control protocols tighten. Diagnostic procedures generate the highest procedural volume, though therapeutic interventions carry superior reimbursement rates and drive margin concentration for manufacturers.
FDA 510(k) clearance requirements and EPA sterilant regulations govern device approval and reprocessing standards in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence thresholds for reusable endoscope systems marketed in Europe. Japan's PMDA maintains rigorous quality management system inspections that shape export competitiveness for manufacturers seeking access to Asian markets. Stakeholders must monitor how reimbursement policy shifts toward value-based care models influence capital allocation between reusable platforms and disposable alternatives.
Market Dynamics
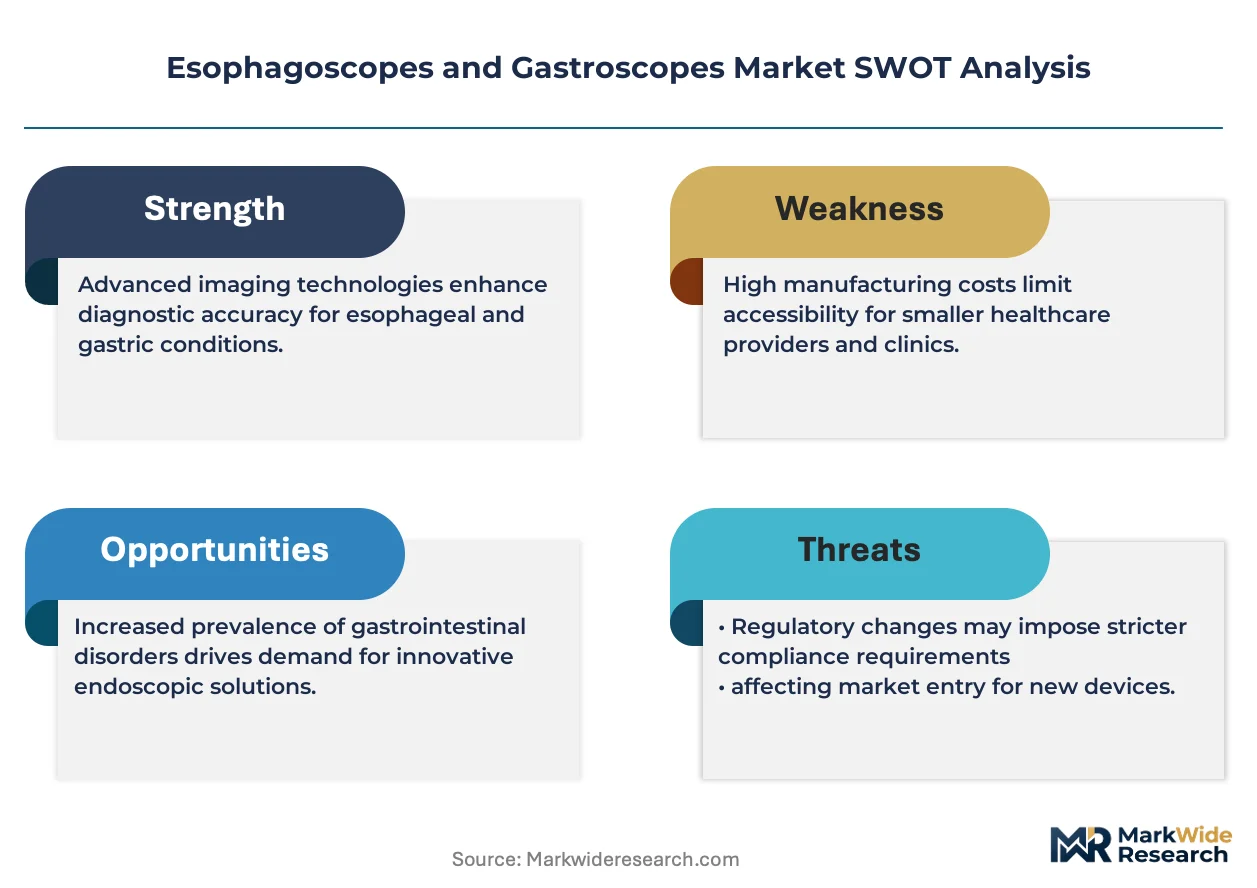
Single-use endoscope adoption is restructuring capital allocation across ambulatory surgical centers, compressing reprocessing infrastructure investments while elevating consumable purchasing power.
Growth Catalysts
- Reprocessing liability elimination:Outpatient facilities in the United States are abandoning sterilization workflows to avoid FDA enforcement actions on duodenoscope-related infections.
- AI-assisted polyp detection:Computer vision integration with 4K imaging platforms is expanding reimbursement eligibility for screening procedures.
- Ambulatory surgical center expansion:United States-based ASCs are adding endoscopy suites to capture same-day procedural volume from hospital outpatient departments.
Market Restraints
- Optical component supply concentration:CMOS sensor fabrication concentrates in East Asian foundries, exposing manufacturers to geopolitical trade friction.
- Capital intensity of visualization platforms:Processor unit upgrades require seven-figure commitments that strain mid-sized hospital capital budgets.
- EU MDR clinical evidence thresholds:Stricter documentation requirements for reusable endoscope systems are extending time-to-market for European launches.
Strategic Opportunities
- India's diagnostic infrastructure gap:Underpenetrated upper GI screening programs present white space for mobile endoscopy units.
- Subscription-based equipment access:Managed service contracts are displacing capital purchase models among United States community hospitals.
- Japan's aging proceduralist workforce:Remote mentoring platforms integrated with endoscope systems address skill transfer bottlenecks.
Industry Challenges
- Reprocessing technician certification backlog:Competency validation delays for high-level disinfection protocols are constraining reusable device throughput.
- Interoperability fragmentation:Proprietary video processor architectures complicate multi-vendor suite configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Esophagoscopes and Gastroscopes Market |
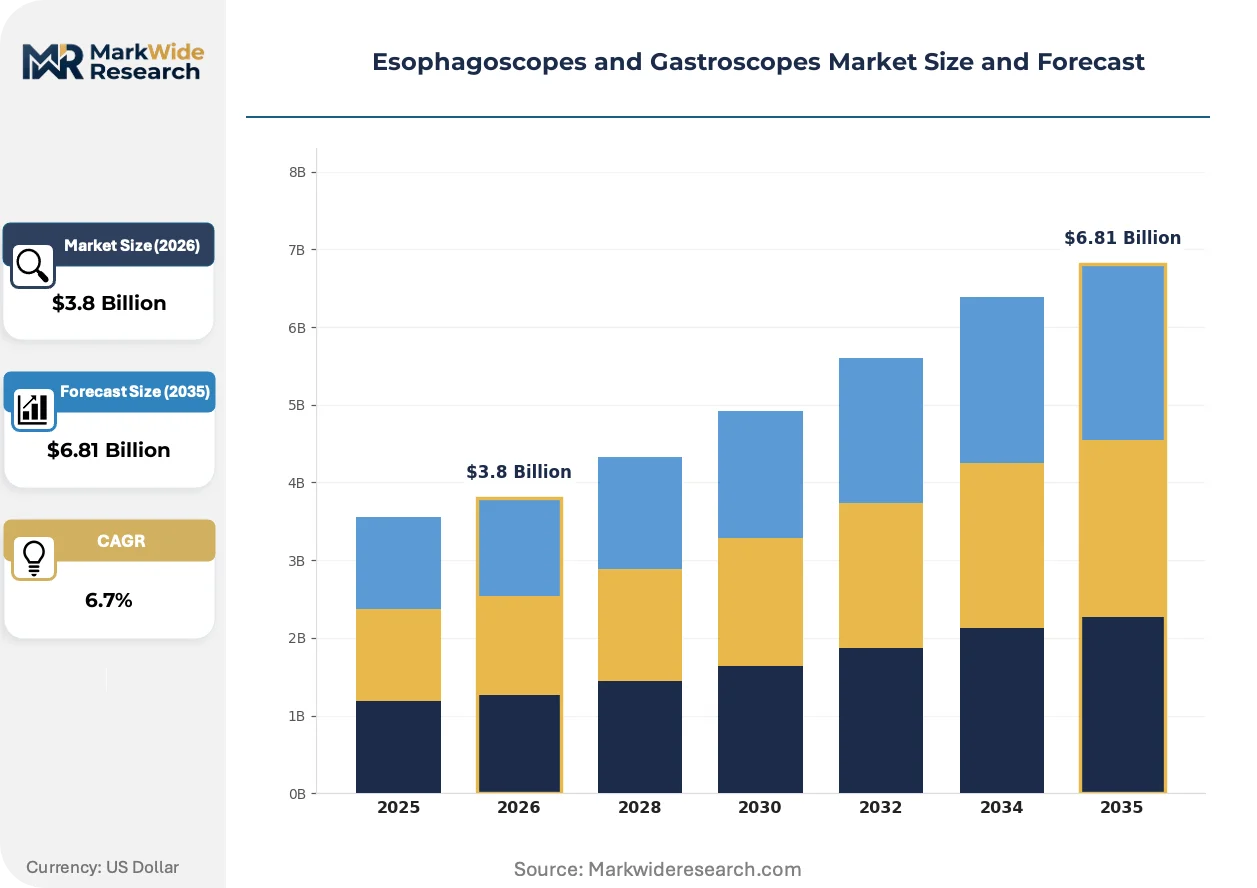
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Esophagoscope, Rigid Gastroscope, Video Endoscope, Single-Use Device End User: Hospitals, Clinics, Outpatient Centers, Diagnostic Labs Technology: HD Imaging, Fiber Optic, 3D Visualization, Robotic Assistance Application: Diagnostic Procedures, Therapeutic Interventions, Biopsies, Polypectomy |
| Companies Covered | Olympus Corporation, Boston Scientific Corporation, Fujifilm Holdings Corporation, Karl Storz SE & Co. KG, Pentax Medical, HOYA Corporation, Medtronic, Stryker, Johnson & Johnson Services, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Esophagoscopes and Gastroscopes Market Emerging Trajectories
Digital imaging architectures are displacing fiber optic transmission, compressing device form factors while expanding diagnostic fidelity across procedural settings.
CMOS sensor arrays with backside illumination are digitizing image capture at the distal tip, eliminating fiber bundle transmission losses. United States-based academic medical centers are piloting these platforms for chromoendoscopy applications. This transition is digitizing the supply chain for optical components, concentrating sourcing decisions among semiconductor foundries rather than glass fiber manufacturers.
The FDA's updated reprocessing guidance for flexible endoscopes is mandating enhanced surveillance cultures and quarantine protocols. Manufacturers of reusable devices face expanded liability exposure while single-use competitors capture outpatient migration. United States ASCs are responding by accelerating disposable gastroscope procurement, particularly for ERCP-adjacent procedures.
Hospital procurement departments are unbundling service contracts from capital equipment purchases, negotiating standalone maintenance agreements with third-party providers. Original equipment manufacturers face margin compression on aftermarket revenue as independent service organizations capture repair volume. This disintermediation is most visible in the United States, where group purchasing organizations are standardizing multi-vendor service level agreements.
Esophagoscopes and Gastroscopes Market Segmentation
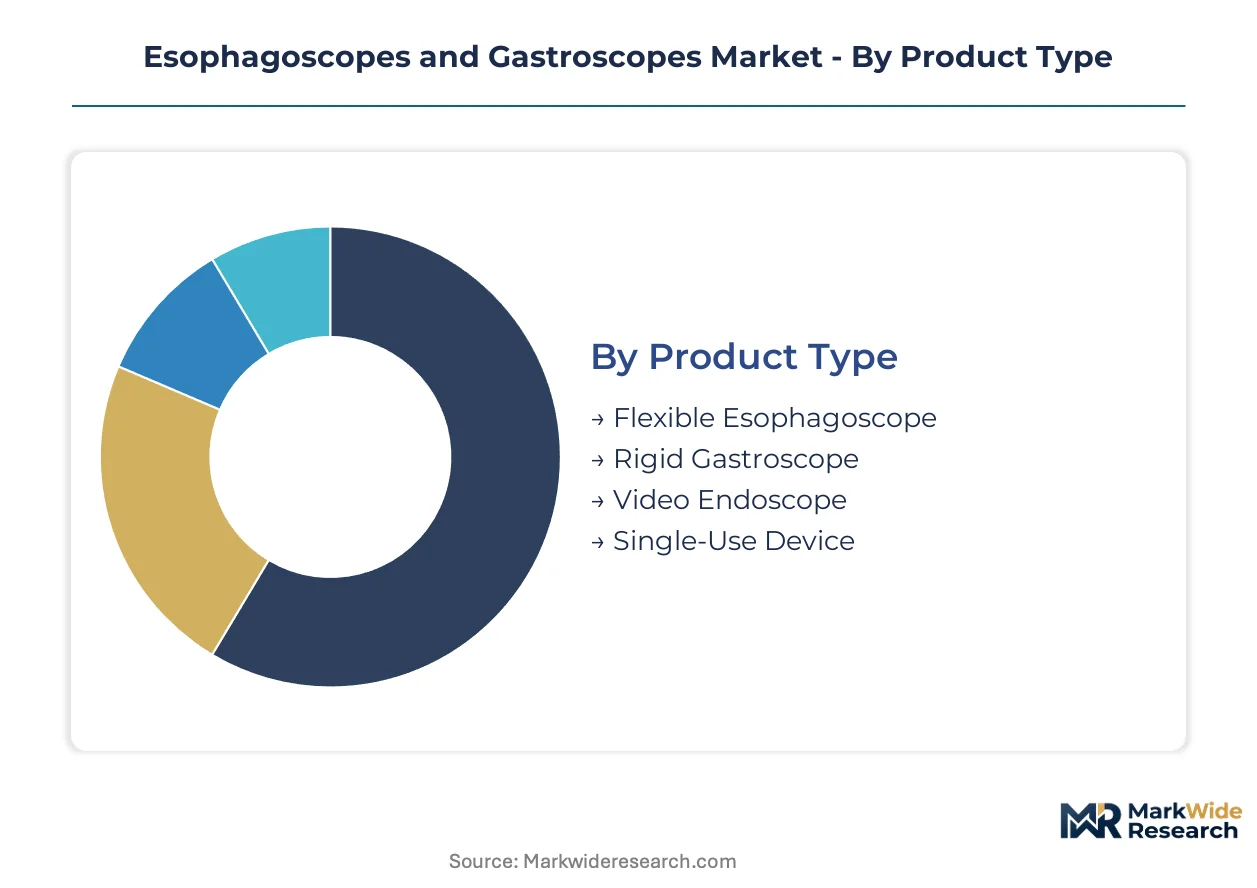
Product architecture and procedural setting define competitive positioning in upper GI endoscopy. Each segmentation dimension carries distinct margin profiles, regulatory exposure, and capital requirements that shape procurement decisions across care delivery sites.
Product Type:
Cost tier stratification separates capital-intensive reusable platforms from consumable-heavy single-use alternatives.
- Flexible Esophagoscope:Fiber optic or digital imaging channels navigate the esophageal lumen for diagnostic visualization and therapeutic access. Demand concentrates in United States hospital outpatient departments where screening volumes sustain high device utilization rates and reprocessing infrastructure investments.
- Single-Use Device:Sterile disposable instruments eliminate cross-contamination risk and reprocessing labor costs. Ambulatory surgical centers in the United States are expanding procurement of these devices to avoid FDA enforcement actions on flexible endoscope-related infections.
- Rigid Gastroscope:Stainless steel tubular construction for operative interventions requiring instrument stability.
- Video Endoscope:Integrated CMOS sensor arrays with processor-dependent image enhancement capabilities.
Video endoscopes command the established base. The steepest expansion runs through single-use devices.
End User:
Customer type determines capital deployment models and service contract structures across the care continuum.
- Hospitals:Integrated delivery networks with centralized sterile processing departments and dedicated endoscopy suites. United States academic medical centers are prioritizing 4K visualization platform upgrades to maintain referral capture for complex therapeutic procedures.
- Outpatient Centers:Freestanding ambulatory surgical centers with streamlined workflows and same-day discharge protocols. These facilities in the United States are abandoning reusable device programs to compress reprocessing infrastructure and labor costs.
- Clinics:Physician office laboratories with limited procedure volume and constrained capital budgets.
- Diagnostic Labs:Specialized pathology services with outsourced endoscopy partnerships.
Hospitals retain the procedural volume base. The steepest expansion runs through outpatient centers.
Technology:
Imaging fidelity and procedural assistance capabilities differentiate premium platforms from standard configurations.
- HD Imaging:1080p resolution standards with narrow band imaging enhancement for mucosal pattern recognition. United States community hospitals are standardizing on these platforms as baseline procurement specifications for new endoscopy suite construction.
- 3D Visualization:Stereoscopic depth perception for therapeutic interventions requiring spatial precision. Academic medical centers in the United States are piloting integration with AI-assisted polyp detection software to expand reimbursement eligibility for screening colonoscopy.
- Fiber Optic:Traditional glass bundle transmission with lower capital acquisition costs.
- Robotic Assistance:Motorized tip articulation and instrument stabilization for complex therapeutic access.
HD imaging anchors the installed base. The steepest expansion runs through 3D visualization.
Application:
Procedural intent separates high-volume screening workflows from high-margin therapeutic interventions.
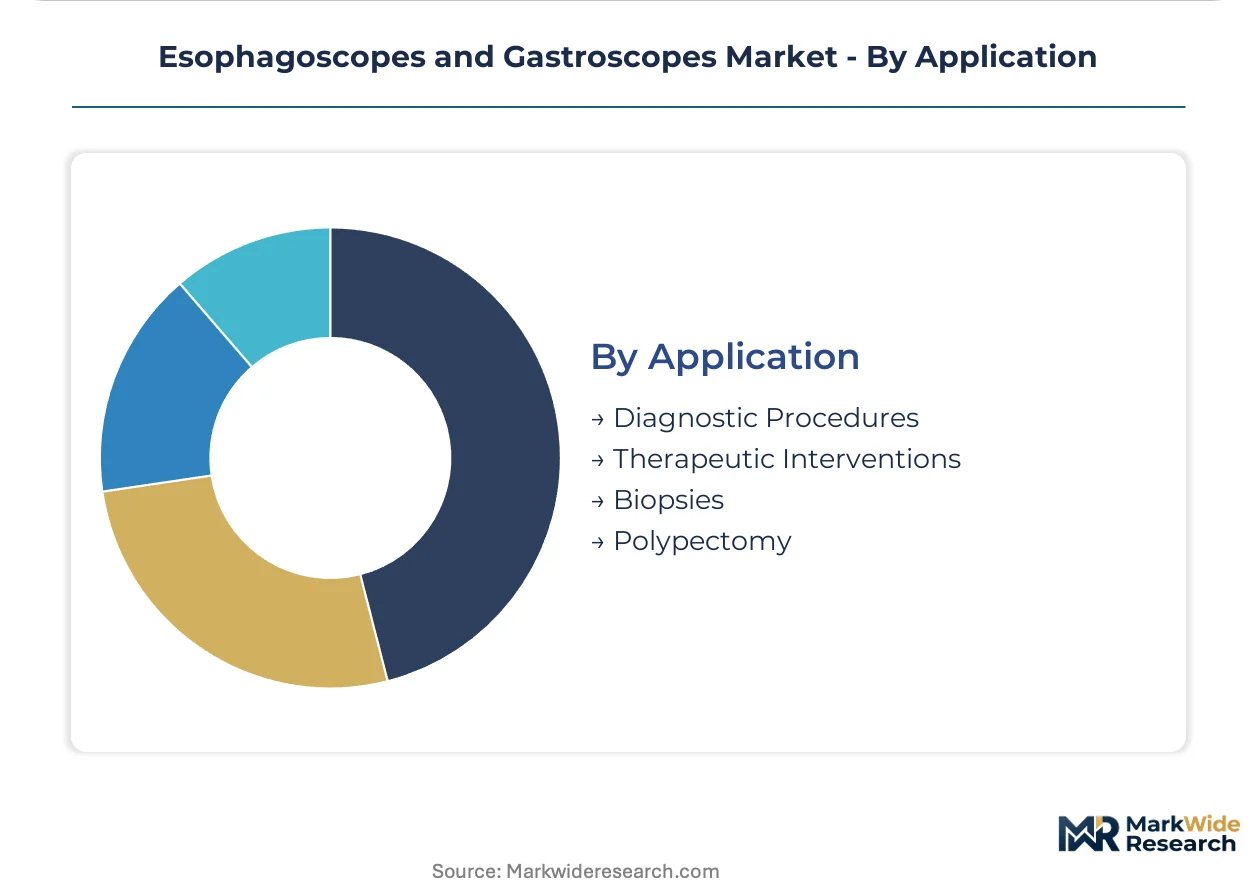
- Diagnostic Procedures:Screening esophagogastroduodenoscopy and surveillance examinations for Barrett's esophagus and gastric lesions. Medicare reimbursement policies in the United States sustain elevated procedural volumes for age-eligible screening populations.
- Therapeutic Interventions:Endoscopic mucosal resection, submucosal dissection, and stricture dilation with superior reimbursement rates. United States hospital outpatient departments concentrate these procedures to capture margin concentration from complex case mix.
- Biopsies:Tissue sampling for histopathological evaluation with standardized forceps instrumentation.
- Polypectomy:Endoscopic resection of gastric and esophageal polyps with electrocautery accessories.
Diagnostic procedures capture the volume base. The steepest expansion runs through therapeutic interventions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where Medicare reimbursement sustains premium visualization platform procurement, while cost-sensitive procurement in India compresses margins for standard-definition equipment.
United States
Ambulatory surgical centers are abandoning reprocessing infrastructure for single-use gastroscope procurement to avoid FDA enforcement actions on flexible endoscope-related infections. The FDA's updated reprocessing guidance mandates enhanced surveillance cultures and quarantine protocols for reusable devices. Cleveland Clinic and Mayo Clinic anchor academic medical center demand for 4K and 3D visualization platforms with AI-assisted polyp detection integration.
Germany
Hospital procurement departments are unbundling service contracts from capital equipment purchases to negotiate standalone maintenance agreements with third-party providers. The EU Medical Device Regulation imposes stricter clinical evidence thresholds for reusable endoscope systems marketed in Europe. Berlin and Munich host integrated delivery networks prioritizing processor unit upgrades for complex therapeutic procedure capture.
Japan
Aging proceduralist demographics are driving demand for remote mentoring platforms integrated with endoscope systems to address skill transfer bottlenecks. The PMDA maintains rigorous quality management system inspections that shape export competitiveness for manufacturers seeking Asian market access. Tokyo and Osaka medical device clusters concentrate CMOS sensor array development for distal tip digitization.
India
Underpenetrated upper GI screening programs present white space for mobile endoscopy units targeting tier-2 and tier-3 cities. The CDSCO regulates medical device imports while domestic PLI scheme incentives support local manufacturing scale-up. Maharashtra and Karnataka host diagnostic infrastructure expansion with hospital chains deploying leased visualization platforms to avoid capital intensity.
China
Domestic manufacturers are capturing share in standard-definition segments while import dependence persists for 4K and 3D visualization platforms. The NMPA governs device approval timelines and clinical trial requirements for novel imaging technologies. Shanghai and Beijing medical centers pilot AI-assisted polyp detection software integration with next-generation processor units.
Esophagoscopes and Gastroscopes Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in optical sensor and illumination module supply. Market structure consolidates around processor-dependent ecosystems where proprietary consumables lock in recurring revenue streams. Three archetypes dominate: diversified medical device conglomerates with endoscopy divisions, pure-play visualization platform specialists, and single-use disposable entrants. Competitive moves concentrate on M&A for AI software capabilities and strategic partnerships for semiconductor foundry access.
Among diversified medical device conglomerates, Olympus Corporation and Boston Scientific Corporation exemplify contrasting platform strategies. Olympus anchors the reusable system tier through installed base leverage and proprietary consumable ecosystems. Boston Scientific occupies the single-use disruptive position, eliminating reprocessing liability for outpatient migration. Fujifilm Holdings Corporation represents the imaging technology specialist archetype, with 4K and 3D platform integration anchoring premium tier positioning.
| Leading Market Players |
|---|
| Olympus Corporation |
| Boston Scientific Corporation |
| Fujifilm Holdings Corporation |
| Karl Storz SE & Co. KG |
| Pentax Medical |
| HOYA Corporation |
| Medtronic |
| Stryker |
| Johnson & Johnson Services, Inc. |
| Others |
Supply Flow & Price Mechanics
Undercapacity in CMOS sensor foundries across Taiwan and South Korea is compressing lead times for distal tip digitization components while simultaneously elevating procurement premiums for video endoscope manufacturers, forcing pricing discipline to split between premium visualization platforms and commoditized fiber optic alternatives.
Pricing Analysis
Customization-premium spreads separate configured-to-order 4K visualization platforms from standard-definition fiber optic bundles. The dominant pricing structure runs through tiered premium-standard-economy levels, with FDA 510(k) clearance tier and volume scale serving as the primary price differentiation drivers. Pricing pressure stems from ASC procurement committees negotiating subscription-based equipment access models that displace capital purchases. Outpatient centers exhibit the highest price sensitivity due to constrained capital budgets, while academic medical centers remain least sensitive given Medicare reimbursement capture for complex therapeutic procedures.
Supply Chain Analysis
Contract manufacturing concentrates among East Asian EMS providers specializing in medical device assembly and semiconductor foundries fabricating backside-illumination CMOS arrays. Geographic supply concentration centers on Taiwan, South Korea, and Japan for optical sensors, with Germany and the United States anchoring precision illumination module production. Raw material dependencies include rare-earth phosphors for LED light sources, specialized polymers for flexible insertion tubes, and high-purity glass for lens systems. Single-source vulnerability around CMOS wafer supply presents acute exposure to geopolitical trade friction. Distribution runs through manufacturer-direct sales forces serving integrated delivery networks, with group purchasing organizations consolidating procurement for mid-sized hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in upper GI endoscopy are shifting toward processor-dependent ecosystems where proprietary consumables lock in recurring revenue, with interoperability fragmentation between Olympus, Fujifilm, and Boston Scientific architectures forcing buyers into single-vendor commitments.
For Market Incumbents: Pre-empt single-use competitors by embedding AI-assisted polyp detection software directly into processor units, creating switching costs that outpatient centers cannot replicate with disposable alternatives. Acquire semiconductor packaging capabilities to secure CMOS sensor supply continuity against foundry allocation constraints. Vertical integration into distal tip manufacturing reduces exposure to East Asian contract manufacturer concentration. For New Entrants and Emerging Players: Establish a beachhead in India's mobile endoscopy unit segment where diagnostic infrastructure gaps and PLI scheme incentives create white space beyond entrenched multinational installed bases. Target tier-2 city hospital chains with leased visualization platforms that bypass capital intensity barriers. A software-first go-to-market angle—selling AI detection modules compatible with existing processor units—circumvents hardware ecosystem lock-in. For Investors and Strategic Acquirers: Capital is best deployed toward single-use disposable specialists with FDA 510(k) clearance momentum and ASC distribution relationships, as these assets capture the fastest-expanding segment without reprocessing liability exposure. Long-term viability hinges on reimbursement policy durability for screening procedures and semiconductor supply security. The signal to watch is CMS Medicare contractor LCD (local coverage determination) shifts toward value-based care models that disadvantage capital-intensive reusable platforms.| Strategic Initiative | Industry Significance |
|---|---|
| AI Software Companion Development | FDA-cleared polyp detection algorithms expand reimbursement eligibility for screening colonoscopy at academic medical centers. |
| Single-Use Portfolio Expansion | Disposable gastroscope procurement eliminates reprocessing liability exposure for ambulatory surgical centers facing FDA enforcement. |
| Semiconductor Foundry Partnership | CMOS sensor allocation agreements secure distal tip digitization supply against Taiwan Strait geopolitical friction. |
| Managed Service Contract Scaling | Subscription-based equipment access displaces capital purchase models among United States community hospitals. |
| Reimbursement Strategy Investment | CMS Medicare coverage pathway navigation sustains procedural volume for age-eligible screening populations. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with clinicians, hospital purchasing committee members, biomedical engineers, and GPO contracts managers; and secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement contract disclosures, and semiconductor foundry capacity reports. Bottom-up triangulation across product type, end user, technology, and application segments was cross-checked against top-down macroeconomic indicators and regulatory policy trajectories.
Forecast inputs incorporated procedural volume modeling across diagnostic and therapeutic application splits, capital expenditure cycles for visualization platform upgrades, and single-use device adoption curves in ambulatory settings. Segmentation dimensions included product architecture, customer type, imaging fidelity tier, and procedural intent. CAGRs were derived from elasticity-adjusted demand projections and supply-side capacity constraints across the analysis window, with specific weighting given to Medicare reimbursement policy durability and FDA reprocessing guidance evolution.
Stress conditions across semiconductor supply disruption, CMS reimbursement rate compression, and EU MDR clinical evidence threshold escalation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding procedural volume growth and technology substitution rates. Quarterly review of FDA enforcement action patterns, ASC construction permit filings, and foundry utilization rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Electronic Stethoscope Market
Medical Devices
Global Wheelchair Market
Medical Devices
Intrasaccular Embolization Systems Market
Medical Devices
Asia Pacific Veterinary Equipment and Disposables Market
Medical Devices
Cochlear Implant Systems Market
Medical Devices
Radiofrequency Skin Rejuvenation Devices Market
Medical Devices
Japan Electric Wheelchair Market
Medical Devices
Asia Pacific Reprocessed Medical Devices Market
Medical Devices
Acne Treatment Devices Market
Medical Devices
Slit Lamps Market
Medical Devices
Global Traumatic Brain Injury Assessment and Management Devices Market
Medical Devices
Lacrimal Dilator Market
Medical Devices
Interventional Oncology Devices Market
Medical Devices
Chest Drainage System Market
Medical Devices
Global Automated External Defibrillators Market
Medical Devices
Water Flosser Market