
 Urethral Bulking System Market | 2026-2036
Urethral Bulking System Market Size, Share, and Industry Trends Forecast 2026-2036
Urethral Bulking System Market Outlook
Silicone gel is consolidating its position as the preferred injectable material over traditional collagen-based formulations in urethral bulking systems, reducing per-procedure costs and extending product shelf life. Merz Aesthetics leverages its European manufacturing footprint to sustain supply continuity across specialist practices. Boston Scientific Corporation competes through its diversified urology portfolio, while Coloplast Corp anchors its position via deep channel control in Nordic hospital systems.
A urethral bulking system comprises injectable biomaterials—typically cross-linked dextranomer microspheres in hyaluronic acid carrier, polydimethylsiloxane elastomer, or glutaraldehyde cross-linked bovine collagen—delivered cystoscopically to augment urethral coaptation and restore continence in patients with intrinsic sphincter deficiency. Collagen-based products retain dominance in reimbursement-covered hospital settings despite declining unit growth, whereas silicone gel formulations capture margin pools in cash-pay ambulatory environments where durability claims command premium positioning. The therapy area segmentation reveals urology departments driving procedural volume, though gynecology practices represent the fastest-expanding channel as female pelvic medicine specialists integrate bulking into mixed incontinence protocols.
The FDA's 510(k) clearance pathway and the EU Medical Device Regulation (MDR) impose divergent clinical evidence requirements that fragment product launch sequencing between the United States and European markets. Health Canada's alignment with FDA predicate device standards accelerates cross-border approvals, while Japan's PMDA maintains distinct biocompatibility testing protocols that extend registration timelines for foreign manufacturers. Stakeholders must monitor reimbursement recalibrations for outpatient stress incontinence procedures as payors weigh bulking against mid-urethral sling cost-effectiveness data.
Market Dynamics
Silicone gel formulations are displacing collagen-based injectables as the dominant biomaterial in urethral bulking systems, compressing per-procedure costs while extending shelf stability and reshaping procurement patterns across ambulatory surgical networks.
Growth Catalysts
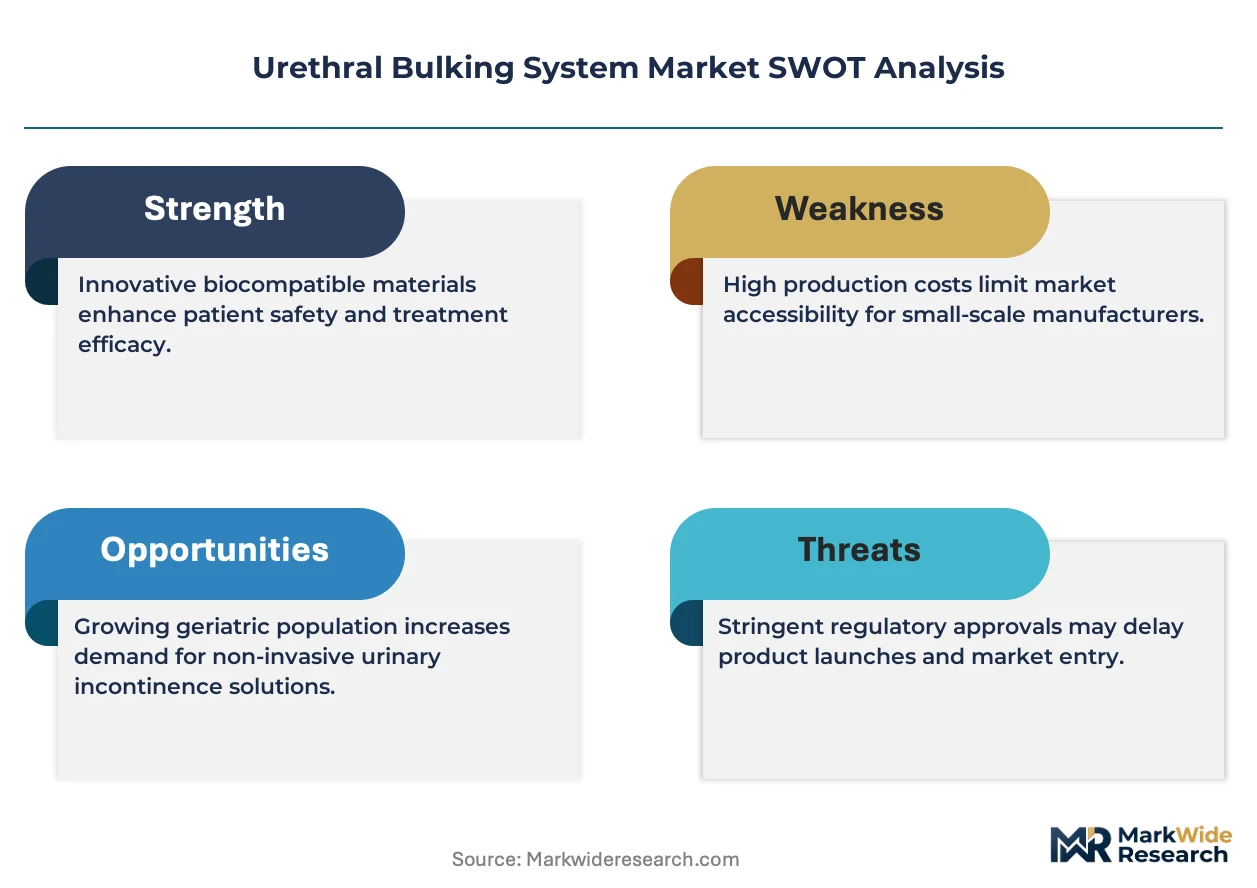
- Aging demographics:The United States, Germany, and Japan exhibit expanding populations over 65 years with stress urinary incontinence prevalence, driving procedural demand in outpatient urology clinics.
- EU MDR harmonization:The Medical Device Regulation's standardized clinical evidence requirements are streamlining cross-border product registrations and accelerating market access for compliant manufacturers.
- Minimally invasive protocols:Cystoscopic delivery techniques are reducing anesthesia requirements and recovery times, enabling same-day discharge protocols that expand addressable patient pools.
Market Restraints
- Biocompatibility testing costs:Japan's PMDA maintains distinct testing protocols that extend registration timelines and inflate pre-market expenditure for foreign manufacturers.
- Reimbursement uncertainty:US commercial payors and Medicare Advantage plans are recalibrating coverage criteria for outpatient stress incontinence procedures, creating revenue visibility gaps.
- Durability limitations:Injectable bulking agents require repeat interventions every 12-24 months, constraining lifetime value per patient relative to surgical alternatives.
Strategic Opportunities
- Gynecology practice integration:Female pelvic medicine specialists are incorporating bulking into mixed incontinence treatment protocols, opening procedural volume in previously underpenetrated channels.
- Health Canada alignment:The regulator's predicate device standards with FDA pathways enable accelerated cross-border approvals and reduced duplication costs.
- Hyaluronic acid carrier innovation:Cross-linked dextranomer microspheres in advanced carriers are enabling longer-lasting coaptation and premium positioning in cash-pay segments.
Industry Challenges
- Specialist training gaps:Cystoscopic injection technique requires urogynecology fellowship-level proficiency, limiting deployable physician pools and constraining procedural scaling.
- Legacy system integration:Electronic health record compatibility with procedure documentation templates varies across hospital networks, complicating quality tracking and reimbursement claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Urethral Bulking System Market |
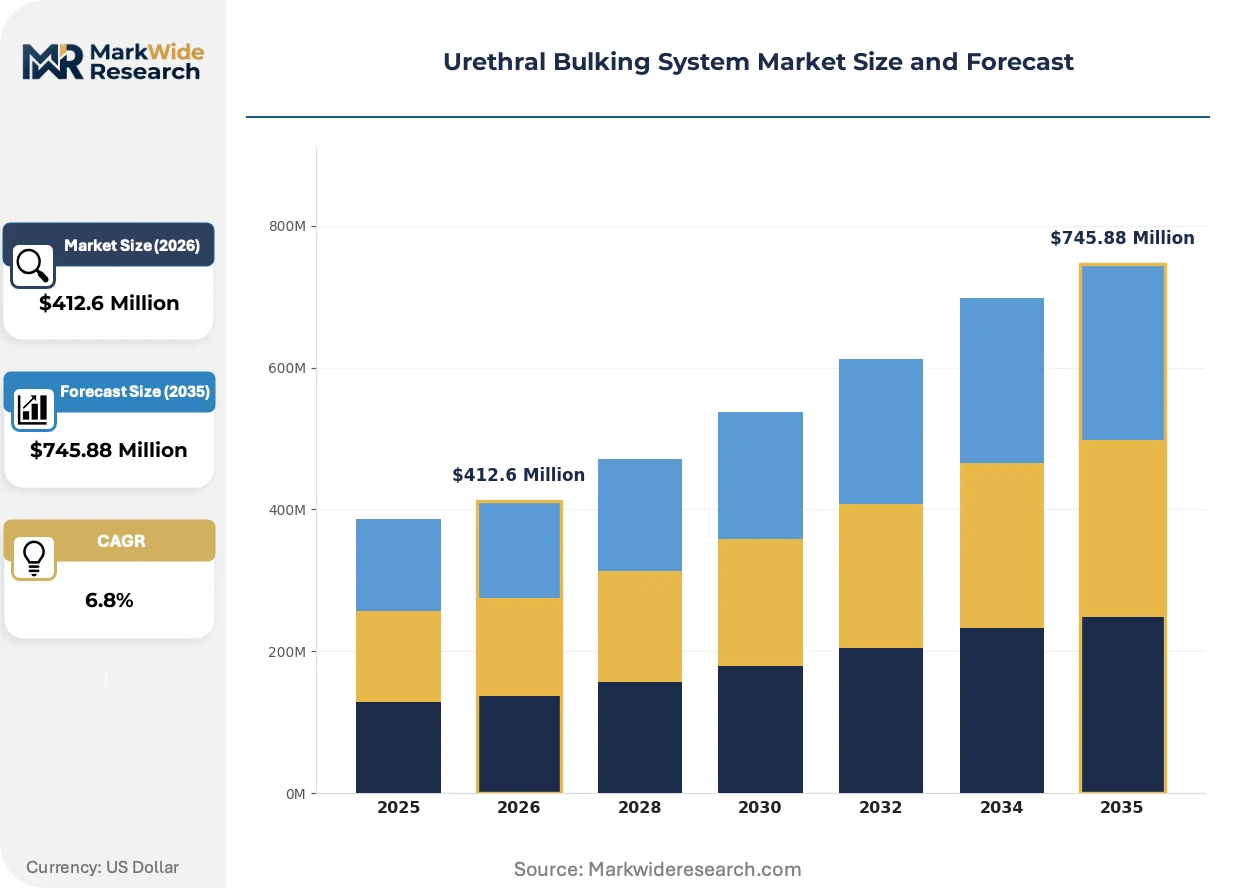
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Collagen-Based, Silicone Gel, Polyacrylate, Others Therapy Area: Urology, Gynecology, Urethral Dysfunction, Incontinence End User: Hospitals, Clinics, Ambulatory Surgical Centers, Specialist Practices Application: Surgical Procedure, Minimally Invasive Treatment, Diagnostic Purpose, Research Use |
| Companies Covered | Merz Aesthetics, Contura, Boston Scientific Corporation, ASCENTX MEDICAL, Laborie, CR Bard, Cogentix Medical, Q-Med, Coloplast Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Urethral Bulking System Market Strategic Shifts
Biomaterial science advances and regulatory pathway refinements are compressing product development cycles while shifting competitive advantage toward manufacturing scale and clinical data depth.
Silicone gel is consolidating its position as the preferred injectable material in urethral bulking systems. Ambulatory surgical centers are adopting this formulation at accelerating rates due to extended shelf life and reduced cold-chain requirements. The technology is consolidating margin pools away from collagen-based products by enabling premium pricing in cash-pay environments where durability claims command patient preference.
The FDA's evolving 510(k) clearance guidance is tightening safety documentation requirements for injectable bulking agents. Manufacturers must now submit expanded biocompatibility profiles and longer-term follow-up data, elevating barriers to entry. Hospital systems in the United States are responding by consolidating supplier relationships toward established players with predicate device histories and robust clinical libraries.
After-sales service unbundling is reshaping procurement relationships between manufacturers and ambulatory surgical centers. Facilities are negotiating device-only contracts and sourcing procedure support independently, compressing vendor margins. This pattern is most visible in Germany's specialist practice networks, where purchasing cooperatives are aggregating volume and disintermediating traditional distribution channels.
Urethral Bulking System Market Segmentation
Segmentation in urethral bulking systems reveals how biomaterial selection, clinical setting, and procedural approach determine procurement patterns and margin capture. Manufacturers configure product portfolios around these divides to optimize reimbursement pathways and channel economics.
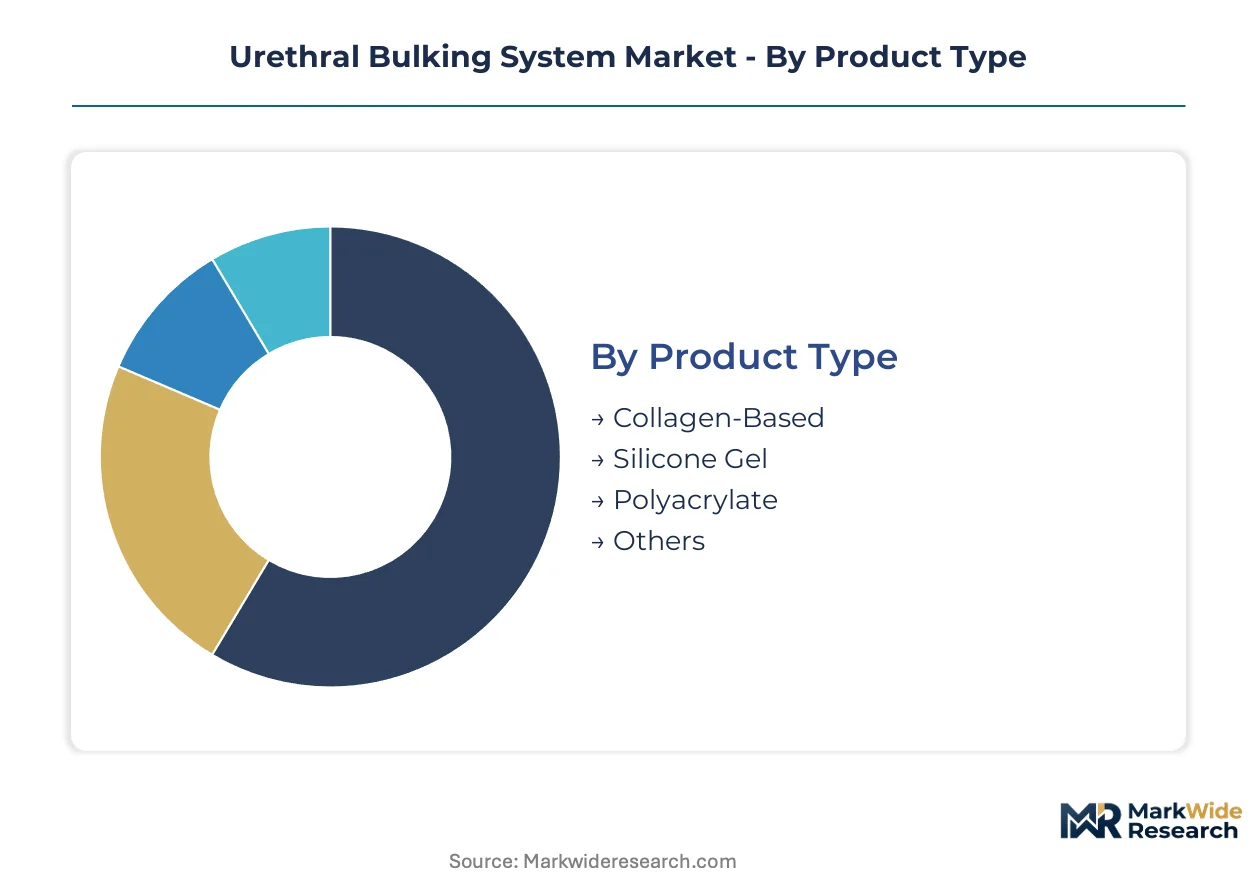
Product Type:
Standalone injectable formulations dominate hospital procurement, while combination systems with delivery devices embed deeper into ambulatory workflows.
- Collagen-Based:Glutaraldehyde cross-linked bovine collagen formulations maintain entrenched positions in Medicare-reimbursed hospital settings despite requiring cold-chain logistics and shorter shelf stability. Demand concentrates in US academic medical centers where predicate device histories simplify purchasing committee approvals.
- Silicone Gel:Polydimethylsiloxane elastomer systems eliminate refrigeration requirements and extend shelf life to 36 months, enabling premium positioning in German and Japanese cash-pay ambulatory networks where durability claims support out-of-pocket pricing.
- Polyacrylate:Synthetic polymer microspheres in stabilized carriers offer intermediate biocompatibility profiles for cost-sensitive European clinics navigating EU MDR documentation burdens.
- Others:Cross-linked dextranomer-hyaluronic acid composites and experimental biodegradable scaffolds occupy niche research and compassionate-use channels.
Volume placements concentrate in collagen-based formulations; the faster expansion belongs to silicone gel.
Therapy Area:
Cost-tier stratification separates high-reimbursement surgical indications from diagnostic and maintenance applications with compressed margins.
- Urology:Male and female urology departments drive procedural volume through established cystoscopic infrastructure and fellowship-trained specialist density in US metropolitan hospital systems.
- Gynecology:Female pelvic medicine specialists integrate bulking into mixed incontinence protocols, expanding fastest among therapy areas as gynecology practices acquire cystoscopy capabilities and direct-to-consumer marketing raises patient awareness.
- Urethral Dysfunction:Post-radiation and post-surgical sphincter deficiency cases command premium pricing in tertiary referral centers with reconstructive urology expertise.
- Incontinence:Primary stress urinary incontinence without complicating factors represents the largest addressable population but faces reimbursement pressure from mid-urethral sling cost-comparison studies.
Procedure economics favor urology for current revenue; gynecology is climbing the fastest as channel access broadens.
End User:
Customer-type fragmentation creates distinct procurement rhythms between capital-intensive hospital systems and agile ambulatory operators.
- Hospitals:Integrated delivery networks in the United States leverage volume commitments to extract device-only pricing and unbundle technical support, compressing vendor margins while demanding comprehensive liability coverage.
- Clinics:Independent urology and gynecology clinics in Germany's purchasing cooperatives aggregate procurement power and disintermediate traditional distribution, accelerating same-day procedure throughput.
- Ambulatory Surgical Centers:US Medicare-certified ASCs optimize case mix toward same-day discharge protocols, favoring silicone gel formulations with minimal inventory management overhead.
- Specialist Practices:Nordic hospital-affiliated specialist practices maintain deep channel relationships with Coloplast and Merz through exclusive supply agreements and embedded clinical training.
Hospital systems anchor current volume; ambulatory surgical centers are gaining share fastest as site-of-service migration accelerates.
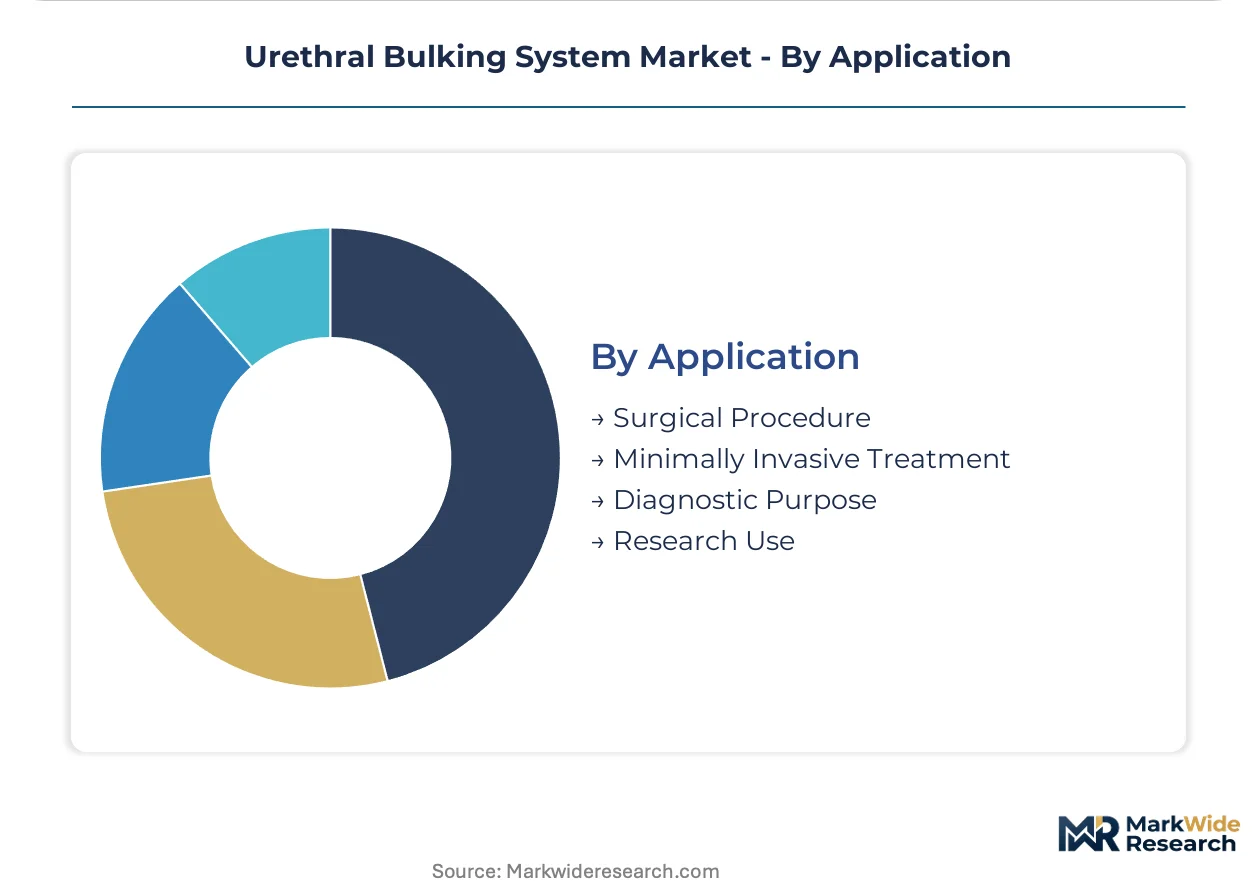
Application:
Maturity-stage differentiation separates established therapeutic indications from emerging diagnostic and research channels with unproven commercial models.
- Surgical Procedure:Open and laparoscopic adjunctive bulking during concomitant pelvic surgery maintains steady utilization in Japanese tertiary centers with consolidated urogynecology departments.
- Minimally Invasive Treatment:Cystoscopic injection under local anesthesia enables office-based protocols that expand addressable patient pools beyond surgical candidates, driving fastest growth across all application segments.
- Diagnostic Purpose:Temporary bulking as a predictive test for surgical candidacy occupies limited niches in academic research protocols without established reimbursement.
- Research Use:Investigational device exemptions and compassionate-use pathways support biomaterial innovation pipelines, particularly for next-generation biodegradable scaffolds.
Established surgical applications dominate current placements; minimally invasive treatment shows the steepest expansion trajectory as office-based protocols proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Research Triangle Park in North Carolina concentrates US urology device development through tax-advantaged R&D facilities. Similar biomedical zones in Germany, Japan, and Switzerland anchor European and Asian market expansion through specialized manufacturing infrastructure and regulatory fast-tracks.
United States
Medicare Advantage plans in Florida and Arizona drive ambulatory surgical center volume for stress incontinence procedures among retiree populations. The FDA's 510(k) clearance pathway requires expanded biocompatibility documentation that extends registration timelines for new entrants. Minneapolis and Boston hospital networks consolidate purchasing power through integrated delivery network contracts that favor established predicate devices.
Germany
Purchasing cooperatives in Bavaria and Baden-Württemberg aggregate demand from independent urology clinics seeking device-only procurement terms. The EU MDR harmonizes clinical evidence standards across member states while elevating documentation burdens for foreign manufacturers. Stuttgart's specialist practice networks disintermediate traditional distribution channels through direct manufacturer relationships.
Japan
Aging demographics in Tokyo and Osaka metropolitan areas generate procedural demand exceeding domestic manufacturing capacity for injectable bulking agents. PMDA maintains distinct biocompatibility testing protocols that inflate pre-market expenditure and extend registration timelines for US and European suppliers. Nagoya's tertiary urogynecology centers pioneer same-day discharge protocols for cystoscopic bulking procedures.
Switzerland
Swissmedic's alignment with EU MDR standards accelerates cross-border product registrations for manufacturers serving German and French hospital systems. Geneva and Zurich ambulatory networks favor silicone gel formulations with extended shelf stability that reduce inventory management overhead. Basel's medical device cluster hosts contract manufacturing operations supplying Nordic specialist practices.
United Kingdom
NHS England's tariff negotiations for outpatient urological procedures create reimbursement uncertainty that compresses vendor margins in London and Manchester hospital trusts. The MHRA's post-Brexit regulatory pathway diverges from EU MDR timelines, fragmenting launch sequencing for continental manufacturers. Cambridge's biomedical research corridor supports investigational device trials for next-generation biodegradable bulking scaffolds.
Urethral Bulking System Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated urology portfolios commanding hospital procurement committees while single-product firms capture ambulatory margin pools. The vendor base concentrates around three strategic archetypes: diversified medtech conglomerates with predicate device histories, regional aesthetic medicine specialists leveraging European manufacturing footprints, and Nordic hospital-system integrators with embedded clinical training capabilities. Competitive moves center on M&A activity targeting hyaluronic acid carrier technologies and strategic partnerships with gynecology practice networks seeking cystoscopy capability expansion.
Within the diversified medtech tier, Boston Scientific Corporation and Coloplast Corp exemplify contrasting geographic anchoring strategies. Boston Scientific's US incorporation positions it within Medicare reimbursement pathways and FDA predicate device libraries. Coloplast's Danish origins align with Nordic hospital system purchasing patterns and EU MDR compliance sequencing. Merz Aesthetics occupies a distinct position as a German GmbH-structured specialist with manufacturing concentration in European aesthetic and urological channels.
| Leading Market Players |
|---|
| Merz Aesthetics |
| Contura |
| Boston Scientific Corporation |
| ASCENTX MEDICAL |
| Laborie |
| CR Bard |
| Cogentix Medical |
| Q-Med |
| Coloplast Corp |
| Others |
Value Chain & Pricing Dynamics
Collagen-versus-silicone material bifurcation splits procurement economics between cold-chain-dependent hospital tiers and shelf-stable ambulatory tiers, with each tier demanding distinct supplier footprints and inventory risk allocations. German purchasing cooperatives and US Medicare-certified ASCs now negotiate device-only contracts that strip out bundled training services, compressing vendor margins while shifting supply chain complexity downstream to facility operators.
Pricing Analysis
Volume placements concentrate in collagen-based formulations reimbursed through Medicare hospital pathways, while silicone gel commands premium positioning in cash-pay German and Japanese ambulatory networks where durability claims justify out-of-pocket expenditure. Price differentiation hinges on cold-chain logistics requirements and shelf stability metrics, with collagen products carrying higher per-unit handling costs. Pricing pressure stems from after-sales service unbundling as facilities source procedure support independently. US hospital systems exhibit lowest price sensitivity due to integrated delivery network volume commitments, whereas independent German clinics negotiate aggressively through purchasing cooperatives.
Supply Chain Analysis
Single-source vulnerability sits with European contract manufacturers supplying cross-linked dextranomer-hyaluronic acid carriers to specialty urology device firms. Raw material dependencies include pharmaceutical-grade polydimethylsiloxane elastomer, stabilized hyaluronic acid base stocks, and glutaraldehyde cross-linking agents. Supply chain risk centers on EU MDR documentation burdens that delay raw material qualification timelines for non-European suppliers. Distribution runs through Nordic hospital-affiliated specialist practices with embedded Coloplast and Merz supply agreements, alongside German purchasing cooperative networks that disintermediate traditional distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FDA's expanding 510(k) biocompatibility documentation requirements erect a cost-of-compliance barrier that favors established predicate device holders with robust clinical libraries, creating a defensive moat against undercapitalized entrants.
For Market Incumbents: Lock in hospital system purchasing committee relationships through comprehensive liability coverage and embedded electronic health record integration that complicates vendor switching. Boston Scientific and Coloplast should deepen backward integration into hyaluronic acid carrier production to secure supply continuity against EU MDR raw material qualification delays. Reinforce gynecology practice channel control by funding cystoscopy capability expansion in female pelvic medicine clinics before competitors establish training relationships. For New Entrants and Emerging Players: Capture the fastest-expanding gynecology therapy area channel where procedural volume climbs as specialists integrate bulking into mixed incontinence protocols without entrenched supplier relationships. Target Health Canada-aligned cross-border approval pathways that leverage FDA predicate device standards to reduce duplication costs and accelerate revenue generation. Prioritize silicone gel formulation development to exploit cash-pay ambulatory margin pools where durability claims support premium positioning. For Investors and Strategic Acquirers: Re-rating potential sits with European manufacturing specialists possessing EU MDR compliance sequencing advantages and established Nordic hospital system relationships, given the regulatory barrier expansion in US markets. Long-term viability over a five-to-ten year horizon favors acquirers of hyaluronic acid carrier technology platforms that enable next-generation bulking agent durability claims. Monitor US Medicare Advantage reimbursement recalibrations for outpatient stress incontinence procedures as the critical inflection signal for ambulatory surgical center volume trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Compliance Sequencing | Accelerates cross-border product registrations for manufacturers serving German hospital systems. |
| Hyaluronic Acid Carrier Acquisition | Secures next-generation bulking agent durability claims for premium cash-pay positioning. |
| Gynecology Practice Partnership | Opens fastest-expanding therapy area channel through cystoscopy capability funding. |
| Health Canada Alignment Pathway | Reduces regulatory duplication costs for FDA-cleared predicate device holders. |
| After-Sales Service Unbundling | Responds to German purchasing cooperative demand for device-only procurement terms. |
Study Parameters
FDA 510(k) filings, EU MDR technical documentation databases, and hospital procurement contract records formed the secondary backbone, cross-referenced against primary interviews with urogynecology fellowship directors, ambulatory surgical center administrators, GPO contracts managers, and biomedical engineers specializing in injectable biomaterials. Bottom-up segmentation modeling triangulated against top-down macroeconomic drivers including aging demographic projections and reimbursement policy trajectories.
Historical trendline analysis of procedural volume and biomaterial placement patterns informed the analytical framework across the projection horizon, with segmentation dimensions covering product type, therapy area, end user, and application. CAGRs derived from regression analysis of installed base expansion and replacement cycle dynamics, incorporating Japan PMDA registration timeline differentials and US Medicare Advantage coverage recalibration scenarios as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to reimbursement policy shifts and regulatory documentation burden escalations. Forecasts reflect documented assumptions about predicate device library availability and biocompatibility testing protocol harmonization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Medical Tricorder Market
Medical Devices
United Kingdom Aesthetic Devices Market
Medical Devices
North America C-Arms Market
Medical Devices
Luer Lock Connector Market
Medical Devices
Mexico Ophthalmic Devices Market
Medical Devices
AI Colonoscopy Withdrawal Quality Monitoring System Market
Medical Devices
Breast Lesion Localization Device Market
Medical Devices
Artificial Urinary Sphincters Market
Medical Devices
Leadless Pacing Systems Market
Medical Devices
Global Hernia Mesh Devices Market
Medical Devices
Anti-Decubitus Dynamic Mattress Market
Medical Devices
India Minimally Invasive Surgery Devices Market
Medical Devices
United States Ultrasound Devices Market
Medical Devices
Leadless Cardiac Pacemaker Market
Medical Devices
Veterinary Arthroscopy Device Market
Medical Devices
Tourniquet Systems Market