
 Medical Imaging Agent-Producing System Market | 2026-2036
Medical Imaging Agent-Producing System Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Imaging Agent-Producing System Market Foresight
Asset-light leasing models for cyclotron and synthesis modules is rewriting competitive entry barriers for mid-sized health systems. GE Healthcare leverages its installed base of imaging equipment to anchor long-term service contracts for agent-producing systems. Siemens Healthineers sustains R&D intensity across magnetic resonance and molecular imaging agent platforms. Bracco Imaging specializes in iodinated contrast agent synthesis systems for interventional radiology suites.
A medical imaging agent-producing system encompasses the integrated hardware, synthesis modules, and quality-control infrastructure used to manufacture radiopharmaceuticals, contrast media, and dual-modality imaging agents on-site or at centralized facilities, typically operating under Good Manufacturing Practice conditions with automated dispensing, sterility assurance, and real-time radiochemical purity verification. These systems serve the primary commercial purpose of enabling hospitals and diagnostic networks to produce short-half-life tracers such as fluorodeoxyglucose without decay-related transport losses. Radiopharmaceuticals command the dominant share of product-type revenue due to cyclotron infrastructure requirements and isotope supply complexity. Diagnostic centers represent the fastest-growing end-user category as outpatient imaging chains seek captive production to bypass third-party markup. Injectable delivery mode occupies the largest volume position across oncology and cardiology applications where vascular administration remains standard.
The FDA enforces Current Good Manufacturing Practice standards for positron emission tomography drug production under 21 CFR Part 212, while the EMA's radiopharmaceutical guideline harmonizes quality specifications across European member states. ISO 13485 certification governs quality management for system manufacturers seeking market access in regulated jurisdictions. Stakeholders must monitor isotope supply chain vulnerabilities and cyclotron decommissioning cycles to calibrate capacity investments against tracer demand curves.
Market Dynamics
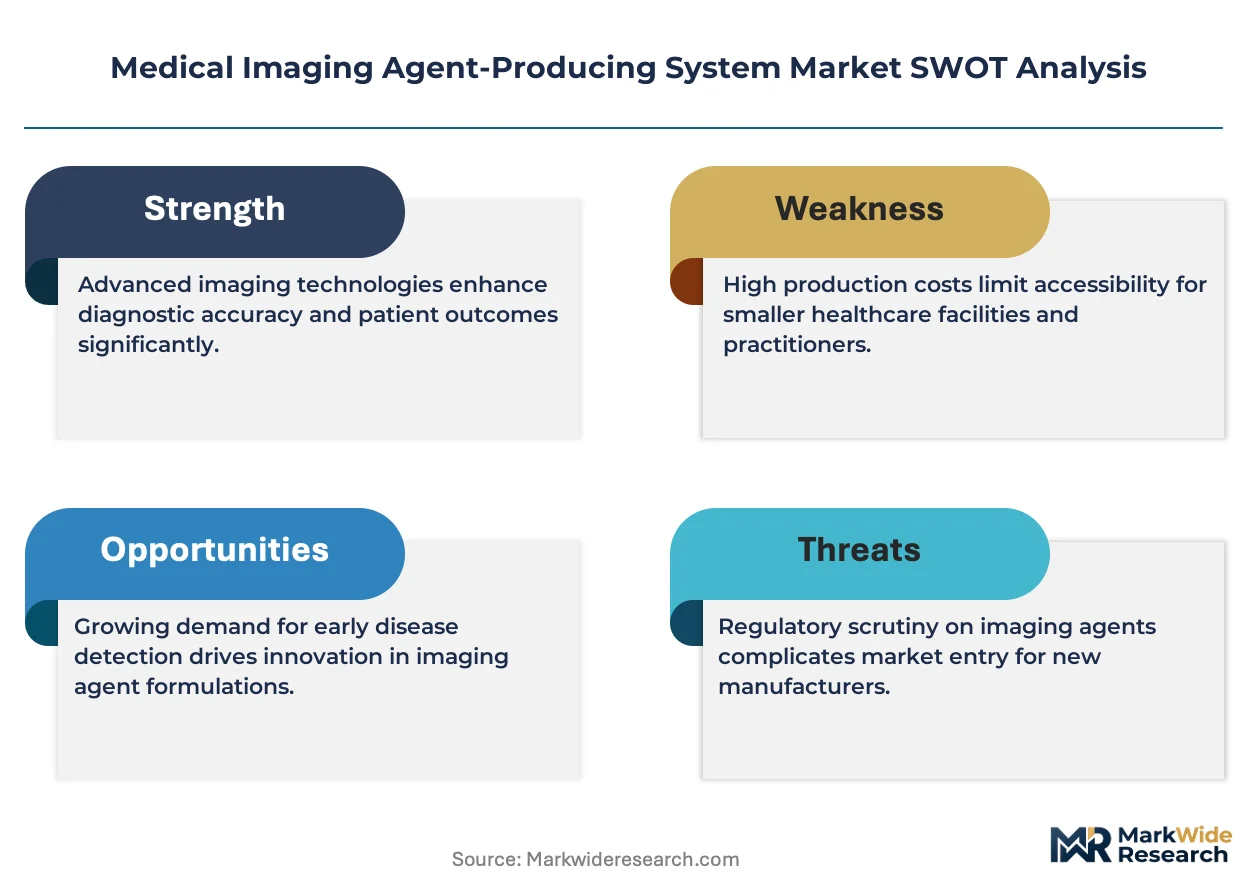
Supply chain sovereignty pressures are forcing health systems to internalize cyclotron-based production capacity, collapsing the traditional reliance on centralized commercial radiopharmacy networks and rewriting capital deployment patterns across diagnostic infrastructure.
Growth Catalysts
- 21 CFR Part 212 enforcement:FDA's tightened Current Good Manufacturing Practice standards for PET drug production are accelerating hospital investments in compliant on-site synthesis infrastructure.
- Fluorodeoxyglucose decay economics:The 110-minute half-life of F-18 isotopes makes local production economically imperative for high-volume oncology centers.
- Diagnostic center consolidation:Outpatient imaging chains are building captive production capabilities to eliminate third-party tracer markup and secure scheduling autonomy.
Market Restraints
- Molybdenum-99 supply concentration:Ageing research reactors in Canada and Europe create vulnerability for technetium-based agent production.
- Cyclotron decommissioning cycles:20-year equipment lifespans trigger capital replacement cliffs that strain mid-sized health system budgets.
- Specialized radiochemist scarcity:Limited training pipelines for cGMP-qualified synthesis operators constrain facility commissioning timelines.
Strategic Opportunities
- India's nuclear medicine expansion:CDSCO's streamlined radiopharmaceutical approval pathways are opening greenfield diagnostic infrastructure investment.
- Alpha-emitter theranostics:Lutetium-177 and actinium-225 production systems represent unpenetrated capacity expansion beyond diagnostic tracers.
- Modular synthesis platforms:Containerized GMP units are enabling distributed production models for rural and secondary hospital networks.
Industry Challenges
- ISO 13485 certification timelines:System manufacturers face 18-24 month quality management audits that delay market entry.
- Legacy PACS integration friction:New synthesis modules require custom middleware to connect with existing radiology information systems.
- Radioactive waste handling protocols:Evolving EPA disposal standards demand continuous operational recertification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Imaging Agent-Producing System Market |
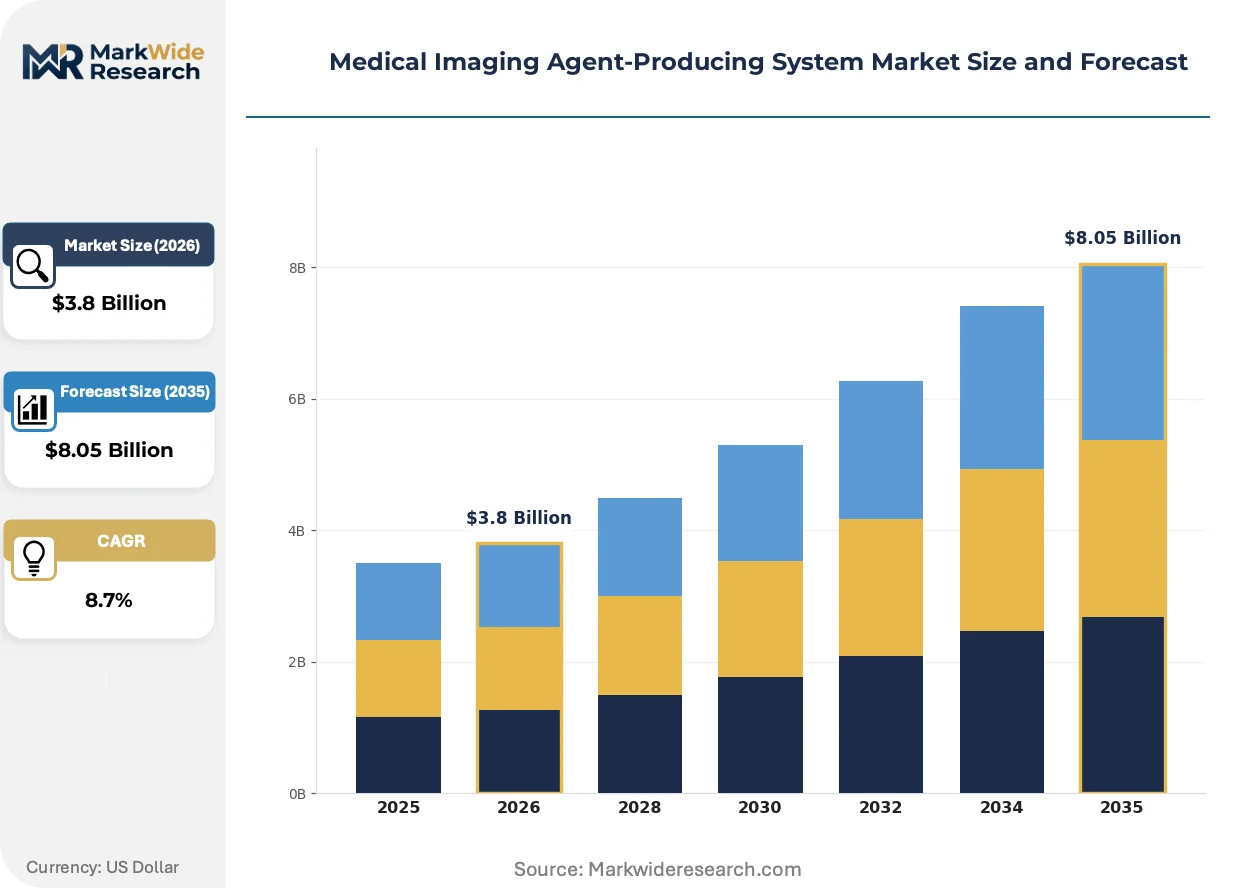
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radiopharmaceuticals, Contrast Agents, Imaging Agents, Dual-Modality Agents End User: Hospitals, Diagnostic Centers, Research Organizations, Imaging Labs Delivery Mode: Injectable, Oral, Inhalation, Topical Application: Oncology, Cardiology, Neurology, Gastroenterology |
| Companies Covered | GE Healthcare, Siemens Healthineers, Bayer AG, Lantheus Medical Imaging, Guerbet Group, Bracco Imaging, Philips Healthcare, Canon Medical Systems, Eli Lilly, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Imaging Agent-Producing System Market Shifts & Advancements
Automation and closed-loop quality systems are displacing manual synthesis workflows, compressing batch-to-batch variability and enabling 24-hour production cycles that match imaging demand curves.
Artificial intelligence-driven radiochemical purity verification is digitizing the final release testing sequence. Academic medical centers in Germany and the United States are piloting machine-vision systems that replace human chromatography interpretation. This compression of quality assurance labor is enabling leaner night-shift operations without compromising FDA batch documentation requirements.
EMA's 2023 radiopharmaceutical guideline revision harmonizes positron emission tomography drug specifications across European member states. The industrial consequence is simplified cross-border facility validation for centralized production hubs serving multiple national markets. Manufacturers in Belgium and the Netherlands are consolidating regional supply under single cGMP licenses rather than maintaining country-specific quality systems.
After-sales service unbundling is fragmenting traditional equipment-vendor relationships. Hospital procurement teams are separating cyclotron hardware purchases from maintenance contracts and isotope supply agreements. This disintermediation is most visible in United States academic medical centers, where independent service organizations now compete with OEMs for synthesis module calibration and spare parts logistics.
Medical Imaging Agent-Producing System Market Segmentation
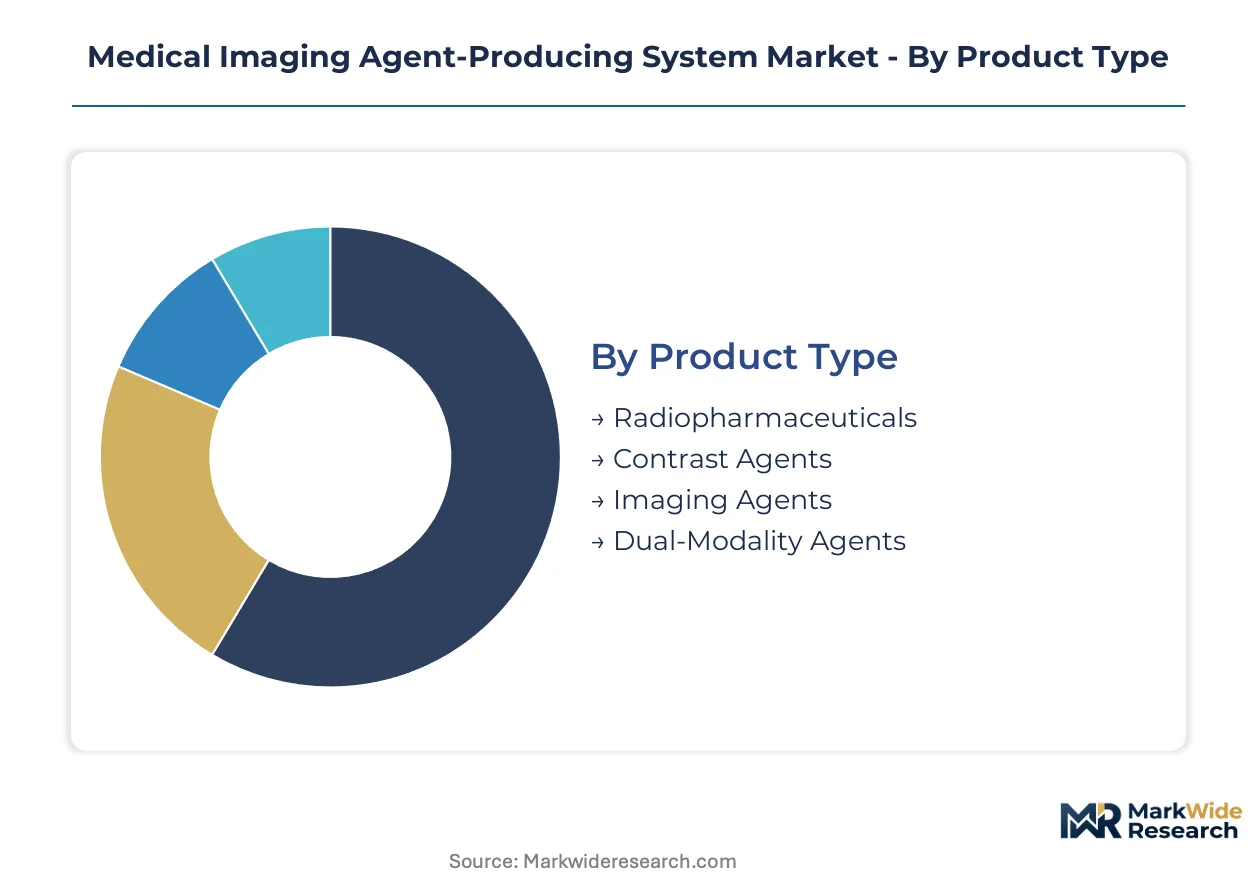
Segmentation in this market determines capital intensity, regulatory pathway, and operational complexity. Product type dictates cyclotron versus chemical synthesis infrastructure. End-user category shapes service model and financing structure.
Product Type:
Cost tier stratification separates cyclotron-dependent isotope production from chemical synthesis platforms.
- Radiopharmaceuticals:Cyclotron-produced positron emitters and generator-derived technetium isotopes require shielded GMP suites and real-time radiochemical purity verification. Academic medical centers in the United States anchor demand as FDA 21 CFR Part 212 compliance tightens quality thresholds for PET drug manufacturing.
- Contrast Agents:Iodinated and gadolinium-based compounds deploy non-radioactive chemical synthesis with lower shielding requirements. Diagnostic center chains in Germany and Japan are standardizing on automated dispensing systems to reduce batch-to-batch variability in high-throughput CT suites.
- Imaging Agents:Optical and fluorescent probes serve intraoperative navigation and microscopy applications with minimal regulatory burden.
- Dual-Modality Agents:PET-MRI and SPECT-CT hybrid tracers combine radiolabeled and paramagnetic moieties in single molecular constructs.
Radiopharmaceuticals command the established base. The steepest expansion runs through dual-modality agents as theranostic applications mature.
End User:
Customer type determines procurement authority, financing mechanism, and service integration depth.
- Hospitals:Integrated health systems deploy captive production to secure supply chain sovereignty and eliminate third-party tracer markup. In-house cyclotron facilities in the United States are expanding as Medicare reimbursement shifts favor site-of-care production economics.
- Diagnostic Centers:Outpatient imaging chains are consolidating regional production hubs under centralized GMP licenses. CDSCO's streamlined radiopharmaceutical pathways in India are accelerating greenfield diagnostic infrastructure investment by private imaging networks.
- Research Organizations:Academic radiochemistry departments pilot novel tracer synthesis for clinical translation studies.
- Imaging Labs:Contract manufacturing organizations serve niche isotope demands with flexible batch sizing.
Hospitals command the established base. Diagnostic centers are expanding most quickly as consolidation creates economies of scale in captive production.
Delivery Mode:
Volume concentration follows vascular administration routes where rapid biodistribution is clinically essential.
- Injectable:Intravenous and intra-arterial delivery dominates oncology and cardiology applications where tracer kinetics determine image quality. Automated sterile filling lines in Belgium and the Netherlands are consolidating regional supply under single EMA cGMP licenses.
- Oral:Barium suspensions and encapsulated radiotracers serve gastrointestinal transit studies with simpler handling protocols.
- Inhalation:Aerosolized ventilation agents target pulmonary function assessment in specialized respiratory clinics.
- Topical:Dermal application of fluorescent dyes supports intraoperative margin assessment in dermatologic and breast surgery.
Injectable delivery commands the established base. Oral administration shows the steepest expansion trajectory as capsule-based molecular imaging agents enter clinical trials.
Application:
Maturity gradients separate decades-established oncology tracer protocols from emerging neurologic indications.
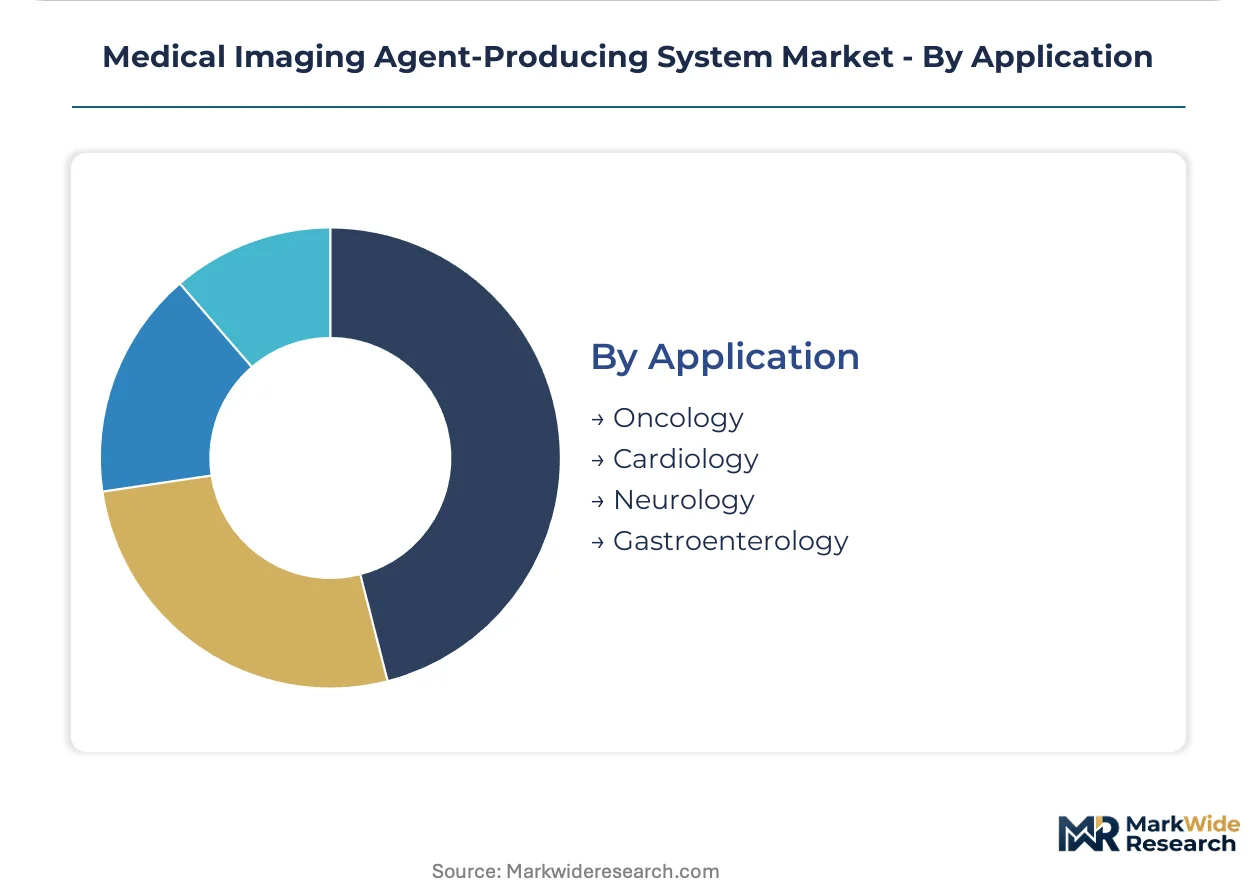
- Oncology:Fluorodeoxyglucose PET dominates staging and response assessment with standardized synthesis protocols. The 110-minute half-life of F-18 isotopes makes local production economically imperative for high-volume cancer centers in the United States and Germany.
- Cardiology:Myocardial perfusion agents and viability tracers serve established stress-testing workflows with predictable demand curves.
- Neurology:Amyloid and tau imaging agents for Alzheimer's disease are scaling production as diagnostic criteria incorporate biomarker confirmation.
- Gastroenterology:Motility studies and bleeding localization employ specialized sulfur colloid and labeled red blood cell preparations.
Oncology commands the established base. Neurology is climbing the fastest as aging demographics expand addressable patient populations for neurodegenerative disease diagnostics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States runs a structural surplus in cyclotron-based agent production systems, exporting synthesis modules to Germany and Japan while importing raw isotope feedstock from Canada and the Netherlands. Trade flows concentrate around FDA-cleared hardware platforms and EMA-harmonized quality documentation.
United States
Academic medical centers in Boston and Houston are commissioning in-house fluorodeoxyglucose production lines to eliminate decay-related transport losses. FDA's 21 CFR Part 212 enforcement tightens cGMP thresholds for PET drug manufacturing. The Mayo Clinic cluster in Rochester anchors regional supply chain sovereignty investments across the Upper Midwest.
Germany
University hospitals in Munich and Heidelberg are consolidating theranostic production under single EMA cGMP licenses. The 2023 EMA radiopharmaceutical guideline revision harmonizes cross-border facility validation. The Rhine-Ruhr industrial corridor hosts centralized hubs serving Dutch and Belgian diagnostic networks with automated dispensing systems.
Japan
PMDA's streamlined approval pathways for novel tau imaging agents are accelerating cyclotron deployment in Tokyo and Osaka. METI's nuclear medicine infrastructure subsidies support rural hospital networks adopting containerized synthesis platforms. The Kansai region concentrates manufacturing partnerships between imaging equipment vendors and regional pharmacy chains.
India
Private diagnostic chains in Mumbai and Bangalore are building captive production capabilities following CDSCO's radiopharmaceutical pathway streamlining. The country's national pharmaceutical regulator is aligning quality standards with IAEA safety protocols. Hyderabad's life sciences cluster attracts contract manufacturing organizations serving Southeast Asian export markets.
Belgium
Regional production hubs in Antwerp and Liège leverage centralized EMA licensing to supply tracer doses across France and Luxembourg. The country's national pharmaceutical regulator maintains mutual recognition agreements with Dutch and German counterparts. Wallonia's nuclear research infrastructure supports isotope processing for European diagnostic networks.
Medical Imaging Agent-Producing System Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in isotope supply and quality verification subsystems. The vendor base stratifies across three tiers: imaging equipment OEMs anchoring long-term service contracts, pure-play radiopharmaceutical firms with cyclotron networks, and emerging modular synthesis platform developers. Dominant competitive moves include backward integration into isotope production and geographic licensing partnerships to bypass regulatory entry barriers.
Among diversified health technology conglomerates, GE Healthcare and Siemens Healthineers occupy positions spanning cyclotron hardware through imaging system integration. Bracco Imaging exemplifies the contrast agent specialization archetype, sitting within the chemical synthesis tier rather than radioactive isotope production. These three anchors represent distinct strategic postures: full-stack platform control, magnetic resonance and molecular imaging convergence, and interventional radiology suite concentration.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Bayer AG |
| Lantheus Medical Imaging |
| Guerbet Group |
| Bracco Imaging |
| Philips Healthcare |
| Canon Medical Systems |
| Eli Lilly |
| Others |
Supply & Pricing Matrix
The Rotterdam-Antwerp isotope corridor channels molybdenum-99 feedstock from Dutch reactors to Belgian processing facilities, with freight cost volatility translating directly into regional price spreads for technetium-based agents and forcing hospital buyers into long-term offtake commitments to stabilize unit economics.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with FDA 21 CFR Part 212 certification tier and cyclotron shielding grade as primary differentiation drivers. Pricing pressure stems from mid-sized health system budget constraints as cyclotron decommissioning cycles trigger replacement cliffs. Academic medical centers show lowest price sensitivity due to research funding insulation, while diagnostic center chains negotiate aggressively on per-dose contracts.
Supply Chain Analysis
Tariff exposure between Canada and the United States dominates supply risk calculations for molybdenum-99, the backbone isotope for technetium generator production. Raw material dependencies center on enriched uranium targets, specialized target plating services, and helium-3 for neutron detection. Distribution runs through centralized radiopharmacy networks that batch doses for last-mile delivery to imaging suites, with single-source vulnerability at the reactor level creating systemic fragility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as hospital system consolidation creates regional purchasing coalitions capable of dictating synthesis module specifications and service terms to equipment vendors.
For Market Incumbents: Build regulatory moats through early FDA 21 CFR Part 212 compliance investments that mid-sized competitors cannot replicate. Secure backward integration into isotope production to neutralize molybdenum-99 supply vulnerability. Anchor long-term service contracts by embedding predictive maintenance algorithms that raise switching costs for hospital customers. For New Entrants and Emerging Players: Build out modular containerized synthesis platforms for rural and secondary hospital networks underserved by centralized radiopharmacy infrastructure. Target India's private diagnostic chains following CDSCO pathway streamlining, where greenfield facility construction outpaces incumbent coverage. Lead with asset-light leasing models that collapse capital barriers for mid-tier health systems. For Investors and Strategic Acquirers: Pure-play radiochemistry firms with established cGMP licenses and cyclotron networks represent the most defensible acquisition archetype as theranostic applications expand beyond diagnostic tracers. Long-term viability hinges on Lu-177 and Ac-225 production capability buildout. Watch for inflection when alpha-emitter therapy reimbursement codes stabilize in Medicare and major European payer systems.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 21 CFR Part 212 Compliance Investment | Accelerates hospital capital deployment toward certified on-site synthesis infrastructure. |
| Backward Integration into Isotope Production | Neutralizes molybdenum-99 supply concentration risk from ageing Canadian and European reactors. |
| Modular Synthesis Platform Deployment | Enables distributed production models for rural hospital networks in Japan and India. |
| Alpha-Emitter Theranostic Capacity Expansion | Captures unpenetrated demand for Lu-177 and Ac-225 production beyond diagnostic tracers. |
| After-Sales Service Unbundling | Creates competitive entry points for independent service organizations against OEM maintenance contracts. |
Research Methodology
Initial hypotheses were tested against primary input from cyclotron facility directors, radiopharmacy operations managers, hospital procurement committees, and GPO contract specialists and refined through secondary validation against FDA 21 CFR Part 212 guidance documents, EMA radiopharmaceutical guidelines, IAEA safety protocol publications, and hospital capital expenditure databases. Bottom-up facility deployment counts were triangulated with top-down health system budget forecasts.
Demand-supply balance modeling across the analysis window incorporated product type segmentation by cyclotron versus chemical synthesis infrastructure, end-user category by hospital system versus diagnostic center, and application maturity by oncology versus neurology tracer protocols. CAGRs were derived from tracer dose volume projections calibrated against imaging procedure growth and isotope half-life economics. Forecast inputs included cyclotron decommissioning replacement cycles and radiochemist training pipeline constraints.
The forecast holds incumbent behavior within observed patterns; aggressive moves by modular synthesis platform developers or isotope production startups would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Structural Heart Imaging Market
Medical Imaging
SPECT Scanning Services Market
Medical Imaging
MR-Linac and Image-Guided Radiotherapy QA Measurement Systems Market
Medical Imaging
Radio-Fluoroscopy Systems Market
Medical Imaging
Magnetic Resonance Imaging Equipment Coils Market
Medical Imaging
Australia Computed Tomography Market
Medical Imaging
Japan Mammography Market
Medical Imaging
Canada Magnetic Resonance Imaging (MRI) Market
Medical Imaging
Brazil Nuclear Imaging Market
Medical Imaging
North America Medical Imaging Software Market
Medical Imaging
Europe Mobile Tomography Market
Medical Imaging
Mobile Tomography Market
Medical Imaging
China Magnetic Resonance Imaging Market
Medical Imaging
Point-Of-Care Medical Imaging Market
Medical Imaging
South Korea Computed Tomography Market
Medical Imaging
China Mammography Market