
 Global Biopsy Punch Market | 2026-2036
Global Biopsy Punch Market Size, Share, and Industry Trends Forecast 2026-2036
Global Biopsy Punch Market Foresight
Asset-light leasing models for surgical instrument fleets are rewriting competitive access in the biopsy punch sector. Integra LifeSciences Holdings Corporation leverages its specialized dermatology portfolio to dominate premium disposable segments. Merit Medical Systems, Inc. sustains manufacturing scale across multiple punch geometries for interventional radiology. Becton, Dickinson and Company anchors hospital system procurement through integrated supply contracts that bundle biopsy devices with pathology consumables.
A biopsy punch is a cylindrical surgical instrument with a sharpened distal edge, typically manufactured from stainless steel or medical-grade polymers, designed to extract full-thickness tissue cores for histopathological examination. The instrument functions by manual rotation or motorized advancement to incise and retrieve cylindrical tissue samples ranging from two to eight millimeters in diameter. Disposable punches lead volume share due to cross-contamination elimination and simplified reprocessing logistics, while motorized variants capture expanding margin pools in high-throughput ambulatory settings. Laser-assisted technology segments are gaining procedural traction in cosmetic surgery applications where precision margins reduce scarring risk.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape product development timelines and market entry costs for biopsy punch manufacturers. ISO 13485 quality management standards and biocompatibility testing under ISO 10993 govern material selection and sterilization validation across all commercialized devices. Stakeholders must monitor evolving notified body capacity constraints in Europe and emerging market regulator harmonization initiatives that could reshape certificate portability and competitive positioning.
Market Dynamics
Single-use instrument mandates under FDA and EU MDR are compressing reusable device lifecycles and forcing capital redeployment toward sterile disposable manufacturing lines.
Growth Catalysts
- EU MDR sterilization protocols:Technical documentation requirements for reusable instrument revalidation are accelerating hospital conversions to pre-sterilized disposable formats.
- Dermatology clinic expansion:Ambulatory procedural volumes in skin cancer screening are broadening addressable demand for 2-4mm disposable punch geometries.
- Laser-assisted precision technology:Cosmetic surgery applications requiring minimal scarring margins are creating premium positioning for optical guidance integration.
Market Restraints
- Medical-grade polymer cost volatility:Polypropylene and polycarbonate feedstock price swings compress margin stability for high-volume disposable manufacturers.
- Notified body capacity constraints:EU MDR certification backlogs at TÜV SÜD and BSI extend product launch timelines by 8-14 months.
- Core needle biopsy substitution:Vacuum-assisted breast biopsy systems capture share in soft-tissue applications where cylindrical extraction is non-critical.
Strategic Opportunities
- Brazil ANVISA harmonization:Emerging market regulator alignment with ISO 13485 standards reduces certificate duplication costs for manufacturers entering Latin America.
- Motorized-robotic convergence:Integration of battery-powered advancement mechanisms with robotic positioning systems opens precision oncology applications.
- Direct-to-clinic distribution:Bypassing distributor markups through e-procurement platforms captures margin in independent dermatology practices.
Industry Challenges
- Biocompatibility testing bottlenecks:ISO 10993 cytotoxicity and sensitization study queues at contract laboratories delay sterilization validation.
- Legacy sterilization asset stranding:Ethylene oxide facility closures under EPA emissions rules force rapid transition to gamma irradiation partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Biopsy Punch Market |
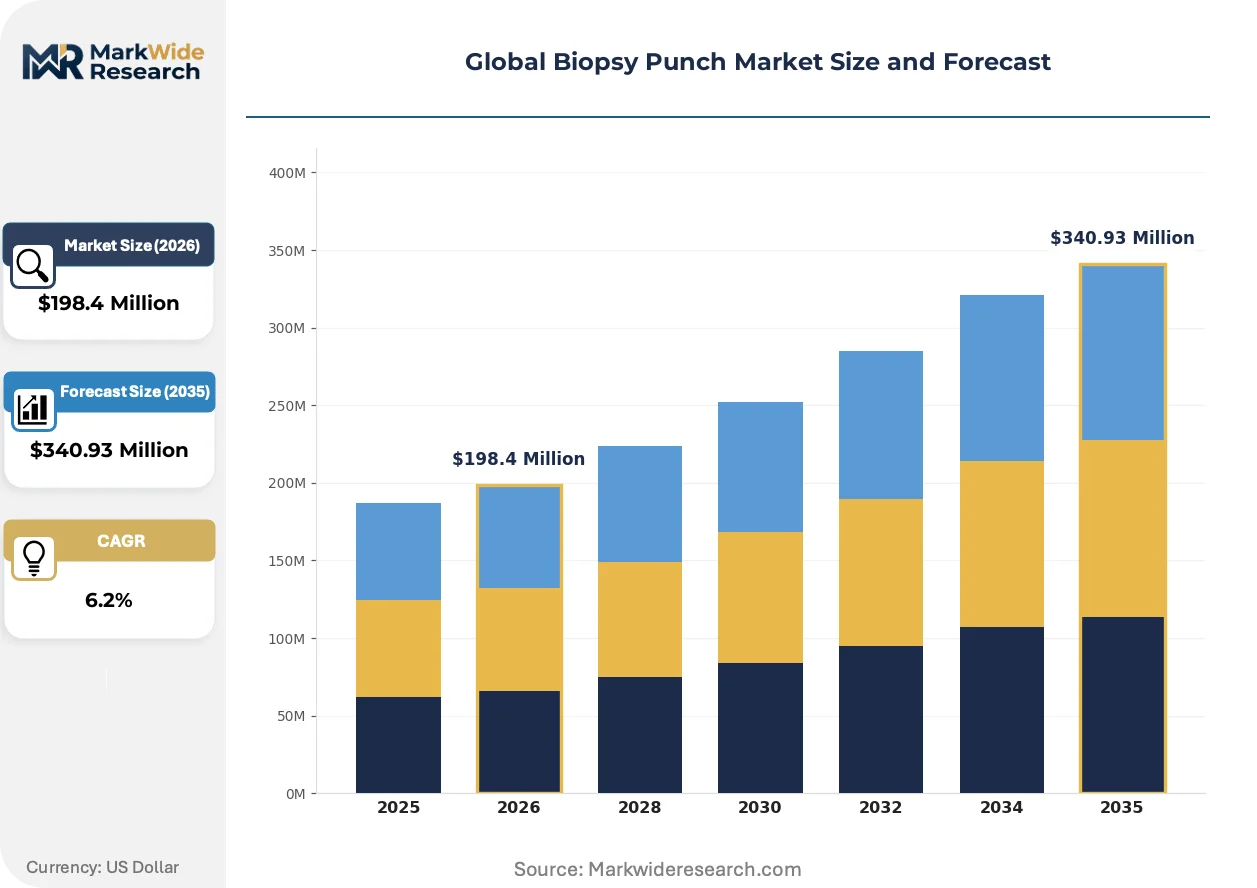
| Market Size in 2026 | $198.4 Million |
| Market Size in 2035 | $340.93 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable Punch, Reusable Punch, Motorized Punch, Manual Punch Application: Dermatology, Gynecology, Oral Pathology, Veterinary Medicine, Cosmetic Surgery End User: Pathology Labs, Dermatology Clinics, Dental Clinics, Animal Hospitals, Ambulatory Surgical Centers Technology: Mechanical, Laser-Assisted, Cryogenic, Electric Motor, Ultrasonic |
| Companies Covered | Integra LifeSciences Holdings Corporation, Merit Medical Systems, Inc., Medtronic plc, Acuderm, Inc., Becton, Dickinson and Company, B. Braun Melsungen AG, Teleflex Incorporated, Kai Medical, Inc., Cardinal Health, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Biopsy Punch Market Shifts & Advancements
Disposable format dominance and precision automation are converging to redefine manufacturing scale requirements and clinical workflow integration across biopsy punch applications.
Motorized biopsy systems with integrated depth control and automated tissue retrieval are hybridizing manual and powered modalities. High-throughput ambulatory surgery centers in Germany and Japan are adopting these hybrid platforms to reduce operator fatigue during sequential procedures. The technology is hybridizing capital equipment and consumable revenue models, compressing traditional manual punch margins while expanding per-procedure value capture.
EU MDR Article 10 technical documentation requirements are forcing systematic clinical evidence collection for legacy device recertification. Manufacturers must now generate post-market surveillance data for predicate devices previously cleared under MDD. Small and mid-cap suppliers without dedicated regulatory affairs infrastructure are consolidating or exiting, concentrating notified body engagement among scaled players.
Hospital procurement departments are unbundling pathology consumables from device supply contracts to negotiate separate category management. Integrated delivery networks in the United States are driving this disintermediation, replacing bundled agreements with modular sourcing that segments biopsy instruments from laboratory reagents. The shift is most visible in multi-site health systems seeking granular spend visibility across service lines.
Global Biopsy Punch Market Segmentation
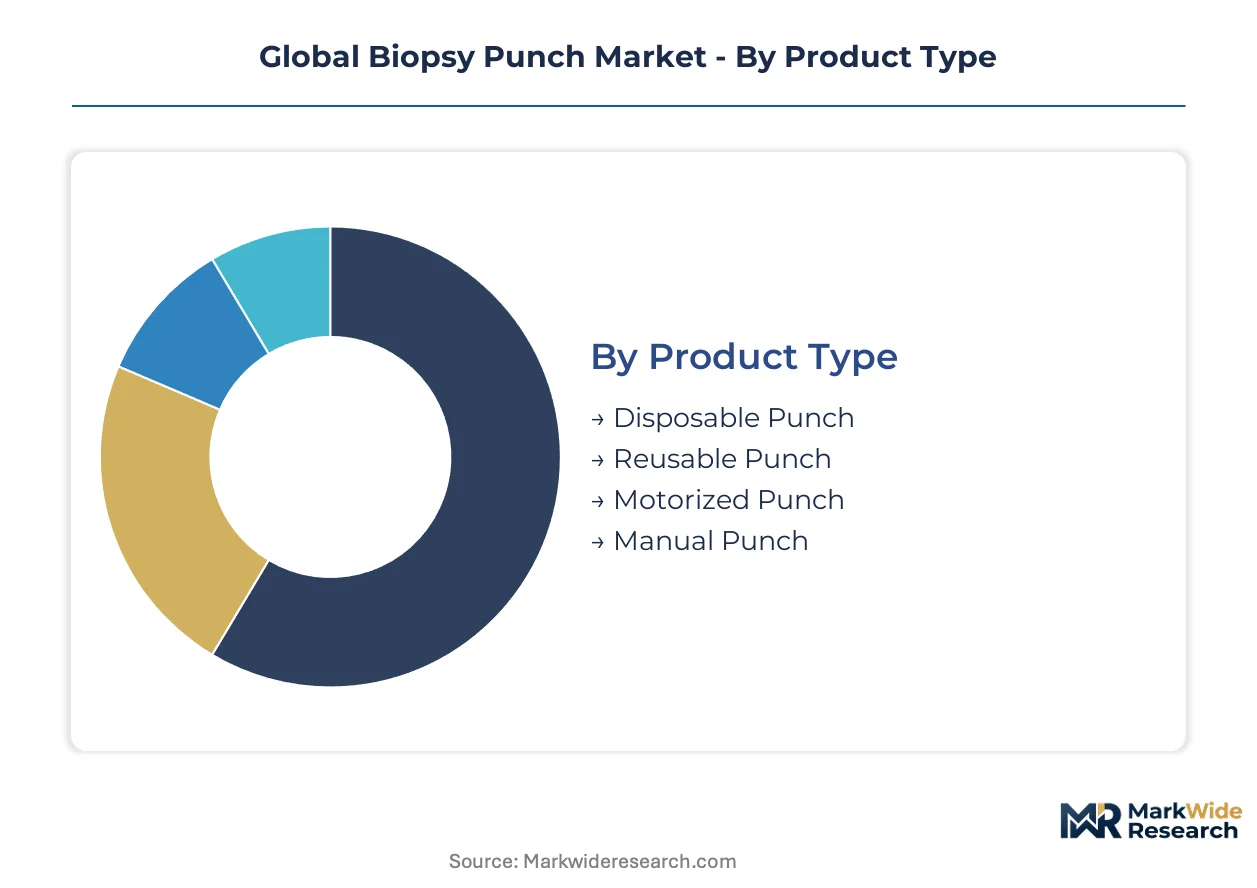
Biopsy punch segmentation reveals how procurement priorities diverge across clinical settings, from high-volume disposable consumption in dermatology chains to capital-intensive motorized platforms in academic pathology networks. Understanding these divides sharpens targeting for manufacturers navigating divergent margin structures and regulatory pathways.
Product Type:
Cost tier stratification separates single-use disposables from capital-intensive reusable and motorized systems, with sterilization economics driving hospital procurement decisions.
- Disposable Punch:Polypropylene and medical-grade polymer construction eliminates cross-contamination risk and reprocessing labor. Demand concentrates in United States dermatology clinic chains where sequential procedural volume favors sterile single-use workflows. FDA single-use instrument guidance and EU MDR sterilization mandates compress reusable alternatives.
- Motorized Punch:Battery-powered advancement mechanisms with integrated depth control reduce operator fatigue during high-throughput screening. Germany and Japan ambulatory surgery centers adopt these platforms for sequential melanoma excisions, capturing premium per-procedure value despite higher capital outlay.
- Reusable Punch:Stainless steel construction with autoclave compatibility serves cost-constrained veterinary and dental settings where sterilization infrastructure exists.
- Manual Punch:Basic cylindrical steel instruments dominate emerging market price-sensitive procurement and training environments.
Disposable formats command the established base. The steepest expansion runs through motorized platforms with precision automation.
Application:
Clinical application maps directly to lesion accessibility and tissue architecture requirements, with skin surface procedures dominating volume against deeper tissue or cosmetic precision niches.
- Dermatology:Skin cancer screening and melanoma diagnosis generate the highest procedural volume for 2-4mm punch geometries. Aging populations in Japan and Germany sustain biopsy throughput in dedicated dermatology networks.
- Cosmetic Surgery:Laser-assisted and ultrasonic technologies enable sub-millimeter precision margins for facial procedures where scarring minimization commands premium pricing. Beverly Hills and Seoul clinic clusters drive adoption of optical guidance integration.
- Gynecology:Cervical and vulvar biopsy applications favor 4-6mm diameter punches with integrated cautery for hemostasis.
- Oral Pathology:Dental clinic demand focuses on compact 2-3mm instruments for mucosal lesion sampling.
- Veterinary Medicine:Animal hospitals utilize cost-optimized manual and reusable formats for companion animal dermatopathology.
Dermatology anchors volume concentration. Cosmetic surgery applications are climbing fastest on precision technology premiums.
End User:
Customer type determines procurement modality, with integrated health systems favoring bundled supply contracts against independent practice spot purchasing.
- Pathology Labs:High-throughput histopathology services in Cleveland Clinic and Mayo Clinic networks standardize on disposable punch formats to eliminate cross-contamination risk in multi-specimen workflows.
- Dermatology Clinics:Independent practices in Florida and Arizona sun-belt regions drive demand for 3mm disposable geometries through direct-to-clinic e-procurement platforms.
- Ambulatory Surgical Centers:Medicare-certified facilities in Texas and California adopt motorized platforms for ASC-specific efficiency metrics.
- Dental Clinics:Oral pathology sampling in group dental practices favors compact manual instruments.
- Animal Hospitals:VCA and Banfield corporate chains standardize veterinary dermatopathology protocols.
Pathology labs hold the volume core. Ambulatory surgical centers are expanding most quickly on efficiency mandates.
Technology:
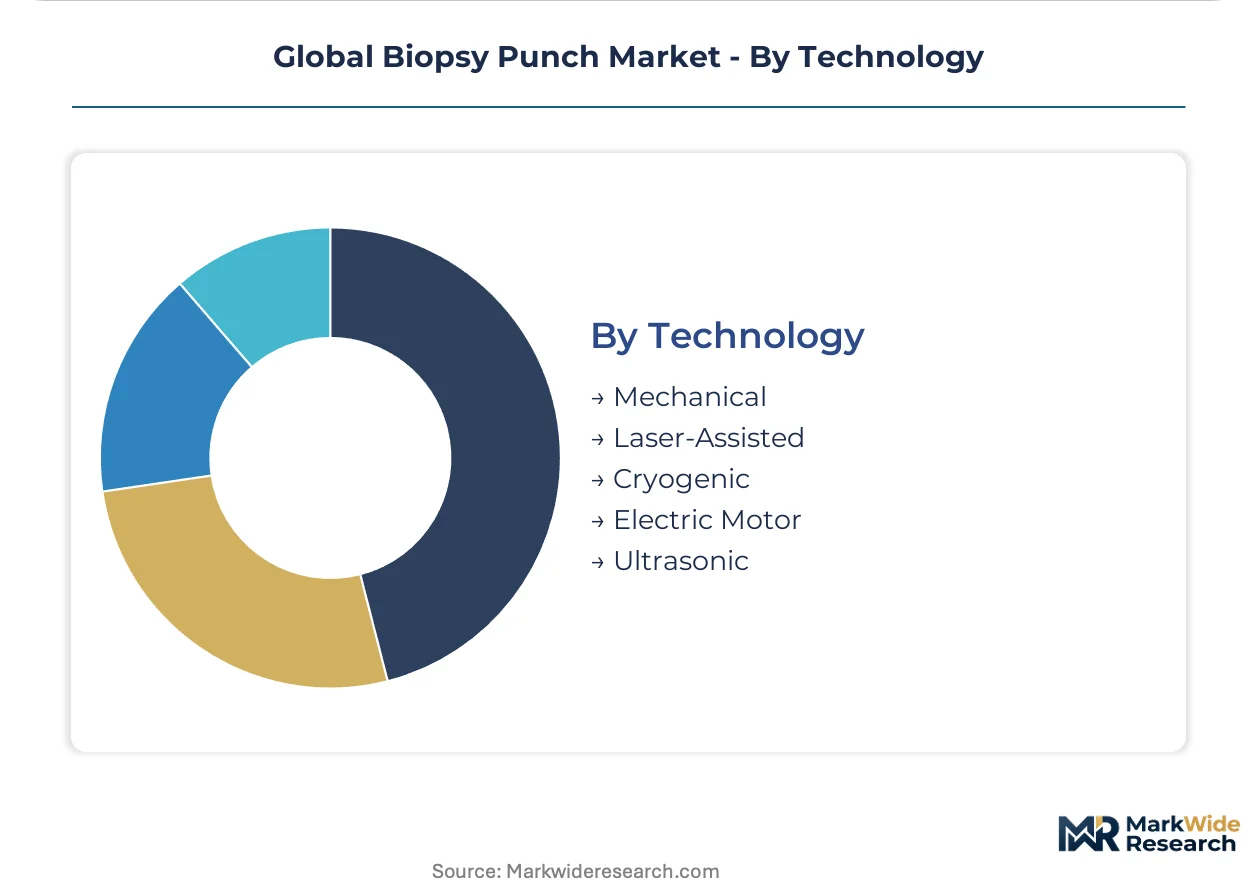
Technology maturity spans century-old mechanical designs against emerging energy-based modalities, with regulatory clearance timelines segmenting competitive access.
- Mechanical:Rotating cylindrical steel edges with manual advancement dominate cost-sensitive procurement across all geographies.
- Laser-Assisted:Optical guidance with thermal cutting action enables sub-millimeter precision for cosmetic applications. Seoul and Los Angeles aesthetic surgery centers drive validation studies for expanded indications.
- Electric Motor:Battery-powered consistent advancement reduces inter-operator variability in Germany and Japan high-volume screening programs.
- Ultrasonic:High-frequency vibration cutting minimizes tissue crush artifact for research-grade specimen quality.
- Cryogenic:Frozen tissue extraction preserves cellular architecture for intraoperative margin assessment in academic oncology centers.
Mechanical technology retains the installed base. Laser-assisted modalities are gaining share fastest on cosmetic surgery premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows from German precision instrument manufacturers balance against import dependence for polymer feedstocks across Asian disposable producers. Trade patterns concentrate finished device shipments toward United States dermatology networks while raw material sourcing spans petrochemical corridors in Saudi Arabia and South Korea.
United States
Melanoma screening protocols at Cleveland Clinic and Mayo Clinic networks sustain high-throughput demand for sterile disposable formats. FDA single-use instrument guidance compresses reusable alternatives through enforcement discretion letters. Sun-belt dermatology clusters in Florida and Arizona drive spot purchasing through direct-to-clinic e-procurement channels.
Germany
Ambulatory surgery center efficiency mandates favor motorized platform adoption for sequential melanoma excisions. EU MDR technical documentation requirements at TÜV SÜD extend recertification timelines for legacy stainless steel instruments. Baden-Württemberg precision engineering clusters supply advancement mechanism components to hybrid platform assemblers.
Japan
Aging demographic profiles sustain biopsy throughput in dedicated dermatology networks across Kanto and Kansai regions. PMDA quality management inspections align with MHLW sterilization protocol updates for disposable formats. Tokyo metropolitan pathology labs standardize on 3mm disposable geometries for skin cancer screening workflows.
China
Domestic dermatology chain expansion in Yangtze River Delta cities broadens addressable demand for cost-optimized manual instruments. NMPA Class II medical device registration pathways govern polymer biocompatibility testing requirements. Shenzhen manufacturing corridors supply medical-grade polypropylene to regional disposable fabricators.
Brazil
Independent dermatology practices in São Paulo and Rio de Janeiro drive procurement of imported disposable formats. ANVISA harmonization initiatives with ISO 13485 standards reduce certificate duplication costs for foreign manufacturers. Southeast Asian polymer suppliers route feedstock through Santos port corridors to domestic converters.
Global Biopsy Punch Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying advancement mechanisms and polymer housings. The vendor base stratifies across three tiers: multinational device conglomerates with integrated pathology portfolios, mid-cap disposable specialists with sterile manufacturing scale, and regional manual instrument fabricators serving price-sensitive procurement. Two strategic archetypes dominate competitive positioning: asset-light leasing model operators and direct-to-clinic distribution platform builders. Capacity expansion in gamma irradiation partnerships and M&A consolidation of notified body-constrained mid-caps represent the dominant competitive moves.
Within the multinational tier, Integra LifeSciences Holdings Corporation and Becton, Dickinson and Company anchor integrated supply positioning through bundled pathology consumable contracts. Merit Medical Systems, Inc. exemplifies the mid-cap disposable specialist archetype with manufacturing scale across multiple punch geometries. These three entities represent divergent strategic vectors: dermatology-focused portfolio depth, hospital system procurement anchoring, and interventional radiology manufacturing flexibility respectively.
| Leading Market Players |
|---|
| Integra LifeSciences Holdings Corporation |
| Merit Medical Systems, Inc. |
| Medtronic plc |
| Acuderm, Inc. |
| Becton, Dickinson and Company |
| B. Braun Melsungen AG |
| Teleflex Incorporated |
| Kai Medical, Inc. |
| Cardinal Health, Inc. |
| Others |
Supply & Pricing Matrix
Santos port corridor freight rates from Southeast Asian polypropylene suppliers compress margin buffers for Brazilian disposable punch converters while amplifying price spreads between premium motorized platforms and economy manual instruments. This logistics-cost wedge reinforces supply-chain-driven price differentiation across tiered procurement channels.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in the biopsy punch market. Price differentiation hinges on sterilization certification grade—FDA 510(k) cleared devices command substantial premiums over basic CE-marked alternatives—and volume scale commitments from integrated health system procurement. Pricing pressure stems from medical-grade polymer feedstock volatility pressuring disposable manufacturer margins. Independent dermatology clinics exhibit highest price sensitivity due to spot purchasing patterns, while academic pathology networks demonstrate lowest sensitivity given bundled supply contract structures.
Supply Chain Analysis
Extended payment terms from German precision component suppliers and supply-chain finance facilities at Asian polymer distributors shape working capital dynamics across the biopsy punch value chain. Manufacturing concentrates in Germany, China, and the United States—Baden-Württemberg engineering clusters feed advancement mechanisms, Shenzhen corridors supply medical-grade polypropylene housings, and Massachusetts sterile manufacturing sites serve domestic hospital procurement. Raw material dependencies center on polypropylene resin, stainless steel surgical grades, and lithium-ion battery cells for motorized platforms. Single-source vulnerability in gamma irradiation sterilization capacity poses structural risk following EPA-mandated ethylene oxide facility closures. Distribution runs through integrated delivery network contracts and direct-to-clinic e-procurement platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The biopsy punch market functions as a service-attach opportunity where sterile disposable replenishment and preventive maintenance contracts for motorized platforms expand faster than capital hardware sales. Recurring revenue layers from sterilization validation services and calibration subscriptions deepen customer lifetime value beyond initial instrument placement.
For Market Incumbents: Entrench market position through backward integration into gamma irradiation partnerships and captive supply of medical-grade polymer compounds. Core needle biopsy systems threaten cylindrical punch share in soft-tissue applications; defensive R&D investment in laser-assisted precision technology preserves premium positioning. Capacity addition in sterilization infrastructure represents the priority defensive lever against supply-constrained competitors. For New Entrants and Emerging Players: Brazilian independent dermatology practices present the most penetrable white-space target given ANVISA harmonization reducing certificate duplication costs. Direct-to-clinic e-procurement platforms enable bypass of established distributor markups. White-label manufacturing partnerships with Shenzhen polymer fabricators offer the lowest-capital go-to-market angle for cost-optimized manual instrument entry. For Investors and Strategic Acquirers: Mid-cap disposable specialists with dedicated EU MDR regulatory affairs infrastructure represent the priority acquisition archetype. Long-term viability across the analysis window rests on sterilization protocol adaptation speed and notified body relationship depth. The signal to watch is consolidation velocity among MDR-constrained suppliers unable to fund post-market surveillance data generation for legacy device recertification.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | TÜV SÜD and BSI engagement secures recertification timelines for legacy predicate devices. |
| Gamma Irradiation Partnership Formation | EPA emissions rules strand ethylene oxide assets; sterilization capacity access determines supply security. |
| Direct-to-Clinic E-Procurement Platform Launch | Arizona and Florida dermatology clusters favor spot purchasing through digital channels over distributor networks. |
| Laser-Assisted Precision Technology Development | Seoul and Los Angeles cosmetic surgery centers validate sub-millimeter margin capabilities for expanded indications. |
| Brazil ANVISA Harmonization Certification | ISO 13485 alignment reduces entry costs for Latin American market penetration. |
Research Methodology
A standing panel of dermatology clinic procurement managers, hospital biomedical engineers, GPO contracts specialists, and sterile manufacturing quality directors provided ongoing calibration against operating reality. Primary interviews combined with secondary validation from FDA 510(k) clearance databases, EU MDR technical documentation filings, hospital procurement contract registries, and medical device trade flow customs records. Bottom-up shipment data triangulated against top-down pathology lab instrument census estimates.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation modeled by product type, application, end user, technology, and regional regulatory cluster. CAGRs derived from procedural volume elasticity to screening protocol penetration and capital equipment replacement cycles. Forecast inputs incorporated EU notified body capacity constraints and polymer feedstock price trajectory assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by platform-integrating multinational device conglomerates would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Stimulation Therapies Market
Medical Devices
North America Medical Device Regulatory Affairs Outsourcing Market
Medical Devices
Portable Dialysis Machines Market
Medical Devices
Pocket Ventilation Systems Market
Medical Devices
Peripheral Guidewires Market
Medical Devices
Canada Insulin Delivery Devices Market
Medical Devices
Tattoo Removal Lasers Market
Medical Devices
Global Brain Implants Market
Medical Devices
Vascular Closure Device (VCD) Market
Medical Devices
Electroencephalography Devices Market
Medical Devices
Neurovascular Devices Market
Medical Devices
Batteries for Skin Patches Market
Medical Devices
Colposcopes Market
Medical Devices
Mexico Spinal Surgery Devices Market
Medical Devices
Digital BTE Market
Medical Devices
Global Digital Pathology Systems Market