
 Insulin Pen Needles Market | 2026-2036
Insulin Pen Needles Market Size, Share, and Industry Trends Forecast 2026-2036
Insulin Pen Needles Market Intelligence
The ISO 11608-2 standard, which governs needle compatibility and safety for pen-injectors, is collapsing the distinction between branded and third-party needles. This compliance requirement creates a level playing field where manufacturing scale becomes critical. BD leverages its global manufacturing footprint to compete on cost and availability. Novo Nordisk A/S differentiates through integrated systems, bundling its needles with its proprietary insulin pens. Meanwhile, Ypsomed AG specializes in developing innovative injection devices for other pharmaceutical partners.
Insulin pen needles are sterile, single-use medical devices for subcutaneous insulin delivery via a pen-injector. They feature ultra-thin walls and multi-bevel tips, specifications designed to minimize patient discomfort and tissue trauma. Their primary function is to facilitate accurate and consistent dosing for individuals managing diabetes. Shorter needle lengths, particularly 4mm and 5mm, are gaining preference to reduce the risk of intramuscular injection. Demand from homecare settings and retail pharmacies is expanding rapidly, outpacing growth in traditional hospital channels.
Market access is contingent on adherence to strict medical device regulations. Compliance with the FDA's 510(k) clearance in the United States and CE marking under the Medical Device Regulation (MDR) in Europe are fundamental requirements for manufacturers. In China, the NMPA enforces its own distinct and rigorous approval process for all medical devices. Stakeholders must now prioritize strategies for navigating fragmented national reimbursement frameworks and competitive government tender systems.
Market Dynamics
The convergence of patient preference for less painful injections and regulatory mandates for device interoperability is the central force shaping the market. This dynamic pressures manufacturers to innovate on needle design while complying with standards like ISO 11608-2, creating a more uniform competitive landscape.
Growth Catalysts
- Expanding Homecare Settings:National health policies promoting self-management of chronic conditions are increasing demand from patients self-administering insulin, particularly in home environments and via retail pharmacy channels.
- Technological Advancements in Needle Design:The development of ultra-fine gauge needles and multi-bevel tips reduces injection pain and tissue trauma, which directly improves patient adherence to prescribed insulin regimens.
- High Diabetes Prevalence:The growing diabetic population, especially in high-density countries such as India and China, creates a sustained and expanding user base for insulin delivery devices.
Market Restraints
- Alternative Delivery Systems:The emergence of insulin pumps and patch-based delivery technologies presents a long-term substitution threat, offering users an alternative to daily injections.
- Reimbursement Pressure:National health systems and large group purchasing organizations exert significant downward pressure on pricing, limiting manufacturer margins, especially for standard-length needles.
- Fragmented Regulatory Pathways:Navigating disparate and rigorous approval processes, such as the FDA's 510(k) and China's NMPA requirements, increases time-to-market and compliance costs for manufacturers.
Strategic Opportunities
- Smart Needle Development:Integration of connectivity features into pen needles to create "smart" devices that can log dosage data and sync with mobile health apps represents a key innovation frontier.
- Emerging Market Penetration:Significant growth potential exists in markets across Southeast Asia and Latin America, where diabetes incidence is rising but pen needle adoption remains below European levels.
- Digital Distribution Channels:Building direct-to-consumer e-commerce platforms offers a new channel to reach patients, bypassing traditional distribution intermediaries for certain product categories and improving access.
Industry Challenges
- Manufacturing Scalability:Achieving the massive production scale required to compete on cost, while maintaining tight tolerances for ultra-fine needles, presents a significant capital expenditure challenge.
- Raw Material Constraints:Dependence on a limited number of suppliers for high-grade surgical steel for cannula production creates vulnerability to price fluctuations and supply disruptions.
- Sterilization Compliance:Adhering to evolving global standards for medical device sterilization and packaging integrity requires continuous investment in quality control and validation processes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insulin Pen Needles Market |
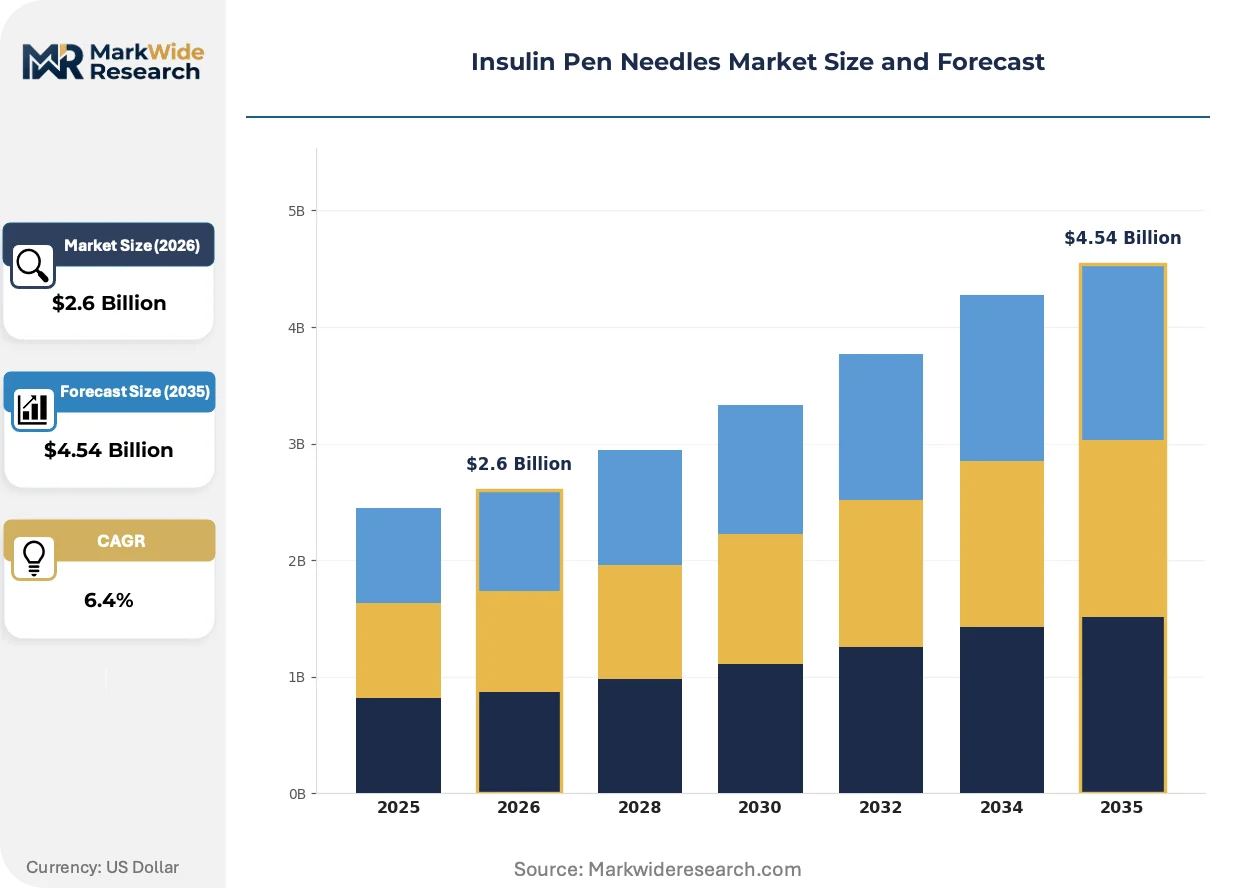
| Market Size in 2026 | $2.6 Billion |
| Market Size in 2035 | $4.54 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Needle Length: 4 mm, 5 mm, 6 mm, 8 mm, 10 mm Gauge Size: 31G, 32G, 33G, 34G Application: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Latent Autoimmune Diabetes End User: Hospitals, Specialty Clinics, Retail Pharmacies, Homecare Settings |
| Companies Covered | B. Braun SE, Terumo Corporation, Embecta Corp., HTL-STREFA, Owen Mumford, Novo Nordisk A/S, BD, UltiMed, Inc., Ypsomed AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insulin Pen Needles Market Strategic Shifts & Innovations
The market's innovation trajectory is defined by a deep focus on improving the patient experience and integrating injection events into digital health ecosystems. This patient-centric shift influences everything from physical product design to regulatory compliance strategies across major markets.
Ultra-thin wall technology enables a larger inner diameter within a finer gauge needle, improving insulin flow while reducing the needle's external profile. Patients in homecare settings, especially pediatric users, are the primary adopters due to the significant reduction in injection pain. This technological drive is miniaturizing the physical point of patient contact, which enhances user comfort and supports better long-term adherence to therapy.
Europe’s Medical Device Regulation (MDR) elevates requirements for clinical evidence, post-market surveillance, and supply chain transparency for all medical devices. This regulation forces manufacturers to invest heavily in generating robust clinical data to secure and maintain CE marking. Third-party needle producers face the most significant impact, as they must now rigorously document performance equivalency to meet the heightened scrutiny.
Patient purchasing behavior is moving towards online pharmacies and direct-to-consumer subscription models for replenishing supplies. This pattern disrupts the role of traditional retail pharmacies, creating an advantage for manufacturers with sophisticated e-commerce and fulfillment operations. The shift is most pronounced in the United States and Western European countries with well-established digital commerce infrastructure.
Insulin Pen Needles Market Segmentation
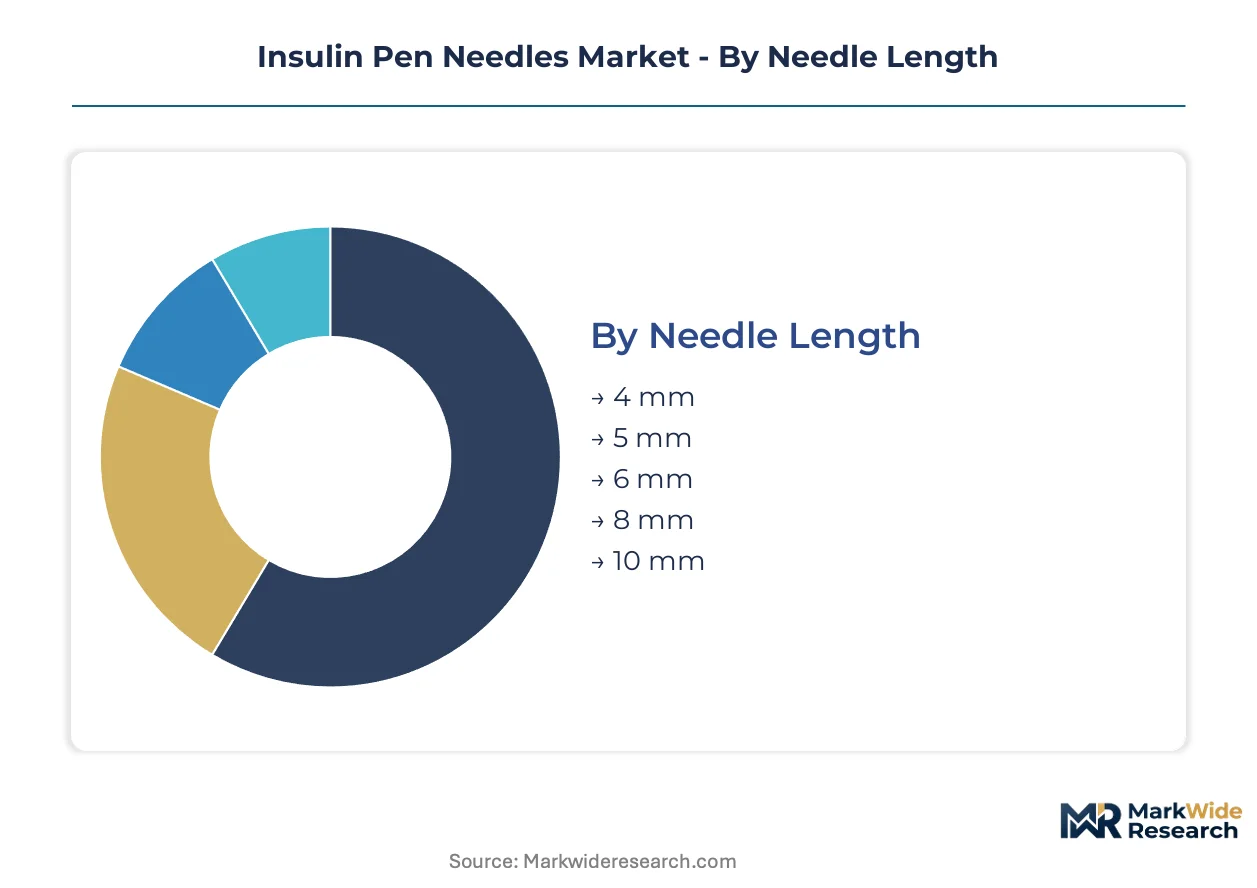
The insulin pen needles market categorizes product offerings and user groups to understand demand patterns. This segmentation highlights specific patient needs and commercial opportunities for manufacturers. Analyzing these distinct segments reveals where innovation and market access strategies are most effective.
Needle Length:
Margin pools sit with finer, shorter needle lengths due to enhanced patient preference and technological differentiation.
- 4 mm:These ultra-short needles are designed to minimize pain and reduce the risk of intramuscular injection, making them highly preferred by pediatric and adult patients. Demand is concentrating in homecare settings, driven by increased self-administration of insulin.
- 5 mm:Offering a balance between comfort and effective subcutaneous delivery, 5mm needles are widely adopted across various patient populations. This length is favored in European markets due to established clinical guidelines promoting shorter needles.
- 6 mm:A traditional needle length, 6mm products offer reliable insulin delivery for a broad user base. These needles maintain a consistent presence in retail pharmacy channels.
- 8 mm:These standard-length needles are utilized for patients requiring deeper subcutaneous penetration, particularly those with higher body mass index. Hospitals and specialty clinics maintain consistent procurement volumes for 8mm needles.
- 10 mm:The longest available pen needle, 10mm is used for specific clinical indications where deeper tissue access is necessary. This segment sees stable demand from specialized medical facilities.
8 mm needles hold installed capacity. 4 mm needles are rotating up the share rankings.
Gauge Size:
Volume distribution across gauge sizes reflects a shift towards thinner needles for improved patient experience.
- 34G:Representing the finest gauge available, 34G needles offer the least painful injection experience due to their ultra-thin profile. This segment experiences high demand from patients prioritizing comfort and from pediatric diabetes care programs.
- 33G:These fine-gauge needles provide a good balance of comfort and insulin flow, appealing to a wide range of patients. Adoption is increasing in countries like Germany and the UK, where patient-centric care is emphasized.
- 32G:A common fine-gauge option, 32G needles are widely used for daily insulin injections. This gauge size maintains a significant presence in retail pharmacy sales.
- 31G:These standard-gauge needles are robust and widely available, serving a large base of insulin users. Hospitals and older patient demographics frequently utilize 31G needles.
The 34G segment is expanding most quickly, driven by patient comfort priorities.
Application:
The primary application areas for insulin pen needles directly correlate with global diabetes prevalence patterns.
- Type 1 Diabetes:Individuals with Type 1 Diabetes require lifelong insulin therapy, making this a consistent and foundational application segment. Patient compliance is critical, driving demand for less painful needle designs.
- Type 2 Diabetes:This application represents the largest and fastest-growing segment due to the rising global incidence of Type 2 Diabetes. Homecare settings are a primary channel for insulin pen needle distribution to these patients.
- Gestational Diabetes:Temporary insulin therapy for pregnant individuals with gestational diabetes utilizes pen needles for precise dosing. This application sees cyclical demand linked to birth rates.
- Latent Autoimmune Diabetes:Patients with Latent Autoimmune Diabetes in Adults (LADA) require insulin therapy similar to Type 1, contributing to steady demand. Specialty clinics often manage LADA patients.
Type 2 Diabetes applications command the largest market share.
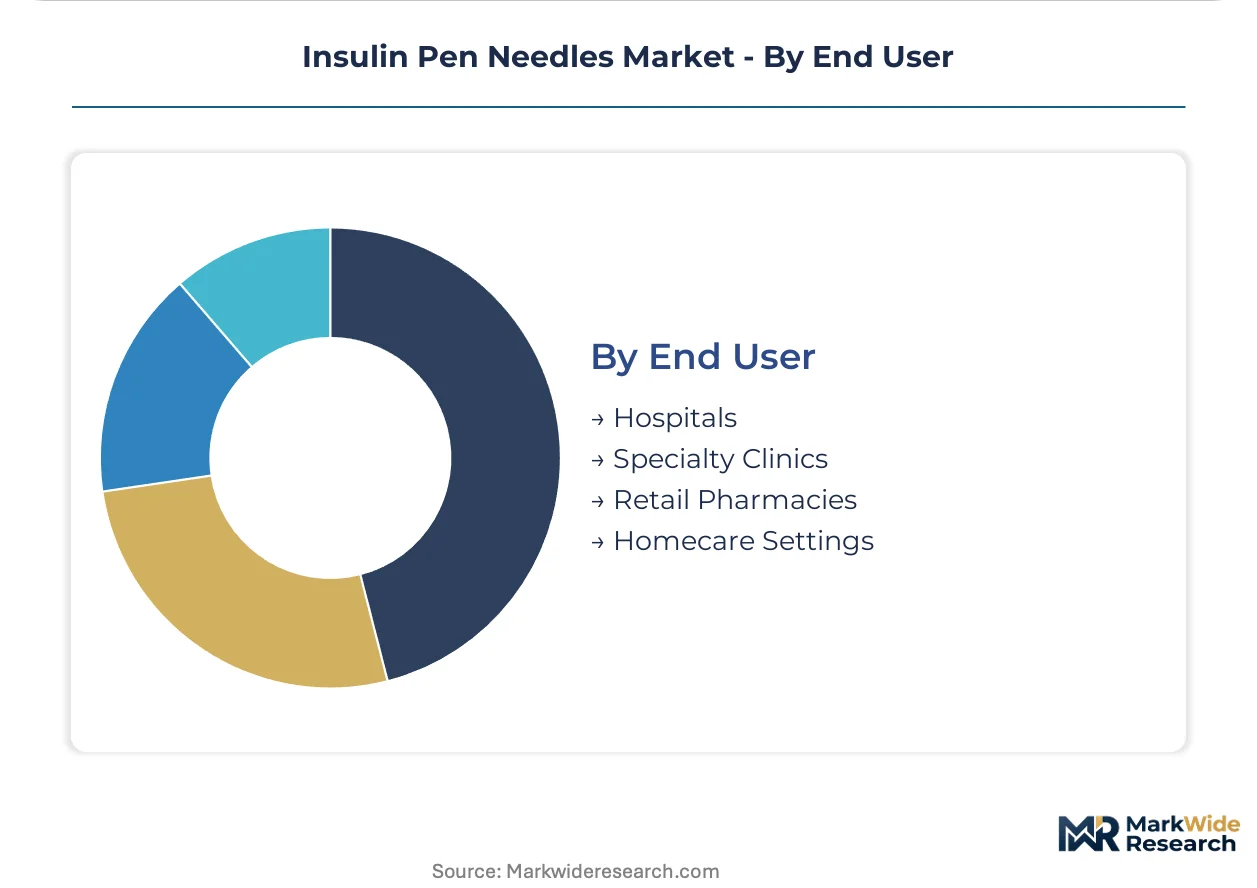
End User:
The customer base for insulin pen needles is rapidly shifting towards decentralized care models and direct patient access.
- Hospitals:Acute care facilities and inpatient settings utilize insulin pen needles for controlled administration to hospitalized patients. Procurement through group purchasing organizations often dictates product selection.
- Specialty Clinics:Diabetes clinics and endocrinology practices serve as key points of prescription and education for pen needle users. These clinics often influence patient choice and product recommendations.
- Retail Pharmacies:Pharmacies provide convenient access to insulin pen needles for patients managing diabetes at home. This channel is crucial for regular replenishment and over-the-counter sales in many regions.
- Homecare Settings:This segment is experiencing significant expansion as more patients self-administer insulin in their residences. Digital distribution channels and subscription models are increasingly serving homecare users.
Homecare settings are demonstrating the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extensive pharmaceutical supply chain networks underpin the global distribution of insulin pen needles, ensuring patient access. These established logistical pathways facilitate movement of essential medical devices from manufacturing hubs to end-user settings.
China
China's vast diabetic population drives substantial demand for insulin pen needles, particularly in expanding homecare settings. The NMPA enforces rigorous approval processes for all medical devices, influencing market entry. Manufacturing hubs in the Yangtze River Delta concentrate production for both domestic consumption and export.
India
India's escalating diabetes burden creates significant demand for affordable insulin pen needles across urban and rural areas. The CDSCO regulates medical device quality and market access, impacting both local and international manufacturers. Hyderabad's growing medical technology cluster sees increasing investment in localized production.
United States
The United States market exhibits strong demand for advanced, patient-friendly insulin pen needles, especially shorter lengths. FDA 510(k) clearance remains a fundamental requirement for market entry and product commercialization. Medtech innovation hubs in Boston and California drive development of next-generation injection devices.
Germany
Germany maintains high adoption rates for insulin pen needles, with a strong preference for 5mm lengths due to patient comfort initiatives. CE marking under the Medical Device Regulation (MDR) sets stringent requirements for product quality and clinical evidence. Medical device clusters in Bavaria and North Rhine-Westphalia foster specialized manufacturing and research.
Brazil
Brazil's expanding diabetic population fuels demand for insulin pen needles, supported by public health initiatives. ANVISA regulates medical device registration and post-market surveillance, influencing market access for manufacturers. São Paulo serves as a central hub for pharmaceutical distribution, reaching a wide patient base.
Insulin Pen Needles Market Key Industry Players
Listed leaders compete with private specialists across product innovation and global distribution capabilities. The market demonstrates a tiered structure, encompassing integrated pharmaceutical companies, pure-play medical device specialists, and regional manufacturers. These archetypes often pursue portfolio diversification to capture adjacent opportunities. Geographic expansion into emerging markets and strategic partnerships for technology development are common competitive moves.
Integrated pharmaceutical and medical device giants like BD and Novo Nordisk A/S exemplify the scale-driven approach, leveraging extensive global manufacturing footprints. BD competes on cost and broad availability, utilizing its established presence to maintain market share. Novo Nordisk A/S differentiates through bundled, integrated systems, offering proprietary insulin pens paired with their needles. Ypsomed AG, a Swiss-based company, occupies a position as a specialist in developing innovative injection devices for other pharmaceutical partners, highlighting a focus on B2B solutions and custom engineering.
| Leading Market Players |
|---|
| B. Braun SE |
| Terumo Corporation |
| Embecta Corp. |
| HTL-STREFA |
| Owen Mumford |
| Novo Nordisk A/S |
| BD |
| UltiMed, Inc. |
| Ypsomed AG |
| Others |
Cost & Logistics Intelligence
The shift from traditional needle designs to advanced ultra-thin wall technology is reshaping manufacturing processes and simultaneously influencing supply chain concentration and pricing dynamics.
Pricing Analysis
Volume-based discount tiering structures define insulin pen needle pricing across most markets. Price differentiation stems from factors like gauge size, with finer 34G needles commanding a premium, and the specific regulatory certifications achieved. National health systems and large group purchasing organizations exert significant downward pressure on pricing, particularly for standard-length needles. Patient segments in homecare settings, especially for over-the-counter purchases, exhibit higher price sensitivity compared to hospitals procuring specialized lengths.
Supply Chain Analysis
Maintaining optimal inventory levels and managing lead times are critical for ensuring consistent supply of sterile insulin pen needles. Geographic supply concentration for production centers in China's Yangtze River Delta, Germany's medical device clusters, and specialized facilities in the United States. The industry relies heavily on a limited number of suppliers for high-grade surgical steel, creating vulnerability to raw material constraints and price volatility. Distribution centers on retail pharmacies and direct-to-consumer channels, alongside established hospital procurement networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The insulin pen needles market is in an early-cycle expansion phase, driven by the increasing patient preference for less painful injections and self-administration in homecare settings.
For Market Incumbents:Fortify core market positions by accelerating investment in ultra-fine gauge needle R&D to counter the long-term threat from alternative insulin delivery systems. Expand global manufacturing footprints strategically, particularly in emerging markets, to achieve cost leadership and navigate fragmented regulatory pathways. Deepen upstream control over critical raw materials like specialized surgical steel to mitigate supply chain risks and ensure production continuity.
For New Entrants and Emerging Players:Anchor in underserved emerging markets where diabetes incidence is rising and pen needle adoption remains lower than in developed economies. Target the rapidly expanding homecare segment with patient-centric designs, such as 4mm and 5mm needles, focusing on comfort and ease of use. Leverage digital distribution channels and direct-to-consumer e-commerce platforms to build brand recognition and bypass traditional intermediaries.
For Investors and Strategic Acquirers:Capital is best deployed toward innovative medical device specialists demonstrating robust intellectual property in pain-reducing needle designs or digital health integration capabilities. Focus on companies with strong regulatory compliance track records and established market access in key geographies like Europe and the United States. A signal to watch is increased M&A activity targeting firms with proprietary smart needle technology or advanced manufacturing automation.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Gauge R&D | Develop next-generation ultra-fine needles for improved patient comfort and adherence. |
| Digital Distribution Channel Expansion | Establish direct-to-consumer platforms to reach homecare patients and bypass traditional retail. |
| Emerging Market Regulatory Navigation | Prioritize NMPA and ANVISA approvals to access high-growth diabetic populations. |
| Smart Needle Technology Integration | Incorporate connectivity features for dosage logging and mobile health app synchronization. |
| Manufacturing Scale Optimization | Invest in automated production lines to achieve cost leadership for high-volume standard needles. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and extensive secondary validation from published sources. Primary insights came from conversations with device manufacturers, hospital procurement managers, endocrinologists, and retail pharmacy buyers. Secondary data included FDA 510(k) filings, CE marking documentation, national health system reports, and diabetes association statistics, triangulated using both bottom-up and top-down approaches.
The forecast framework modeled market dynamics across the analysis window, segmenting by needle length, gauge size, application, and end-user, alongside regional regulatory clusters. Compound annual growth rates were derived from historical data and projected growth drivers, incorporating industry-specific forecast inputs such as diabetes prevalence rates and homecare adoption trends.
Decision-makers should treat outputs as directional under stable regulatory environments and consistent diabetes management protocols; material deviation would warrant model refresh. Forecasts acknowledge potential risks from the emergence of non-injectable insulin technologies or major shifts in reimbursement policies. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Brazil Blood Glucose Monitoring Market
Diabetes Care
Iran Diabetes Care Devices Market
Diabetes Care
Global Blood Glucose Monitoring Systems Market
Diabetes Care
Asia Pacific Blood Glucose Monitoring Market
Diabetes Care
Diabetic Pen Cap Market
Diabetes Care
BRICS Diabetes Treatment and Prevention Market
Diabetes Care
New Zealand Continuous Glucose Monitoring Devices Market
Diabetes Care
Global Pet Diabetes Care Market
Diabetes Care
Global Diabetic Foot Ulcer Treatment Market
Diabetes Care
North America Oral Anti-Diabetic Drug Market
Diabetes Care
Next Generation Diabetes Therapy and Drug Delivery Market
Diabetes Care
Blood Glucose Monitoring Devices Market
Diabetes Care
Global Diabetes Pen Market
Diabetes Care
South Korea Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Latin America Diabetes Care Devices Market
Diabetes Care
BRIC Diabetes Care Devices Market