
 BRICS Diabetes Treatment and Prevention Market | 2026-2036
BRICS Diabetes Treatment and Prevention Market Size, Share, and Industry Trends Forecast 2026-2036
BRICS Diabetes Treatment and Prevention Market Outlook
The manufacturing scale gap between multinational biologics producers and domestic generic houses is bifurcating competitive dynamics across the BRICS diabetes landscape. Novo Nordisk leverages its recombinant insulin fermentation infrastructure to dominate the GLP-1 agonist segment in Brazil and Russia. Biocon Ltd anchors its position through in-house production of biosimilar insulins, competing on cost in India's price-sensitive hospital procurement channels.
Diabetes treatment and prevention encompasses pharmacological interventions, glucose monitoring systems, and lifestyle modification programs designed to regulate blood glucose levels and prevent diabetic complications through HbA1c target achievement below 7%. The field serves clinical endocrinology, primary care, and public health systems managing chronic metabolic disease burdens. Insulin and GLP-1 agonists command the deepest margin pools due to biologics manufacturing complexity and patent-protected pricing, while SGLT2 inhibitors represent the fastest-growing oral therapy class as cardiorenal outcome data expands reimbursable indications. Delivery mode segmentation shows injection platforms sustaining the largest revenue share, though transdermal patches are gaining traction in homecare settings across China's aging urban populations.
India's CDSCO and China's NMPA operate divergent approval pathways for biosimilar insulins, with CDSCO's abbreviated review process accelerating market entry for domestic manufacturers while NMPA enforces stricter comparability studies that favor established multinationals. Brazil's ANVISA recently aligned its glucose monitoring device standards with ISO 15197, tightening accuracy thresholds that reshape product eligibility for public health system tenders. Stakeholders must monitor how BRICS national pricing authorities calibrate reimbursement between patented biologics and emerging biosimilar portfolios.
Market Dynamics
Hospital procurement systems across Brazil and India are consolidating purchasing power around biosimilar insulin portfolios, compressing margins for originator biologics while accelerating domestic manufacturing scale-up through production-linked incentive frameworks.
Growth Catalysts
- China's NMPA Accelerated Review Pathway:Streamlined biosimilar approval timelines for GLP-1 agonists are shortening commercialization cycles for domestic developers targeting tier-one city hospital networks.
- Cardiorenal Outcome Data Expansion:SGLT2 inhibitor reimbursement broadening across Russia's mandatory health insurance system is pulling prescribing patterns away from sulfonylureas in high-risk patient cohorts.
- Continuous Glucose Monitoring Integration:Homecare settings in China's aging urban populations are adopting sensor-based glucose tracking, creating pull-through demand for interoperable insulin delivery devices.
Market Restraints
- Recombinant Protein Fermentation Capacity Concentration:Brazil and India remain dependent on imported active pharmaceutical ingredients for analog insulin production, exposing supply continuity to geopolitical trade friction.
- ANVISA Device Accuracy Threshold Alignment:Brazil's tightened ISO 15197 glucose monitoring standards are disqualifying legacy meter models from public health system tenders, forcing portfolio rationalization.
- Biologics Cold Chain Infrastructure Gaps:Last-mile temperature-controlled distribution in Russia's interior regions limits GLP-1 agonist reach, constraining addressable patient populations outside major urban clusters.
Strategic Opportunities
- India's PLI Scheme for API Manufacturing:Domestic fermentation capacity expansion incentives are enabling backward integration into recombinant insulin production, reducing import dependency for hospital procurement channels.
- Transdermal Patch Delivery Convergence:Microneedle array technology combined with continuous glucose monitoring algorithms is opening non-injection insulin administration pathways for needle-averse patient segments.
- Tier-Two City Clinic Network Penetration:Underdeveloped diabetes specialist infrastructure in China's interior provinces presents whitespace for standardized care protocol rollout through telemedicine-linked hub-and-spoke models.
Industry Challenges
- Biosimilar Comparability Study Talent Scarcity:Russia and Brazil lack sufficient clinical immunogenicity assessment specialists to support abbreviated regulatory filings, extending approval timelines for domestic developers.
- Legacy Hospital Information System Interoperability:Electronic health record fragmentation across India's state-level health programs complicates centralized diabetes registry construction for population health management.
- Patent Cliff Litigation Complexity:GLP-1 agonist biosimilar entrants face originator defensive patent thickets that delay market entry despite expired composition-of-matter protections.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | BRICS Diabetes Treatment and Prevention Market |
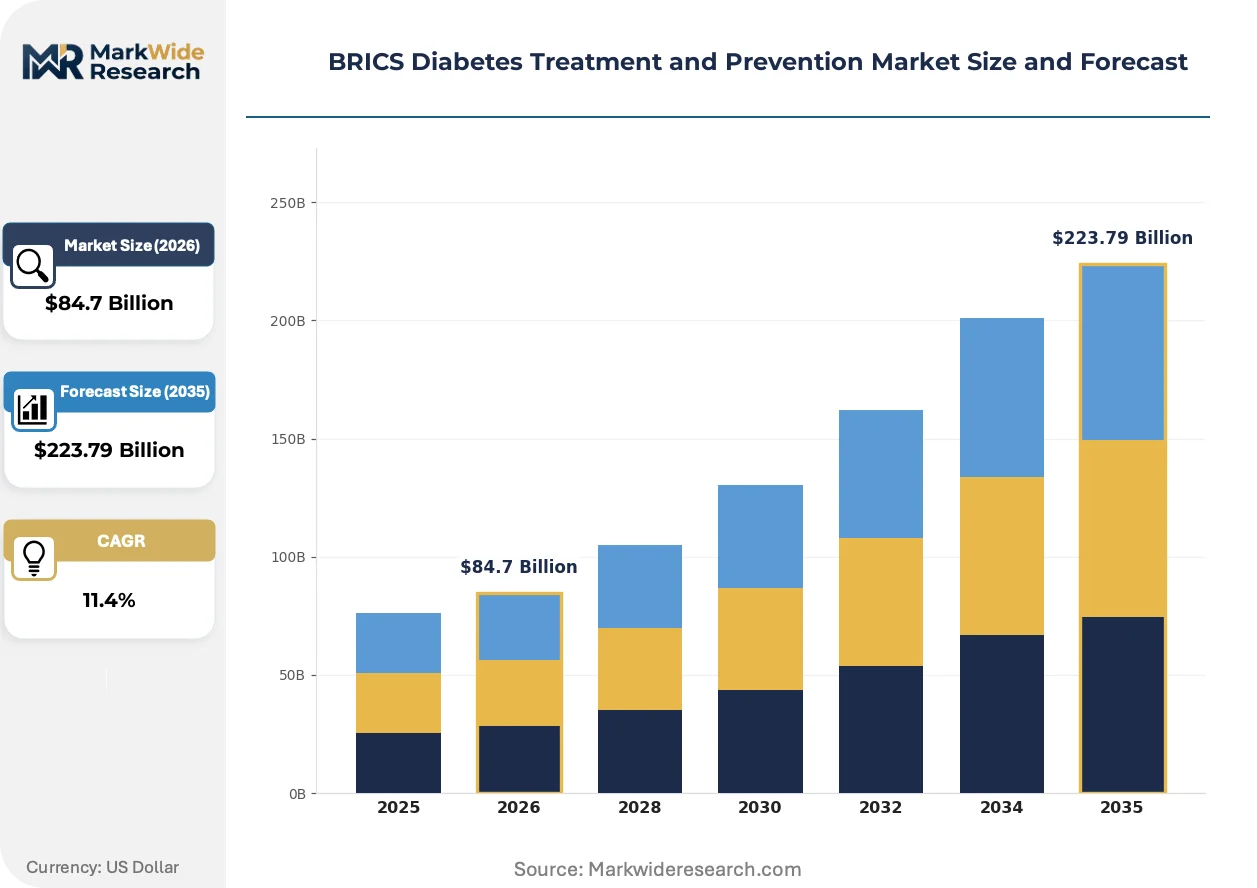
| Market Size in 2026 | $84.7 Billion |
| Market Size in 2035 | $223.79 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin, Metformin, GLP-1 Agonists, SGLT2 Inhibitors Delivery Mode: Injection, Oral, Intranasal, Transdermal End User: Hospitals, Clinics, Homecare, Retail Pharmacies Application: Type 1 Diabetes, Type 2 Diabetes, Prediabetes, Gestational Diabetes |
| Companies Covered | Roche, Bristol-Myers Squibb, Novo Nordisk, Aurobindo Pharma Ltd, Biocon Ltd, Sanofi, Boehringer Ingelheim, Takeda Pharmaceutical Company, Abbott Laboratories, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
BRICS Diabetes Treatment and Prevention Market Strategic Shifts
Digital therapeutics and connected device ecosystems are reconfiguring how glucose management interventions are delivered, reimbursed, and integrated into chronic care workflows across the five BRICS markets.
Dual-hormone artificial pancreas systems combining insulin and glucagon delivery algorithms are fragmenting the traditional insulin pump market. Pediatric endocrinology units in Brazil's São Paulo and Rio de Janeiro hospital networks are piloting closed-loop configurations. This technology is fragmenting competitive positioning among established pump manufacturers as software-enabled glycemic control displaces hardware-centric differentiation.
India's CDSCO abbreviated biosimilar review framework is compressing regulatory timelines for insulin analog developers. Domestic manufacturers leveraging this pathway are securing hospital tender awards ahead of multinationals completing full comparability studies. The CDSCO pathway most acutely affects basal insulin segments where price sensitivity in government procurement channels favors accelerated entrants.
Hospital pharmacy committees across China's tier-one cities are consolidating formularies around single-source GLP-1 agonist contracts. Volume-based procurement is displacing multi-brand stocking in favor of exclusive supplier arrangements with steep unit price concessions. This concentration is most visible in Shanghai and Beijing where municipal health bureaus pilot centralized purchasing for chronic disease medications.
BRICS Diabetes Treatment and Prevention Market Segmentation
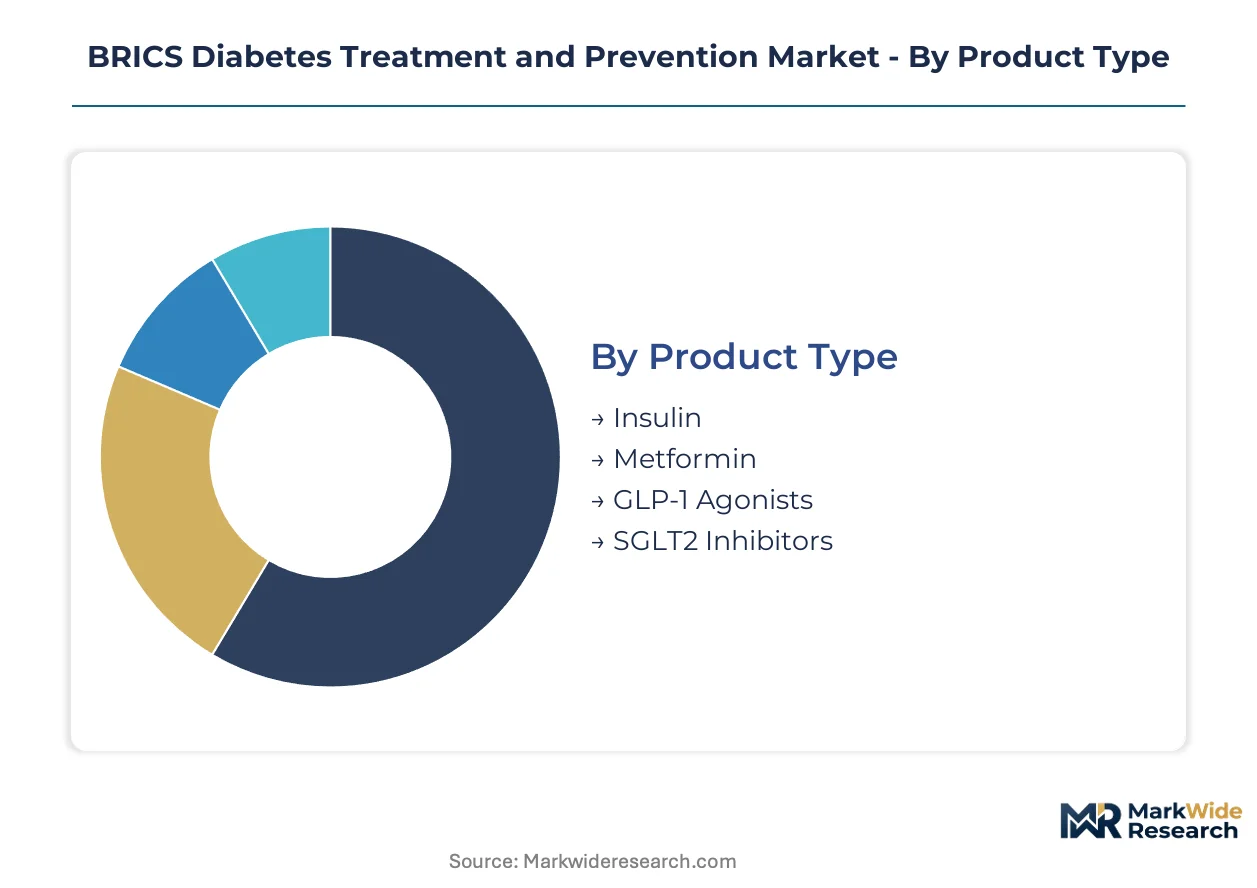
Segmentation in the BRICS diabetes market reveals divergent supply chains and regulatory pathways across product classes and delivery platforms. Understanding these divisions illuminates where domestic manufacturing incentives reshape procurement patterns versus where multinational patent portfolios still command pricing power.
Product Type:
Domestic fermentation capacity concentrates insulin and biosimilar development in India and China, while GLP-1 agonists and SGLT2 inhibitors remain import-dependent across Brazil and Russia.
- Insulin:Recombinant human and analog insulin production anchors India's PLI-backed manufacturing expansion. Hospital procurement in Brazil and India consolidates purchasing around biosimilar portfolios, compressing margins for originator biologics while accelerating domestic scale-up.
- Metformin:The foundational oral therapy for Type 2 diabetes management commands universal formulary inclusion across BRICS public health systems. China's NMPA maintains abbreviated approval pathways for metformin generics, enabling rapid market saturation and price erosion in tier-one city hospital networks.
- GLP-1 Agonists:Patent-protected biologics dominate Brazilian and Russian hospital formularies; CDSCO's accelerated review pathway enables Indian domestic developers to challenge this concentration.
- SGLT2 Inhibitors:Cardiorenal outcome data expansion drives reimbursement broadening across Russia's mandatory health insurance system, pulling prescribing patterns away from sulfonylureas in high-risk cohorts.
Insulin holds the largest share; momentum sits with SGLT2 inhibitors as cardiorenal indications expand reimbursable patient pools.
Delivery Mode:
Cost tier stratification separates premium injection systems from economy oral tablets, with emerging transdermal platforms targeting needle-averse segments in China's aging urban populations.
- Injection:Pen devices and syringes sustain the deepest revenue pools due to biologics manufacturing complexity and cold chain requirements. Brazil's ANVISA device accuracy standards tighten eligibility for public health system tenders, forcing portfolio rationalization among meter and pen manufacturers.
- Oral:Metformin and SGLT2 inhibitor tablets dominate volume prescriptions across primary care networks in India and China. Price erosion from domestic generic competition compresses margins, though volume scale sustains manufacturer participation in government procurement channels.
- Intranasal:Limited commercial penetration; developmental programs target needle-averse pediatric and geriatric segments in Russia's major urban clusters.
- Transdermal:Microneedle array technology combined with continuous glucose monitoring algorithms opens non-injection insulin administration pathways. Homecare adoption concentrates in China's tier-one cities where disposable income supports premium device uptake.
Injection platforms command premium pricing; transdermal delivery is climbing the fastest as sensor integration matures.
End User:
Customer type determines reimbursement pathway complexity, with hospital procurement consolidating volume while homecare channels fragment across retail and direct-to-patient models.
- Hospitals:Tertiary care centers in São Paulo, Mumbai, and Shanghai anchor GLP-1 agonist prescribing. Volume-based procurement in China's tier-one cities displaces multi-brand stocking in favor of exclusive supplier arrangements with steep unit price concessions.
- Clinics:Primary care and diabetes specialist networks in India's state-level health programs manage the bulk of Type 2 diabetes diagnoses. Electronic health record fragmentation complicates centralized registry construction for population health management.
- Homecare:Continuous glucose monitoring integration creates pull-through demand for interoperable insulin delivery devices. Sensor-based glucose tracking adoption concentrates in China's aging urban populations with sufficient disposable income.
- Retail Pharmacies:Out-of-pocket metformin and insulin purchases dominate in Brazil's supplementary health system gaps and India's uninsured population segments.
Hospitals retain the largest share; homecare channels are gaining share fastest as remote monitoring infrastructure penetrates BRICS urban centers.
Application:
Disease severity and progression stage dictate therapy intensity, with Type 2 diabetes volume overwhelming specialized segments despite lower per-patient revenue.
- Type 1 Diabetes:Lifelong insulin dependence sustains predictable demand for analog formulations and pump delivery systems. Pediatric endocrinology units in Brazil's São Paulo and Rio de Janeiro hospital networks pilot dual-hormone artificial pancreas configurations.
- Type 2 Diabetes:The predominant metabolic disease burden across BRICS populations drives oral therapy volume and late-stage insulin initiation. India's price-sensitive hospital procurement channels favor cost-optimized biosimilar insulin entry.
- Prediabetes:Lifestyle intervention and metformin prophylaxis programs remain underpenetrated relative to diagnosed diabetes prevalence. China's municipal health bureaus pilot standardized care protocol rollout through telemedicine-linked hub-and-spoke models in tier-two cities.
- Gestational Diabetes:Specialized maternal-fetal medicine protocols concentrate in urban tertiary centers; insulin therapy preference over oral agents aligns with fetal safety guidelines across ANVISA and CDSCO regulatory frameworks.
Type 2 Diabetes holds the largest share; momentum sits with Prediabetes as screening expansion and digital therapeutics enable earlier intervention capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement channels in India and Brazil exhibit extreme price elasticity, squeezing margins on originator biologics, while China's tier-one cities absorb premium GLP-1 agonist pricing with limited volume sensitivity. Russia's interior regions face cold chain infrastructure constraints that distort effective demand regardless of patient need.
Brazil
ANVISA's tightened ISO 15197 glucose monitoring standards are disqualifying legacy meter models from public health system tenders. São Paulo's hospital networks anchor GLP-1 agonist prescribing, with municipal health bureaus consolidating volume around exclusive supplier arrangements. Rio de Janeiro's pediatric endocrinology units pilot dual-hormone artificial pancreas configurations.
Russia
Mandatory health insurance reimbursement expansion for SGLT2 inhibitors is pulling prescribing patterns away from sulfonylureas in high-risk cardiovascular cohorts. Last-mile temperature-controlled distribution gaps in interior regions constrain GLP-1 agonist reach outside Moscow and St. Petersburg. The country's national pharmaceutical regulator enforces stricter comparability studies for biosimilar insulins than India's abbreviated pathway.
India
CDSCO's accelerated biosimilar review framework compresses regulatory timelines for insulin analog developers, enabling domestic manufacturers to secure hospital tender awards ahead of multinationals. Maharashtra's state-level health programs manage the bulk of Type 2 diabetes diagnoses through fragmented electronic health record systems. Karnataka's Biocon Ltd anchors in-house production of biosimilar insulins for price-sensitive procurement channels.
China
NMPA's streamlined biosimilar approval timelines for GLP-1 agonists shorten commercialization cycles for domestic developers targeting tier-one city hospital networks. Shanghai and Beijing municipal health bureaus pilot centralized volume-based purchasing that displaces multi-brand stocking. The Yangtze River Delta's aging urban populations drive sensor-based glucose tracking adoption in homecare settings.
South Africa
Public health system procurement concentrates metformin and human insulin volume through centralized tender processes, with limited biosimilar penetration compared to India. Western Cape Province's tertiary centers manage complex Type 1 diabetes cases through referral networks from under-resourced rural clinics. The country's national pricing authority calibrates reimbursement between patented biologics and emerging generic portfolios.
BRICS Diabetes Treatment and Prevention Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with fermentation-capable biologics producers commanding pricing power while domestic generic houses compete on cost in government procurement channels. The structure bifurcates between patent-protected GLP-1 agonist developers and biosimilar insulin manufacturers. Three archetypes dominate: multinational biologics leaders with recombinant protein infrastructure, domestic fermentation specialists leveraging abbreviated regulatory pathways, and diversified pharmaceutical conglomerates with hospital formulary relationships. Capacity expansion and strategic partnerships with continuous glucose monitoring device makers represent the dominant competitive moves.
Within the multinational biologics tier, Novo Nordisk and Sanofi occupy positions anchored by recombinant insulin fermentation infrastructure across Brazil and Russia. Roche exemplifies the diagnostics-integrated archetype through glucose monitoring ecosystem control. Among India-based specialists, Biocon Ltd and Aurobindo Pharma Ltd represent the domestic biosimilar manufacturing cluster competing on cost in government hospital tenders.
| Leading Market Players |
|---|
| Roche |
| Bristol-Myers Squibb |
| Novo Nordisk |
| Aurobindo Pharma Ltd |
| Biocon Ltd |
| Sanofi |
| Boehringer Ingelheim |
| Takeda Pharmaceutical Company |
| Abbott Laboratories |
| Others |
Value Chain & Pricing Dynamics
ANVISA's ISO 15197 alignment for glucose monitoring devices gates both product qualification for Brazil's public health tenders and price differentiation between legacy meter models and next-generation continuous sensors, compressing margins on non-compliant portfolios while enabling premium positioning for accuracy-certified systems.
Pricing Analysis
After-sales revenue from continuous glucose monitoring sensor subscriptions and insulin delivery device consumables drives lifetime patient value beyond initial hardware placement. Three-tier pricing structure across premium closed-loop systems, standard pen-based injection platforms, and economy vial-and-syringe configurations separates reimbursement-eligible hospital formularies from out-of-pocket retail channels. Cost compression in India's government procurement runs through PLI-backed domestic biosimilar manufacturing, eroding originator insulin margins. Hospital systems exhibit extreme price sensitivity, while China's aging urban homecare segments absorb premium device pricing with limited volume elasticity.
Supply Chain Analysis
Recombinant protein fermentation capacity concentration in Denmark, India, and China underwrites global insulin and GLP-1 agonist production, with active pharmaceutical ingredient sourcing drawing from specialized bioreactor facilities in Maharashtra and the Yangtze River Delta. Cold chain logistics dependencies, glucose sensor semiconductor components, and sterilized injection device polymers anchor input requirements. Single-source vulnerability in temperature-controlled last-mile distribution for Russia's interior regions constrains product reach. Distribution runs through hospital procurement consortia in tier-one cities, state-level tender processes, and direct-to-patient specialty pharmacy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market exhibits cyclical recovery characteristics as cardiorenal outcome data expansion pulls prescribing patterns toward SGLT2 inhibitors and GLP-1 agonists, creating replacement demand cycles that favor manufacturers with outcome-linked reimbursement capabilities.
For Market Incumbents: Fortify recombinant fermentation infrastructure through capacity addition in India's PLI-designated zones, defending against CDSCO-accelerated biosimilar entrants capturing government hospital tenders. Anchor hospital formulary control through exclusive volume-based procurement contracts in China's municipal health bureaus, neutralizing price erosion from multi-brand stocking displacement.
For New Entrants and Emerging Players: CDSCO's abbreviated biosimilar review pathway enables accelerated hospital tender penetration in India's price-sensitive procurement channels, the most penetrable segment for domestic insulin analog developers. Target tier-two city clinic networks in China's interior provinces through telemedicine-linked hub-and-spoke models, exploiting whitespace in standardized diabetes care protocols. Pursue go-to-market alignment with continuous glucose monitoring device interoperability standards to capture sensor-integrated delivery system demand.
For Investors and Strategic Acquirers: NMPA's streamlined GLP-1 agonist approval timelines reshape the acquisition landscape toward domestic Chinese developers with tier-one city hospital network relationships, positioning them for volume-based procurement concentration. Fermentation-capable mid-cap specialists with backward-integrated API production represent the priority acquisition archetype over pure marketing plays. Monitor ANVISA device accuracy threshold enforcement as the signal indicating portfolio rationalization pressure on legacy meter manufacturers and consolidation opportunity timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | CDSCO abbreviated biosimilar review accelerates market entry ahead of full comparability studies. |
| Manufacturing Scale-Up | PLI-backed fermentation capacity expansion in India reduces import dependency for hospital procurement. |
| Hospital System Partnership | Exclusive supplier arrangements with Shanghai municipal health bureaus displace multi-brand stocking. |
| Software Companion Development | Continuous glucose monitoring algorithm integration enables closed-loop insulin delivery differentiation. |
| Reimbursement Strategy | Cardiorenal outcome data expansion broadens SGLT2 inhibitor coverage across Russia's mandatory insurance system. |
Study Parameters
The analysis maps insulin analogs, GLP-1 agonists, SGLT2 inhibitors, and glucose monitoring devices, each validated through hospital procurement managers, formulary directors, regulatory affairs leads, and CDSCO/NMPA submission specialists. Primary interviews with state-level health program administrators and continuous glucose monitoring device engineers combine with secondary validation against FDA 510(k) filings, CDSCO biosimilar approval databases, ANVISA tender documentation, and hospital GPO contract records. Bottom-up patient population modeling and top-down pharmaceutical sales data triangulation anchor volume estimates.
Consistency checks against external benchmarks validate projection outputs across the analysis window, with segmentation dimensions covering therapy class, delivery mode, end-user channel, and regional regulatory cluster. CAGRs derive from patient prevalence trend extrapolation, reimbursement expansion trajectories, and biosimilar penetration curve modeling. Forecast inputs incorporate PLI scheme capacity addition timelines, NMPA accelerated review completion rates, and ANVISA device standard enforcement phasing.
Underlying assumptions cover stable cardiorenal outcome data reimbursement expansion, with deviation risk concentrated in biosimilar comparability study talent scarcity extending approval timelines. Practitioners should keep alternative scenarios live as BRICS national pricing authority calibration between patented biologics and biosimilar portfolios evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Egypt Diabetes Care Devices Market
Diabetes Care
Vietnam Oral Anti-Diabetic Drug Market
Diabetes Care
Latin America Diabetes Care Devices Market
Diabetes Care
South Africa Continuous Glucose Monitoring Market
Diabetes Care
Network Point-Of-Care Glucose Testing Market
Diabetes Care
Asia Pacific Blood Glucose Test Strip Market
Diabetes Care
Asia Pacific Blood Glucose Monitoring Market
Diabetes Care
Global Continuous Glucose Monitoring Systems Market
Diabetes Care
Pet Diabetes Care Devices Market
Diabetes Care
Vietnam Insulin Infusion Pump Market
Diabetes Care
Global Proliferative Diabetic Retinopathy Market
Diabetes Care
South Korea Oral Anti-Diabetic Drug Market
Diabetes Care
Vietnam Diabetes Care Devices Market
Diabetes Care
Latin America Oral Anti-Diabetic Drug Market
Diabetes Care
Diabetic Lancing Devices Market
Diabetes Care
Philippines Oral Anti-Diabetic Drug Market