
 Global Pet Diabetes Care Market | 2026-2036
Global Pet Diabetes Care Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pet Diabetes Care Market Foresight
Bundle configurations pairing glucometers with subscription test strip replenishment is hardening as the dominant commercial format. Zoetis leverages its veterinary diagnostics infrastructure to lock in recurring consumable revenue. Merck Animal Health anchors its position through insulin formulations calibrated for canine metabolic profiles. Boehringer Ingelheim competes by extending its human diabetes manufacturing expertise into companion animal dosage formats.
Pet diabetes care encompasses glucose monitoring devices, insulin delivery systems, and supportive therapeutics engineered for species-specific pharmacokinetics, with feline insulin requiring distinct amino acid sequencing from canine analogs. The primary purpose centers on maintaining glycemic control to prevent neuropathy, cataracts, and organ failure in diabetic companion animals. Continuous glucose monitors are capturing margin pools as veterinarians shift from point-of-care testing to real-time metabolic tracking. Insulin pens dominate volume among injection devices due to dosing precision in small-breed dogs. Veterinary hospitals as an end user concentrate procurement power through group purchasing organizations.
FDA Center for Veterinary Medicine regulates insulin analog approval pathways, while EMA veterinary product standards shape European market access requirements. ISO 10993 biocompatibility standards govern materials used in implantable glucose sensors. Stakeholders must monitor how regulatory divergence between FDA and EMA approval timelines affects product launch sequencing across North America and Europe.
Market Dynamics
Continuous glucose monitoring hardware is absorbing diagnostic workflows previously handled by point-of-care analyzers, compressing margins for traditional glucometer suppliers while elevating data-driven care protocols in specialty veterinary clinics.
Growth Catalysts
- Pet insurance penetration:Rising coverage rates in Germany and Japan reduce out-of-pocket treatment costs, expanding addressable patient populations for insulin therapy.
- FDA Center for Veterinary Medicine oversight:Tightened insulin analog standards accelerate product quality differentiation and professional trust in prescribed formulations.
- Veterinary hospital consolidation:Group purchasing organizations concentrate procurement volume, enabling bulk glucose sensor adoption across multi-site clinic networks.
Market Restraints
- Species-specific pharmacokinetics:Feline insulin requires distinct amino acid sequencing from canine analogs, fragmenting R&D investment and manufacturing scale.
- Input cost volatility:Biocompatible sensor materials face ISO 10993 compliance premiums that fluctuate with medical-grade polymer supply constraints.
- Regulatory friction:Divergent FDA and EMA veterinary approval timelines force sequential rather than simultaneous product launches across North America and Europe.
Strategic Opportunities
- Subscription test strip replenishment:Bundled glucometer-service models lock in recurring revenue from home-monitoring pet owners.
- Real-time metabolic tracking:Continuous glucose monitors penetrate small-breed dog segments where dosing precision demands exceed pen-and-syringe capabilities.
- EMA veterinary product standards:Harmonized European certification pathways enable faster cross-border market access for insulin delivery devices.
Industry Challenges
- Specialized veterinary endocrinology training:Shortage of certified practitioners limits diagnostic throughput in community clinics outside major metropolitan hubs.
- Legacy glucose meter integration:Data silos between point-of-care devices and cloud-based monitoring platforms complicate longitudinal patient record management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pet Diabetes Care Market |
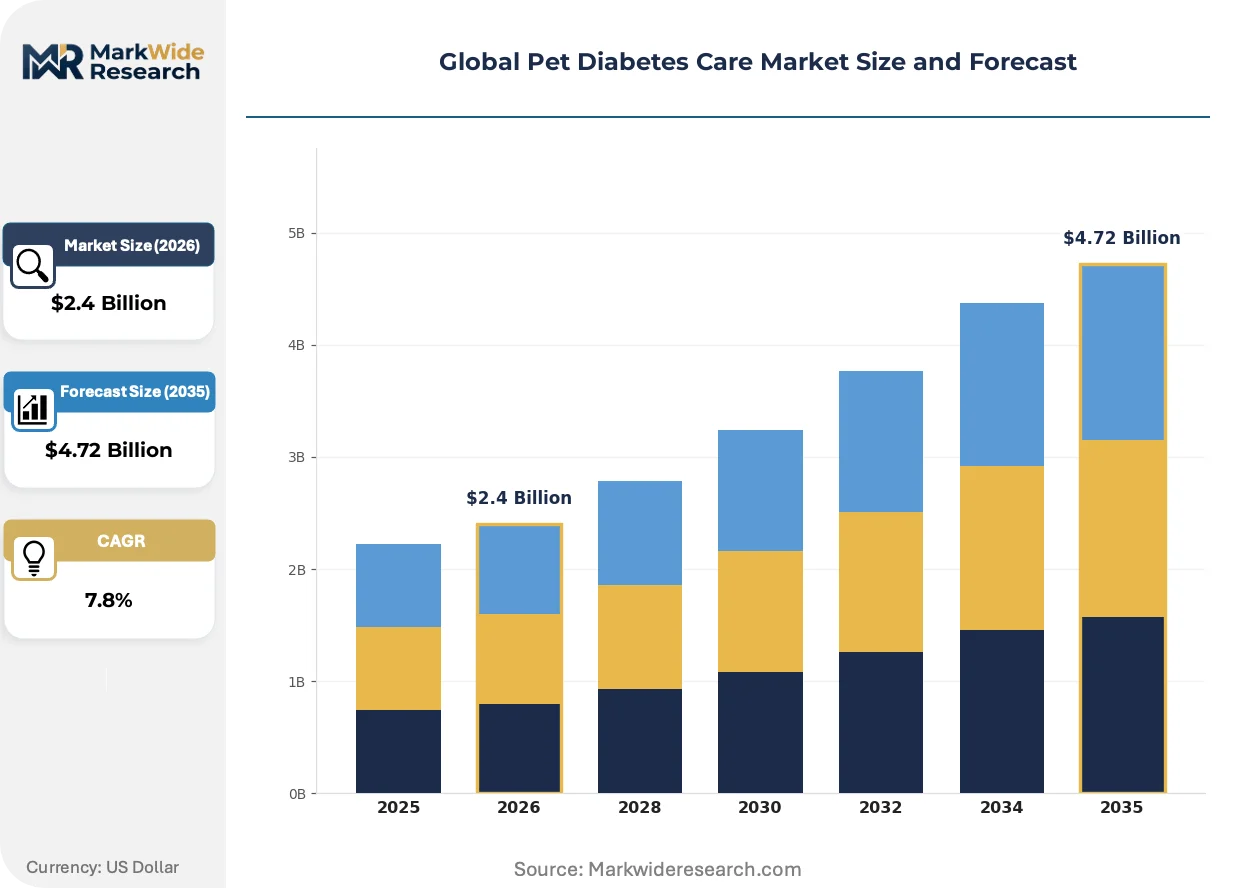
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.72 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glucometers, Insulin Pens, Test Strips, Continuous Glucose Monitors, Injection Devices Application: Canine Diabetes Management, Feline Diabetes Management, Exotic Pets, Veterinary Clinics End User: Veterinary Hospitals, Animal Specialty Clinics, Home Care Providers, Mobile Vet Services Distribution Channel: Online Retailers, Veterinary Distributors, Pharmacies, Pet Specialty Stores, Direct Sales |
| Companies Covered | Zoetis, Merck Animal Health, Boehringer Ingelheim, Becton, Dickinson and Company, Allison Medical, UltiMed, Eli Lilly and Company, Novo Nordisk, Vetoquinol, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pet Diabetes Care Market Shifts & Advancements
Hardware miniaturization and wireless telemetry are collapsing the distinction between clinical and home-based glucose management, enabling remote veterinary supervision that was previously confined to hospital settings.
Implantable glucose sensors leveraging Bluetooth Low Energy transmission are absorbing telemetry functions from handheld readers, allowing direct smartphone data visualization. Specialty veterinary hospitals in the United States are deploying these systems for diabetic cats requiring intensive glycemic stabilization. The technology is absorbing margin pools from traditional glucometer consumables while shifting diagnostic value toward data analytics platforms.
EMA veterinary product standards now mandate enhanced pharmacovigilance reporting for novel insulin analogs, extending post-market surveillance obligations. European manufacturers face compressed development timelines to align with these requirements before commercial launch. Veterinary pharmaceutical distributors in Germany and France are restructuring quality assurance departments to manage documentation intensity.
Pet owners in Japan are consolidating purchasing decisions through veterinary clinic subscription programs rather than retail pharmacy channels. These bundled service contracts combine insulin delivery devices with telemedicine consultations, displacing transactional equipment sales. The shift concentrates buyer power among clinic networks and reduces price transparency for individual consumers.
Global Pet Diabetes Care Market Segmentation
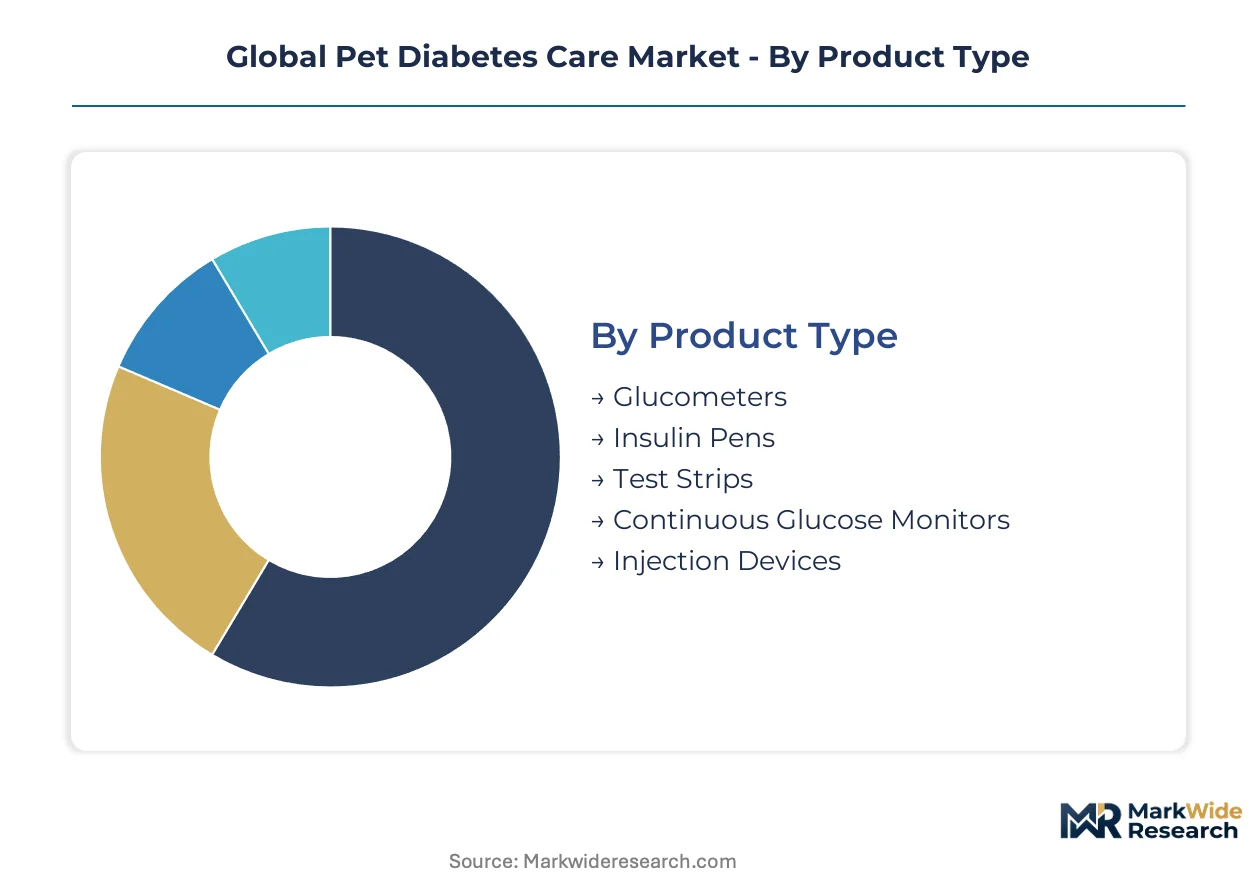
Product heterogeneity in pet diabetes care demands granular segmentation. Species-specific pharmacokinetics fragment device requirements between canine and feline patients, while distribution channel evolution concentrates buyer power among veterinary networks.
Product Type:
Cost tier separates budget-conscious home monitors from premium hospital-grade systems.
- Continuous Glucose Monitors:Implantable sensors transmit real-time data via Bluetooth Low Energy to smartphone dashboards. Specialty veterinary hospitals in the United States deploy these for diabetic cats requiring intensive stabilization protocols. The technology absorbs margin pools from traditional consumables while shifting diagnostic value toward analytics platforms.
- Insulin Pens:Precision dosing mechanisms accommodate small-breed metabolic profiles with graduated unit increments. Demand concentrates in Germany and Japan where pet insurance penetration reduces out-of-pocket therapy costs. Veterinarians favor pen systems for owner-administered home care protocols.
- Glucometers:Point-of-care analyzers remain standard in community veterinary practice for acute diagnostic confirmation.
- Test Strips:Subscription replenishment models lock recurring revenue from chronic disease management programs.
- Injection Devices:Traditional syringe systems persist in price-sensitive segments and exotic pet applications.
Insulin pens lead volumes today; continuous glucose monitors are gaining share fastest.
Application:
Species metabolic divergence fragments therapeutic protocols and device specifications.
- Feline Diabetes Management:Distinct amino acid sequencing requirements for insulin analogs necessitate species-calibrated delivery systems. Japan's veterinary clinic subscription programs bundle monitoring devices with telemedicine consultations, displacing retail pharmacy channels. Feline patients drive demand for miniaturized glucose sensors.
- Canine Diabetes Management:Larger patient mass enables broader insulin formulation compatibility and higher-volume delivery devices. United States specialty hospitals concentrate procurement through group purchasing organizations for multi-site glucose sensor deployment. Breed-specific metabolic variation demands flexible dosing platforms.
- Exotic Pets:Ferret and rabbit diabetes cases require micro-dose insulin delivery and specialized veterinary expertise.
- Veterinary Clinics:In-house diagnostic workflows absorb point-of-care testing for acute presentations and treatment initiation.
Canine applications dominate prescription volumes; feline segments show steepest expansion trajectory.
End User:
Customer type determines procurement scale and service bundling sophistication.
- Veterinary Hospitals:Consolidated networks leverage group purchasing organizations for bulk glucose sensor adoption across multi-site operations. These institutions anchor insulin therapy volume through in-house pharmacy dispensing and captive diagnostic workflows. FDA Center for Veterinary Medicine oversight tightens standards for hospital-procured insulin analogs.
- Home Care Providers:Trained veterinary technicians deliver injection and monitoring services for mobility-limited pet owners. Demand clusters in metropolitan United States markets with aging pet populations and high service labor availability.
- Animal Specialty Clinics:Endocrinology-focused practices command premium pricing for complex diabetic case management.
- Mobile Vet Services:House-call models expand access in rural Germany and suburban Japan where clinic density remains limited.
Veterinary hospitals capture the largest procurement volumes; mobile services are expanding most quickly.
Distribution Channel:
Supply concentration shapes margin capture and price transparency for end purchasers.
- Veterinary Distributors:Regional wholesalers in Germany and France manage quality assurance documentation for EMA veterinary product standards compliance. These intermediaries consolidate insulin delivery device procurement for independent clinic networks. Post-market surveillance obligations extend distributor liability exposure for novel analogs.
- Online Retailers:Direct-to-consumer platforms bypass clinic intermediaries for glucometer and test strip sales. Pet owners in Japan increasingly consolidate purchasing through subscription programs rather than transactional retail channels.
- Pharmacies:Community drugstores retain insulin formulation dispensing where veterinary clinic pharmacies remain underdeveloped.
- Pet Specialty Stores:Retail chains stock basic glucose monitoring consumables for established diabetic patients.
- Direct Sales:Manufacturers like Zoetis leverage veterinary diagnostics infrastructure for bundled device-service contracts.
Veterinary distributors maintain volume leadership; online channels are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Veterinary pharmaceutical manufacturing for companion animals first achieved industrial scale in the United States during the 1980s, with insulin analog development subsequently spreading to European and Asian markets. Regional differentiation now reflects divergent regulatory frameworks, insurance penetration rates, and veterinary practice consolidation patterns.
United States
Specialty veterinary hospital networks in metropolitan corridors drive procurement volume for continuous glucose monitoring hardware. FDA Center for Veterinary Medicine oversight of insulin analogs tightens quality standards for hospital-dispensed formulations. The Greater Boston and San Francisco Bay Area clusters anchor telemedicine-enabled diabetes management platforms for remote patient monitoring.
Germany
Pet insurance penetration exceeding regional averages reduces out-of-pocket therapy costs and expands addressable populations for insulin delivery devices. EMA veterinary product standards mandate enhanced pharmacovigilance documentation for novel analog approvals. The Munich-Stuttgart corridor concentrates veterinary pharmaceutical distribution infrastructure serving independent clinic networks.
Japan
Veterinary clinic subscription programs displace retail pharmacy channels for glucometer and test strip procurement. METI guidelines shape medical device certification pathways for Bluetooth-enabled glucose sensors. Tokyo and Osaka metropolitan areas concentrate specialty endocrinology practices with intensive glycemic stabilization protocols.
United Kingdom
Group purchasing organizations within consolidated veterinary chains concentrate demand for point-of-care diagnostic equipment. The Veterinary Medicines Directorate aligns with EMA standards while maintaining national approval pathways for species-specific insulin formulations. The Cambridge-Oxford-London triangle hosts veterinary diagnostics R&D facilities.
France
ANSM oversight of veterinary medical devices creates parallel regulatory requirements alongside EMA centralized procedures. Lyon and Toulouse veterinary schools supply certified endocrinology practitioners to regional hospital networks. Quality assurance restructuring among distributors addresses intensified post-market surveillance obligations for novel insulin analogs.
Global Pet Diabetes Care Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the technology-differentiation axis, with continuous glucose monitoring systems commanding superior returns versus legacy glucometer consumables. The vendor base organizes into three tiers: human pharmaceutical incumbents extending diabetes portfolios into veterinary applications, dedicated animal health specialists with captive veterinary distribution, and device manufacturers supplying precision injection and monitoring hardware. Consolidation pressure intensifies as hospital procurement centralization favors suppliers with multi-product portfolios and service bundling capabilities.
Within the dedicated animal health tier, Zoetis and Merck Animal Health exemplify archetypes of veterinary-centric market positioning, while Boehringer Ingelheim represents the human-pharmaceutical-extension model leveraging manufacturing scale from companion human diabetes therapies.
| Leading Market Players |
|---|
| Zoetis |
| Merck Animal Health |
| Boehringer Ingelheim |
| Becton, Dickinson and Company |
| Allison Medical |
| UltiMed |
| Eli Lilly and Company |
| Novo Nordisk |
| Vetoquinol |
| Others |
Supply & Pricing Matrix
Implantable glucose sensor miniaturization is collapsing manufacturing scale thresholds, simultaneously compressing per-unit production costs and concentrating component supply among three specialized medical-grade polymer processors in Germany, Japan, and the United States.
Pricing Analysis
Subscription bundling of glucometers with recurring test strip replenishment anchors revenue models across the market. Price differentiation separates FDA-validated continuous glucose monitors from CE-marked equivalents and unvalidated economy alternatives. Pricing pressure stems from veterinary hospital group purchasing organizations consolidating procurement volume across multi-site networks. Home-monitoring pet owners exhibit highest price sensitivity; specialty endocrinology clinics demonstrate lowest.
Supply Chain Analysis
Freight cost premiums for temperature-controlled insulin analog shipments are compressing margins on cross-border European routes. Manufacturing concentrates in the United States, Germany, and Denmark. Biocompatible sensor materials draw from medical-grade polymer feedstock, precision-machined dosing mechanisms, and Bluetooth Low Energy chipsets. Single-source vulnerability sits with ISO 10993-certified polymer suppliers facing medical-device demand surges. Distribution runs through veterinary distributors consolidating procurement for independent clinic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Veterinary pharmaceutical manufacturing cost arbitrage between FDA-regulated United States facilities and EMA-aligned European plants creates margin expansion opportunities for cross-border production strategies.
For Market Incumbents: Cement recurring revenue streams by deepening subscription test strip replenishment penetration among home-monitoring pet owners. Acquire ISO 13485-certified sensor manufacturing capacity to defend against continuous glucose monitor entrants eroding glucometer consumable margins. Lock in group purchasing organization contracts before veterinary hospital consolidation peaks. For New Entrants and Emerging Players: EMA harmonized certification pathways for veterinary medical devices in Europe open a window for insulin delivery device specialists to bypass sequential FDA-EMA launch delays. Target mobile veterinary services in rural Germany and suburban Japan where clinic density constraints limit incumbent reach. Pursue telemedicine-integrated subscription models displacing transactional retail channels. For Investors and Strategic Acquirers: Roll-up economics work for regional veterinary distributor networks because EMA pharmacovigilance documentation requirements are forcing quality assurance restructuring that favors scaled players. Five-to-ten year viability hinges on data analytics platform capabilities absorbing diagnostic value from hardware commoditization. Watch FDA Center for Veterinary Medicine insulin analog guidance revisions as inflection signal for quality-tier repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Harmonization Investment | EMA-aligned documentation accelerates cross-border European market access for novel insulin analogs. |
| Subscription Service Platform Launch | Telemedicine-integrated bundles displace transactional retail channels in Japanese metropolitan markets. |
| Continuous Glucose Monitor Certification | FDA validation separates premium-tier hardware from CE-marked competitors in United States specialty hospitals. |
| Group Purchasing Organization Partnership | Multi-site veterinary hospital networks concentrate procurement volume for bulk glucose sensor adoption. |
| Biocompatible Sensor Material Backward Integration | In-house ISO 10993 polymer processing defends against medical-grade supply constraints and cost volatility. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary research engaged veterinary endocrinologists, group purchasing organization contract managers, FDA regulatory affairs specialists, and animal health distributor quality assurance directors. Secondary validation drew from FDA Center for Veterinary Medicine filings, EMA veterinary product assessment reports, ISO 10993 biocompatibility standards documentation, and pet insurance penetration databases. Bottom-up product-level volume estimates and top-down market sizing triangulated to anchor projections.
Historical reference periods spanning veterinary pharmaceutical commercialization trends anchored the forecast window across the modeling period. Segmentation dimensions modeled include product type, species application, end-user category, and regional regulatory cluster. CAGRs derived from regression analysis of insurance penetration rates, veterinary hospital consolidation trajectories, and technology adoption curves. Forecast inputs incorporated insulin analog approval timelines and continuous glucose monitor reimbursement pathway developments.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt shifts in FDA-EMA regulatory divergence or pet insurance coverage expansion rates. A model refresh is warranted upon material change in veterinary hospital group purchasing organization consolidation velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Middle East and Africa Insulin Pens Market
Diabetes Care
Saudi Arabia Diabetes Care Devices Market
Diabetes Care
Japan Self-Monitoring Blood Glucose Devices Market
Diabetes Care
France Diabetes Devices Market
Diabetes Care
Thailand Oral Antidiabetic Drug Market
Diabetes Care
Self-Monitoring Blood Glucose Strips Market
Diabetes Care
Japan Continuous Glucose Monitoring Devices Market
Diabetes Care
Insulin Resistance Market
Diabetes Care
Egypt Diabetes Care Devices Market
Diabetes Care
North America Insulin Market
Diabetes Care
Diabetic Ketoacidosis Treatment Market
Diabetes Care
Middle East and Africa Blood Glucose Test Strip Market
Diabetes Care
Gestational Diabetes Market
Diabetes Care
Japan Insulin Infusion Pump Market
Diabetes Care
New Zealand Continuous Glucose Monitoring Devices Market
Diabetes Care
Global Smart Insulin Pens Market