
 Diabetic Pen Cap Market | 2026-2036
Diabetic Pen Cap Market Size, Share, and Industry Trends Forecast 2026-2036
Diabetic Pen Cap Market Outlook
Modularization of pen injector systems is decoupling cap procurement from device bundling, letting buyers source caps independently for cost and compatibility optimization. Novo Nordisk A/S leverages its vertical integration across insulin delivery ecosystems to sustain captive demand for proprietary cap interfaces. Eli Lilly and Company anchors its position through R&D intensity in connected device programs. Ypsomed Holding AG specializes in third-party cap manufacturing, competing on scale for contract supply to multi-source drug portfolios.
A diabetic pen cap is a detachable, dose-protective closure component for insulin pen injectors, typically injection-molded from medical-grade polypropylene or ABS with integrated desiccant chambers to preserve drug stability. Its primary commercial purpose is to prevent needle contamination, accidental dosing, and moisture ingress during storage and transport. Reusable caps dominate unit volume across hospital and homecare channels where durability and cost-per-use economics favor multi-cycle designs. Safety caps represent the fastest-expanding segment as needle-stick prevention mandates tighten across regulated jurisdictions. Plastic formulations anchor material selection due to sterilization compatibility and dimensional precision in high-speed molding.
FDA 21 CFR Part 820 quality system requirements and EMA Medical Device Regulation (MDR) classifications shape product standards, testing protocols, and market access timelines for cap manufacturers seeking multi-region commercialization. ISO 11608 needle-based injection system standards further define dimensional interchangeability and performance verification thresholds. Stakeholders must monitor evolving connected-device regulations as Bluetooth-enabled dose-tracking caps advance through regulatory pre-submission pathways.
Market Dynamics
Modular procurement of pen injector components is decoupling cap sourcing from device bundling contracts, enabling third-party manufacturers to compete directly with captive suppliers on price and interoperability.
Growth Catalysts
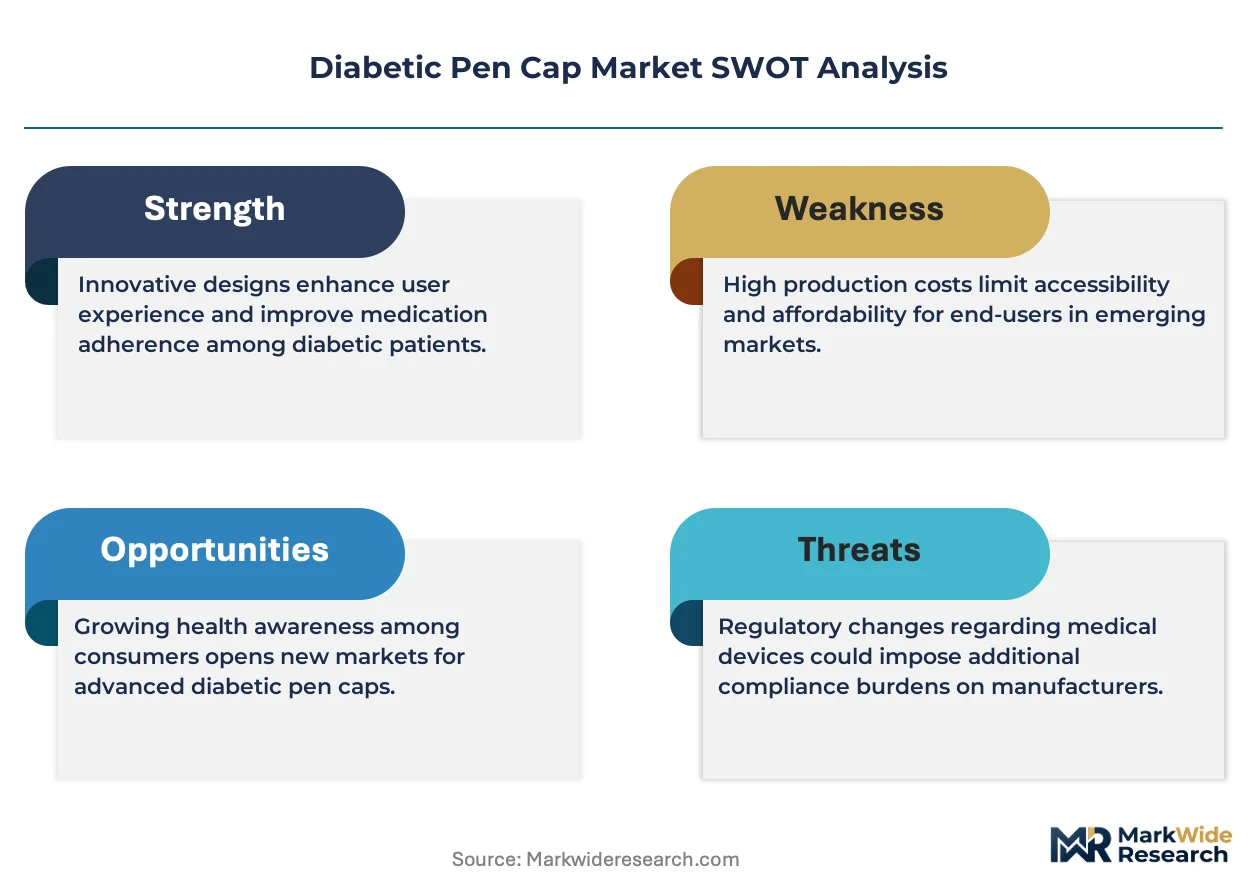
- MDR compliance deadlines:EMA Medical Device Regulation reclassification of pen caps as Class I sterile devices accelerates replacement cycles across European distribution channels.
- Homecare self-administration:Patient preference for at-home insulin management drives demand for user-friendly cap designs with tactile dose indicators.
- Polypropylene molding advances:High-speed injection molding with integrated desiccant chambers reduces per-unit manufacturing costs for reusable cap variants.
Market Restraints
- Medical-grade resin price volatility:Polypropylene and ABS feedstock costs fluctuate with petrochemical supply chains concentrated in Gulf Coast refining clusters.
- Proprietary interface lock-in:Major insulin pen manufacturers maintain non-standard thread geometries that fragment compatibility across third-party cap suppliers.
- ISO 11608 certification timelines:Dimensional interchangeability testing requirements extend product development cycles by 12-18 months for new market entrants.
Strategic Opportunities
- Bluetooth-enabled dose tracking:Wireless connectivity modules embedded in pen caps are converging with mobile health platforms to capture adherence data for payers.
- Japan's aging diabetes population:METI reimbursement expansion for pen injector accessories creates a premium segment for ergonomic cap designs with arthritis-friendly grips.
- Direct-to-patient e-commerce:Online pharmacy channels bypass traditional hospital procurement, enabling cap manufacturers to build subscription-based replenishment models.
Industry Challenges
- Cleanroom molding capacity constraints:ISO 13485-certified production lines for medical-grade plastics face 6-9 month lead times for new equipment installation.
- Legacy pen interface integration:Backward compatibility testing against 15+ years of installed pen devices consumes substantial engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diabetic Pen Cap Market |
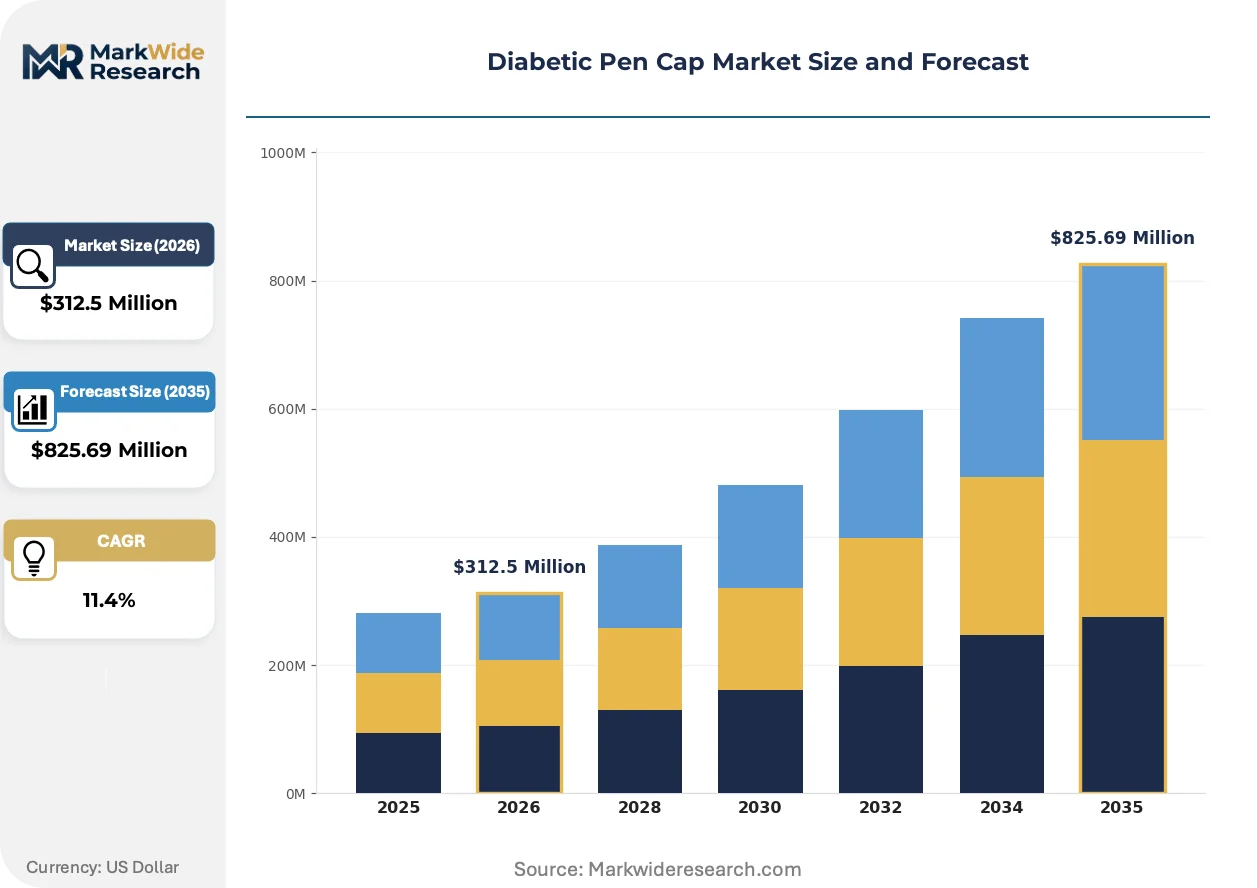
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $825.69 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reusable Caps, Disposable Caps, Customizable Caps, Safety Caps Material: Plastic, Silicone, Rubber, Metal End User: Hospitals, Homecare, Clinics, Pharmacies Distribution Channel: Online Retailers, Drugstores, Supermarkets, Direct Sales |
| Companies Covered | Novo Nordisk A/S, Eli Lilly and Company, Sanofi, Ypsomed Holding AG, Medtronic plc, Emperra GmbH E-Health Technologies, Owen Mumford Ltd, Becton, Dickinson and Company, Jiangsu Delfu Medical Device Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diabetic Pen Cap Market Strategic Shifts
Active materials and embedded electronics are transforming pen caps from passive protective closures into data-capturing health interfaces that bridge drug delivery and digital therapeutics ecosystems.
Biodegradable polymer formulations derived from polylactic acid blends are converging with sterilization-compatible packaging requirements as German hospital procurement groups pilot cap recycling programs. Device manufacturers in Bavaria and Baden-Württemberg are sourcing these materials for single-use safety caps to meet CSRD-mandated supply chain disclosure targets. The structural consequence is compressing virgin plastic demand while creating premium pricing tiers for certified sustainable alternatives.
FDA 21 CFR Part 820 quality system documentation requirements are tightening batch record retention and complaint handling protocols for foreign manufacturers seeking US market access. The industrial consequence is forcing contract manufacturers to deploy electronic quality management systems that automate deviation tracking. Asian suppliers with legacy paper-based systems face the steepest compliance costs and are consolidating under larger medical device holding companies to share audit infrastructure.
Hospital group purchasing organizations are consolidating cap procurement under multi-year device bundling agreements that marginalize standalone cap vendors. German hospital networks and US integrated delivery networks are the primary architects of this shift, leveraging volume commitments to extract price concessions. Independent homecare patients and smaller diabetes clinics remain the residual market for unbundled cap sourcing, though their share of total volume is compressing.
Diabetic Pen Cap Market Segmentation
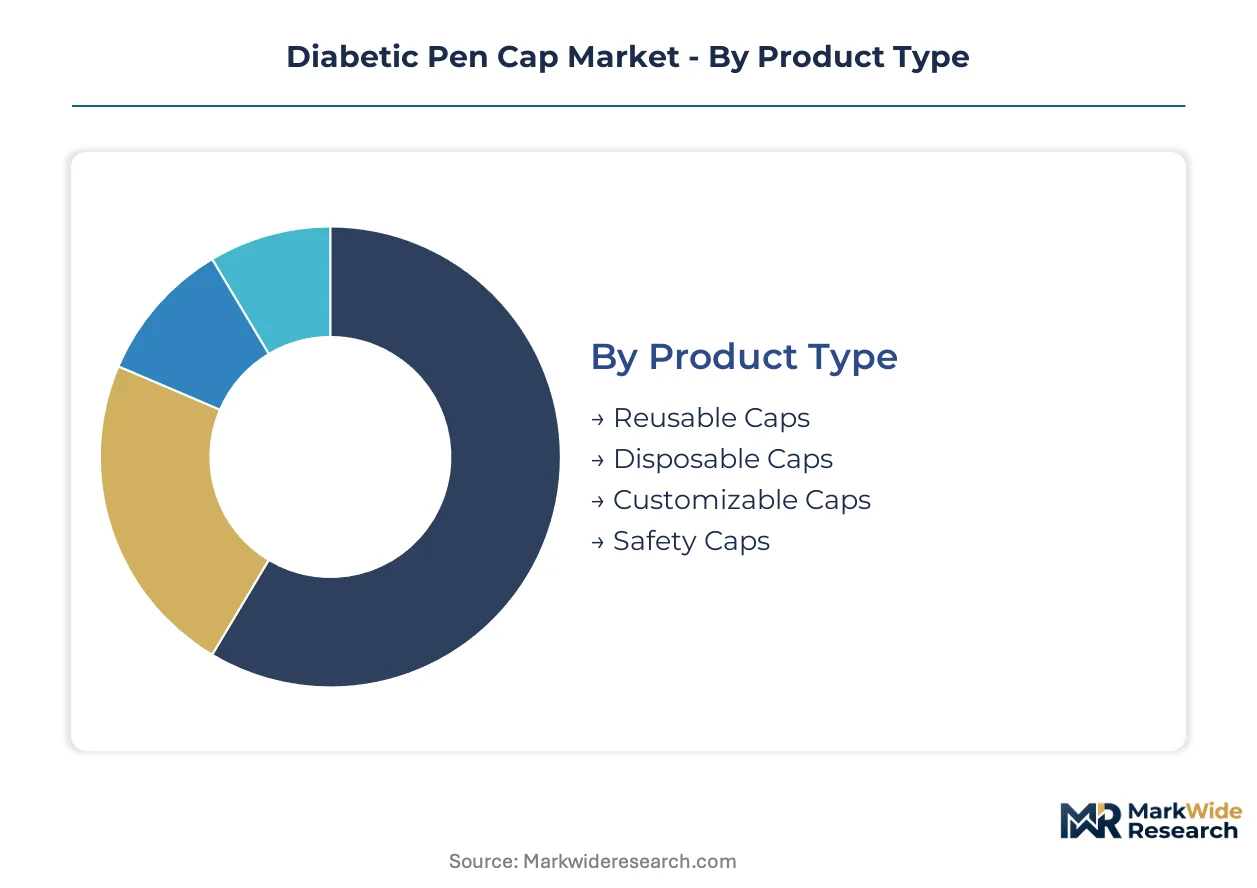
Diabetic pen cap procurement splits across four distinct category axes, each carrying different certification burdens and margin profiles. Manufacturers optimize production lines around material sterilization compatibility and end-user volume concentration rather than pursuing full portfolio coverage.
Product Type:
FDA 21 CFR Part 820 quality system documentation applies universally, while EMA MDR Class I sterile device classification imposes additional clinical evaluation requirements on safety-focused variants.
- Reusable Caps:Injection-molded polypropylene shells with threaded interfaces designed for 100+ use cycles. Hospital procurement in Germany and Japan favors these for cost-per-use economics in high-volume insulin delivery programs.
- Safety Caps:Integrated needle-stick prevention mechanisms with automatic shield deployment. METI reimbursement expansion in Japan and OSHA-aligned mandates across US healthcare systems are accelerating specification into institutional contracts.
- Disposable Caps:Single-use polypropylene closures for travel and emergency kits.
- Customizable Caps:Patient-specific color coding and dose indicator configurations for multi-pen households.
Leading the category by volume: Reusable Caps. Growing fastest: Safety Caps.
Material:
Cost tiers separate medical-grade formulations from commodity alternatives, with sterilization method dictating viable options for each application.
- Plastic:Medical-grade polypropylene and ABS dominate through gamma sterilization compatibility and sub-millimeter dimensional precision in high-speed molding. FDA-cleared suppliers in Bavaria and US Gulf Coast clusters anchor supply.
- Silicone:Soft-touch overmolding for arthritis-friendly grip surfaces. Japanese geriatric homecare demand and German CSRD-mandated recycling programs are expanding specification for premium pen systems.
- Rubber:Compression-molded seals for moisture barrier layers in desiccant-integrated designs.
- Metal:Stainless steel threaded inserts for legacy pen interface compatibility and extended durability.
Plastic formulations command institutional volume. Silicone variants are expanding most quickly in premium geriatric segments.
End User:
Customer type determines packaging format, with hospital GPOs demanding bulk sterile packaging and homecare channels requiring individual unit retail presentation.
- Homecare:Direct-to-patient consumption through retail pharmacy and e-commerce channels. US Medicare Part B reimbursement for pen injector accessories and Japanese long-term care insurance expansion are concentrating demand for ergonomic, self-administration designs.
- Hospitals:Integrated delivery network procurement with multi-year device bundling agreements. German hospital networks and US IDNs extract volume pricing through consolidated cap sourcing.
- Clinics:Smaller diabetes specialty practices with unbundled procurement flexibility.
- Pharmacies:Over-the-counter replacement cap sales and prescription fulfillment accessories.
Homecare channels lead volume as self-administration expands. Hospital procurement is consolidating fastest under bundled contracts.
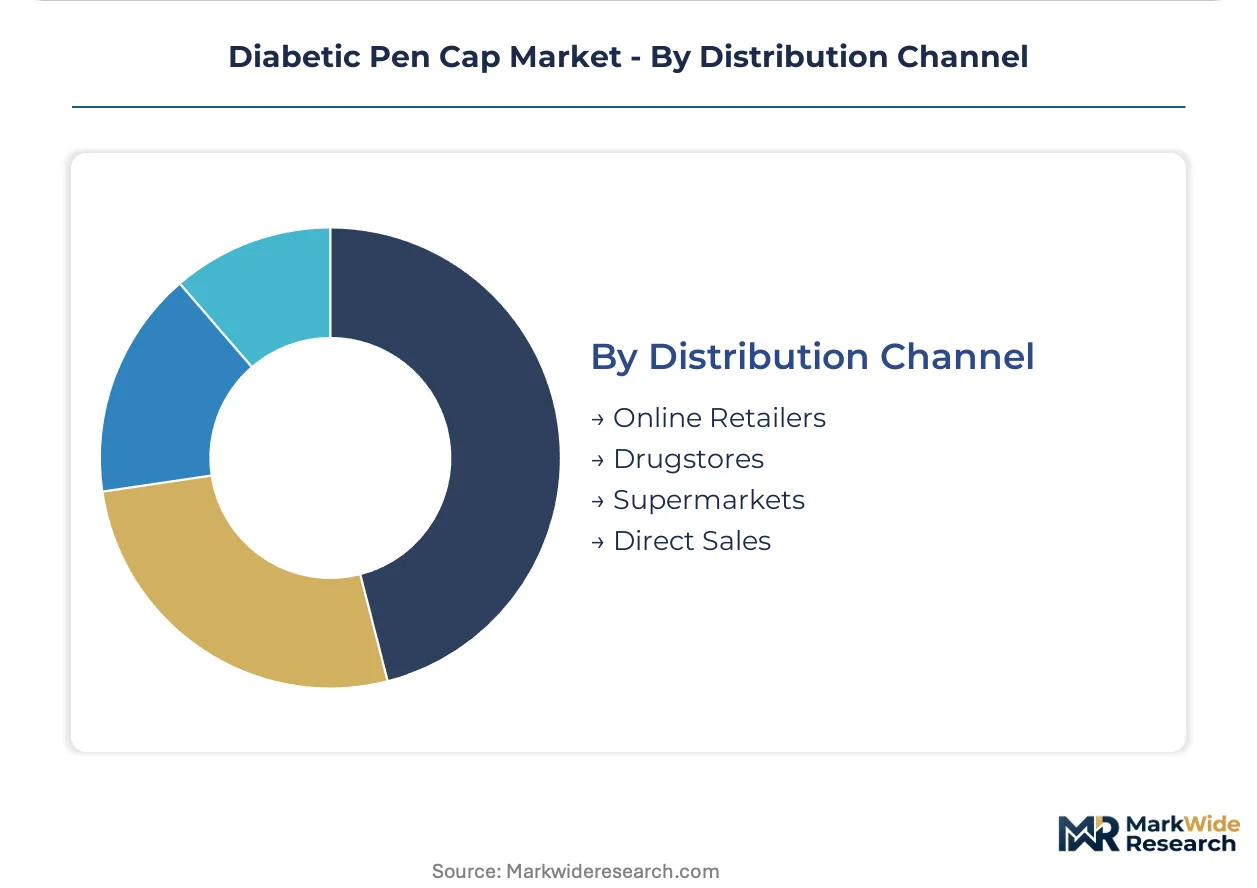
Distribution Channel:
Channel selection determines margin capture, with direct sales preserving manufacturer pricing power and retail intermediaries demanding promotional support.
- Online Retailers:Amazon Pharmacy and specialized diabetes supply platforms enabling subscription replenishment models. Direct-to-patient e-commerce bypasses traditional hospital procurement in US and German markets.
- Drugstores:CVS, Walgreens, and Boots networks with pharmacy counter placement for immediate replacement needs.
- Supermarkets:Mass-market retail with limited SKU availability for emergency purchase scenarios.
- Direct Sales:Manufacturer-controlled channels for proprietary pen system accessories and connected device programs.
Online Retailers are gaining share fastest. Drugstores retain the largest transaction volume for immediate-need purchases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in Shenzhen and Singapore are concentrating injection molding capacity for medical-grade polypropylene components serving pen injector supply chains across Asia-Pacific.
United States
Medicare Part B reimbursement for pen injector accessories and OSHA-aligned needle-stick prevention mandates drive institutional procurement. FDA 21 CFR Part 820 quality system requirements shape compliance timelines for foreign suppliers. Gulf Coast petrochemical clusters near Houston anchor medical-grade resin production for domestic cap manufacturers.
Germany
Hospital network consolidation under bundled procurement agreements concentrates volume with integrated device suppliers. EMA MDR Class I sterile device reclassification accelerates replacement cycles across European distribution. Bavarian medical device clusters around Munich and Erlangen specialize in high-precision molding for reusable cap variants.
Japan
METI reimbursement expansion for pen injector accessories targets the aging diabetes population with geriatric-friendly designs. Long-term care insurance coverage extension creates premium demand for ergonomic grip surfaces. Kansai manufacturing corridors around Osaka concentrate silicone overmolding capacity for arthritis-adapted caps.
China
Domestic diabetes prevalence expansion and government procurement localization policies shift demand toward indigenous suppliers. NMPA medical device registration requirements extend market access timelines for imported caps. Yangtze River Delta industrial zones near Shanghai cluster cleanroom molding facilities serving both domestic and export markets.
India
CDSCO streamlined medical device approval pathways accelerate market entry for pen injector accessories. Government hospital procurement programs under Ayushman Bharat concentrate volume in institutional channels. Gujarat pharmaceutical manufacturing corridors near Ahmedabad anchor polypropylene compounding capacity for regional cap production.
Diabetic Pen Cap Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the pen cap value chain. Market structure tilts toward captive supply arrangements where insulin pen manufacturers maintain proprietary interface control. Three archetypes dominate: vertically integrated pharmaceutical device divisions, contract manufacturing specialists, and independent component suppliers. Consolidation through strategic partnerships and capacity expansion in cleanroom molding represents the primary competitive dynamic.
Among European-based specialists, Ypsomed Holding AG exemplifies the contract manufacturing archetype serving multi-source drug portfolios. Novo Nordisk A/S and Eli Lilly and Company occupy positions as integrated pharmaceutical-device entities with captive demand for proprietary cap interfaces. These three anchors illustrate the competitive tension between unbundled component sourcing and vertically controlled supply ecosystems.
| Leading Market Players |
|---|
| Novo Nordisk A/S |
| Eli Lilly and Company |
| Sanofi |
| Ypsomed Holding AG |
| Medtronic plc |
| Emperra GmbH E-Health Technologies |
| Owen Mumford Ltd |
| Becton, Dickinson and Company |
| Jiangsu Delfu Medical Device Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Captive supply arrangements within insulin pen manufacturing ecosystems anchor pricing power for proprietary interface controllers while fragmenting third-party suppliers into price-competitive commodity tiers. Novo Nordisk and Eli Lilly leverage backward integration into molding operations to preserve margin control over cap accessories, whereas independent manufacturers compete on ISO 11608 certification speed and resin cost pass-through efficiency.
Pricing Analysis
Short lead-time premiums of 15-20% apply to safety cap variants required for MDR compliance deadlines, while spot inventory of standard reusable caps trades at compressed margins. Three-tier pricing structure across premium connected-device caps, standard ISO-certified variants, and economy non-certified alternatives separates hospital GPO procurement from homecare retail channels. Pricing pressure stems from polypropylene feedstock volatility tied to Gulf Coast refining disruptions. Hospital procurement committees exhibit highest price sensitivity through bundled volume negotiations, whereas Japanese long-term care insurance channels absorb premium ergonomic pricing.
Supply Chain Analysis
Freight cost differentials of 8-12% separate Asian molding exports from European regional production, reshaping sourcing decisions for time-sensitive MDR replacement cycles. Medical-grade polypropylene compounding concentrates in Germany, the United States, and China, with cleanroom molding capacity clustering in Bavaria, the Yangtze River Delta, and Gujarat pharmaceutical corridors. Raw material dependencies rest on petrochemical feedstocks, gamma sterilization equipment, and desiccant chamber components. Single-source vulnerability pervades ISO 13485-certified production lines facing 6-9 month equipment lead times. Distribution runs through hospital GPOs, online pharmacy platforms, and direct manufacturer channels with diverging margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bluetooth-enabled dose-tracking modules are displacing passive mechanical caps, forcing incumbents to defend installed base through software companion integration while opening white-space for connectivity-native entrants.
For Market Incumbents: Deploy backward integration into silicone overmolding capacity to capture Japan's geriatric premium segment before connectivity entrants establish adherence-data relationships with payers. Fortify proprietary thread geometries against ISO 11608 interoperability pressures by accelerating connected-device FDA submission timelines. Consolidate cleanroom molding capacity under shared audit infrastructure to defray EMA MDR compliance cost escalation. For New Entrants and Emerging Players: Online pharmacy subscription platforms offer the most penetrable channel for unbundled cap sourcing, bypassing hospital GPO consolidation that marginalizes standalone vendors. Target German diabetes clinics with CSRD-mandated sustainable material alternatives to penetrate procurement networks outside integrated delivery network control. Prioritize direct-to-patient e-commerce with replenishment automation to build recurring revenue before incumbent connectivity programs scale. For Investors and Strategic Acquirers: Exit pathways concentrate in contract manufacturing specialists with ISO 13485 infrastructure and multi-source drug portfolio relationships. Five-to-ten year viability hinges on connected-device data platform integration rather than component commoditization. Acquisition target archetype: cleanroom molding facilities with EMA MDR transition experience and existing relationships with Ypsomed-tier contract manufacturers. Watch FDA pre-submission pathway acceleration for Bluetooth-enabled caps as inflection signal for connectivity premium realization.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission for Connected Caps | Accelerates market access for dose-tracking accessories before MDR compliance deadlines tighten. |
| CE Marking Pathway Under MDR Class I | Secures European institutional procurement eligibility through sterile device reclassification compliance. |
| Hospital System Partnership for Bundled Supply | Locks volume commitments through multi-year agreements that marginalize standalone competitors. |
| Software Companion Development for Adherence Data | Captures payer value through mobile health platform integration beyond hardware margins. |
| Reimbursement Strategy for Medicare Part B | Enables premium pricing capture in US homecare channels through accessory coverage expansion. |
Study Parameters
Multi-period observation of MDR compliance timelines, resin price indices, and pen injector shipment volumes anchored the trend analysis, supplemented by interviews with hospital GPO contracts managers, biomedical engineers at integrated delivery networks, regulatory affairs specialists at cap manufacturers, and pharmacy procurement officers at online retailers. Secondary validation drew from FDA 510(k) filings, EMA MDR transition databases, CMS Medicare Part B reimbursement schedules, and ISO 11608 certification registries. Bottom-up segmentation modeling triangulated against top-down insulin prevalence and pen injector penetration estimates.
Input-output matrices mapped polypropylene resin costs, cleanroom molding capacity utilization, and reimbursement policy changes to volume and value projections across the analysis window. Segmentation dimensions modeled included product type, material sterilization compatibility, end-user channel, and regional regulatory cluster. CAGRs derived from curve-fitting historical pen injector accessory pricing against diabetes prevalence trajectories and connected-device adoption S-curves. Forecast inputs incorporated METI reimbursement expansion schedules and CSRD supply chain disclosure implementation timelines.
Caveats apply where FDA connected-device guidance revisions or EMA MDR enforcement intensity shifts could materially shift the outlook for premium cap variants. Forecasts reflect assumptions about resin price stabilization and hospital GPO consolidation trajectories that remain sensitive to macroeconomic conditions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Diabetic Footwear Market
Diabetes Care
Global Blood Glucose Test Strip Market
Diabetes Care
Japan Insulin Drugs and Delivery Devices Market
Diabetes Care
Australia Insulin Infusion Pump Market
Diabetes Care
Europe Insulin Infusion Pumps Market
Diabetes Care
Malaysia Insulin Infusion Pump Market
Diabetes Care
North America Diabetes Care Devices Market
Diabetes Care
Italy Oral Anti-Diabetic Drug Market
Diabetes Care
Vietnam Insulin Drug and Delivery Device Market
Diabetes Care
Self-Monitoring Blood Glucose (SMBG) Market
Diabetes Care
France Oral Anti-Diabetic Drug Market
Diabetes Care
United Kingdom Blood Glucose Monitoring Market
Diabetes Care
Germany Digital Diabetes Management Market
Diabetes Care
Next Generation Diabetes Therapy and Drug Delivery Market
Diabetes Care
Global Glucose Monitoring Devices Market
Diabetes Care
Diabetic Gastroparesis Treatment Market