
 Next Generation Diabetes Therapy and Drug Delivery Market | 2026-2036
Next Generation Diabetes Therapy and Drug Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
Next Generation Diabetes Therapy and Drug Delivery Market Foresight
The FDA breakthrough device designation is pivoting the cost-of-entry calculus for sensor-augmented pump developers, compressing clinical validation timelines while raising evidence standards. Medtronic plc leverages its vertically integrated manufacturing footprint to sustain hardware-software iteration cycles. Dexcom, Inc. anchors its position through direct-to-consumer channel control in the continuous glucose monitoring segment. Novo Nordisk A/S differentiates via biologic-insulin compatibility with emerging automated delivery platforms.
Next generation diabetes therapy and drug delivery encompasses closed-loop systems, smart insulin delivery devices, and continuous metabolic monitoring hardware engineered to subcutaneous tissue interstitial fluid glucose correlation within 15% mean absolute relative difference. These platforms serve the primary commercial purpose of reducing glycemic variability while minimizing hypoglycemic event frequency in insulin-dependent populations. Continuous glucose monitors command the dominant installed base among product types, though smart pens capture expanding margin pools through software subscription attach rates. The Type 1 diabetes therapy area remains the most penetrated segment, while Type 2 diabetes represents the fastest-growing addressable population as oral GLP-1 therapies create downstream demand for companion monitoring devices.
The FDA, EMA, and Japan's PMDA collectively shape device approval pathways, with each regulator imposing distinct software-as-medical-device validation requirements that fragment commercialization timelines. The EU MDR and FDA quality system regulation both mandate cybersecurity documentation for connected insulin delivery systems, creating compliance overhead that favors established manufacturers with dedicated regulatory affairs infrastructure. Stakeholders must monitor reimbursement parity between standalone sensors and integrated closed-loop systems, as payer bundling decisions will determine whether hardware margins shift toward software and data services.
Market Dynamics
Closed-loop insulin delivery systems are compressing clinical validation timelines through the FDA's breakthrough device designation pathway, forcing manufacturers to restructure evidence-generation workflows around real-world performance data rather than traditional pivotal trials.
Growth Catalysts
- Breakthrough Device Pathway:The FDA's accelerated review channel shortens time-to-market for sensor-augmented pumps by prioritizing pre-submission feedback and rolling data submission protocols.
- Hospital Procurement Consolidation:Integrated delivery networks in the United States are bundling continuous glucose monitors with electronic health record systems, creating captive demand for interoperable platforms.
- Interstitial Fluid Sensing:Factory-calibrated glucose oxidase sensors eliminate fingerstick calibration requirements, expanding addressable populations to Type 2 insulin users previously deterred by complexity.
Market Restraints
- EU MDR Compliance Burden:Software-as-medical-device validation requirements under the Medical Device Regulation fragment commercialization timelines and favor established players with dedicated regulatory infrastructure.
- Palladium Electrode Supply:Electrochemical sensor manufacturing depends on concentrated Russian and South African palladium refining, exposing production schedules to geopolitical supply shocks.
- Algorithm Training Data Scarcity:Hypoglycemia prediction models require diverse glycemic datasets that remain siloed within institutional review board restrictions, limiting generalizability across patient phenotypes.
Strategic Opportunities
- Japan PMDA Reimbursement Expansion:METI's 2024 revision to medical device pricing standards creates parity between standalone sensors and closed-loop systems, enabling premium hardware margins.
- Smart Pen Software Subscriptions:Dose logging and pattern recognition applications transform injection devices into recurring revenue platforms with attach rates decoupled from insulin volume.
- Biologic-Device Convergence:GLP-1 therapy expansion creates companion monitoring demand as prescribers seek glycemic variability data to optimize dosing intervals.
Industry Challenges
- Cybersecurity Documentation:FDA quality system regulation mandates threat modeling and penetration testing for connected insulin delivery, extending development timelines by 8-14 months.
- Legacy Pump Integration:Automated insulin delivery algorithms must accommodate heterogeneous hardware footprints, complicating software updates across installed bases spanning multiple device generations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Next Generation Diabetes Therapy and Drug Delivery Market |
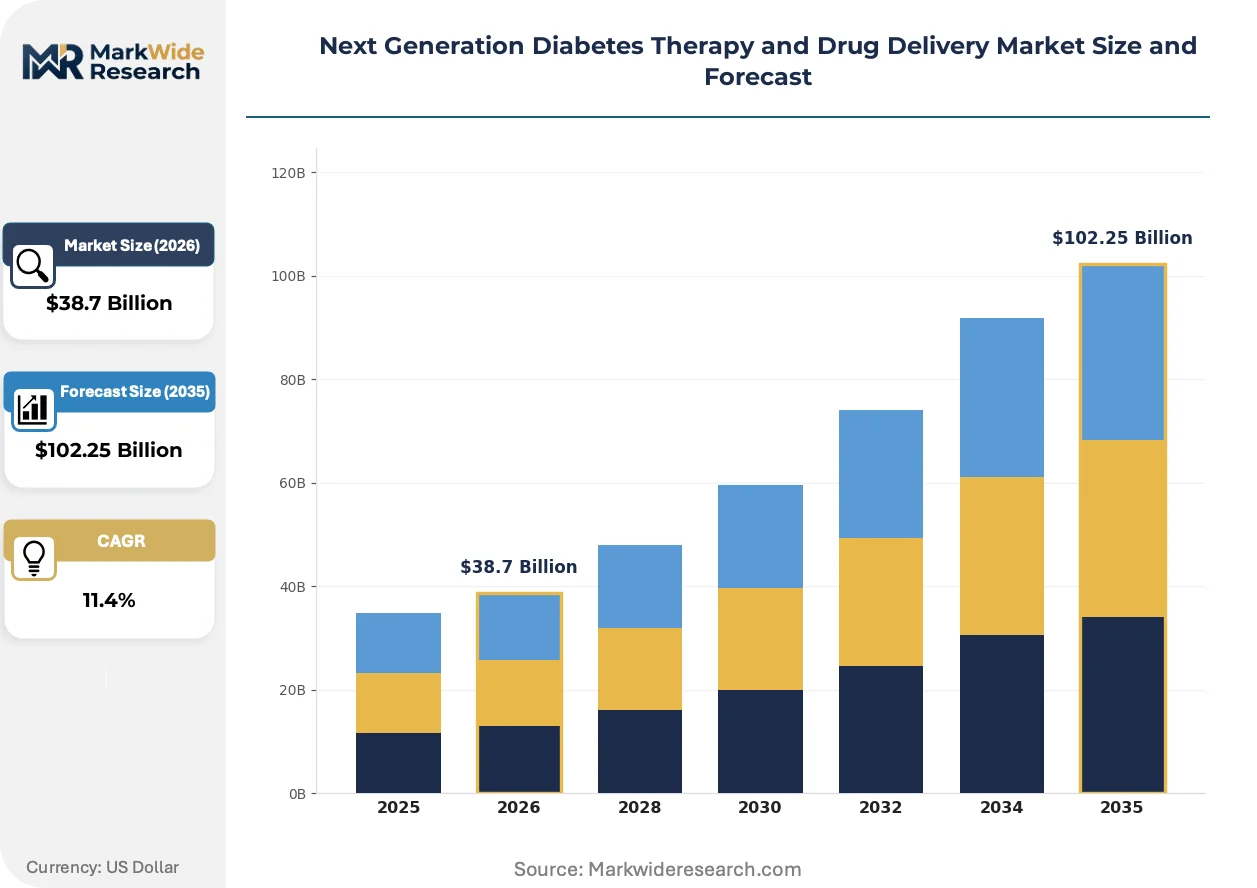
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable Insulin, Continuous Glucose Monitors, Insulin Pumps, Smart Pens Therapy Area: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Prediabetes Administration Route: Subcutaneous, Intravenous, Inhalation, Oral End User: Hospitals, Home Care, Specialty Clinics, Pharmacies |
| Companies Covered | Abbott Laboratories, Medtronic plc, Sanofi, Novo Nordisk A/S, Eli Lilly and Company, Dexcom, Inc., Johnson & Johnson, MannKind Corporation, Senseonics Holdings, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Next Generation Diabetes Therapy and Drug Delivery Market Shifts & Advancements
Algorithm-driven insulin dosing is displacing patient-managed bolus calculations across both inpatient and ambulatory settings, while regulatory frameworks coalesce around software validation standards that privilege real-world evidence over simulated glucose control.
Dual-hormone closed-loop systems incorporating glucagon alongside insulin are modularizing hardware architectures to accommodate future peptide formulations. Pediatric endocrinology departments in Germany and the Netherlands are piloting these platforms for nocturnal hypoglycemia prevention. The approach is modularizing supplier relationships, enabling device manufacturers to source glucagon cartridges from specialty pharmaceutical partners rather than developing captive biologic capabilities.
The EU AI Act's risk classification for medical decision-support software is forcing glucose prediction algorithms into conformity assessment procedures previously reserved for active implantable devices. Manufacturers must now document training data provenance and algorithmic interpretability for notified body review. Closed-loop systems with autonomous dosing authority face the most stringent scrutiny, prompting some developers to recalibrate automation levels for initial CE marking.
Direct-to-consumer channel expansion is disrupting traditional durable medical equipment distribution for continuous glucose monitors. Pharmacy benefit managers in the United States are building preferred networks that bypass endocrinology referrals, compressing patient onboarding to same-day sensor activation. This shift concentrates demand forecasting risk with manufacturers while transferring inventory carrying costs to retail pharmacy chains.
Next Generation Diabetes Therapy and Drug Delivery Market Segmentation
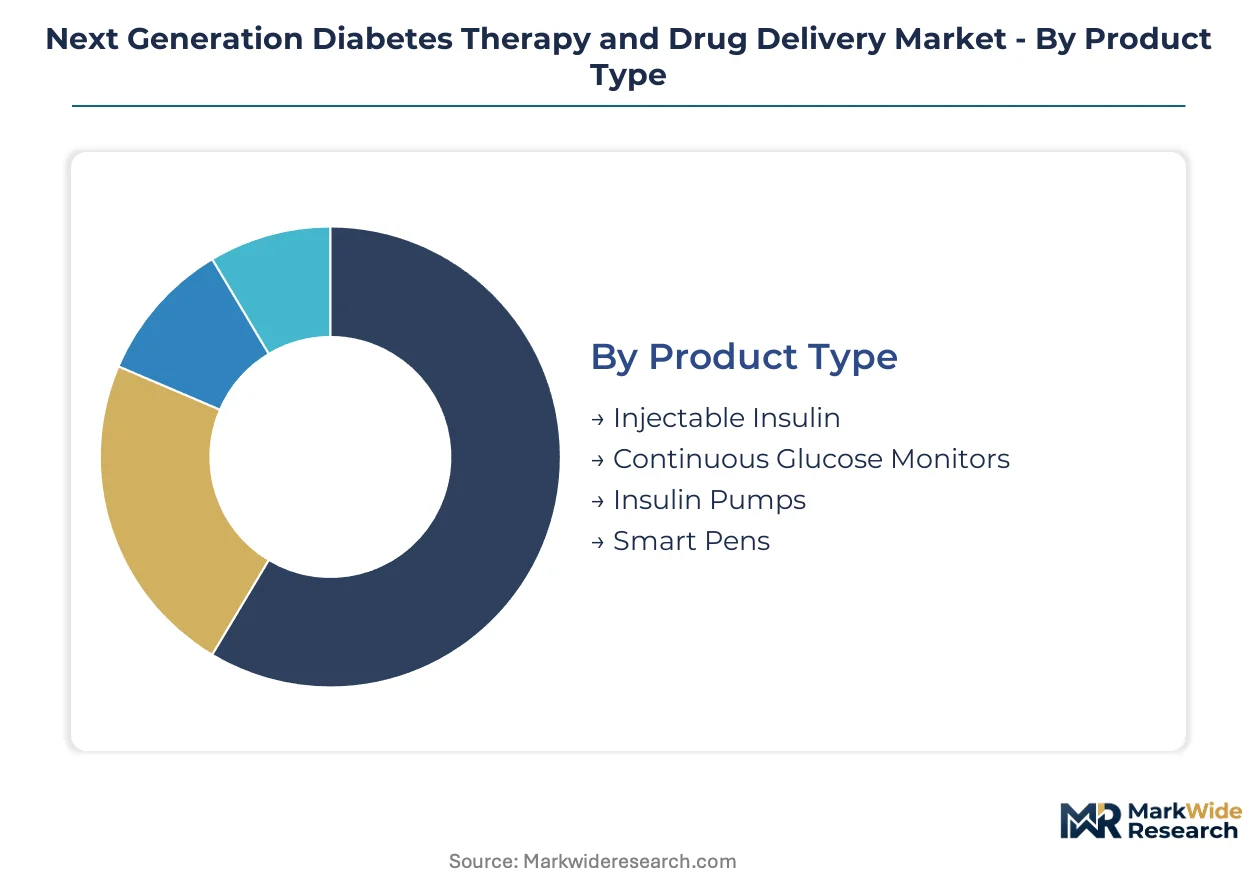
Segmentation in next-generation diabetes therapy reveals how regulatory pathways, reimbursement tiers, and patient acuity stratify commercial opportunity. Device manufacturers must align product portfolios with specific approval burdens and end-user procurement patterns to capture margin pools effectively.
Product Type:
FDA breakthrough device designation and EU MDR software-as-medical-device requirements impose divergent validation timelines across hardware categories, with closed-loop systems facing the most stringent cybersecurity documentation mandates.
- Injectable Insulin:Biologic formulations require cold-chain distribution infrastructure and compatibility testing with emerging automated delivery platforms. Demand concentrates in hospital formularies seeking standardized insulin protocols for glycemic control.
- Continuous Glucose Monitors:Factory-calibrated electrochemical sensors eliminate fingerstick calibration through glucose oxidase chemistry sealed in biocompatible membranes. Home care adoption in Germany and Japan accelerates as reimbursement frameworks achieve parity between standalone sensors and integrated systems.
- Insulin Pumps:Tethered and patch pump configurations with Bluetooth connectivity enable smartphone-based dose logging.
- Smart Pens:Dose-capture devices transform injection therapy into data-generating platforms with software subscription attach rates.
Leading the category by volume: Continuous Glucose Monitors. Growing fastest: Smart Pens.
Therapy Area:
Patient phenotype determines device complexity tolerance, reimbursement eligibility, and companion diagnostic requirements across commercial segments.
- Type 1 Diabetes:Absolute insulin deficiency mandates intensive insulin therapy with automated delivery algorithms. Penetration rates peak in pediatric and young adult populations across United States academic medical centers.
- Type 2 Diabetes:Progressive beta-cell dysfunction creates expanding demand for insulin adjunctive to oral GLP-1 therapies. Specialty clinics in Japan report rising sensor adoption among insulin-naive patients seeking glycemic variability data for dosing optimization.
- Gestational Diabetes:Temporary hyperglycemia during pregnancy requires short-duration monitoring with obstetric workflow integration.
- Prediabetes:Lifestyle intervention support drives consumer-wearable crossover demand for metabolic awareness tools.
Dominant installed base: Type 1 Diabetes. Steepest expansion trajectory: Type 2 Diabetes.
Administration Route:
Route selection constrains formulation stability, device form factor, and pharmacokinetic profile matching to meal-time glucose excursions.
- Subcutaneous:Interstitial tissue absorption via pen needles or infusion sets remains the standard for basal-bolus insulin delivery. United States home care settings drive volume through patient-administered therapy preference.
- Intravenous:Hospital intensive care units utilize IV insulin protocols for critical glycemic management during acute metabolic decompensation.
- Inhalation:Pulmonary insulin delivery offers rapid onset kinetics for prandial coverage without injection burden.
- Oral:Gastrointestinal enzyme barriers limit bioavailability of peptide therapies, though permeation enhancers advance clinical validation.
Highest procedure volume: Subcutaneous. Emerging route with pipeline investment: Oral.
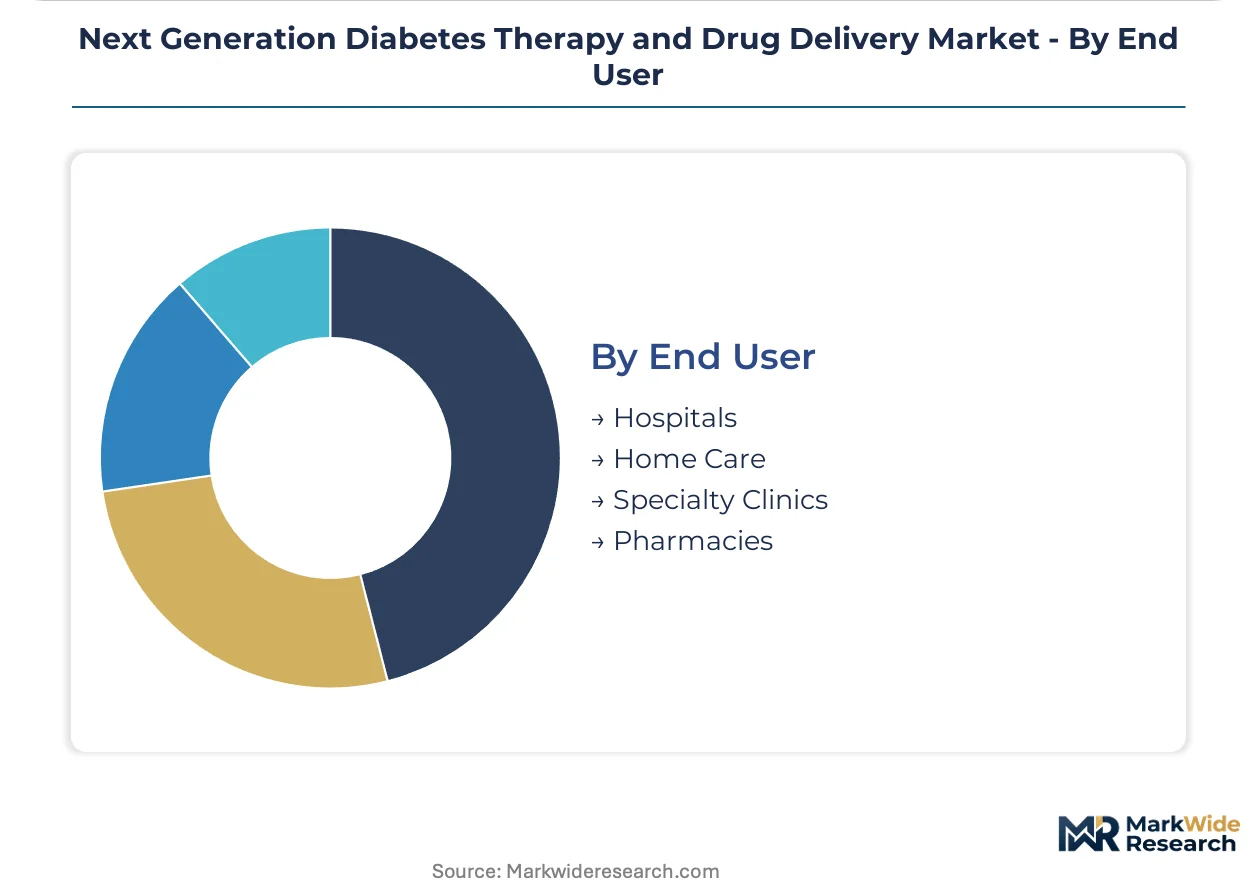
End User:
Procurement authority and reimbursement mechanism vary sharply across care settings, dictating sales channel strategy and contract structure.
- Hospitals:Integrated delivery networks bundle continuous glucose monitors with electronic health record interoperability requirements. United States health systems negotiate enterprise contracts covering inpatient and discharge transitions.
- Home Care:Direct-to-consumer pharmacy channels bypass endocrinology referrals for sensor activation, concentrating demand forecasting risk with manufacturers.
- Specialty Clinics:Endocrinology practices serve as gatekeepers for advanced therapy authorization and device training.
- Pharmacies:Retail chains absorb inventory carrying costs for over-the-counter glucose monitoring supplies.
Primary revenue concentration: Hospitals. Channel expanding most quickly: Home Care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medtronic's manufacturing campus in Northridge anchors sensor-augmented pump production for the western United States. Germany's MedTech cluster around Tübingen concentrates electrochemical sensor R&D with dedicated cleanroom infrastructure.
United States
FDA breakthrough device designations for closed-loop systems compress commercialization timelines by 12-18 months. The Centers for Medicare & Medicaid Services maintains reimbursement parity between standalone continuous glucose monitors and integrated automated insulin delivery platforms. Minneapolis-St. Paul hosts the dominant vertically integrated manufacturing footprint for insulin pump hardware.
Germany
Hospital procurement networks in Baden-Württemberg bundle continuous glucose monitors with electronic health record systems from SAP and Cerner. EU MDR software-as-medical-device validation requirements impose 8-14 month documentation timelines for algorithm-driven dosing systems. The Tübingen-Reutlingen corridor concentrates glucose oxidase sensor fabrication with dedicated palladium electrode supply contracts.
Japan
METI's 2024 revision to medical device pricing standards achieves reimbursement parity between standalone sensors and closed-loop insulin delivery systems. PMDA accelerated review pathways prioritize pre-submission feedback for factory-calibrated interstitial fluid monitors. The Kansai region around Osaka anchors electrochemical sensor manufacturing with dedicated biocompatible membrane production facilities.
United Kingdom
NICE technology appraisals mandate cost-effectiveness thresholds for continuous glucose monitor adoption in Type 1 diabetes populations. MHRA software-as-medical-device guidance requires algorithm training data documentation for glucose prediction models. The Oxford-Cambridge arc concentrates dual-hormone closed-loop research with pediatric endocrinology pilot programs.
Netherlands
Academic medical centers in Amsterdam and Utrecht pilot nocturnal hypoglycemia prevention protocols using dual-hormone closed-loop systems. EMA centralized procedures for automated insulin delivery create CE marking pathways distinct from FDA timelines. The Eindhoven Brainport cluster hosts glucose sensor algorithm development with dedicated machine learning validation infrastructure.
Next Generation Diabetes Therapy and Drug Delivery Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across hardware, biologics, and data services segments. The vendor base stratifies into three tiers: vertically integrated device manufacturers with captive sensor production, pharmaceutical firms with biologic-device convergence strategies, and software-centric platforms with direct-to-consumer channel control. Strategic moves concentrate on regulatory pre-positioning through FDA breakthrough device submissions and pharmacy benefit manager preferred network negotiations.
Within the diversified medical technology tier, Medtronic plc and Johnson & Johnson occupy positions spanning insulin pumps, continuous glucose monitors, and surgical devices. Abbott Laboratories and Dexcom, Inc. exemplify the sensor-focused archetype with factory-calibrated electrochemical platforms. Novo Nordisk A/S represents pharmaceutical-device convergence through biologic-insulin compatibility with emerging automated delivery platforms.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Medtronic plc |
| Sanofi |
| Novo Nordisk A/S |
| Eli Lilly and Company |
| Dexcom, Inc. |
| Johnson & Johnson |
| MannKind Corporation |
| Senseonics Holdings, Inc. |
| Others |
Supply & Pricing Matrix
Palladium electrode costs cascade from Russian and South African refiners through glucose oxidase sensor fabrication, concentrating pricing power with manufacturers holding dedicated supply contracts while forcing tiered hardware margins on spot-market dependent assemblers.
Pricing Analysis
Lead-time-driven pricing stratifies across premium, standard, and economy tiers, with hospital procurement networks commanding volume discounts against direct-to-consumer pharmacy premiums. FDA breakthrough device designation and EU MDR certification tiers differentiate price bands, while cost compression in factory-calibrated sensors intensifies from expanding Type 2 addressable populations. Home care channels exhibit highest price sensitivity; integrated closed-loop systems in academic medical centers show lowest.
Supply Chain Analysis
Dual-sourcing requirements from United States health systems and German hospital networks mandate multi-supplier qualification for electrochemical sensors and insulin pump hardware. Manufacturing concentrates in the United States, Germany, and Japan, with palladium electrodes, glucose oxidase chemistry, and biocompatible membranes anchoring upstream dependencies. Single-source vulnerability in Russian palladium refining exposes production schedules. Distribution runs through integrated delivery networks and direct-to-consumer pharmacy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Palladium electrode supply concentration props hardware pricing, with sensor fabrication capacity bottlenecks limiting production scale-up regardless of downstream demand expansion.
For Market Incumbents: Extend regulatory pre-positioning through FDA breakthrough device submissions and pharmacy benefit manager preferred network negotiations. Backward integration into glucose oxidase sensor fabrication defends margin position against spot-market palladium exposure. CE marking under EU MDR software-as-medical-device requirements preserves European access against emerging entrant certification delays. For New Entrants and Emerging Players: Capture Type 2 diabetes companion monitoring demand as GLP-1 therapy expansion creates glycemic variability data requirements. Japan's METI reimbursement parity revision offers the most penetrable geography for closed-loop system entry. Direct-to-consumer channel partnerships bypass endocrinology referral bottlenecks. For Investors and Strategic Acquirers: FDA breakthrough device designation awards are the leading indicator that commercialization timelines have compressed sufficiently to justify premium hardware valuations. Five-to-ten year viability favors sensor-focused platforms with factory-calibrated manufacturing scale over biologic-dependent pump hardware. Watch PMDA accelerated review pathway decisions as inflection signal for Asia-Pacific reimbursement expansion.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Compresses validation timelines by 12-18 months for sensor-augmented pumps. |
| Hospital System Partnership | Locks in enterprise contracts covering inpatient and discharge transitions. |
| Software Companion Development | Transforms injection devices into recurring revenue platforms via subscription attach. |
| Reimbursement Strategy | Achieves parity between standalone sensors and integrated closed-loop systems. |
| CE Marking Pathway | Navigates EU MDR software-as-medical-device requirements for algorithm-driven dosing. |
Research Methodology
Document review covered FDA 510(k) filings, EMA centralized procedure decisions, PMDA accelerated review pathway documentation, and CMS reimbursement determinations, complemented by interviews with regulatory affairs leads at device manufacturers, hospital procurement committee chairs, endocrinology practice administrators, and pharmacy benefit manager formulary directors. Secondary validation drew from ClinicalTrials.gov entries, medical device registration databases, and GPO contract disclosures. Bottom-up sensor shipment estimates triangulated against top-down insulin-dependent population projections.
Installed base forecasts and revenue estimates reflect analytical framework segmentation across product type, therapy area, administration route, and end user, with geographic regulatory clusters layered throughout the projection horizon. CAGRs derived from logistic diffusion curves fitted to historical adoption patterns in continuous glucose monitoring and insulin pump penetration. Model inputs incorporated palladium price volatility indices, reimbursement parity achievement timelines, and software-as-medical-device validation duration estimates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU MDR notified body capacity constraints and geopolitical palladium supply disruptions. Deviation in FDA breakthrough device designation award velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Philippines Oral Anti-Diabetic Drug Market
Diabetes Care
Global Type 2 Diabetes Treatment Market
Diabetes Care
Diabetes Care Devices and Drugs Market
Diabetes Care
Pet Diabetes Care Devices Market
Diabetes Care
Russia Self-Monitoring Blood Glucose Devices Market
Diabetes Care
South Korea Insulin Infusion Pump Market
Diabetes Care
Global Type 1 Diabetes (T1D) Market
Diabetes Care
Japan Self-Monitoring Blood Glucose Devices Market
Diabetes Care
United States Self-Monitoring Blood Glucose Market
Diabetes Care
Vietnam Diabetes Care Devices Market
Diabetes Care
Digital Diabetes Market
Diabetes Care
China Continuous Glucose Monitoring Devices Market
Diabetes Care
Diabetic Gastroparesis Treatment Market
Diabetes Care
Continuous Glucose Monitoring Device Market
Diabetes Care
Hyperglycemia Treatment Market
Diabetes Care
Thailand Oral Antidiabetic Drug Market