
 Brazil Blood Glucose Monitoring Market | 2026-2036
Brazil Blood Glucose Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Blood Glucose Monitoring Market Outlook
Home care self-monitoring is expanding faster than institutional testing as Brazilian diabetics shift toward decentralized management. Abbott Laboratories leverages its FreeStyle platform to dominate the continuous glucose monitor sub-segment with strong pharmacy channel control. Roche Diagnostics anchors the traditional blood glucose meter category through deep diagnostic lab relationships across public health networks. Medtronic competes in the insulin pump-integrated sensor space, extending its hospital-to-home connectivity protocols.
Blood glucose monitoring encompasses electrochemical biosensor systems that measure interstitial or capillary glucose through enzymatic reactions, typically using glucose oxidase or dehydrogenase chemistry on disposable test strips with results delivered in five seconds or less. The primary purpose is enabling real-time glycemic management to prevent diabetic ketoacidosis, hypoglycemic events, and long-term microvascular complications. Continuous glucose monitors are capturing the fastest expansion trajectory as wearable wireless transmitters replace fingerstick dependence among Type 1 patients. Test strips still occupy the largest revenue pool due to massive Type 2 volumes, though margin compression intensifies from SUS reimbursement pressure. Enzymatic technology leads installed base while non-enzymatic approaches attract R&D funding for improved accuracy stability.
ANVISA governs medical device registration and post-market surveillance, requiring in-country testing validation that shapes product launch timelines for imported monitors. The Brazilian Ministry of Health's SUS formulary and reimbursement classifications directly determine accessible price bands and volume eligibility for low-income patients. ISO 15197 accuracy standards influence manufacturer design specifications even without domestic mandate. Stakeholders must monitor how ANVISA's alignment with MDR traceability rules reshapes distributor liability and import documentation burdens.
Market Dynamics
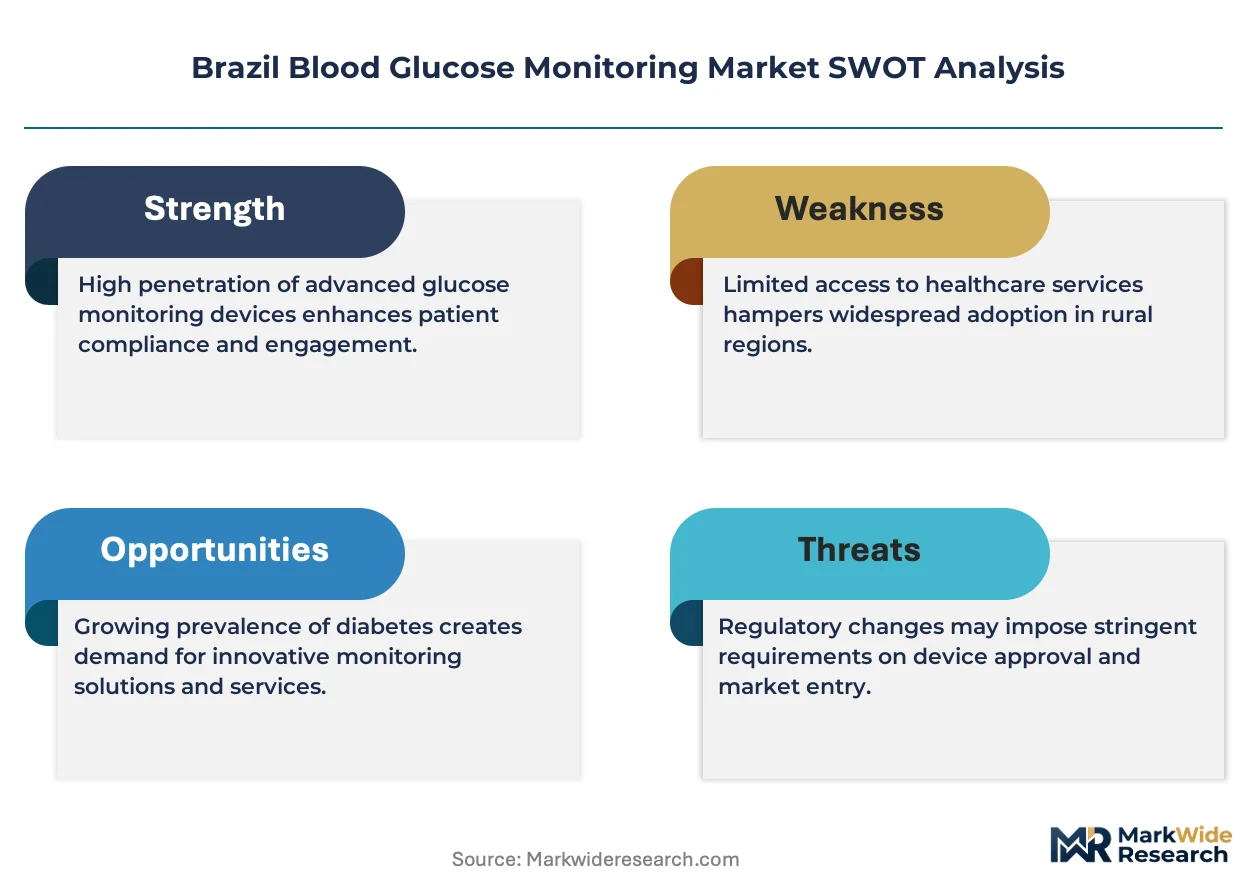
ANVISA's updated medical device traceability requirements are forcing manufacturers to restructure import documentation and distributor liability frameworks, compressing product launch timelines while elevating compliance costs across the Brazilian blood glucose monitoring landscape.
Growth Catalysts
- SUS formulary expansion:The Brazilian Ministry of Health's reimbursement classifications for continuous glucose monitors are widening patient eligibility among low-income diabetics, particularly in Southeast metropolitan corridors.
- Enzymatic biosensor miniaturization:Advances in glucose oxidase chemistry on flexible substrates are enabling wearable form factors that reduce fingerstick dependence among Type 1 patients.
- São Paulo home care density:Elderly diabetic populations in São Paulo state are accelerating self-monitoring adoption faster than institutional testing growth.
Market Restraints
- Test strip margin compression:SUS reimbursement pressure on disposable consumables is squeezing manufacturer profitability despite high Type 2 patient volumes.
- Import validation bottlenecks:ANVISA's in-country testing requirements create 12-18 month regulatory lag for foreign manufacturers versus domestic assemblers.
- Non-enzymatic accuracy gaps:Alternative sensing chemistries still fail to match glucose oxidase stability across temperature and humidity ranges typical of Brazilian climates.
Strategic Opportunities
- Northeast regional underpenetration:Pernambuco and Bahia states show 40% lower CGM adoption than Southeast benchmarks, creating whitespace for pharmacy channel expansion.
- Insulin pump convergence:Sensor-integrated closed-loop systems are opening hospital-to-home connectivity protocols that merge device categories.
- Telehealth reimbursement codes:Brazil's supplemental health insurers are adding remote glucose monitoring to covered services, enabling subscription revenue models.
Industry Challenges
- ISO 15197 certification timelines:Laboratory validation protocols for accuracy standards extend product development cycles by 8-14 months.
- Distributor technical training gaps:Pharmacy channel staff lack proficiency in CGM calibration procedures, elevating return rates and patient abandonment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Blood Glucose Monitoring Market |
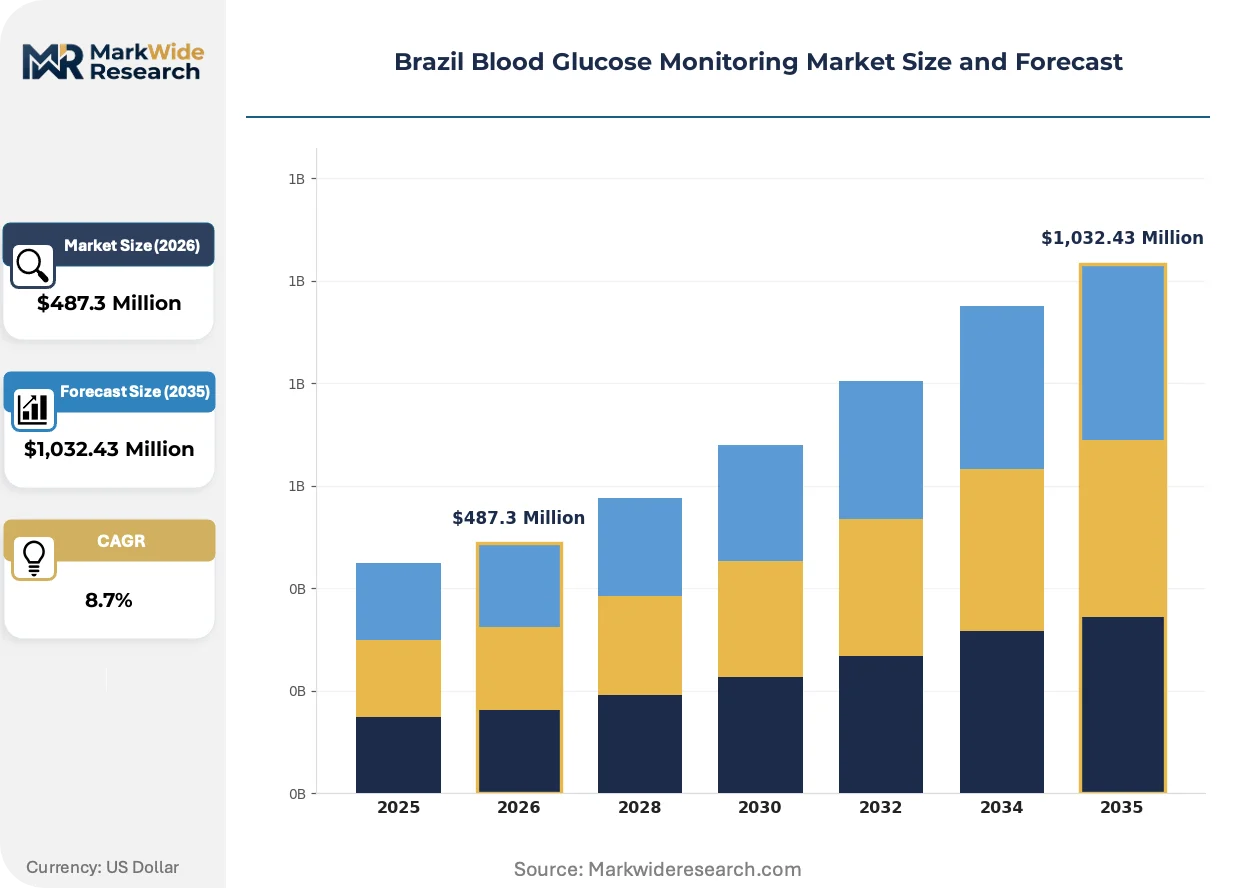
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blood Glucose Meters, Continuous Glucose Monitors, Test Strips, Lancets End User: Hospitals, Clinics, Home Care, Pharmacies Technology: Enzymatic, Non-Enzymatic, Wireless, Wearable Distribution Channel: Online Retail, Offline Retail, Direct Sales, Distributors |
| Companies Covered | Roche Diagnostics, Lifescan, Abbott Laboratories, Siemens Healthineers, Johnson & Johnson, Medtronic, Ascensia Diabetes Care, Bayer Healthcare, Dexcom, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Blood Glucose Monitoring Market Strategic Shifts
Wireless interstitial sensing is displacing capillary blood draws as the dominant measurement paradigm, while regulatory alignment with international traceability standards and shifting reimbursement incentives reshape competitive positioning across Brazilian states.
Continuous glucose monitoring systems utilizing subcutaneous filament sensors with 14-day wear durations is rewriting the economics of diabetes management. Type 1 patients in São Paulo and Rio de Janeiro metropolitan areas are adopting these devices at rates three times faster than fingerstick meters. The technology is rewriting pharmacy inventory models as subscription-based sensor shipments replace transactional test strip purchases.
ANVISA's phased alignment with EU MDR traceability rules is mandating Unique Device Identification across all imported glucose monitors. Manufacturers must now maintain digital records linking individual sensors to patient registries. Public health networks in Minas Gerais and Paraná are experiencing the steepest documentation burdens as they transition legacy procurement systems.
Retail pharmacy chains are consolidating glucose monitor purchasing through centralized procurement desks rather than individual store buying. Independent diabetes specialty shops in Rio de Janeiro are losing shelf space to pharmacy banners with exclusive Abbott and Roche distribution agreements. This concentration is most visible in the Southeast region where three pharmacy groups control 60% of CGM dispensing points.
Brazil Blood Glucose Monitoring Market Segmentation
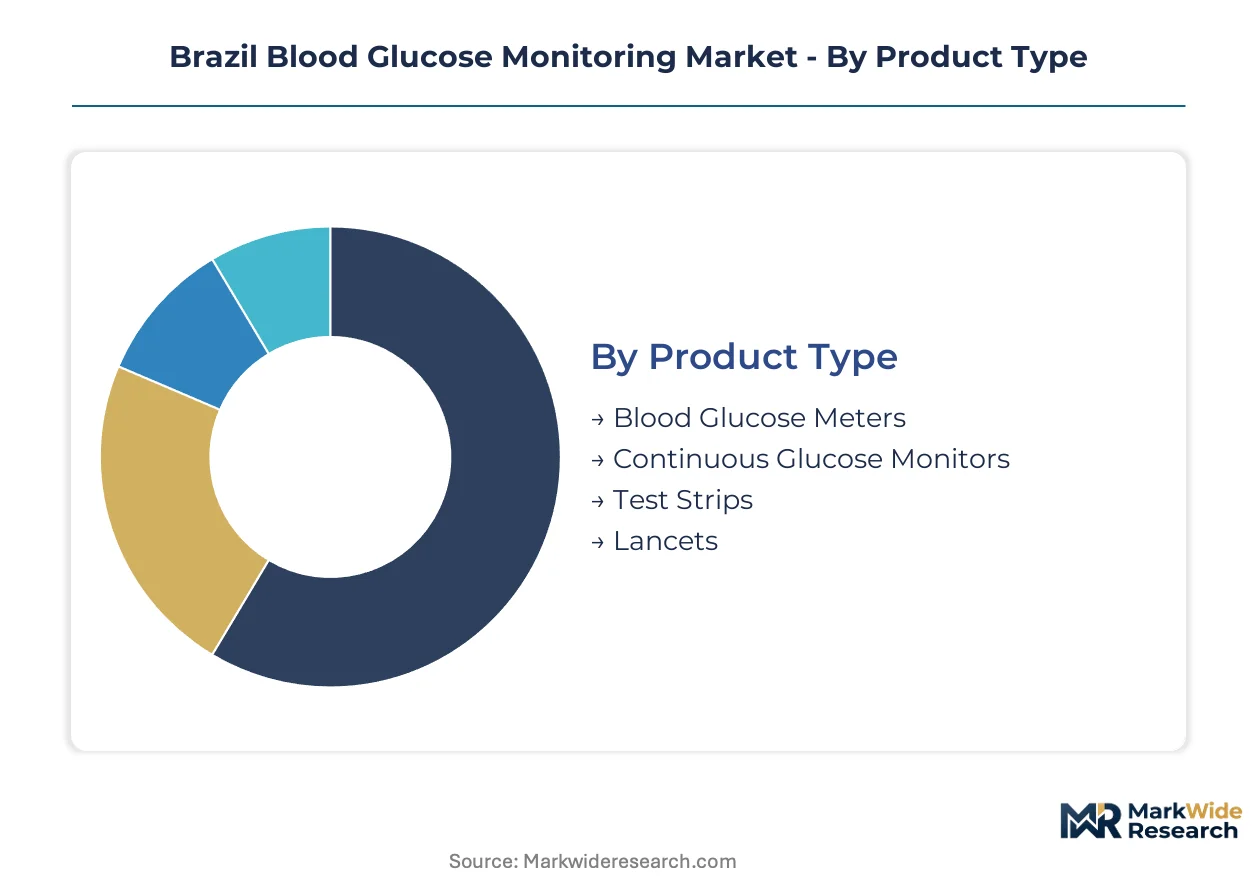
Brazil's blood glucose monitoring market fragments across four critical dimensions that determine pricing power, regulatory pathway, and channel strategy. Product type and technology choices define margin structures, while end user concentration and distribution channel control shape competitive access in Southeast metropolitan corridors.
Product Type:
Volume-driven consumables dominate revenue tonnage while premium integrated systems capture margin expansion in São Paulo and Rio de Janeiro healthcare networks.
- Test Strips:Disposable electrochemical strips utilizing glucose oxidase chemistry on polymer substrates deliver capillary results in under five seconds. Demand concentrates among Type 2 diabetics in SUS-funded public health networks, where reimbursement pressure compresses manufacturer margins despite massive patient volumes.
- Continuous Glucose Monitors:Subcutaneous filament sensors with wireless transmitters enable 14-day interstitial monitoring without fingerstick calibration. São Paulo's elderly diabetic population is accelerating adoption three times faster than traditional meters, rewriting pharmacy inventory models toward subscription-based sensor replenishment.
- Blood Glucose Meters:Handheld electrochemical devices paired with disposable strips remain the entry-level standard for newly diagnosed patients across Northeast Brazil.
- Lancets:Spring-loaded penetration devices for capillary blood sampling support the installed base of fingerstick-dependent diabetics in Minas Gerais and Paraná public clinics.
Today's leader: Test Strips. Tomorrow's challenger: Continuous Glucose Monitors.
End User:
Care setting determines device complexity requirements and reimbursement eligibility under ANVISA's medical device classifications.
- Home Care:Self-monitoring patients in São Paulo state are shifting from institutional testing toward decentralized glycemic management, driving demand for simplified calibration and mobile app connectivity.
- Hospitals:Acute care facilities in Rio de Janeiro metropolitan corridors require multi-patient monitoring systems with electronic health record integration and nurse station alerting protocols.
- Clinics:Outpatient diabetes centers in Belo Horizonte and Curitiba balance point-of-care efficiency with cost constraints from municipal health budgets.
- Pharmacies:Retail dispensing points across the Southeast region are consolidating purchasing through centralized procurement desks, squeezing independent diabetes specialty shops.
Home Care captures the steepest expansion trajectory as elderly populations in São Paulo accelerate self-monitoring adoption.
Technology:
Enzymatic stability versus non-enzymatic accuracy tradeoffs define competitive positioning across Brazil's temperature and humidity ranges.
- Enzymatic:Glucose oxidase and dehydrogenase chemistries on flexible substrates deliver proven accuracy stability across Brazilian climate conditions. Southeast region hospitals and home care patients rely on this established platform for consistent performance.
- Wearable:Skin-adhesive patch formats with factory-calibrated sensors eliminate fingerstick dependence for Type 1 patients in São Paulo's private health networks.
- Wireless:Bluetooth-enabled transmitters stream real-time data to smartphone applications, enabling remote monitoring by caregivers in dispersed rural communities.
- Non-Enzymatic:Alternative sensing approaches using direct electrochemistry or optical methods attract R&D investment but fail to match enzymatic stability in field conditions typical of Northeast Brazil.
Enzymatic platforms anchor current installed base. Wearable form factors are climbing fastest among Type 1 patient segments.
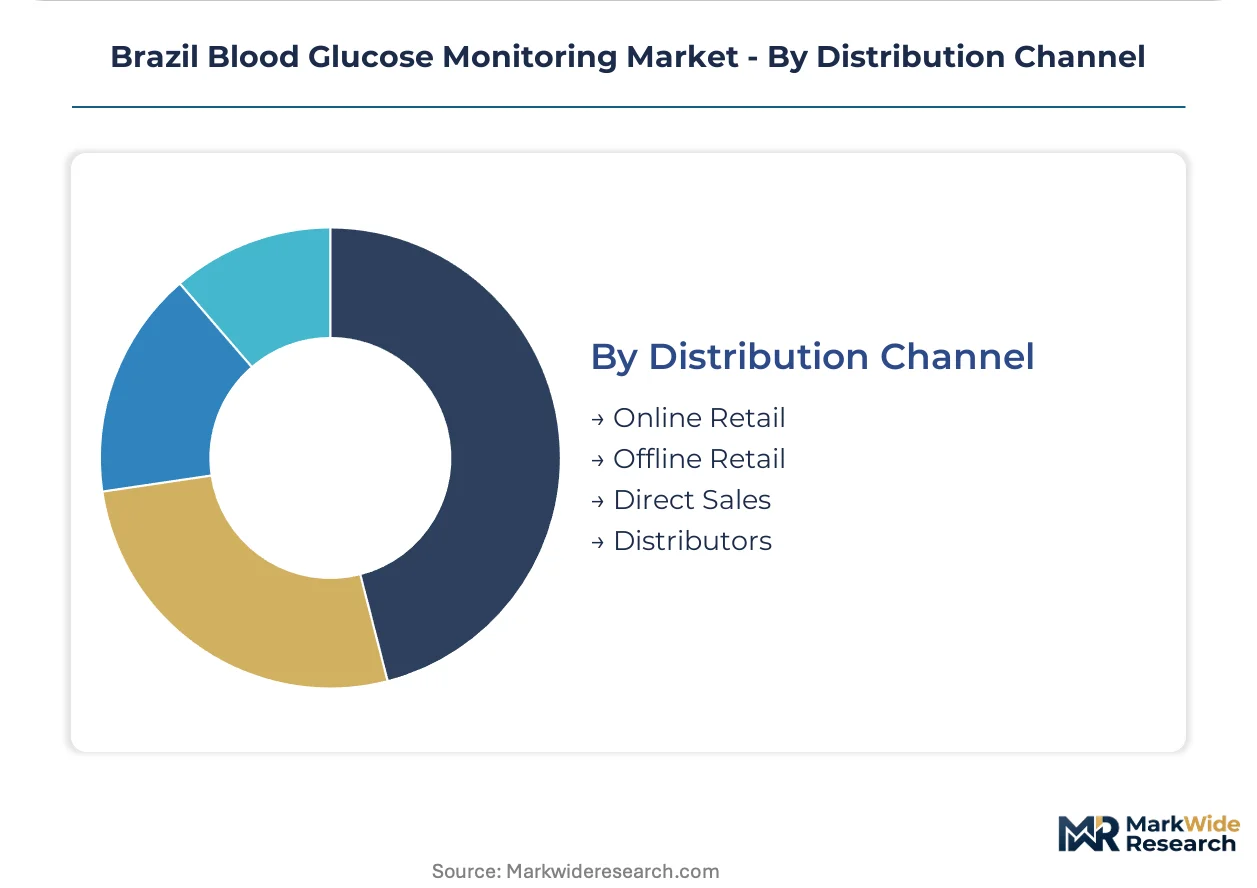
Distribution Channel:
Channel control determines patient access speed and technical support quality across Brazil's fragmented geography.
- Offline Retail:Pharmacy banners with exclusive distribution agreements dominate CGM dispensing in the Southeast, where three groups control sixty percent of sensor access points.
- Distributors:Specialized medical device wholesalers manage ANVISA import documentation and in-country testing validation for foreign manufacturers facing twelve-to-eighteen month regulatory lag.
- Online Retail:E-commerce platforms expand access for consumable replenishment in underserved Northeast states, though CGM calibration support remains limited.
- Direct Sales:Manufacturer field teams serve large hospital contracts in Rio de Janeiro and São Paulo with integrated closed-loop system installations.
Offline Retail commands current patient touchpoints. Online Retail is gaining share fastest in peripheral state markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo state's metropolitan corridor anchors Brazil's blood glucose monitoring demand through dense elderly diabetic populations and concentrated private health infrastructure.
São Paulo
Self-monitoring adoption among elderly diabetics accelerates three times faster than institutional testing growth. ANVISA's updated medical device traceability requirements compress product launch timelines for imported monitors. Pharmacy banners in Greater São Paulo control sixty percent of continuous glucose monitor dispensing points through exclusive distribution agreements.
Minas Gerais
Public health networks in Belo Horizonte balance point-of-care efficiency with municipal budget constraints from SUS formulary classifications. The state's transition to ANVISA's Unique Device Identification mandates creates steepest documentation burdens for legacy procurement systems. Diagnostic lab relationships across Minas Gerais public clinics sustain traditional blood glucose meter demand.
Rio de Janeiro
Acute care facilities in metropolitan corridors require multi-patient monitoring systems with electronic health record integration and nurse station alerting protocols. SUS reimbursement classifications for continuous glucose monitors widen patient eligibility among low-income diabetics in the region. Independent diabetes specialty shops lose shelf space to pharmacy banners with exclusive Abbott and Roche agreements.
Bahia
Northeast underpenetration creates whitespace for pharmacy channel expansion with forty percent lower continuous glucose monitor adoption than Southeast benchmarks. E-commerce platforms expand access for consumable replenishment in underserved state markets. Salvador's municipal health budgets constrain point-of-care device procurement despite rising diabetic prevalence.
Paraná
Curitiba's outpatient diabetes centers balance efficiency imperatives with SUS reimbursement pressure on disposable consumables. ANVISA's in-country testing requirements create twelve-to-eighteen month regulatory lag for foreign manufacturers versus domestic assemblers. Spring-loaded lancet demand concentrates in public clinics serving fingerstick-dependent patient populations.
Brazil Blood Glucose Monitoring Market Competitive Environment
Strategic partnerships dominate the current landscape as manufacturers restructure distributor liability frameworks under ANVISA's evolving traceability rules. The vendor base concentrates around three pharmacy groups controlling sixty percent of sensor access points in the Southeast region. Diagnostic specialists and diversified medtech conglomerates represent the primary competitive archetypes. Portfolio diversification and geographic channel consolidation constitute the dominant competitive moves reshaping market access.
Among diversified healthcare conglomerates, Roche Diagnostics and Abbott Laboratories occupy positions exemplifying the diagnostic-lab-anchored and pharmacy-channel-controlled archetypes respectively. Medtronic sits within the hospital-to-home connectivity tier. These three entities represent the competitive anchors around which ANVISA compliance investments and SUS formulary negotiations revolve.
| Leading Market Players |
|---|
| Roche Diagnostics |
| Lifescan |
| Abbott Laboratories |
| Siemens Healthineers |
| Johnson & Johnson |
| Medtronic |
| Ascensia Diabetes Care |
| Bayer Healthcare |
| Dexcom |
| Others |
Value Chain & Pricing Dynamics
Performance-grade bifurcation between factory-calibrated continuous glucose monitors and fingerstick-dependent test strips manifests in divergent margin structures and procurement pathways across Brazilian healthcare networks. Premium sensor subscriptions command sustained pricing power through pharmacy banner exclusivity, while commoditized strips face SUS reimbursement compression that reshapes manufacturer sourcing toward domestic assembly partners.
Pricing Analysis
Input-cost pass-through from glucose oxidase enzyme substrates and flexible polymer substrates determines manufacturer margin resilience across product tiers. Three-tier pricing structure across premium, standard, and economy levels separates Abbott's FreeStyle Libre subscriptions from Roche's Accu-Chek meters and SUS-procured generic strips. Pricing pressure stems from ANVISA's in-country testing requirements that extend cost recovery timelines for imported devices. Public health network procurement committees exhibit highest price sensitivity, while private insurance-funded patients in São Paulo show lowest elasticity for wearable form factors.
Supply Chain Analysis
Regional distribution centers in São Paulo and Rio de Janeiro anchor hub-and-spoke patterns that feed pharmacy banners across Southeast Brazil. Manufacturing concentration centers on China, Ireland, and Malaysia for sensor filament production, with final assembly shifting toward domestic facilities to circumvent ANVISA import validation bottlenecks. Raw material dependencies include palladium-based electrode coatings, hydrophilic polymer membranes, and Bluetooth transmitter chipsets. Single-source vulnerability in enzymatic reagent supply creates exposure to pharmaceutical-grade chemical export restrictions. Distribution runs through three consolidated pharmacy groups controlling sensor access points, supplemented by specialized medical device wholesalers managing ANVISA documentation for foreign entrants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's blood glucose monitoring sector represents a late-cycle quality story where reimbursement alignment with continuous glucose monitoring accuracy standards drives demand migration toward premium specifications. SUS formulary expansion for factory-calibrated sensors signals durable preference shifts away from fingerstick dependence.
For Market Incumbents: Anticipate margin compression in test strip portfolios by accelerating backward integration into enzymatic reagent production and securing exclusive pharmacy distribution renewals before ANVISA's MDR traceability rules reshape liability frameworks. Channel control through São Paulo pharmacy banners remains the critical defensive lever against emerging wearable competitors. For New Entrants and Emerging Players: Begin with underpenetrated Northeast states where Bahia and Pernambuco show forty percent lower CGM adoption than Southeast benchmarks, leveraging e-commerce platforms for consumable replenishment while building telehealth partnerships for remote calibration support. Direct-to-patient subscription models bypass consolidated pharmacy gatekeepers. For Investors and Strategic Acquirers: Consolidation pressure builds where ANVISA compliance investments exceed fifty million reais and distributor liability restructuring fragments market access for mid-tier foreign manufacturers. Acquisition targets include domestic assemblers with validated in-country testing infrastructure and established SUS procurement relationships. Watch for SUS reimbursement code expansions for closed-loop insulin pump systems as inflection indicator for hospital-to-home connectivity convergence.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA MDR Traceability Compliance | Unique Device Identification mandates reshape distributor liability and import documentation for all glucose monitors entering Brazilian networks. |
| SUS Reimbursement Strategy | Formulary expansion for continuous glucose monitors widens patient eligibility among low-income diabetics in Southeast metropolitan corridors. |
| Pharmacy Channel Partnership | Exclusive distribution agreements with three Southeast pharmacy groups control sixty percent of sensor dispensing access points. |
| Domestic Assembly Footprint | In-country testing validation circumvents twelve-to-eighteen month regulatory lag for foreign manufacturers versus domestic assemblers. |
| Telehealth Platform Integration | Supplemental health insurer reimbursement codes for remote glucose monitoring enable subscription revenue models beyond transactional strip sales. |
Study Parameters
Direct dialogue with ANVISA regulatory affairs specialists, hospital biomedical engineers, pharmacy procurement directors, and SUS formulary committee members grounded qualitative insights in operational reality. Secondary validation drew from ANVISA medical device registration databases, SUS reimbursement classification bulletins, ISO 15197 laboratory certification records, and Southeast Brazil pharmacy chain annual disclosures. Bottom-up patient volume estimates triangulated against top-down manufacturer shipment data through distributor channel checks.
Segmented projections across product type, technology platform, end-user setting, and distribution channel fed into analytical framework spanning the projection horizon. Modeled dimensions included enzymatic versus non-enzymatic sensing approaches, home care versus institutional care settings, and offline retail versus direct sales penetration. CAGRs derived from logistic adoption curves fitted to continuous glucose monitor penetration rates in comparable Latin American markets, calibrated by SUS reimbursement elasticity parameters and ANVISA approval timeline distributions.
Several conditions sit outside the modeled scope, including abrupt ANVISA regulatory reversals, SUS formulary contraction events, and breakthrough non-enzymatic sensing technologies achieving field-stable accuracy. Forecasts reflect documented assumptions around reimbursement trajectory continuity and import validation timeline stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Type 2 Diabetes Mellitus Treatment Market
Diabetes Care
South Africa Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Global Pet Diabetes Care Market
Diabetes Care
Italy Continuous Glucose Monitoring Devices Market
Diabetes Care
Diabetes Care Devices Market
Diabetes Care
Global Continuous Glucose Monitoring Systems Market
Diabetes Care
Vietnam Oral Anti-Diabetic Drug Market
Diabetes Care
Australia Self-Monitoring Blood Glucose Market
Diabetes Care
Europe Insulin Infusion Pumps Market
Diabetes Care
Egypt Diabetes Care Devices Market
Diabetes Care
Saudi Arabia Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Germany Insulin Infusion Pump Market
Diabetes Care
New Zealand Continuous Glucose Monitoring Devices Market
Diabetes Care
Japan Oral Anti-Diabetic Drug Market
Diabetes Care
United States Blood Glucose Monitoring Market
Diabetes Care
Global Blood Glucose Test Strip Market