
 Pen Needles Market | 2026-2036
Pen Needles Market Size, Share, and Industry Trends Forecast 2026-2036
Pen Needles Market Intelligence
Needle gauge miniaturization is narrowing the gap between injection comfort and drug delivery reliability across pen needle platforms. Novo Nordisk A/S leverages its integrated diabetes care ecosystem to sustain premium positioning in high-gauge segments. Becton, Dickinson and Company anchors North American supply through captive distribution networks and hospital formulary control. Ypsomed AG differentiates via self-injection systems that bundle pen needles with connected delivery devices.
Pen needles are hollow, beveled-tip steel cannulas mounted on plastic hubs, engineered for attachment to prefilled drug pens and typically manufactured through electro-polished stainless steel drawing with silicone lubrication to minimize tissue trauma during subcutaneous administration. Safety pen needles command widening share as sharps-protection regulations harden, while 32G and 33G gauges lead growth trajectories due to reduced pain perception in insulin and GLP-1 therapy. Homecare patients now represent the dominant end-user channel as chronic disease management shifts from clinical settings to domestic environments, concentrating margin pools in direct-to-patient and pharmacy subscription models.
FDA 510(k) clearance pathways and EMA Medical Device Regulation (MDR) conformity assessments govern market access, with OSHA Bloodborne Pathogens Standard and EU sharps directive mandating safety-engineered designs that elevate engineering costs but barrierize commoditized competitors. ISO 11608-2 needle performance standards define dimensional tolerances and penetration force thresholds that manufacturers must certify against for multi-market registration. Stakeholders must monitor evolving GLP-1 drug viscosity profiles and biologic formulation trends to align needle bore and lubrication investments with next-generation therapy requirements.
Market Dynamics
GLP-1 therapy expansion and homecare self-injection protocols are compressing hospital channel volumes while elevating safety-engineered needle specifications across regulated markets.
Growth Catalysts
- FDA Safety-Engineered Device Mandates:OSHA Bloodborne Pathogens Standard enforcement drives conversion from conventional to retractable and shielded pen needle platforms in US clinical settings.
- Homecare Patient Migration:Chronic disease management protocols now prioritize domestic insulin and biologic administration, expanding pharmacy-direct and subscription-based procurement channels.
- Silicone Lubrication Advances:Electropolished stainless steel drawing combined with enhanced surface coatings reduces penetration force thresholds, improving patient compliance in high-frequency injection regimens.
Market Restraints
- Raw Material Concentration:Medical-grade stainless steel supply concentrates in German and Japanese specialty metallurgy producers, exposing manufacturers to input volatility and alloy specification delays.
- Regulatory Friction:EMA MDR conformity assessment timelines extend market access durations for novel safety mechanisms, compressing effective patent windows.
- Substitution Pressure:Needle-free jet injectors and microneedle arrays advance in vaccine and insulin delivery, threatening conventional cannula platforms in specific therapeutic categories.
Strategic Opportunities
- Brazil ANVISA Safety Mandates:Pending sharps-protection regulations will compel device upgrades across Latin America's largest diabetes patient population, creating first-mover positioning for compliant suppliers.
- Connected Delivery Convergence:Bluetooth-enabled dose tracking integrated with pen needle platforms opens recurring revenue streams through data subscription models.
- GLP-1 Formulation Evolution:Higher-viscosity biologic therapies require optimized bore geometries and lubrication chemistries, differentiating engineering-capable manufacturers from commodity producers.
Industry Challenges
- ISO 11608-2 Certification Complexity:Multi-market registration requires dimensional tolerance verification across varying metrology standards, extending quality assurance timelines.
- Sharps Disposal Infrastructure:Homecare waste management lacks standardized collection protocols, creating liability exposure and patient education burdens for device manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pen Needles Market |
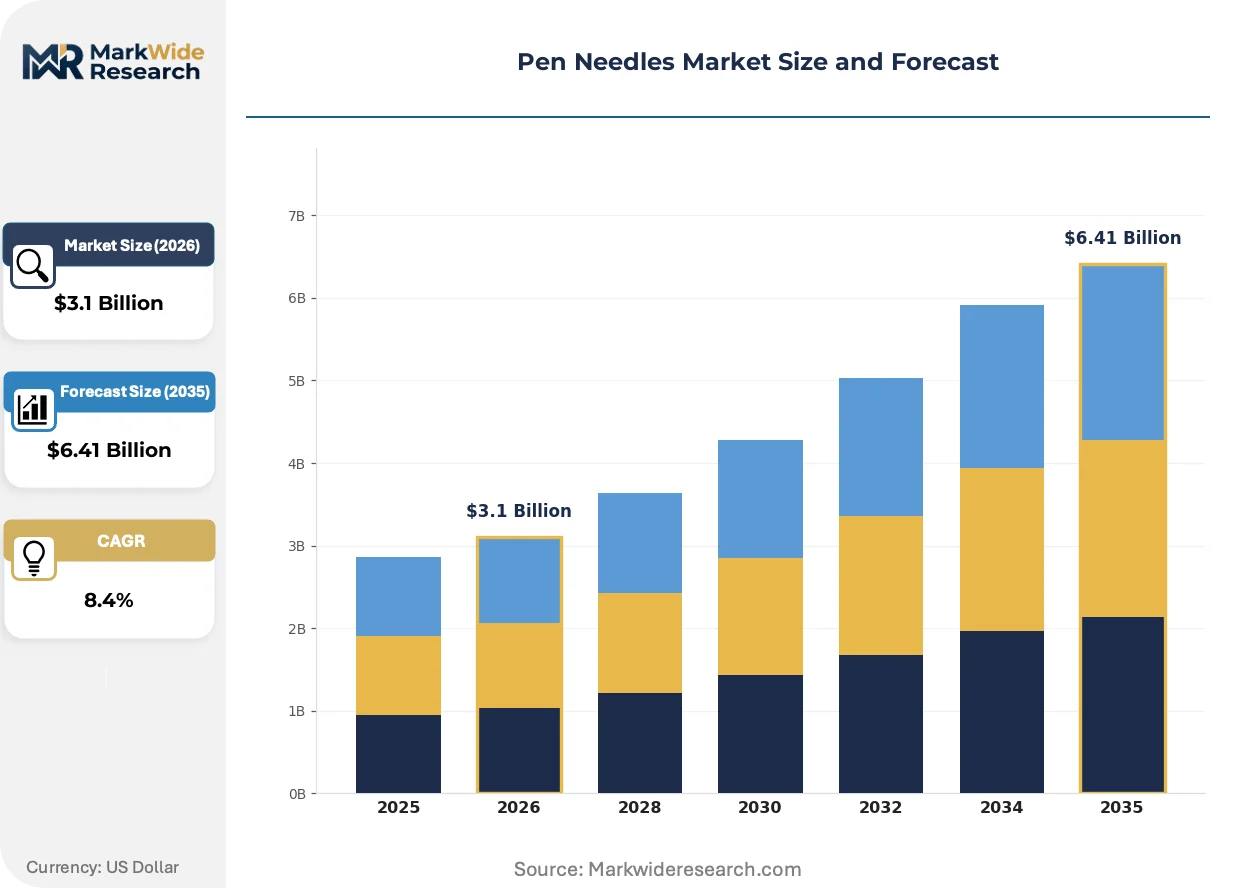
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $6.41 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Pen Needles, Safety Pen Needles, Vial Pen Needles, Custom Pen Needles Needle Size: 31G, 32G, 33G, 34G End User: Homecare Patients, Hospitals, Clinics, Pharmacies Material: Stainless Steel, Plastic, Coated Needles, Biodegradable Materials |
| Companies Covered | Novo Nordisk A/S, Becton, Dickinson and Company, Terumo Corporation, Ypsomed AG, Embecta Corp., Owen Mumford Ltd., B. Braun SE, HTL-STREFA, NIPRO Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pen Needles Market Strategic Shifts & Innovations
Needle gauge miniaturization, connected device integration, and regulatory harmonization pressures are restructuring competitive requirements across pen needle manufacturing.
Ultra-thin wall 33G cannula technology with enhanced structural integrity is rendering obsolete 30G and 31G platforms in insulin and GLP-1 therapy segments. Endocrinology practices and pharmacy chains in Germany and Japan are accelerating adoption of these finer gauges. The shift is compressing average selling prices for legacy gauge categories while concentrating margin capture among metallurgy specialists capable of maintaining lumen patency at reduced diameters.
EU MDR Article 10 technical documentation requirements and FDA 510(k) third-party review pilot programs are elevating clinical evidence thresholds for safety-engineered pen needle variants. Manufacturers now face expanded biocompatibility testing and human factors validation studies prior to market authorization. High-gauge safety pen needle segments bear disproportionate compliance costs, favoring scaled producers with dedicated regulatory affairs infrastructure.
Direct-to-patient subscription models displace traditional distributor intermediaries in chronic therapy pen needle procurement. Pharmacy benefit managers and diabetes care platforms in the United States are consolidating purchasing volume through exclusive formulary arrangements. This channel compression rewards manufacturers with integrated logistics capabilities and penalizes pure-play component suppliers dependent on wholesale distribution networks.
Pen Needles Market Segmentation
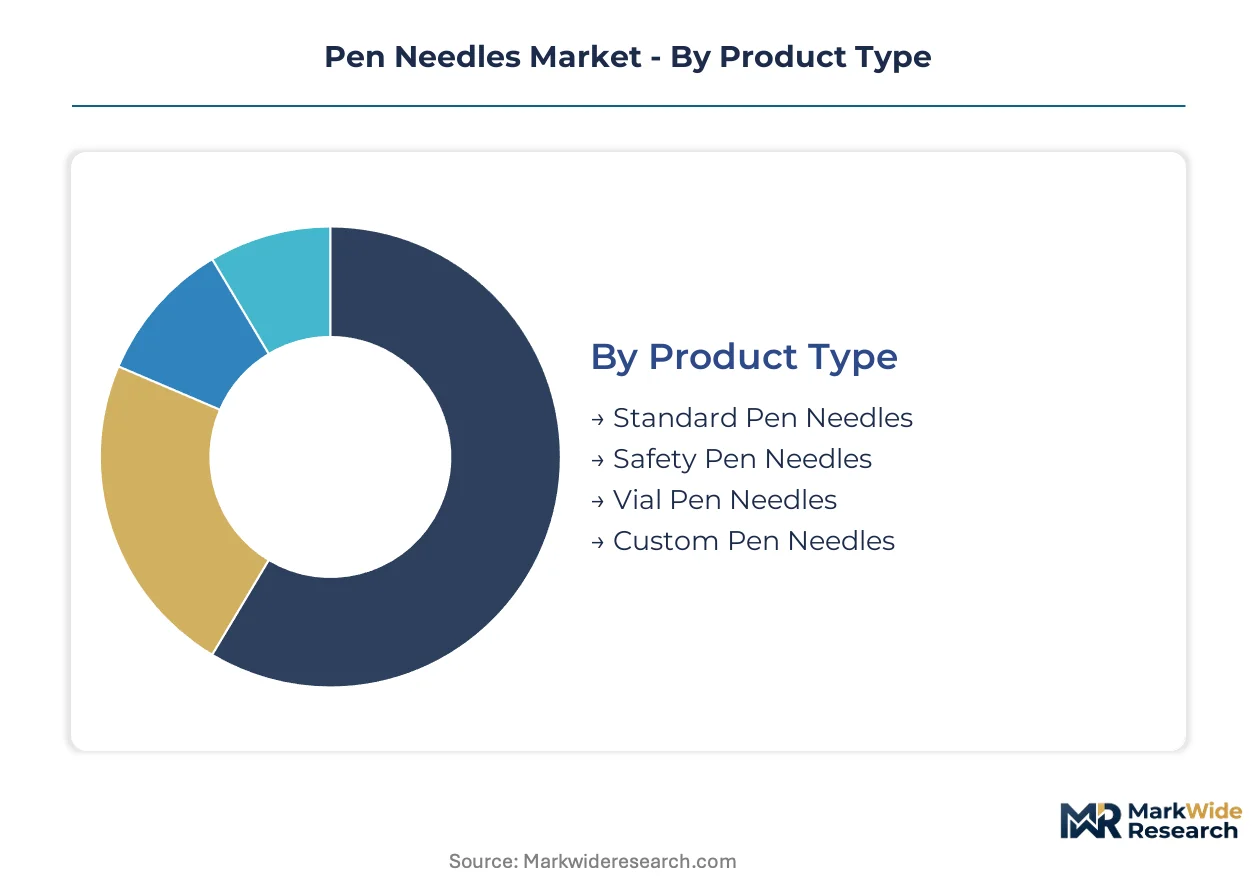
Pen needle segmentation reflects divergent clinical requirements across self-administration versus institutional settings, with gauge miniaturization and safety-engineered designs commanding distinct margin pools. Product architecture choices directly determine reimbursement eligibility and formulary access in regulated markets.
Product Type:
Standard configurations dominate high-frequency insulin therapy, while safety-engineered variants capture institutional procurement mandates.
- Standard Pen Needles:Conventional electro-polished stainless steel cannulas with fixed or removable hubs serve cost-sensitive homecare populations. Demand concentrates in pharmacy-direct channels across the United States and Germany, where patient copay structures favor basic specifications over premium safety features.
- Safety Pen Needles:Retractable and shielded mechanisms activate upon injection completion, eliminating post-use sharps exposure. OSHA Bloodborne Pathogens Standard enforcement in US hospitals and the EU sharps directive in German clinical settings are accelerating procurement conversion toward these engineered platforms despite 40-60% unit cost premiums.
- Vial Pen Needles:Dual-purpose designs compatible with both prefilled pens and traditional vial-syringe combinations address transitional patient populations. These hybrid specifications retain relevance in emerging markets where pen adoption lags vial-based protocols.
- Custom Pen Needles:Bespoke hub geometries and proprietary luer-lock interfaces serve biopharma partnerships for co-developed delivery systems. Novo Nordisk and Eli Lilly captive supply arrangements exemplify this segment's strategic value.
Established volume favors Standard Pen Needles; emerging adoption favors Safety Pen Needles.
Needle Size:
Gauge selection balances pain perception against lumen patency requirements for viscous biologic formulations.
- 31G:Legacy specification retaining installed base among long-duration insulin users. German and Japanese reimbursement frameworks still classify 31G as the standard of care for conventional human insulin.
- 32G:Electropolished thin-wall construction delivers 20% reduced penetration force versus 31G equivalents. US pharmacy chains and Japanese diabetes platforms are consolidating formulary preference around this gauge for GLP-1 and rapid-acting insulin portfolios.
- 33G:Ultra-fine platforms with enhanced structural ribbing prevent deflection during subcutaneous insertion. Homecare patients in the United States and Germany report highest satisfaction scores, driving fastest volume expansion among gauge categories.
- 34G:Experimental platforms approaching the metallurgical limits of lumen patency for standard insulin viscosities. PMDA in Japan and FDA pilot programs are evaluating human factors data for regulatory authorization.
Procurement gravity centers on 32G specifications; patient preference data favors 33G adoption curves.
End User:
Channel structure determines packaging formats, with institutional buyers requiring bulk configurations and homecare favoring unit-dose convenience.
- Homecare Patients:Direct-to-patient subscription models and pharmacy benefit manager formularies concentrate volume in this segment. US Medicare Part D and German statutory health insurance reimbursement frameworks prioritize pen needle access for domestic self-administration.
- Hospitals:Safety-engineered specifications dominate acute care procurement through group purchasing organization contracts. OSHA compliance audits and Joint Commission accreditation standards mandate sharps-protection features.
- Clinics:Endocrinology and diabetes specialty practices balance patient education needs with inventory efficiency. Mixed gauge availability supports individualized therapy initiation protocols.
- Pharmacies:Retail and mail-order channels intermediate between manufacturer and patient, with 90-day supply configurations gaining share in US commercial insurance plans.
Margin concentration favors Homecare Patients; regulatory compliance spending favors Hospitals.
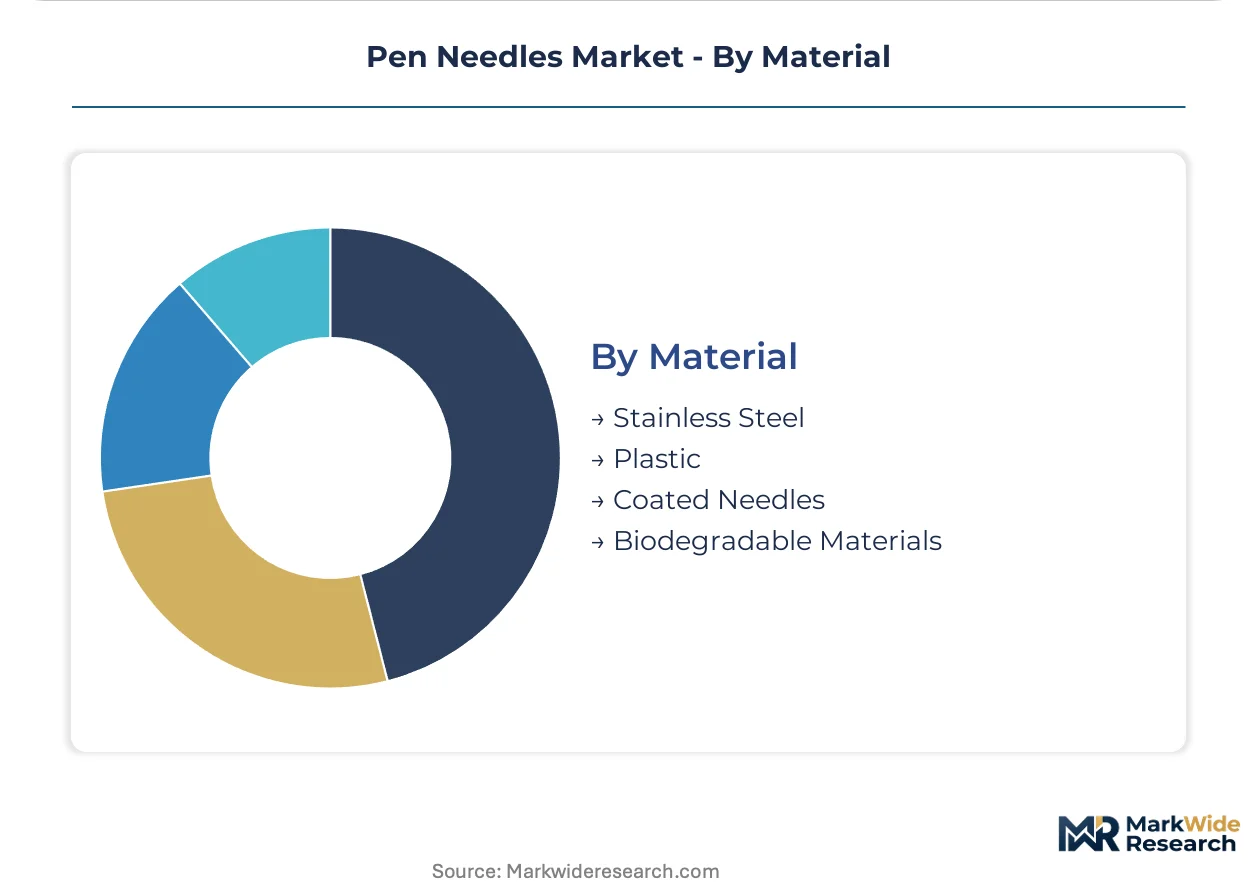
Material:
Substrate selection governs manufacturing yield, biocompatibility certification pathways, and end-of-life disposal characteristics.
- Stainless Steel:Medical-grade 304 and 316L alloys from German and Japanese metallurgy suppliers constitute the dominant cannula substrate. Electropolishing and passivation processes determine surface roughness and protein adhesion properties.
- Plastic:Hub components utilize medical-grade polypropylene and polycarbonate resins with dimensional stability for luer-lock interfaces. US and German medical device manufacturers maintain captive molding operations for supply security.
- Coated Needles:Silicone and fluoropolymer lubrication layers reduce penetration force and tissue trauma. EMA MDR biocompatibility testing requirements for novel coating chemistries extend development timelines.
- Biodegradable Materials:Polylactic acid and polyhydroxyalkanoate prototypes address sharps waste accumulation in homecare settings. ANVISA in Brazil and EPA guidelines in the United States are evaluating environmental impact claims.
Supply security favors Stainless Steel; sustainability positioning favors Biodegradable Materials.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows from German and Japanese metallurgy suppliers concentrate premium stainless steel substrate supply, while import dependence shapes manufacturing cost structures in pen needle assembly hubs across North America and Western Europe.
United States
Medicare Part D reimbursement frameworks and pharmacy benefit manager formularies drive homecare patient procurement volume. FDA 510(k) clearance pathways and OSHA Bloodborne Pathogens Standard enforcement elevate safety-engineered device specifications. Diabetes care platforms in the Greater Boston and Minneapolis-St. Paul corridors anchor GLP-1 therapy distribution networks.
Germany
Statutory health insurance pen needle access policies and endocrinology practice consolidation sustain high-frequency injection therapy demand. EMA MDR conformity assessments and EU sharps directive implementation tighten product authorization timelines. The Baden-Württemberg medical technology cluster concentrates electropolishing and surface coating capabilities for high-gauge cannula production.
Japan
PMDA regulatory frameworks and aging demographic diabetes prevalence sustain premium needle gauge adoption curves. METI industrial standards and JIS dimensional tolerances govern multi-market registration compatibility. The Kansai region around Osaka anchors specialty stainless steel drawing operations for ultra-thin wall 33G platforms.
Brazil
Pending ANVISA sharps-protection regulations and Latin America's largest diabetes patient population create safety-engineered device upgrade cycles. Public health system procurement centralization and pharmacy retail expansion reshape distribution channel structures. The São Paulo state industrial corridor concentrates plastic hub molding and final assembly operations for regional supply.
United Kingdom
NHS diabetes pathway standardization and primary care network self-injection training protocols elevate homecare patient channel volume. MHRA post-Brexit regulatory alignment processes and CE marking transition timelines extend market access procedures. The Midlands medical device manufacturing belt maintains hub component supply relationships with German metallurgy suppliers.
Pen Needles Market Key Industry Players
On the supply side, the industry is consolidating around integrated diabetes care ecosystems and captive distribution networks that barrierize commodity component producers. Tiered competitive positioning separates metallurgy-specialist manufacturers with electropolishing capabilities from pure-play assembly operations dependent on external substrate supply. Two strategic archetypes dominate: vertically integrated pharmaceutical-device hybrids and independent medical technology specialists with regulatory affairs infrastructure. Competitive moves concentrate on formulary control through pharmacy benefit manager relationships and geographic expansion via pending safety mandate compliance in Latin American markets.
Within the integrated pharmaceutical-device tier, Novo Nordisk A/S and Becton, Dickinson and Company occupy positions that exemplify divergent ecosystem strategies. Novo Nordisk represents the therapy-anchored archetype where pen needle supply secures biologic drug delivery continuity. Becton, Dickinson sits within the independent medical technology specialist category, with geographic naming suggesting North American supply chain anchoring. Ypsomed AG, with Swiss naming convention indicating European base, exemplifies the self-injection systems convergence archetype bundling pen needles with connected delivery platforms.
| Leading Market Players |
|---|
| Novo Nordisk A/S |
| Becton, Dickinson and Company |
| Terumo Corporation |
| Ypsomed AG |
| Embecta Corp. |
| Owen Mumford Ltd. |
| B. Braun SE |
| HTL-STREFA |
| NIPRO Corporation |
| Others |
Cost & Logistics Intelligence
German and Japanese specialty metallurgy producers concentrate medical-grade stainless steel supply, anchoring margin capture among electropolishing-capable manufacturers while compressing assembly-only competitors into price-taker positions.
Pricing Analysis
Homecare patients anchor pen needle pricing structures through pharmacy benefit manager formularies and direct-to-patient subscription models. Three-tier pricing structure across premium safety-engineered, standard electropolished, and economy basic specifications separates reimbursement-eligible from cash-pay segments. Cost compression in standard gauge categories is intensifying because of pharmacy chain generic substitution and 90-day supply consolidation. Uninsured cash-pay patients exhibit highest price sensitivity; integrated diabetes care platforms with captive device supply show lowest.
Supply Chain Analysis
Medical-grade 304 and 316L stainless steel feedstock draws from Baden-Württemberg electropolishing clusters and Osaka-Kobe drawing operations. Hub components source from US and German medical-grade polypropylene resin suppliers; silicone lubrication coatings hinge on fluoropolymer specialty chemical producers. Single-source vulnerability concentrates in ultra-thin wall 33G cannula metallurgy where Japanese suppliers dominate structural ribbing patents. Distribution runs through pharmacy benefit manager formularies and hospital group purchasing organization contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward pharmacy benefit managers and diabetes care platforms as formulary consolidation concentrates procurement volume, fragmenting margin pools among device manufacturers competing for exclusive supply arrangements.
For Market Incumbents: Entrench formulary control through backward integration into connected delivery ecosystems that bundle pen needles with Bluetooth-enabled dose tracking. Deepen regulatory affairs infrastructure to compress EMA MDR conformity timelines before patent windows narrow. Prioritize ISO 11608-2 certification maintenance across multi-market registrations to barrierize commodity competitors.
For New Entrants and Emerging Players: Pursue white-space positioning in Brazil's pending ANVISA safety mandate upgrade cycle before incumbent supply contracts solidify. Target biodegradable material prototypes for homecare sharps waste liability exposure where environmental claims differentiate. Deploy direct-to-patient digital pharmacy partnerships to bypass wholesale distributor gatekeepers.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed medical technology specialists holding FDA 510(k) cleared safety-engineered portfolios but lacking GLP-1 therapy alignment. Five-to-ten year viability hinges on viscosity-adaptive bore geometry capabilities as biologic formulations evolve. Watch for PMDA 34G gauge authorization signals as inflection indicator for next-generation metallurgy premium capture.
| Strategic Initiative | Industry Significance |
|---|---|
| Connected Device Integration | Bluetooth-enabled dose tracking opens recurring data subscription revenue streams beyond per-unit sales. |
| EMA MDR Conformity Investment | Accelerated technical documentation capabilities compress market access timelines for safety-engineered variants. |
| Brazil ANVISA Compliance Pre-positioning | First-mover safety-engineered supply arrangements capture Latin America's largest diabetes patient population. |
| GLP-1 Viscosity Adaptation R&D | Optimized bore geometries and lubrication chemistries differentiate engineering-capable manufacturers from commodity producers. |
| Direct-to-Patient Channel Development | Pharmacy subscription models displace distributor intermediaries and concentrate margin in manufacturer-patient relationships. |
Research Approach
Initial hypotheses were tested against primary input from hospital procurement managers, pharmacy benefit manager formulary directors, biomedical engineers at diabetes care platforms, and regulatory affairs leads at device manufacturers, then refined through secondary validation against FDA 510(k) filings, EMA MDR technical documentation databases, hospital GPO contract repositories, and CMS Medicare Part D utilization data. Bottom-up gauge-specific volume estimates triangulated against top-down therapy expansion projections.
Demand-supply balance modeling across the projection horizon incorporated patient population epidemiology, reimbursement framework evolution, and regulatory mandate implementation schedules. Segmentation dimensions included product type, needle gauge, end-user channel, material substrate, and geographic regulatory cluster. CAGRs derived from iterative convergence of patient volume forecasts and pricing trajectory assumptions, with GLP-1 therapy viscosity profiles and biologic formulation pipelines as key industry-specific inputs.
Macroeconomic conditions sit as an overlay; deviation in diabetes prevalence trajectories, statutory health insurance reimbursement rates, or medical device tariff structures would shift the trajectory. Cross-checking against WHO diabetes atlas projections and national health expenditure benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Chronic Total Occlusion Devices Market
Medical Devices
Syringe Filling Machine Market
Medical Devices
Spherical IOL Market
Medical Devices
Digital Flexible Ureteroscopes Market
Medical Devices
Global Trauma Fixation Devices Market
Medical Devices
Vaginal Specula Market
Medical Devices
Light Therapy Beauty Devices Market
Medical Devices
Adsorption Apheresis Devices Market
Medical Devices
Medical LED Headlight Market
Medical Devices
I.V. Fluid Warmer Market
Medical Devices
Global Casting Devices Market
Medical Devices
Global Continuous Peripheral Nerve Block Catheter Market
Medical Devices
IoT Medical Devices Market
Medical Devices
Ophthalmoscopes Market
Medical Devices
France Contraceptive Devices Market
Medical Devices
United Kingdom Spinal Surgery Devices Market