
 Global Diabetes Pen Market | 2026-2036
Global Diabetes Pen Market Size, Share, and Industry Trends Forecast 2026-2036
Global Diabetes Pen Market Analysis
Asset-light leasing models for smart pen platforms is tilting competitive dynamics toward firms with recurring revenue infrastructure rather than pure manufacturing scale. Novo Nordisk A/S leverages its vertical integration across insulin and delivery devices to sustain pricing power in premium segments. Eli Lilly and Company anchors its position through deep R&D investment in automated dosing systems. Ypsomed AG specializes in private-label manufacturing and competes aggressively on OEM partnerships with mid-tier pharma firms.
A diabetes pen is a handheld injection device designed for subcutaneous insulin delivery, typically featuring dose-adjustment mechanisms accurate to one-unit increments and compatible with standard 3-milliliter cartridges. Its primary commercial purpose centers on enabling precise, repeatable self-administration by patients outside clinical settings. Reusable pens and smart pens capture the strongest margin pools as Bluetooth-enabled devices command premium positioning through data integration with glucose monitors. Disposable pens dominate volume in emerging markets where upfront cost sensitivity shapes purchasing decisions, while pre-filled pens lead in hospital procurement channels due to workflow efficiency.
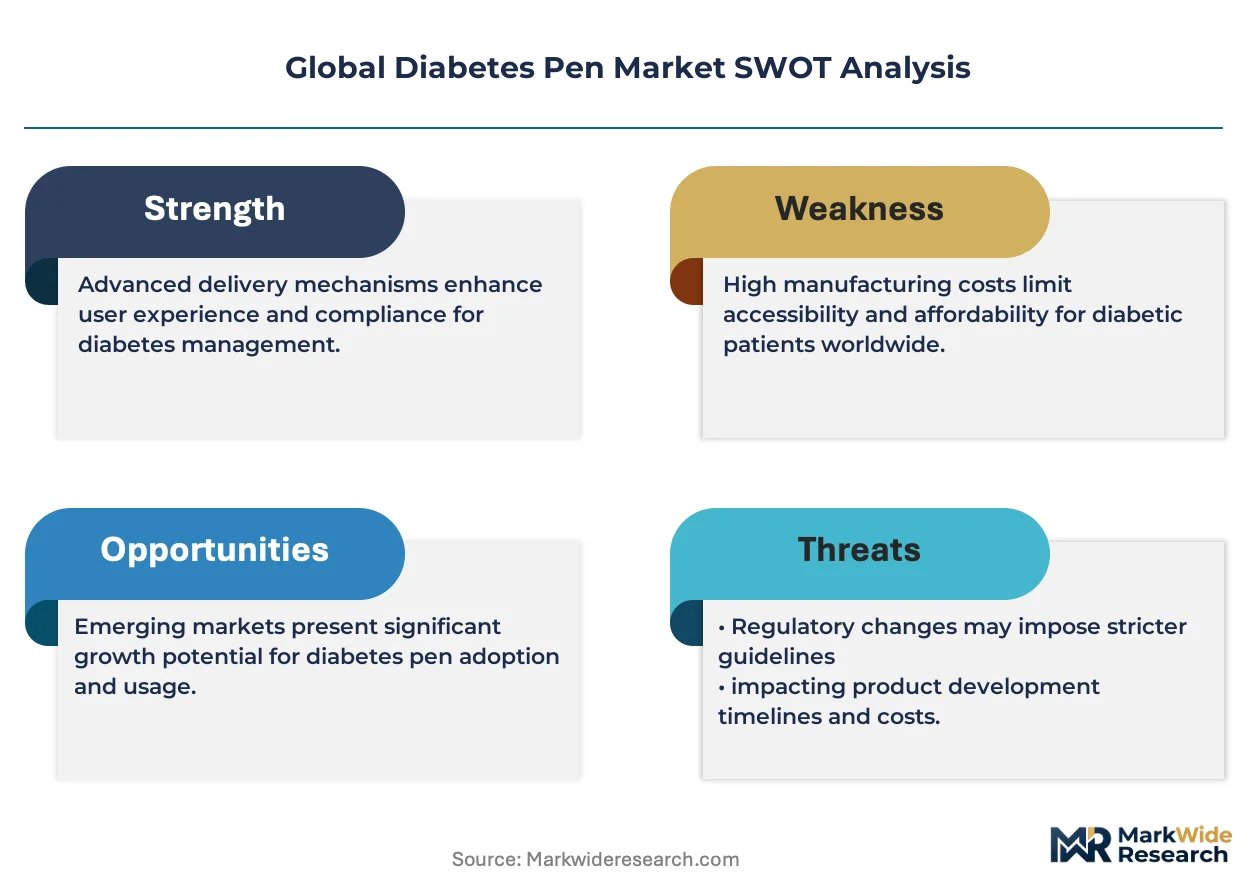
FDA premarket notification requirements for combination products and the EU Medical Device Regulation (MDR) establish divergent compliance burdens that fragment go-to-market timelines across the United States and Europe. The FDA's digital health software precertification pilot and EMA's evolving guidance on drug-device interoperability are creating new gatekeeping criteria for connected pen entrants. Stakeholders must monitor how reimbursement authorities in Germany, Japan, and the United States classify smart pens relative to traditional delivery devices, as this determination will shape investment allocation between connectivity features and core mechanical reliability.
Market Dynamics
The convergence of drug-device combination regulation with Bluetooth-enabled dosing systems is fragmenting competitive timelines and forcing dual-track compliance investments across the United States and Europe.
Growth Catalysts
- Home care migration:Patient self-administration preferences in the United States and Germany are pulling device procurement away from hospital formularies toward retail pharmacy channels.
- FDA digital health precertification:The pilot program is compressing software validation cycles for connected pen entrants seeking 510(k) clearance for glucose monitor integration.
- Reimbursement expansion:Japan's Ministry of Health, Labour and Welfare is adding smart pen categories to device-specific fee schedules, reducing out-of-pocket cost barriers for elderly diabetes patients.
Market Restraints
- EU MDR compliance burden:The 2017 Medical Device Regulation is extending notified body review timelines for pen needle combinations, delaying European launches by 12-18 months relative to FDA 510(k) pathways.
- Insulin cartridge supply concentration:Borosilicate glass sourcing for 3-milliliter cartridges clusters in Germany and India, exposing device makers to energy cost volatility and freight disruptions.
- Mechanical reliability thresholds:Dose accuracy requirements of plus-minus 5% at one-unit increments demand precision molding capabilities that concentrate among Swiss and Japanese component suppliers.
Strategic Opportunities
- Brazilian market underpenetration:ANVISA's accelerated pathway for Class II medical devices is opening access to a patient population where disposable pen adoption lags North American benchmarks by approximately fifteen years.
- Closed-loop convergence:Integration of continuous glucose monitor data streams with automated insulin dosing algorithms is creating premium positioning for pen platforms that can serve as bridge devices to full artificial pancreas systems.
- Direct-to-patient subscription models:Pharmacy benefit managers in the United States are piloting bundled device-and-consumable programs that bypass traditional durable medical equipment distribution.
Industry Challenges
- Combination product expertise scarcity:Engineers fluent in both pharmaceutical stability requirements and electromechanical design are concentrated at FDA-regulated firms, constraining expansion timelines for mid-tier manufacturers.
- Legacy health record integration:Hospital IT systems in Germany and Japan require HL7 FHIR compliance for connected device data, forcing pen makers to maintain multiple software stacks.
- Needlestick safety certification:ISO 11608-1:2022 needle-based injection system standards demand extensive usability testing that extends development cycles and consumes clinical trial budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Diabetes Pen Market |
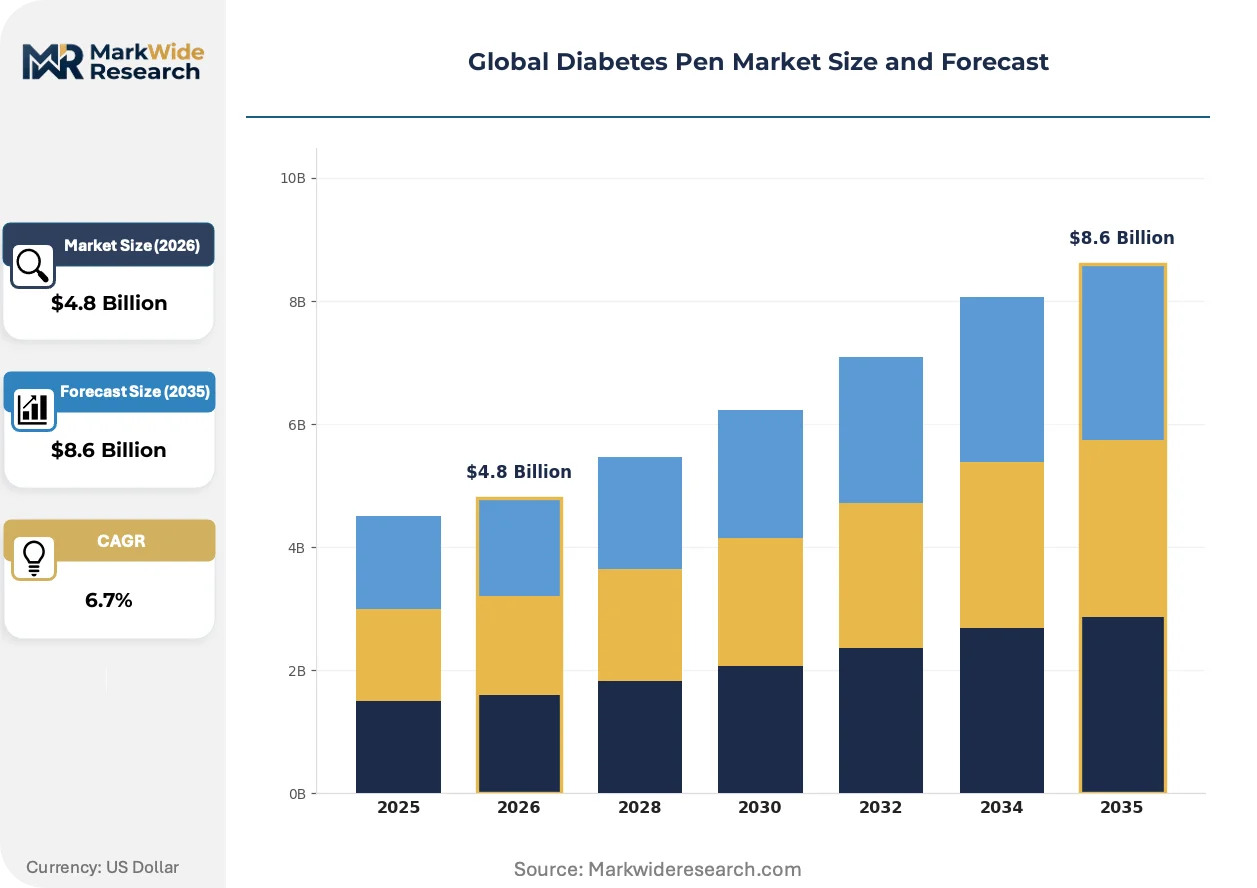
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable Pens, Reusable Pens, Smart Pens, Pre-filled Pens End User: Clinics, Hospitals, Home Care, Pharmacies Technology: Insulin Delivery, Bluetooth-enabled, Manual Injection, Automated Systems Dosage Form: Rapid-acting Insulin, Long-acting Insulin, Combination Insulin, Others |
| Companies Covered | Novo Nordisk A/S, Eli Lilly and Company, Sanofi S.A., Becton, Dickinson and Company, Ypsomed AG, Embecta Corp., Medtronic plc, Biocon Biologics, Terumo Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Diabetes Pen Market Emerging Trajectories
Connectivity architectures are forcing a redefinition of what constitutes the device itself, with software and data infrastructure now capturing margin pools that mechanical engineering once monopolized.
Bluetooth Low Energy modules paired with capacitive dose-sensing mechanisms are hybridizing the traditional pen from a passive delivery tool into an active data capture node. Endocrinology practices in the United States are adopting these platforms at replacement-cycle velocity, with patient monitoring services now bundled into device pricing. The technology is hybridizing competitive differentiation away from injection comfort metrics toward algorithmic dosing recommendations and retrospective glycemic pattern analysis.
The EU Medical Device Regulation's emphasis on post-market surveillance and unique device identification is tightening traceability requirements for pen-needle combinations sold in Germany, France, and Italy. Manufacturers must now maintain electronic systems capable of field safety corrective action initiation within 24 hours of incident reporting. Class IIa device reclassification for reusable pen bodies is forcing European-focused firms to rebuild quality management systems around notified body audit schedules rather than internal compliance calendars.
Hospital procurement committees are unbundling device acquisition from consumable supply contracts that previously locked institutions into single-source arrangements. Group purchasing organizations in the United States are negotiating pen platform-agnostic deals that separate mechanical device pricing from cartridge and needle economics. This disaggregation is most visible in integrated delivery networks across Texas and California, where pharmacy directors now evaluate connected pen platforms on interoperability with existing electronic health record investments rather than total cost of ownership metrics alone.
Global Diabetes Pen Market Segmentation
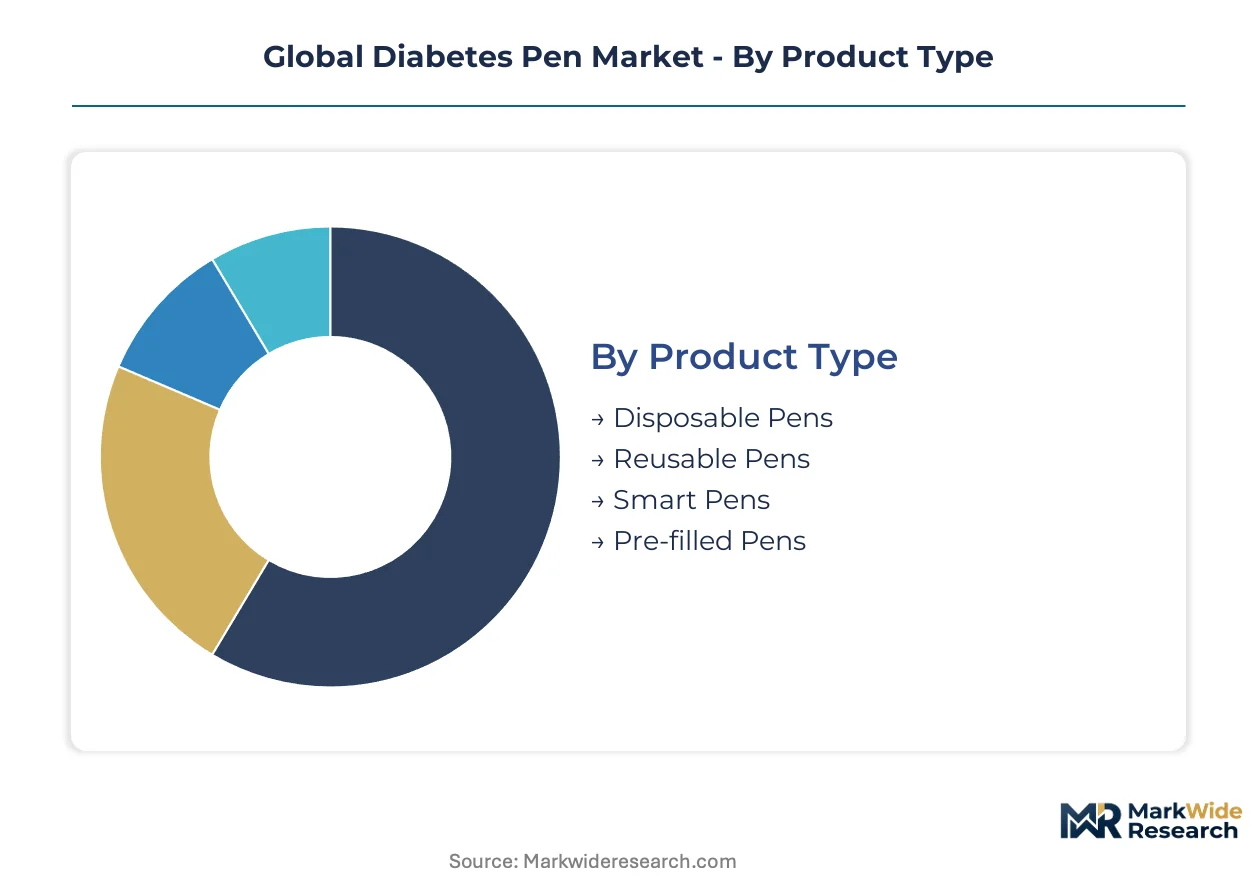
Diabetes pen segmentation reveals how device economics fragment across patient self-sufficiency levels, clinical settings, and reimbursement tiers. Understanding these divides exposes where margin pools concentrate versus where volume scales.
Product Type:
Reusable and smart pen platforms capture premium positioning through recurring revenue infrastructure, while disposable formats compete on patient acquisition cost.
- Disposable Pens:Single-use devices with fixed insulin cartridges eliminate cleaning protocols and cross-contamination risk. Demand concentrates in Brazil and India where out-of-pocket payment dominates and pharmacy retail channels prioritize low entry cost over lifetime value.
- Reusable Pens:Durable mechanical bodies accept replaceable 3-milliliter cartridges across multiple injection cycles. German and Japanese patients favor these devices under device-specific reimbursement schedules that separate durable equipment from consumable supplies.
- Smart Pens:Bluetooth-enabled dose logging and glucose monitor integration command premium pricing in United States endocrinology practices.
- Pre-filled Pens:Factory-sealed insulin-cartridge combinations dominate hospital procurement for workflow efficiency.
Established volume favors disposable pens; emerging adoption favors smart pens.
End User:
Procurement authority is decentralizing from hospital pharmacy committees toward retail channels and direct-to-patient platforms.
- Home Care:Patients self-administering insulin outside clinical settings drive replacement-cycle velocity for connected devices. United States pharmacy benefit managers are piloting subscription bundles that bypass durable medical equipment distributors.
- Hospitals:Integrated delivery networks in Texas and California evaluate pen platforms on HL7 FHIR interoperability with Epic and Cerner installations rather than total cost metrics alone.
- Clinics:Endocrinology practices adopt smart pens at replacement velocity to bundle monitoring services into device pricing.
- Pharmacies:Retail channels in Germany and Japan handle reimbursement processing for device-specific fee schedules.
Hospital procurement still commands volume scale; home care channels are climbing the fastest on connectivity pull-through.
Technology:
Electromechanical differentiation is displacing injection comfort as the primary competitive axis.
- Bluetooth-enabled:Low-energy modules paired with capacitive dose-sensing transform passive delivery tools into active data capture nodes. FDA digital health precertification is compressing software validation cycles for glucose monitor integration.
- Automated Systems:Dosing algorithms using continuous glucose monitor data streams serve as bridge devices to artificial pancreas systems. Eli Lilly anchors development here through deep R&D investment.
- Insulin Delivery:Core mechanical platforms without connectivity compete on dose accuracy and ergonomic design.
- Manual Injection:Spring-driven plunger mechanisms dominate emerging markets where electromechanical reliability remains unproven.
Mechanical reliability secures baseline volume; algorithmic dosing features are gaining share fastest among reimbursed populations.
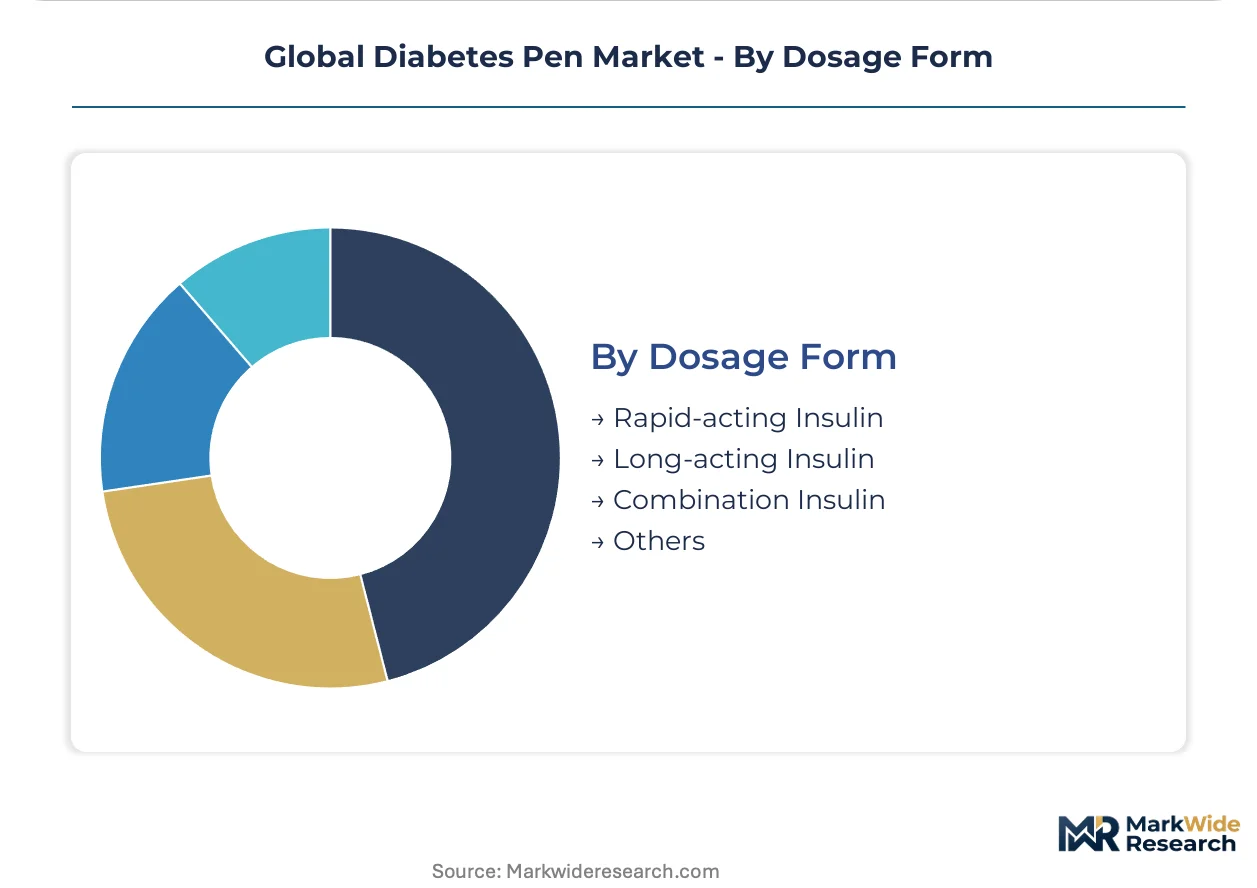
Dosage Form:
Insulin pharmacokinetics determine device compatibility requirements and cartridge formulation stability.
- Rapid-acting Insulin:Meal-time dosing demands precise one-unit increment adjustment and rapid absorption profiles. United States patients using CGM-driven correction boluses favor pens with dose logging to retrospectively analyze glycemic patterns.
- Long-acting Insulin:Basal coverage requires consistent subcutaneous deposition over 24-hour intervals. German reimbursement authorities classify these devices separately from prandial insulin delivery.
- Combination Insulin:Fixed-ratio mixtures of rapid and intermediate-acting formulations simplify regimens for elderly patients.
- Others:Biosimilar and concentrated insulin formulations require cartridge modifications.
Basal insulin maintains volume concentration; rapid-acting formats are expanding most quickly on closed-loop convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany runs a structural export surplus in precision-molded pen components, while the United States and Japan import finished devices to serve their expanding home-care patient populations. Trade flows concentrate borosilicate glass cartridges from German and Indian suppliers toward assembly operations in Switzerland and Japan.
United States
Pharmacy benefit managers pilot subscription bundles that bypass durable medical equipment distributors entirely. FDA digital health precertification compresses software validation cycles for glucose monitor integration. Endocrinology practices in Texas and California adopt connected pens at replacement-cycle velocity.
Germany
Device-specific reimbursement schedules separate durable equipment from consumable supplies, favoring reusable pen adoption. EU MDR extends notified body review timelines for pen-needle combinations by 12-18 months relative to FDA pathways. Industrial clusters around Stuttgart and Frankfurt concentrate precision molding capabilities for dose-accuracy components.
Japan
Ministry of Health, Labour and Welfare adds smart pen categories to device-specific fee schedules, reducing out-of-pocket barriers for elderly patients. PMDA reviews concentrate on electromechanical reliability for Bluetooth-enabled dosing systems. Manufacturing gravity centers on Nagoya and Osaka for spring-driven plunger mechanisms.
Brazil
ANVISA's accelerated pathway for Class II medical devices opens access to a patient population where disposable pen adoption lags North American benchmarks. Out-of-pocket payment dominance in pharmacy retail channels prioritizes low entry cost over lifetime value. São Paulo anchors distribution networks serving the Southeast region's concentrated diabetes prevalence.
India
Borosilicate glass sourcing for 3-milliliter cartridges clusters in Gujarat and Maharashtra, exposing device makers to energy cost volatility. CDSCO regulatory pathways for drug-device combinations remain less prescriptive than FDA or EMA frameworks. Hyderabad and Bangalore host emerging private-label manufacturing operations for mid-tier pharma firms.
Global Diabetes Pen Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying precision-molded bodies and cartridge interfaces. The vendor base concentrates around three strategic archetypes: vertically integrated pharmaceutical-device combinations, pure-play delivery system manufacturers, and private-label OEM suppliers. Consolidation pressures favor firms with recurring revenue infrastructure over pure manufacturing scale. Dominant competitive moves include backward integration into insulin formulation and technology licensing for Bluetooth connectivity modules.
Within the integrated pharmaceutical tier, Novo Nordisk A/S and Eli Lilly and Company exemplify platform control through captive supply of both drug and delivery device. Ypsomed AG occupies a position among specialized component fabricators competing aggressively on OEM partnerships. These three anchors illustrate how competitive differentiation fragments between connectivity-enabled premium positioning and mechanical reliability at scale-driven price points.
| Leading Market Players |
|---|
| Novo Nordisk A/S |
| Eli Lilly and Company |
| Sanofi S.A. |
| Becton, Dickinson and Company |
| Ypsomed AG |
| Embecta Corp. |
| Medtronic plc |
| Biocon Biologics |
| Terumo Corporation |
| Others |
Supply Flow & Price Mechanics
Stuttgart's precision molding cluster supplies dose-accuracy components to pen manufacturers worldwide, concentrating upstream capacity in German industrial zones that translate into downstream pricing leverage for reusable and smart pen tiers. This geographic anchoring of critical electromechanical capabilities shapes how device makers negotiate cartridge interfaces and plunger mechanisms across reimbursement markets.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Smart pens with Bluetooth-enabled glucose monitor integration command premium positioning through bundled patient monitoring services, while disposable formats compete on patient acquisition cost in pharmacy retail channels. Pricing pressure stems from group purchasing organizations unbundling device acquisition from consumable supply contracts in United States integrated delivery networks. Pharmacy benefit managers exhibit highest price sensitivity through direct-to-patient subscription pilots, whereas endocrinology practices demonstrate lowest sensitivity when evaluating interoperability with Epic and Cerner installations.
Supply Chain Analysis
Contract manufacturing for pen bodies concentrates among Swiss and Japanese component specialists with precision molding capabilities for ISO 11608-1:2022 compliance. Borosilicate glass for 3-milliliter cartridges draws from German and Indian suppliers, exposing device makers to energy cost volatility and freight disruptions. Single-source vulnerability clusters around spring-driven plunger mechanisms manufactured in Nagoya and Osaka. Distribution runs through durable medical equipment channels in Germany and Japan, while United States pharmacy benefit managers pilot bundled device-and-consumable programs bypassing traditional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Diabetes pen platforms are crossing into ecosystem economics where data infrastructure and glucose monitor interoperability determine competitive survival rather than mechanical reliability alone. This shift rewards firms with recurring revenue infrastructure and penalizes pure manufacturing scale.
For Market Incumbents: Entrench platform control through backward integration into insulin formulation and captive supply of cartridge interfaces. Novo Nordisk's vertical integration across drug and device illustrates defensive positioning against pure-play delivery system manufacturers. Invest in FDA digital health precertification to compress software validation cycles for connected pen entrants. Maintain dual-track compliance investments for EU MDR notified body audits that extend European launch timelines.
For New Entrants and Emerging Players: Pursue white-space opportunities in Brazilian pharmacy retail channels where disposable pen adoption lags North American benchmarks and ANVISA's accelerated Class II pathway reduces regulatory friction. Target private-label manufacturing partnerships with mid-tier pharma firms lacking in-house delivery system capabilities. Anchor go-to-market strategy on OEM relationships rather than branded device competition against vertically integrated pharmaceutical-device combinations.
For Investors and Strategic Acquirers: Long-term, this sits as a recurring revenue infrastructure play because pharmacy benefit manager subscription bundles and connected pen data services are displacing transactional device economics. Acquisition targets should emphasize firms with Bluetooth connectivity module licensing and HL7 FHIR compliance capabilities. Monitor FDA premarket notification timelines for combination products as inflection indicator for competitive access fragmentation.
| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy | Japan's Ministry of Health, Labour and Welfare device-specific fee schedules reduce out-of-pocket barriers for elderly patients. |
| Software Companion Development | FDA digital health precertification compresses validation cycles for glucose monitor integration in connected pen platforms. |
| Hospital System Partnership | Texas and California integrated delivery networks evaluate pen platforms on Epic and Cerner interoperability rather than total cost metrics. |
| CE Marking Pathway | EU MDR extends notified body review timelines for pen-needle combinations, forcing quality management system rebuilds. |
| Regulatory Approval Pathway | ANVISA's accelerated Class II medical device pathway opens Brazilian access where disposable pen adoption lags benchmarks. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EMA submissions, hospital procurement databases, and GPO contracts. Primary interviews engaged regulatory affairs leads at combination product firms, biomedical engineers at precision molding suppliers, formulary directors at pharmacy benefit managers, and GPO contracts managers at United States integrated delivery networks. Bottom-up triangulation across device shipment data and top-down validation through insulin prescription volumes ensure segmentation integrity.
Forecast inputs include patient self-administration migration rates, reimbursement schedule expansions for smart pen categories, and regulatory timeline divergence between FDA and EU MDR pathways. Segmentation models incorporate product type, end user channel, connectivity technology, and insulin dosage form across the projection horizon. CAGRs derive from replacement-cycle velocity analysis for connected devices and volume scaling assumptions for disposable formats in emerging markets.
Macroeconomic conditions sit as an overlay; deviation in energy costs for borosilicate glass production or freight rates from German and Indian suppliers would shift the trajectory. Forecasts reflect assumptions around FDA digital health precertification program continuity and EU MDR notified body capacity expansion. Quarterly review of regulatory submission timelines, reimbursement authority device classifications, and pharmacy benefit manager pilot program expansions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Japan Insulin Drugs and Delivery Devices Market
Diabetes Care
Global Smart Diabetes Management Market
Diabetes Care
Latin America Insulin Infusion Pump Market
Diabetes Care
Asia Pacific Continuous Glucose Monitoring (CGM) Market
Diabetes Care
Japan Insulin Infusion Pump Market
Diabetes Care
Oman Insulin Drugs and Delivery Devices Market
Diabetes Care
Diabetic Pen Cap Market
Diabetes Care
South Africa Continuous Glucose Monitoring Market
Diabetes Care
Malaysia Insulin Infusion Pump Market
Diabetes Care
India Oral Anti-Diabetic Drug Market
Diabetes Care
Oman Diabetes Drugs Market
Diabetes Care
Mexico Diabetes Care Devices Market
Diabetes Care
Wearable Glucometers Market
Diabetes Care
Global Pet Diabetes Care Market
Diabetes Care
Middle East and Africa Diabetes Market
Diabetes Care
Canada Self-Monitoring Blood Glucose Market