
 Iran Diabetes Care Devices Market | 2026-2036
Iran Diabetes Care Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Iran Diabetes Care Devices Market Foresight
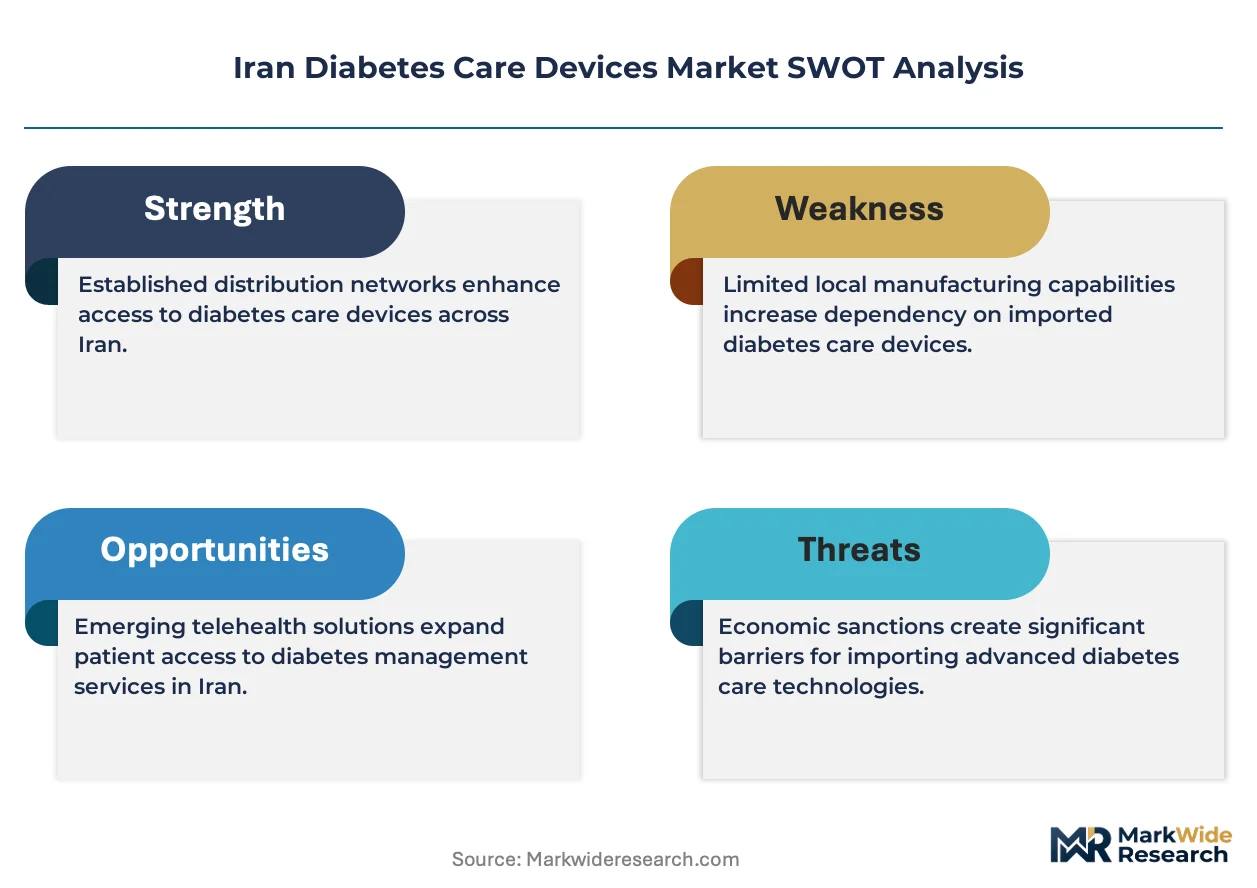
Leasing arrangements for insulin pump systems is rewriting competitive dynamics among Iranian distributors and foreign manufacturers. Abbott leverages its established diagnostics footprint to sustain glucose monitoring sales through local partnerships. Medtronic anchors the premium pump segment with direct service capabilities in Tehran. Sanofi competes across multiple device categories while navigating Iran's complex pharmaceutical import licensing framework.
Iran diabetes care devices encompass electromechanical and disposable instruments engineered to measure blood glucose concentration, deliver exogenous insulin, or continuously track interstitial glucose levels with calibration accuracy typically within 15% of laboratory reference values. These systems serve to reduce hyperglycemic episodes, prevent microvascular complications, and enable patient self-management outside clinical settings. Blood glucose meters retain the largest installed base across Iranian healthcare facilities, while continuous glucose monitors represent the fastest-expanding category driven by wireless connectivity integration. Homecare deployment of Bluetooth-enabled devices is accelerating as patients seek remote monitoring capabilities, though hospitals still capture the dominant margin pool through bulk procurement of integrated systems.
Iran's national pharmaceutical regulator enforces medical device registration requirements that shape import timelines and product standardization for diabetes care equipment. The country's central bank oversees foreign currency allocation for pharmaceutical and device imports, directly influencing supply availability and pricing stability. Stakeholders must monitor regulatory pathway efficiency and currency access protocols to determine market entry timing and partnership structures.
Market Dynamics
Hospital procurement centralization under Iran's Ministry of Health is compressing distributor margins while accelerating registration timelines for integrated glucose monitoring systems. This structural shift favors manufacturers with direct Tehran service capabilities over traditional import-dependent distribution models.
Growth Catalysts
- Medical Device Registration Protocols:Iran's national pharmaceutical regulator has streamlined approval pathways for continuous glucose monitors, reducing import clearance delays and enabling faster hospital adoption of wireless-enabled systems.
- Tehran Clinic Concentration:Specialized diabetes clinics in the capital serve as referral hubs for advanced insulin delivery systems, creating concentrated demand pull for premium device categories.
- Bluetooth Connectivity Integration:Wireless data transmission is digitizing patient self-monitoring workflows and enabling remote physician oversight outside traditional clinical settings.
Market Restraints
- Foreign Currency Allocation Bottlenecks:Iran's central bank controls pharmaceutical and device import financing, creating supply volatility when currency access tightens for distributor payment settlements.
- Single-Source Pump Component Supply:Precision insulin pump motors and sensors concentrate among European and Asian specialty manufacturers, exposing procurement to geopolitical shipment disruptions.
- Calibration Accuracy Limitations:Continuous glucose monitors require laboratory reference validation that remains unevenly available across provincial healthcare networks.
Strategic Opportunities
- Isfahan and Shiraz Provincial Expansion:Secondary city diabetes clinics currently rely on Tehran referral networks, creating whitespace for regional distribution partnerships and localized service centers.
- Homecare Remote Monitoring:Patient-managed Bluetooth-enabled devices are penetrating residential settings faster than hospital procurement cycles, opening direct-to-patient channel development.
- Leasing Model Innovation:Insulin pump rental arrangements reduce upfront patient cost barriers while generating recurring revenue streams for distributors with maintenance capabilities.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Device calibration, repair, and patient training functions require specialized technicians that Iranian technical universities produce in insufficient volume.
- Import License Renewal Complexity:Iran's pharmaceutical import licensing framework demands annual revalidation that consumes distributor administrative bandwidth and creates product availability gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iran Diabetes Care Devices Market |
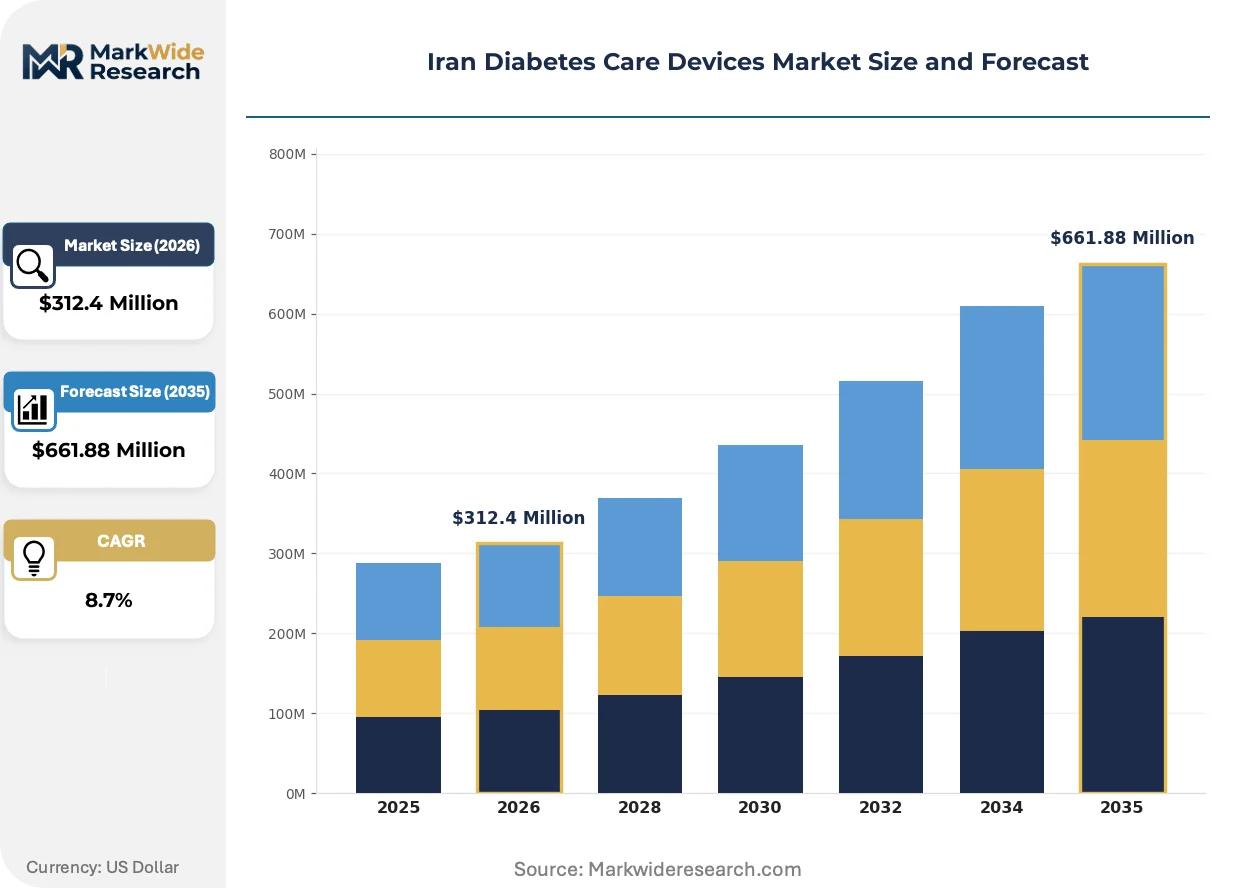
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin Pumps, Continuous Glucose Monitors, Blood Glucose Meters, Lancets Technology: Wireless, Bluetooth, Integrated, USB End User: Hospitals, Homecare, Diabetes Clinics, Research Institutions Application: Management, Monitoring, Diagnostics, Education |
| Companies Covered | Abbott, Sanofi, Medtronic, Becton Dickinson, Eli Lilly, Roche, Dexcom, Insulet, Novo Nordisk, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iran Diabetes Care Devices Market Shifts & Advancements
Wireless connectivity integration is compressing the gap between hospital-grade and home-use glucose monitoring capabilities. Three distinct forces are reshaping how devices reach patients and how data flows between clinical and non-clinical settings.
Continuous glucose monitoring systems with factory-calibrated sensors are digitizing the traditional blood glucose meter supply chain. Tehran's specialized diabetes clinics are adopting these systems at accelerated pace to reduce nursing staff measurement workload. The technology is digitizing patient record integration and enabling automated insulin dosing recommendations that previously required manual physician calculation.
Iran's national pharmaceutical regulator is enforcing stricter medical device registration protocols that mandate local clinical trial data for wireless-enabled monitors. This regulatory friction is extending approval timelines for new entrants while insulating incumbent manufacturers with existing registration dossiers. Continuous glucose monitor categories face the most significant compliance burden as connectivity features trigger additional cybersecurity review requirements.
Patient-initiated device acquisition is displacing pure hospital procurement as the dominant demand channel for insulin delivery systems. Iranian distributors are responding by building direct patient education capabilities and retail pharmacy partnerships that bypass traditional clinic referral pathways. This behavioral shift is most visible in Tehran's northern districts where higher disposable incomes support out-of-pocket premium device purchases.
Iran Diabetes Care Devices Market Segmentation
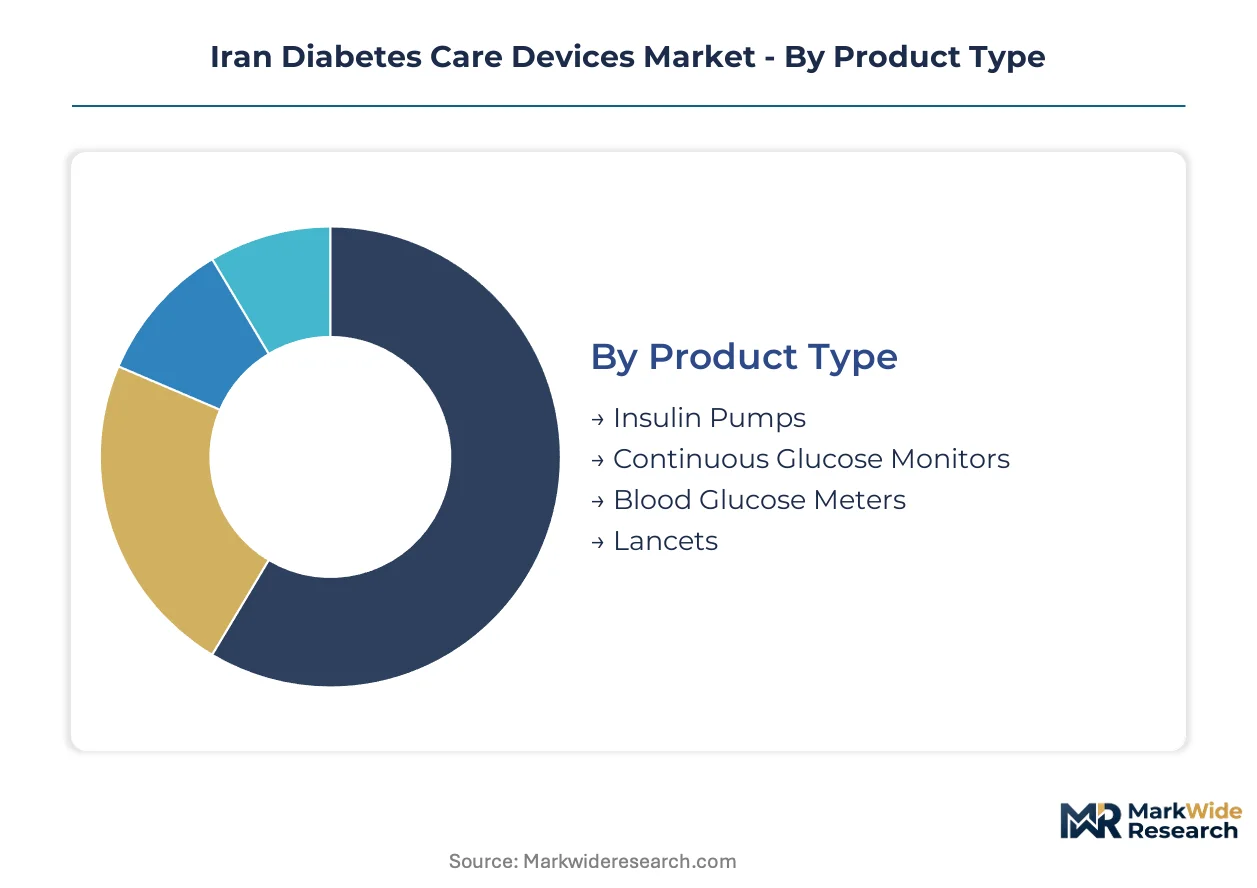
Segmentation of Iran's diabetes care devices market reveals distinct procurement patterns across product categories, connectivity technologies, and care settings. Tehran's concentrated healthcare infrastructure creates uneven penetration rates that reward targeted channel strategies.
Product Type:
Mature electromechanical systems anchor hospital procurement budgets while emerging sensor-based platforms reshape outpatient economics.
- Insulin Pumps:Precision motor-driven delivery systems administer basal and bolus insulin doses through subcutaneous infusion sets. Tehran's specialized diabetes clinics drive demand for programmable pumps with carbohydrate ratio calculators, constrained by foreign currency allocation bottlenecks for European-sourced precision components.
- Continuous Glucose Monitors:Factory-calibrated interstitial sensors transmit glucose readings wirelessly to receivers or smartphones. Adoption concentrates among northern Tehran districts where disposable income supports out-of-pocket acquisition, accelerated by the national pharmaceutical regulator's streamlined registration protocols for wireless-enabled systems.
- Blood Glucose Meters:Electrochemical strip-based devices retain dominant installed base across provincial healthcare networks.
- Lancets:Single-use sterile penetration devices accompany meter procurement in bulk hospital tenders.
Blood glucose meters retain volume leadership; continuous glucose monitors hold the steepest expansion curve.
Technology:
Cost tier stratification separates premium wireless systems from economy wired alternatives, with connectivity features commanding 3-4x price multiples.
- Wireless:Radiofrequency-enabled devices transmit data without physical tethering to display units. Hospital procurement centralization under Iran's Ministry of Health favors integrated wireless systems that reduce nursing documentation burden, though cybersecurity review requirements extend registration timelines.
- Bluetooth:Short-range wireless protocol enables direct smartphone integration for patient self-monitoring. Homecare deployment accelerates fastest in Tehran's northern districts where patients seek remote physician oversight without clinic visits, bypassing traditional referral pathways.
- Integrated:Closed-loop systems combine sensing and delivery in unified hardware platforms.
- USB:Wired data transfer remains standard for economy meter segments and legacy hospital installations.
Bluetooth-enabled devices gain share fastest in direct-to-patient channels; integrated systems command premium positioning in centralized hospital tenders.
End User:
Customer type determines procurement mechanism, with institutional buyers negotiating bulk pricing against individual patient out-of-pocket purchases.
- Hospitals:Acute care facilities and tertiary medical centers procure integrated monitoring systems through Ministry of Health central tenders. Bulk purchasing compresses distributor margins while accelerating registration timelines for manufacturers with direct Tehran service capabilities.
- Homecare:Patient-managed settings drive fastest growth for Bluetooth-enabled devices that bypass clinical workflows. Iranian distributors build retail pharmacy partnerships and direct education capabilities to capture this demand shift outside traditional clinic channels.
- Diabetes Clinics:Specialized outpatient facilities serve as referral hubs for advanced insulin delivery systems.
- Research Institutions:Academic medical centers generate limited but high-specification demand for clinical trial equipment.
Hospitals retain dominant margin pool concentration; homecare represents the fastest-climbing demand channel.
Application:
Volume distribution across use cases reflects Iran's healthcare system structure, with therapeutic management commanding resources against preventive monitoring.
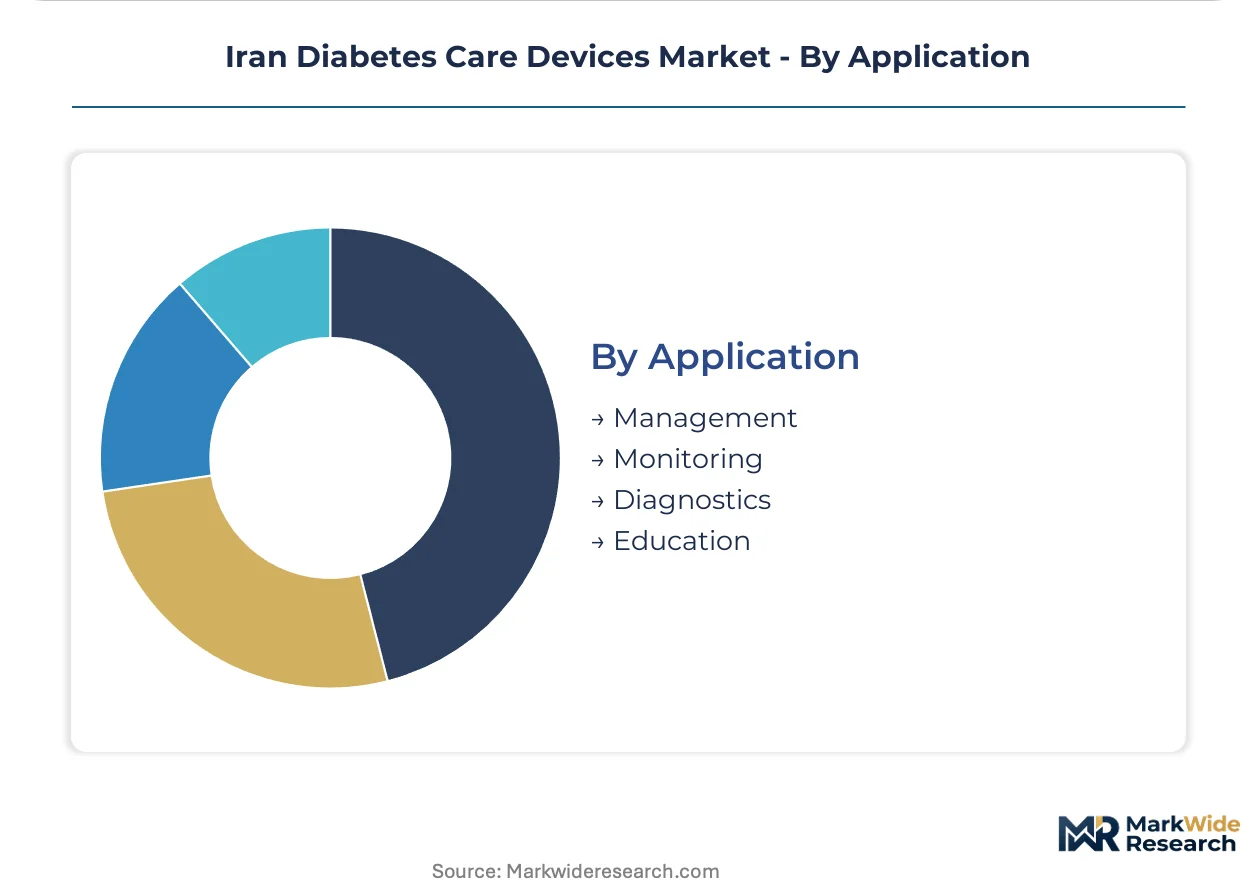
- Management:Insulin dosing and glycemic control interventions consume largest device expenditure share. Tehran's specialized clinics concentrate demand for programmable delivery systems that automate dosing calculations, reducing physician consultation frequency.
- Monitoring:Continuous and episodic glucose measurement enables patient self-adjustment of therapy. Provincial healthcare networks outside Tehran face uneven laboratory reference validation availability, constraining calibration accuracy for sensor-based systems.
- Diagnostics:Screening and confirmation testing for diabetes mellitus classification.
- Education:Training devices and demonstration equipment for patient self-management instruction.
Management applications anchor revenue concentration; monitoring functions expand most quickly as wireless connectivity penetrates residential settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tehran commands premium device pricing power that provincial markets cannot replicate, while Isfahan and Shiraz operate under tighter foreign currency constraints that compress margins for identical product categories.
Tehran Province
Specialized diabetes clinics in northern Tehran districts drive concentrated demand for continuous glucose monitors and programmable insulin pumps. Iran's Ministry of Health centralizes hospital procurement through this region, accelerating registration timelines for wireless-enabled systems. The capital's healthcare infrastructure anchors national distribution networks, with direct service capabilities determining manufacturer competitive positioning.
Isfahan Province
Secondary city diabetes clinics rely on Tehran referral networks for advanced insulin delivery systems, creating whitespace for regional distribution partnerships. The national pharmaceutical regulator's import licensing framework extends clearance delays outside the capital, constraining product availability. Localized service centers are emerging to reduce patient travel burden for device calibration and training.
Shiraz Province
Fars province healthcare networks face uneven laboratory reference validation availability, limiting continuous glucose monitor calibration accuracy. Iran's central bank foreign currency allocation prioritizes Tehran-based distributors, exposing Shiraz procurement to payment settlement volatility. Retail pharmacy partnerships are developing to bypass traditional clinic channels for patient-initiated device acquisition.
Mashhad Region
Khorasan Razavi province serves as an eastern hub connecting Afghan border trade routes with domestic distribution networks. Stricter medical device registration protocols under the national pharmaceutical regulator delay new entrant approvals relative to Tehran timelines. Homecare deployment of Bluetooth-enabled devices accelerates fastest where disposable incomes support out-of-pocket purchases outside hospital procurement cycles.
Tabriz and Northwest
East Azerbaijan province maintains cross-border equipment trade relationships with Turkish medical device suppliers. The region's industrial base supports limited biomedical engineering talent pools for device repair and patient training functions. Provincial healthcare networks concentrate blood glucose meter procurement in bulk tenders while continuous glucose monitor penetration lags Tehran benchmarks by several years.
Iran Diabetes Care Devices Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream where precision motors and sensors concentrate among European and Asian manufacturers. The vendor base stratifies across three tiers: multinational manufacturers with direct Tehran service capabilities, regional distributors managing import licensing complexity, and local assemblers serving economy meter segments. Two strategic archetypes dominate—diagnostics conglomerates leveraging established distribution footprints, and diabetes-focused specialists anchoring premium pump categories. Competitive moves center on leasing model innovation for insulin pumps and direct patient education capabilities that bypass traditional clinic referral pathways.
Among multinational platform providers, Abbott, Medtronic, and Sanofi exemplify contrasting archetype strategies. Abbott occupies a position representing diagnostics footprint leverage, sustaining glucose monitoring sales through local partnerships without direct service infrastructure. Medtronic anchors the premium pump segment with direct Tehran capabilities that compress competitor response times. Sanofi sits within a diversified pharmaceutical-device hybrid archetype, competing across multiple categories while navigating Iran's complex import licensing framework. These three companies collectively illustrate how regulatory pathway efficiency and currency access protocols determine partnership structures and market entry timing.
| Leading Market Players |
|---|
| Abbott |
| Sanofi |
| Medtronic |
| Becton Dickinson |
| Eli Lilly |
| Roche |
| Dexcom |
| Insulet |
| Novo Nordisk |
| Others |
Supply & Pricing Matrix
Bandar Abbas port clearance costs shape procurement economics for European insulin pump components entering Iran, concentrating supply leverage among Tehran-based distributors with established customs relationships while forcing three-tier pricing stratification across provincial healthcare networks.
Pricing Analysis
Hospital procurement committees anchor contract pricing for integrated glucose monitoring systems, with Ministry of Health tenders favoring wireless-enabled platforms that command premium positioning against economy meter alternatives. Price differentiation stems from CE marking tier and after-sales calibration service bundling. Cost compression in the standard tier is intensifying because foreign currency allocation bottlenecks squeeze distributor margins. Provincial clinics exhibit highest price sensitivity; northern Tehran private patients show least.
Supply Chain Analysis
Tariff exposure between Germany and Iran dominates procurement planning for precision insulin pump motors, with alternative sourcing from South Korea and Japan providing partial hedge. Component dependencies center on electrochemical sensor substrates, lithium battery cells, and sterile infusion set polymers. Single-source vulnerability concentrates in European specialty manufacturers for programmable pump controllers. Distribution runs through Tehran-based authorized distributors with direct Ministry of Health registration dossiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Iran's diabetes care devices market is recovering from currency-driven supply disruptions, with cyclical normalization of central bank pharmaceutical import financing enabling restocking momentum across provincial clinic networks.
For Market Incumbents: Harden service infrastructure in Isfahan and Shiraz before regional competitors establish localized calibration centers. Consolidate distributor relationships to offset emerging direct-to-patient channel threats from retail pharmacy partnerships. Prioritize backward integration into maintenance technician training programs to address biomedical engineering talent scarcity.
For New Entrants and Emerging Players: Establish a beachhead in Bluetooth-enabled homecare devices for Tehran's northern districts, where disposable income supports out-of-pocket acquisition outside hospital procurement cycles. Target secondary city diabetes clinics in Mashhad and Tabriz that currently rely on Tehran referral networks. Deploy direct patient education capabilities through retail pharmacy partnerships as the primary go-to-market angle.
For Investors and Strategic Acquirers: Regional distributors with established import licensing dossiers and maintenance service capabilities represent the most defensible acquisition archetype in this market. Long-term viability rests on regulatory pathway efficiency rather than volume scale, given Iran's national pharmaceutical regulator's extended approval timelines for wireless-enabled systems. Watch foreign currency allocation priority shifts for pharmaceutical imports as the primary inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy | Navigating Iran's Ministry of Health central tender protocols accelerates hospital procurement adoption. |
| Hospital System Partnership | Direct Tehran service capabilities compress competitor response times for integrated system deployments. |
| Software Companion Development | Bluetooth-enabled remote monitoring platforms bypass traditional clinic referral pathways in homecare settings. |
| CE Marking Pathway | European certification expedites registration dossier approval under Iran's national pharmaceutical regulator. |
| Biomedical Engineering Talent Program | In-house technician training addresses calibration and repair scarcity constraining provincial service expansion. |
Research Methodology
Desk research of Iranian customs import records, Ministry of Health procurement databases, and central bank pharmaceutical financing circulars preceded structured interviews with hospital purchasing committee members, biomedical engineering directors at Tehran diabetes clinics, distributor operations managers, and national pharmaceutical regulator officials. Primary fieldwork combined with secondary validation against GPO contracts and device registration dossiers. Bottom-up provincial demand modeling and top-down import value triangulation anchored market sizing.
Forecast assumptions held Iran's medical device registration protocol efficiency and foreign currency allocation priority for pharmaceutical imports constant across the analysis window, while varying provincial healthcare infrastructure investment rates and patient self-monitoring technology adoption curves. Segmentation dimensions modeled include product type, connectivity technology, end-user setting, and regional procurement cluster. CAGRs derived from trend extrapolation of import clearance timelines and hospital tender award patterns, with insulin pump leasing penetration and continuous glucose monitor calibration accuracy serving as industry-specific forecast inputs.
Sensitivities concentrate around central bank currency access protocol revisions and national pharmaceutical regulator cybersecurity review timeline extensions for wireless-enabled systems. Forecasts reflect documented assumptions regarding Ministry of Health procurement centralization momentum and provincial laboratory network expansion. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Vietnam Diabetes Care Devices Market
Diabetes Care
Germany Digital Diabetes Management Market
Diabetes Care
Asia Pacific Blood Glucose Test Strip Market
Diabetes Care
Diabetes Monitors Market
Diabetes Care
Global Diabetes Pen Market
Diabetes Care
China Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Insulin Pen Needles Market
Diabetes Care
Latin America Oral Anti-Diabetic Drug Market
Diabetes Care
South Africa Blood Glucose Monitoring Market
Diabetes Care
Global Glucose Monitoring Devices Market
Diabetes Care
Diabetic Pen Cap Market
Diabetes Care
Glycated Albumin Market
Diabetes Care
Sensor Based Glucose Measuring Systems Market
Diabetes Care
Canada Diabetes Care Drugs and Devices Market
Diabetes Care
Digital Diabetes Market
Diabetes Care
New Zealand Oral Anti-Diabetic Drug Market