
 Blood Glucose Monitoring Devices Market | 2026-2036
Blood Glucose Monitoring Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Blood Glucose Monitoring Devices Market Intelligence
The direct-to-consumer channel for blood glucose monitors is fragmenting as new subscription-based models and digital pharmacy partnerships emerge. Dexcom Inc. leverages its strong brand in the continuous glucose monitoring (CGM) space to secure payer contracts. Abbott Laboratories competes through its Flash Glucose Monitoring technology, offering a lower-cost alternative to traditional CGM. Medtronic plc integrates its monitoring devices with its insulin pump systems, creating a closed-loop ecosystem for diabetes management.
Blood glucose monitoring devices are medical instruments that measure glucose concentration in blood, typically via electrochemical sensors reacting with glucose oxidase. Their primary purpose is enabling individuals with diabetes to manage their condition. Continuous Glucose Monitors (CGMs) are displacing traditional self-monitoring devices due to real-time data capabilities. The Home Users segment dominates purchasing volume, driven by the shift toward patient-centric care models.
Regulatory bodies such as the US FDA, Europe's EMA, and China's NMPA impose stringent requirements for device accuracy and data security. These regulations directly influence product design, clinical trial protocols, and market access pathways for manufacturers. For instance, CE marking in Europe is a prerequisite for commercialization. Future device approval will increasingly depend on demonstrating interoperability with digital health platforms and proving cybersecurity resilience.
Market Dynamics
The market's central dynamic is the transition from reactive glucose measurement to proactive, data-driven diabetes management. This shift is enabled by the integration of continuous monitoring sensors with wireless connectivity and digital health ecosystems, fundamentally altering patient care models.
Growth Catalysts
- Favorable Reimbursement Policies:Expanded coverage for Continuous Glucose Monitors (CGMs) by public and private payers in developed markets, such as in Germany and the United States, significantly lowers the financial barrier for patient adoption and encourages switching from traditional meters.
- Telemedicine Integration:The proliferation of remote care platforms allows healthcare providers to monitor patient glucose levels in real-time. This capability drives device demand within the Home Users segment, which prioritizes convenience and continuous clinical oversight.
- Advancements in Sensor Technology:Innovations leading to smaller, more accurate, and longer-lasting electrochemical sensors reduce the burden of device management for patients. This enhances user experience and adherence, particularly for next-generation CGM and Flash Glucose Monitoring systems.
Market Restraints
- High Device and Consumable Costs:The upfront cost of CGM systems and the recurring expense of disposable sensors remain a significant barrier to adoption, especially in emerging economies without widespread reimbursement frameworks for advanced diabetes technology.
- Stringent Regulatory Hurdles:Manufacturers face rigorous and lengthy approval processes from bodies like the US FDA and Europe's EMA. Requirements for clinical accuracy, data security, and interoperability can delay product launches and increase development costs.
- Technical Limitations and Calibration Needs:Despite improvements, some glucose monitoring devices still require periodic calibration with finger-prick tests to ensure accuracy. This limitation can diminish the perceived convenience of continuous monitoring for some users.
Strategic Opportunities
- Expansion in Underpenetrated Markets:A substantial opportunity exists in large, developing countries like India and Brazil, where rising diabetes prevalence and a growing middle class create latent demand for more affordable and accessible monitoring solutions.
- Closed-Loop System Development:Integrating CGM devices with automated insulin delivery pumps creates "artificial pancreas" systems. This technology convergence represents a significant value-add, moving towards fully automated diabetes management and attracting a premium patient segment.
- Subscription-Based Business Models:New direct-to-consumer channels, including subscription services for sensors and digital coaching, allow manufacturers to build recurring revenue streams and foster direct relationships with end-users, bypassing traditional pharmacy distribution.
Industry Challenges
- Cybersecurity of Connected Devices:Ensuring the security of patient data transmitted wirelessly from CGMs to smartphones and cloud platforms is a critical operational challenge. A single data breach could erode patient trust and attract severe regulatory penalties under rules like HIPAA.
- Data Interoperability Standards:A lack of universal standards for data sharing between different monitoring devices, insulin pumps, and electronic health record (EHR) systems creates fragmentation. This complicates the creation of a seamless, integrated care experience for patients and clinicians.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blood Glucose Monitoring Devices Market |
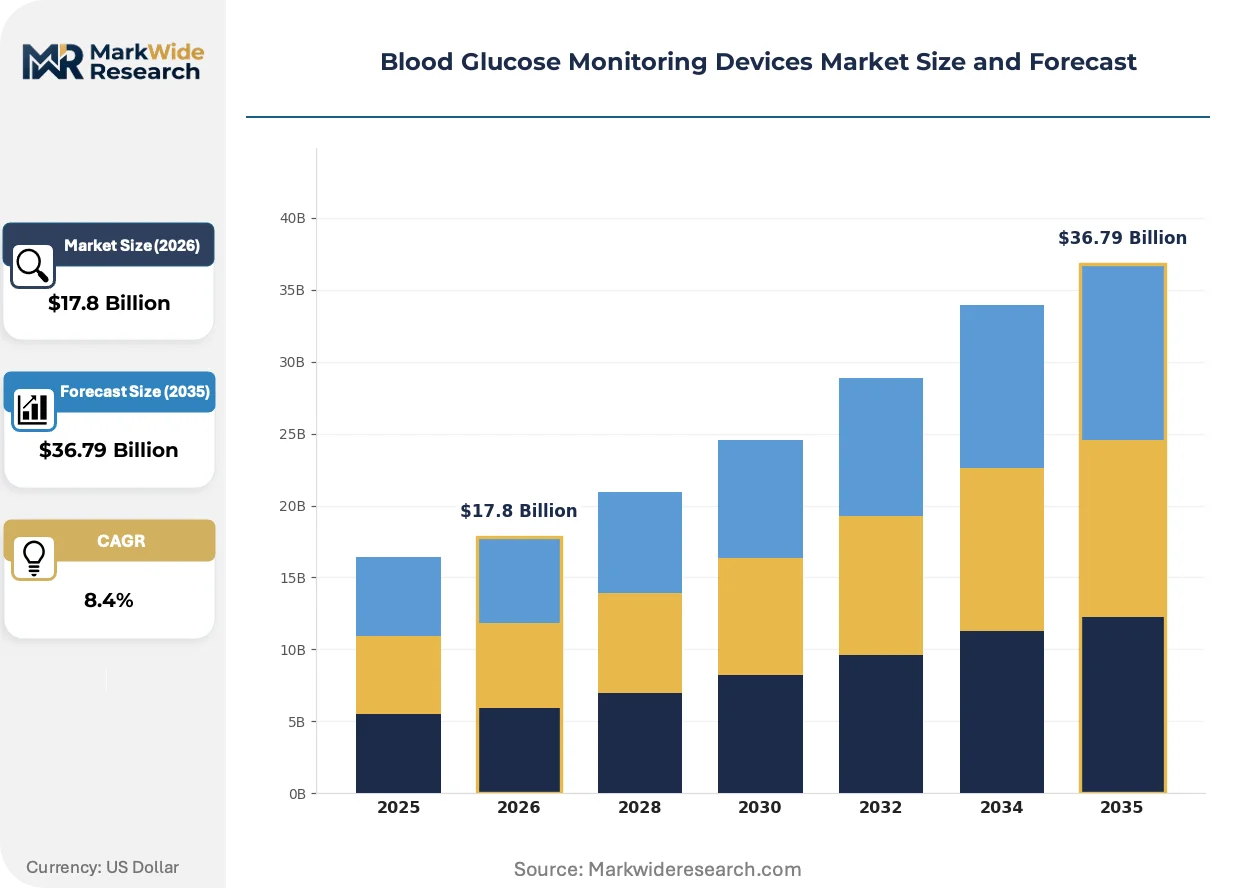
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $36.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Monitoring Devices, Continuous Glucose Monitors, Flash Glucose Monitoring, Non-Invasive Meters, Laboratory Analyzers, Mobile Monitoring Systems Technology: Electrochemical Sensors, Optical Sensors, Enzymatic Detection, Microfluidics, Photometric Methods, Wireless Connectivity Application: Diabetes Management, Prediabetes Screening, Gestational Diabetes, Hypoglycemia Monitoring, Research & Development, Fitness Tracking End User: Home Users, Diagnostic Labs, Pharmacies, Diabetes Clinics, Telemedicine Providers, Health Insurance Providers |
| Companies Covered | Abbott Laboratories, Dexcom Inc., Medtronic plc, F. Hoffmann-La Roche Ltd, Ascensia Diabetes Care Holdings AG, LifeScan IP Holdings LLC, Senseonics Holdings Inc., Sinocare, B. Braun SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blood Glucose Monitoring Devices Market Strategic Shifts & Innovations
The evolution of blood glucose monitors is defined by increasing device autonomy and data intelligence. This empowers patients and care teams with predictive insights, shifting the focus from episodic glucose checks to continuous, actionable health management within a connected digital framework.
Minimally invasive sensor technology is a primary focus of product evolution, utilizing micro-needles or advanced electrochemical methods to reduce patient discomfort. Adoption is highest among pediatric patients and individuals with active lifestyles who seek less intrusive monitoring solutions. The device market is migrating from periodic, painful finger-prick tests to a paradigm of passive, continuous data collection that significantly improves quality of life.
Regulatory frameworks are tightening their focus on software and connectivity. The European Union's Medical Device Regulation (MDR) imposes stricter requirements for clinical evidence and post-market surveillance, particularly for software as a medical device (SaMD). This directly impacts CGM manufacturers selling in Europe, compelling them to invest heavily in updated quality management systems and cybersecurity protocols to maintain CE marking.
A distinct behavioral shift involves patients treating their glucose data as a shareable personal health asset. This disrupts the conventional model where data was siloed on a device, with users now actively connecting their CGMs to third-party wellness apps and sharing real-time streams with caregivers. This trend is most pronounced in the United States and key European countries, driven by high smartphone use and a growing ecosystem of compatible health applications.
Blood Glucose Monitoring Devices Market Segmentation
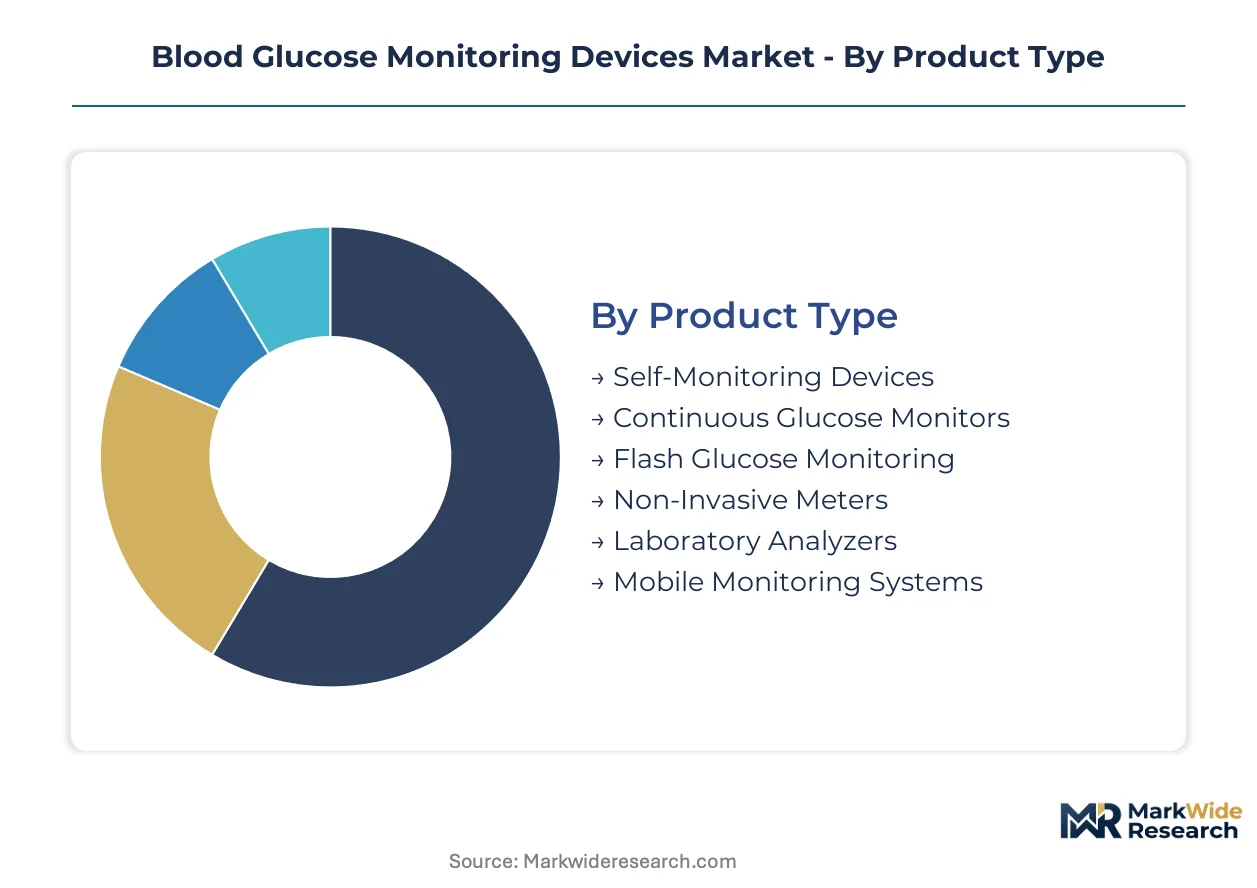
The Blood Glucose Monitoring Devices Market segmentation provides a granular view into the diverse product offerings, underlying technologies, primary applications, and key end-user groups. This detailed breakdown illuminates distinct growth drivers and competitive dynamics shaping the market landscape for both established and emerging solutions.
Product Type:
The product type segmentation reveals a market transitioning from mature, traditional devices to innovative, real-time monitoring solutions.
- Continuous Glucose Monitors:These devices provide real-time glucose readings via a sensor inserted under the skin, often eliminating routine finger-pricks. Demand concentrates in developed healthcare systems like the United States due to favorable reimbursement policies.
- Flash Glucose Monitoring:Flash Glucose Monitoring offers on-demand glucose readings by scanning a sensor worn on the arm, a more affordable alternative to full CGMs. Adoption is high in European markets, like Germany, bridging traditional meters and continuous monitoring.
- Self-Monitoring Devices:Traditional finger-prick blood glucose meters provide episodic data points for diabetes control.
- Non-Invasive Meters:Emerging technologies aim to measure glucose without skin penetration, currently in early development.
- Laboratory Analyzers:High-precision instruments used in clinical settings for definitive glucose measurements and diagnostic purposes.
- Mobile Monitoring Systems:Devices integrate with smartphone apps for data tracking and sharing, enhancing patient engagement.
Self-Monitoring Devices handle the majority of throughput; Continuous Glucose Monitors are the fastest mover on share.
Technology:
Technology segmentation highlights varying cost structures and performance capabilities in glucose measurement.
- Electrochemical Sensors:These utilize glucose oxidase enzymes reacting with glucose, generating an electrical signal proportional to concentration. This core technology underpins most continuous and flash monitors, driving accuracy.
- Wireless Connectivity:Integration of Bluetooth, NFC, or cellular modules enables real-time data transmission from devices to smartphones or cloud platforms. This feature is critical for telemedicine platforms and remote patient monitoring in the United States.
- Enzymatic Detection:A fundamental biochemical method used in many glucose tests, relying on enzyme-catalyzed reactions.
- Optical Sensors:Technologies exploring light-based glucose measurement, aiming for non-invasive solutions.
- Microfluidics:Miniaturized systems for handling small fluid volumes, enabling smaller, more efficient sensor designs.
- Photometric Methods:Techniques measuring glucose concentration based on light absorption changes, often used in laboratory settings.
Electrochemical Sensors underpin the highest volume of measurements, while Wireless Connectivity drives innovation in data accessibility.
Application:
The application breakdown reflects diverse needs across patient populations and clinical objectives.
- Diabetes Management:This primary application involves routine glucose monitoring for individuals with Type 1 or Type 2 diabetes to maintain glycemic control. Demand is universally high, particularly in countries with large diabetic populations like India.
- Hypoglycemia Monitoring:This application focuses on detecting dangerously low blood sugar levels, critical for patient safety during sleep or intense activity. CGMs are essential here, offering alerts and trend data for proactive intervention.
- Prediabetes Screening:Identifying individuals at risk of developing Type 2 diabetes, often using less frequent monitoring.
- Gestational Diabetes:Monitoring glucose levels in pregnant women to manage pregnancy complications.
- Research & Development:Utilization of advanced glucose monitoring devices in clinical trials and new product development.
- Fitness Tracking:Emerging use of glucose data for performance optimization and metabolic health insights in wellness programs.
Diabetes Management accounts for the largest revenue concentration, with Hypoglycemia Monitoring showing significant growth in clinical importance.
End User:
End user segmentation reveals where purchasing volume concentrates and how care delivery models are evolving.
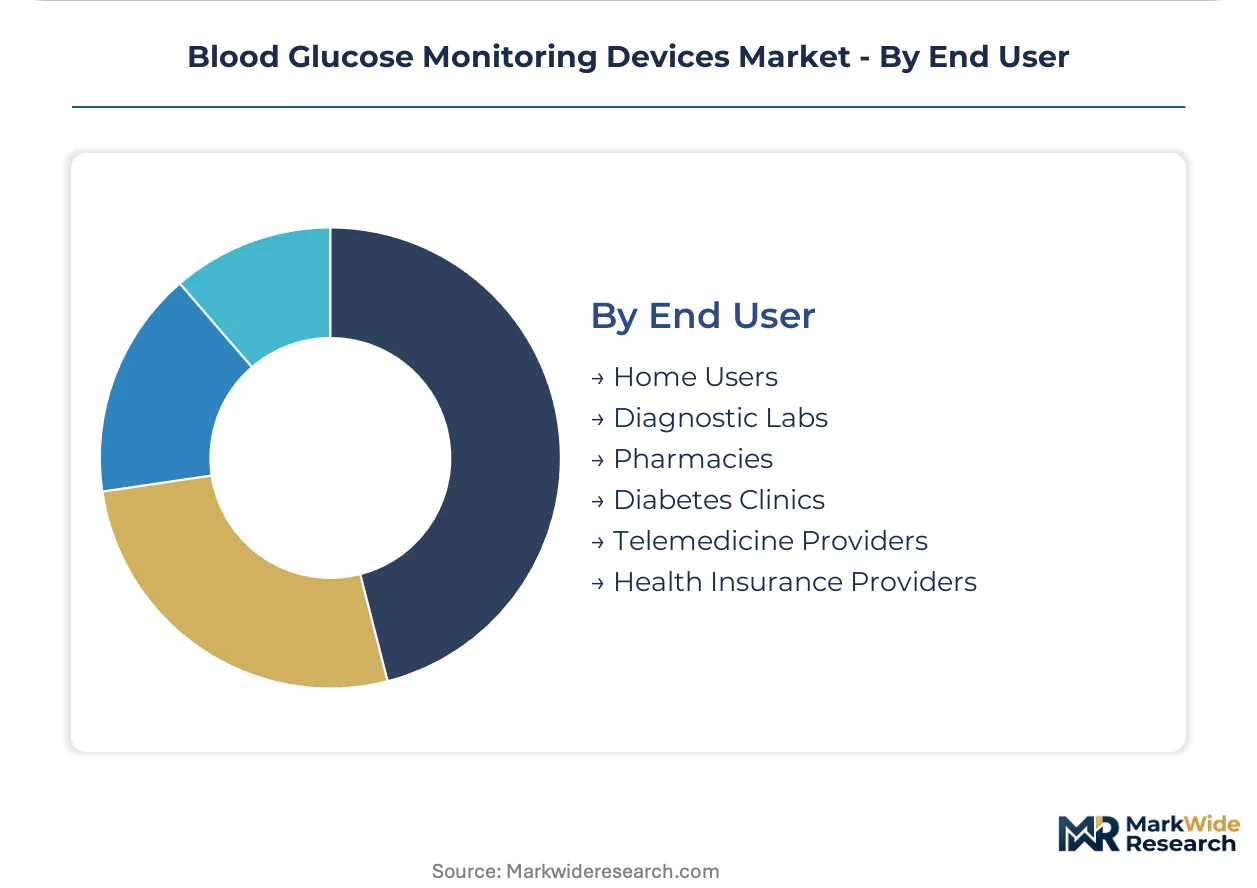
- Home Users:Individuals with diabetes who self-monitor their glucose levels using personal devices, often integrating with mobile applications. This segment represents the largest purchasing volume, driven by convenience and patient-centric care in the United States.
- Telemedicine Providers:Healthcare organizations leveraging remote platforms to monitor patient glucose data, offering virtual consultations and care adjustments. This segment's demand surged with remote care adoption in developed economies.
- Diagnostic Labs:Centralized facilities performing high-volume, precise glucose measurements for diagnostic purposes.
- Pharmacies:Retail outlets distributing blood glucose meters and consumables, offering accessibility for patients.
- Diabetes Clinics:Specialized medical centers providing comprehensive diabetes care, education, and device recommendations.
- Health Insurance Providers:Entities influencing device adoption through reimbursement policies and coverage decisions.
Home Users demonstrate the highest device adoption rate, while Telemedicine Providers are accelerating new service models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Robust digital health infrastructure underwrites the significant role of several key geographies in the blood glucose monitoring devices market. These regions exhibit varying stages of market maturity, driven by diverse healthcare systems and regulatory frameworks. Developed markets lead in advanced technology adoption.
United States
The United States leads in continuous glucose monitor adoption, fueled by telemedicine integration and robust patient-centric care models. Expanded CGM coverage by public and private payers significantly lowers financial barriers. Biopharmaceutical hubs like Greater Boston drive innovation in sensor technology and digital health platform integration.
Germany
Germany demonstrates high adoption of Flash Glucose Monitoring systems, supported by comprehensive reimbursement policies within its advanced healthcare system. Manufacturers require CE marking under the Medical Device Regulation (MDR) for commercialization. Bavaria's medical technology cluster develops advanced electrochemical sensors and integrated diabetes management solutions.
China
China represents a substantial growth opportunity, driven by its large diabetic population and increasing healthcare expenditure. The NMPA imposes stringent requirements for device accuracy and market access. The Yangtze River Delta region is a hub for domestic medical device manufacturing and digital health platform development.
India
India offers significant latent demand due to its high diabetes prevalence and a growing middle class seeking accessible monitoring solutions. The CDSCO regulates medical device approvals, while the PLI scheme encourages domestic manufacturing. Bengaluru's tech and healthcare startup ecosystem focuses on developing cost-effective, mobile-integrated glucose monitoring devices.
Brazil
Brazil's expanding middle class and increasing diabetes rates create a growing need for improved glucose monitoring solutions. ANVISA oversees medical device registration and post-market surveillance. São Paulo's robust healthcare sector facilitates the distribution and adoption of both traditional and advanced monitoring technologies.
Blood Glucose Monitoring Devices Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, supplying critical sensor technologies and connectivity modules. The blood glucose monitoring devices market exhibits a tiered structure, with established medical device giants alongside innovative digital health startups. Key strategic archetypes include integrated solution providers, specialized sensor manufacturers, and digital ecosystem developers focusing on patient engagement. Companies actively pursue strategic partnerships and portfolio diversification to enhance their market reach and technological offerings across diverse patient needs.
Within the integrated solution provider archetype, Abbott Laboratories occupies a strong position, known for its Flash Glucose Monitoring technology, offering a lower-cost alternative. Dexcom Inc. exemplifies leadership in the continuous glucose monitoring space, leveraging its brand strength and extensive payer contracts. Medtronic plc, a global medical technology company, represents a comprehensive approach, integrating its monitoring devices with insulin pump systems to create closed-loop diabetes management ecosystems, addressing a premium patient segment.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Dexcom Inc. |
| Medtronic plc |
| F. Hoffmann-La Roche Ltd |
| Ascensia Diabetes Care Holdings AG |
| LifeScan IP Holdings LLC |
| Senseonics Holdings Inc. |
| Sinocare |
| B. Braun SE |
| Others |
Cost & Logistics Intelligence
The Trans-Pacific shipping corridor's fluctuating freight costs directly influence the concentrated supply of blood glucose monitoring components, impacting downstream device price differentiation across global markets. This dynamic shapes market access and affordability for patients.
Pricing Analysis
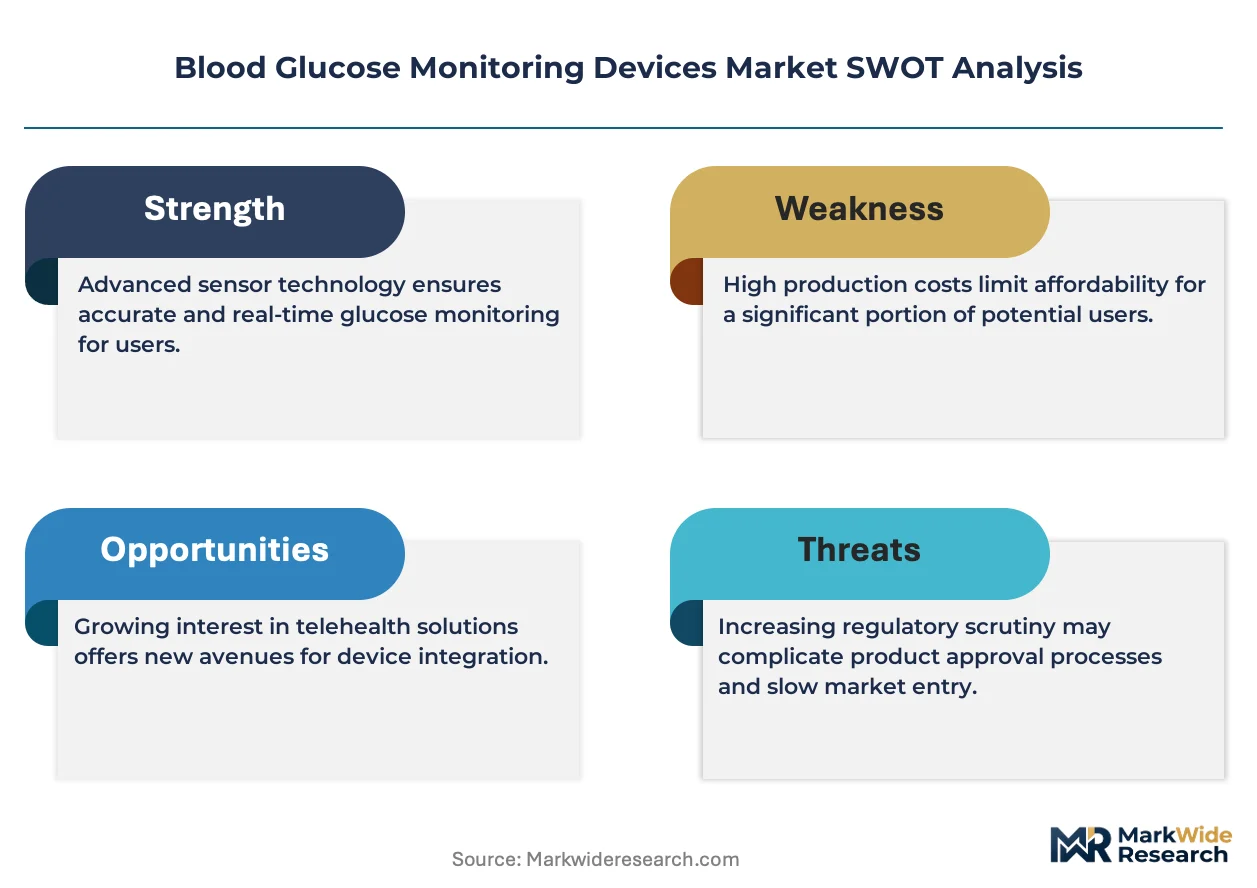
Tiered pricing structures differentiate blood glucose monitoring devices based on technology and feature sets. Brand premium from established players like Dexcom Inc. and Abbott Laboratories allows for higher price points, while regulatory approval status, such as CE marking or US FDA clearance, commands trust and market access. Pricing softness reflects increasing competition from Flash Glucose Monitoring systems that offer a more affordable entry point. Home users without comprehensive reimbursement demonstrate the highest price sensitivity, while telemedicine providers prioritize integrated solutions.
Supply Chain Analysis
Upstream feedstock for electrochemical sensors, particularly glucose oxidase enzymes, primarily sources from specialized chemical manufacturers. Supply concentration for core device components, including microcontrollers and wireless modules, largely centers in China and specific manufacturing hubs in the United States. Single-source vulnerability for specialized sensor films poses a structural risk. Distribution runs through a hybrid model, combining direct-to-consumer channels, traditional pharmacies, and specialized medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The blood glucose monitoring market requires a strong substitution defense as non-invasive monitoring technologies mature. Incumbents must proactively navigate this evolving landscape to maintain market share against disruptive innovations.
For Market Incumbents: Pre-empt emerging non-invasive device entrants by accelerating R&D in miniaturized, highly accurate sensor technologies. Deepen integration with digital health platforms and telemedicine providers to create sticky, comprehensive diabetes management ecosystems. Secure long-term payer contracts to reinforce reimbursement pathways. This strategic focus mitigates the threat of disruptive substitutes and strengthens competitive positioning.
For New Entrants and Emerging Players: Underpenetrated markets in large developing countries like India and Brazil represent the most penetrable entry points for accessible monitoring solutions. Focus on cost-effective Flash Glucose Monitoring alternatives or mobile-integrated devices tailored for these regions. A direct-to-consumer subscription model, coupled with localized digital coaching, offers a strong go-to-market angle. Emphasize affordability and ease of use to capture latent demand.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical device conglomerates seeking to divest non-core diabetes assets, particularly older self-monitoring device portfolios. Long-term viability across a 5-10 year window favors companies with strong intellectual property in next-generation sensors or AI-driven data analytics. Acquisition targets should possess robust regulatory approvals and established telemedicine integration capabilities. A significant increase in reimbursement for advanced CGM technology acts as a key signal to watch for inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Non-Invasive Sensor R&D | This advances technology beyond traditional electrochemical sensors, improving patient comfort and adherence. |
| Expand Telemedicine Platform Partnerships | This integrates devices into remote care ecosystems, enhancing clinical oversight for Home Users. |
| Develop Subscription-Based Service Models | This builds recurring revenue streams and fosters direct relationships with end-users. |
| Secure Payer Reimbursement Contracts | This lowers financial barriers for patient adoption in markets like the United States. |
| Target Emerging Market Expansion | This addresses significant latent demand in countries such as India and Brazil. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and extensive secondary validation. Engagements included diabetes specialists, R&D directors from device manufacturers, procurement managers at telemedicine providers, and regulatory affairs leads. Secondary sources comprised US FDA filings, EMA submissions, NMPA guidelines, and specialized medical device industry reports. This approach facilitated robust bottom-up and top-down triangulation of market data.
Forecast inputs considered historical market performance, technological advancements, regulatory changes, and epidemiological trends across the analysis window. The analytical framework modeled segmentation dimensions including product type, technology, application, end user, and patient demographics. Compound Annual Growth Rates (CAGRs) derived from robust regression models captured projected market expansion. Key inputs included global diabetes prevalence rates and evolving healthcare expenditure trends.
Practitioners should monitor regulatory policy shifts and significant technological breakthroughs for early signals impacting market trajectory. Forecasts reflect assumptions regarding healthcare infrastructure development and patient adoption rates. Cross-checking against World Health Organization (WHO) diabetes statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Network Point-Of-Care Glucose Testing Market
Diabetes Care
Self-Monitoring Blood Glucose (SMBG) Market
Diabetes Care
South Korea Oral Anti-Diabetic Drug Market
Diabetes Care
Vietnam Insulin Infusion Pump Market
Diabetes Care
Insulin Pen Needles Market
Diabetes Care
South Africa Blood Glucose Monitoring Market
Diabetes Care
New Zealand Insulin Drugs and Devices Market
Diabetes Care
Oman Insulin Drugs and Delivery Devices Market
Diabetes Care
Middle East and Africa Diabetes Market
Diabetes Care
Latin America Insulin Infusion Pump Market
Diabetes Care
Russia Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Japan Insulin Drugs and Delivery Devices Market
Diabetes Care
France Continuous Glucose Monitoring Market
Diabetes Care
Australia Insulin Infusion Pump Market
Diabetes Care
France Insulin Infusion Pump Market
Diabetes Care
Diabetic Footwear Market