
 North America Diabetes Care Devices Market | 2026-2036
North America Diabetes Care Devices Market Size, Share, and Industry Trends Forecast 2026-2036
North America Diabetes Care Devices Market Outlook
Buyer concentration among specialty diabetes centers and integrated health networks is recalibrating procurement patterns across the region. Abbott Laboratories leverages its vertically integrated sensor manufacturing to secure long-term supply agreements with major hospital systems. Dexcom competes through aggressive direct-to-consumer channel investments that bypass traditional durable medical equipment distributors. Medtronic anchors its position via deep clinical trial partnerships with academic medical centers that generate real-world evidence for payers.
North America diabetes care devices encompass electrochemical biosensors, infusion mechanisms, and wireless telemetry hardware engineered to measure interstitial glucose or deliver insulin with subcutaneous precision. These systems integrate enzymatic glucose oxidase reactions with algorithmic predictive dosing to reduce glycemic variability and hypoglycemic events in ambulatory patients. Continuous glucose monitors capture expanding margin pools as sensor accuracy tightens toward laboratory reference standards and replacement cycles shorten. Blood glucose meters occupy a mature revenue tier where price compression forces manufacturers toward strip-razor economics and private-label contracts. Insulin pumps sustain premium positioning through closed-loop algorithm differentiation and interoperability with third-party sensors.
FDA premarket review under the de novo pathway shapes device design requirements for artificial pancreas systems and interoperable components. CMS national coverage determinations directly dictate patient access thresholds and reimbursement rates across Medicare and Medicaid programs. Health Canada and the FDA coordinate on software-as-medical-device frameworks that accelerate cloud-based platform approvals while tightening cybersecurity validation. Stakeholders must monitor evolving interoperability standards and payer evidence requirements to sustain competitive positioning as regulatory convergence between Washington and Ottawa intensifies.
Market Dynamics
Interoperability mandates from the FDA are compressing development timelines and forcing manufacturers to redesign sensor-pump communication protocols for seamless data exchange across competing platforms.
Growth Catalysts
- CMS National Coverage Determinations:Medicare reimbursement expansion for continuous glucose monitors removes cost barriers for ambulatory seniors, expanding addressable patient pools across the United States.
- Home care migration:Post-acute patients increasingly demand self-management flexibility, driving demand for wearable sensors with smartphone connectivity and remote monitoring dashboards.
- Closed-loop algorithm maturation:Predictive insulin dosing systems reduce hypoglycemic events, generating real-world evidence that satisfies payer prior-authorization requirements.
Market Restraints
- Single-source sensor membrane supply:Electrochemical glucose oxidase membranes concentrate among three specialty chemical suppliers, creating input vulnerability for disposable CGM manufacturing.
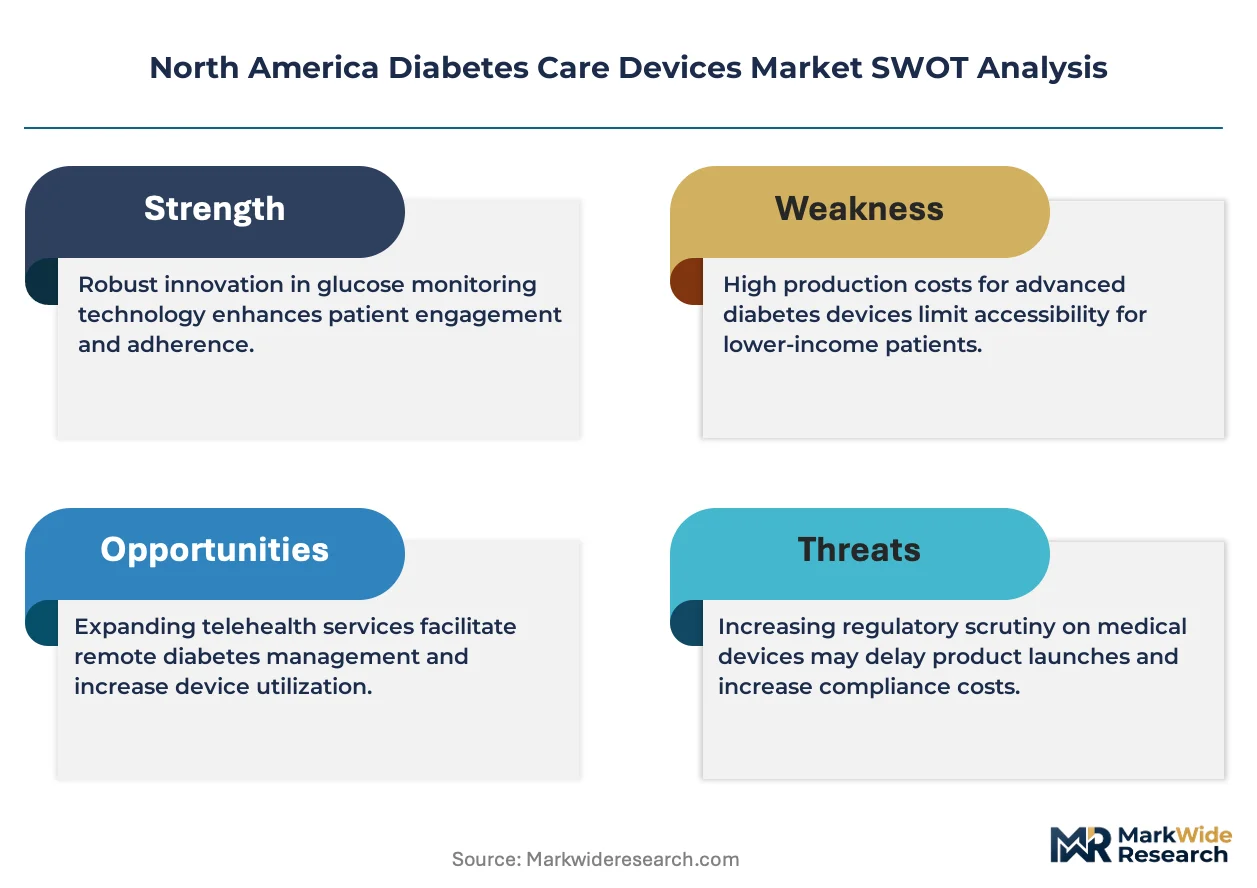
- FDA software-as-medical-device validation:Cloud-based platform updates require cybersecurity documentation that extends clearance timelines by eight to fourteen months.
- Strip-razor economics compression:Blood glucose meter margins collapse as private-label contracts capture pharmacy chain procurement, forcing branded manufacturers toward consumable volume dependence.
Strategic Opportunities
- Canada's lagging CGM penetration:Health Canada approval pathways for interoperable devices create first-mover advantage for manufacturers with existing FDA clearances.
- Type 2 non-intensive user segment:Intermittent scanning protocols and longer-wear sensors open ambulatory populations previously excluded from intensive insulin therapy.
- Direct-to-consumer channel bypass:Subscription models that circumvent durable medical equipment distributors capture margin and accelerate patient onboarding.
Industry Challenges
- Algorithm validation talent scarcity:Machine learning engineers with clinical trial design experience command premium compensation, constraining closed-loop development velocity.
- Legacy EHR integration friction:Hospital systems running decade-old Epic or Cerner deployments resist API upgrades needed for automated glucose data ingestion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Diabetes Care Devices Market |
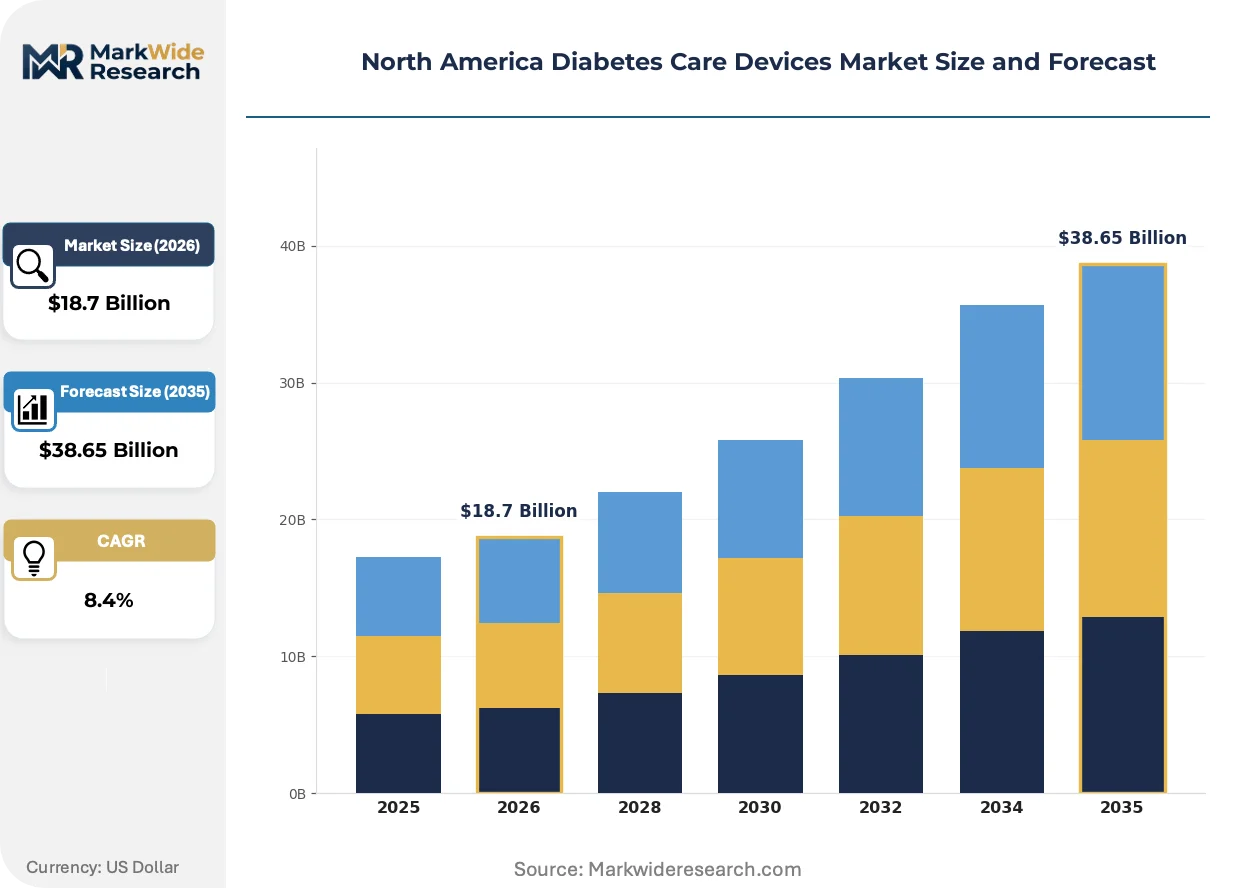
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin Pumps, Continuous Glucose Monitors, Blood Glucose Meters, Pen Needles Application: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Diabetes Management End User: Hospitals, Home Care, Clinics, Specialty Diabetes Centers Technology: Wearable Devices, Mobile Applications, Cloud-based Systems, Telehealth Solutions |
| Companies Covered | Abbott Laboratories, F. Hoffmann-La Roche, Dexcom, Medtronic, LifeScan, Ascensia Diabetes Care, Insulet Corporation, Becton Dickinson and Company, Tandem Diabetes Care, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Diabetes Care Devices Market Strategic Shifts
Algorithmic predictive dosing and wireless telemetry hardware are converging to reduce clinical decision burden, while regulatory coordination between Washington and Ottawa accelerates cross-border platform approvals.
Non-invasive optical glucose sensing is absorbing substantial R&D investment from sensor manufacturers seeking to eliminate enzymatic consumables. Academic medical centers in California and Massachusetts are piloting near-infrared spectroscopy devices in controlled settings. This technology is absorbing regulatory attention as the FDA develops validation frameworks for optical reference accuracy against laboratory standards.
The FDA de novo pathway for interoperable artificial pancreas components is compressing design requirements for third-party sensor-pump pairings. Manufacturers must now submit cybersecurity documentation and interoperability testing protocols alongside traditional safety data. Insulin pump OEMs in Minnesota and Massachusetts are restructuring quality systems to accommodate modular premarket submissions.
Specialty diabetes centers and integrated health networks are consolidating procurement authority, displacing independent endocrinology practices from volume contracting. Hospital systems in Texas and Florida now mandate standardized CGM brands across employed physician networks. This concentration is most visible in Medicare Advantage plan regions where vertical integration between payers and delivery systems tightens device formularies.
North America Diabetes Care Devices Market Segmentation
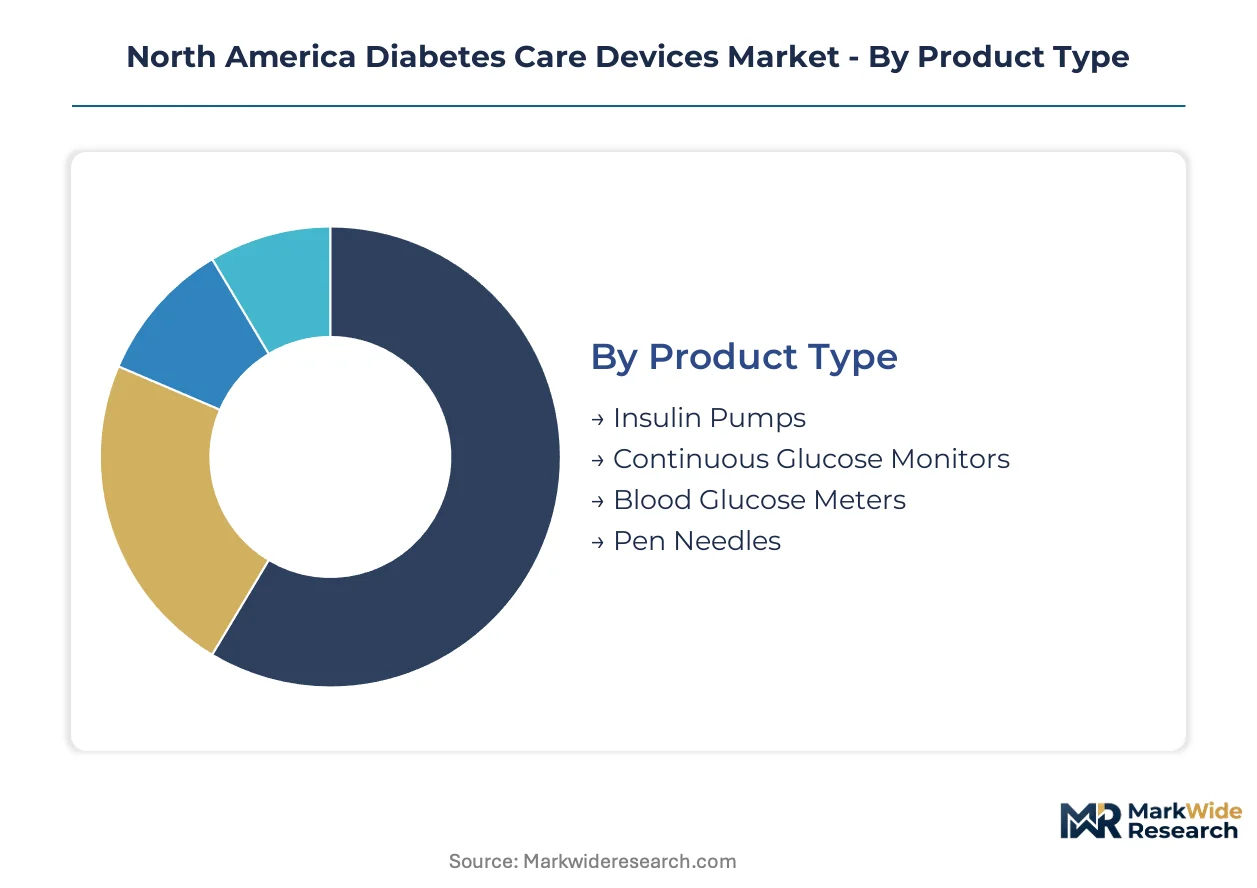
Segmentation in the North America diabetes care devices market reveals how procurement authority concentrates among integrated health networks and how reimbursement pathways favor specific device categories over others. Manufacturers must align product portfolios with Medicare coverage determinations and hospital system standardization mandates to capture volume.
Product Type:
Supply concentration for electrochemical sensor membranes and infusion mechanisms varies sharply across device categories, creating divergent margin profiles and sourcing vulnerabilities.
- Insulin Pumps:Motor-driven subcutaneous infusion systems with closed-loop algorithm integration. Demand concentrates among Medicare Advantage enrollees in Texas and Florida where vertical payer-provider integration tightens formularies. Premium positioning depends on interoperability with third-party CGM sensors.
- Continuous Glucose Monitors:Wearable electrochemical biosensors capturing interstitial glucose via enzymatic oxidase reactions. CMS national coverage determinations for ambulatory seniors in the United States are removing cost barriers and expanding addressable patient pools fastest among all device types.
- Blood Glucose Meters:Handheld enzymatic strip readers facing strip-razor economics compression.
- Pen Needles:Disposable subcutaneous injection accessories governed by pharmacy chain procurement contracts.
Continuous glucose monitors absorb the bulk of installed capacity; insulin pumps are expanding most quickly as closed-loop algorithms mature.
Application:
Cost tier stratification across diabetes severity levels determines device sophistication requirements and reimbursement intensity.
- Type 1 Diabetes:Absolute insulin deficiency requiring intensive glucose monitoring and automated insulin delivery. Demand concentrates at specialty diabetes centers in California and Massachusetts where academic medical centers generate payer-recognized real-world evidence for closed-loop systems.
- Type 2 Diabetes:Progressive insulin resistance spanning non-intensive to intensive therapy stages. Intermittent scanning protocols and longer-wear sensors are opening ambulatory populations in the United States previously excluded from device reimbursement.
- Gestational Diabetes:Temporary hyperglycemia during pregnancy requiring short-duration monitoring solutions.
- Diabetes Management:Comprehensive care protocols integrating multiple device categories across care settings.
Type 1 diabetes commands the highest device revenue per patient; Type 2 diabetes is climbing the fastest as sensor technology broadens eligibility criteria.
End User:
Customer type migration from institutional settings toward ambulatory self-management is redistributing procurement authority and margin capture.
- Home Care:Patient-directed glucose monitoring and insulin delivery outside clinical facilities. Demand concentrates among Medicare beneficiaries prioritizing self-management flexibility with smartphone-connected wearables and remote monitoring dashboards.
- Hospitals:Acute and post-acute inpatient settings requiring integrated EHR connectivity. Legacy Epic and Cerner deployments in Texas and Florida systems resist API upgrades needed for automated glucose data ingestion.
- Clinics:Outpatient facilities with limited device standardization authority.
- Specialty Diabetes Centers:Concentrated endocrinology practices consolidating procurement leverage.
Home care captures margin fastest through direct-to-consumer subscription models; hospitals retain the largest installed base of legacy systems.
Technology:
Margin structure varies by platform architecture, with cloud infrastructure and algorithmic capabilities commanding premium positioning over commodity hardware.
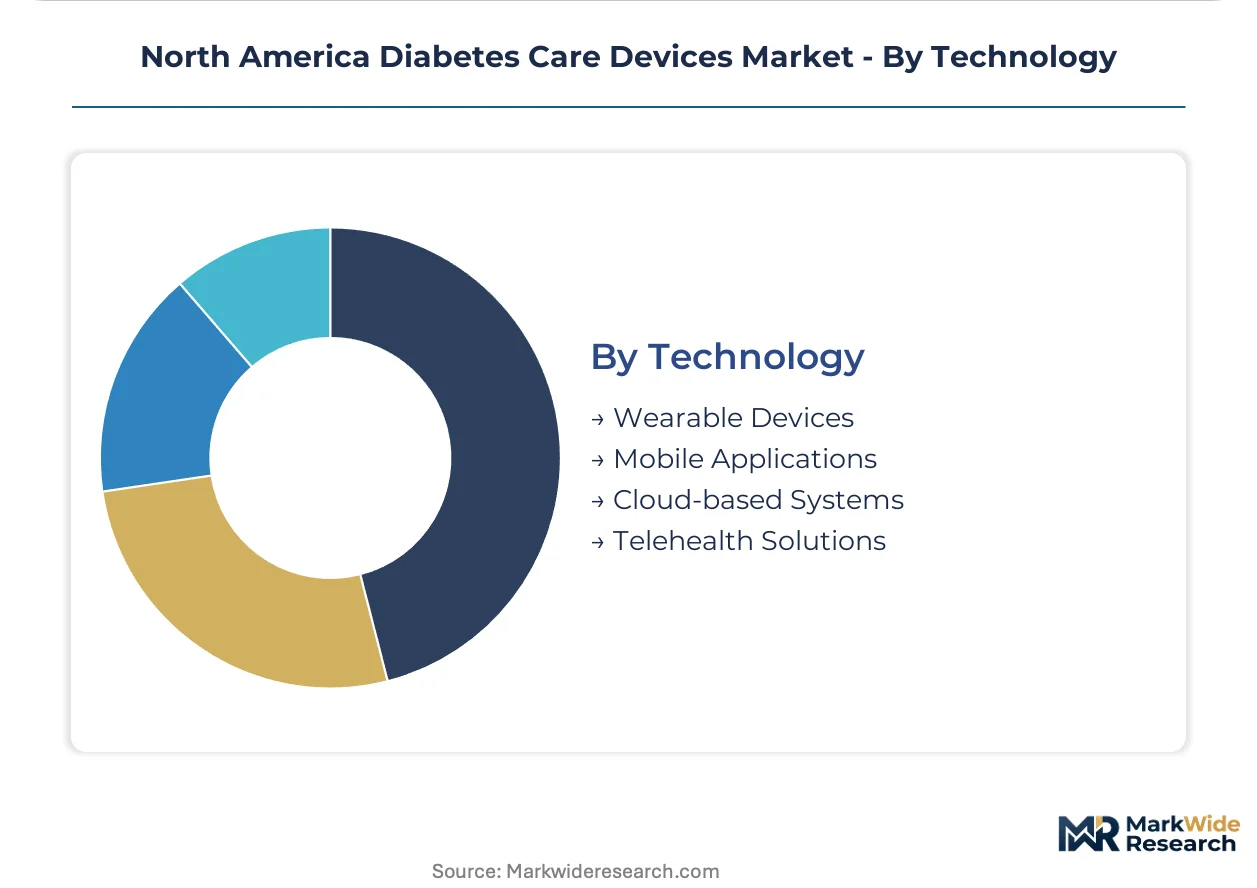
- Wearable Devices:Body-worn sensors and pumps with wireless telemetry hardware. FDA de novo pathway clearances for interoperable components in the United States are compressing design requirements and accelerating modular premarket submissions.
- Cloud-based Systems:Remote data aggregation platforms with predictive analytics. Health Canada and FDA coordination on software-as-medical-device frameworks accelerates cross-border approvals while tightening cybersecurity validation timelines.
- Mobile Applications:Smartphone interfaces for device control and data visualization.
- Telehealth Solutions:Remote clinical consultation platforms integrated with device data streams.
Wearable devices dominate current revenue; cloud-based systems are gaining share fastest as algorithmic predictive dosing reduces clinical decision burden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for diabetes care devices concentrates in the United States, where Medicare reimbursement expansion and vertical payer-provider integration drive procurement volume. Canada and Mexico present divergent regulatory timelines and reimbursement frameworks that shape market entry sequencing for device manufacturers.
United States
CMS national coverage determinations for continuous glucose monitors remove cost barriers for ambulatory seniors, expanding addressable patient pools fastest among North American markets. FDA de novo pathway clearances for interoperable artificial pancreas components compress design requirements for third-party sensor-pump pairings. The Minneapolis-St. Paul corridor anchors insulin pump OEM activity, while California's academic medical centers generate payer-recognized real-world evidence for closed-loop systems.
Canada
Health Canada approval pathways for interoperable devices create first-mover advantage for manufacturers with existing FDA clearances, particularly in provinces with lagging CGM penetration. Coordination between Health Canada and the FDA on software-as-medical-device frameworks accelerates cross-border platform approvals while tightening cybersecurity validation timelines. Ontario's hospital systems concentrate procurement authority for provincial formularies, displacing independent endocrinology practices from volume contracting.
Mexico
Private health insurance expansion in major metropolitan areas generates demand for premium insulin delivery systems among affluent patient segments. The national pharmaceutical regulator maintains distinct validation requirements for glucose monitoring devices that extend clearance timelines relative to US benchmarks. Mexico City's specialty diabetes centers consolidate referral networks for advanced device therapies, creating concentrated demand nodes for multinational manufacturers.
Southeast United States
Medicare Advantage enrollee concentration in Texas and Florida tightens device formularies through vertical payer-provider integration. Hospital systems in this sub-region mandate standardized CGM brands across employed physician networks, reducing procurement fragmentation. Legacy Epic and Cerner deployments in Florida resist API upgrades needed for automated glucose data ingestion, creating EHR integration friction for cloud-based platform vendors.
Greater Boston and California
Academic medical centers in Massachusetts and California anchor clinical trial partnerships that generate real-world evidence satisfying payer prior-authorization requirements for closed-loop algorithms. FDA premarket review offices in these states maintain direct channels to device developers, compressing feedback loops for artificial pancreas submissions. Research institutions in both sub-regions pilot near-infrared spectroscopy devices, absorbing regulatory attention as optical glucose sensing technology matures.
North America Diabetes Care Devices Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue direct-to-consumer subscription models and algorithmic differentiation. The vendor base clusters around three strategic archetypes: vertically integrated sensor manufacturers securing long-term supply agreements, direct-to-consumer channel specialists bypassing durable medical equipment distributors, and academic medical center partners generating payer-recognized real-world evidence. Dominant competitive moves include aggressive direct-to-consumer channel investments and deep clinical trial partnerships with integrated health networks.
Among US-based diversified health technology conglomerates, Abbott Laboratories and Medtronic exemplify vertically integrated archetypes with captive sensor manufacturing capabilities. Dexcom occupies a position within the direct-to-consumer specialist tier, representing the channel-bypass strategy that captures margin and accelerates patient onboarding. These three anchors illustrate how procurement concentration among specialty diabetes centers and integrated health networks recalibrates competitive positioning across the region.
| Leading Market Players |
|---|
| Abbott Laboratories |
| F. Hoffmann-La Roche |
| Dexcom |
| Medtronic |
| LifeScan |
| Ascensia Diabetes Care |
| Insulet Corporation |
| Becton Dickinson and Company |
| Tandem Diabetes Care |
| Others |
Value Chain & Pricing Dynamics
Captive sensor manufacturing by Abbott Laboratories and Medtronic anchors both supply security and premium pricing power across continuous glucose monitor and insulin pump categories. This backward integration into electrochemical membrane production insulates against input volatility while supporting subscription-based revenue models that bypass durable medical equipment distributor markups.
Pricing Analysis
Volume capture concentrates in blood glucose meters where strip-razor economics compress margins toward consumable dependence, while margin pools migrate to continuous glucose monitors with shorter replacement cycles and algorithmic differentiation. Pricing stratifies across closed-loop premium tiers, interoperable standard tiers, and private-label economy tiers for legacy strip-based systems. Cost compression in blood glucose meters intensifies as pharmacy chain procurement consolidates around house brands. Medicare Advantage enrollees in Texas and Florida demonstrate lowest price sensitivity due to integrated payer-provider formularies, while uninsured ambulatory patients in Mexico face highest out-of-pocket burden.
Supply Chain Analysis
Reverse-logistics flows for insulin pump refurbishment and sensor recycling remain underdeveloped, creating stranded asset risk as hardware replacement cycles accelerate. Electrochemical glucose oxidase membranes concentrate among United States, Germany, and Japan specialty chemical suppliers, creating single-source vulnerability for disposable CGM manufacturing. Key inputs include platinum catalysts, medical-grade polymers, and enzymatic reagents. Tariff exposure on Chinese-sourced electronics components threatens wireless telemetry hardware costs. Distribution runs through durable medical equipment distributors for institutional procurement, while direct-to-consumer subscription models capture ambulatory home care volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous glucose monitors are displacing blood glucose meters as the dominant ambulatory monitoring modality, with algorithmic predictive dosing replacing manual insulin calculation across Type 1 and intensive Type 2 populations.
For Market Incumbents: Anchor market position through exclusive long-term supply agreements with integrated health networks in Texas and Florida, where Medicare Advantage concentration tightens formularies. Deepen backward integration into electrochemical membrane production to offset single-source chemical supplier vulnerability. Prioritize FDA de novo pathway submissions for interoperable artificial pancreas components ahead of Health Canada coordination deadlines. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the lowest barrier to patient onboarding in Canada's lagging CGM penetration provinces, where provincial reimbursement gaps create cash-pay opportunity. Target intermittent scanning protocols for Type 2 non-intensive users previously excluded from device reimbursement. Deploy smartphone-integrated telehealth bundles that circumvent durable medical equipment distributor networks entirely. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by diversified health technology conglomerates seeking algorithmic capabilities and captive sensor manufacturing. Long-term viability hinges on sustained Medicare reimbursement expansion and successful closed-loop algorithm validation. Monitor FDA software-as-medical-device clearance timelines as the critical inflection signal for cloud-based platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| FDA De Novo Pathway Submission | Accelerates interoperable artificial pancreas component approvals ahead of Health Canada coordination. |
| Hospital System Partnership | Secures standardized CGM brand mandates across employed physician networks in Texas and Florida. |
| Software Companion Development | Enables cloud-based predictive dosing platforms that satisfy CMS prior-authorization evidence requirements. |
| Reimbursement Strategy | Expands Medicare Advantage formulary inclusion for closed-loop systems among ambulatory seniors. |
| CE Marking Pathway | Facilitates cross-border platform approvals through Health Canada and FDA regulatory convergence. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and continuous glucose monitor reimbursement specialists. FDA 510(k) and de novo submission databases, CMS national coverage determination records, Health Canada medical device licenses, and hospital procurement databases provided secondary validation. Bottom-up patient population estimates triangulated against top-down manufacturer revenue disclosures across the analysis window.
Data-stream reconciliation across installed base surveys, replacement cycle assumptions, and pricing tier distributions informed the analytical framework. Segmentation dimensions modeled include device category, diabetes type severity, end-user setting, and technology platform architecture. CAGRs derived from slope-log regression on annual volume estimates, with insulin pump growth calibrated to closed-loop algorithm maturation timelines and CGM expansion tied to Medicare reimbursement threshold changes.
The model holds under stable CMS national coverage determination frameworks and continued FDA-Health Canada regulatory coordination; deviation in reimbursement policy or interoperability mandate timing would shift volume trajectories. Practitioners should monitor Health Canada software-as-medical-device validation timelines and provincial formulary expansion signals for early indicators of Canadian market acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
SGLT2 Inhibitors Treatment Market
Diabetes Care
Self-Monitoring Blood Glucose Strips Market
Diabetes Care
India Insulin Infusion Pump Market
Diabetes Care
United Kingdom Continuous Glucose Monitoring Market
Diabetes Care
Disposable Insulin-Delivery Device Market
Diabetes Care
BRIC Diabetes Care Devices Market
Diabetes Care
Diabetes Monitors Market
Diabetes Care
United States Self-Monitoring Blood Glucose Market
Diabetes Care
Diabetes Care Devices and Drugs Market
Diabetes Care
Mexico Diabetes Care Devices Market
Diabetes Care
OTC Glucose Monitors Market
Diabetes Care
India Oral Anti-Diabetic Drug Market
Diabetes Care
Spain Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Global Continuous Subcutaneous Insulin Infusion Market
Diabetes Care
Europe Diabetic Foot Ulcer Treatment Market
Diabetes Care
Egypt Diabetes Care Devices Market