
 North America Advanced Wound Care Market | 2026-2036
North America Advanced Wound Care Market Size, Share, and Industry Trends Forecast 2026-2036
North America Advanced Wound Care Market Outlook
Home healthcare agencies are reorganizing procurement patterns for advanced wound care supplies as payors shift reimbursement toward lower-acuity settings. Smith & Nephew leverages its negative pressure wound therapy portfolio to sustain institutional relationships while building direct-to-provider channels. Mölnlycke Health Care anchors its North American position through specialized silicone foam technology that dominates post-operative segments. Organogenesis competes on bioengineered tissue platforms developed under FDA quality system regulation frameworks.
Advanced wound care comprises therapeutic products and devices engineered to maintain moist wound environments, modulate protease activity, or deliver active biological components such as living keratinocytes and fibroblasts in matrix scaffolds. These systems serve primarily to accelerate closure in chronic, surgical, and traumatic wounds that fail standard gauze-and-tape protocols. Foam dressings and hydrogels lead current volume due to established reimbursement codes and clinician familiarity, while biologics represents the fastest-expanding margin pool as grafting technologies penetrate outpatient settings. Negative pressure wound therapy equipment commands the highest capital intensity per patient episode, creating distinct financing dynamics from disposable dressing segments.
FDA regulates advanced wound care products through 510(k), PMA, and HCT/P pathways depending on biological activity claims, while CMS national coverage determinations directly shape provider adoption economics for home-based therapy. State Medicaid programs in Texas and California layer additional prior authorization requirements that fragment access patterns across the region. Stakeholders must monitor evolving FDA guidance on regenerative medicine advanced therapy designation criteria as these classifications will determine which biologic platforms receive accelerated review and premium reimbursement positioning.
Market Dynamics
Post-acute care migration is compressing patient episodes into home settings, forcing manufacturers to reconfigure distribution networks around decentralized wound management rather than hospital-centric supply chains.
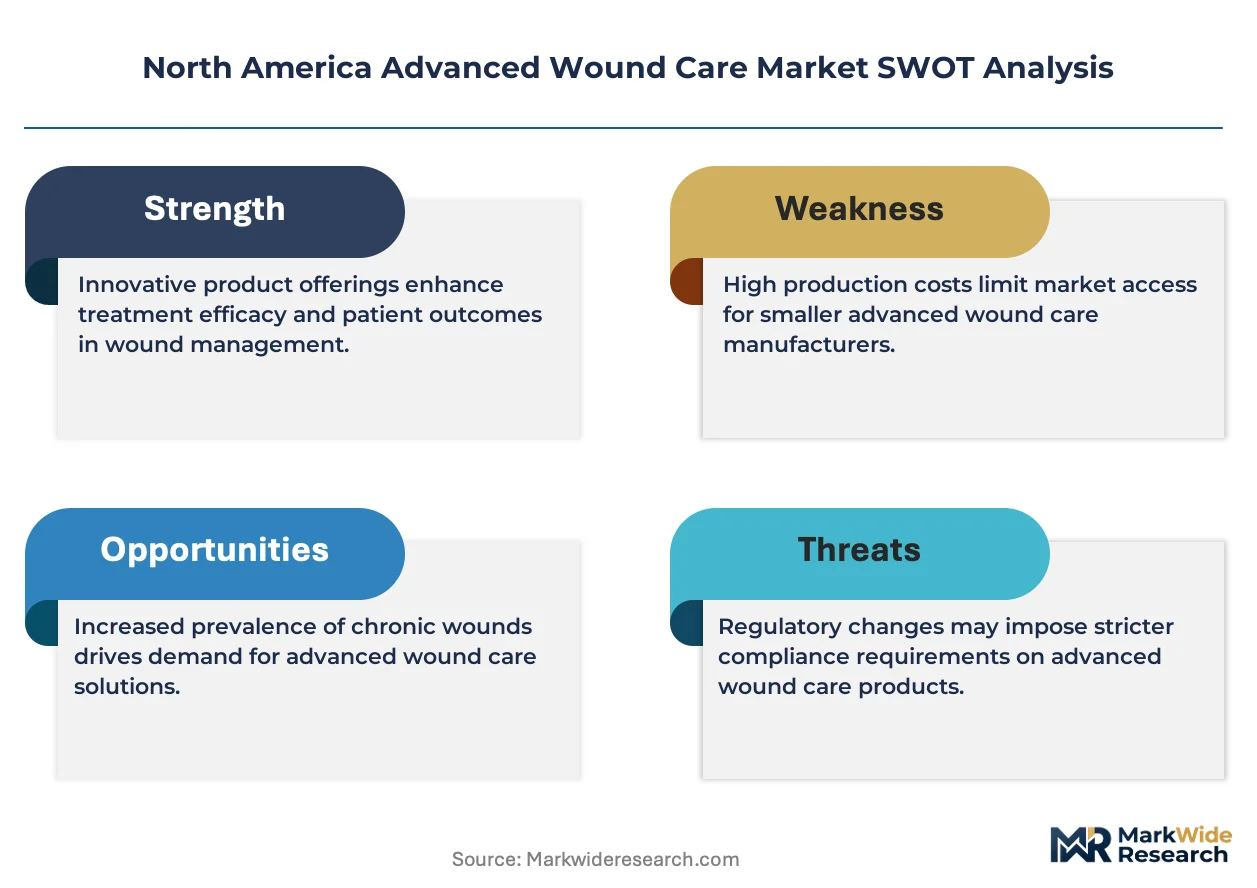
Growth Catalysts
- Regenerative Medicine Advanced Therapy (RMAT) Designation:FDA's expedited review pathway for bioengineered skin substitutes accelerates commercialization timelines for cell-based wound grafts. This compresses development cycles and expands reimbursement eligibility for living tissue products.
- Diabetes Prevalence Concentration:Texas, Florida, and California generate disproportionate chronic ulcer volumes due to aging demographics and metabolic disease burdens. These states drive demand for advanced moisture-retentive dressings and negative pressure systems.
- Negative Pressure Wound Therapy Miniaturization:Portable battery-powered devices enable therapy continuation outside acute care facilities. This technology shift expands addressable patient populations into skilled nursing and residential settings.
Market Restraints
- Silicone Raw Material Volatility:Specialized medical-grade silicone foam depends on petrochemical feedstocks subject to supply fluctuations. Input cost instability compresses margin predictability for advanced dressing manufacturers.
- Prior Authorization Fragmentation:State Medicaid programs in Texas and California impose non-uniform coverage requirements for home-based biologic therapies. This regulatory friction creates access disparities and administrative burden for providers.
- Standard Gauze Substitution:Basic wound care protocols in cost-constrained long-term care facilities resist upgrade to advanced modalities. Lower-acuity settings maintain legacy dressing practices despite clinical evidence for moist wound healing.
Strategic Opportunities
- Rural Home Health Penetration:Underserved regions across the Mountain West and Central Plains lack specialized wound care infrastructure. Telemedicine-integrated dressing delivery models can capture these geographic white spaces.
- Cellular Matrix-Hydrogel Convergence:Hybrid products combining living keratinocytes with moisture-modulating substrates address multiple healing phases. This technology integration creates premium positioning between biologics and traditional dressings.
- Medicare Advantage Channel Expansion:Managed care plans increasingly authorize advanced wound products for capitated home health episodes. This reimbursement evolution rewards direct contracting with integrated delivery networks.
Industry Challenges
- Wound Care Specialist Workforce Scarcity:Certified wound ostomy continence nurses remain concentrated in urban hospital systems. Rural home health agencies struggle to staff qualified clinicians for complex dressing protocols.
- HCT/P Compliance Complexity:Human cells, tissues, and cellular products face dual FDA and state tissue bank oversight. Multi-jurisdictional registration requirements extend time-to-market for allogeneic graft manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Advanced Wound Care Market |
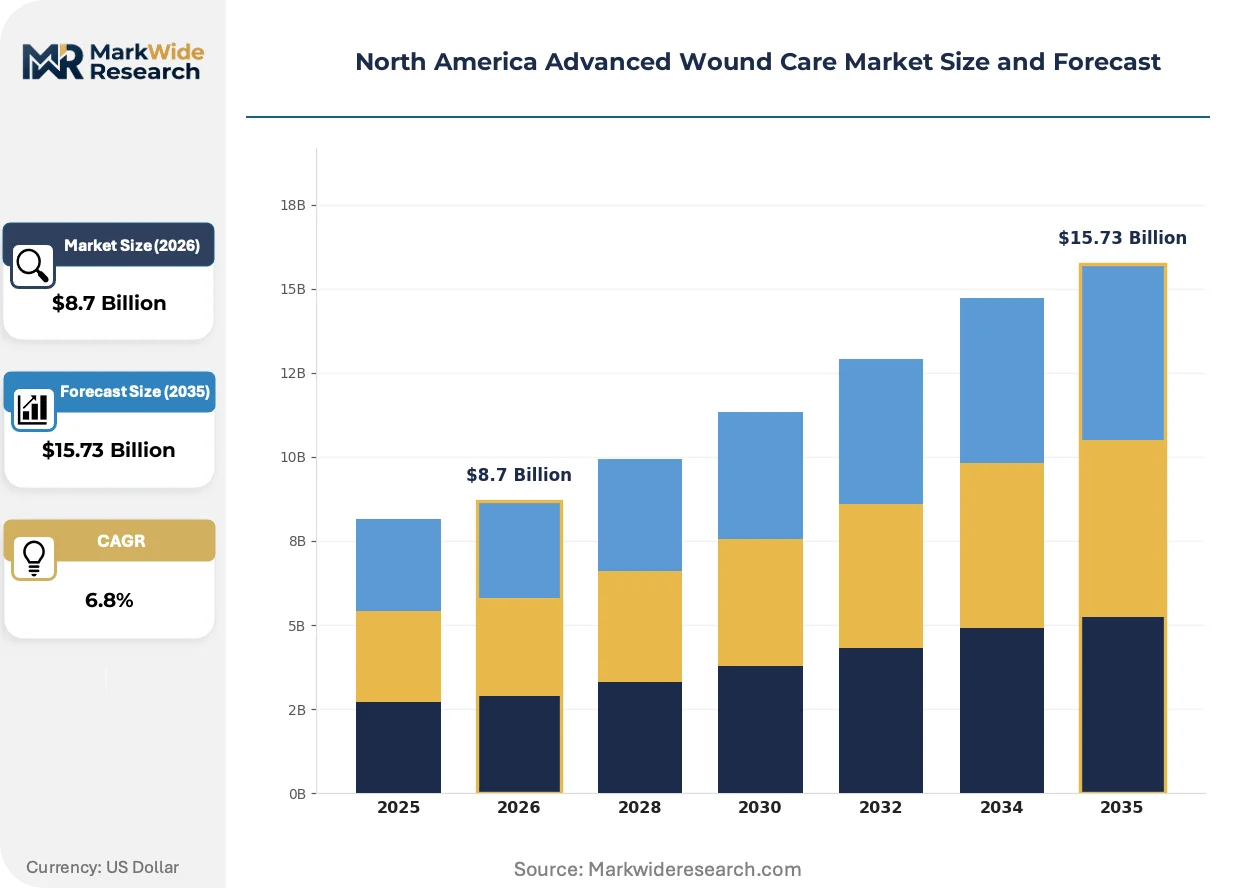
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrogels, Foam Dressings, Film Dressings, Biologics End User: Hospitals, Home Healthcare, Long-term Care Facilities, Outpatient Clinics Technology: Negative Pressure Wound Therapy, Electrical Stimulation, Bioengineered Tissue, Advanced Bandages Application: Traumatic Wounds, Surgical Wounds, Chronic Ulcers, Burns |
| Companies Covered | Solventum, Smith & Nephew, Mölnlycke Health Care, ConvaTec Group, Organogenesis, Cardinal Health, Coloplast, Integra LifeSciences Corporation, B. Braun, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Advanced Wound Care Market Strategic Shifts
Bioactive dressing platforms are converging with digital monitoring capabilities, creating intelligent wound management systems that transmit healing progression data to remote clinical teams.
Antimicrobial silver-impregnated foam is displacing standard silicone foam in post-operative and diabetic foot ulcer applications. Outpatient surgical centers and home health agencies are adopting these infection-preventing substrates at accelerating rates. This displacement is compressing commodity dressing margins while expanding premium product addressable markets.
FDA's evolving guidance on regenerative medicine advanced therapy designation criteria is reshaping competitive entry barriers for bioengineered tissue platforms. Manufacturers with RMAT-classified products gain expedited review and enhanced reimbursement negotiation positioning. Biologic graft segments in Texas and Florida are responding with accelerated clinical trial investments to secure these regulatory advantages.
Hospital supply chain consolidation is forcing wound care vendors toward direct-to-provider contracting models. Integrated delivery networks in California are unbundling traditional distributor relationships to capture procurement savings through manufacturer-direct agreements. This channel restructuring concentrates purchasing power among fewer buyer entities while fragmenting legacy distribution economics.
North America Advanced Wound Care Market Segmentation
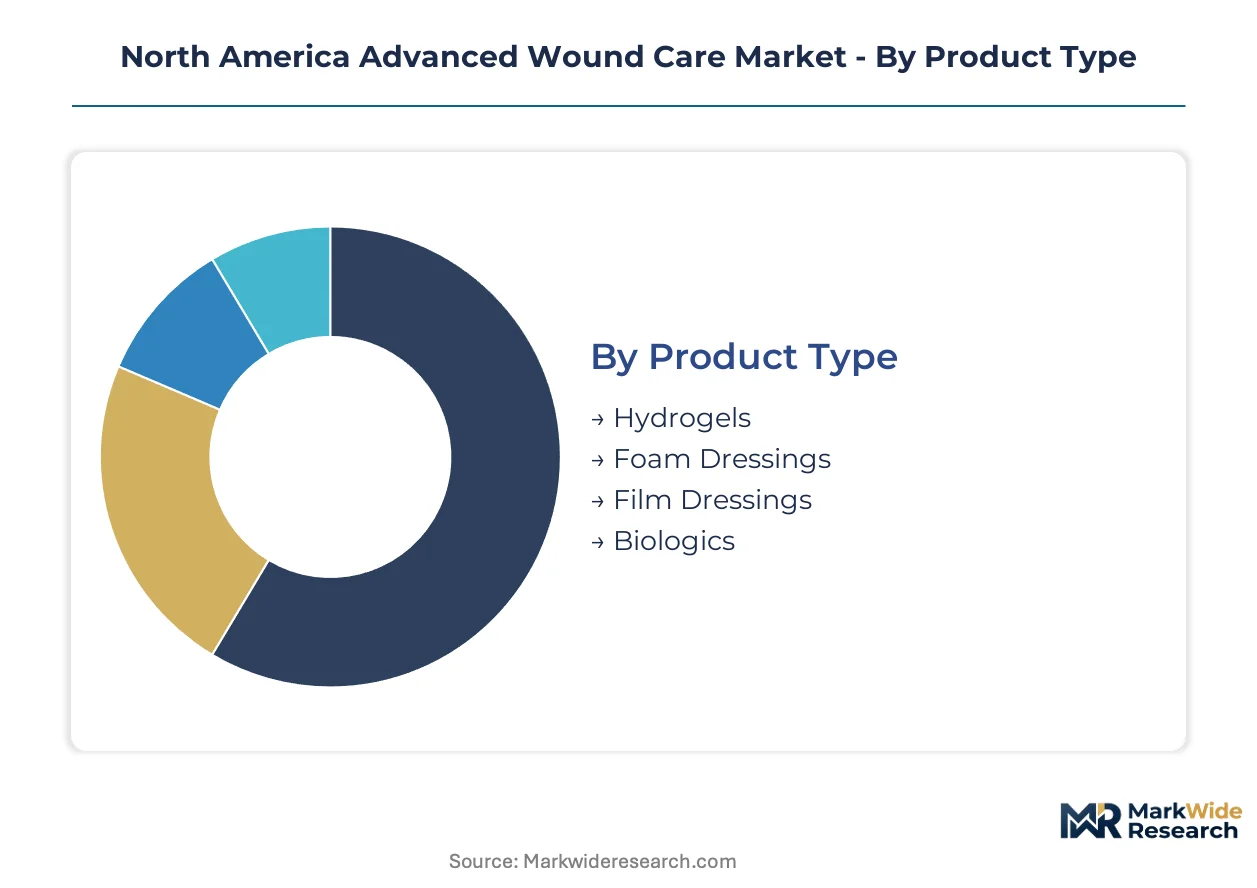
Advanced wound care procurement patterns diverge sharply across care settings and wound etiologies. Manufacturers must align product portfolios with reimbursement pathways that favor specific modalities in hospitals versus home health environments.
Product Type:
Highest-margin opportunities concentrate in biologics and specialized foam substrates where proprietary formulations command premium positioning.
- Biologics:Living cell matrices and growth factor formulations deliver accelerated closure in diabetic foot ulcers and venous leg ulcers. Texas and Florida wound centers drive concentrated procurement of bioengineered skin substitutes as FDA 510(k) clearances expand outpatient eligibility.
- Foam Dressings:Silicone-adherent foam dominates post-operative segments through moisture-modulating vapor transmission. California integrated delivery networks standardize on antimicrobial silver-impregnated variants for surgical site infection prevention.
- Hydrogels:Cross-linked polymer sheets maintain hydrated environments for dry necrotic wounds in long-term care settings where staffing constraints favor low-maintenance protocols.
- Film Dressings:Semi-permeable polyurethane barriers protect superficial abrasions and IV sites with minimal dressing change frequency.
The dominant share belongs to foam dressings, while biologics is gaining share fastest through Medicare Advantage authorization expansion.
End User:
Revenue concentration is shifting toward decentralized settings as CMS reimbursement migrates patients out of acute care.
- Home Healthcare:Portable negative pressure systems and disposable biologic grafts enable complex wound management in residential settings. Prior authorization requirements in Texas Medicaid create access friction for cellular products.
- Hospitals:Operating room procurement of antimicrobial foam and bioengineered tissue anchors institutional relationships despite declining episode volumes.
- Long-term Care Facilities:Cost-constrained skilled nursing operations in the Central Plains resist upgrade from standard gauze despite clinical evidence for moist wound healing protocols.
- Outpatient Clinics:Ambulatory surgical centers in Florida and California adopt silver-impregnated foam for same-day procedure discharge protocols.
Home healthcare now captures the steepest expansion trajectory, though hospitals retain the largest absolute spend.
Technology:
Capital intensity varies dramatically between durable equipment and disposable platforms.
- Negative Pressure Wound Therapy:Battery-powered portable devices extend therapy into skilled nursing and residential settings. Miniaturization trends in Texas and California home health agencies reduce hospital readmission penalties.
- Bioengineered Tissue:Allogeneic and autologous graft platforms face dual FDA and state tissue bank oversight. RMAT designation accelerates commercialization timelines for cell-based products in concentrated diabetes markets.
- Electrical Stimulation:Bioelectric wound healing devices penetrate chronic ulcer segments where Medicare coverage determinations support durable medical equipment claims.
- Advanced Bandages:Composite substrates combining hydrogel layers with foam backing address multiple healing phases in single-product protocols.
Negative pressure wound therapy commands the highest capital commitment per patient, while bioengineered tissue is climbing the fastest through regenerative medicine designations.
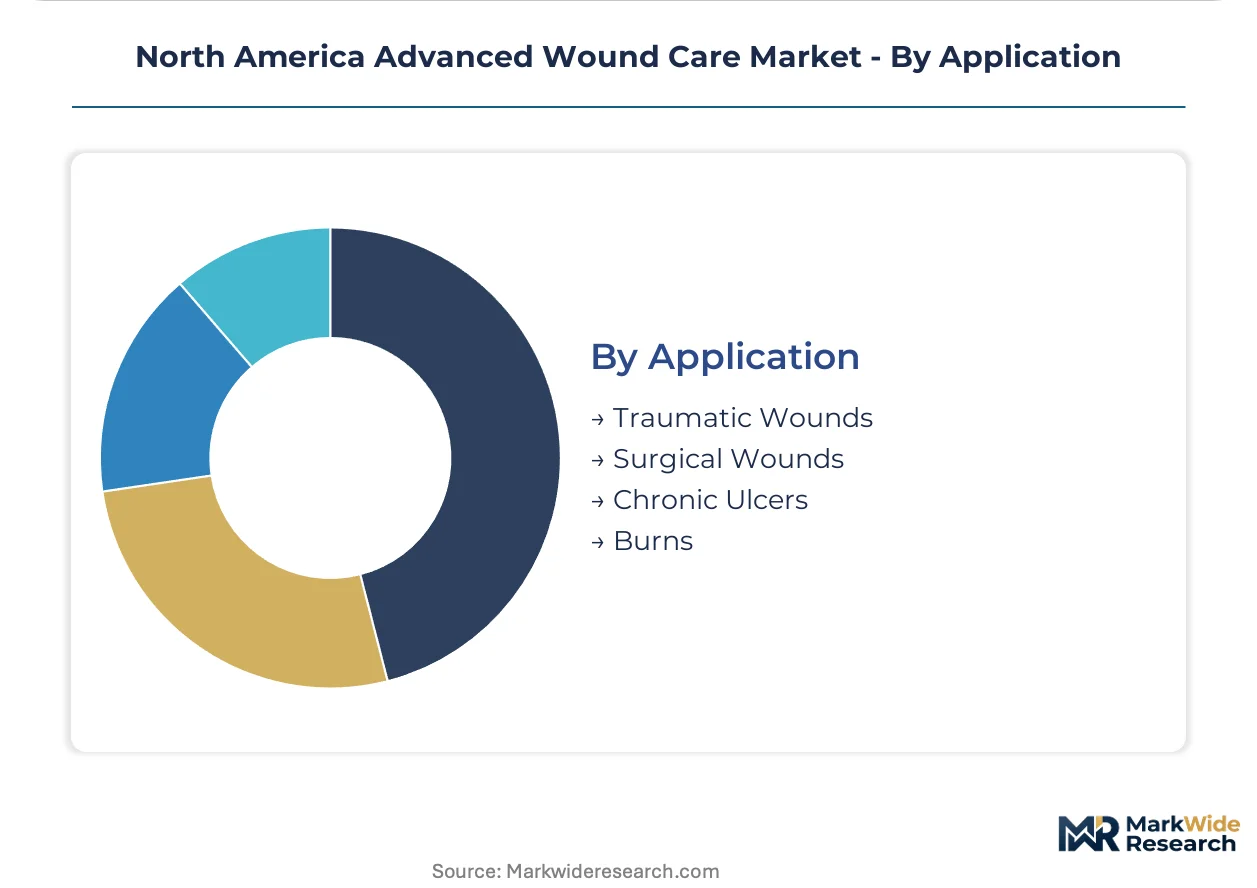
Application:
Chronic ulcer management generates recurring revenue streams that outperform one-time traumatic wound episodes.
- Chronic Ulcers:Diabetic foot and venous leg ulcers in aging Texas and Florida populations sustain long-term dressing consumption. Bioengineered grafts and antimicrobial foam address infection risk in neuropathic wounds.
- Surgical Wounds:Post-operative incision care in California ambulatory centers drives silver-impregnated foam adoption for infection prevention.
- Traumatic Wounds:Emergency department procurement of hemostatic dressings and temporary skin substitutes stabilizes acute injury presentations.
- Burns:Specialized burn centers in regional referral networks utilize cellular matrix products for partial-thickness coverage.
Chronic ulcers dominate absolute volume, though surgical wound applications are expanding most quickly through outpatient migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The I-35 corridor freight network and Port of Long Beach container throughput underpin North American wound care distribution infrastructure, connecting Texas manufacturing clusters to Pacific Rim biologics suppliers and enabling just-in-time delivery to decentralized care settings.
United States
Texas, Florida, and California generate concentrated chronic ulcer demand from aging demographics and diabetes prevalence. FDA 510(k) clearance pathways compress commercialization timelines for bioengineered skin substitutes. Dallas-Fort Worth wound centers drive procurement of negative pressure systems and cellular matrices for outpatient protocols.
Canada
Provincial health authorities in Ontario and Quebec consolidate purchasing through centralized tender processes for advanced dressings. Health Canada regulates biologics through the Biologics and Genetic Therapies Directorate parallel to FDA frameworks. Toronto's hospital networks anchor institutional adoption of antimicrobial foam technologies.
Mexico
COFEPRIS regulatory alignment with FDA standards accelerates cross-border product registration for US manufacturers. Mexico City metropolitan area concentrates private hospital procurement of post-operative wound care. Guadalajara medical device manufacturing clusters supply silicone foam substrates to North American distribution networks.
North America Advanced Wound Care Market Competitive Environment
Concentration sits with diversified medical technology conglomerates that leverage institutional relationships and direct-to-provider channels simultaneously. The vendor base spans three tiers: integrated multinationals with full wound care portfolios, specialized biologics developers focused on regenerative platforms, and regional distributors capturing decentralized home health procurement. Competitive positioning depends on securing Medicare Advantage direct contracts and obtaining RMAT designation for accelerated FDA review.
Among diversified wound care suppliers, Solventum, Smith & Nephew, and Mölnlycke Health Care exemplify archetypes spanning negative pressure systems, silicone foam technology, and institutional supply chain integration. These entities anchor competitive dynamics through differentiated technology platforms and reimbursement navigation capabilities rather than commodity dressing volumes.
| Leading Market Players |
|---|
| Solventum |
| Smith & Nephew |
| Mölnlycke Health Care |
| ConvaTec Group |
| Organogenesis |
| Cardinal Health |
| Coloplast |
| Integra LifeSciences Corporation |
| B. Braun |
| Others |
Value Chain & Pricing Dynamics
Ninety-day inventory cycles for medical-grade silicone foam concentrate pricing power among Texas and California wound care manufacturers with backward-integrated polymer sourcing. This lead-time band creates margin predictability for vertically positioned suppliers while forcing spot-market dependent competitors into defensive pricing postures.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates RMAT-designated biologic grafts from antimicrobial silver-foam intermediates and commodity hydrogel base layers. Price differentiation hinges on FDA clearance tier and volume commitment scale, with integrated delivery networks extracting steepest discounts through direct manufacturer contracts. Pricing pressure stems from Medicare Advantage capitation models that compress per-episode reimbursement. Long-term care facilities exhibit highest price sensitivity due to fixed per-diem funding, while academic medical centers prioritize clinical outcomes over unit cost.
Supply Chain Analysis
Port of Long Beach container throughput serves as the primary chokepoint for Pacific Rim-sourced collagen matrices and silicone raw materials entering North American wound care manufacturing. Supply concentration centers on China for antimicrobial silver compounds, Germany for precision pump components in negative pressure systems, and Mexico for silicone foam substrates. Raw material dependencies include petrochemical-derived medical-grade silicone, porcine-derived collagen scaffolds, and lithium-ion cells for portable therapy devices. Tariff exposure on Chinese-sourced active ingredients creates margin vulnerability for hydrogel and antimicrobial dressing producers. Distribution runs through specialized medical-surgical distributors and direct-to-provider channels serving integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where FDA 510(k) clearance databases and Medicare coverage determinations create substantial switching costs for provider institutions. Regulatory entrenchment protects incumbent positions against commodity substitution.
For Market Incumbents: Fortify institutional relationships through exclusive GPO contracting with Texas and Florida hospital systems while deepening captive supply of medical-grade silicone foam substrates. Emerging biologics developers with RMAT designations threaten premium positioning in diabetic foot ulcer segments. Capacity addition in Guadalajara manufacturing clusters secures polymer supply continuity against petrochemical volatility. For New Entrants and Emerging Players: FDA's RMAT designation fast-track offers accelerated pathway into Medicare Advantage reimbursement channels for cell-based wound graft developers. Rural home health agencies across the Mountain West represent the most penetrable white space, underserved by wound care specialist staffing. Telemedicine-integrated dressing delivery models enable direct-to-provider bypass of consolidated distributor networks. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical technology conglomerates seeking to divest non-core wound care portfolios amid supply chain restructuring. Long-term viability favors biologics platforms with regenerative medicine designations over commodity dressing manufacturers facing silicone cost volatility. Watch FDA guidance evolution on HCT/P oversight as inflection indicator for allogeneic graft commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| RMAT Designation Pursuit | Expedited FDA review compresses commercialization timelines for bioengineered skin substitutes in Texas and Florida wound centers. |
| Direct-to-Provider Contracting | Bypass of traditional distributors captures procurement savings for California integrated delivery networks negotiating manufacturer-direct agreements. |
| Silicone Foam Backward Integration | Captive polymer supply insulates margin predictability against petrochemical feedstock volatility affecting medical-grade foam production. |
| Telemedicine Platform Integration | Remote monitoring capabilities extend advanced wound care penetration into rural home health markets lacking specialist staffing. |
| Medicare Advantage Reimbursement Strategy | Capitated episode authorization unlocks biologic graft access for managed care plans seeking readmission penalty avoidance. |
Study Parameters
A standing panel of wound center medical directors, hospital GPO contract managers, home health agency procurement leads, and FDA regulatory affairs specialists provided ongoing calibration against secondary validation. Primary fieldwork combined structured interviews with biomedical engineers at negative pressure device manufacturers and purchasing committee members at California integrated delivery networks. Secondary sources encompassed FDA 510(k) clearance databases, CMS national coverage determinations, hospital procurement contract disclosures, and state Medicaid prior authorization requirements. Bottom-up patient episode modeling triangulated against top-down manufacturer revenue segmentation.
Consistency checks validated volume and value outputs against external benchmarks including Medicare claims data patterns and GPO contract value disclosures across the analysis window. The analytical framework segmented by product type, end-user setting, wound etiology, and geographic reimbursement cluster. CAGRs derived from patient population projections, episode frequency assumptions, and product mix shifts toward higher-margin biologics. Forecast inputs incorporated diabetes prevalence trajectories, post-acute migration rates, and FDA regenerative medicine designation pipeline status.
Decision-makers should treat outputs as directional under assumptions of stable Medicare reimbursement methodology and continued FDA 510(k) pathway availability for bioengineered tissues; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as state Medicaid prior authorization requirements and silicone raw material supply conditions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Post-Operative Wound Treatment Market
Wound Care
Infectious Wound Care Management Market
Wound Care
Hemostats for Wound Closure Market
Wound Care
Global Diabetic Foot Ulcers Market
Wound Care
Antimicrobial Regenerative Wound Matrix Market
Wound Care
Bioactive Wound Dressing Market
Wound Care
Wound Management Market
Wound Care
Venous Skin Ulcer Treatment Market
Wound Care
Moist Wound Dressings Market
Wound Care
Global Traditional Wound Management Market
Wound Care
Enzymatic Wound Debridement Market
Wound Care
Patch Based Wound Healing Products Market
Wound Care
Italy Wound Care Market
Wound Care
Smart Bandages and Smart Wound Dressings Market
Wound Care
Pressure Ulcer Treatment Market
Wound Care
Pressure Bandages Market