
 Global Diabetic Foot Ulcer Treatment Market | 2026-2036
Global Diabetic Foot Ulcer Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Diabetic Foot Ulcer Treatment Market Foresight
The capital-intensity divergence between advanced biologic manufacturers and commoditized dressing suppliers is unwinding competitive boundaries across the diabetic foot ulcer treatment landscape. Smith & Nephew Plc leverages its vertically integrated tissue-engineering platform to capture premium positioning in bioactive wound care. Mölnlycke Health Care AB anchors its European manufacturing base to sustain cost-competitive supply of antimicrobial foam dressings. Organogenesis Inc. specializes in living cell-based therapies, differentiating its portfolio from conventional passive wound coverings.
Diabetic foot ulcer treatment encompasses medical interventions, devices, and biologics designed to manage neuropathic, ischemic, or infected lower-extremity wounds in patients with diabetes mellitus, typically involving debridement, moisture-balanced dressings, offloading footwear, and advanced cellular or tissue-based products that modulate the wound microenvironment to accelerate closure and prevent amputation. Wound dressings and growth factors command the deepest margin pools as clinicians shift from saline-moistened gauze toward antimicrobial silver-impregnated foams and platelet-derived growth factor formulations that demonstrably reduce healing time. Homecare providers represent the fastest-expanding end-user channel as payors push cost-bearing toward outpatient settings and remote wound monitoring technologies mature.
The FDA regulates cellular and tissue-based products under 21 CFR Part 1271, while the EU MDR imposes stricter clinical evidence requirements on advanced wound care devices, elevating compliance costs but also consolidating market access around well-capitalized innovators. The WHO's Global Diabetes Compact further amplifies demand by embedding foot ulcer prevention and treatment into national noncommunicable disease strategies across member states. Stakeholders must weigh the pace of bioengineered skin substitute reimbursement expansion against the commoditization risk inherent in basic wound dressing categories.
Market Dynamics
The diabetic foot ulcer treatment landscape is bifurcating around reimbursement access for bioengineered skin substitutes versus commoditized advanced dressings, with payor gatekeeping functions now determining competitive viability more than clinical efficacy alone.
Growth Catalysts
- FDA Breakthrough Devices Program:Accelerated review pathways for living cell-based therapies compress time-to-market for regenerative medicine developers seeking premium reimbursement tiers.
- Homecare channel expansion:Remote wound monitoring platforms enable payors to shift site-of-care from inpatient facilities to outpatient settings without sacrificing clinical oversight.
- Silver-impregnated foam adoption:Antimicrobial dressing protocols in hospital outpatient departments displace saline-moistened gauze as first-line standard of care.
Market Restraints
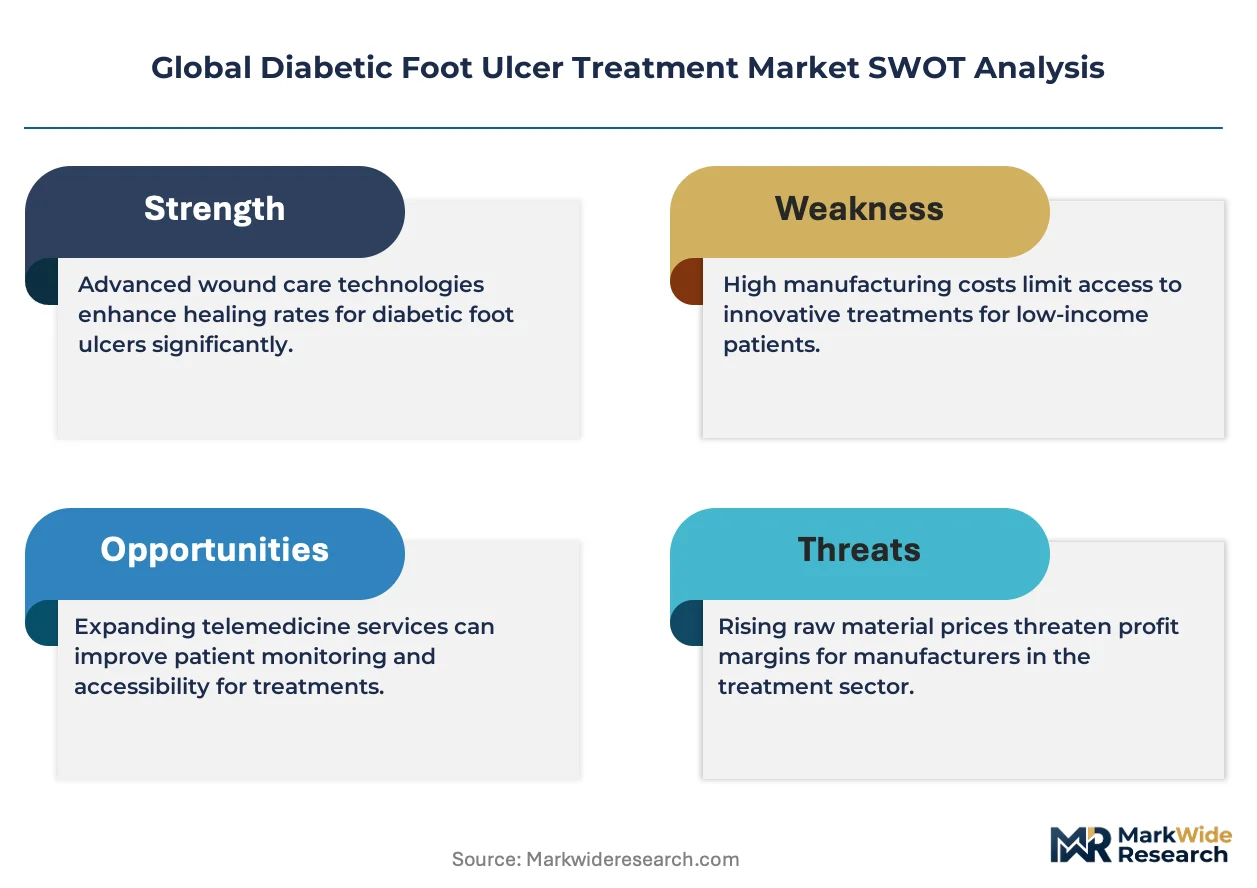
- Bioengineered skin substitute cost barriers:Manufacturing complexity and cold-chain logistics limit production scale, constraining patient access in cost-sensitive reimbursement environments.
- EU MDR clinical evidence requirements:Stricter premarket conformity assessment timelines extend certification cycles for advanced wound care devices, elevating capital requirements for market entry.
- Physician training gaps:Limited specialist familiarity with cellular therapy application protocols slows protocol adoption in community wound care settings.
Strategic Opportunities
- Underpenetrated screening infrastructure:India's national diabetes control programs present whitespace for integrated foot ulcer prevention and early intervention service models.
- Digital therapeutics convergence:AI-powered wound imaging combined with automated measurement tools enables predictive healing analytics for remote patient management.
- Japan's regenerative medicine regulatory sandbox:Conditional early approval frameworks for cell-based products accelerate commercial validation timelines relative to conventional PMA pathways.
Industry Challenges
- Reimbursement code fragmentation:Inconsistent HCPCS and CPT classification for bioactive dressings across Medicare administrative contractors creates billing uncertainty for outpatient providers.
- Supply chain cold-chain integrity:Living cell-based therapies require validated temperature-controlled distribution networks that many regional distributors lack infrastructure to support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Diabetic Foot Ulcer Treatment Market |
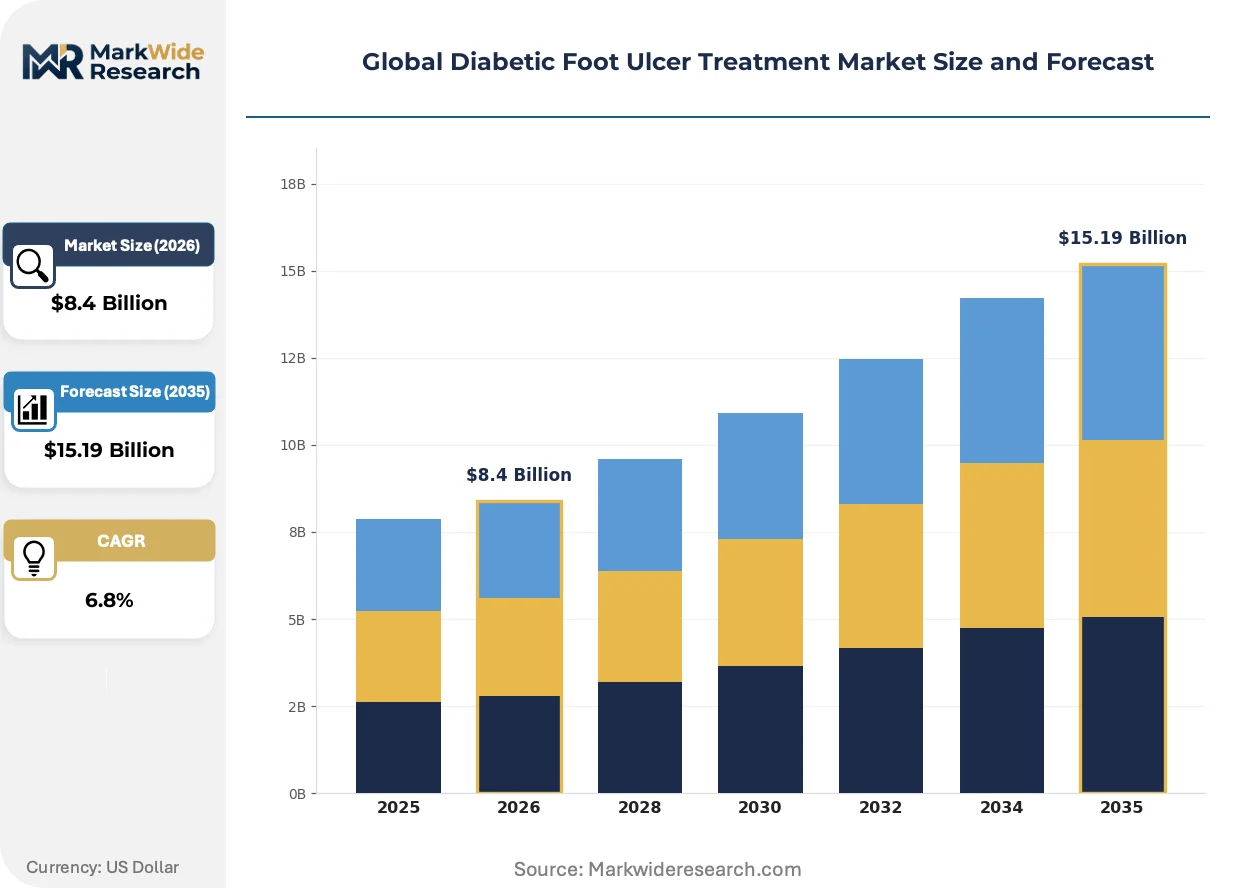
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Agents, Wound Dressings, Therapeutic Shoes, Debridement Tools, Growth Factors Therapy Area: Infection Control, Wound Closure, Pressure Offloading, Inflammation Reduction, Tissue Regeneration End User: Specialty Clinics, Podiatry Centers, Homecare Providers, Rehabilitation Facilities, Community Health Services Distribution Channel: Pharmacies, Online Retailers, Medical Supply Stores, Direct Hospital Procurement, Specialty Distributors |
| Companies Covered | Smith & Nephew Plc, 3M Health Care, ConvaTec Group Plc, Coloplast A/S, Mölnlycke Health Care AB, B. Braun Melsungen AG, Solventum Corporation, Organogenesis Inc., Integra LifeSciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Diabetic Foot Ulcer Treatment Market Shifts & Advancements
Three convergent forces are restructuring how diabetic foot ulcer therapies reach patients: biologic manufacturing scale-up, algorithmic wound assessment, and site-of-care migration toward lower-acuity settings.
Platelet-derived growth factor formulations are decomposing the traditional wound dressing hierarchy by demonstrating measurable healing acceleration in randomized trials. Hospital outpatient departments in Germany and Japan are integrating these biologics into step-up protocols after foam dressing failure. The technology is decomposing margin pools previously captured by passive moisture-management products.
REACH chemical substance restrictions are forcing reformulation of antimicrobial agents in foam dressings across European manufacturing facilities. Suppliers must substitute legacy silver complexes with alternative biocidal compounds or absorb registration costs for continued market access. Advanced dressing categories face the steepest compliance burden, while bioengineered substitutes with living cellular components fall outside REACH scope.
Integrated wound care service contracts are consolidating purchasing decisions around health system-level procurement rather than individual clinician preference. United States accountable care organizations are bundling dressing supplies with specialist consultation and offloading footwear into per-member-per-month arrangements. This shift concentrates vendor selection authority within supply chain functions rather than wound care nursing staff.
Global Diabetic Foot Ulcer Treatment Market Segmentation
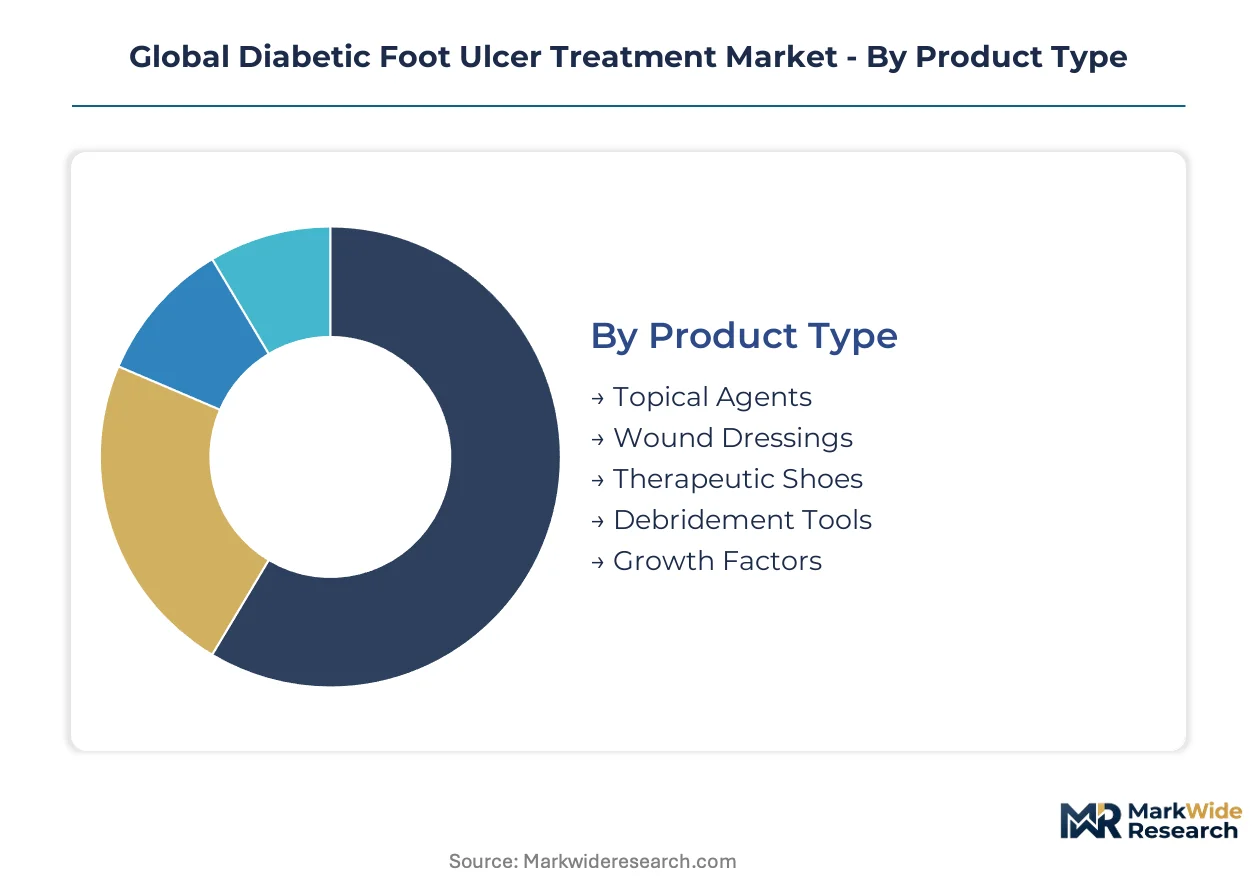
Segmentation in diabetic foot ulcer treatment reveals how substitution dynamics between biologics and conventional products reshape procurement priorities across care settings. Understanding these category boundaries clarifies where margin compression concentrates versus where premium positioning endures.
Product Type:
Wound dressings face the most acute substitution pressure as antimicrobial foam protocols displace saline-moistened gauze in hospital outpatient departments across the United States and Germany.
- Wound Dressings:Silver-impregnated foam and hydrocolloid formulations dominate hospital formularies. Demand concentrates in Germany's integrated care networks where REACH chemical restrictions force biocidal reformulation. Cost-sensitive procurement in India's national diabetes programs sustains basic alginate volume despite margin erosion.
- Growth Factors:Platelet-derived formulations represent the biologic tier with strongest clinical differentiation. Recombinant human PDGF-BB concentrates in United States Medicare Advantage plans that reimburse advanced wound care under bundled payment models. Manufacturing scale constraints limit access in Japan's community wound clinics.
- Topical Agents:Enzymatic and collagenase preparations serve debridement adjunct roles in podiatry centers.
- Therapeutic Shoes:Custom-molded offloading footwear anchors diabetic foot prevention protocols in United States accountable care organizations.
- Debridement Tools:Ultrasonic and hydrosurgical devices automate tissue removal in specialty clinics seeking procedure efficiency.
Wound dressings anchor the volume base while growth factors gain share at the steepest rate.
Therapy Area:
Cost tier stratification separates acute intervention categories from chronic management protocols, with tissue regeneration commanding premium reimbursement while infection control faces generic substitution.
- Infection Control:Systemic antibiotics and topical antimicrobial protocols prevent limb-threatening sepsis. Demand concentrates in United States emergency departments where CMS sepsis quality metrics drive rapid intervention. Silver resistance patterns in European hospital networks constrain long-term efficacy.
- Tissue Regeneration:Bioengineered skin substitutes and cellular therapies modulate wound microenvironments. Japan's regenerative medicine sandbox accelerates conditional approvals for living cell products ahead of conventional PMA timelines. Cold-chain infrastructure gaps in Brazil limit distribution reach.
- Wound Closure:Negative pressure wound therapy and advanced dressings accelerate epithelialization in podiatry centers.
- Pressure Offloading:Total contact casting and removable boot systems redistribute plantar pressure in rehabilitation facilities.
- Inflammation Reduction:Matrix metalloproteinase modulators address chronic wound protease imbalance in specialty clinics.
Infection control captures the deepest volume while tissue regeneration climbs the fastest as reimbursement frameworks mature for cellular therapies.
End User:
Site-of-care migration concentrates procurement authority differently across channels, with homecare providers gaining purchasing influence as payors shift cost-bearing from inpatient facilities.
- Homecare Providers:Remote wound monitoring platforms enable outpatient management without clinical oversight sacrifice. Demand concentrates in United States Medicare Advantage networks where per-member-per-month contracts bundle supplies with telehealth consultation. Nurse training gaps on cellular therapy application slow protocol adoption in Germany's decentralized home nursing sector.
- Specialty Clinics:Dedicated wound care centers integrate advanced biologics into step-up treatment algorithms. United States hospital outpatient departments leverage 340B drug pricing to capture margin on physician-administered growth factors. Japan's clinic licensing requirements restrict cellular therapy administration to certified wound specialists.
- Podiatry Centers:Foot and ankle specialists anchor preventive screening and early intervention in United States urban markets.
- Rehabilitation Facilities:Post-acute settings manage offloading compliance and mobility restoration in Germany's statutory insurance system.
- Community Health Services:India's national diabetes control programs embed foot ulcer prevention into primary care infrastructure.
Specialty clinics anchor the volume base while homecare providers expand most quickly as remote monitoring technologies mature.
Distribution Channel:
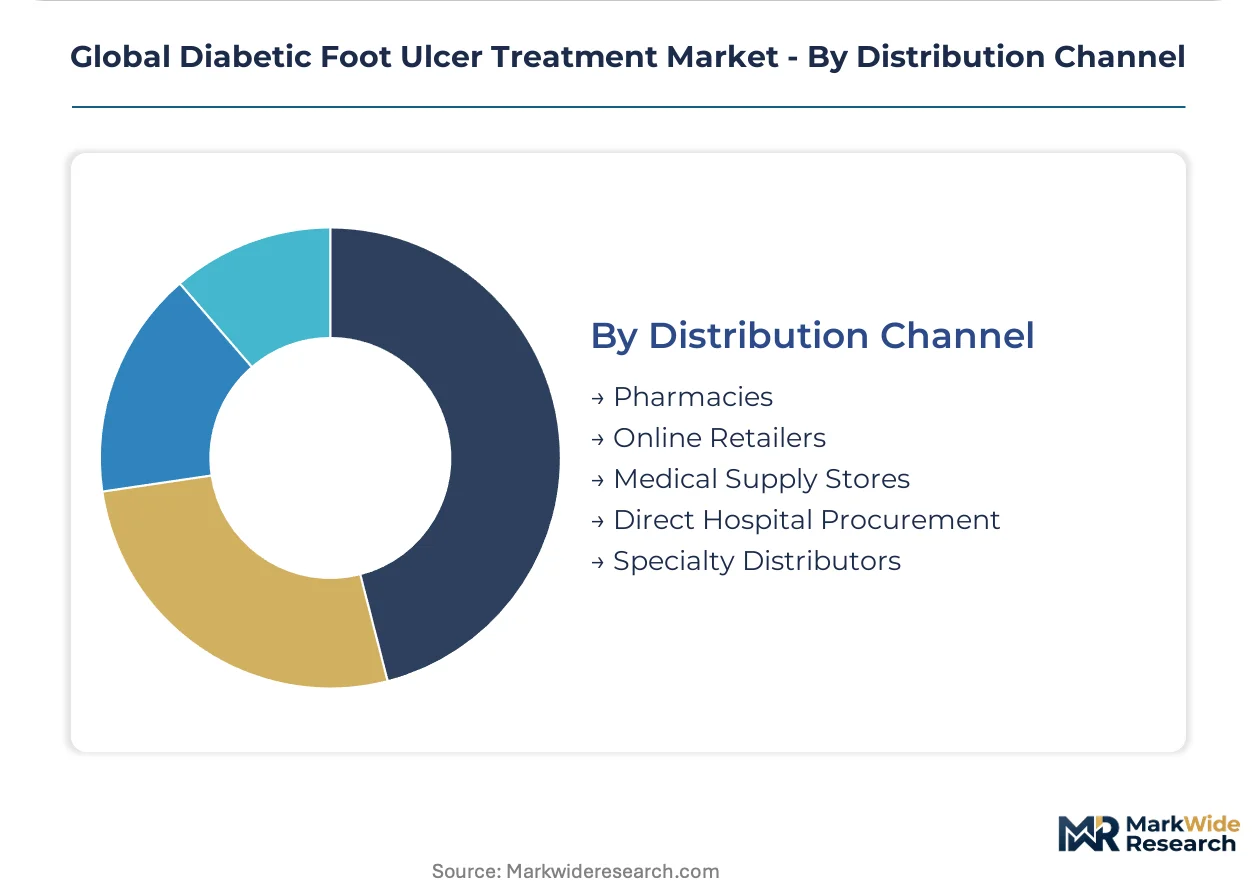
Supply concentration in direct hospital procurement contrasts with fragmentation in retail channels, shaping how manufacturers configure sales force deployment and inventory positioning.
- Direct Hospital Procurement:Integrated delivery networks consolidate purchasing decisions around value-analysis committees. Demand concentrates in United States health systems where GPO contracts bundle advanced dressings with biologic access. EU MDR certificate delays disrupt supplier qualification timelines for new market entrants.
- Specialty Distributors:Cold-chain validated logistics networks serve living cell therapy requirements. United States regional distributors invest in temperature-controlled infrastructure to capture bioengineered skin substitute volume. Brazil's distributor base lacks validated capabilities, constraining patient access to cellular products.
- Pharmacies:Retail and outpatient pharmacy channels dispense topical agents and basic dressings in Germany's integrated care model.
- Medical Supply Stores:Durable medical equipment providers deliver offloading footwear and negative pressure devices to United States homecare settings.
- Online Retailers:E-commerce platforms capture commoditized dressing volume in India's direct-to-patient market.
Direct hospital procurement anchors the volume base while specialty distributors gain share fastest as cellular therapy cold-chain requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for advanced biologics concentrates in high-reimbursement markets while basic dressing manufacturing disperses across cost-optimized production zones. The United States, Germany, Japan, India, and Brazil represent the critical demand nodes where regulatory frameworks and reimbursement depth determine competitive access.
United States
Medicare Advantage bundled payment models accelerate adoption of bioengineered skin substitutes in hospital outpatient departments. The FDA's Breakthrough Devices Program compresses review timelines for living cell-based therapies seeking premium reimbursement tiers. Boston and Minneapolis anchor specialized wound care research clusters where academic medical centers validate cellular therapy protocols.
Germany
Integrated care networks consolidate procurement decisions around value-analysis committees in statutory insurance frameworks. REACH chemical restrictions force silver-impregnated foam reformulation across manufacturing facilities. The Ruhr industrial corridor hosts advanced dressing production while Heidelberg and Berlin concentrate regenerative medicine research infrastructure.
Japan
Conditional early approval frameworks under the regenerative medicine regulatory sandbox accelerate commercial validation for cell-based products. METI prioritizes diabetic foot screening integration into national noncommunicable disease strategies. Osaka and Tokyo metropolitan areas concentrate specialist wound clinics licensed for cellular therapy administration.
India
National diabetes control programs embed foot ulcer prevention into primary care infrastructure with cost-sensitive procurement protocols. CDSCO device registration pathways streamline market entry for basic dressing categories. Maharashtra and Gujarat manufacturing clusters supply alginate and foam dressing volume for domestic consumption and regional export.
Brazil
ANVISA certification requirements create compliance barriers for advanced biologic imports while sustaining demand for conventional wound care. Cold-chain infrastructure gaps in regional distribution networks constrain patient access to cellular therapies. São Paulo state concentrates private hospital capacity where outpatient wound centers adopt negative pressure therapy protocols.
Global Diabetic Foot Ulcer Treatment Market Competitive Landscape
Concentration sits with diversified medical technology conglomerates controlling integrated tissue-engineering platforms and antimicrobial dressing supply chains. The vendor base stratifies across three tiers: vertically integrated biologic manufacturers, regional dressing specialists with cost-optimized production, and emerging cellular therapy developers seeking conditional regulatory pathways. M&A activity targets cold-chain logistics capabilities and digital wound monitoring platforms. Portfolio diversification moves concentrate on bridging passive dressing commoditization with premium biologic access.
Within the biologic-specialist tier, Organogenesis Inc. exemplifies living cell-based therapy positioning, while Smith & Nephew Plc anchors diversified wound care conglomeration across advanced dressings and tissue-engineered platforms. Mölnlycke Health Care AB represents European manufacturing-base concentration for antimicrobial foam supply. These three entities occupy distinct competitive coordinates: cellular therapy specialization, full-spectrum wound care integration, and regional cost-competitive production respectively.
| Leading Market Players |
|---|
| Smith & Nephew Plc |
| 3M Health Care |
| ConvaTec Group Plc |
| Coloplast A/S |
| Mölnlycke Health Care AB |
| B. Braun Melsungen AG |
| Solventum Corporation |
| Organogenesis Inc. |
| Integra LifeSciences |
| Others |
Supply & Pricing Matrix
Capacity utilization disparities between biologic manufacturing suites and commodity dressing lines concentrate pricing power among vertically integrated tissue-engineering platforms while eroding margins for undifferentiated foam suppliers. Cold-chain infrastructure requirements for living cell therapies erect natural price floors that commoditized antimicrobial dressings cannot match, segmenting procurement decisions across hospital value-analysis committees and homecare distributors.
Pricing Analysis
Hospital outpatient departments anchor three-tier pricing stratification across premium bioengineered skin substitutes, standard antimicrobial foam protocols, and economy saline-moistened gauze. Price differentiation hinges on FDA Breakthrough Device certification status and REACH-compliant biocidal formulation grades. Cost compression in basic dressing tiers intensifies as India's national diabetes programs drive volume procurement at reimbursement-constrained price points. Medicare Advantage bundled payment administrators exhibit lowest price sensitivity, while Germany's statutory insurance value-analysis committees enforce aggressive tender competition.
Supply Chain Analysis
Inventory lead times for living cell-based therapies extend substantially beyond conventional dressing cycles due to validated cold-chain requirements and batch-release testing protocols. Manufacturing concentrates in the United States, Germany, and Japan where FDA, EU MDR, and PMDA certification infrastructure supports biologic production. Raw material dependencies span porcine collagen substrates, recombinant growth factor cell lines, and silver-complex antimicrobial compounds. Single-source vulnerability concentrates in temperature-controlled logistics networks where regional distributors lack validated infrastructure. Distribution runs through integrated delivery network procurement offices for hospital systems and specialty distributors for cellular therapy products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating around United States accountable care organizations and Germany's integrated care networks, compressing vendor margins through bundled contracting and step-therapy protocols that prioritize cost containment over clinician preference.
For Market Incumbents: Secure cold-chain logistics partnerships in Brazil and India before regional distributors achieve temperature-validated capabilities, locking out late entrants from cellular therapy distribution. Reinforce reimbursement strategy investments around HCPCS code consolidation to reduce billing uncertainty that slows hospital adoption of bioengineered substitutes. Capacity expansion in Maharashtra and Gujarat manufacturing clusters will defend margin position against cost-optimized alginate imports. For New Entrants and Emerging Players: Remote wound monitoring platform integration represents the service-layer gap where incumbents under-serve homecare providers seeking predictive healing analytics without specialist oversight. India's national diabetes control programs offer the most penetrable geography for integrated prevention-and-treatment service models. A direct-to-homecare go-to-market angle bypasses hospital value-analysis committee gatekeeping that favors established GPO contract holders. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among digital therapeutics developers combining AI-powered wound imaging with automated measurement tools. Long-term viability over the next decade rests on reimbursement expansion for cellular therapies outpacing commoditization in passive dressing categories. Acquisition targets should prioritize cold-chain logistics specialists with validated regional distribution networks. The signal to watch is Japan's regenerative medicine sandbox approval velocity as an indicator of conditional pathway feasibility in other jurisdictions.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Logistics Partnership | Validated temperature-controlled networks unlock cellular therapy distribution in Brazil's underserved regional markets. |
| Reimbursement Strategy Investment | HCPCS code consolidation reduces billing friction for hospital outpatient departments adopting bioengineered substitutes. |
| Digital Therapeutics Platform Integration | AI-powered wound imaging enables predictive analytics for Medicare Advantage per-member-per-month contracts. |
| Manufacturing Scale-Up in Cost-Optimized Clusters | Maharashtra and Gujarat production bases supply alginate and foam dressing volume for India's national programs. |
| Regulatory Sandbox Pathway Navigation | Japan's conditional early approval frameworks accelerate commercial validation timelines for living cell products. |
Research Methodology
Operator-level perspectives from wound care clinicians, hospital purchasing committee members, GPO contracts managers, and homecare nursing directors anchored the qualitative base for this analysis. Primary interviews with these stakeholders combined with secondary validation from FDA 510(k) filings, EU MDR notified body certificates, CMS Medicare claims data, and hospital procurement databases. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the diabetic foot ulcer treatment landscape.
Sensitivity analysis tested forecast outputs against reimbursement policy shifts, regulatory approval timeline variations, and supply chain disruption scenarios across the projection horizon. Segmentation dimensions modeled include product type, therapy area, end user channel, and distribution pathway alongside regional regulatory cluster differentiation. CAGRs were derived from historical volume trajectories adjusted for technology substitution elasticities and payor policy evolution. Industry-specific inputs incorporated diabetic foot screening program expansion rates and bioengineered skin substitute manufacturing capacity buildout schedules.
Underlying assumptions cover sustained Medicare Advantage bundled payment adoption, EU MDR certificate issuance velocity, and cold-chain infrastructure investment continuity, with deviation risk concentrated in reimbursement code fragmentation and REACH chemical restriction enforcement stringency. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Global Type 1 Diabetes (T1D) Market
Diabetes Care
Hyperglycemia Treatment Market
Diabetes Care
Self-Monitoring Blood Glucose Strips Market
Diabetes Care
Pet Diabetes Care Devices Market
Diabetes Care
Germany Digital Diabetes Management Market
Diabetes Care
OTC Glucose Monitors Market
Diabetes Care
Asia-Pacific Insulin Delivery Devices Market
Diabetes Care
Mexico Diabetes Care Devices Market
Diabetes Care
Alternatives for Injectable Diabetes Care Market
Diabetes Care
BRICS Diabetes Drugs Market
Diabetes Care
US Continuous Glucose Monitoring Market
Diabetes Care
BRICS Diabetes Treatment and Prevention Market
Diabetes Care
Thailand Diabetes Care Devices Market
Diabetes Care
Brazil Oral Anti-Diabetic Drug Market
Diabetes Care
Global Blood Glucose Test Strip Market
Diabetes Care
South Korea Oral Anti-Diabetic Drug Market