
 Global Blood Glucose Monitoring Systems Market | 2026-2036
Global Blood Glucose Monitoring Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Blood Glucose Monitoring Systems Market Foresight
Continuous glucose monitoring interoperability with smartphone ecosystems is reconfiguring how data flows between patients and clinicians. Dexcom Inc. leverages cloud-native architecture to sustain real-time analytics leadership. Abbott Laboratories anchors its competitive position through vertically integrated sensor manufacturing at scale. Medtronic plc differentiates via closed-loop insulin delivery integration that extends its addressable therapeutic footprint.
Blood glucose monitoring systems comprise electrochemical, optical, enzymatic, microfluidic, and wireless transmission technologies designed to quantify glucose concentration in interstitial fluid or capillary blood, typically operating within 15-20% accuracy variance against laboratory reference methods under ISO 15197 standards. These systems serve diabetes management, clinical research, sports performance, nutritional monitoring, and pregnancy care applications where glycemic visibility drives therapeutic decisions. Continuous glucose monitors capture the fastest growth trajectory as electrochemical sensor miniaturization reduces insertion pain and extends wear duration. Self-monitoring blood glucose devices retain volume dominance in emerging markets where cost sensitivity and pharmacy channel density favor strip-based testing. Laboratory analyzers occupy stable margin pools in hospital networks requiring regulatory-grade precision for diagnostic confirmation.
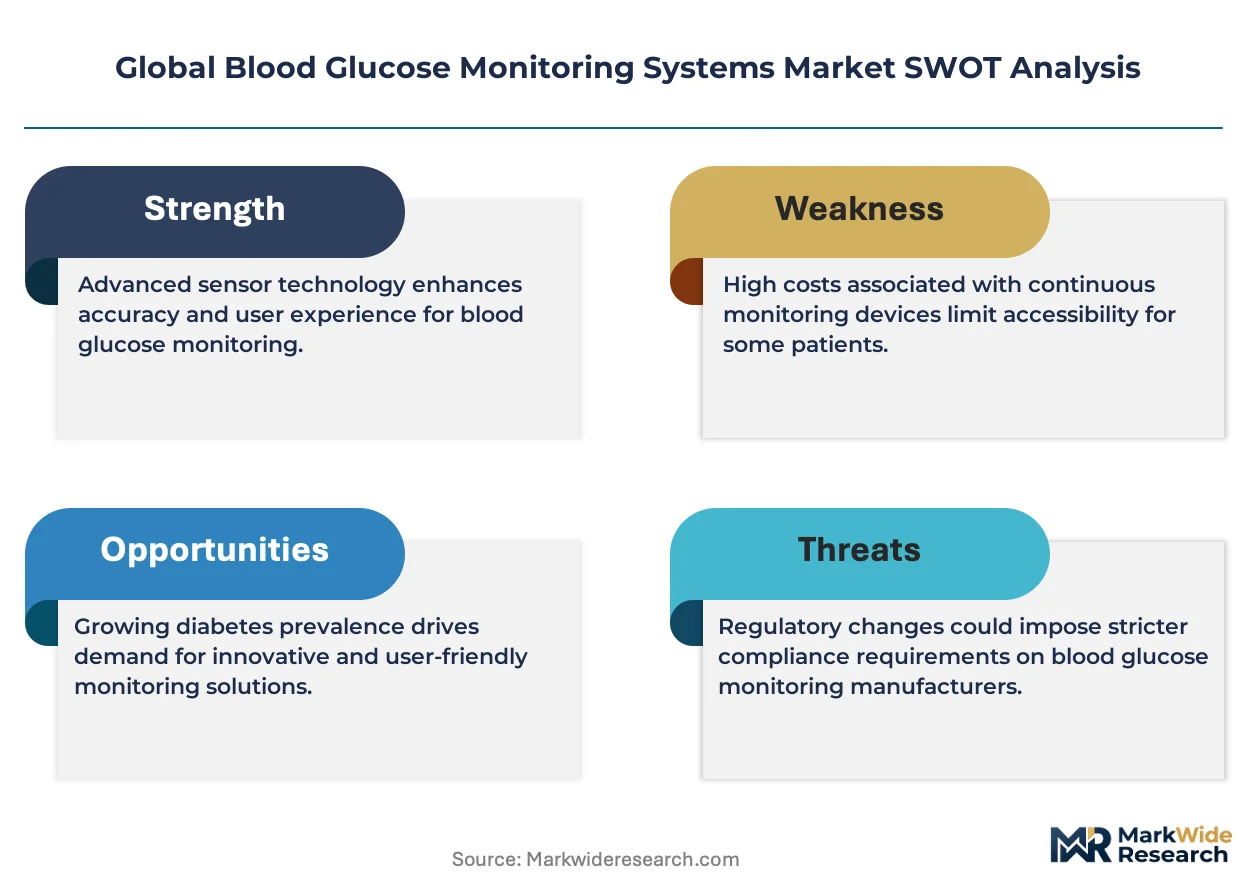
FDA premarket notification pathways and EMA MDR conformity assessments shape product launch cadence and clinical evidence requirements across the United States and European Union. Japan's PMDA enforces localized accuracy validation that filters market access for wireless transmission-enabled devices. China's NMPA accelerates review timelines for home care patient-oriented systems under revised innovative medical device channels. Stakeholders must monitor evolving reimbursement parity between continuous and flash glucose monitoring modalities as payers recalibrate cost-effectiveness thresholds.
Market Dynamics
Continuous glucose monitor interoperability with smartphone ecosystems is compressing data latency between patients and clinicians, forcing electrochemical sensor manufacturers to prioritize wireless transmission protocols over standalone device architectures.
Growth Catalysts
- FDA 510(k) clearance pathway acceleration:Streamlined premarket notification for non-invasive optical sensing technologies reduces time-to-market for home care patient-oriented systems.
- Home care patient self-management protocols:Rising glycemic visibility requirements among Type 1 diabetes populations in the United States and Germany expand reimbursement eligibility for continuous monitoring.
- Electrochemical sensor miniaturization:Reduced insertion pain and extended wear duration capture patient preference shifts away from capillary blood testing.
Market Restraints
- Enzyme electrode raw material concentration:Platinum and glucose oxidase supply chains concentrate among specialty chemical suppliers in Germany and Japan, creating input cost volatility.
- ISO 15197 accuracy validation requirements:Laboratory reference method compliance adds 18-24 month certification timelines that filter smaller entrants from commercialization.
- Flash glucose monitoring substitution threat:Factory-calibrated optical sensors eliminate fingerstick calibration requirements, eroding traditional self-monitoring blood glucose strip volumes.
Strategic Opportunities
- Japan's PMDA localized accuracy validation:Wireless transmission-enabled devices face filtered market access that rewards early regulatory investment with reduced competitive density.
- Sports performance and nutritional monitoring applications:Non-diabetic consumer segments in the United States adopt glucose visibility for metabolic optimization, expanding addressable population beyond clinical indications.
- China's NMPA innovative medical device channel:Revised review timelines for home care patient systems create first-mover advantages for cloud-native data architectures.
Industry Challenges
- Biocompatibility engineering talent scarcity:Interstitial fluid sensor design requires specialized polymer chemistry expertise concentrated among academic medical centers in Massachusetts and Zurich.
- Closed-loop insulin delivery integration complexity:Algorithm validation for automated insulin suspension demands simultaneous hardware-software certification across FDA and EMA jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Blood Glucose Monitoring Systems Market |
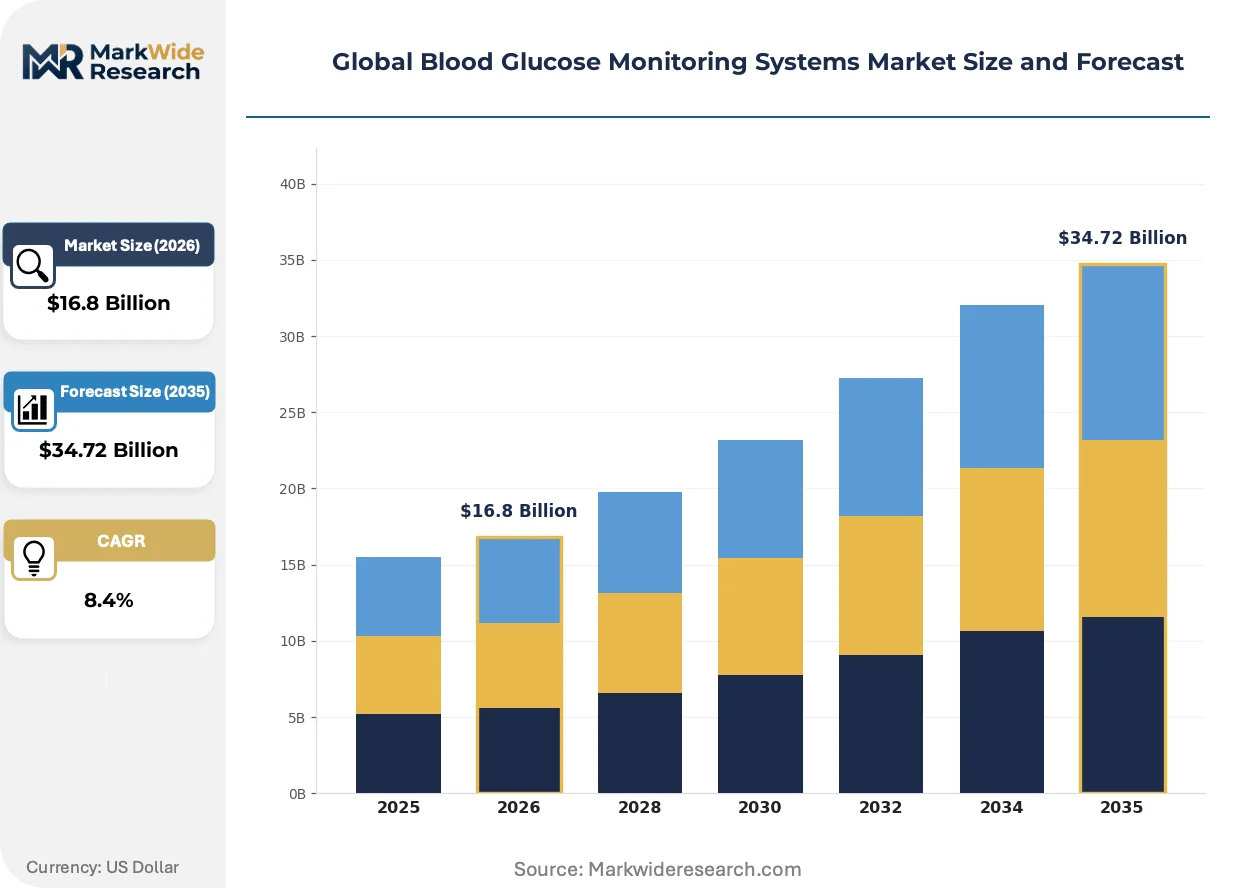
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $34.72 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Glucose Monitors, Flash Glucose Monitoring, Self-Monitoring Blood Glucose Devices, Laboratory Analyzers Technology: Electrochemical, Optical, Enzymatic, Microfluidic, Wireless Transmission Application: Diabetes Management, Clinical Research, Sports Performance, Nutritional Monitoring, Pregnancy Care End User: Diabetes Clinics, Research Laboratories, Home Care Patients, Pharmacies, Diagnostic Centers |
| Companies Covered | Abbott Laboratories, Dexcom Inc., Medtronic plc, F. Hoffmann-La Roche Ltd, LifeScan Inc., Senseonics Holdings, Johnson & Johnson, Novo Nordisk A/S, Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Blood Glucose Monitoring Systems Market Shifts & Advancements
Data architecture decisions now precede hardware design in glucose monitoring, as real-time analytics platforms determine competitive positioning before sensor specifications reach procurement.
Optical glucose sensing is migrating from laboratory reference methods toward wearable consumer applications. Home care patients in Germany and Japan adopt photonic interstitial fluid measurement for factory-calibrated operation without fingerstick validation. This technology is migrating from clinical-grade accuracy requirements toward ±15% variance tolerance that compresses manufacturing cost structures and accelerates over-the-counter channel penetration.
EMA MDR conformity assessments for electrochemical sensors now mandate post-market clinical follow-up studies that extend evidence generation timelines. Manufacturers must maintain active surveillance registries capturing adverse event data across European Union member states. Small-to-mid scale sensor producers face disproportionate compliance burden, consolidating commercialization capacity among vertically integrated manufacturers with captive clinical affairs infrastructure.
Patients now demand unbundled data ownership that permits direct API integration with third-party nutrition and fitness platforms. Pharmacy channel dominance in emerging markets faces disintermediation from direct-to-consumer subscription models that ship sensors through parcel logistics networks. This behavioral shift concentrates in the United States where high-deductible health plans increase price transparency sensitivity and reduce physician gatekeeper influence on device selection.
Global Blood Glucose Monitoring Systems Market Segmentation
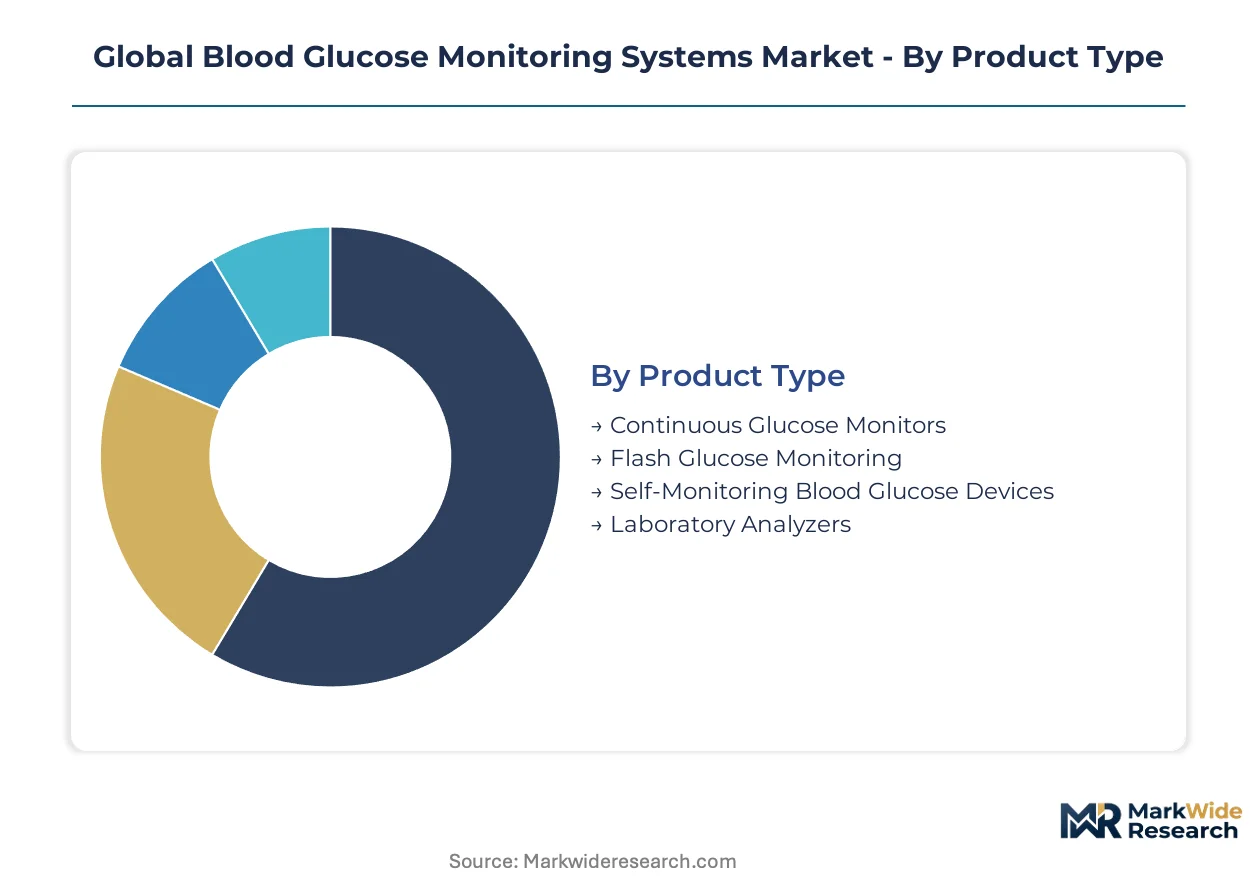
Segmentation in blood glucose monitoring reveals how technology maturity, reimbursement pathways, and patient self-management preferences split demand across distinct commercial pockets. Manufacturers configure sensor architectures, calibration protocols, and data platforms differently for each slice.
Product Type:
Cost tier stratification separates premium subscription-based continuous systems from economy strip-based alternatives, with reimbursement eligibility determining addressable population in each bracket.
- Continuous Glucose Monitors:Electrochemical sensors transmit interstitial fluid readings every 1-5 minutes to smartphone receivers. Demand concentrates among Type 1 diabetes patients in Germany and the United States where reimbursement frameworks cover 80-100% of sensor costs under durable medical equipment benefits.
- Flash Glucose Monitoring:Factory-calibrated optical sensors eliminate fingerstick calibration through photonic interstitial fluid measurement. Adoption accelerates in Japan's pharmacy channels where PMDA clearance for over-the-counter sale removes prescription gatekeeper friction.
- Self-Monitoring Blood Glucose Devices:Capillary blood testing via enzyme electrode strips dominates emerging market volume.
- Laboratory Analyzers:Regulatory-grade precision systems serve hospital diagnostic confirmation workflows.
Self-monitoring blood glucose devices command the established base. The steepest expansion runs through continuous glucose monitors.
Technology:
Application context determines which sensing modality captures design investment, with clinical accuracy requirements diverging sharply from consumer wellness tolerance bands.
- Electrochemical:Amperometric glucose oxidase reactions on platinum electrodes deliver 15-20% accuracy variance against laboratory reference methods. Manufacturing scales through vertically integrated sensor production in Massachusetts and Zurich where polymer chemistry expertise clusters.
- Optical:Near-infrared spectroscopy and photonic interstitial fluid measurement enable factory calibration without enzyme degradation. China's NMPA accelerates review timelines for home care patient-oriented optical systems under revised innovative medical device channels.
- Enzymatic:Glucose oxidase catalytic reactions remain the reference standard for laboratory analyzers.
- Microfluidic:Lab-on-chip architectures reduce sample volume requirements for neonatal and geriatric testing.
- Wireless Transmission:Bluetooth Low Energy and proprietary RF protocols compress data latency between sensors and analytics platforms.
Enzymatic technology commands the established base. Optical sensing gains share fastest as non-invasive form factors penetrate wellness applications.
Application:
Customer type maturity splits the market between regulated clinical indications and emerging consumer wellness segments with divergent accuracy requirements and pricing elasticity.
- Diabetes Management:Glycemic visibility drives insulin dosing decisions for Type 1 and insulin-dependent Type 2 populations. Reimbursement concentration in the United States and Germany creates volume anchors for continuous monitor manufacturers.
- Sports Performance:Metabolic optimization through real-time glucose visibility attracts endurance athletes and biohackers. United States direct-to-consumer subscription models bypass pharmacy channel markups through parcel logistics networks.
- Clinical Research:Regulatory-grade data capture supports pharmaceutical trials and algorithm validation studies.
- Nutritional Monitoring:Postprandial glucose response tracking enables personalized diet optimization.
- Pregnancy Care:Gestational diabetes screening requires frequent glucose surveillance without maternal stress induction.
Diabetes management commands the established base. Sports performance climbs fastest as non-diabetic consumer adoption expands addressable population beyond clinical indications.
End User:
Volume concentration tracks reimbursement pathway maturity, with home care patient segments expanding fastest where self-management protocols reduce clinical infrastructure dependency.
- Home Care Patients:Self-monitoring protocols reduce HbA1c variability through real-time behavioral feedback. Germany's statutory health insurance funds expanded continuous glucose monitor eligibility criteria, accelerating patient-directed procurement decisions.
- Diabetes Clinics:Specialist practices integrate continuous glucose data into therapeutic optimization workflows. Japan's clinic networks favor flash glucose monitoring for patient education and treatment initiation.
- Research Laboratories:Academic medical centers in Massachusetts and Zurich concentrate biocompatibility engineering talent for next-generation sensor development.
- Pharmacies:Strip-based self-monitoring blood glucose device distribution dominates emerging market access.
- Diagnostic Centers:Centralized laboratory analyzers serve population-scale screening programs.
Pharmacies command the established base. Home care patients expand most quickly as reimbursement parity between continuous and flash monitoring modalities improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision electrochemical sensors to diabetes clinics across France and the Netherlands, while the United States ships cloud-native continuous monitors to patient populations in Canada and Australia.
United States
Type 1 diabetes populations and high-deductible health plans drive home care patient procurement of subscription-based continuous monitors. FDA 510(k) clearance pathways compress premarket timelines for wireless transmission-enabled systems. Massachusetts academic medical centers concentrate biocompatibility engineering talent for next-generation interstitial fluid sensor development.
Germany
Statutory health insurance funds expanded continuous glucose monitor reimbursement eligibility, accelerating patient-directed procurement decisions. EMA MDR conformity assessments mandate post-market clinical follow-up studies that extend evidence generation timelines for electrochemical sensor manufacturers. North Rhine-Westphalia hosts vertically integrated polymer chemistry clusters supplying glucose oxidase electrode substrates.
Japan
Pharmacy channel density and aging demographics expand flash glucose monitoring adoption among Type 2 diabetes populations. PMDA enforces localized accuracy validation that filters market access for wireless transmission-enabled devices, rewarding early regulatory investment. Kanto region clinic networks favor factory-calibrated optical sensors for patient education and treatment initiation protocols.
China
Home care patient-oriented systems gain traction as revised NMPA innovative medical device channels accelerate review timelines. The country's national pharmaceutical regulator prioritizes cloud-native data architectures for real-time glycemic visibility platforms. Yangtze River Delta manufacturing hubs scale optical sensing component production for domestic and export markets.
India
Cost sensitivity and pharmacy channel density sustain self-monitoring blood glucose strip volumes among undiagnosed diabetes populations. CDSCO regulatory frameworks for medical devices filter import-dependent supply chains for continuous monitor penetration. Maharashtra and Gujarat concentrate contract manufacturing capacity for enzyme electrode strip production serving emerging market demand.
Global Blood Glucose Monitoring Systems Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered reimbursement and direct-to-consumer vectors. The vendor base stratifies between vertically integrated manufacturers with captive clinical affairs infrastructure and sensor specialists dependent on third-party distribution. Three archetypes dominate: scale-driven platform players, precision-focused component suppliers, and wellness-oriented consumer entrants. Dominant competitive moves include backward integration into polymer chemistry supply chains and strategic partnerships with cloud analytics providers.
Among US-based platform players, Abbott Laboratories and Dexcom Inc. exemplify the scale-driven archetype through vertically integrated sensor manufacturing and real-time data architectures. Medtronic plc anchors the closed-loop integration tier, representing therapeutic footprint extension beyond standalone monitoring into automated insulin delivery systems.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Dexcom Inc. |
| Medtronic plc |
| F. Hoffmann-La Roche Ltd |
| LifeScan Inc. |
| Senseonics Holdings |
| Johnson & Johnson |
| Novo Nordisk A/S |
| Sanofi |
| Others |
Supply & Pricing Matrix
Yangtze River Delta port congestion on semiconductor-grade polymer shipments feeds directly into sensor substrate cost volatility, compressing margins for electrochemical manufacturers while amplifying price spreads between subscription-based continuous monitors and economy strip-based alternatives across German and United States procurement channels.
Pricing Analysis
Cost-plus contracts with glucose oxidase enzyme suppliers index to platinum spot markets, creating input price pass-through mechanisms that shield vertically integrated manufacturers from margin erosion. Pricing stratifies across premium continuous monitoring subscriptions, standard flash glucose systems, and economy self-monitoring strips, with FDA 510(k) certification tier driving the widest spreads. Cost compression in the strip segment intensifies as Indian contract manufacturers scale enzyme electrode production for emerging market volume. Pharmacy channel buyers in India and China exhibit highest price sensitivity, while United States home care patients under durable medical equipment benefits show lowest elasticity.
Supply Chain Analysis
Export controls on precision photonics equipment from Germany and Japan limit optical sensor manufacturing capacity expansion in China, constraining flash glucose monitor supply growth despite NMPA accelerated review timelines. Manufacturing concentrates in Germany for polymer chemistry substrates, Japan for glucose oxidase enzyme refinement, and China for optical component assembly. Raw material dependencies center on platinum catalysts, specialty polymer membranes, and near-infrared photonic chips. Single-source vulnerability runs through Japanese enzyme suppliers for electrochemical sensor production. Distribution runs through pharmacy networks in emerging markets and direct-to-consumer subscription logistics in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous glucose monitoring penetration among Type 2 diabetes populations remains below fifteen percent across major reimbursement markets, positioning the sector for multi-year expansion as eligibility criteria broaden and optical sensing costs decline.
For Market Incumbents: Harden regulatory moats through simultaneous FDA 510(k) and EMA MDR submission strategies that exploit smaller competitors' clinical affairs capacity constraints. Deepen backward integration into polymer chemistry supply chains to offset platinum and glucose oxidase input volatility. Flash glucose monitoring substitution threatens traditional continuous monitor volume; counter through closed-loop insulin delivery ecosystem lock-in. For New Entrants and Emerging Players: Pursue sports performance and nutritional monitoring white space in United States direct-to-consumer channels where reimbursement gatekeeper friction disappears. China's NMPA innovative medical device channel offers fastest regulatory path for cloud-native optical systems. Target biometric platform partnerships as primary go-to-market angle, embedding glucose data streams within fitness and nutrition app ecosystems rather than standalone device sales. For Investors and Strategic Acquirers: Cloud-native analytics specialists with captive sensor hardware capabilities represent the most defensible acquisition archetype as data platform control eclipses manufacturing scale in competitive positioning. Long-term viability hinges on unbundled data ownership models that permit third-party API integration. Watch for reimbursement parity legislation between continuous and flash monitoring modalities as the critical inflection signal for volume acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Streamlined premarket pathways compress time-to-revenue for wireless transmission-enabled systems. |
| CE Marking Pathway Investment | EMA MDR conformity assessments demand post-market surveillance infrastructure that filters smaller competitors. |
| Hospital System Partnership | Diabetes clinic integration secures therapeutic workflow embedding and reduces patient acquisition costs. |
| Software Companion Development | Real-time analytics platforms determine competitive positioning before sensor specifications reach procurement. |
| Reimbursement Strategy Execution | Statutory health insurance fund eligibility expansion in Germany and United States unlocks patient-directed volume. |
Research Methodology
Cross-validation between primary interviews with continuous glucose monitor product managers, hospital biomedical engineers, GPO contracts managers, and pharmacy procurement leads and secondary validation through FDA 510(k) filings, EMA MDR submissions, CMS Medicare reimbursement databases, and hospital procurement records anchors the qualitative findings. Bottom-up sensor shipment triangulation against top-down reimbursement eligibility population estimates ensures volume coherence.
Calibration against historical continuous monitor adoption curves in Germany and the United States shapes the analytical framework across the analysis window. Segmentation dimensions modeled include product type tier, technology modality, application context, and end-user channel. CAGRs derive from patient population growth, reimbursement expansion trajectories, and sensor cost decline curves. Forecast inputs incorporate PMDA localized accuracy validation timelines and NMPA innovative device channel throughput rates.
Sensitivities concentrate around platinum price volatility, enzyme electrode supply disruptions, and reimbursement parity policy shifts. Forecasts reflect assumptions on regulatory clearance cadence and patient self-management protocol adoption. Material shifts in FDA 510(k) pathway stringency or EMA MDR post-market surveillance requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Diabetic Pen Cap Market
Diabetes Care
Asia Pacific Diabetes Pen Market
Diabetes Care
Diabetes Care Devices and Drugs Market
Diabetes Care
Latin America Oral Anti-Diabetic Drug Market
Diabetes Care
Europe Insulin Infusion Pumps Market
Diabetes Care
Europe Diabetes Care Devices Market
Diabetes Care
Combination Anti-Diabetes Drugs Market
Diabetes Care
Philippines Diabetes Care Devices Market
Diabetes Care
China Self-Monitoring Blood Glucose Devices Market
Diabetes Care
South Africa Continuous Glucose Monitoring Market
Diabetes Care
Latin America Diabetes Care Devices Market
Diabetes Care
Global Diabetic Foot Ulcer Treatment Market
Diabetes Care
Italy Continuous Glucose Monitoring Devices Market
Diabetes Care
South Africa Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Type 2 Diabetes Mellitus Treatment Market
Diabetes Care
Internet of Things for Diabetes Market