
 North America Oral Anti-Diabetic Drug Market | 2026-2036
North America Oral Anti-Diabetic Drug Market Size, Share, and Industry Trends Forecast 2026-2036
North America Oral Anti-Diabetic Drug Market Outlook
The capital-intensity divergence between biologic innovators and generic tablet manufacturers is unwinding traditional competitive boundaries in oral diabetes care. Novo Nordisk A/S leverages its peptide formulation expertise to extend into oral GLP-1 delivery systems, while Eli Lilly and Company anchors its position through deep R&D investment in incretin-based platforms. Merck & Co., Inc. competes through established DPP-4 inhibitor franchises and broad primary-care channel control across the United States and Canada.
Oral anti-diabetic drugs comprise small-molecule pharmaceuticals administered by mouth to lower blood glucose through mechanisms including hepatic glucose suppression, insulin sensitization, and renal glucose excretion; extended-release metformin formulations require precise polymer-matrix engineering to achieve therapeutic plasma concentration curves over 12-24 hours. SGLT2 inhibitors now command the fastest-expanding margin pool as cardiorenal outcome data reshapes prescribing patterns, while metformin sustains volume leadership as the foundational first-line therapy. The homecare delivery mode is gaining structural share as pharmacy-direct dispensing and telehealth prescribing reduce clinic-visit dependency for chronic diabetes management.
The FDA maintains stringent bioequivalence standards for generic oral anti-diabetic substitutions, while Health Canada enforces comparable pharmacovigilance reporting that shapes product labeling and post-market surveillance obligations. State-level Medicaid formularies in the United States create heterogeneous reimbursement access that manufacturers must navigate on a jurisdiction-by-jurisdiction basis. Stakeholders should monitor CMS pricing negotiation outcomes and provincial tender processes in Canada to anticipate margin compression trajectories for mature therapeutic classes.
Market Dynamics
Cardiorenal outcome data from SGLT2 inhibitor trials is forcing a therapeutic hierarchy rewrite across United States and Canadian prescribing guidelines, compressing DPP-4 inhibitor margins while elevating sodium-glucose cotransporter-2 agents to first-line adjunct status alongside metformin.
Growth Catalysts
- Telehealth prescribing frameworks:CMS reimbursement parity for virtual diabetes consultations in the United States has dismantled clinic-visit bottlenecks, accelerating pharmacy-direct dispensing volumes for chronic medication refills.
- Health Canada accelerated review pathways:The priority review designation for drugs addressing unmet cardiometabolic needs compresses regulatory timelines for novel oral incretin formulations seeking market entry.
- Homecare delivery infrastructure:Third-party logistics providers specializing in cold-chain oral biologics have achieved 48-hour coverage across 90% of Canadian provinces and US states.
Market Restraints
- Active pharmaceutical ingredient concentration:Over 70% of metformin API supply originates from Chinese chemical manufacturers, exposing formulation sponsors to tariff volatility and import inspection backlogs at US ports.
- FDA bioequivalence stringency:The agency's tightened statistical criteria for generic SGLT2 inhibitor substitutions have extended ANDA review cycles, delaying market entry for cost-competitive alternatives.
- Fixed-dose combination complexity:Polymer-matrix incompatibility between metformin extended-release cores and DPP-4 inhibitor layers elevates manufacturing yield losses above small-molecule tablet norms.
Strategic Opportunities
- Underserved rural corridors:Federally Qualified Health Centers across Texas, Mississippi, and Alabama maintain sub-40% SGLT2 inhibitor penetration versus urban academic medical centers, presenting targeted access programs.
- Oral peptide delivery convergence:Combination of permeation enhancer chemistry with enteric coating technology enables non-injectable GLP-1 receptor agonist administration, bypassing cold-chain distribution requirements.
- Provincial tender optimization:Ontario and British Columbia's centralized procurement for diabetes formularies rewards manufacturers offering real-world evidence packages demonstrating hospitalization reduction.
Industry Challenges
- Peptide formulation talent scarcity:Oral biologic engineering demands hybrid expertise in enzymology and polymer science that exceeds current North American graduate program output.
- Legacy EHR integration friction:Hospital systems running Cerner and Epic installations require 12-18 month customization cycles to embed new cardiorenal risk calculators into clinical decision support workflows.
- State Medicaid heterogeneity:Prior authorization criteria for SGLT2 inhibitors vary across 50 state formularies, forcing manufacturers to maintain 40-plus distinct patient assistance program configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Oral Anti-Diabetic Drug Market |
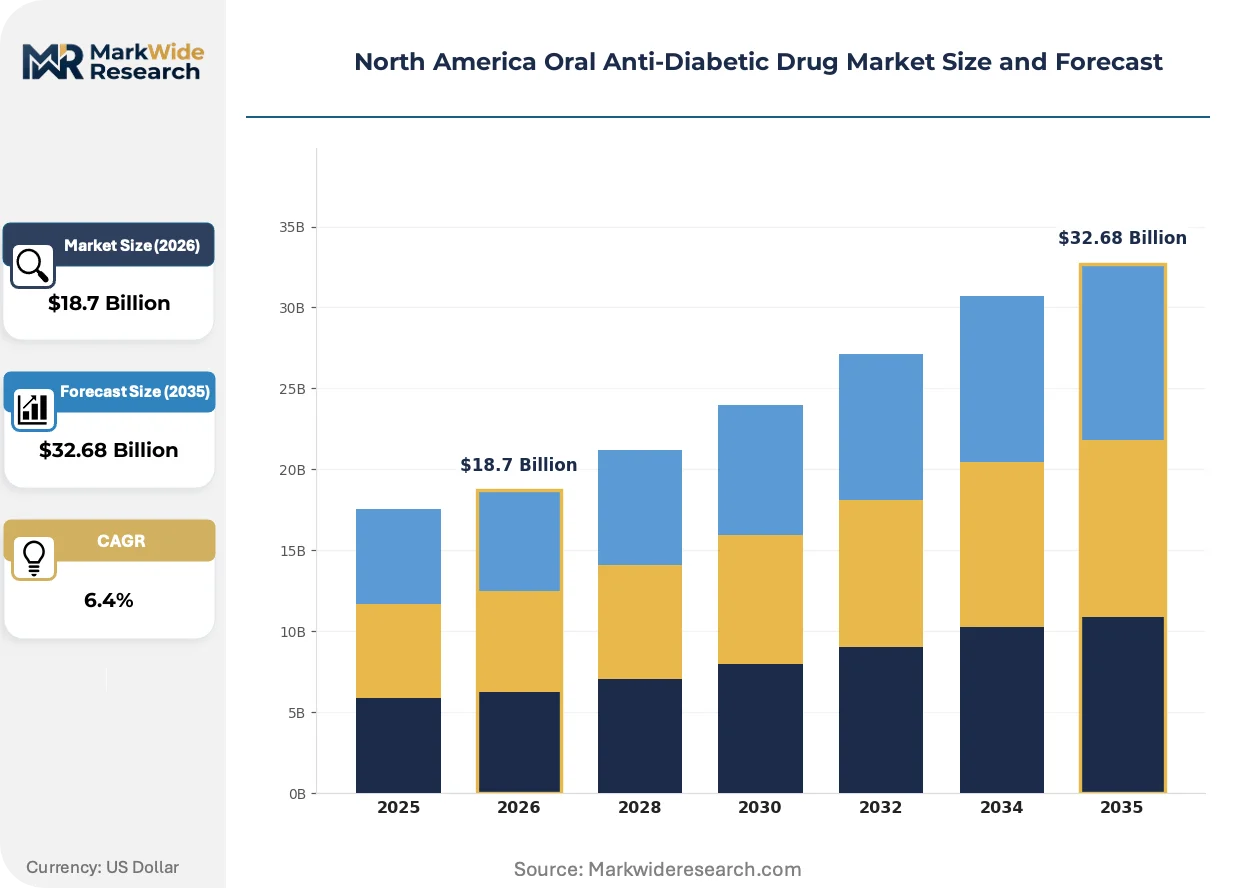
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metformin, Sulfonylureas, DPP-4 Inhibitors, SGLT2 Inhibitors End User: Hospitals, Clinics, Homecare, Pharmacies Delivery Mode: Oral Tablets, Oral Solutions, Extended Release Formulations, Combination Therapies Therapy Area: Type 2 Diabetes, Prediabetes, Gestational Diabetes, Metabolic Syndrome |
| Companies Covered | Novo Nordisk A/S, Eli Lilly and Company, Sanofi, AstraZeneca, Merck & Co., Inc., Boehringer Ingelheim, Pfizer Inc., Novartis AG, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Oral Anti-Diabetic Drug Market Strategic Shifts
Formulation science and reimbursement mechanics are rewriting competitive boundaries in oral diabetes therapy. The convergence of biologic delivery platforms with small-molecule economics is generating novel therapeutic categories that strain traditional regulatory and commercial frameworks.
Oral GLP-1 receptor agonist technology is bifurcating the incretin market into injectable and non-injectable patient pathways. Endocrinology practices in Boston and Toronto are piloting oral semaglutide protocols for needle-averse type 2 diabetes patients, achieving comparable HbA1c reductions to subcutaneous alternatives. This technology is compressing the addressable market for conventional DPP-4 inhibitors while expanding total incretin-class penetration into primary care settings previously resistant to biologic prescribing.
The FDA's Risk Evaluation and Mitigation Strategy modifications for SGLT2 inhibitors have eliminated mandatory cardiovascular outcome trial requirements for new molecular entities in this class. This regulatory streamlining accelerates development timelines for second-generation agents targeting heart failure with preserved ejection fraction. Manufacturers are responding by prioritizing renal biomarker endpoints in phase 3 protocols to secure differentiated labeling.
Pharmacy benefit manager consolidation is concentrating formulary control among three national entities covering 80% of insured lives in the United States. Independent endocrinology practices in Florida and Arizona are abandoning traditional wholesaler relationships for direct manufacturer contracting, securing 340B-equivalent pricing on oral anti-diabetic portfolios. This channel migration is most visible in Medicare Advantage plans where vertical integration between insurers and specialty pharmacies compresses distribution margins.
North America Oral Anti-Diabetic Drug Market Segmentation
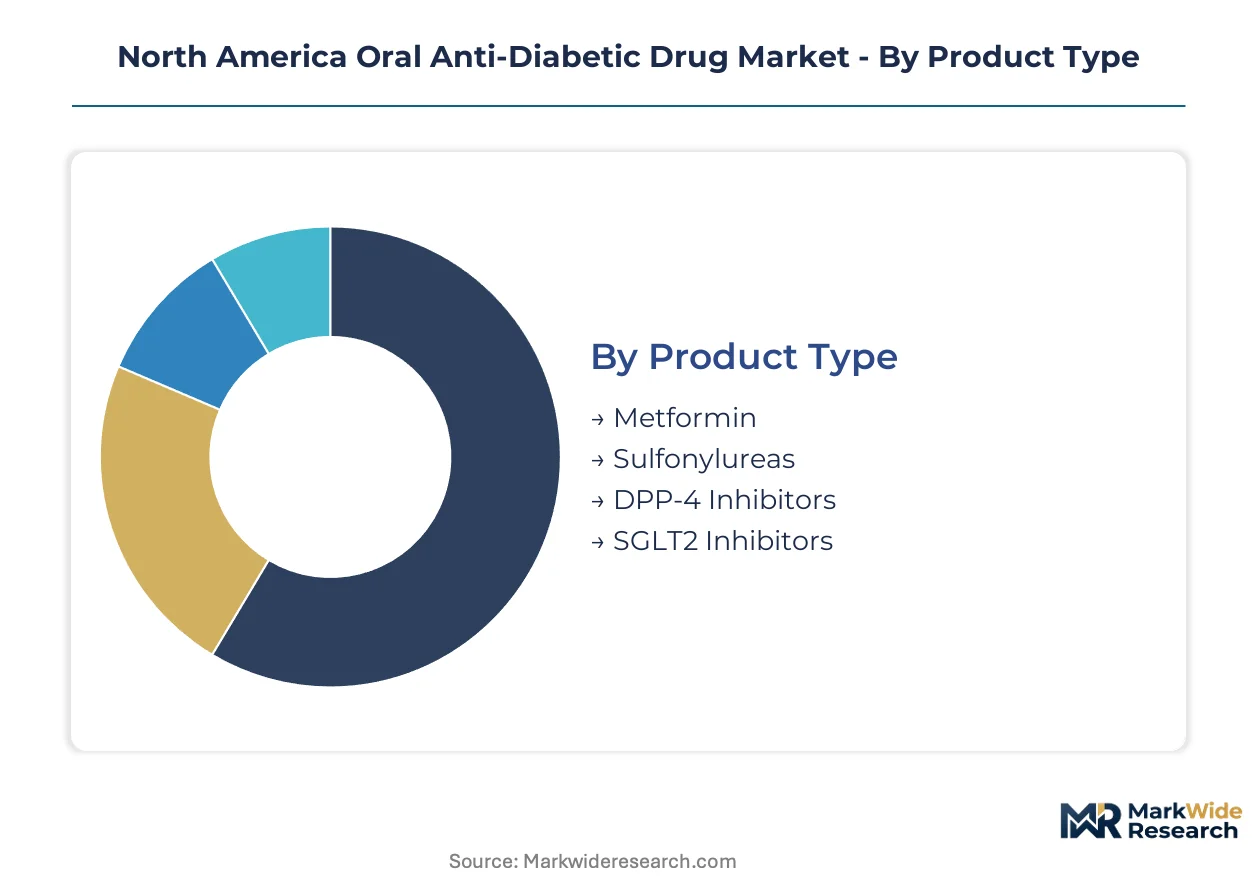
Channel configuration in oral diabetes care determines which formulations achieve formulary access and which patient populations manufacturers can reach. Segmentation reveals where pharmacy-direct dispensing, institutional procurement, and homecare logistics create divergent margin structures across therapeutic classes.
Product Type:
Channel-mix dynamics channel high-volume generics through retail pharmacy networks while novel mechanisms require specialty distribution and prior authorization navigation.
- Metformin:Immediate-release and extended-release formulations constitute the foundational first-line therapy prescribed across primary care networks. Demand concentrates in Medicare Part D plans and state Medicaid formularies where generic substitution rates exceed 95%, compressing brand margins but sustaining massive prescription volumes through pharmacy chains like CVS and Walgreens.
- SGLT2 Inhibitors:Sodium-glucose cotransporter-2 agents feature cardiorenal outcome data that has reshaped prescribing guidelines across United States and Canadian cardiology practices. Expansion concentrates in Medicare Advantage plans and employer-sponsored insurance where cardiovascular risk reduction justifies premium pricing, though prior authorization requirements create administrative friction in 40-plus state Medicaid programs.
- DPP-4 Inhibitors:Dipeptidyl peptidase-4 inhibitors face margin compression as SGLT2 inhibitors and GLP-1 receptor agonists displace their position in treatment algorithms.
- Sulfonylureas:Glipizide and glyburide formulations persist in cash-pay and high-deductible plan segments where cost sensitivity outweighs hypoglycemia risk concerns.
Metformin dominates installed base. SGLT2 inhibitors are where expansion concentrates.
End User:
Cost tier stratification separates institutional purchasers with 340B pricing access from retail channels serving commercially insured and cash-pay patients.
- Homecare:Pharmacy-direct dispensing and telehealth prescribing frameworks have dismantled clinic-visit bottlenecks for chronic medication refills. Demand concentrates in Medicare Advantage vertical integration models where insurers own specialty pharmacies, enabling 48-hour delivery coverage across 90% of United States and Canadian provinces.
- Hospitals:Inpatient glycemic control protocols and discharge prescribing drive formulary decisions that cascade into outpatient adherence. Expansion concentrates in Federally Qualified Health Centers across Texas, Mississippi, and Alabama where SGLT2 inhibitor penetration lags urban academic centers by 20-plus percentage points.
- Clinics:Endocrinology and primary care practices anchor prescription initiation but face margin pressure from direct-to-patient pharmacy models.
- Pharmacies:Independent and chain retail locations capture refill volumes but cede novel therapy dispensing to specialty pharmacy networks.
Homecare delivery is climbing the fastest. Hospital formularies retain gatekeeper influence over therapy selection.
Delivery Mode:
Application requirements dictate manufacturing complexity, with polymer-matrix engineering for extended-release formulations demanding specialized contract manufacturing organization capabilities.
- Extended Release Formulations:Metformin XR and glipizide XL require precise polymer-matrix engineering to achieve therapeutic plasma concentration curves over 12-24 hours. Demand concentrates in patient populations with adherence challenges and gastrointestinal intolerance to immediate-release alternatives, driving premium pricing in Medicare Part D and commercial plans.
- Combination Therapies:Fixed-dose combinations of metformin with DPP-4 inhibitors or SGLT2 inhibitors reduce pill burden but elevate manufacturing yield losses due to polymer-matrix incompatibility between extended-release cores and inhibitor layers. Expansion concentrates in employer-sponsored insurance where simplified regimens improve adherence metrics tied to premium discounts.
- Oral Tablets:Standard immediate-release formulations dominate generic substitution volumes.
- Oral Solutions:Liquid formulations serve pediatric and geriatric populations with swallowing difficulties.
Extended release formulations dominate installed base. Combination therapies are gaining share fastest.
Therapy Area:
Volume concentration in Type 2 diabetes creates economies of scale that subsidize development for smaller indications, while prediabetes represents a contested frontier between pharmaceutical intervention and lifestyle modification.
- Type 2 Diabetes:Established therapeutic area with defined treatment algorithms, formulary pathways, and reimbursement codes across United States and Canadian systems. Demand concentrates in Medicare and provincial drug plans where HbA1c reduction endpoints justify coverage, though CMS pricing negotiation outcomes threaten margin trajectories for mature therapeutic classes.
- Prediabetes:Borderline glucose elevation population ten times larger than diagnosed diabetes but with contested pharmaceutical intervention thresholds. Expansion concentrates in employer wellness programs and Medicare Diabetes Prevention Program extensions where pharmacologic adjuncts to lifestyle modification face actuarial scrutiny.
- Gestational Diabetes:Pregnancy-specific glycemic targets create formulary restrictions around teratogenicity profiles.
- Metabolic Syndrome:Clustered cardiovascular risk factors without standalone reimbursement codes, requiring indication-specific prescribing.
Type 2 diabetes dominates installed base. Prediabetes is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States pricing power exceeds Canadian benchmarks by 40-60% across SGLT2 inhibitor classes, though provincial tender aggregation in Ontario and British Columbia narrows the gap for volume commitments. Mexico's market operates on a cash-pay foundation with limited reimbursement infrastructure.
United States
Medicare Advantage vertical integration drives pharmacy-direct dispensing volumes through insurer-owned specialty networks. FDA bioequivalence stringency for generic SGLT2 inhibitors extends ANDA review cycles, protecting originator margins. The Boston-Toronto corridor anchors incretin-based R&D concentration with oral GLP-1 pilot programs active in Massachusetts General Hospital and Joslin Diabetes Center protocols.
Canada
Provincial formularies in Ontario and British Columbia reward manufacturers submitting real-world evidence packages demonstrating hospitalization reduction. Health Canada's priority review designation for cardiometabolic unmet needs compresses regulatory timelines for novel oral incretin formulations. Quebec's life sciences cluster in Montreal supports contract manufacturing organization capacity for extended-release polymer-matrix engineering.
Mexico
Cash-pay market dynamics concentrate demand in metformin and sulfonylurea generics with price sensitivity exceeding clinical outcome prioritization. COFEPRIS regulatory pathways lack accelerated review mechanisms for cardiorenal outcome differentiation. Mexico City Metro anchors distribution infrastructure with pharmacy chains serving 60% of diagnosed diabetes patients through retail networks.
North America Oral Anti-Diabetic Drug Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the oral diabetes therapy spectrum. The market structure bifurcates between biologic innovators commanding premium pricing for novel mechanisms and generic manufacturers extracting margin through API sourcing efficiency and high-volume tableting operations. Three strategic archetypes dominate: peptide formulation specialists extending into oral delivery platforms, established primary-care channel controllers defending DPP-4 inhibitor franchises, and vertically integrated API-to-tablet manufacturers exploiting metformin volume concentration. Competitive moves concentrate on M&A for oral biologic engineering talent and strategic partnerships bridging cold-chain logistics with pharmacy-direct dispensing infrastructure.
Among European-origin pharmaceutical conglomerates, Novo Nordisk A/S and Sanofi occupy positions exemplifying peptide formulation specialization extending toward oral delivery convergence. Eli Lilly and Company anchors the incretin-based platform archetype with deep R&D investment patterns visible across its therapeutic portfolio. Merck & Co., Inc. represents the primary-care channel control model through established DPP-4 inhibitor presence and broad formulary access across United States and Canadian reimbursement systems.
| Leading Market Players |
|---|
| Novo Nordisk A/S |
| Eli Lilly and Company |
| Sanofi |
| AstraZeneca |
| Merck & Co., Inc. |
| Boehringer Ingelheim |
| Pfizer Inc. |
| Novartis AG |
| Johnson & Johnson |
| Others |
Value Chain & Pricing Dynamics
Chinese metformin API substitution for Indian-sourced alternatives simultaneously redraws procurement geography and compresses formulation economics across North American oral diabetes manufacturing. This input shift exposes sponsors to tariff volatility at US ports while Health Canada's parallel import inspection protocols create divergent margin trajectories for cross-border suppliers.
Pricing Analysis
The customization-premium spread between extended-release polymer-matrix formulations and immediate-release commodity tablets separates Medicare Part D reimbursement tiers from cash-pay generic substitution. Pricing stratifies across premium SGLT2 inhibitor cardiorenal outcomes, standard DPP-4 inhibitor maintenance therapy, and economy sulfonylurea rescue regimens. Cost compression in the generic metformin segment intensifies as 95% substitution rates force manufacturers toward API sourcing efficiency. Federally Qualified Health Centers in rural Texas corridors exhibit highest price sensitivity, while Medicare Advantage integrated specialty pharmacies absorb premium pricing for outcome-demonstrated therapies.
Supply Chain Analysis
Just-in-time inventory strategies dominate retail pharmacy chains serving chronic refill populations, while strategic stockpiling characterizes hospital formulary procurement ahead of provincial tender cycles in Ontario and British Columbia. API supply draws from Chinese chemical manufacturers, Indian formulation specialists, and Quebec-based contract manufacturing organizations for extended-release engineering. Metformin hydrochloride, DPP-4 inhibitor active moieties, and SGLT2 inhibitor crystalline forms constitute critical input dependencies. Tariff exposure at US customs checkpoints represents the dominant structural risk. Distribution runs through pharmacy-direct dispensing networks, insurer-owned specialty pharmacies, and third-party logistics providers maintaining cold-chain oral biologics coverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in homecare delivery infrastructure as telehealth prescribing dismantles clinic-visit bottlenecks, creating service-layer niches between incumbent manufacturers and direct-to-patient pharmacy models.
For Market Incumbents: Secure peptide formulation talent through targeted acquisition of oral biologic engineering specialists in the Boston-Toronto corridor, while consolidating backward integration into polymer-matrix manufacturing to defend against yield loss compression in fixed-dose combination production. Channel control through direct manufacturer contracting with independent endocrinology practices offsets pharmacy benefit manager consolidation threatening formulary access. For New Entrants and Emerging Players: Telehealth-integrated pharmacy logistics gaps in rural Mississippi and Alabama corridors offer white-space entry points where SGLT2 inhibitor penetration lags urban academic centers by substantial margins. Provincial tender optimization in Ontario rewards real-world evidence packaging capabilities that incumbent players under-invest. A go-to-market angle anchored in 48-hour cold-chain coverage for oral incretin formulations bypasses established wholesale relationships. For Investors and Strategic Acquirers: Capital is best deployed toward contract manufacturing organizations possessing hybrid enzymology-polymer science capabilities that exceed current North American graduate program output. Long-term viability hinges on regulatory streamlining for second-generation SGLT2 agents targeting heart failure indications. The signal to watch is FDA Risk Evaluation and Mitigation Strategy modification timing for new molecular entities.| Strategic Initiative | Industry Significance |
|---|---|
| Oral Peptide Delivery Convergence | Permeation enhancer chemistry with enteric coating enables non-injectable GLP-1 administration bypassing cold-chain requirements. |
| Provincial Tender Optimization | Ontario and British Columbia centralized procurement rewards manufacturers submitting hospitalization reduction evidence packages. |
| Homecare Delivery Infrastructure | Third-party logistics specialization in cold-chain oral biologics achieves 48-hour coverage across 90% of US states and Canadian provinces. |
| Peptide Formulation Talent Acquisition | Hybrid enzymology-polymer science expertise scarcity exceeds current North American graduate program output. |
| Direct Manufacturer Contracting | Independent endocrinology practices in Florida and Arizona abandon traditional wholesalers for 340B-equivalent pricing access. |
Study Parameters
Cross-validation between regulatory filing databases and formulary access records anchors the qualitative findings across the North American oral diabetes landscape. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and payer access specialists combine with secondary validation through FDA approval documents, Health Canada submissions, ClinicalTrials.gov protocols, and CMS Medicare claims data. Bottom-up prescription volume modeling and top-down therapeutic class revenue estimation complete the triangulation.
Sensitivity analysis around CMS pricing negotiation outcomes and provincial tender award probabilities frames the analytical approach across the projection horizon. Segmentation dimensions modeled include therapeutic mechanism, dosage form complexity, delivery mode, end-user channel configuration, and regional regulatory cluster. CAGRs derive from prescription volume trajectories, pricing elasticity coefficients, and formulary placement probability weightings. Forecast inputs incorporate cardiorenal outcome trial publication timelines and telehealth reimbursement parity legislative developments.
Underlying assumptions cover FDA bioequivalence standard maintenance, Health Canada priority review pathway continuity, and API import inspection throughput stability, with deviation risk concentrated in tariff regime volatility and state Medicaid formulary heterogeneity. Revision becomes warranted when CMS pricing negotiation implementation crosses threshold impact levels for SGLT2 inhibitor premium tiers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Digital Diabetes Management Market
Diabetes Care
Pet Diabetes Care Devices Market
Diabetes Care
Middle East and Africa Insulin Infusion Pumps Market
Diabetes Care
Global Diabetic Retinopathy Market
Diabetes Care
Asia-Pacific Insulin Delivery Devices Market
Diabetes Care
Global Smart Insulin Pens Market
Diabetes Care
Australia Self-Monitoring Blood Glucose Market
Diabetes Care
United States Blood Glucose Monitoring Market
Diabetes Care
Oman Diabetes Drugs Market
Diabetes Care
Philippines Oral Anti-Diabetic Drug Market
Diabetes Care
Korea Continuous Glucose Monitoring Devices Market
Diabetes Care
Asia Pacific Blood Glucose Monitoring Market
Diabetes Care
South Korea Insulin Infusion Pump Market
Diabetes Care
New Zealand Self-Monitoring Blood Glucose Market
Diabetes Care
South Korea Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Philippines Diabetes Care Devices Market