
 BRIC Diabetes Care Devices Market | 2026-2036
BRIC Diabetes Care Devices Market Size, Share, and Industry Trends Forecast 2026-2036
BRIC Diabetes Care Devices Market Analysis
Leasing-based equipment financing is narrowing the competitive field for mid-tier hospitals seeking continuous glucose monitor deployments. Medtronic plc leverages its manufacturing scale to supply bundled monitoring systems across Brazilian hospital networks. Abbott Laboratories anchors its position through deep channel control in Indian diagnostic chains. Dexcom, Inc. specializes in wearable sensor platforms that compete directly with traditional blood glucose meter suppliers.
BRIC Diabetes Care Devices encompass instruments for glucose measurement, insulin delivery, and metabolic monitoring, typically operating with electrochemical sensor strips or interstitial fluid sampling at measurement intervals under fifteen minutes for real-time glycemic management. Continuous Glucose Monitors command premium positioning due to sensor miniaturization and data connectivity requirements, while Testing Strips retain volume dominance across price-sensitive clinic segments in Russia and China. Wearable Devices and Smart Sensors represent the fastest-expanding technology clusters, though Telemedicine integration lags in regions with fragmented broadband infrastructure.
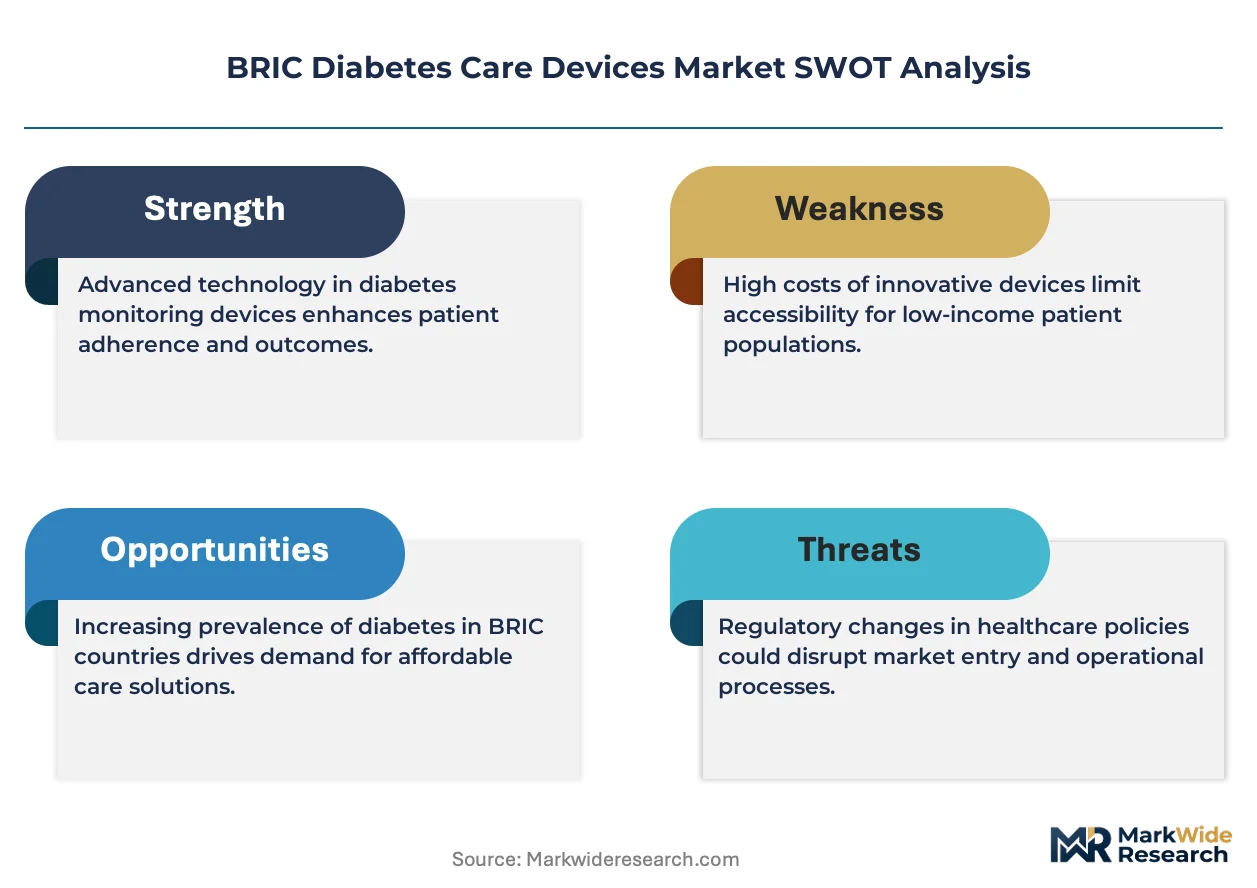
Brazil's ANVISA and India's CDSCO enforce divergent approval pathways for imported versus domestically manufactured glucose monitors, creating compliance complexity for multinational suppliers. Russia's national regulator mandates local clinical trial data for Class IIb device registration, extending market access timelines. China's NMPA accelerates review channels for innovative devices under its priority review framework. Stakeholders must weigh regulatory capital requirements against the margin profiles of subscription-based sensor replenishment models.
Market Dynamics
Hospital procurement departments across Brazil, Russia, India, and China are consolidating vendor relationships around connected glucose monitoring systems that bundle hardware with recurring sensor subscriptions, compressing supplier margins while locking in long-term replenishment revenue streams.
Growth Catalysts
- India's PLI scheme:Production-linked incentives for medical device manufacturing are accelerating domestic glucose monitor assembly capacity and reducing import dependency for hospital networks in Mumbai and Delhi.
- Continuous glucose monitoring adoption:Brazilian tertiary care centers are replacing episodic blood glucose testing with real-time interstitial fluid sensors that transmit data directly to electronic health records.
- Sensor miniaturization:Advances in electrochemical strip manufacturing are enabling wearable form factors that expand addressable patient populations beyond traditional Type 1 diabetes management.
Market Restraints
- Import tariff structures:Russia's customs framework imposes layered duties on finished glucose monitoring devices that inflate landed costs for multinational suppliers serving regional hospital chains.
- Platinum electrode volatility:Electrochemical sensor production depends on precious metal inputs subject to commodity price swings that compress manufacturing margins unpredictably.
- Clinical trial localization:ANVISA and CDSCO mandate jurisdiction-specific validation studies that extend registration timelines and duplicate development expenditures.
Strategic Opportunities
- Tier-2 Indian hospital expansion:Diagnostic chains in Pune, Hyderabad, and Chennai remain underpenetrated by continuous monitoring systems relative to saturated Mumbai-Delhi corridors.
- Telemedicine integration:Remote glucose data transmission aligns with China's internet hospital licensing framework and creates subscription revenue streams beyond device sales.
- Sensor-platform convergence:Wearable devices that combine glucose monitoring with blood pressure and pulse oximetry are capturing multi-parameter diagnostic budgets in Brazilian integrated health networks.
Industry Challenges
- Biocompatibility certification:Subcutaneous sensor materials must demonstrate 14-day irritation profiles under ISO 10993 standards that extend pre-market testing cycles.
- Interoperability fragmentation:Proprietary data protocols between competing glucose monitor ecosystems prevent seamless integration with hospital information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | BRIC Diabetes Care Devices Market |
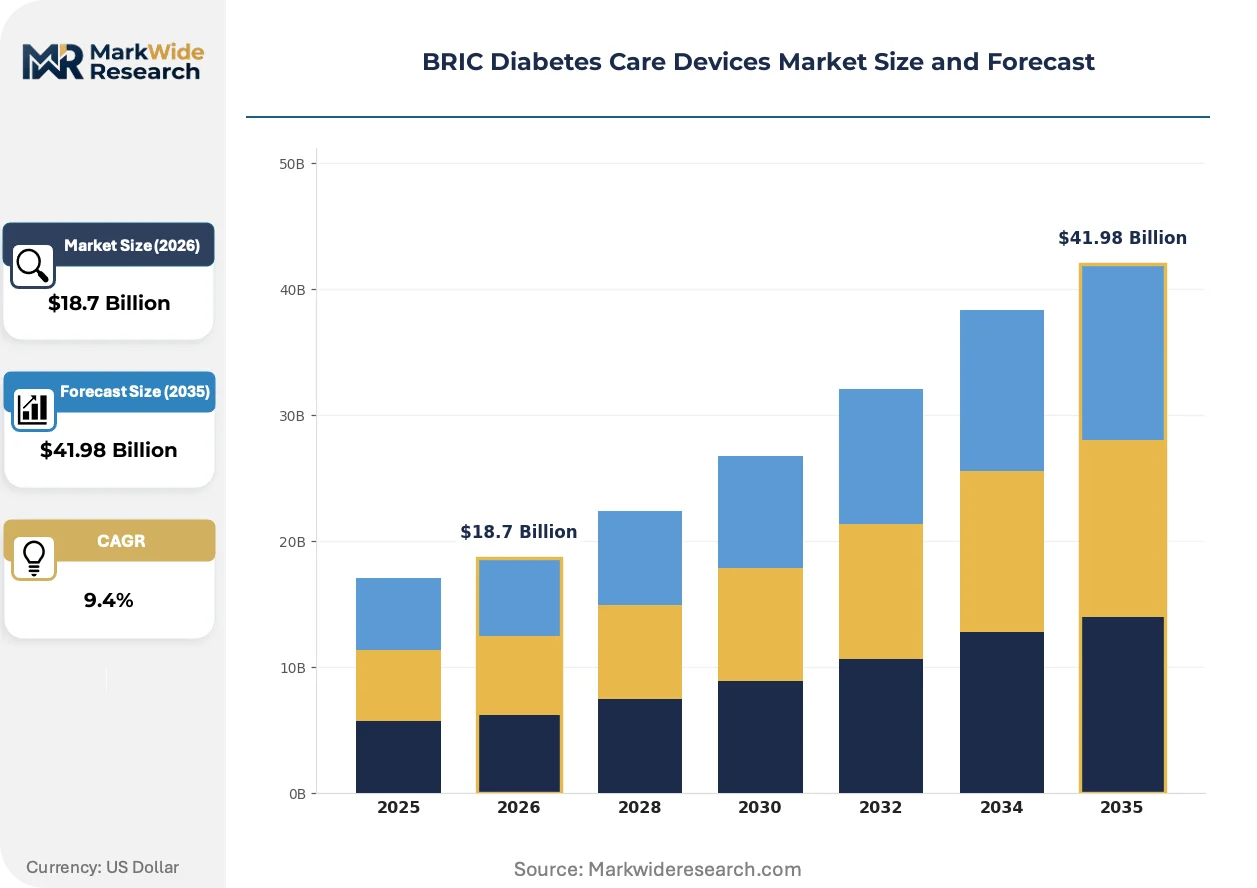
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin Pens, Blood Glucose Meters, Continuous Glucose Monitors, Testing Strips Technology: Wearable Devices, Smart Sensors, Telemedicine, Mobile Applications End User: Hospitals, Clinics, Homecare, Ambulatory Surgical Centers Application: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Diabetes Prevention |
| Companies Covered | Medtronic plc, Abbott Laboratories, F. Hoffmann-La Roche Ltd, Dexcom, Inc., LifeScan, Inc., B. Braun SE, Novo Nordisk A/S, Sanofi, Insulet Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
BRIC Diabetes Care Devices Market Emerging Trajectories
Connected diabetes care is pivoting from episodic measurement toward predictive glycemic management platforms that algorithmically anticipate hypoglycemic events before symptomatic onset.
Non-invasive optical glucose sensing is hybridizing spectroscopic techniques with machine learning calibration models. Research consortia in Shanghai and Bangalore are piloting Raman-based approaches that eliminate finger-prick blood draws entirely. Early hospital adopters in China's tier-1 cities are testing these platforms for pre-diabetic screening populations, though regulatory validation timelines remain extended.
CDSCO's 2023 risk-based classification amendment for software-as-medical-device is accelerating review pathways for AI-enabled glucose prediction algorithms. Domestic Indian manufacturers are leveraging this framework to register cloud-based analytics platforms that process continuous monitor data streams. Russian importers face parallel requirements from the national regulator for algorithm transparency documentation that extends registration preparation.
Hospital purchasing committees are unbundling device procurement from consumable supply agreements that historically locked facilities into single-vendor ecosystems. Brazilian public hospital networks now tender glucose test strips and continuous sensors through separate competitive processes. This fragmentation benefits specialized sensor suppliers in India's diagnostic chain segment while compressing bundled system margins for integrated device manufacturers.
BRIC Diabetes Care Devices Market Segmentation
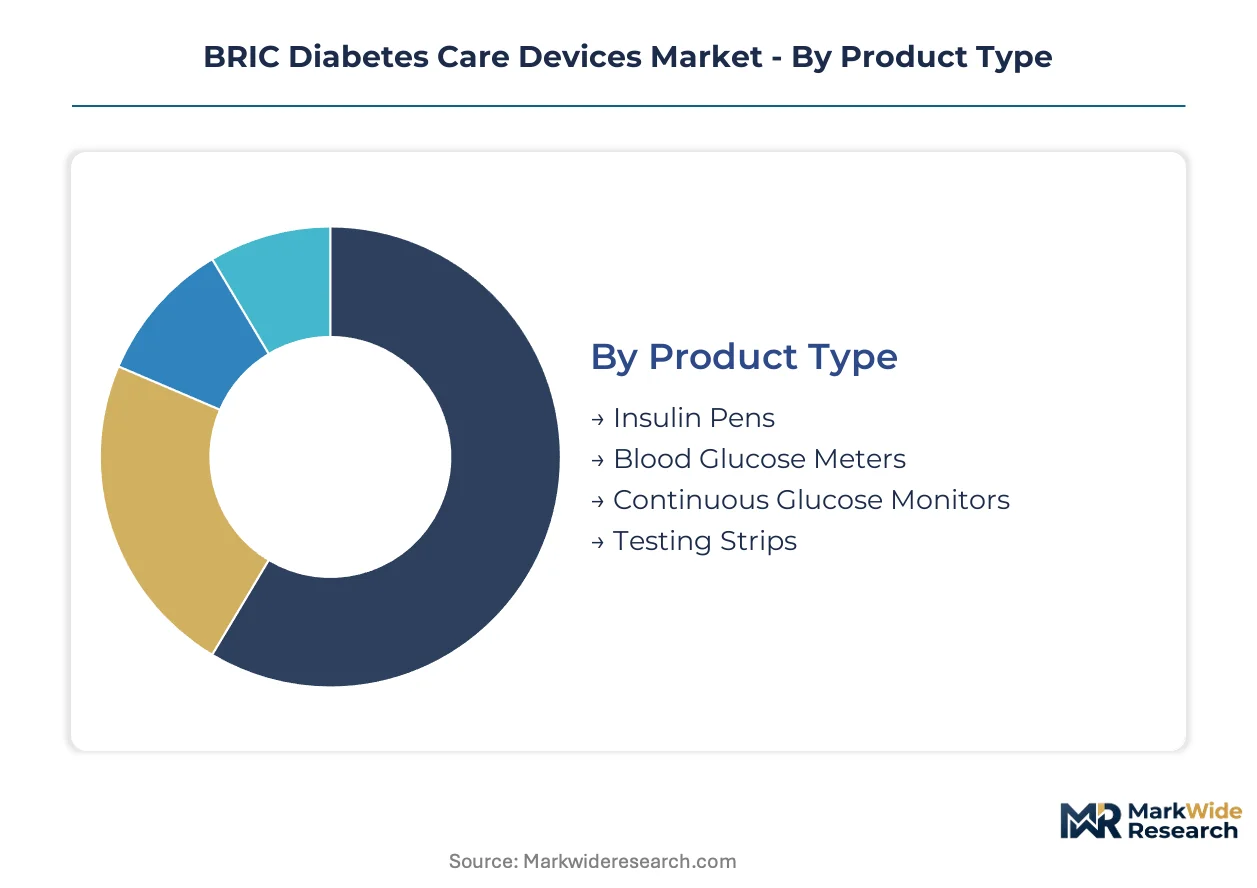
BRIC hospital procurement committees unbundle device purchases from consumable agreements, fragmenting historical single-vendor lock-ins. Segmentation reveals where sensor miniaturization commands premium positioning versus where electrochemical strips retain volume dominance across price-sensitive clinic networks.
Product Type:
Mature electrochemical platforms anchor hospital volume commitments while emerging sensor architectures capture expanding reimbursement codes.
- Continuous Glucose Monitors:Interstitial fluid sampling systems transmit real-time glycemic data to electronic health records at sub-fifteen-minute intervals. Brazilian tertiary care centers in São Paulo and Rio de Janeiro are replacing episodic testing with these platforms, though sensor subscription costs strain public hospital budgets.
- Testing Strips:Disposable electrochemical strips using precious metal electrodes dominate clinic throughput across Russian regional chains and Chinese county-level hospitals. Platinum price volatility compresses manufacturing margins unpredictably.
- Insulin Pens:Reusable and disposable injection devices with dose memory features.
- Blood Glucose Meters:Handheld episodic measurement units for home and clinical use.
Testing Strips handles the majority of throughput; Continuous Glucose Monitors is the fastest mover on share.
Technology:
Hardware-software convergence determines margin capture, with cloud-connected platforms extracting recurring revenue beyond initial device placement.
- Smart Sensors:Miniaturized electrochemical and optical transducers enable multi-day wear without calibration fingersticks. India's CDSCO accelerated review pathways under its 2023 software-as-medical-device framework, allowing domestic manufacturers to register cloud-based analytics processing continuous data streams.
- Telemedicine:Remote glucose data transmission aligns with China's internet hospital licensing framework. Fragmented broadband infrastructure in Russian rural oblasts and Indian tier-3 towns limits deployment reach.
- Wearable Devices:Body-worn form factors integrating glucose monitoring with cardiovascular parameters.
- Mobile Applications:Smartphone-based glucose logging and insulin dosing calculators.
Smart Sensors captures the premium tier; Telemedicine is expanding most quickly where infrastructure permits.
End User:
Site-of-care economics drive purchasing authority concentration, with hospital networks consolidating vendor relationships around bundled subscription models.
- Hospitals:Integrated health networks in Brazil and India centralize procurement for connected monitoring systems. Mumbai and Delhi metropolitan hospital chains are expanding purchasing fastest, while tier-2 diagnostic chains in Pune and Hyderabad remain underpenetrated.
- Homecare:Patient-managed glucose monitoring is shifting toward rechargeable wearable platforms with smartphone connectivity. Reimbursement fragmentation across BRIC jurisdictions creates pricing pressure on traditional meter suppliers.
- Clinics:Outpatient facilities relying on episodic testing with lower per-patient technology budgets.
- Ambulatory Surgical Centers:Pre-operative glycemic screening and perioperative monitoring sites.
Hospitals controls the procurement budget concentration; Homecare is gaining share fastest on patient preference shifts.
Application:
Disease progression stage determines monitoring intensity requirements, with pre-diabetic populations creating new addressable demand beyond traditional insulin-dependent management.
- Type 2 Diabetes:Non-insulin-dependent and insulin-requiring patients represent the largest addressable population across BRIC markets. Chinese tier-1 cities are piloting non-invasive optical sensing for pre-diabetic screening, though regulatory validation timelines remain extended.
- Type 1 Diabetes:Insulin-dependent patients requiring intensive glucose monitoring and pump integration. Continuous monitor adoption is highest in this segment due to hypoglycemia risk and reimbursement support.
- Gestational Diabetes:Pregnancy-related glucose dysregulation requiring temporary monitoring protocols.
- Diabetes Prevention:Lifestyle intervention programs targeting pre-diabetic populations with lower-intensity screening.
Type 2 Diabetes accounts for the patient volume base; Type 1 Diabetes shows the steepest technology penetration trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement departments in Brazil, Russia, India, and China concentrate purchasing authority for connected glucose monitoring systems, with tier-1 metropolitan networks driving volume commitments and tier-2 cities presenting expansion targets.
Brazil
Integrated health networks in São Paulo and Rio de Janeiro are replacing episodic blood glucose testing with real-time interstitial fluid sensors. ANVISA enforces divergent approval pathways for imported versus domestically manufactured glucose monitors, creating compliance complexity for multinational suppliers. Tertiary care centers in São Paulo anchor the fastest adoption of continuous monitoring platforms, though sensor subscription costs strain public hospital budgets.
Russia
Regional hospital chains face layered import duties on finished glucose monitoring devices that inflate landed costs for multinational suppliers. The national regulator mandates local clinical trial data for Class IIb device registration, extending market access timelines beyond those in competing BRIC jurisdictions. Moscow and St. Petersburg metropolitan clusters concentrate procurement for connected systems, while rural oblasts remain limited by fragmented broadband infrastructure for telemedicine integration.
India
CDSCO's 2023 risk-based classification amendment for software-as-medical-device is accelerating review pathways for AI-enabled glucose prediction algorithms. The PLI scheme for medical device manufacturing is accelerating domestic glucose monitor assembly capacity and reducing import dependency for hospital networks in Mumbai and Delhi. Tier-2 diagnostic chains in Pune, Hyderabad, and Chennai remain underpenetrated by continuous monitoring systems relative to saturated Mumbai-Delhi corridors.
China
NMPA accelerates review channels for innovative devices under its priority review framework, compressing timelines for domestic manufacturers. Non-invasive optical glucose sensing research consortia in Shanghai are piloting Raman-based approaches that eliminate finger-prick blood draws entirely. Tier-1 cities including Beijing and Shanghai are testing these platforms for pre-diabetic screening populations, though regulatory validation timelines remain extended.
BRIC Diabetes Care Devices Market Vendor Landscape
Channel-controlling players compete with product-specialist players across procurement tiers, with hospital networks consolidating vendor relationships around bundled subscription models that lock in long-term sensor replenishment revenue. The competitive structure tilts toward scale-driven integrated manufacturers and focused sensor technology developers. Three archetypes dominate: multinational device manufacturers with manufacturing scale, diagnostic chain channel controllers, and wearable sensor platform specialists. Dominant competitive moves include strategic partnerships for regulatory localization and portfolio diversification into multi-parameter diagnostic devices.
Within the multinational device manufacturer tier, Medtronic plc and Abbott Laboratories exemplify scale-driven positions, while Dexcom, Inc. occupies a specialist role in wearable sensor platforms. These three companies represent the channel-control versus product-specialist tension, with Medtronic leveraging manufacturing scale to supply bundled monitoring systems, Abbott anchoring through deep channel control in Indian diagnostic chains, and Dexcom competing directly with traditional blood glucose meter suppliers through sensor miniaturization.
| Leading Market Players |
|---|
| Medtronic plc |
| Abbott Laboratories |
| F. Hoffmann-La Roche Ltd |
| Dexcom, Inc. |
| LifeScan, Inc. |
| B. Braun SE |
| Novo Nordisk A/S |
| Sanofi |
| Insulet Corporation |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese electrochemical sensor substrate manufacturing is compressing contract manufacturing margins while simultaneously enabling aggressive pricing postures for domestic glucose monitor assemblers serving BRIC hospital networks. This utilization dynamic feeds directly into procurement leverage for Indian and Brazilian hospital systems negotiating bundled subscription contracts.
Pricing Analysis
Cost-plus contracts with platinum electrode indexation dominate sensor replenishment agreements across Brazilian public hospital networks. Price differentiation hinges on ISO 10993 biocompatibility certification tier and volume scale commitments, with tier-1 metropolitan chains commanding standard-tier pricing while tier-2 diagnostic chains face premium markups for smaller batch orders. Pricing pressure stems from hospital procurement committees unbundling device and consumable tenders, fragmenting historical single-vendor lock-ins. Clinic networks in Russian regional oblasts exhibit highest price sensitivity due to constrained per-patient technology budgets, whereas Chinese tier-1 internet hospitals demonstrate lowest sensitivity where reimbursement codes cover connected monitoring subscriptions.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Indian PLI scheme beneficiaries are restructuring working capital flows for domestic glucose monitor assemblers in Mumbai and Delhi manufacturing clusters. Geographic supply concentration centers on China for electrochemical sensor substrates, India for device assembly under production-linked incentives, and Germany for precision molding equipment. Raw material dependencies include platinum-group metals for electrode fabrication, medical-grade polymers for biocompatible housings, and specialized adhesives for subcutaneous sensor attachment. Single-source vulnerability around platinum electrode suppliers exposes manufacturers to commodity price volatility. Distribution runs through diagnostic chain central warehouses in tier-1 cities, with direct-to-hospital fulfillment gaining share for continuous monitor deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where sensor subscription revenue layers expand faster than hardware placement economics, particularly for cloud-connected analytics platforms processing continuous glucose data streams.
For Market Incumbents: Build regulatory data moats through jurisdiction-specific clinical trial repositories that emerging entrants cannot replicate quickly. Consolidate backward integration into platinum electrode supply through captive offtake agreements with precious metal refiners, insulating margin compression from commodity volatility. Defend against diagnostic chain channel fragmentation by embedding biomedical engineers within hospital purchasing committees to influence technical specifications.
For New Entrants and Emerging Players: Establish a beachhead in India's tier-2 diagnostic chains where continuous monitoring penetration lags saturated Mumbai-Delhi corridors by substantial margins. Target gestational diabetes applications with temporary monitoring protocols that bypass entrenched insulin-dependent patient relationships held by incumbents. Pursue software-as-medical-device registration under CDSCO's accelerated 2023 framework to capture AI-enabled glucose prediction algorithm revenue before hardware incumbents adapt.
For Investors and Strategic Acquirers: Long-term, this sits as a consumable-recurring play because sensor replenishment economics dominate lifetime value capture regardless of hardware manufacturer. Acquisition candidates include domestic Indian assemblers with PLI scheme qualification and established CDSCO registration pathways. Monitor NMPA priority review framework expansion as signal for Chinese innovative device approval acceleration that would validate optical sensing technology bets.
| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Software-as-Medical-Device Registration | Accelerates AI-enabled glucose prediction algorithm market entry under India's 2023 risk-based classification amendment. |
| Platinum Electrode Supply Agreement | Secures precious metal input stability against commodity volatility compressing electrochemical sensor manufacturing margins. |
| Tier-2 Hospital System Partnership | Captures underpenetrated diagnostic chains in Pune, Hyderabad, and Chennai relative to saturated metropolitan corridors. |
| Telemedicine Platform Integration | Aligns with China's internet hospital licensing framework for remote glucose data transmission subscription revenue. |
| Multi-Parameter Wearable Development | Captures combined glucose-cardiovascular diagnostic budgets in Brazilian integrated health network procurement tenders. |
Methodological Framework
The analysis maps continuous glucose monitors, testing strips, smart sensors, and telemedicine platforms, each validated through hospital procurement managers, biomedical engineers, GPO contracts specialists, and regulatory affairs leads at multinational device manufacturers. Primary interview intelligence combined with secondary validation from CDSCO registration databases, ANVISA approval records, NMPA priority review disclosures, and hospital procurement tender documents. Bottom-up unit economics triangulated against top-down BRIC healthcare expenditure allocations.
Assumptions held fixed include current reimbursement code coverage for continuous monitoring, prevailing platinum electrode pricing bands, and existing regulatory pathway timelines across Brazil, Russia, India, and China. Variables stress-tested include PLI scheme extension decisions, NMPA priority review framework expansion, and internet hospital licensing acceleration in China. Segmentation dimensions modeled encompass product type, technology architecture, end-user site-of-care, and disease application intensity across the projection horizon. CAGRs derived from equipment placement trajectories and per-patient sensor consumption rates, with insulin-dependent population growth and pre-diabetic screening expansion as key demand inputs.
Stress conditions across platinum price volatility, regulatory pathway delays, and reimbursement code revisions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about technology adoption curves and procurement centralization trends. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Global Blood Glucose Monitoring Systems Market
Diabetes Care
Smart Glucose Monitors Market
Diabetes Care
Global Diabetes Pen Market
Diabetes Care
Global Diabetic Retinopathy Market
Diabetes Care
Asia Pacific Blood Glucose Test Strip Market
Diabetes Care
Latin America Insulin Infusion Pump Market
Diabetes Care
Next Generation Diabetes Therapy and Drug Delivery Market
Diabetes Care
OTC Glucose Monitors Market
Diabetes Care
United Kingdom Blood Glucose Monitoring Market
Diabetes Care
US Continuous Glucose Monitoring Market
Diabetes Care
Digital Diabetes Market
Diabetes Care
Global Smart Diabetes Management Market
Diabetes Care
Canada Continuous Glucose Monitoring Market
Diabetes Care
BRICS Diabetes Treatment and Prevention Market
Diabetes Care
Self-Monitoring Blood Glucose (SMBG) Market
Diabetes Care
Egypt Diabetes Care Devices Market