
 Asia Pacific Blood Glucose Monitoring Market | 2026-2036
Asia Pacific Blood Glucose Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Blood Glucose Monitoring Market Analysis
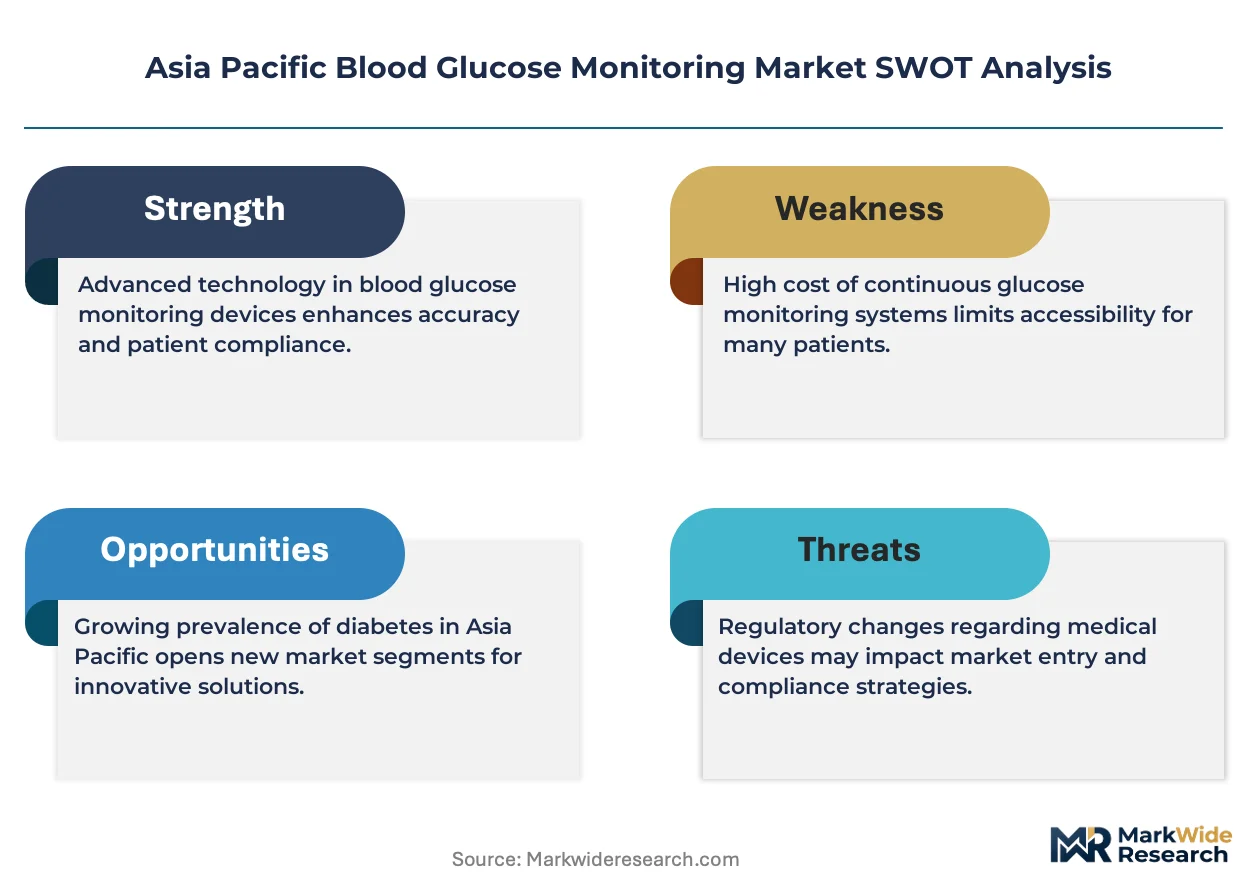
China's manufacturing corridor for electrochemical biosensors is reshaping regional supply dynamics. Abbott Laboratories leverages its FreeStyle platform to dominate continuous glucose monitor channels across Australian clinics. Sinocare anchors its position through cost-optimized strip production serving China's homecare segment. Dexcom competes on sensor accuracy and interoperability with insulin delivery systems.
Blood glucose monitoring encompasses devices and consumables that measure glucose concentration in blood through enzymatic or electrochemical reactions, typically requiring sample volumes under one microliter and producing results within five seconds for point-of-care decisions. These systems serve diabetes management by enabling real-time glycemic control and reducing complication risks. Continuous glucose monitors lead technology adoption while test strips retain the largest revenue pool due to recurring purchase patterns. Homecare represents the fastest-growing end user channel as remote patient monitoring infrastructure matures across the region. Electrochemical technology dominates production volumes, though non-invasive approaches attract R&D investment for future differentiation.
China's NMPA, India's CDSCO, and Japan's PMDA enforce divergent medical device registration pathways that shape product launch timelines and clinical evidence requirements across the region. Australia's TGA alignment with MDR-equivalent standards creates a secondary compliance benchmark for manufacturers targeting premium segments. Stakeholders must monitor harmonization efforts between ASEAN regulatory frameworks and national pharmacopeia standards to optimize market entry sequencing.
Market Dynamics
Hospital-at-home program expansion across China's tier-1 cities is compressing traditional clinical testing volumes while amplifying demand for connected, calibration-free monitoring systems that integrate with remote patient management platforms.
Growth Catalysts
- CDSCO Quality Norms:India's tightened medical device quality standards for glucose monitors are accelerating formal channel registration and displacing unapproved imports through mandatory quality audits.
- Homecare Infrastructure:Southeast Asian telehealth platform rollouts are embedding glucose monitoring into bundled chronic disease management subscriptions.
- Electrochemical Biosensor Manufacturing:China's concentrated production corridor is driving unit cost reductions that expand addressable patient populations across price-sensitive markets.
Market Restraints
- Enzyme Strip Input Volatility:Glucose oxidase and mediator chemical supply concentration in Chinese chemical parks creates raw material cost instability for strip manufacturers.
- Calibration Burden:Non-continuous fingerstick systems require frequent calibration against laboratory reference methods, limiting adoption among working-age populations with irregular schedules.
- Substitution Threat:Flash glucose monitoring systems are capturing moderate-complexity patients who would otherwise purchase high-frequency test strip regimens.
Strategic Opportunities
- Indonesia's Archipelago Penetration:Pharmacy chain consolidation across Indonesian islands is creating direct-to-patient distribution infrastructure previously absent in dispersed rural diabetes populations.
- Insulin Delivery Convergence:Closed-loop algorithm integration between continuous glucose sensors and patch pump systems is opening premium positioning for interoperable device ecosystems.
- Japan's PMDA Fast-Track:Breakthrough device designation pathways for non-invasive optical glucose sensing are compressing clinical evidence requirements for novel modality entrants.
Industry Challenges
- Embedded Firmware Talent Scarcity:Algorithm development for real-time glucose prediction requires specialized biomedical engineering competencies that compete with broader IoT device sectors.
- Multi-Market Certification Parallelism:Simultaneous NMPA, PMDA, and TGA submission requirements force duplicate clinical study designs that extend capital lockup periods.
- Legacy Meter Data Silos:Proprietary data formats from installed base devices obstruct seamless migration to platform-agnostic cloud analytics services.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Blood Glucose Monitoring Market |
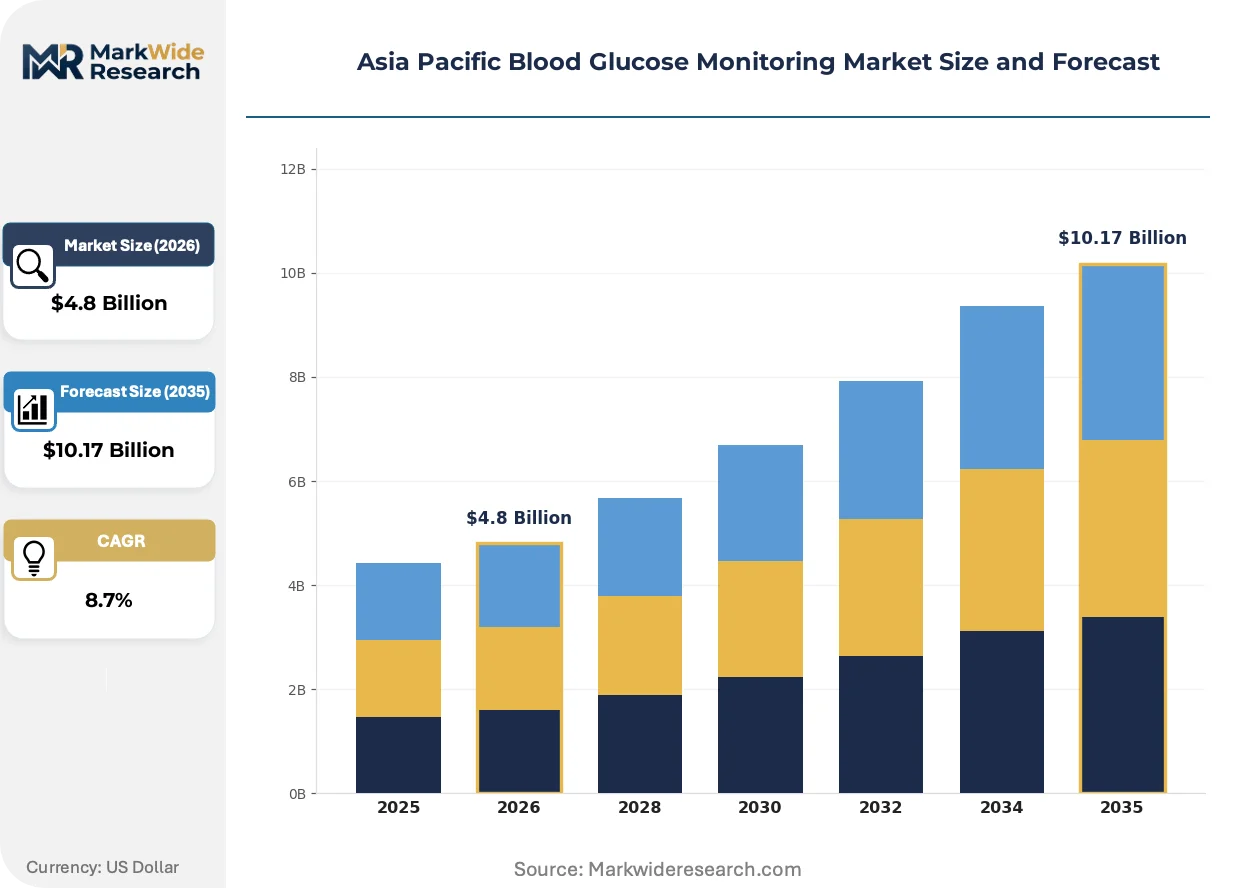
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glucometers, Continuous Glucose Monitors, Test Strips, Lancets End User: Homecare, Hospitals, Clinics, Diagnostic Laboratories Technology: Electrochemical, Optical, Non-Invasive, Enzymatic Application: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Others |
| Companies Covered | Medtronic, i-SENS, Abbott Laboratories, LifeScan, Ascensia Diabetes Care, Dexcom, Sinocare, Arkray, F. Hoffmann-La Roche Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Blood Glucose Monitoring Market Emerging Trajectories
Sensor miniaturization and cloud-native data architectures are converging to enable passive glucose surveillance without patient-initiated sampling, fundamentally altering the compliance economics of diabetes management across Asia Pacific.
Optical glucose sensing through near-infrared spectroscopy and Raman scattering is digitizing the calibration workflow by eliminating consumable dependencies and enabling factory-calibrated devices. Australian endocrinology clinics are piloting these systems for type 2 diabetes screening programs. The technology is digitizing patient onboarding by removing the training burden associated with strip-handling protocols.
PMDA's revised software-as-a-medical-device guidance is mandating algorithm update traceability for machine learning-enabled glucose prediction tools. Manufacturers must now submit retraining dataset documentation for each model iteration. Continuous glucose monitor vendors with Japan market presence are restructuring quality management systems to accommodate this evidentiary overhead.
Subscription-based device provisioning is displacing outright purchase models in Australian and South Korean employer insurance schemes. Patients receive sensor hardware at zero upfront cost in exchange for committed data sharing that feeds population health analytics. This shift is most pronounced among technology sector employers with self-insured health benefit structures.
Asia Pacific Blood Glucose Monitoring Market Segmentation
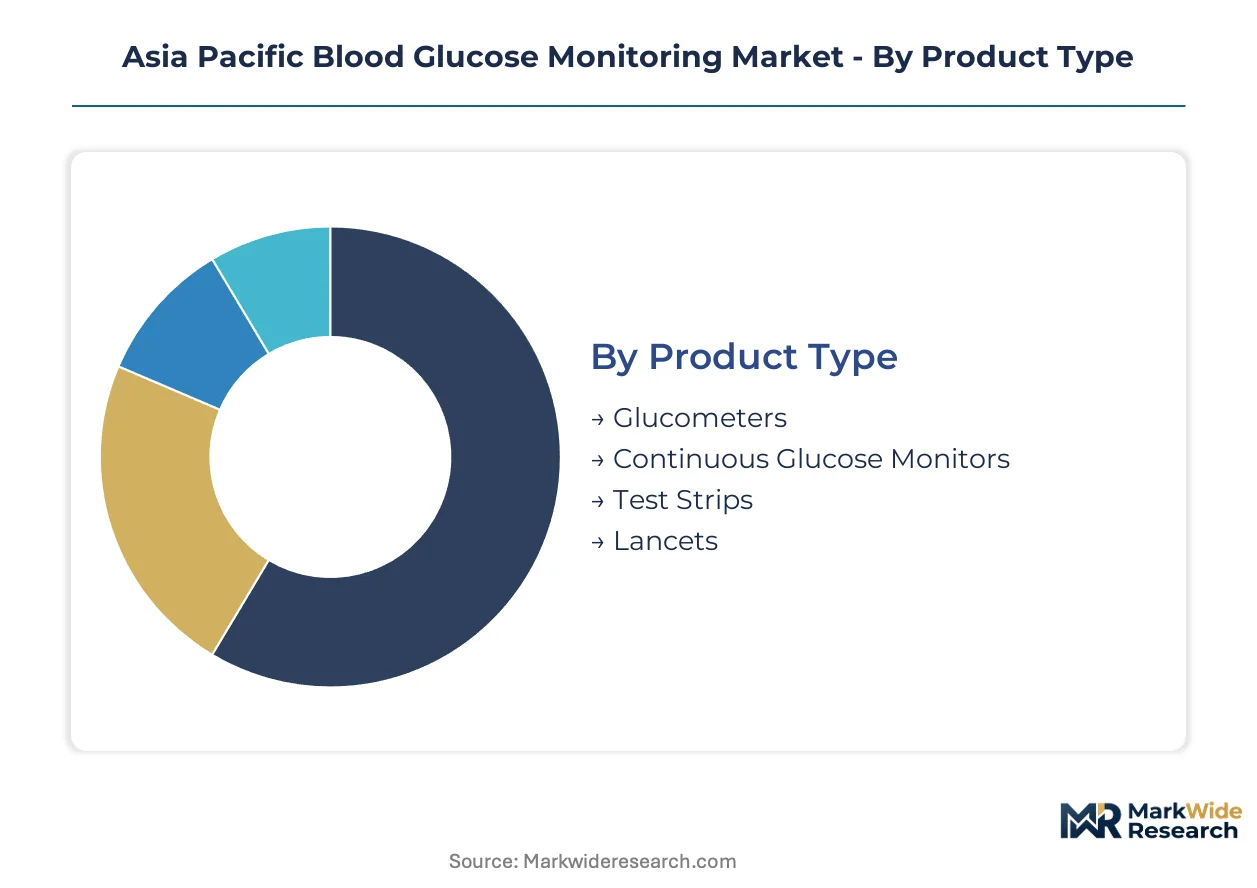
Segmentation in blood glucose monitoring reveals distinct service intensity patterns across product categories. Test strips and continuous glucose monitors demand radically different replenishment cadences, calibration support, and patient education touchpoints that reshape manufacturer go-to-market economics across Asia Pacific.
Product Type:
After-sales service intensity varies dramatically across product categories, with consumables requiring high-frequency replenishment logistics while capital equipment demands technical support and warranty management.
- Test Strips:Enzymatic reagent strips utilizing glucose oxidase chemistry dominate unit volumes through recurring purchase patterns. Demand concentrates in India's tier-2 and tier-3 cities where CDSCO registration requirements are displacing unapproved imports and formalizing distribution channels.
- Continuous Glucose Monitors:Factory-calibrated electrochemical sensors with 10-14 day wear periods command premium positioning through reduced calibration burden. Australian employer insurance schemes are embedding these devices into subscription-based chronic disease management programs.
- Glucometers:Handheld electrochemical readers requiring fingerstick sampling retain installed base relevance across Southeast Asian price-sensitive markets.
- Lancets:Single-use penetration devices represent low-margin, high-volume accessories bundled with strip purchases.
By volume, test strips lead. By growth pace, continuous glucose monitors are expanding most quickly.
End User:
Channel cost structures diverge sharply, with institutional procurement emphasizing total cost of ownership while homecare channels prioritize patient self-management convenience and remote monitoring integration.
- Homecare:Patient-directed monitoring outside clinical settings is climbing the fastest as China's hospital-at-home programs expand across Beijing, Shanghai, and Shenzhen. Telehealth platform integration is embedding glucose data into bundled chronic disease subscriptions across Southeast Asia.
- Hospitals:Acute care settings demand calibration-traceable systems with laboratory correlation protocols for glycemic control in surgical and critical care units.
- Clinics:Outpatient diabetes management centers prioritize rapid-turnaround point-of-care devices for same-visit therapeutic adjustments.
- Diagnostic Laboratories:Centralized reference testing facilities maintain venous plasma glucose validation capabilities for meter calibration disputes.
Homecare channels dominate volume expansion, while hospital procurement retains the highest per-unit value concentration.
Technology:
Production cost tiers separate established electrochemical platforms from emerging optical modalities, with manufacturing scale determining competitive viability across Asia Pacific's price-differentiated markets.
- Electrochemical:Amperometric biosensors with mediator-enhanced electron transfer constitute the dominant production volume. China's concentrated manufacturing corridor in Jiangsu and Zhejiang provinces is driving unit cost reductions that expand addressable populations.
- Optical:Near-infrared spectroscopy and Raman scattering approaches are digitizing calibration workflows by eliminating consumable dependencies. Australian endocrinology clinics are piloting these systems for type 2 diabetes screening programs.
- Enzymatic:Glucose oxidase and hexokinase-based systems retain relevance in legacy meter installed bases and laboratory reference methods.
- Non-Invasive:Transdermal and interstitial fluid extraction technologies attract R&D investment for future differentiation despite current accuracy limitations.
Electrochemical platforms anchor current volume, while optical sensing shows the steepest expansion trajectory in pilot deployments.
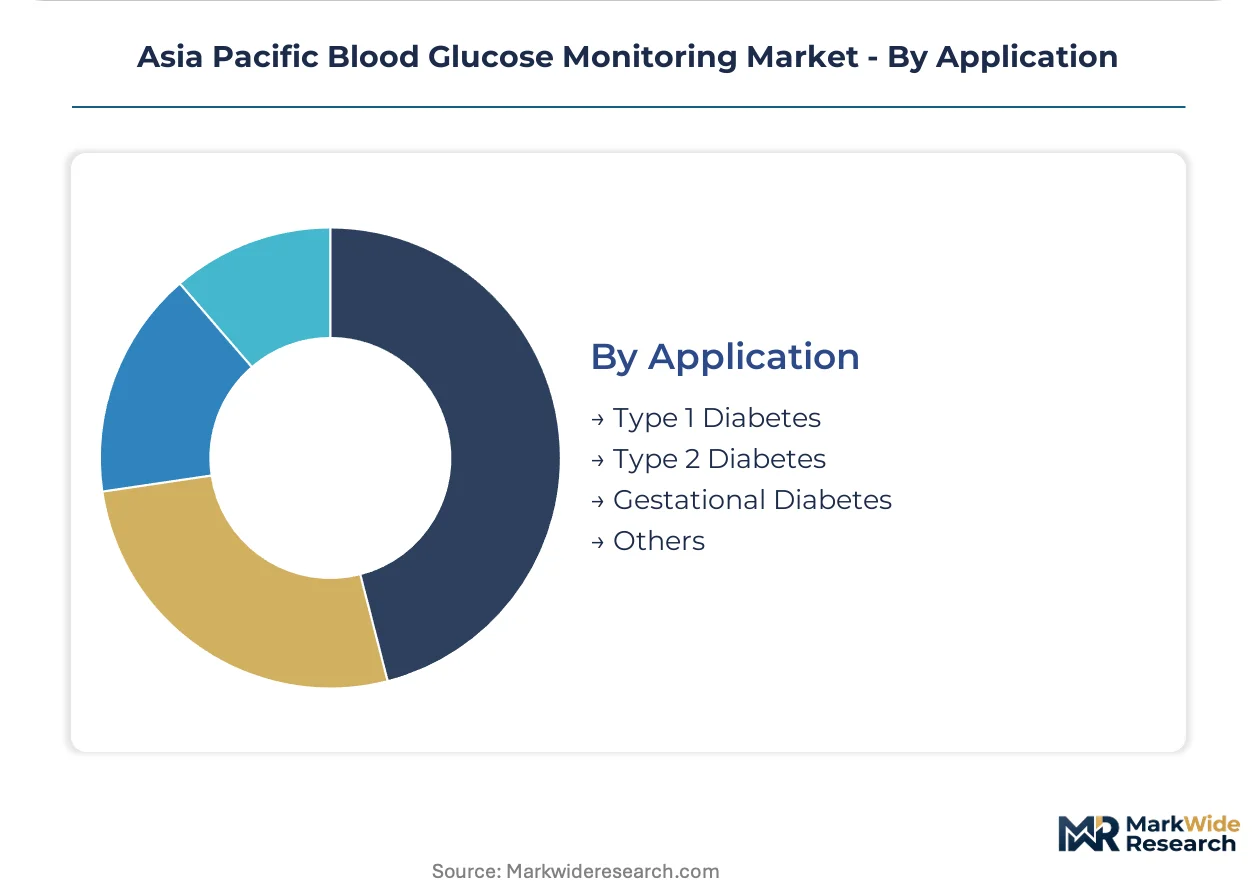
Application:
Disease severity and monitoring frequency requirements create distinct patient segments with diverging device performance needs and reimbursement eligibility across national health systems.
- Type 2 Diabetes:The largest addressable population segment requires varying intensity based on therapeutic regimen, from diet-controlled cases using episodic testing to insulin-dependent patients needing continuous surveillance.
- Type 1 Diabetes:Absolute insulin deficiency mandates intensive glucose monitoring with closed-loop system compatibility, driving premium device adoption in Japan and South Korea.
- Gestational Diabetes:Temporary hyperglycemia during pregnancy creates episodic monitoring demand with specific accuracy requirements for maternal-fetal safety protocols.
- Others:Steroid-induced hyperglycemia, cystic fibrosis-related diabetes, and post-transplant monitoring represent niche indications with specialized clinical requirements.
Type 2 diabetes management generates the highest absolute volume, while type 1 diabetes applications command the strongest technology upgrade momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NMPA's medical device registration pathways anchor regulatory complexity across the region's largest glucose monitoring market. Divergent national pharmacopeia standards between China, India, Japan, South Korea, and Australia compress product launch timelines and force duplicate clinical evidence generation.
China
Hospital-at-home programs across Beijing, Shanghai, and Shenzhen are amplifying demand for connected, calibration-free monitoring systems. NMPA's tightened software-as-a-medical-device guidance mandates algorithm update traceability for machine learning-enabled prediction tools. Jiangsu and Zhejiang provinces anchor electrochemical biosensor manufacturing, driving unit cost reductions that expand addressable patient populations.
India
CDSCO's tightened quality norms for glucose monitors are accelerating formal channel registration and displacing unapproved imports through mandatory quality audits. Tier-2 and tier-3 cities concentrate demand for enzymatic test strips as formal distribution channels replace informal procurement. Maharashtra and Gujarat host emerging domestic manufacturing clusters serving price-sensitive homecare segments.
Japan
PMDA's breakthrough device designation pathways for non-invasive optical glucose sensing are compressing clinical evidence requirements for novel modality entrants. Type 1 diabetes applications command premium device adoption through closed-loop system compatibility requirements. Kanto region endocrinology clinics pilot near-infrared spectroscopy systems for type 2 diabetes screening programs.
Australia
Employer insurance schemes are embedding continuous glucose monitors into subscription-based chronic disease management programs with zero upfront hardware costs. TGA alignment with MDR-equivalent standards creates a secondary compliance benchmark for manufacturers targeting premium segments. Sydney and Melbourne clinics drive adoption of factory-calibrated electrochemical sensors with 10-14 day wear periods.
South Korea
Technology sector employers with self-insured health benefit structures are displacing outright purchase models with subscription-based device provisioning. MFDS regulatory pathways emphasize interoperability requirements with insulin delivery systems for closed-loop algorithm integration. Seoul Capital Area concentrates demand for premium continuous monitoring systems among working-age diabetic populations.
Asia Pacific Blood Glucose Monitoring Market Vendor Landscape
Multinational platform specialists and regional cost-optimized manufacturers split the market into divergent value capture tiers. The vendor base concentrates around electrochemical biosensor production scale on one vector and continuous monitoring algorithm sophistication on another. Three archetypes dominate: integrated diabetes management platforms, consumables-focused strip manufacturers, and interoperability-first sensor specialists. Competitive moves center on backward integration into enzyme chemistry supply and strategic partnerships with telehealth platform operators.
Among multinational platform developers, Abbott Laboratories and Dexcom exemplify the interoperability-first archetype through premium positioning in closed-loop ecosystems. Sinocare anchors the regional cost-optimized tier through concentrated manufacturing in China's Jiangsu-Zhejiang corridor. Medtronic occupies a position spanning both platform integration and consumables scale, representing the hybrid archetype that competes across multiple price-performance tiers simultaneously.
| Leading Market Players |
|---|
| Medtronic |
| i-SENS |
| Abbott Laboratories |
| LifeScan |
| Ascensia Diabetes Care |
| Dexcom |
| Sinocare |
| Arkray |
| F. Hoffmann-La Roche Ltd. |
| Others |
Supply Flow & Price Mechanics
Overcapacity in China's Jiangsu-Zhejiang electrochemical biosensor corridor is compressing strip manufacturing margins while amplifying pricing power for calibration-free continuous glucose monitor vendors serving hospital-at-home programs. This utilization asymmetry splits the market into commoditized consumables and premium connected devices with divergent supplier economics.
Pricing Analysis
Geographic price spreads between Australia's subscription-based employer insurance schemes and India's tier-2 retail channels exceed threefold for equivalent sensor performance tiers. Three-tier pricing structure across premium, standard, and economy levels dominates, with differentiation driven by calibration burden and telehealth platform integration depth. Pricing pressure stems from flash glucose monitoring substitution eroding high-frequency test strip volumes. Working-age populations in South Korean technology employers show lowest price sensitivity due to self-insured benefit structures, while Indian tier-3 retail patients drive economy-tier volume.
Supply Chain Analysis
Tariff exposure between China and ASEAN markets dominates supply chain risk planning for glucose oxidase reagent strip manufacturers. Production concentrates in China's Jiangsu and Zhejiang provinces, with secondary strip assembly emerging in Maharashtra and Gujarat, India. Raw material dependencies center on glucose oxidase enzymes, palladium-based mediator chemicals, and hydrophilic polymer membranes. Single-source vulnerability in Chinese chemical park enzyme concentration creates input cost instability. Distribution runs through pharmacy chain consolidation in Indonesia's archipelago markets and telehealth platform bundling across Southeast Asian homecare channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering a cyclical recovery phase as hospital-at-home program expansion across China's tier-1 cities rebuilds demand for connected monitoring infrastructure. The recovery is anchored by reimbursement policy normalization following pandemic-era telehealth embedding.
For Market Incumbents: Insulate installed base revenue through backward integration into enzyme chemistry supply and firmware update subscriptions that obstruct migration to platform-agnostic cloud services. Threats from optical sensing non-invasive alternatives in Japanese PMDA fast-track pathways demand defensive patent clustering. Channel control through exclusive telehealth platform partnerships represents the critical retention lever. For New Entrants and Emerging Players: Indonesian pharmacy chain consolidation across the archipelago offers white-space access to dispersed rural diabetes populations previously unreachable through formal distribution. India's CDSCO registration acceleration creates entry timing for quality-audited strip manufacturers displacing unapproved imports. Target closed-loop algorithm integration partnerships with patch pump vendors as the differentiated go-to-market angle. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among continuous glucose monitor vendors with employer insurance subscription traction and data-sharing monetization capabilities. Long-term viability over a multi-year horizon favors acquisition targets with PMDA breakthrough device designation progress and interoperable insulin delivery system certifications. Watch for NMPA software-as-a-medical-device guidance enforcement as the inflection signal compressing algorithm update evidentiary overhead.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Enzyme Chemistry | Captive glucose oxidase supply secures margin control against Chinese chemical park volatility. |
| Closed-Loop Algorithm Partnership | Interoperability with patch pump vendors opens premium positioning in South Korean and Japanese markets. |
| Telehealth Platform Embedding | Bundled chronic disease subscriptions across Southeast Asia lock in recurring strip replenishment volumes. |
| PMDA Breakthrough Device Pathway | Compressed clinical evidence requirements accelerate non-invasive optical sensing market entry in Japan. |
| CDSCO Quality Audit Compliance | Mandatory registration displaces unapproved imports and formalizes distribution channels across Indian tier-2 cities. |
Methodological Framework
Cross-validation between hospital procurement database analysis and biomedical engineering expert interviews anchors the qualitative findings in operational reality. Primary research engaged clinicians, hospital purchasing committee members, GPO contracts managers, and CDSCO regulatory affairs specialists across China, India, Japan, Australia, and South Korea. Secondary sources included NMPA medical device registration filings, PMDA software-as-a-medical-device guidance documents, TGA MDR-equivalent standards, hospital procurement contract databases, and employer insurance scheme benefit structures. Bottom-up patient population modeling triangulated against top-down manufacturer revenue segmentation.
Calibration against historical glucose monitor adoption curves and reimbursement policy shift timelines validates the projection framework. Segmentation dimensions span product type, end-user channel, technology modality, application severity, and national regulatory cluster. CAGRs derive from installed base erosion rates, replacement cycle compression, and subscription conversion velocity across the modeling period. Forecast inputs incorporate telehealth platform penetration trajectories and CDSCO audit enforcement intensity.
Practitioners should monitor NMPA software guidance algorithm update traceability requirements, PMDA breakthrough device designation granting velocity, and Indonesian pharmacy chain consolidation pace for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
North America Oral Anti-Diabetic Drug Market
Diabetes Care
Alternatives for Injectable Diabetes Care Market
Diabetes Care
Global Diabetes Pen Market
Diabetes Care
South Africa Blood Glucose Monitoring Market
Diabetes Care
Philippines Oral Anti-Diabetic Drug Market
Diabetes Care
Glycated Albumin Market
Diabetes Care
Italy Oral Anti-Diabetic Drug Market
Diabetes Care
Asia-Pacific Diabetes Care Devices Market
Diabetes Care
Philippines Diabetes Care Devices Market
Diabetes Care
Philippines Diabetes Drugs and Devices Market
Diabetes Care
Global Smart Insulin Pens Market
Diabetes Care
India Oral Anti-Diabetic Drug Market
Diabetes Care
Mexico Diabetes Medication Market
Diabetes Care
Oman Diabetes Drugs Market
Diabetes Care
Global Non-Invasive Blood Glucose Monitoring Devices Market
Diabetes Care
Japan Insulin Drugs and Delivery Devices Market