
 South Korea Self-Monitoring Blood Glucose Devices Market | 2026-2036
South Korea Self-Monitoring Blood Glucose Devices Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Self-Monitoring Blood Glucose Devices Market Insights
Subscription-based leasing for continuous glucose monitor hardware is reshaping competitive dynamics in South Korea's diabetes care sector. i-Sens leverages its domestic manufacturing base to anchor pricing power against multinational entrants. Roche Diabetes Care competes through specialized hospital channel partnerships in Seoul's tertiary care centers. Abbott Laboratories extends its presence via Bluetooth-enabled meter ecosystems that integrate with national health record infrastructure.
Self-monitoring blood glucose devices comprise portable electrochemical or optical systems that quantify glucose concentration in capillary blood samples, typically requiring 0.3–1.0 microliter volumes and delivering results within five seconds for therapeutic adjustment. Their primary commercial purpose centers on enabling real-time glycemic management outside clinical settings. Continuous glucose monitors lead technology segment momentum as flash glucose monitoring displaces traditional fingerstick routines among insulin-dependent users. Test strips still occupy the largest revenue pool due to recurring consumable demand, though Bluetooth connectivity features now differentiate premium meter tiers. Retail pharmacies dominate distribution channel volume, while online stores capture the fastest growth trajectory among younger diabetic cohorts.
MFDS medical device approval pathways and national health insurance reimbursement schedules jointly determine product launch timelines and patient out-of-pocket exposure for glucose monitoring systems. The Korean Ministry of Food and Drug Safety enforces electromagnetic compatibility and software validation standards that constrain connected device certification timelines. Stakeholders must monitor evolving digital therapeutics classification criteria that could reclassify app-integrated monitors as regulated software-as-medical-device platforms.
Market Dynamics
Flash glucose monitoring systems are compressing traditional fingerstick meter volumes as insulin-dependent patients in Seoul's tertiary hospitals migrate toward continuous data streams. MFDS reimbursement recalibration accelerates this substitution curve.
Growth Catalysts
- Aging Demographics:South Korea's diabetic population over 65 expands rapidly, creating sustained demand for home-based glycemic management tools.
- MFDS Digital Therapeutics Pathway:The regulator's streamlined software-as-medical-device classification reduces certification timelines for app-integrated monitors.
- Gyeonggi Province Hospital Density:Concentrated endocrinology infrastructure in this corridor generates clustered prescription volumes for connected glucose systems.
Market Restraints
- Test Strip Cost Structure:Recurring consumable expenses strain national health insurance reimbursement budgets, pressuring patient co-payment levels.
- Electrochemical Sensor Import Dependency:Precision enzyme electrode supply concentrates among Japanese and German specialty chemical suppliers.
- MFDS Electromagnetic Compatibility Validation:Bluetooth-enabled devices face extended certification timelines due to software validation requirements.
Strategic Opportunities
- Busan-Ulsan Manufacturing Corridor:Underpenetrated diabetes screening infrastructure in this southern region offers whitespace for point-of-care glucose system deployment.
- Retail Pharmacy Channel Integration:Community pharmacists in Daegu are piloting subscription-based meter leasing programs.
- National Health Record Interoperability Mandate:Government data-sharing standards create regulatory tailwind for cloud-connected monitoring platforms.
Industry Challenges
- Firmware Validation Expertise Scarcity:Connected device manufacturers face acute shortages of embedded systems engineers capable of MFDS-compliant software documentation.
- Legacy Hospital IT Integration:Tertiary care centers in Seoul require costly middleware development to incorporate patient-generated glucose data into electronic health records.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Self-Monitoring Blood Glucose Devices Market |
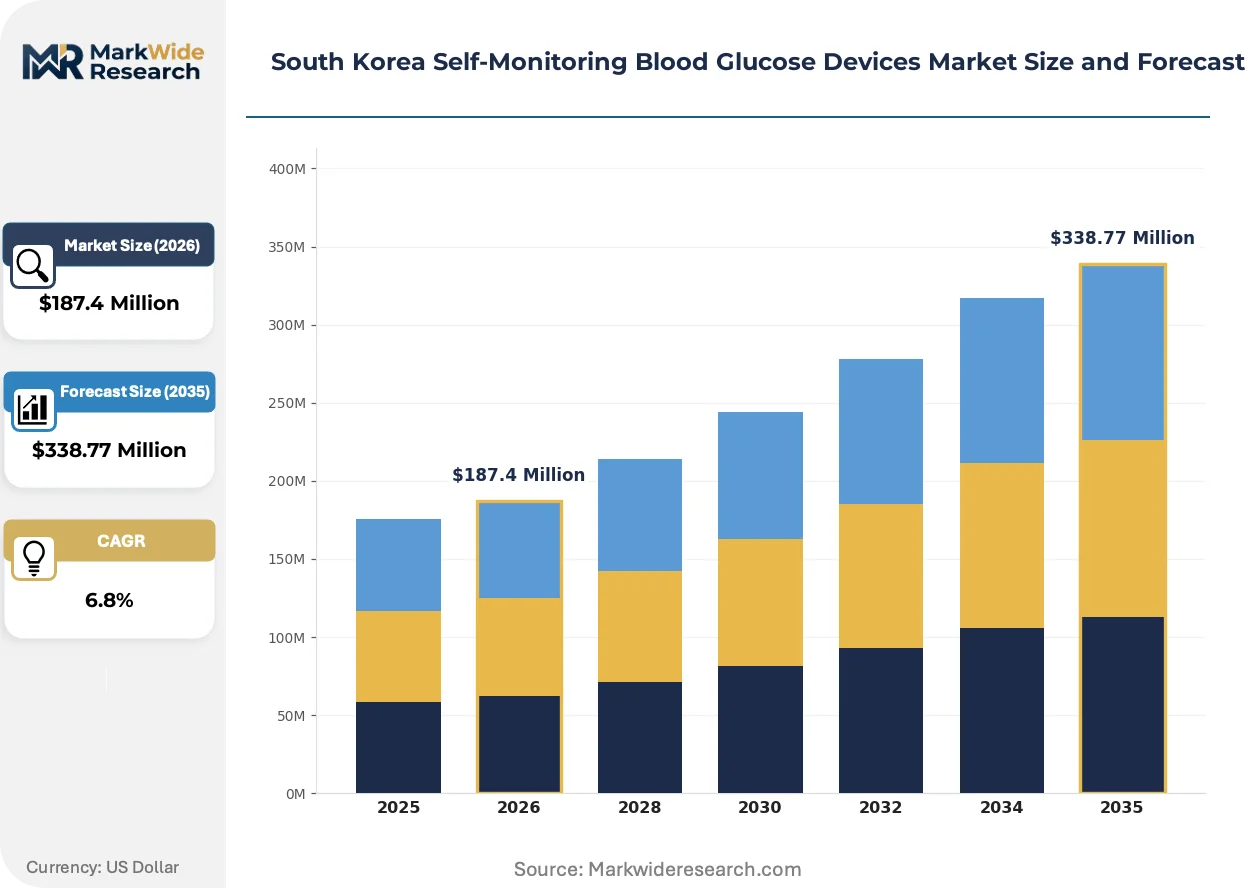
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glucose Meters, Continuous Glucose Monitors, Test Strips, Lancing Devices Technology: Capillary Blood Sampling, Flash Glucose Monitoring, Integrative Health Apps, Bluetooth Connectivity End User: Individuals with Diabetes, Healthcare Professionals, Hospitals, Clinics Distribution Channel: Retail Pharmacies, Online Stores, Medical Supply Companies, Hospital Networks |
| Companies Covered | i-Sens, Roche Diabetes Care, Abbott Laboratories, Lifescan, Arkray, Dexcom, Medtronic, Ascensia Diabetes Care, Acon Laboratories, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Self-Monitoring Blood Glucose Devices Market Trends and Innovations
Digital biomarker integration and non-invasive sensing modalities are redefining competitive boundaries in South Korea's glucose monitoring sector. Three developments merit particular attention.
Non-invasive optical glucose sensing using near-infrared spectroscopy is rendering obsolete the fingerstick paradigm for pre-diabetic screening applications. Occupational health clinics in Incheon's manufacturing zones are piloting these wrist-worn devices for workforce metabolic monitoring. The technology compresses preventive care timelines by eliminating blood draw hesitancy among asymptomatic populations.
MFDS software-as-medical-device classification criteria are tightening validation requirements for algorithm-driven insulin dosing recommendations. This regulatory evolution forces manufacturers to separate hardware certification from predictive analytics module approval. Connected meter ecosystems with integrated bolus calculators face segmented compliance timelines that delay full-feature launches.
Younger diabetic cohorts in Seoul's digital-native population are migrating glucose data management to smartphone-native platforms, bypassing traditional meter-native displays. Retail pharmacy foot traffic for strip refills is declining in Gangnam and Mapo districts as subscription direct-shipping models capture refill loyalty. Channel disintermediation concentrates purchasing influence with telehealth platforms rather than endocrinology clinics.
South Korea Self-Monitoring Blood Glucose Devices Market Segmentation
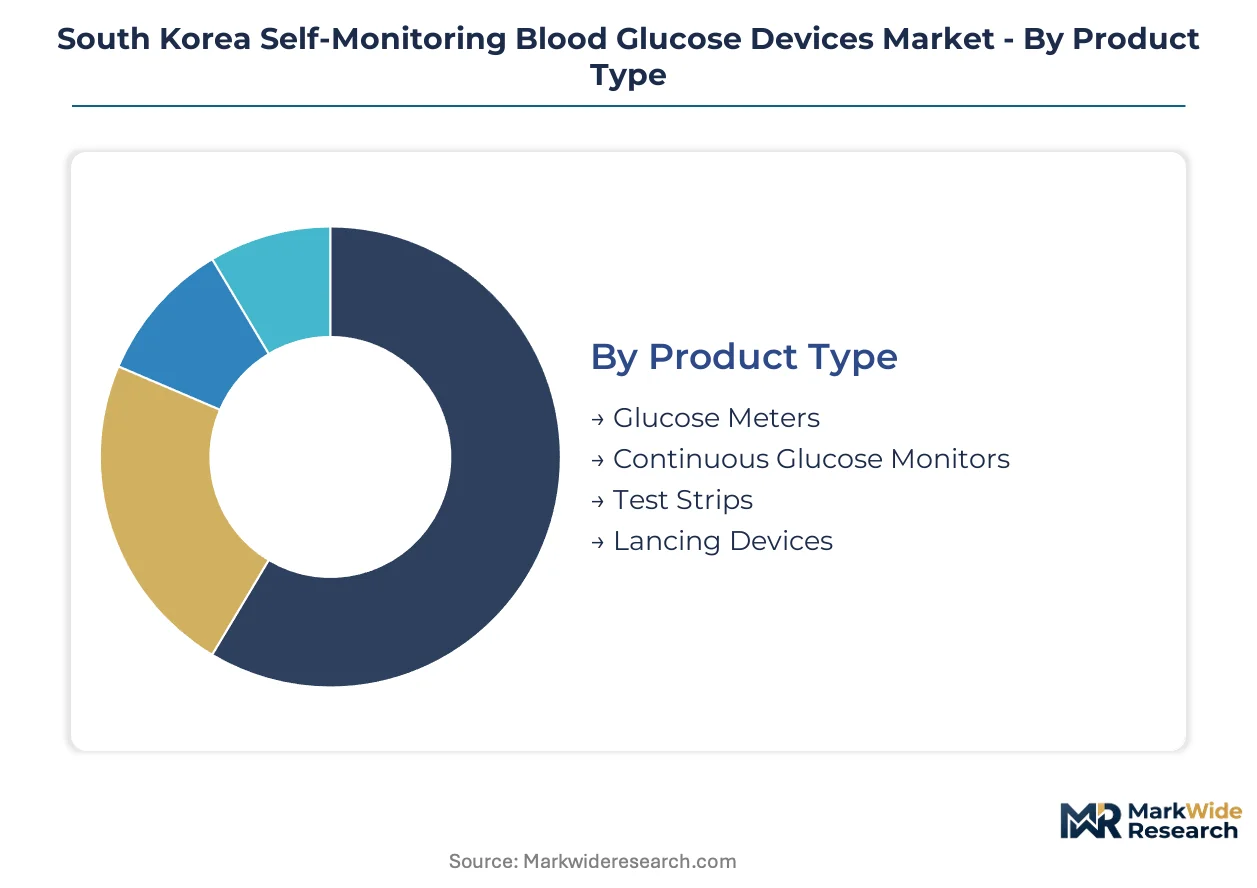
Segmentation in South Korea's glucose monitoring market exposes divergent service intensity requirements across hardware and consumable categories. Test strip replenishment cycles demand continuous pharmacy engagement, while connected meter ecosystems require firmware update pipelines and cloud infrastructure support.
Product Type:
After-sales service intensity varies dramatically across this category, with disposable consumables requiring minimal technical support versus complex continuous monitoring hardware demanding calibration assistance and sensor replacement training.
- Glucose Meters:Handheld electrochemical devices measuring capillary glucose via enzyme-impregnated test strips. Demand concentrates in Seoul's metropolitan clinic networks where Type 2 diabetes patients require frequent therapeutic adjustments. MFDS electromagnetic compatibility standards extend certification timelines for Bluetooth-enabled variants.
- Continuous Glucose Monitors:Wearable sensor-transmitter systems providing interstitial glucose readings at five-minute intervals. Adoption accelerates among insulin-dependent users in Gyeonggi Province's dense endocrinology corridor as flash glucose monitoring displaces fingerstick routines.
- Test Strips:Single-use consumables containing glucose oxidase chemistry. Recurring purchase patterns dominate retail pharmacy channel volume across Daegu and Busan distribution hubs.
- Lancing Devices:Spring-loaded mechanisms for capillary blood extraction. Minimal service requirements limit margin capture for distributors outside hospital procurement networks.
By volume, Test Strips leads. By growth pace, Continuous Glucose Monitors is ahead.
Technology:
Cost tier differentiation separates premium connected systems from basic electrochemical platforms, with software validation expenses driving price stratification.
- Capillary Blood Sampling:Traditional fingerstick methodology using 0.3–1.0 microliter blood volumes. Dominates budget-conscious patient segments in Busan-Ulsan corridor where reimbursement co-payments constrain device selection.
- Flash Glucose Monitoring:Factory-calibrated sensors eliminating routine fingerstick confirmation. Seoul's tertiary hospitals drive prescription volumes as endocrinologists prioritize glycemic pattern visibility.
- Integrative Health Apps:Smartphone platforms aggregating glucose data with dietary and activity logs. Younger diabetic cohorts in Gangnam and Mapo districts favor these native interfaces over meter-native displays.
- Bluetooth Connectivity:Wireless data transmission to cloud repositories and electronic health records. MFDS software-as-medical-device classification creates segmented compliance timelines that delay full-feature launches.
By installed base, Capillary Blood Sampling leads. By expansion trajectory, Flash Glucose Monitoring is climbing the fastest.
End User:
Application context determines device specification requirements, with clinical settings demanding interoperability features absent from home-use configurations.
- Individuals with Diabetes:Home-based patients managing glycemic control through self-directed testing. Gyeonggi Province's aging demographic sustains volume demand for simplified meter interfaces.
- Healthcare Professionals:Endocrinologists and diabetes educators interpreting patient-generated data. MFDS digital therapeutics pathway streamlines certification for algorithm-integrated platforms these specialists prescribe.
- Hospitals:Tertiary care centers in Seoul requiring middleware development to incorporate patient glucose streams into electronic health records.
- Clinics:Community endocrinology practices in Incheon's occupational health zones piloting non-invasive screening for workforce metabolic monitoring.
By patient contact volume, Individuals with Diabetes leads. By technology upgrade frequency, Hospitals is gaining share fastest.
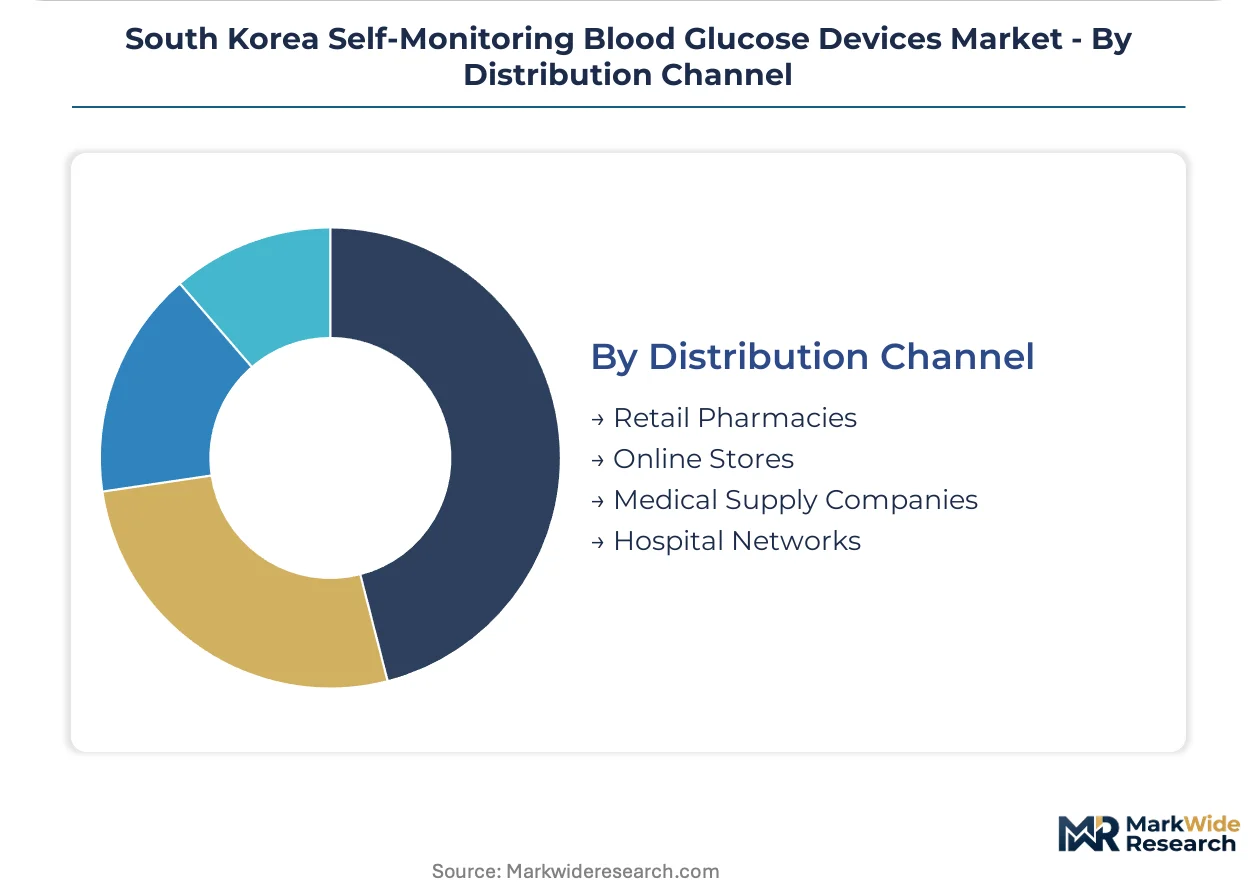
Distribution Channel:
Customer type stratification separates institutional procurement from retail consumption, with divergent margin structures and loyalty mechanisms.
- Retail Pharmacies:Community dispensaries handling test strip replenishment and meter sales. Foot traffic is declining in Seoul's digital-native districts as subscription models capture refill loyalty.
- Online Stores:E-commerce platforms offering direct-shipping for consumable subscriptions. Younger diabetic cohorts drive steepest expansion trajectory in this channel.
- Medical Supply Companies:Specialized distributors serving hospital and clinic networks with bulk procurement contracts.
- Hospital Networks:Integrated procurement systems within tertiary care centers standardizing on connected monitoring ecosystems.
By transaction volume, Retail Pharmacies leads. By channel shift momentum, Online Stores is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gyeonggi Province commands premium pricing power for connected glucose systems, while Busan-Ulsan corridor patients face higher co-payment burdens on basic electrochemical meters. This regional asymmetry reflects hospital network density variations and MFDS reimbursement tier differentiation across South Korea's administrative zones.
Seoul Capital Area
Seoul's tertiary care centers generate concentrated prescription volumes for flash glucose monitoring systems as endocrinologists prioritize glycemic pattern visibility. MFDS digital therapeutics pathway streamlines certification for algorithm-integrated platforms these specialists prescribe. Gangnam and Mapo districts host the densest clusters of diabetes educators piloting smartphone-native data management platforms.
Gyeonggi Province
Aging demographics in this corridor sustain volume demand for simplified meter interfaces among home-based Type 2 diabetes patients. National health insurance reimbursement schedules favor connected monitoring platforms in this region's dense hospital network. Suwon and Yongin cities anchor the highest per-capita continuous glucose monitor adoption rates outside Seoul proper.
Busan-Ulsan Corridor
Budget-conscious patient segments in this southern region select basic electrochemical platforms where reimbursement co-payments constrain device selection. Underpenetrated diabetes screening infrastructure offers whitespace for point-of-care glucose system deployment. Ulsan's manufacturing zones are piloting non-invasive wrist-worn devices for workforce metabolic monitoring.
Daegu-Gyeongbuk
Community pharmacists in Daegu are piloting subscription-based meter leasing programs that reshape local distribution economics. Retail pharmacy foot traffic patterns here diverge from Seoul's digital-native districts. Gyeongsan city's hospital procurement networks standardize on Korean-manufactured test strip supplies.
Daejeon-Sejong
Government data-sharing standards create regulatory tailwind for cloud-connected monitoring platforms in this administrative hub. Sejong's smart city infrastructure integrates patient-generated glucose data into municipal health record pilots. Daejeon's research hospitals conduct clinical validation studies for MFDS software-as-medical-device classifications.
South Korea Self-Monitoring Blood Glucose Devices Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the enzyme electrode supply chain. The vendor base stratifies across three tiers: multinational diagnostics conglomerates with hospital channel partnerships, domestic manufacturers leveraging captive production cost structures, and specialized continuous monitoring entrants with sensor-transmitter ecosystems. Strategic archetypes include subscription-model platform operators, regional manufacturing anchors, and algorithm-integrated digital therapeutic developers. Competitive moves concentrate on firmware differentiation and cloud infrastructure partnerships rather than hardware specification races.
Among domestic manufacturers, i-Sens anchors pricing power through vertical control over test strip production. Roche Diabetes Care and Abbott Laboratories exemplify the multinational platform tier, occupying positions defined by Bluetooth-enabled meter ecosystems and specialized hospital channel access. These three entities represent the competitive structure: domestic cost leadership, multinational integration capability, and connected system architecture respectively.
| Leading Market Players |
|---|
| i-Sens |
| Roche Diabetes Care |
| Abbott Laboratories |
| Lifescan |
| Arkray |
| Dexcom |
| Medtronic |
| Ascensia Diabetes Care |
| Acon Laboratories |
| Others |
Pricing and Supply Chain Analysis
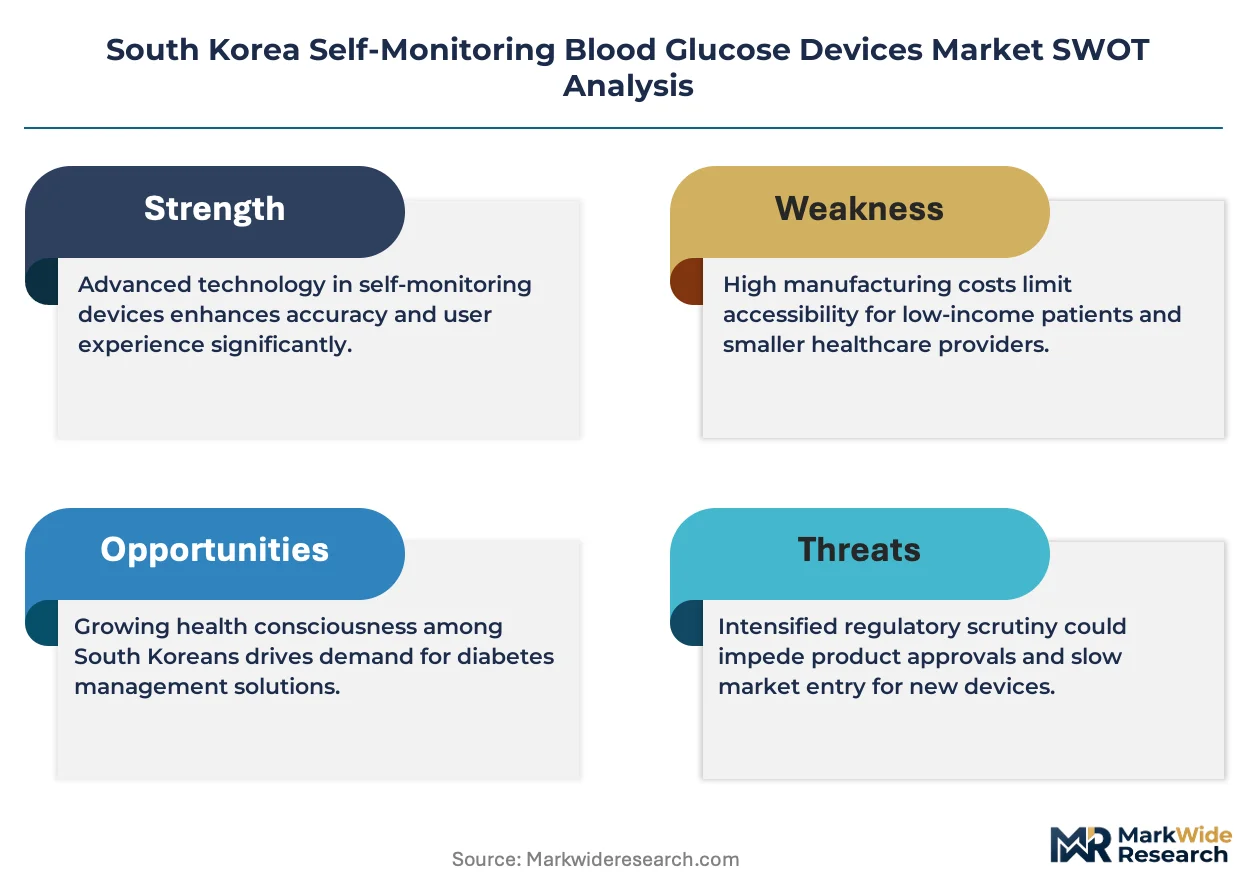
Overcapacity in domestic test strip manufacturing compresses margin capture for Korean producers while simultaneously enabling aggressive pricing postures against multinational meter entrants. This utilization dynamic forces i-Sens and domestic competitors to anchor pricing power through captive enzyme electrode production rather than hardware specification races.
Pricing Analysis
The customization-premium spread separates Bluetooth-enabled connected meters from basic electrochemical platforms by roughly two-to-three co-payment tiers under MFDS reimbursement schedules. Subscription-based leasing for continuous glucose monitor hardware now dominates the premium pricing model, while per-unit transactional sales of test strips anchor the volume tier. Price differentiation hinges on MFDS software-as-medical-device certification status and hospital network procurement scale, with tertiary care centers in Seoul showing least price sensitivity and Busan-Ulsan corridor patients facing highest co-payment burdens. Pricing pressure stems from national health insurance reimbursement recalibration on recurring consumable expenses.
Supply Chain Analysis
Upstream feedstock for precision glucose oxidase enzymes concentrates among Japanese and German specialty chemical suppliers, creating import dependency for Korean test strip manufacturers. The supply chain draws from enzyme electrode chemistry in Japan, polymer substrates from Germany, and semiconductor components for transmitter units from Taiwan and South Korea itself. Single-source vulnerability around electrochemical sensor feedstock represents the dominant structural risk. Distribution runs through retail pharmacy networks for consumable replenishment, with direct-shipping subscription models capturing fastest channel shift momentum among younger diabetic cohorts in Seoul's digital-native districts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in underpenetrated diabetes screening infrastructure and algorithm-integrated platform niches as patient data management migrates from meter-native displays to smartphone-native ecosystems.
For Market Incumbents: Pre-empt subscription-model platform consolidation by securing cloud infrastructure partnerships before telehealth platforms capture refill loyalty. Anchor backward integration into enzyme electrode chemistry to defend margin position against import cost volatility. Prioritize firmware differentiation over hardware specification races as MFDS software-as-medical-device classification tightens validation timelines for algorithm-driven features. For New Entrants and Emerging Players: Busan-Ulsan corridor underpenetration offers whitespace for point-of-care glucose system deployment with simplified meter interfaces targeting budget-conscious patient segments. Daegu-Gyeongbuk's community pharmacy subscription pilot programs provide a replicable go-to-market template for meter leasing economics. Flash glucose monitoring adoption gaps among insulin-dependent users outside Gyeonggi Province's dense endocrinology corridor represent the most penetrable technology segment. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among connected monitoring platform operators with established hospital channel partnerships in Seoul's tertiary care network. Long-term viability across the analysis window favors acquisition targets with demonstrated MFDS certification velocity and captive test strip production capacity. The signal to watch is MFDS reimbursement policy recalibration toward preventive digital therapeutics classification, which would revalue algorithm-integrated platform assets.| Strategic Initiative | Industry Significance |
|---|---|
| MFDS Software-as-Medical-Device Certification | Accelerates market entry for app-integrated glucose monitors by streamlining validation timelines. |
| Hospital System Partnership | Secures prescription volume concentration in Seoul's tertiary care endocrinology networks. |
| Cloud Infrastructure Integration | Enables National Health Record interoperability mandated by government data-sharing standards. |
| Enzyme Electrode Backward Integration | Reduces import dependency on Japanese and German specialty chemical suppliers. |
| Subscription Direct-Shipping Model | Captures refill loyalty as retail pharmacy foot traffic declines in digital-native districts. |
Research Methodology
The analysis maps glucose meter hardware, continuous glucose monitor systems, test strip consumables, and algorithm-integrated platforms, each validated through endocrinologists, hospital purchasing committees, biomedical engineers, and GPO contracts managers. Primary interviews with these stakeholders combined with secondary validation against MFDS device approval databases, National Health Insurance Service reimbursement schedules, hospital procurement records, and trade customs data. Bottom-up and top-down triangulation reconciles manufacturer shipment data with patient population estimates and prescription volume patterns.
Assumptions held fixed include MFDS regulatory pathway timelines, National Health Insurance reimbursement tier structures, and incumbent hospital channel access patterns; variables tested include digital therapeutics classification evolution and patient migration rates to smartphone-native data management. The forecast framework segments by product type, technology tier, end-user setting, and distribution channel, with CAGRs derived from installed base expansion rates and replacement cycle compression. Industry-specific inputs include diabetes prevalence projections by age cohort and connected device adoption curves from tertiary hospital prescription data.
The forecast holds incumbent behavior within observed patterns; aggressive moves by telehealth platform entrants or non-invasive sensing technology developers would shift outcomes beyond modeled ranges. Specific risk factors include MFDS electromagnetic compatibility validation delays, enzyme electrode supply disruptions, and reimbursement recalibration on consumable cost structures. Cross-checking against National Health Insurance Service expenditure trend data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Malaysia Insulin Infusion Pump Market
Diabetes Care
Russia Self-Monitoring Blood Glucose Devices Market
Diabetes Care
France Insulin Infusion Pump Market
Diabetes Care
India Continuous Glucose Monitoring (CGM) Market
Diabetes Care
Europe Insulin Infusion Pumps Market
Diabetes Care
Global Diabetic Foot Ulcer Treatment Market
Diabetes Care
Diabetes Injection Pens Market
Diabetes Care
Europe Diabetic Foot Ulcer Treatment Market
Diabetes Care
Germany Digital Diabetes Management Market
Diabetes Care
Diabetic Ketoacidosis Treatment Market
Diabetes Care
Self-Monitoring Blood Glucose (SMBG) Market
Diabetes Care
Alternatives for Injectable Diabetes Care Market
Diabetes Care
Type 2 Diabetes Drugs and Devices Market
Diabetes Care
Global Proliferative Diabetic Retinopathy Market
Diabetes Care
Internet of Things for Diabetes Market
Diabetes Care
Spain Self-Monitoring Blood Glucose Devices Market