
 Homecare Surgical Drains Market | 2026-2036
Homecare Surgical Drains Market Size, Share, and Industry Trends Forecast 2026-2036
Homecare Surgical Drains Market Analysis
The capital-intensity gap between integrated manufacturers and assembly-only competitors is collapsing as automated silicone molding and sterile packaging investments become table stakes. BD leverages captive polymer compounding capabilities to sustain margin structures across closed drainage portfolios. Cardinal Health anchors North American distribution through direct-to-home logistics networks that bypass traditional hospital procurement channels.
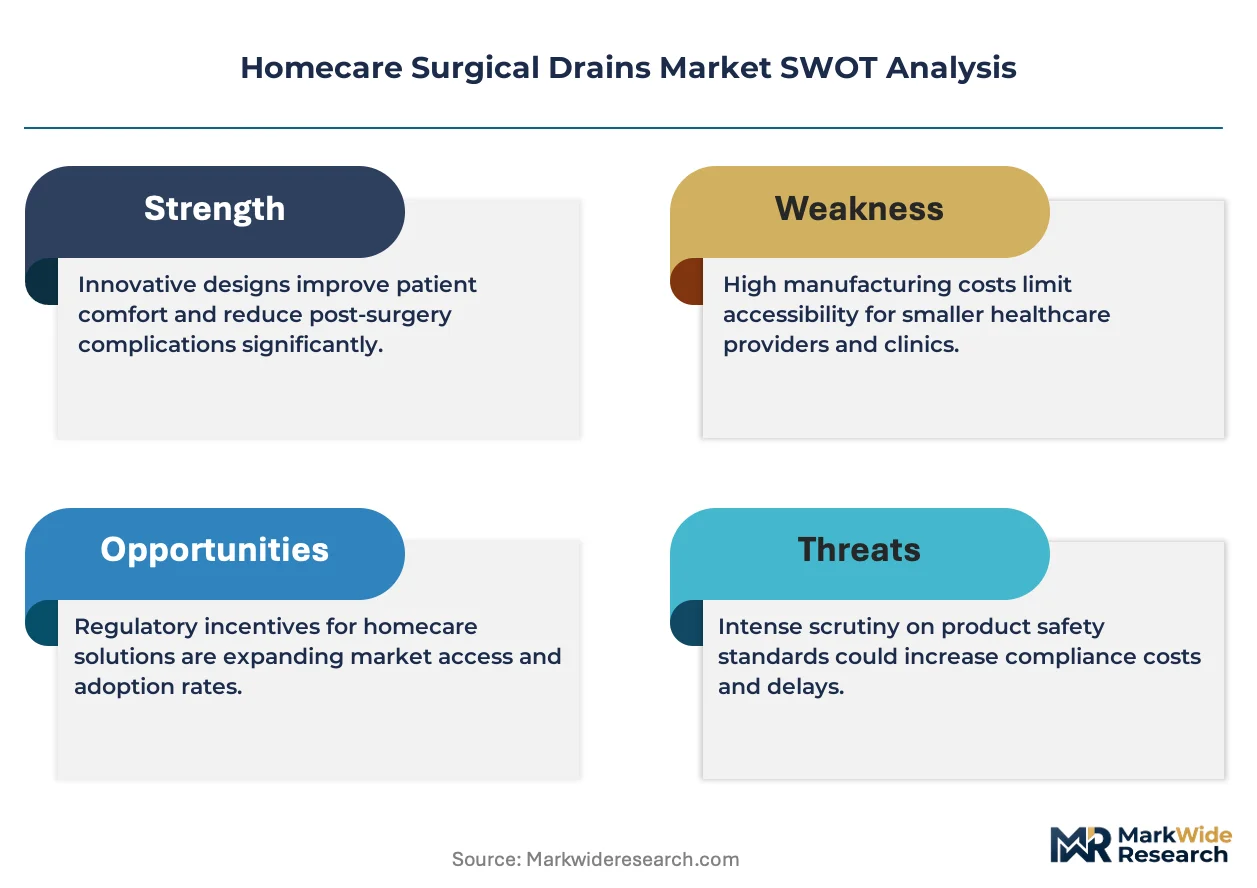
Homecare surgical drains are closed or open reservoir systems—typically constructed from medical-grade silicone, PVC, or polyurethane with graduated collection chambers and anti-reflux valves—designed to evacuate serous fluid, blood, or purulent material from post-operative wound sites in non-acute settings. Silicone-based closed drainage systems dominate premium positioning due to biocompatibility and extended indwelling tolerance, while PVC alternatives occupy cost-sensitive segments where shorter dwell times apply. Active drainage systems with negative pressure mechanisms represent the fastest-expanding category as home health agencies adopt portable suction technologies previously restricted to inpatient wards.
The FDA regulates these devices under Class II medical device pathways requiring 510(k) premarket notification, while the EU Medical Device Regulation imposes stricter clinical evidence thresholds for home-use claims through notified body conformity assessments. These frameworks compel manufacturers to generate home-environment usability data that hospital-only products never required, raising barriers for entrants lacking regulatory infrastructure. Stakeholders must monitor evolving reimbursement coding for home drainage management as payors scrutinize whether reduced readmission rates justify device expenditure against standard wound care protocols.
Market Dynamics
Early hospital discharge protocols are compressing the transition window for surgical drainage from inpatient to home settings, forcing manufacturers to redesign devices for unsupervised patient use without clinical backup.
Growth Catalysts
- Negative pressure wound therapy:Portable suction devices are migrating from hospital wards to home health agency inventories, expanding the addressable patient population beyond traditional passive drainage candidates.
- 510(k) home-use pathway:The FDA's streamlined premarket notification for ambulatory drainage systems reduces regulatory friction for device modifications targeting non-acute environments.
- Silicone biocompatibility:Extended indwelling tolerance of medical-grade silicone enables longer dwell times, reducing intervention frequency and total cost of ownership for payors.
Market Restraints
- Medical-grade silicone supply:Concentration of polymer compounding capacity among three North American suppliers creates input cost volatility and allocation risk during demand surges.
- EU MDR clinical evidence thresholds:Stricter notified body conformity assessments for home-use claims extend time-to-market by 18-24 months compared to hospital-only devices.
- Standard wound care protocols:Conservative clinical practice guidelines in several European markets treat surgical drains as inpatient-only interventions, limiting reimbursement eligibility.
Strategic Opportunities
- Remote patient monitoring integration:Bluetooth-enabled collection chambers transmitting fluid volume data to home health platforms enable proactive intervention and reduce emergency readmissions.
- India's surgical infrastructure expansion:Government hospital capacity building under the Ayushman Bharat scheme is creating downstream demand for post-discharge drainage management in tier-2 cities.
- Japan's aging demographic:METI incentives for home medical device innovation align with hospital bed reduction targets, opening reimbursement pathways for ambulatory drainage systems.
Industry Challenges
- Human factors engineering:Designing anti-reflux valves and chamber emptying mechanisms for arthritic or vision-impaired patients without caregiver assistance requires specialized usability testing protocols.
- Cross-border sterilization validation:Gamma irradiation dose mapping must be repeated for each sterile packaging configuration across regional manufacturing sites, complicating supply chain consolidation efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Homecare Surgical Drains Market |
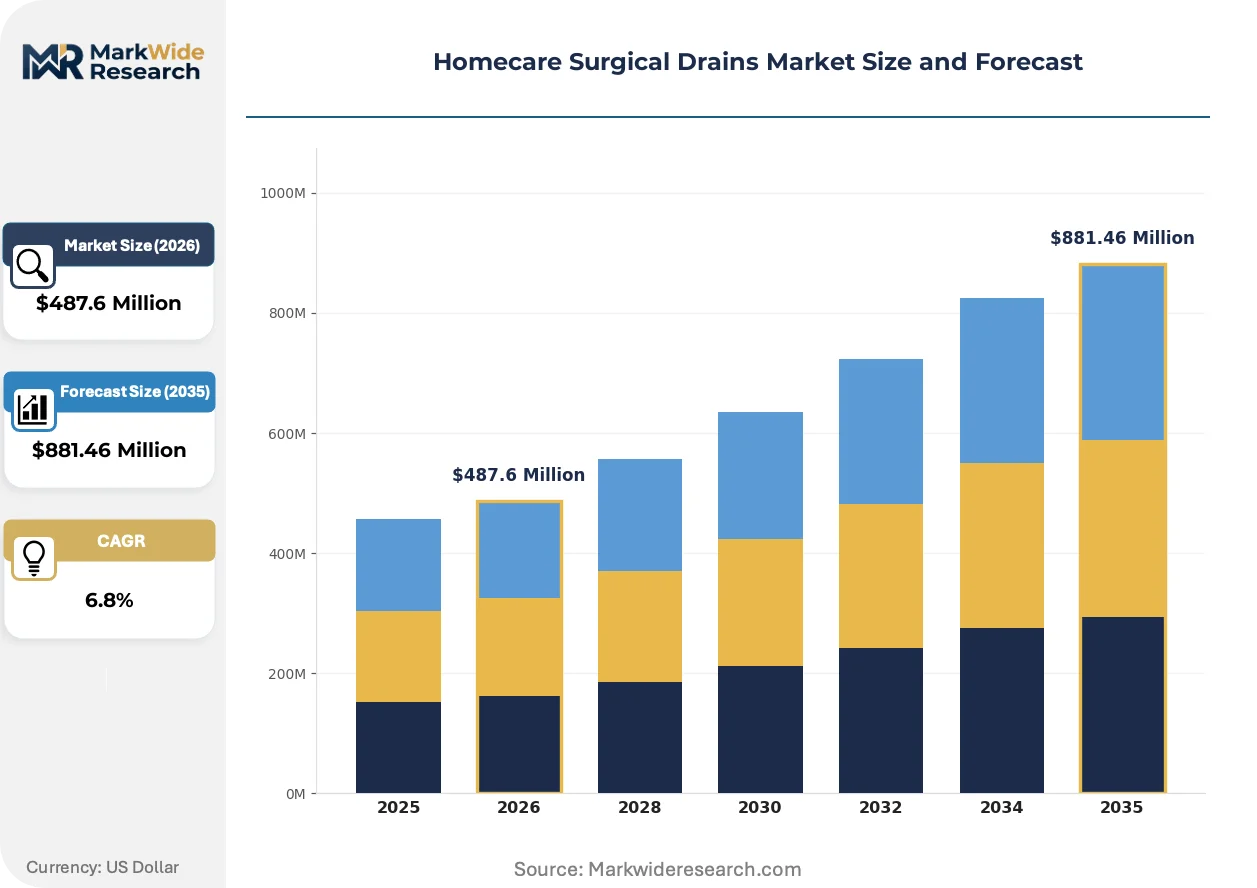
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Closed Drainage Systems, Open Drainage Systems, Passive Drainage Systems, Active Drainage Systems Material: Silicone, PVC, Polyurethane, Latex Capacity: Low Volume, Medium Volume, High Volume, Ultra High Volume Application: Post-Surgical Care, Wound Management, Drainage Management, Infection Prevention |
| Companies Covered | Cardinal Health, BD, B. Braun Melsungen AG, ConvaTec Inc., Medtronic, Stryker, Smith & Nephew plc, Redax, Cook Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Homecare Surgical Drains Market Emerging Trajectories
Active drainage mechanisms are displacing passive gravity-dependent systems as the default technology for post-operative home care, compressing the performance gap between hospital-grade and ambulatory devices.
Miniaturized diaphragm pumps with battery capacities exceeding 72 hours of continuous operation are miniaturizing negative pressure systems into wearable formats. Home health agencies in the United States are adopting these devices for oncology and orthopedic post-surgical cases previously requiring extended inpatient stays. The technology is miniaturizing the physical footprint of active drainage, enabling patient mobility and reducing the clinical labor intensity of home visits.
The EU Medical Device Regulation's usability engineering requirements are mandating human factors validation studies for all devices with home-use labeling. Manufacturers must demonstrate safe operation by lay caregivers through simulated use testing, adding development cost but reducing liability exposure. Closed drainage systems with integrated anti-reflux mechanisms face the steepest compliance burden due to their higher risk classification.
Hospital procurement departments are unbundling drainage device selection from surgical supply contracts, creating direct purchasing relationships between home health agencies and manufacturers. This channel disintermediation is fragmenting volume concentration and enabling specialized vendors to compete on device-specific outcomes rather than bundled pricing. The United States exhibits the most pronounced shift, where Medicare Advantage plans are steering patients toward agency networks with demonstrated readmission reduction metrics.
Homecare Surgical Drains Market Segmentation
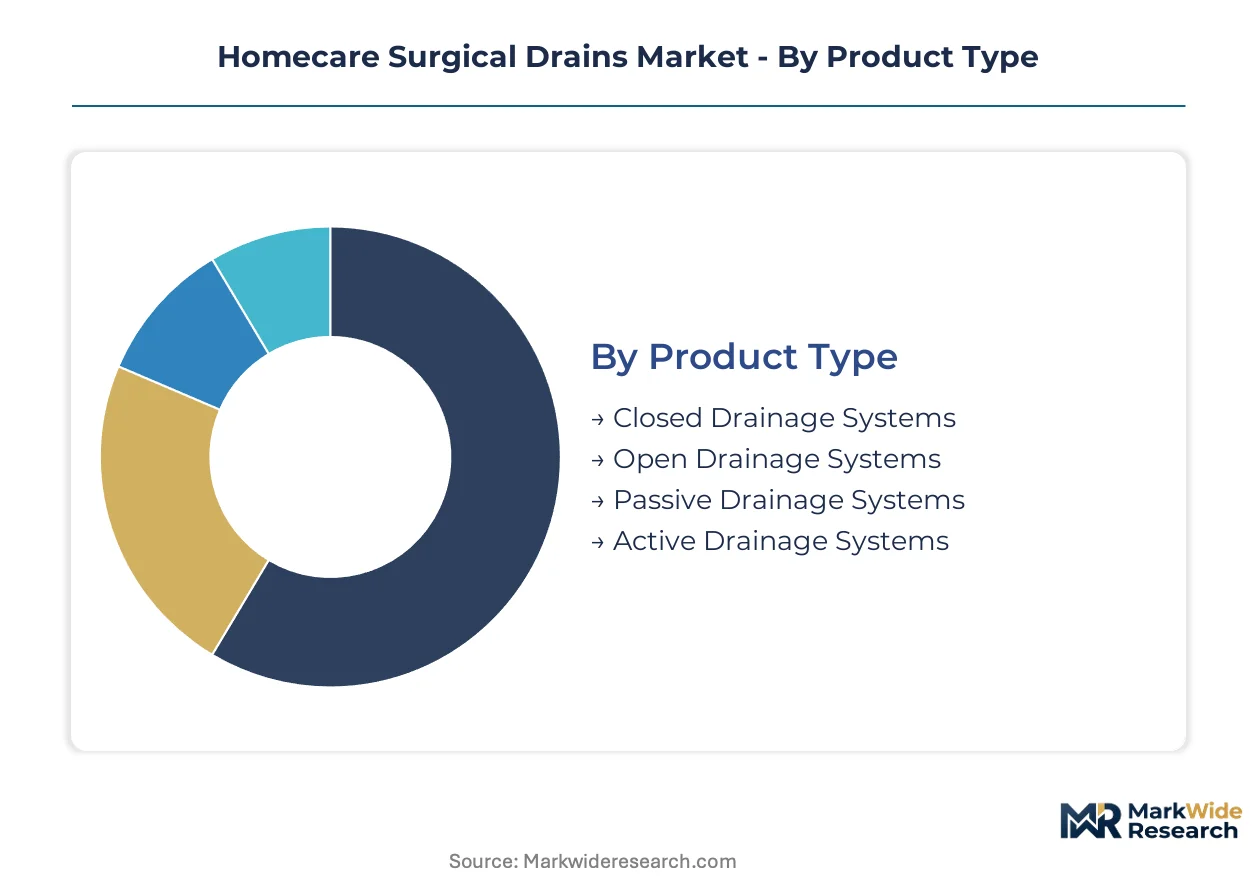
Segmentation in homecare surgical drains reveals distinct technology-material pairings that determine reimbursement eligibility and patient self-management feasibility. Each dimension carries regulatory implications that reshape competitive positioning across ambulatory care channels.
Product Type:
Closed drainage systems dominate domestic hospital discharge protocols in the United States, while active systems with portable suction drive export-led demand from European home health agencies seeking mobility-enabled recovery.
- Closed Drainage Systems:Reservoir chambers with anti-reflux valves prevent backflow contamination during patient mobility. Demand concentrates in United States Medicare Advantage networks where readmission reduction metrics determine contract eligibility. Silicone construction enables 7-14 day indwelling tolerance without irrigation.
- Active Drainage Systems:Battery-powered negative pressure mechanisms evacuate fluid through controlled suction previously restricted to inpatient wards. German and Dutch home health agencies are adopting these devices for oncology resections, expanding the addressable population beyond gravity-dependent candidates. Miniaturized diaphragm pumps now sustain 72-hour operation in wearable formats.
- Open Drainage Systems:Gravity-dependent collection without sealed chambers suits shorter post-operative windows where caregiver supervision remains available.
- Passive Drainage Systems:Simple tubing-to-container designs occupy cost-sensitive segments in emerging markets with limited reimbursement infrastructure.
Closed drainage commands the established base. The steepest expansion runs through active drainage systems.
Material:
Material selection stratifies across cost tiers: silicone anchors premium positioning through biocompatibility, while PVC and latex serve price-sensitive procurement in volume-contracted segments.
- Silicone:Medical-grade polymer with inert surface chemistry minimizes tissue adhesion and enables extended dwell times. United States payors favor silicone-based closed systems for total cost-of-ownership calculations despite higher unit pricing. Three North American suppliers concentrate compounding capacity, creating allocation risk during demand surges.
- Polyurethane:Alternative elastomer with tear resistance for active drainage tubing subjected to patient movement stress. Japanese manufacturers are developing thinner-walled variants for wearable pump integration under METI home medical device incentives.
- PVC:Cost-optimized polymer for short-duration drainage where 48-72 hour dwell limits apply. Dominates Indian tier-2 city procurement under government hospital capacity building programs.
- Latex:Declining share due to allergen concerns; residual demand persists in legacy contract structures and certain emerging markets with limited regulatory enforcement.
Silicone captures margin concentration in reimbursed channels. Polyurethane is climbing fastest through active drainage adoption.
Capacity:
Capacity requirements map directly to surgical procedure type and discharge timing, with medium and high volume segments serving the core orthopedic and abdominal surgery populations.
- High Volume:400-800ml chambers address abdominal and thoracic procedures with substantial serous output. United States home health agencies stock these formats for oncology and bariatric surgery discharges where fluid accumulation risks readmission.
- Medium Volume:200-400ml range serves orthopedic joint replacement protocols, the largest procedure category in ambulatory drainage. German statutory health insurance reimbursement codes specifically reference this capacity band for standard hip and knee arthroplasty aftercare.
- Low Volume:Sub-200ml formats for minor procedures and pediatric applications where output volumes remain minimal.
- Ultra High Volume:Exceeding 800ml for complex oncologic resections with extended drainage requirements; limited to specialized home health networks with clinical oversight capabilities.
Medium volume holds the procedural volume base. High volume is expanding most quickly through earlier discharge of complex cases.
Application:
Application segmentation reflects reimbursement coding evolution, with post-surgical care and wound management representing distinct billing pathways in United States and European systems.
- Post-Surgical Care:Procedure-specific drainage protocols following hospital discharge. United States CMS reimbursement for home health episodes includes device supply when bundled with skilled nursing visits, creating volume concentration through agency networks.
- Drainage Management:Technical service layer encompassing device maintenance, emptying protocols, and complication triage. Dutch and Belgian home care organizations are certifying specialized drainage nurses, differentiating service offerings beyond commodity device supply.
- Wound Management:Broader category incorporating negative pressure wound therapy systems that overlap with surgical drain functionality. FDA 510(k) pathways distinguish pure drainage from therapeutic wound devices, affecting labeling claims.
- Infection Prevention:Anti-reflux and closed system design features that reduce contamination risk; increasingly cited in EU MDR technical documentation for home-use device approvals.
Post-surgical care anchors reimbursement volume. Drainage management services are gaining share fastest through nursing specialization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of medical-grade silicone drainage systems concentrate from North American and European manufacturing bases toward Asia-Pacific healthcare systems building post-surgical home care capacity. Import dependence for polymer compounding inputs shapes regional production economics and device pricing structures.
United States
Medicare Advantage readmission reduction metrics drive home health agency procurement of closed drainage systems with remote monitoring capabilities. FDA 510(k) premarket notifications for ambulatory-use labeling enable faster device modifications than hospital-only pathways. Minneapolis and Cleveland host specialized manufacturing clusters where BD and Medtronic maintain captive polymer compounding operations.
Germany
Statutory health insurance reimbursement codes for medium-volume drainage chambers anchor European demand for orthopedic post-surgical care. EU MDR notified body conformity assessments extend approval timelines for home-use claims by 18-24 months versus hospital-only devices. The Rhine-Ruhr industrial corridor concentrates sterile packaging and gamma irradiation validation services for regional manufacturers.
Japan
METI incentives for home medical device innovation align with hospital bed reduction targets under national healthcare cost containment policies. PMDA streamlined reviews for wearable negative pressure systems accelerate market entry for miniaturized active drainage technologies. Osaka-based manufacturers develop thinner-walled polyurethane tubing variants for portable pump integration.
India
Ayushman Bharat government hospital capacity building generates downstream demand for post-discharge drainage management in tier-2 cities lacking specialized home health infrastructure. CDSCO medical device rules classify surgical drains as Class B or C depending on indwelling duration, affecting import licensing requirements. Ahmedabad and Mumbai medical device clusters specialize in PVC-based cost-optimized systems for 48-72 hour dwell protocols.
Netherlands
Home care organizations certify specialized drainage nurses, differentiating service offerings beyond commodity device supply and creating pull-through demand for technical training-compatible systems. Health Insurance Act reimbursement bundles favor closed systems with anti-reflux mechanisms that reduce complication triage frequency. Eindhoven's medical technology ecosystem supports human factors engineering validation for EU MDR usability requirements.
Homecare Surgical Drains Market Vendor Landscape
Concentration sits with diversified medical device conglomerates possessing captive polymer supply chains and established hospital procurement relationships. Three to five integrated manufacturers control premium silicone drainage segments, while assembly-focused competitors occupy cost-sensitive PVC categories. Strategic archetypes include vertically integrated polymer compounders, sterile packaging specialists with distribution scale, and negative pressure technology licensors. Competitive moves center on M&A for regulatory infrastructure acquisition and capacity expansion into gamma irradiation sterilization services.
Among North American diversified manufacturers, Cardinal Health and BD exemplify the integrated archetype combining polymer compounding with direct-to-home logistics networks. B. Braun Melsungen AG anchors European positioning through German engineering reputation and MDR compliance infrastructure. These three occupy positions where regulatory barrier height and capital intensity filter out assembly-only entrants lacking sterile packaging validation capabilities.
| Leading Market Players |
|---|
| Cardinal Health |
| BD |
| B. Braun Melsungen AG |
| ConvaTec Inc. |
| Medtronic |
| Stryker |
| Smith & Nephew plc |
| Redax |
| Cook Medical |
| Others |
Supply Flow & Price Mechanics
Captive polymer compounding capacity among three North American suppliers anchors scale economies that simultaneously concentrate supply power and establish price floors for silicone-based closed drainage systems. This concentration pattern forces assembly-only competitors to absorb margin compression or cede premium positioning to integrated manufacturers with in-house resin production.
Pricing Analysis
Home health agencies anchor pricing stratification across premium, standard, and economy tiers based on reimbursement eligibility and clinical outcome requirements. Price differentiation rests on FDA 510(k) home-use certification status and silicone biocompatibility grade, with Medicare Advantage networks least sensitive to unit cost when readmission reduction metrics are demonstrable. Pricing pressure stems from PVC alternatives penetrating cost-sensitive discharge protocols where shorter dwell times apply.
Supply Chain Analysis
Six-to-eight week lead times for medical-grade silicone resin reflect concentrated compounding capacity in the United States, Germany, and Japan. Raw material dependencies center on platinum-cured silicone elastomers, anti-reflux valve membranes, and gamma-sterilizable packaging films. Single-source vulnerability in North American polymer supply creates allocation risk during demand surges. Distribution runs through direct-to-home logistics networks that bypass traditional hospital procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward home health agencies as hospital procurement departments unbundle drainage device selection from surgical supply contracts, fragmenting volume concentration and enabling outcome-based contracting.
For Market Incumbents: Consolidate regulatory infrastructure advantages by acquiring sterile packaging validation capabilities and gamma irradiation service providers. Defend premium positioning through backward integration into silicone compounding, countering emerging entrants lacking MDR-compliant usability engineering resources. For New Entrants and Emerging Players: FDA 510(k) streamlined home-use pathways offer fastest market entry for portable negative pressure systems targeting oncology resection discharge protocols. White-space opportunities concentrate in India's tier-2 cities under Ayushman Bharat capacity building and Japanese wearable pump integration under METI incentives. Go-to-market leverage rests on human factors engineering validation for arthritic patient populations. For Investors and Strategic Acquirers: Specialized drainage nurse certification platforms in the Netherlands and Belgium represent acquisition targets with service-layer differentiation. Long-term viability favors manufacturers combining polymer compounding with remote patient monitoring software integration. Watch for Medicare Advantage plan readmission reduction metric thresholds as inflection indicators for device reimbursement eligibility.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Usability Engineering Investment | EU notified body conformity assessments for home-use claims require simulated lay caregiver testing protocols. |
| Silicone Compounding Backward Integration | Captive resin production insulates margin structures from three-supplier concentration risk in North America. |
| Bluetooth-Enabled Chamber Development | FDA 510(k) submissions for fluid volume telemetry align with Medicare Advantage remote monitoring reimbursement. |
| Gamma Irradiation Capacity Expansion | Regional sterilization validation services reduce cross-border dose mapping repetition for packaging configurations. |
| Direct-to-Home Logistics Partnership | Bypassing hospital procurement channels captures agency network volume under bundled episode payment models. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with home health agency procurement directors, biomedical engineers, GPO contracts managers, and FDA regulatory consultants; and secondary validation against FDA 510(k) premarket notification databases, CMS Medicare home health episode data, EU MDR notified body conformity assessment records, and hospital procurement contract repositories. Bottom-up volume modeling triangulated with top-down reimbursement expenditure analysis.
Across the projection horizon, the analytical framework modeled segmentation across product type, material grade, capacity tier, application pathway, and regional regulatory cluster. CAGRs derived from procedure volume forecasting, discharge timing elasticity estimates, and payor reimbursement code evolution. Industry-specific inputs included Medicare Advantage readmission reduction metric weightings and EU MDR approval timeline differentials between home-use and hospital-only device pathways.
The analysis sits within stated boundaries; outcomes outside stable FDA 510(k) review timelines and unchanged Medicare home health episode bundling would require recalibration. Forecasts reflect assumptions regarding silicone resin supply allocation continuity and statutory health insurance reimbursement stability in Germany and the Netherlands. Revision becomes warranted when EU MDR notified body capacity constraints cross thresholds extending approval timelines beyond modeled ranges.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Ischemic Stroke Surgery Market
Surgical Instruments
US Surgical Staplers Market
Surgical Instruments
US Surgical Sutures Market
Surgical Instruments
Absorbable Surgical Suture with Needle Market
Surgical Instruments
Surgical Lamps Market
Surgical Instruments
Minimally Invasive Gastrointestinal Surgical System Market
Surgical Instruments
Cheilectomy Market
Surgical Instruments
Resectoscopes Market
Surgical Instruments
Corneal Transplantation Surgical Instrument Package Market
Surgical Instruments
Surgical Sphincteroplasty Market
Surgical Instruments
Gynecology Surgical Instruments Market
Surgical Instruments
Saudi Arabia General Surgical Devices Market
Surgical Instruments
Global Surgical Case Carts Market
Surgical Instruments
Surgical Drains Market
Surgical Instruments
Robotic Surgery Market
Surgical Instruments
Laparoscopic Power Morcellators Market