
 Latin America Diabetes Care Devices Market | 2026-2036
Latin America Diabetes Care Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Diabetes Care Devices Market Foresight
Aftermarket service revenue for legacy blood glucose meters is narrowing as patients migrate toward subscription-based continuous monitoring platforms. Abbott Laboratories leverages its FreeStyle Libre ecosystem to dominate pharmacy and direct-to-consumer channels across Brazil and Mexico. Medtronic PLC sustains its installed base of insulin pump users through specialized training programs and clinic partnerships. Dexcom Inc. differentiates via G-series sensor accuracy and integration with third-party insulin delivery systems.
Latin America diabetes care devices encompass instruments for glucose measurement, insulin delivery, and metabolic data management, typically operating via electrochemical enzymatic reactions in test strips or subcutaneous interstitial fluid sampling with wireless telemetry to handheld receivers or smartphones. Their primary purpose is enabling glycemic control and hypoglycemia prevention for Type 1 and Type 2 diabetes patients outside centralized clinical settings. Continuous glucose monitors lead technology adoption due to real-time alerting and reduced fingerstick burden, while blood glucose meters retain volume in public health systems with constrained reimbursement. Homecare settings represent the fastest-growing end user segment as telemedicine protocols and pharmacy-based diabetes coaching expand across the region.
ANVISA governs medical device registration and post-market surveillance in Brazil, requiring clinical evidence for connected diabetes devices that slows market entry but elevates product quality benchmarks. COFEPRIS in Mexico and INVIMA in Colombia enforce comparable conformity assessment pathways, with harmonization efforts through the Mercosur and PAHO regulatory forums gradually reducing redundant testing burdens. Stakeholders must monitor reimbursement list updates and digital health integration mandates as public payers across Latin America evaluate cost-effectiveness frameworks for sensor-augmented pump therapy.
Market Dynamics
Subscription-based continuous glucose monitoring platforms are compressing legacy blood glucose meter revenue streams across Brazil, Mexico, and Argentina as patients abandon one-time device purchases for recurring sensor models.
Growth Catalysts
- ANVISA Digital Health Pathway:Brazil's streamlined registration for connected diabetes devices accelerates time-to-market for sensor-integrated pumps and mobile-enabled monitors.
- Pharmacy-based diabetes coaching:Retail chains across Mexico deploy certified educators who drive CGM attachment rates through point-of-care counseling.
- Southeast Brazil clinical density:São Paulo's concentration of endocrinology practices and private payer networks concentrates early adoption of closed-loop insulin delivery systems.
Market Restraints
- Sensor manufacturing concentration:Polymer substrate and enzyme reagent supply chains concentrate among Asian contract manufacturers, exposing Latin American assemblers to input volatility.
- COFEPRIS extended review timelines:Mexico's post-market surveillance requirements for connected devices add regulatory friction that delays reimbursement list inclusion.
- Legacy public procurement cycles:Blood glucose meter tenders in Brazil's SUS system lock hospitals into multi-year strip supply contracts that block CGM conversion.
Strategic Opportunities
- Argentina's underpenetrated CGM base:Economic stabilization and private insurance expansion create whitespace for direct-to-consumer sensor models in Buenos Aires and Córdoba.
- Telemedicine protocol integration:Remote patient monitoring mandates in Colombia and Chile position cloud-connected glucose data platforms for hospital-at-home contracts.
- AI-enabled predictive hypoglycemia alerts:Machine learning algorithms layered atop interstitial glucose streams differentiate next-generation offerings from basic threshold alarms.
Industry Challenges
- Certified diabetes educator scarcity:Training capacity for CGM onboarding and insulin pump titration lags device availability in secondary Brazilian cities.
- Interoperability standard fragmentation:Proprietary data protocols between sensor manufacturers and insulin pump controllers force clinics to maintain multiple software platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Diabetes Care Devices Market |
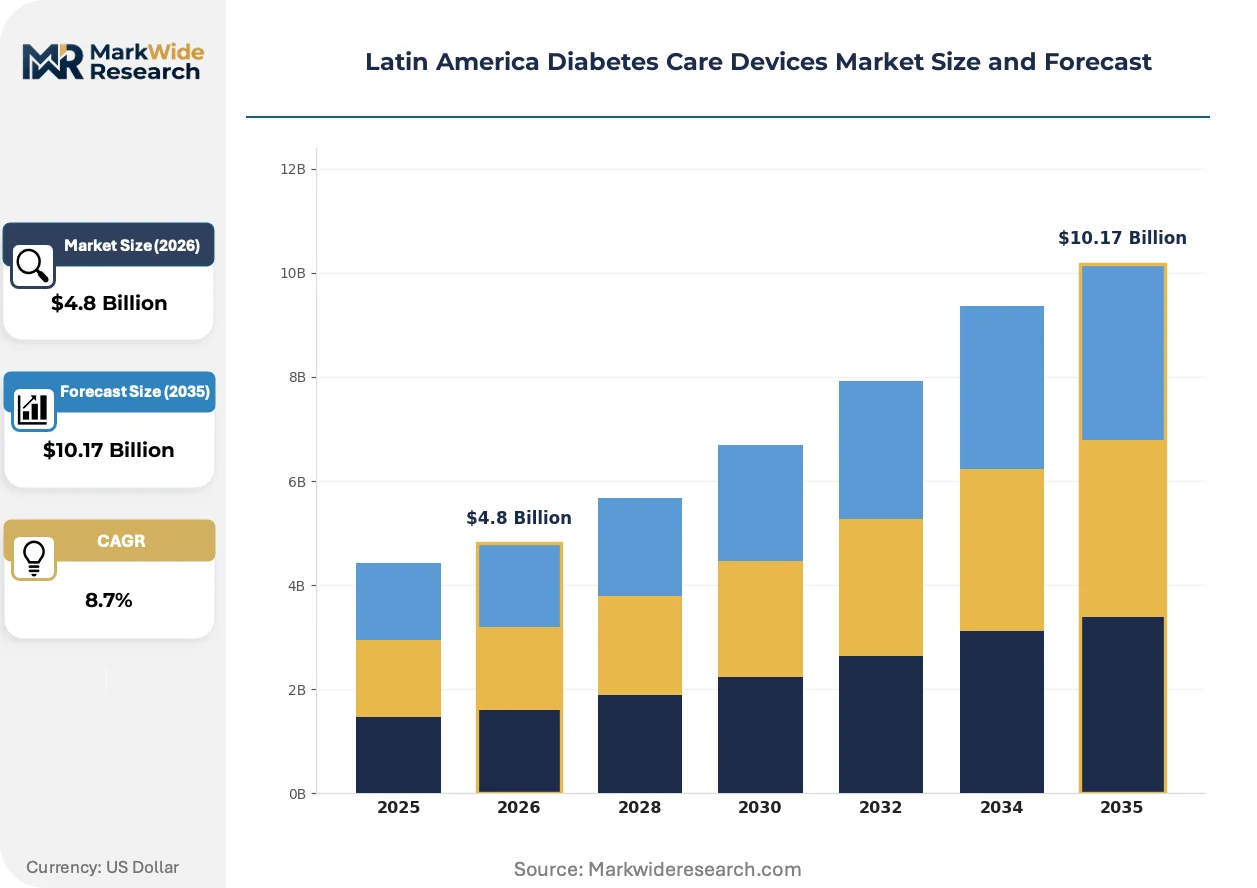
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blood Glucose Meters, Continuous Glucose Monitors, Insulin Pumps, Lancets End User: Hospitals, Clinics, Homecare Settings, Pharmacies Technology: Test Strips, Smart Devices, Wearables, Mobile Applications Distribution Channel: Retail Stores, Online Platforms, Direct Sales, Wholesalers |
| Companies Covered | Abbott Laboratories, Medtronic PLC, Roche Diagnostics, Johnson & Johnson, Novo Nordisk, Dexcom Inc., Terumo, Tandem Diabetes Care, Ascensia Diabetes Care, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Diabetes Care Devices Market Shifts & Advancements
Real-time glucose telemetry is reshaping how Latin American patients manage glycemic variability outside hospital walls, compressing the gap between consumer wearables and clinical-grade monitoring.
Non-adjunctive continuous glucose monitoring is migrating from fingerstick-calibrated sensors to factory-calibrated interstitial fluid systems that eliminate capillary blood confirmation. Type 1 diabetes patients in São Paulo and Mexico City adopt these systems fastest, with private endocrinology clinics reporting conversion rates above public hospital benchmarks. The technology is migrating from specialized diabetes centers toward pharmacy-initiated prescribing, compressing the traditional gatekeeper role of hospital-based specialists.
COFEPRIS and ANVISA are tightening cybersecurity validation requirements for connected diabetes devices, mandating penetration testing and software bill of materials disclosure. Manufacturers must demonstrate encrypted data transmission and over-the-air update integrity before market authorization. Sensor-integrated insulin pumps face the steepest compliance burden, with several submissions delayed for additional firmware documentation.
Patient data ownership preferences are shifting control toward smartphone-native applications that aggregate glucose, insulin, and lifestyle inputs across brands. Younger Type 1 cohorts in Brazil's Southeast region reject closed ecosystems, favoring platforms that export standardized data to third-party analytics tools. This behavior fragments brand loyalty and pressures device makers to open application programming interfaces that were historically proprietary.
Latin America Diabetes Care Devices Market Segmentation
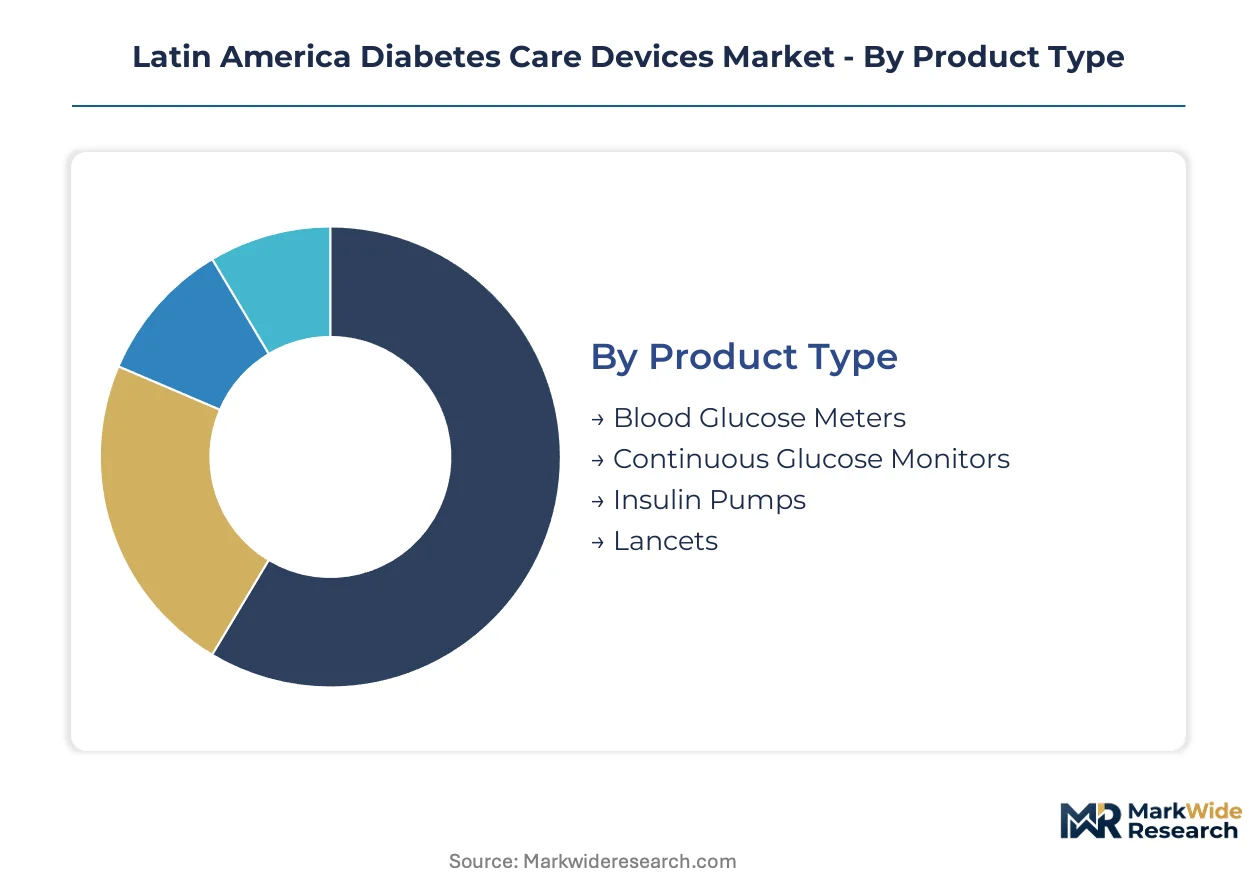
Segmentation in Latin American diabetes care reveals how reimbursement fragmentation and technology maturation create divergent commercial pathways across patient access tiers. Product type and end-user dynamics particularly expose where legacy devices retain volume versus where connected platforms capture margin expansion.
Product Type:
Maturity spans from commoditized consumables to emerging closed-loop systems, with revenue concentration shifting toward recurring sensor models.
- Blood Glucose Meters:Electrochemical enzymatic devices utilizing glucose oxidase or dehydrogenase chemistry on polymer test strips. Public procurement in Brazil's SUS system sustains volume through multi-year strip supply contracts that delay CGM conversion despite patient preference shifts.
- Continuous Glucose Monitors:Factory-calibrated interstitial fluid sensors with wireless telemetry to handheld receivers or smartphones. São Paulo's private endocrinology clinics drive fastest adoption as ANVISA's streamlined digital health pathway accelerates sensor-integrated pump approvals.
- Insulin Pumps:Motor-driven reservoir systems delivering basal-bolus therapy via subcutaneous infusion sets.
- Lancets:Spring-loaded puncture devices for capillary blood sampling, predominantly bundled with meter kits.
Blood Glucose Meters handles the majority of throughput; Continuous Glucose Monitors is the fastest mover on share.
End User:
Customer concentration maps directly to payer density and specialist availability across metropolitan corridors.
- Hospitals:Acute care settings managing diabetic ketoacidosis and perioperative glycemic control. Southeast Brazil's tertiary centers concentrate advanced pump therapy amid certified educator staffing constraints.
- Homecare Settings:Patient-directed management outside clinical facilities via telemedicine protocols. Pharmacy-based diabetes coaching across Mexico expands CGM attachment through point-of-care counseling at retail chains.
- Clinics:Outpatient endocrinology practices providing device titration and training.
- Pharmacies:Retail dispensing points increasingly prescribing connected devices directly.
Hospitals handles the majority of throughput; Homecare Settings is climbing the fastest on patient volume.
Technology:
Cost tiers separate disposable consumables from capital-intensive connected platforms with recurring revenue streams.
- Test Strips:Single-use enzymatic reagents producing electrochemical signals proportional to blood glucose concentration. Argentina's public health system maintains volume through centralized tender programs that favor lowest-unit-cost procurement.
- Smart Devices:Bluetooth-enabled meters and sensors transmitting data to cloud analytics platforms. Colombia's remote patient monitoring mandates position these for hospital-at-home contract expansion.
- Wearables:Body-worn interstitial sensors with adhesive patch interfaces.
- Mobile Applications:Smartphone-native software aggregating glucose, insulin, and lifestyle inputs across brands.
Test Strips handles the majority of throughput; Smart Devices is gaining share fastest on connectivity demand.
Distribution Channel:
Geography determines channel viability, with urban density enabling direct models and dispersed populations requiring intermediary layers.
- Retail Stores:Pharmacy chains and medical supply outlets with certified diabetes educators. Mexico's retail deployment of point-of-care counseling drives CGM conversion faster than hospital-based prescribing.
- Online Platforms:Direct-to-consumer sensor subscriptions bypassing traditional gatekeepers. Buenos Aires and Córdoba present whitespace for this model as Argentina's private insurance expansion stabilizes.
- Direct Sales:Manufacturer field forces targeting endocrinology practices and hospital systems.
- Wholesalers:Regional distributors serving secondary cities with limited manufacturer presence.
Retail Stores handles the majority of throughput; Online Platforms is expanding most quickly on subscription adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity fragments sharply across Latin America, with Argentina's inflation-scarred patients demanding direct-to-consumer subscription models while Brazil's Southeast corridor absorbs premium sensor-integrated pumps through dense private payer networks.
Brazil
ANVISA's streamlined digital health pathway accelerates connected device approvals, drawing sensor-integrated pump manufacturers toward São Paulo's concentration of endocrinology practices. The Southeast region anchors adoption, with tertiary centers managing complex Type 1 cases amid certified diabetes educator shortages in secondary cities. SUS procurement cycles for legacy blood glucose meters create friction against CGM conversion despite patient preference shifts.
Mexico
COFEPRIS post-market surveillance requirements delay reimbursement list inclusion for connected devices, compressing time-to-market advantages for early entrants. Pharmacy-based diabetes coaching at retail chains drives CGM attachment rates through point-of-care counseling, bypassing traditional hospital gatekeepers. Mexico City Metro concentrates private insurance density and specialist availability.
Argentina
Economic stabilization and private insurance expansion create whitespace for direct-to-consumer sensor models in Buenos Aires and Córdoba. Public health system tenders for test strips maintain volume through centralized lowest-unit-cost procurement, delaying smart device penetration. The underpenetrated CGM base offers conversion opportunity as subscription pricing models localize.
Colombia
INVIMA enforces conformity assessment pathways comparable to regional peers, with remote patient monitoring mandates positioning cloud-connected glucose platforms for hospital-at-home contracts. Telemedicine protocol integration accelerates adoption of Bluetooth-enabled meters transmitting data to cloud analytics platforms. Bogotá's clinical infrastructure concentrates early smart device deployment.
Chile
Regulatory harmonization through PAHO forums reduces redundant testing burdens for manufacturers entering the market. Private payer networks in Santiago support premium-tier continuous monitoring adoption, while public sector procurement maintains legacy meter volume. The country's digital health infrastructure maturity enables faster sensor-integrated pump uptake relative to regional peers.
Latin America Diabetes Care Devices Market Competitive Landscape
Capability concentration sits with sensor-integrated pump specialists; scale advantage sits with diversified diagnostics conglomerates with established pharmacy channel relationships. The market structures around three tiers: global device manufacturers with full-stack ecosystems, regional distributors with localized service networks, and emerging direct-to-consumer sensor platforms. Consolidation pressure intensifies as subscription models compress legacy meter aftermarket revenue. Dominant competitive moves include strategic partnerships with retail pharmacy chains and portfolio diversification into AI-enabled predictive analytics.
Within the full-stack ecosystem tier, Abbott Laboratories and Medtronic PLC exemplify divergent strategic positioning. Abbott leverages its FreeStyle Libre ecosystem to dominate pharmacy and direct-to-consumer channels across Brazil and Mexico. Medtronic sustains installed base loyalty through specialized training programs and clinic partnerships. Dexcom Inc. occupies a position differentiated by sensor accuracy and third-party insulin delivery system integration.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Medtronic PLC |
| Roche Diagnostics |
| Johnson & Johnson |
| Novo Nordisk |
| Dexcom Inc. |
| Terumo |
| Tandem Diabetes Care |
| Ascensia Diabetes Care |
| Others |
Supply & Pricing Matrix
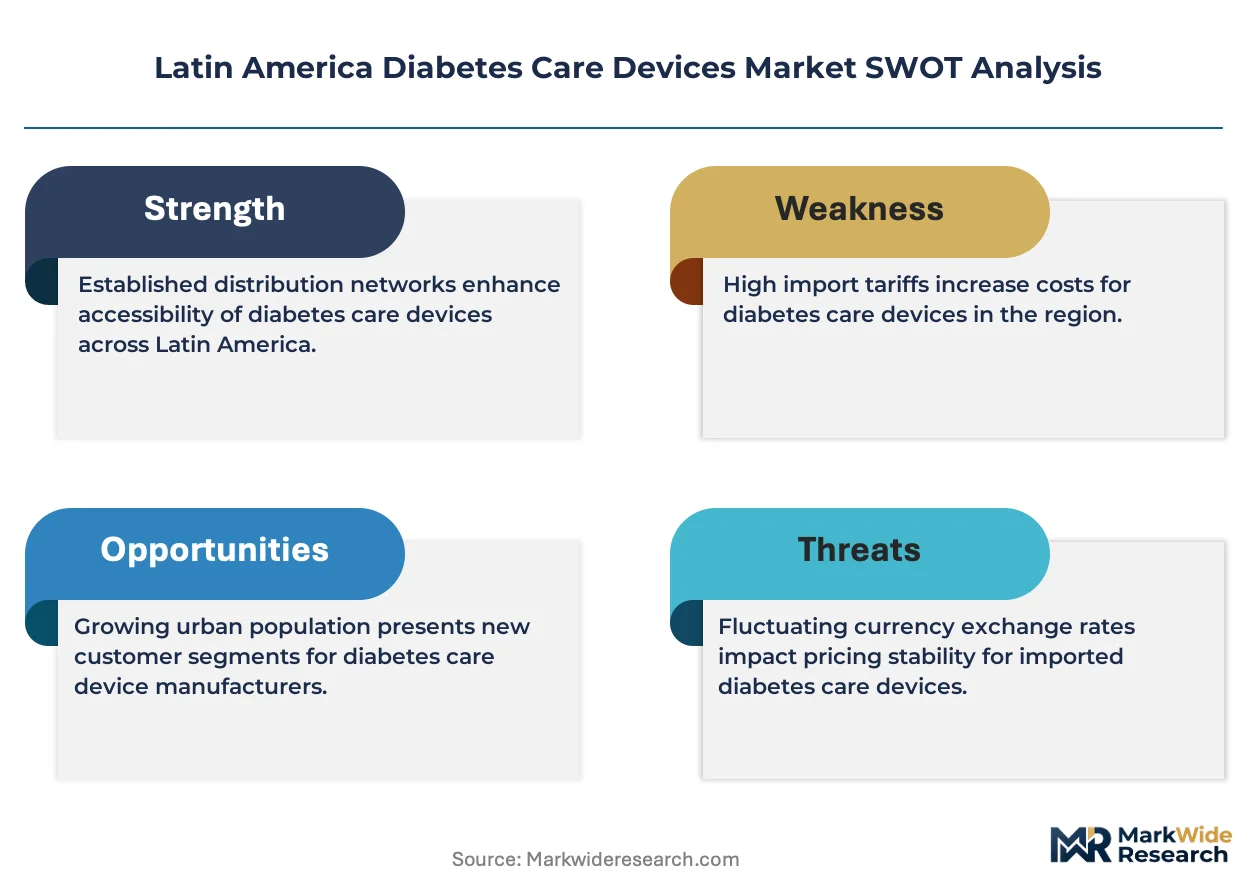
Undercapacity in Asian polymer substrate manufacturing is squeezing Latin American device assemblers into premium sourcing contracts that compress gross margins and force three-tier pricing stratification across premium, standard, and economy sensor tiers.
Pricing Analysis
Aftermarket service revenue for legacy blood glucose meters is narrowing as patients migrate toward subscription-based continuous monitoring platforms. Pricing stratifies across premium, standard, and economy tiers based on sensor accuracy certification and bundled diabetes educator support. Cost compression in the legacy meter segment is intensifying because public procurement tenders favor lowest-unit-cost suppliers. Price-sensitive public health systems in Brazil's SUS demonstrate highest sensitivity, while private payer networks in São Paulo absorb premium sensor-integrated pump pricing.
Supply Chain Analysis
Tariff exposure between China and Brazil dominates supply chain risk calculations for enzyme reagent and polymer substrate inputs. Manufacturing concentration centers on China, South Korea, and Japan for sensor membranes and wireless telemetry chipsets. Raw material dependencies include glucose oxidase biocatalysts, medical-grade adhesives, and lithium coin cell batteries. Single-source vulnerability in firmware programming for connected devices creates bottlenecks. Distribution runs through certified medical device distributors serving hospital systems and retail pharmacy chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated retail pharmacy chains across Mexico and Brazil, fragmenting traditional hospital gatekeeper control over device prescribing decisions.
For Market Incumbents: Insulate installed base loyalty through captive training programs for certified diabetes educators in secondary Brazilian cities. Deepen backward integration into sensor membrane manufacturing to reduce Asian contract manufacturer dependency. Defend against direct-to-consumer sensor platforms by locking exclusive pharmacy chain partnerships. For New Entrants and Emerging Players: Argentina's underpenetrated CGM base in Buenos Aires and Córdoba offers whitespace for subscription-based models bypassing hospital procurement. Target telemedicine-integrated cloud platforms for Colombia's hospital-at-home contracts. Pursue pharmacy-based diabetes coaching partnerships as the primary go-to-market angle. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among sensor-integrated pump specialists with software companion development capabilities. Long-term viability favors platforms demonstrating AI-enabled predictive hypoglycemia alert differentiation. Watch ANVISA reimbursement list updates for sensor-augmented therapy as the inflection indicator for market acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Digital Health Registration | Accelerates time-to-market for connected glucose monitors in Brazil's Southeast corridor. |
| Pharmacy Chain Partnership | Locks point-of-care counseling channels that drive CGM attachment rates in Mexico. |
| Sensor Manufacturing Backward Integration | Reduces input volatility from Asian polymer substrate suppliers. |
| Software Companion Development | Enables smartphone-native data aggregation that younger Type 1 patients demand. |
| Telemedicine Protocol Integration | Positions cloud-connected platforms for Colombia's hospital-at-home contracts. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with endocrinologists, hospital purchasing committee members, biomedical engineers, and retail pharmacy category managers. Secondary validation drew from ANVISA registration databases, COFEPRIS market authorization filings, hospital procurement tender records, and GPO contract repositories. Bottom-up patient population estimates and top-down device shipment data were triangulated to anchor volume projections.
Calibration against historical adoption curves for continuous glucose monitoring across Brazil, Mexico, and Argentina informed the analytical framework over the projection horizon. Segmentation dimensions modeled include product type, end-user setting, technology tier, and distribution channel complexity. CAGRs were derived from fitted growth curves applied to sensor penetration rates and insulin pump replacement cycles. Forecast inputs incorporated reimbursement list inclusion probabilities and certified diabetes educator training capacity expansion.
Macroeconomic conditions sit as an overlay; deviation in Argentine peso stability, Brazilian real exchange rates, or Mexican inflation would shift the trajectory of direct-to-consumer subscription adoption. Forecasts reflect assumptions regarding regulatory harmonization progress through PAHO forums and digital health integration mandates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Global Non-Invasive Blood Glucose Monitoring Devices Market
Diabetes Care
North America Diabetes Care Devices Market
Diabetes Care
Mexico Diabetes Medication Market
Diabetes Care
Mexico Diabetes Care Devices Market
Diabetes Care
Global Blood Glucose Test Strip Market
Diabetes Care
Middle East and Africa Blood Glucose Test Strip Market
Diabetes Care
Global Insulin Infusion Pumps Market
Diabetes Care
Indonesia Diabetes Care Devices Market
Diabetes Care
Japan Insulin Infusion Pump Market
Diabetes Care
Egypt Diabetes Care Devices Market
Diabetes Care
Wearable Glucometers Market
Diabetes Care
Middle East and Africa Diabetes Market
Diabetes Care
United Kingdom Continuous Glucose Monitoring Market
Diabetes Care
Middle East and Africa Continuous Glucose Monitoring Market
Diabetes Care
China Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Philippines Diabetes Care Devices Market