
 New Zealand Continuous Glucose Monitoring Devices Market | 2026-2036
New Zealand Continuous Glucose Monitoring Devices Market Size, Share, and Industry Trends Forecast 2026-2036
New Zealand Continuous Glucose Monitoring Devices Market Foresight
Market Context
New Zealand is tilting toward greater self-management of chronic conditions through subsidized wearable health technologies. Dexcom Inc leverages its real-time data ecosystem to sustain premium positioning among endocrinology practices. Abbott Diabetes Care Inc anchors the flash monitoring segment with pharmacy-distributed systems that bypass traditional clinic workflows. Medtronic PLC competes through hybrid closed-loop integrations that appeal to technologically engaged patient cohorts.
Technical Definition and Segment Structure
Continuous glucose monitoring devices are electrochemical or optical sensor systems that measure interstitial glucose concentrations through subcutaneous filaments, transmitting data to receivers or smartphones for trend analysis and insulin dosing decisions. Flash glucose monitors occupy the volume-dominant tier due to Pharmac subsidy eligibility and fingerstick replacement claims, while smartphone-compatible devices represent the fastest-expanding category as iOS and Android integrations normalize remote data sharing with general practitioners. Implantable sensors command concentrated margin pools despite limited reimbursement, serving patients with dermatological adhesive sensitivities or lifestyle demands incompatible with external wearables.
Regulatory Framework and Outlook
Medsafe governs medical device registration under the Medicines Act 1981, with software-as-a-medical-device amendments tightening cybersecurity validation requirements for cloud-connected glucose platforms. The Therapeutic Products Act 2023 introduces risk-classification harmonization with Australia's TGA, streamlining eventual trans-Tasman market access for manufacturers holding dual certifications. Stakeholders must monitor Pharmac's annual tender negotiations, as subsidy list revisions directly determine patient out-of-pocket exposure and category penetration rates across district health board catchments.
Market Dynamics
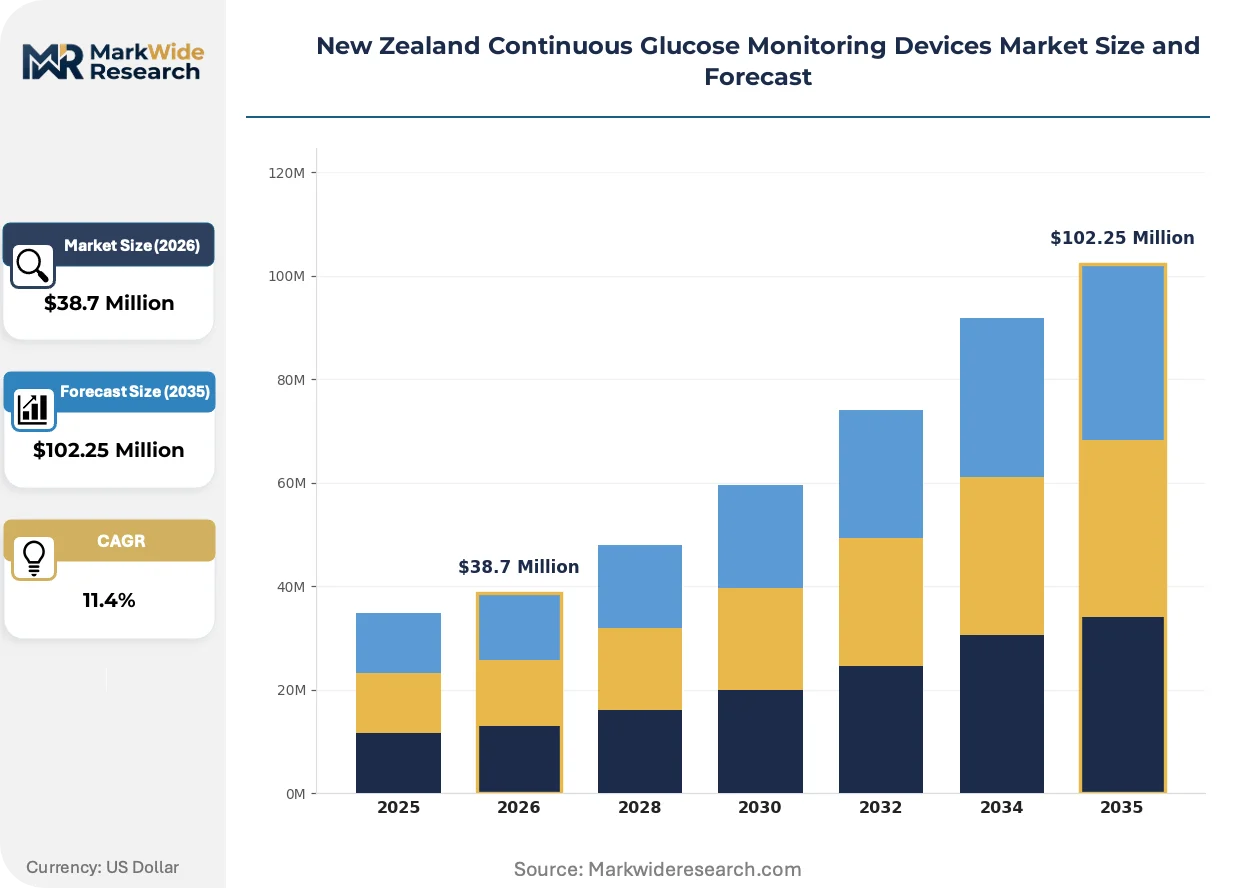
Pharmac's subsidy tender cycles and Medsafe's software-as-a-medical-device amendments are compressing product lifecycles while expanding access pathways for cloud-connected glucose platforms across district health board catchments.
Growth Catalysts
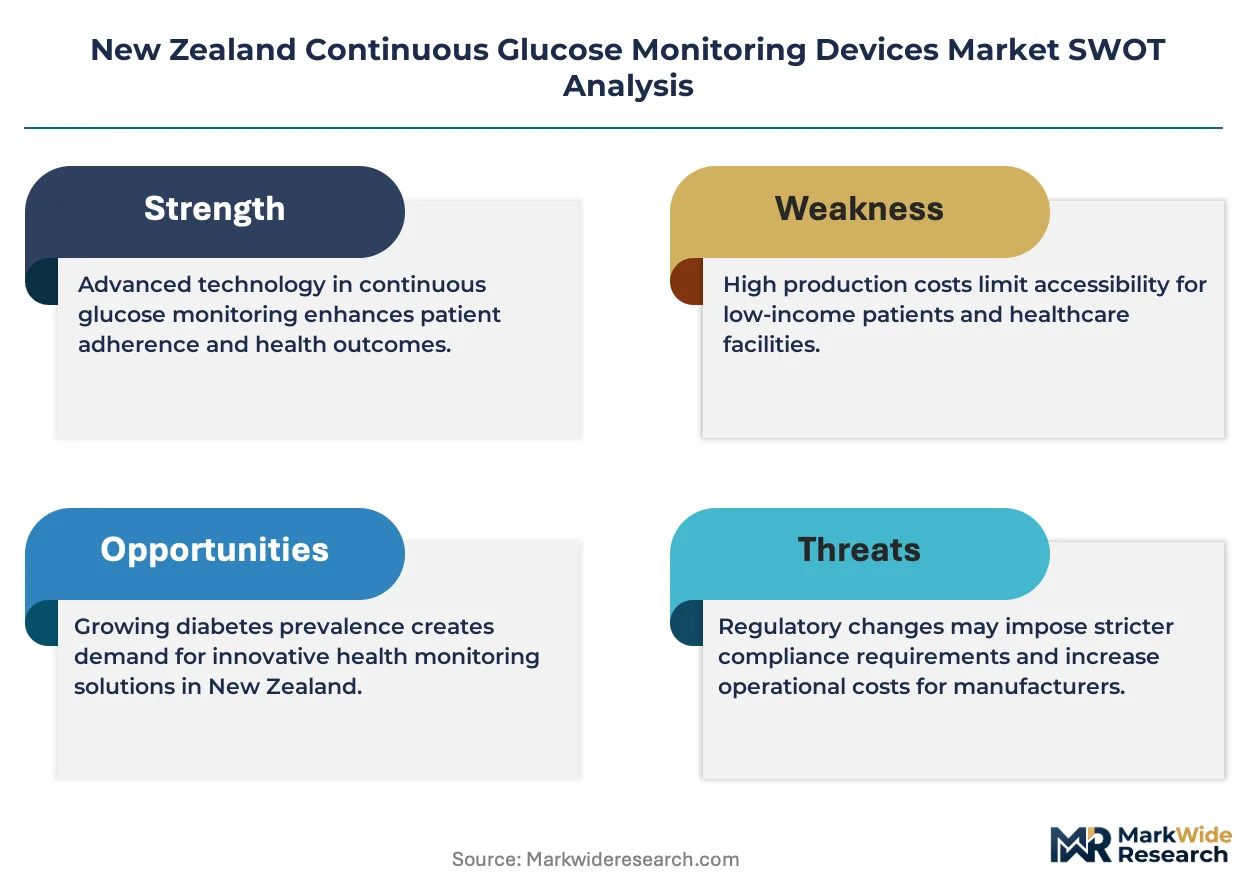
- Therapeutic Products Act 2023:Harmonization with Australia's TGA is reducing dual-certification burdens for manufacturers, accelerating trans-Tasman product launches.
- Type 1 diabetes prevalence:Rising incidence among pediatric and young adult cohorts in Auckland and Canterbury is expanding the addressable patient base for continuous monitoring.
- Smartphone ecosystem maturation:iOS and Android health platform integrations are enabling remote data sharing with general practitioners, reducing clinic visit dependencies.
Market Restraints
- Adhesive dermatitis incidence:Approximately 15-20% of users experience skin reactions to subcutaneous filament adhesives, limiting wear duration and sensor reliability.
- Pharmac reimbursement volatility:Annual tender negotiations create uncertainty in patient out-of-pocket costs, dampening predictable demand forecasting for distributors.
- Flash monitor substitution:Pharmacy-distributed systems with fingerstick replacement claims are capturing price-sensitive patients before continuous monitoring conversion.
Strategic Opportunities
- Implantable sensor segment:Patients with adhesive sensitivities or extreme lifestyle demands represent an underserved premium tier with limited domestic competition.
- Remote patient monitoring integration:Convergence of continuous glucose data with telehealth platforms is creating new reimbursement pathways through virtual care billing codes.
- South Island expansion:Otago and Southland district health boards show lower penetration rates relative to Auckland, presenting whitespace for targeted clinical education programs.
Industry Challenges
- Cybersecurity validation timelines:Medsafe's tightened requirements for cloud-connected platforms are extending software update approval cycles, compressing competitive response windows.
- Endocrinology workforce density:Specialist concentration in Auckland and Wellington creates access bottlenecks for rural patient onboarding to continuous monitoring protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | New Zealand Continuous Glucose Monitoring Devices Market |
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $102.25 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flash Glucose Monitors, Wearable Sensors, Smartphone-Compatible Devices, Implantable Sensors Delivery Mode: Home Use, Professional Use, Remote Monitoring, Cloud-Based Solutions End User: Diabetes Patients, Healthcare Providers, Caregivers, Research Institutions Technology: Electrochemical Sensors, Optical Sensors, Microneedle Technology, Wireless Communication |
| Companies Covered | Dexcom Inc, Abbott Diabetes Care Inc, Medtronic PLC, Eversense, Ascensia Diabetes Care, Roche Diabetes Care, Senseonics, AiDEX, Pharmaco (N.Z.) Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
New Zealand Continuous Glucose Monitoring Devices Market Shifts & Advancements
Sensor miniaturization and algorithmic predictive capabilities are converging to shift diabetes management from reactive glucose correction toward anticipatory insulin dosing across New Zealand's clinical networks.
Non-invasive optical sensing technology is migrating from research-phase validation toward commercial feasibility trials. Endocrinology practices in Auckland's metropolitan hospitals are piloting these platforms for type 2 diabetes screening. The technology is migrating from fingerstick replacement claims toward standalone continuous monitoring reimbursement categories, restructuring Pharmac's evaluation frameworks.
Medsafe's software-as-a-medical-device amendments under the Medicines Act 1981 are mandating pre-market cybersecurity documentation for cloud-connected glucose platforms. Manufacturers must now submit penetration testing protocols and data residency attestations alongside traditional safety filings. Smartphone-integrated systems face the steepest compliance burden, with several international vendors delaying New Zealand launches pending certification clarity.
Patient data ownership preferences are reshaping purchasing conversations in diabetes centers. Individuals increasingly demand portable glucose records compatible with multiple clinical information systems, displacing platform-locked ecosystems. This behavioral shift is most pronounced among technologically engaged cohorts in Wellington and Christchurch, where patient advocacy groups have pressured district health boards to mandate interoperability standards in procurement specifications.
New Zealand Continuous Glucose Monitoring Devices Market Segmentation
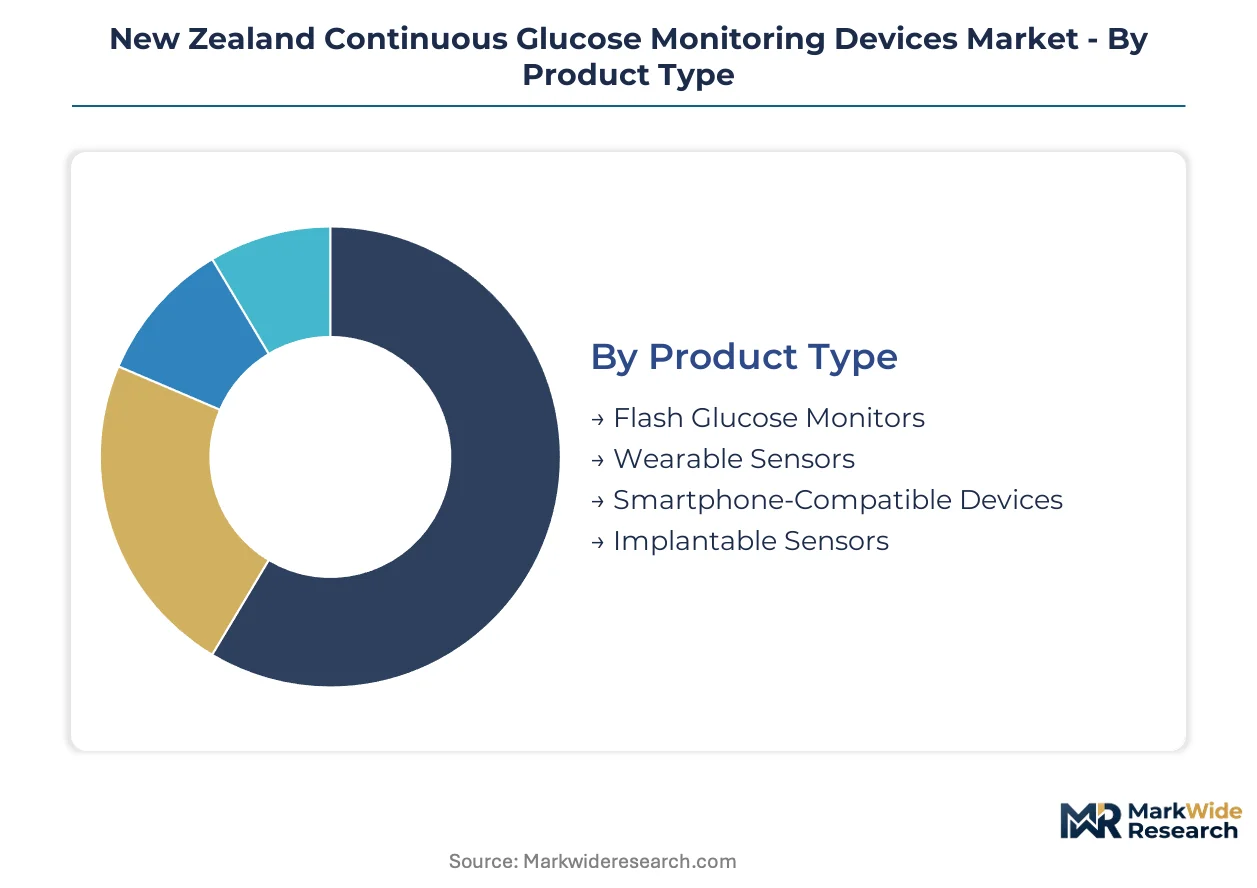
Segmentation in New Zealand's continuous glucose monitoring landscape reveals how subsidy pathways, clinical workflows, and patient self-management preferences fragment demand across distinct technology tiers and care settings.
Product Type:
Use-case spectrum spans fingerstick replacement through anticipatory insulin dosing, with each tier serving different patient capabilities and reimbursement eligibility.
- Flash Glucose Monitors:Optical sensor systems with factory-calibrated filaments eliminate fingerstick requirements through 14-day wear cycles. Pharmac subsidy eligibility concentrates demand in community pharmacy channels across Auckland and Canterbury district health board catchments, where general practitioners favor streamlined clinic workflows.
- Wearable Sensors:Electrochemical platforms with real-time alarm capabilities transmit glucose trends to dedicated receivers or smartphones. Endocrinology practices in Wellington and Christchurch prescribe these for type 1 diabetes patients requiring hypoglycemia alerts, though out-of-pocket costs limit penetration among price-sensitive cohorts.
- Smartphone-Compatible Devices:Bluetooth-enabled transmitters pair with iOS and Android health platforms for remote data sharing with clinicians.
- Implantable Sensors:Subcutaneous glucose sensors with extended duration appeal to patients with adhesive dermatitis or extreme physical activity demands.
Established volume favors Flash Glucose Monitors; emerging adoption favors Smartphone-Compatible Devices.
Delivery Mode:
Care setting determines regulatory pathway, reimbursement coding, and data integration requirements across New Zealand's district health board networks.
- Home Use:Patient-managed sensor application and data interpretation dominate volume, supported by Pharmac-subsidized pharmacy distribution and diabetes nurse educator training programs in metropolitan centers.
- Professional Use:Hospital-based continuous monitoring during acute illness or perioperative periods requires integration with clinical information systems.
- Remote Monitoring:Telehealth platforms enabling glucose data review without clinic visits are gaining reimbursement traction through virtual care billing codes.
- Cloud-Based Solutions:Aggregated population health analytics and predictive algorithm deployment serve district health board diabetes management programs.
Home Use commands current patient volume; Remote Monitoring is climbing the fastest as telehealth infrastructure matures.
End User:
Decision-making authority and purchasing influence vary sharply across patient-directed, clinician-prescribed, and institutional procurement channels.
- Diabetes Patients:Type 1 and insulin-dependent type 2 individuals drive direct-to-consumer demand, with technology engagement levels determining premium versus subsidy-dependent product selection.
- Healthcare Providers:Endocrinologists, general practitioners, and diabetes nurse specialists control prescription pathways and influence brand selection through clinical guideline adherence.
- Caregivers:Parents of pediatric patients and aged care facility staff require simplified interfaces and remote alerting capabilities for dependent monitoring.
- Research Institutions:Universities and clinical trial networks source devices for algorithm validation and novel sensor technology assessment.
Patient self-selection dominates volume; Healthcare Providers gatekeep premium-tier access.
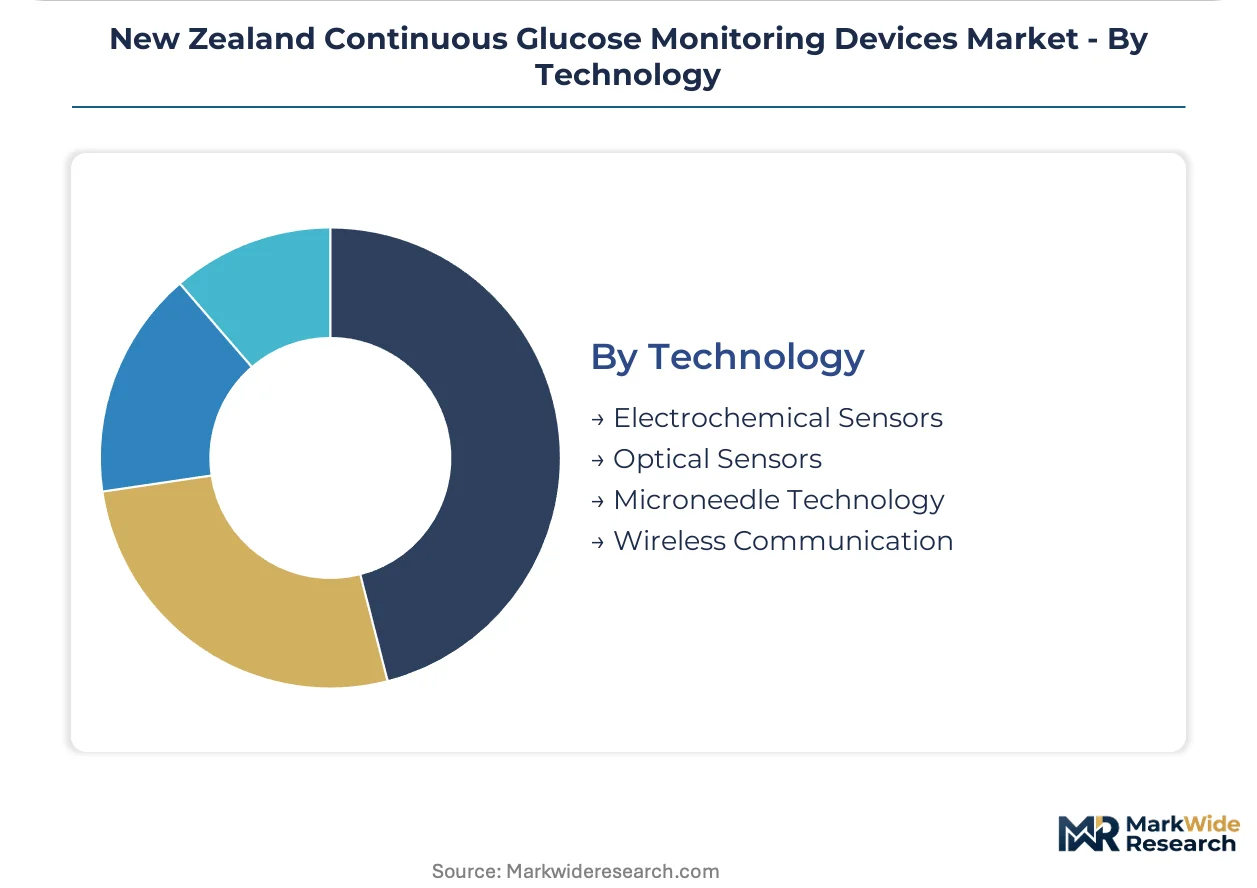
Technology:
Underlying sensing mechanisms determine accuracy specifications, calibration requirements, and manufacturing cost structures for competing device architectures.
- Electrochemical Sensors:Enzyme-based glucose oxidase reactions with interstitial fluid sampling deliver established accuracy for regulatory submission. Medsafe's software-as-a-medical-device amendments now mandate cybersecurity documentation for cloud-connected variants of this mature technology base.
- Optical Sensors:Near-infrared or Raman spectroscopy approaches enable non-invasive glucose estimation, currently in pilot deployment for type 2 diabetes screening at Auckland metropolitan hospitals.
- Microneedle Technology:Minimally invasive filaments reduce insertion trauma and expand patient tolerance for frequent sensor replacement.
- Wireless Communication:Bluetooth Low Energy and proprietary radio protocols enable smartphone pairing and cloud data transmission.
Electrochemical Sensors anchor current reimbursement; Optical Sensors hold the steepest expansion trajectory pending clinical validation completion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device distribution concentrates where district health board procurement budgets and endocrinology specialist density align. Auckland's metropolitan clinical networks handle the majority of patient onboarding for continuous glucose monitoring systems.
Auckland
Endocrinology practices at Auckland City Hospital and Middlemore Hospital drive prescription volumes for real-time alarm systems. Pharmac's subsidy tender negotiations directly determine patient out-of-pocket exposure across the Auckland District Health Board catchment. Diabetes nurse educator programs in South Auckland accelerate home-based sensor adoption among Māori and Pacific patient cohorts.
Canterbury
Christchurch Hospital's pediatric diabetes unit generates concentrated demand for smartphone-compatible devices among adolescent type 1 patients. Medsafe's software-as-a-medical-device amendments require cybersecurity documentation from manufacturers supplying the Canterbury District Health Board. Remote patient monitoring pilots in rural Canterbury integrate continuous glucose data with telehealth platforms.
Wellington
Capital and Coast District Health Board procurement specifications increasingly mandate interoperability standards for glucose data portability. Patient advocacy groups in Wellington have pressured district health boards to reject platform-locked ecosystems. Endocrinology workforce concentration at Wellington Hospital creates access bottlenecks for Hutt Valley and Wairarapa patients.
Otago and Southland
Lower penetration rates relative to Auckland present whitespace for clinical education programs targeting general practitioner prescribing behavior. Southern District Health Board's dispersed rural population favors pharmacy-distributed flash monitors over clinic-dependent continuous systems. Dunedin School of Medicine research collaborations validate novel sensor algorithms for eventual national deployment.
Waikato
Waikato District Health Board's diabetes management programs emphasize cost-containment through Pharmac-subsidized flash monitoring tiers. Hamilton's regional hospital coordinates sensor distribution across a geographically dispersed patient base extending to the Coromandel and Taupō. Manufacturing and logistics employment in the Waikato supports stable private health insurance coverage for premium-tier device access.
New Zealand Continuous Glucose Monitoring Devices Market Competitive Landscape
Real-time data ecosystems and pharmacy-distributed flash systems split the market between premium clinical workflows and streamlined community access. The vendor base concentrates around three strategic archetypes: sensor technology originators, integrated insulin delivery platforms, and regional distribution specialists. Consolidation pressures intensify as Pharmac's annual tender cycles reward scale and subsidy management capabilities. Technology licensing agreements and cybersecurity certification partnerships represent the dominant competitive moves for cloud-connected platform vendors.
Within the sensor technology originator tier, Dexcom Inc and Abbott Diabetes Care Inc anchor opposing strategic positions. Dexcom exemplifies the premium real-time alarm segment through endocrinology practice relationships. Abbott occupies the volume-dominant flash monitoring position through pharmacy channel penetration. Medtronic PLC represents the integrated insulin delivery archetype, competing through hybrid closed-loop system compatibility. These three firms collectively shape Pharmac's evaluation frameworks and district health board procurement specifications.
| Leading Market Players |
|---|
| Dexcom Inc |
| Abbott Diabetes Care Inc |
| Medtronic PLC |
| Eversense |
| Ascensia Diabetes Care |
| Roche Diabetes Care |
| Senseonics |
| AiDEX |
| Pharmaco (N.Z.) Ltd |
| Others |
Supply & Pricing Matrix
Auckland's metropolitan distribution hubs channel imported sensor systems through Pharmac-subsidized procurement pathways, concentrating pricing power among incumbent manufacturers with established reimbursement relationships. District health board tender cycles compress margins for distributors while amplifying volume incentives for manufacturers holding preferred supplier status.
Pricing Analysis
Therapeutic Products Act 2023 dictates the pricing tier structure through its harmonization with Australia's TGA, reducing dual-certification costs that previously inflated premium-tier device pricing. Three-tier pricing structure across premium, standard, and economy levels separates real-time alarm systems from flash monitors from basic fingerstick replacements. Cost compression in the flash monitor tier is intensifying because pharmacy-distributed systems bypass clinic workflow markups. Price-sensitive patients in South Island rural catchments gravitate toward subsidy-eligible flash systems, while least-sensitive cohorts in Wellington and Auckland metropolitan practices absorb out-of-pocket premiums for smartphone-integrated platforms.
Supply Chain Analysis
Export control regimes limiting semiconductor and precision sensor flows from the United States and European Union constrain domestic assembly capacity for cloud-connected glucose platforms. Manufacturing concentrates in Ireland, Malaysia, and the United States for electrochemical sensor filaments, with Bluetooth transmitter modules sourced from Taiwanese and South Korean foundries. Raw material dependencies include glucose oxidase enzymes, medical-grade adhesives, and lithium polymer cells. Single-source vulnerability in enzyme supply chains creates bottlenecks during global pharmaceutical ingredient shortages. Distribution runs through Auckland-based medical device wholesalers with direct hospital and pharmacy contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
New Zealand's continuous glucose monitoring sector sits as a high-growth disruption justified by Medsafe's software-as-a-medical-device amendments accelerating cloud-connected platform adoption. Regulatory clarity around cybersecurity validation is compressing product lifecycles while expanding addressable patient populations.
For Market Incumbents: Pre-empt flash monitor substitution by embedding predictive algorithms that differentiate real-time systems from fingerstick-replacement tiers. Deepen vertical integration into adhesive formulation to mitigate dermatitis-related churn. Secure cybersecurity certification partnerships ahead of Medsafe's tightened documentation requirements. Channel control through exclusive diabetes nurse educator training programs locks in prescription influence at Auckland and Christchurch hospital networks.
For New Entrants and Emerging Players: Otago and Southland's underpenetrated rural catchments offer whitespace for telehealth-integrated remote monitoring solutions bypassing endocrinology access bottlenecks. Target general practitioner prescribing behavior through simplified onboarding protocols that reduce specialist referral dependencies. Pharmacy-direct distribution models circumvent clinic workflow integration barriers that favor incumbent relationships.
For Investors and Strategic Acquirers: Long-term, this sits as a chronic-disease-platform play because diabetes management infrastructure anchors recurring revenue through sensor replacement cycles and software subscription tiers. Acquisition targets with implantable sensor IP address adhesive-sensitivity patient segments underserved by external wearables. Watch Pharmac's annual tender negotiations as the signal for subsidy list expansions that would accelerate category penetration.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-as-a-Medical-Device Certification | Medsafe's tightened cybersecurity requirements create competitive moats for compliant manufacturers. |
| Pharmac Subsidy Tender Positioning | Preferred supplier status determines patient out-of-pocket exposure and volume capture across district health boards. |
| Implantable Sensor Development | Extended-duration platforms address adhesive dermatitis incidence that limits external wearable compliance. |
| Telehealth Platform Integration | Remote patient monitoring reimbursement codes enable virtual care billing for glucose data review. |
| South Island Clinical Education Expansion | Otago and Southland's lower penetration rates present whitespace for targeted general practitioner programs. |
Research Methodology
Operator-level perspectives from endocrinologists, diabetes nurse specialists, hospital procurement managers, and pharmacy distribution heads anchored the qualitative base for this study. Primary interviews with district health board technology assessment committees and biomedical engineers at Auckland City Hospital and Christchurch Hospital combined with secondary validation from Medsafe device registration databases, Pharmac tender documentation, and district health board annual reports. Bottom-up patient population estimates triangulated against top-down reimbursement expenditure data from Pharmac's published pharmaceutical schedule.
Scenario-bracketing around subsidy policy shifts and regulatory harmonization timelines framed the analytical approach across the projection horizon. Segmentation dimensions modeled include product type, delivery mode, end user, and technology platform, with regional adoption patterns calibrated against district health board catchment demographics. CAGRs derived from fitted growth curves incorporating historical penetration rates and projected patient population expansion. Forecast inputs included type 1 diabetes incidence trajectories and smartphone health platform adoption curves specific to New Zealand's iOS and Android user base.
Macroeconomic conditions sit as an overlay; deviation in Pharmac funding allocations or district health board operational budgets would shift the trajectory. Forecasts reflect documented assumptions regarding reimbursement continuity and regulatory certification timelines. Material shifts in Therapeutic Products Act implementation schedules or Medsafe cybersecurity validation requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
APAC Insulin Infusion Pumps Market
Diabetes Care
Diabetes Monitors Market
Diabetes Care
Global Diabetic Ulcers Treatment Market
Diabetes Care
Middle East and Africa Diabetes Market
Diabetes Care
Japan Insulin Drugs and Delivery Devices Market
Diabetes Care
Germany Digital Diabetes Management Market
Diabetes Care
Japan Continuous Glucose Monitoring Devices Market
Diabetes Care
Vietnam Diabetes Care Devices Market
Diabetes Care
Sensor Based Glucose Measuring Systems Market
Diabetes Care
France Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Canada Self-Monitoring Blood Glucose Market
Diabetes Care
Mexico Oral Anti-Diabetic Drug Market
Diabetes Care
China Continuous Glucose Monitoring Devices Market
Diabetes Care
Thailand Oral Antidiabetic Drug Market
Diabetes Care
Global Type 2 Diabetes Treatment Market
Diabetes Care
North America Insulin Infusion Pumps Market