
 Insulin Patch Pumps Market | 2026-2036
Insulin Patch Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Insulin Patch Pumps Market Intelligence
United States manufacturing capacity for wearable drug delivery systems is narrowing the competitive gap between established pump makers and patch-based entrants. Insulet Corporation leverages its tubeless Omnipod platform to sustain channel dominance in ambulatory settings. Medtronic plc anchors its position through backward integration into continuous glucose monitoring sensors and algorithm development. Tandem Diabetes Care differentiates via software-driven dosing algorithms that integrate with third-party continuous monitoring devices.
Insulin patch pumps are wearable, adhesive-mounted devices that deliver subcutaneous insulin through micro-needle or electromechanical mechanisms without external tubing, typically controlled via handheld units or smartphone applications for basal-bolus therapy in diabetes management. Disposable patch configurations lead current volume due to lower upfront patient cost and elimination of cleaning protocols, while wireless connectivity segments capture expanding margin pools through recurring software subscription revenue. Home care end users represent the fastest-growing demand channel as reimbursement frameworks shift toward outpatient chronic disease management.
FDA 510(k) premarket notification requirements shape device design timelines and clinical validation burden for manufacturers seeking US market access, while EU MDR technical documentation and notified body conformity assessments determine European commercialization feasibility. The country's national pharmaceutical regulator in Japan and Health Canada establish parallel approval pathways that fragment go-to-market sequencing for multinational device portfolios. Stakeholders must monitor evolving interoperability standards between patch pumps and continuous glucose monitoring systems as regulatory bodies on both sides of the Atlantic mandate encrypted data exchange protocols.
Market Dynamics
Tubeless form factors are compressing patient switching costs and eroding installed-base moats that once protected incumbent pump manufacturers with legacy tethered systems.
Growth Catalysts
- CGM-Patch Pump Interoperability Mandates:FDA 510(k) clearance pathways for integrated closed-loop systems accelerate development timelines for manufacturers pursuing automated insulin delivery approvals.
- Home Care Reimbursement Expansion:Outpatient chronic disease management frameworks in the United States now cover disposable patch configurations, shifting site-of-care economics toward ambulatory settings.
- Micro-Needle Array Fabrication:Electromechanical pumping mechanisms manufactured through semiconductor-style wafer processes enable thinner, more adhesive-compatible device profiles.
Market Restraints
- Adhesive Biocompatibility Limitations:Extended wear duration beyond three days triggers skin irritation rates that limit patient compliance and drive replacement costs.
- Concentrated Sensor Supply:Continuous glucose monitoring filament production concentrates among single-source suppliers, creating vulnerability for integrated patch pump assemblers.
- EU MDR Conformity Assessment Bottlenecks:Notified body capacity constraints extend technical documentation review timelines for European market entry.
Strategic Opportunities
- Type 2 Diabetes Ambulatory Expansion:Underpenetrated basal-only therapy segments in Germany and France offer volume pools beyond established Type 1 populations.
- Software Subscription Monetization:Predictive dosing algorithm licenses generate recurring revenue streams independent of hardware replacement cycles.
- Japan PMDA Fast-Track Pathways:The country's national pharmaceutical regulator prioritizes review of breakthrough-designated wearable drug delivery devices.
Industry Challenges
- Cybersecurity Validation Burden:FDA premarket submission requirements for encrypted data exchange protocols extend engineering timelines and testing expenditures.
- Legacy Health System Integration:Electronic health record connectivity standards vary across hospital networks, forcing redundant interoperability development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insulin Patch Pumps Market |
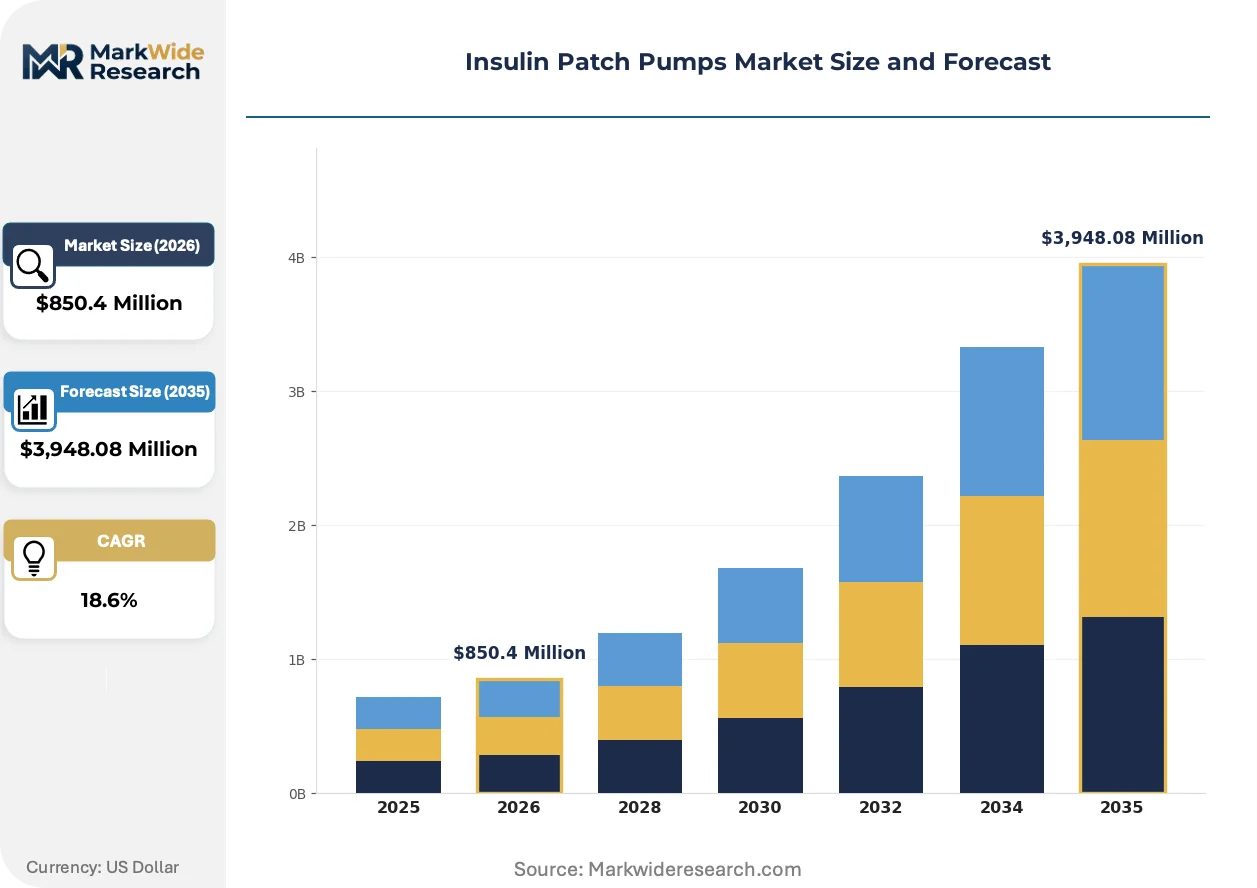
| Market Size in 2026 | $850.4 Million |
| Market Size in 2035 | $3,948.08 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Reusable, Wireless, Integrated Technology: Micro-needle, Electromechanical, Software-driven, Continuous End User: Home Care, Hospitals, Clinics, Specialty Pharmacies Component: Insulin Reservoir, Infusion Set, Adhesive Patch, Control Unit |
| Companies Covered | Medtronic plc, Insulet Corporation, F. Hoffmann-La Roche Ltd, Tandem Diabetes Care, CeQur, Terumo, Medtrum, Debiotech, Valeritas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insulin Patch Pumps Market Strategic Shifts & Innovations
Algorithmic control architectures are displacing manual dosing workflows while adhesive-mounted hardware platforms compress the physical footprint of insulin delivery systems.
Closed-loop artificial pancreas systems are migrating from research-limited deployments to commercial availability through automated basal rate adjustment based on real-time glucose telemetry. Pediatric endocrinology practices in the United States are adopting these configurations at accelerating pace as payer coverage solidifies. This migration is compressing competitive differentiation around hardware specifications and shifting value capture toward software-enabled glycemic outcomes.
EU MDR technical documentation requirements for drug-device combination products are forcing manufacturers to restructure quality management systems and clinical evidence portfolios. Notified body scrutiny of biocompatibility testing protocols has intensified for adhesive-mounted wearable devices. Western European commercialization sequencing now lags US FDA 510(k) clearance timelines by twelve to eighteen months for equivalent product submissions.
Direct-to-patient subscription models are displacing traditional durable medical equipment distribution channels for disposable patch configurations. Pharmacy benefit managers in the United States are consolidating formulary placement decisions around total cost-of-therapy metrics rather than device acquisition pricing alone. This channel restructuring concentrates purchasing influence among three national pharmacy chains and their affiliated specialty distributors.
Insulin Patch Pumps Market Segmentation
Patch pump segmentation reflects divergent replacement economics across hardware configurations. Disposable and adhesive-mounted systems generate recurring revenue through shorter replacement cycles, while reusable platforms concentrate upfront capital expenditure and extended amortization periods.
Product Type:
Replacement cadence separates segments sharply—disposable patches turn over every two to three days versus multi-year lifespans for reusable control units.
- Disposable:Single-use adhesive-mounted reservoirs eliminate cleaning protocols and reduce infection risk. Home care settings in the United States drive volume as pharmacy benefit managers consolidate formulary placement around total cost-of-therapy metrics.
- Reusable:Durable control units with replaceable insulin cartridges spread acquisition costs across extended use periods. Patients with established Type 1 diabetes in Germany and France prefer these configurations for basal-bolus flexibility.
- Wireless:Bluetooth-enabled communication with smartphone applications enables remote dose adjustment and caregiver monitoring. FDA 510(k) clearance pathways for encrypted data exchange protocols shape engineering timelines.
- Integrated:Closed-loop systems combining patch delivery with continuous glucose monitoring sensors automate basal rate adjustments. Pediatric endocrinology practices are adopting these configurations as payer coverage solidifies.
Disposable dominates installed base. Integrated is where expansion concentrates.
Technology:
Cost tier stratification runs from semiconductor-fabricated micro-arrays to algorithm-intensive software platforms with recurring licensing revenue.
- Micro-needle:Silicon wafer-manufactured arrays with sub-millimeter cannula lengths minimize tissue trauma and enable thinner device profiles. Adhesive biocompatibility limitations constrain wear duration beyond three days.
- Electromechanical:Precision piston or peristaltic pumping mechanisms deliver measured insulin boluses through flexible tubing connections. These systems concentrate in hospital and clinic settings requiring precise dose verification.
- Software-driven:Predictive dosing algorithms analyze glucose telemetry patterns to recommend or automate insulin delivery adjustments. Subscription monetization models generate recurring revenue independent of hardware replacement.
- Continuous:Basal rate automation with manual bolus override capabilities bridges manual pump therapy and fully closed-loop artificial pancreas systems. EU MDR conformity assessments for drug-device combination products extend European commercialization timelines.
Electromechanical anchors hospital procurement. Software-driven is climbing the fastest.
End User:
Application context determines reimbursement pathway complexity and device specification requirements.
- Home Care:Ambulatory patients self-manage diabetes through wearable patch systems with smartphone control interfaces. Outpatient chronic disease management frameworks now cover disposable configurations, shifting site-of-care economics.
- Hospitals:Inpatient glycemic management requires integration with electronic health record systems and nurse-call alerting protocols. Legacy health system connectivity standards vary across networks, forcing redundant interoperability development.
- Clinics:Endocrinology practices prescribe and train patients on patch pump initiation, generating recurring follow-up visit revenue. Pediatric specialists in the United States are adopting closed-loop configurations at accelerating pace.
- Specialty Pharmacies:Consolidated distribution channels for disposable patch configurations concentrate purchasing influence among three national pharmacy chains and their affiliated specialty distributors.
Home Care captures volume leadership. Specialty Pharmacies is gaining share fastest.
Component:
Supply concentration varies across subsystems, with sensor filaments and adhesive materials presenting single-source vulnerabilities.
- Insulin Reservoir:Biocompatible polymer chambers with precise volume calibration ensure dose accuracy across temperature variations. Manufacturers backward integrate into reservoir production to defend margin position.
- Infusion Set:Flexible tubing and subcutaneous cannula assemblies require sterilization validation and pyrogen testing. These components turn over on matching cycles with disposable patch configurations.
- Adhesive Patch:Medical-grade acrylic or silicone formulations must balance wear duration against skin irritation rates. Extended wear beyond three days triggers compliance-limiting dermatological reactions.
- Control Unit:Handheld or smartphone-based interfaces manage dose programming, glucose data display, and algorithm execution. Cybersecurity validation burdens for encrypted data exchange extend FDA premarket submission timelines.
Adhesive Patch constrains system economics. Control Unit is where value capture is shifting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tubeless insulin delivery hardware concentrates manufacturing in the United States, Germany, and Japan, with regulatory clearance sequencing determining commercialization priority across geographies. FDA 510(k) pathways accelerate US market entry, while EU MDR conformity assessments and Japan PMDA reviews create staggered launch calendars for multinational device portfolios.
United States
Integrated closed-loop systems drive demand from pediatric endocrinology practices and Type 1 diabetes patients in home care settings. FDA 510(k) clearance pathways for CGM-patch pump interoperability compress development timelines for automated insulin delivery. The Minneapolis-St. Paul corridor anchors sensor algorithm development and wearable device manufacturing clusters.
Germany
Basal-bolus therapy adoption among established Type 1 diabetes populations sustains reusable patch pump preference over disposable configurations. EU MDR technical documentation requirements for drug-device combination products extend notified body review timelines. The Baden-Württemberg region concentrates precision electromechanical component fabrication for insulin delivery mechanisms.
Japan
Aging demographics and rising Type 2 diabetes prevalence expand ambulatory insulin therapy addressable markets beyond traditional Type 1 populations. PMDA fast-track pathways prioritize breakthrough-designated wearable drug delivery devices. The Kanto region around Tokyo houses medical device manufacturing clusters serving domestic and Asia-Pacific export demand.
United Kingdom
NHS reimbursement frameworks for outpatient chronic disease management shift site-of-care economics toward disposable patch configurations. MHRA post-Brexit regulatory autonomy creates parallel but convergent approval pathways with EU MDR standards. The Cambridge-Oxford-London triangle concentrates digital health algorithm development for predictive dosing software.
France
Underpenetrated basal-only therapy segments offer volume expansion opportunities beyond established Type 1 diabetes populations. ANSM conformity assessments align with EU MDR technical documentation requirements for adhesive-mounted wearable devices. The Paris-Saclay cluster anchors medical technology research institutions collaborating with device manufacturers on biocompatibility testing protocols.
Insulin Patch Pumps Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream supplying reservoirs, adhesives, and sensor filaments to finished device assemblers. The vendor base stratifies across three tiers: diversified medtech conglomerates with backward-integrated sensor capabilities, pure-play patch pump specialists with tubeless form factor expertise, and contract manufacturers producing electromechanical subassemblies. Strategic moves concentrate on software algorithm licensing partnerships and adhesive biocompatibility research collaborations.
Among diversified medtech conglomerates, Medtronic plc and Insulet Corporation exemplify contrasting platform strategies—one integrating continuous glucose monitoring sensors through in-house production, the other sustaining channel dominance through tubeless disposable configurations. Tandem Diabetes Care occupies a position within the software-driven tier, representing predictive dosing algorithm development that shifts value capture toward recurring subscription revenue independent of hardware replacement cycles.
| Leading Market Players |
|---|
| Medtronic plc |
| Insulet Corporation |
| F. Hoffmann-La Roche Ltd |
| Tandem Diabetes Care |
| CeQur |
| Terumo |
| Medtrum |
| Debiotech |
| Valeritas |
| Others |
Cost & Logistics Intelligence
Single-source dependency on continuous glucose monitoring filament suppliers determines both pricing tier spreads and supply chain shape, compressing margin pools for integrated patch pump assemblers while amplifying procurement leverage for sensor manufacturers. FDA cybersecurity validation requirements and EU MDR conformity assessments further stratify cost structures across geographic markets.
Pricing Analysis
FDA 510(k) premarket notification requirements dictate the pricing tier structure across disposable, reusable, and integrated system configurations. Three-tier pricing structure across premium closed-loop systems, standard wireless-enabled patches, and economy basal-only devices separates segments by algorithm sophistication and CGM interoperability certification. Cost compression in disposable configurations is intensifying because pharmacy benefit managers consolidate formulary placement around total cost-of-therapy metrics rather than device acquisition pricing alone. Home care patients exhibit highest price sensitivity, while pediatric endocrinology practices demonstrate lowest sensitivity due to reimbursement coverage solidification.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for semiconductor-fabricated micro-needle arrays and electromechanical pumping subassemblies. Manufacturing concentrates in the United States, Germany, and Japan for finished device assembly, with sensor filament production drawing from single-source suppliers in the United States and South Korea. Raw material dependencies span medical-grade silicone adhesives, biocompatible polymer reservoirs, and precision-machined stainless steel cannulae. Distribution runs through three national pharmacy chains and their affiliated specialty distributors for disposable patch configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The insulin patch pumps market sits at a cyclical recovery phase driven by reimbursement framework expansion for outpatient chronic disease management, creating asymmetric return profiles across stakeholder archetypes.
For Market Incumbents: Insulate installed base moats through backward integration into continuous glucose monitoring sensor production, capturing margin pools currently extracted by single-source filament suppliers. Deepen algorithm development capabilities to shift value capture toward recurring software subscription revenue independent of hardware replacement cycles. Prioritize adhesive biocompatibility research collaborations to extend wear duration beyond three-day compliance thresholds.
For New Entrants and Emerging Players: Underpenetrated basal-only therapy segments in Germany and France offer volume pools beyond established Type 1 diabetes populations with lower competitive density. Target direct-to-patient subscription models displacing traditional durable medical equipment distribution channels, leveraging pharmacy benefit manager consolidation for formulary access. Pursue Japan PMDA fast-track pathways for breakthrough-designated wearable drug delivery devices to accelerate commercialization sequencing.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platform integrators with backward-integrated sensor capabilities over pure-play hardware specialists. Long-term viability across the projection horizon hinges on software algorithm licensing revenue durability and CGM interoperability certification breadth. Monitor FDA premarket submission timelines for encrypted data exchange protocols as an inflection indicator for competitive positioning shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission for Closed-Loop Systems | Accelerates automated insulin delivery commercialization through CGM-patch pump interoperability mandates. |
| Adhesive Biocompatibility Research Collaboration | Extends wear duration compliance thresholds through Paris-Saclay cluster dermatological testing protocols. |
| Software Companion Development for Predictive Dosing | Generates recurring subscription revenue independent of hardware replacement cycles. |
| Hospital System Partnership for EHR Integration | Addresses legacy health system connectivity standards variation across network infrastructures. |
| Reimbursement Strategy for Home Care Expansion | Captures outpatient chronic disease management framework shifts in United States pharmacy benefit structures. |
Research Approach
Desk research of FDA 510(k) premarket notification databases, EU MDR technical documentation registries, and hospital procurement contract repositories preceded structured interviews with endocrinology practice administrators, biomedical engineers, GPO contracts managers, and pharmacy benefit manager formulary directors. Primary fieldwork combined with secondary validation against CMS Medicare reimbursement data, clinical trial registries, and SEC filings from publicly traded device manufacturers. Bottom-up patient population modeling and top-down revenue triangulation anchored volume and value estimates.
Fixed assumptions across the modeling period held regulatory clearance timelines, reimbursement coverage expansion trajectories, and sensor supply concentration patterns constant while varying algorithm adoption rates, adhesive wear duration improvements, and direct-to-patient channel penetration. Segmentation dimensions modeled include product type configuration, technology platform, end user setting, and geographic regulatory cluster. CAGRs derived from logistic diffusion curves fitted to historical adoption patterns in analogous wearable drug delivery categories, with insulin price volatility and notified body capacity constraints as industry-specific forecast inputs.
Practitioners should monitor EU MDR conformity assessment bottlenecks, adhesive biocompatibility breakthroughs, and cybersecurity validation burden shifts for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Australia Self-Monitoring Blood Glucose Market
Diabetes Care
Oman Diabetes Care Devices Market
Diabetes Care
Alternatives for Injectable Diabetes Care Market
Diabetes Care
Middle East and Africa Blood Glucose Test Strip Market
Diabetes Care
United Kingdom Continuous Glucose Monitoring Market
Diabetes Care
SGLT2 Inhibitors Treatment Market
Diabetes Care
Global Diabetic Ulcers Treatment Market
Diabetes Care
Next Generation Diabetes Therapy and Drug Delivery Market
Diabetes Care
BRIC Diabetes Care Devices Market
Diabetes Care
Global Proliferative Diabetic Retinopathy Market
Diabetes Care
Point of Care Glucose Testing Market
Diabetes Care
New Zealand Continuous Glucose Monitoring Devices Market
Diabetes Care
Diabetic Shoes Market
Diabetes Care
Germany Digital Diabetes Management Market
Diabetes Care
Asia Pacific Diabetes Drug Market
Diabetes Care
BRICS Diabetes Drugs Market