
 Oman Diabetes Care Devices Market | 2026-2036
Oman Diabetes Care Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Oman Diabetes Care Devices Market Analytics
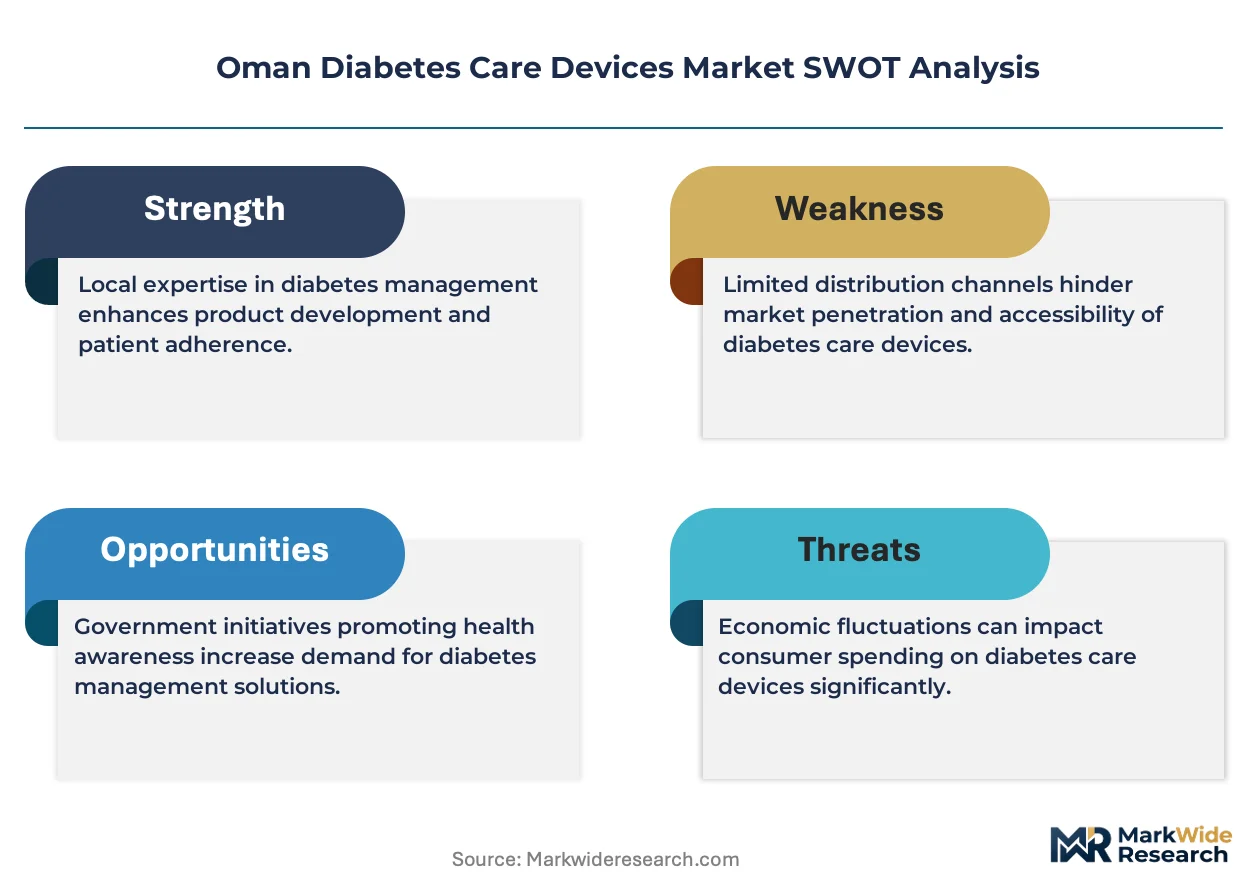
Multi-source procurement of test strips and sensors is realigning how Omani hospitals manage diabetes supply chains. Abbott Diabetes Care leverages its FreeStyle portfolio to anchor hospital tenders across the Sultanate's public health system. Medtronic PLC competes through its integrated pump-CGM ecosystem, while Roche Diabetes Care sustains long-standing relationships with Ministry of Health distribution channels.
Oman diabetes care devices encompass instruments for glucose measurement, insulin delivery, and metabolic monitoring, typically operating through electrochemical enzymatic reactions or subcutaneous interstitial fluid sampling to enable therapeutic decision-making. Blood glucose meters retain the largest installed base among product types, though continuous glucose monitors capture expanding margin pools as clinicians push for tighter glycemic control. Self-monitoring technology still dominates transaction volumes, yet connected devices represent the fastest-growing technology segment as telemedicine infrastructure penetrates Omani healthcare networks.
The Ministry of Health and the country's national pharmaceutical regulator enforce device registration and post-market surveillance protocols that shape import timelines and clinical trial requirements for new entrants. MOHAP-aligned quality standards and IEC 62304 software lifecycle requirements filter which digital health platforms achieve reimbursement eligibility. Stakeholders must monitor how evolving telehealth reimbursement rules reshape the economic viability of remote glucose monitoring deployments.
Market Dynamics
Hospital procurement of connected glucose monitors is accelerating as the Ministry of Health tightens device registration requirements and pushes for tighter glycemic control protocols across Oman's public health system.
Growth Catalysts
- Telemedicine infrastructure expansion:The Ministry of Health is embedding remote glucose monitoring into national diabetes management protocols, creating institutional demand for connected devices in Muscat and surrounding governorates.
- MOHAP-aligned quality standards:Device registration requirements now mandate IEC 62304 software lifecycle compliance, filtering out low-quality imports and elevating reimbursement eligibility for certified platforms.
- Specialist clinic clustering:Diabetes care concentration in Muscat Governorate generates economies of scale for device deployment and patient monitoring at scale.
Market Restraints
- Import dependency for sensors:Test strips and CGM sensors rely on concentrated overseas manufacturing, exposing procurement timelines to shipping volatility and currency fluctuation.
- Registration timeline friction:Ministry of Health post-market surveillance protocols extend approval cycles for new digital health platforms, delaying market entry for novel connected devices.
- Self-monitoring inertia:Blood glucose meters retain dominant installed base among price-sensitive patient segments, slowing continuous glucose monitor penetration outside insured populations.
Strategic Opportunities
- Al Batinah and Dhofar expansion:Governorates outside Muscat show underpenetrated home care demand where specialist diabetes clinic networks remain sparse.
- Insulin pump-CGM convergence:Integrated closed-loop systems create upgrade pathways for Type 1 diabetes patients currently on multiple daily injection regimens.
- Reimbursement rule evolution:Emerging telehealth reimbursement frameworks may expand economic viability of remote glucose monitoring for rural patient cohorts.
Industry Challenges
- Biomedical engineering talent scarcity:Device calibration and maintenance functions require specialized skills that outpace local training program output.
- Legacy system integration:Hospital information systems in regional facilities lack API compatibility with newer connected glucose monitoring platforms, forcing middleware investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oman Diabetes Care Devices Market |
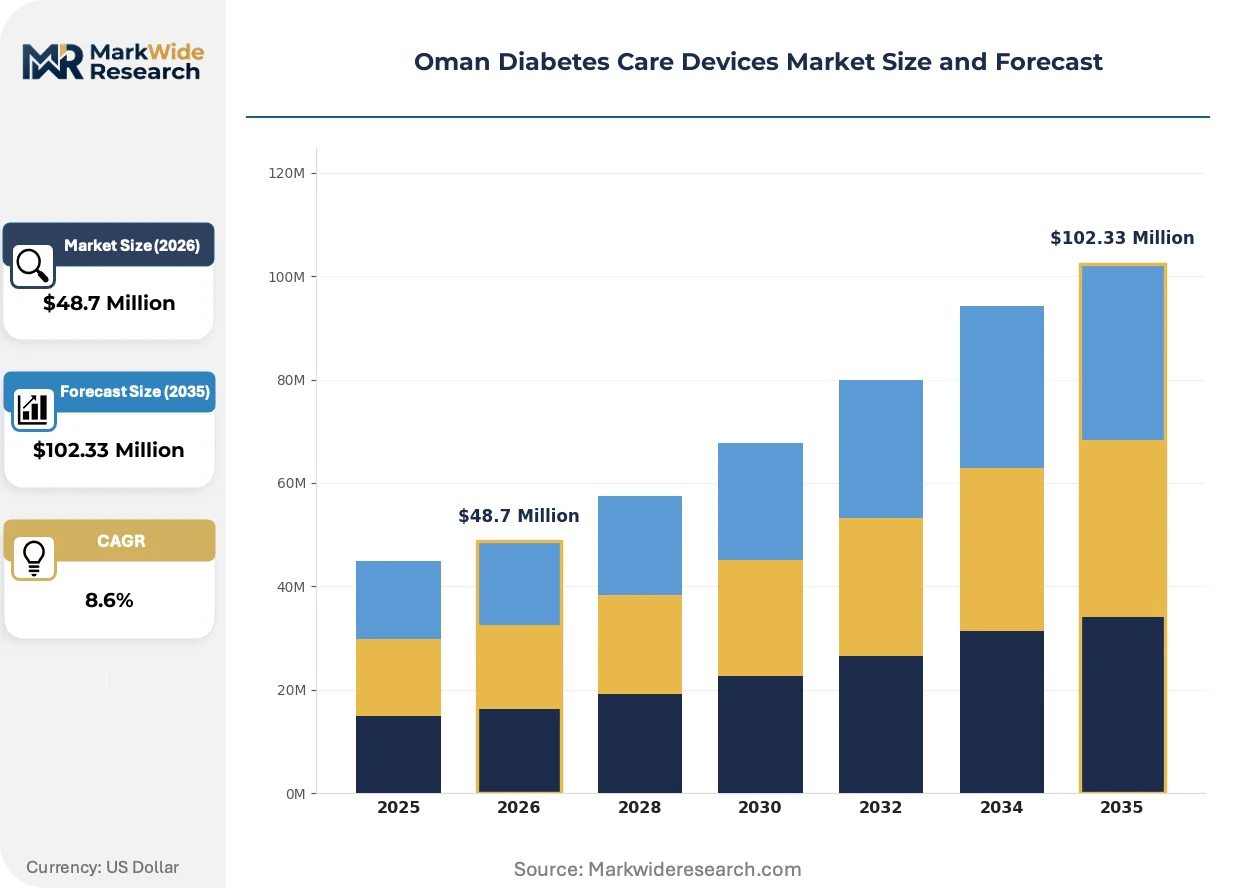
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $102.33 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blood Glucose Meters, Insulin Pumps, Continuous Glucose Monitors, Pen Injectors Technology: Self-Monitoring, Digital Health, Connected Devices, Wearable Tech End User: Hospitals, Clinics, Home Care, Pharmacies Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Medical Supply Distributors |
| Companies Covered | Abbott Diabetes Care, Medtronic PLC, Roche Diabetes Care, Novo Nordisk A/S, Lifescan, Ascensia Diabetes Care, Dexcom Inc., Insulet Corporation, Eli Lilly and Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oman Diabetes Care Devices Market Evolving Landscape
Connected glucose monitoring platforms are absorbing capital and clinical attention as Oman builds telemedicine infrastructure and revises reimbursement rules for remote patient management.
Continuous glucose monitoring technology is absorbing the functionality previously fragmented across separate blood glucose meters, logbooks, and manual insulin dosing decisions. Endocrinology departments at Royal Hospital and Sultan Qaboos University Hospital are piloting real-time data sharing with primary care networks. This convergence is absorbing margin from traditional self-monitoring blood glucose systems while expanding the addressable patient pool for automated insulin delivery.
The Ministry of Health's tightened device registration protocols now require IEC 62304 software lifecycle documentation for all connected diabetes devices seeking public procurement eligibility. Manufacturers must demonstrate post-market surveillance capabilities and local technical support infrastructure before tender participation. This regulatory elevation is compressing the vendor base and favoring platforms with existing Middle East distribution networks.
Hospital procurement committees are consolidating test strip and sensor purchasing through multi-year framework agreements rather than transactional spot buying. Ministry of Health facilities in Muscat Governorate now favor single-source contracts with integrated service provisions including calibration, training, and data analytics. This concentration is visible across the Sultanate's public health system where budget predictability outweighs price optimization in tender evaluations.
Oman Diabetes Care Devices Market Segmentation
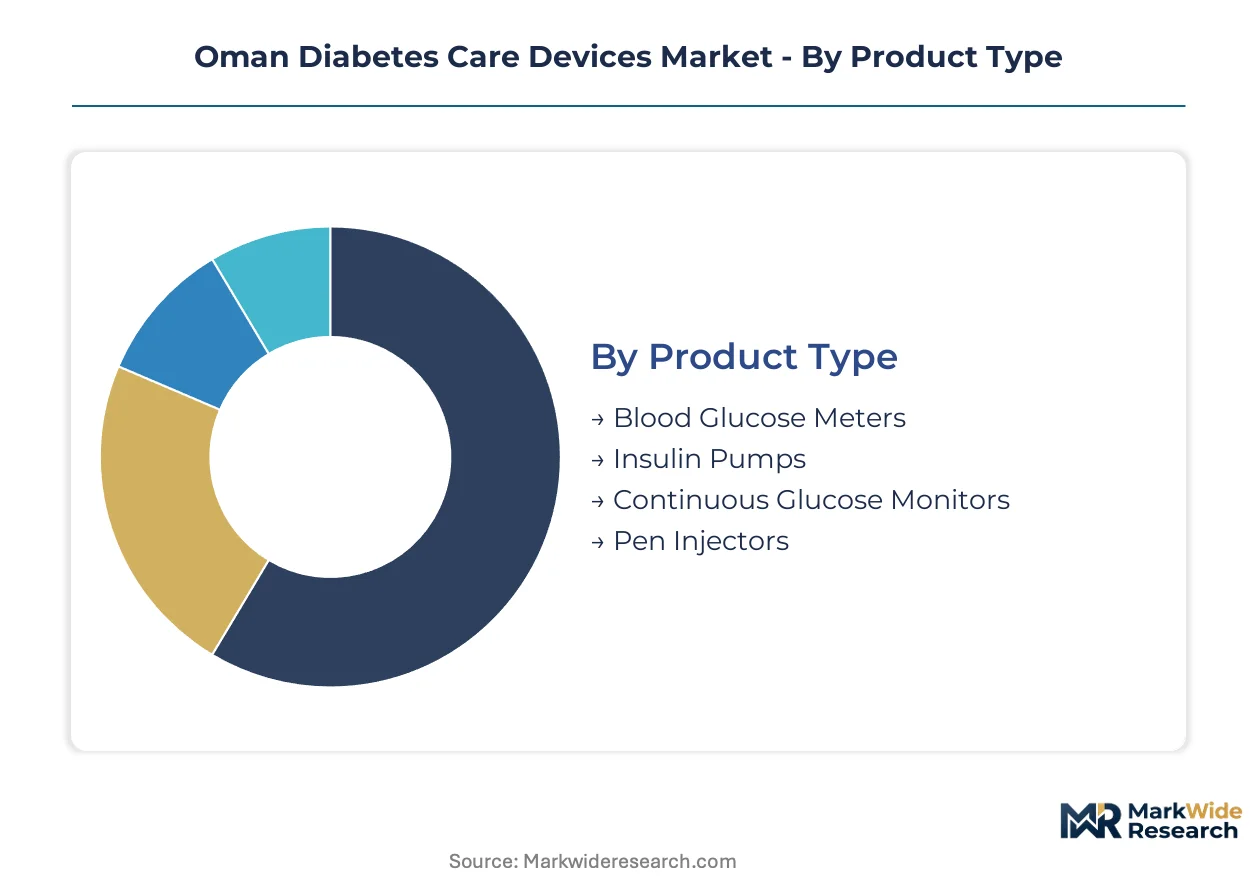
Device segmentation in Oman reveals how procurement concentration in Muscat Governorate shapes demand patterns across product categories. The Ministry of Health's tender consolidation and telemedicine infrastructure investments create divergent growth trajectories that vendors must navigate through targeted positioning.
Product Type:
Customization intensity varies sharply across this category, with hospital-integrated systems demanding extensive calibration support while home-use devices prioritize plug-and-play simplicity.
- Blood Glucose Meters:Electrochemical enzymatic reaction devices using test strips remain the dominant installed base across Oman's public health facilities. Demand concentrates in Ministry of Health hospitals where procurement committees favor multi-year framework agreements bundling devices with consumable supply; price sensitivity among uninsured home care patients slows upgrade cycles to connected alternatives.
- Continuous Glucose Monitors:Subcutaneous interstitial fluid sampling systems with real-time data transmission capture expanding margin pools as Royal Hospital and Sultan Qaboos University Hospital pilot remote monitoring protocols. Clinician demand for tighter glycemic control drives adoption among Type 1 diabetes patients in insured Muscat populations.
- Insulin Pumps:Motor-driven reservoir devices enabling programmable basal-bolus delivery serve specialized endocrinology departments requiring biomedical engineering support.
- Pen Injectors:Disposable and reusable cartridge-based delivery systems dominate multiple daily injection regimens outside pump-eligible patient cohorts.
Leading the category by volume: Blood Glucose Meters. Growing fastest: Continuous Glucose Monitors.
Technology:
Cost tier stratification separates premium connected platforms with full software lifecycle documentation from economy self-monitoring alternatives.
- Connected Devices:IEC 62304-compliant platforms with cellular or Bluetooth data transmission achieve reimbursement eligibility under evolving Ministry of Health telehealth protocols. Procurement committees in Muscat Governorate prioritize these systems for their integration with hospital information networks and remote patient management capabilities.
- Self-Monitoring:Standalone electrochemical measurement without data connectivity retains dominant transaction volumes among price-sensitive patient segments and regional facilities lacking API-compatible infrastructure.
- Digital Health:Cloud-based analytics platforms aggregating glucose data for clinical decision support require local technical support infrastructure for tender participation.
- Wearable Tech:Skin-adhesive sensor form factors with smartphone pairing target convenience-oriented home care users in urban governorates.
Volume concentration: Self-Monitoring. Steepest expansion trajectory: Connected Devices.
End User:
Application urgency drives segmentation, with acute care settings demanding continuous monitoring versus episodic home testing.
- Hospitals:Ministry of Health facilities anchor device procurement through centralized tenders favoring integrated service provisions including calibration, training, and data analytics; glycemic control protocol tightening accelerates connected monitor deployment.
- Home Care:Patient-managed glucose monitoring concentrates in Muscat and surrounding governorates where specialist diabetes clinic clustering enables prescriber support and device troubleshooting access.
- Clinics:Primary care networks receiving real-time data feeds from hospital endocrinology departments require compatible platform investments.
- Pharmacies:Over-the-counter test strip and meter distribution serves uninsured and rural patient segments outside public procurement channels.
Dominant demand source: Hospitals. Expanding most quickly: Home Care.
Distribution Channel:
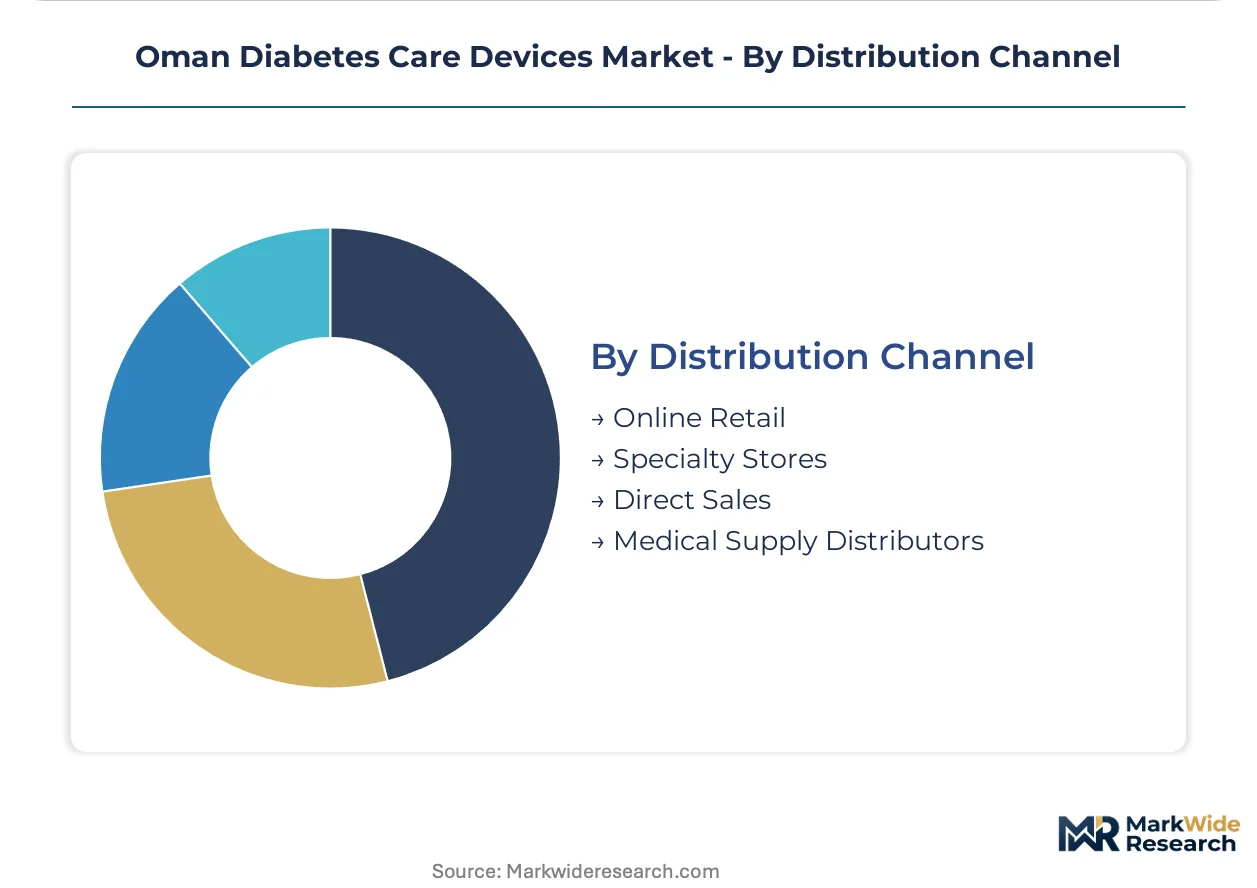
Customer type segmentation separates institutional procurement committees from individual patient purchasing decisions.
- Medical Supply Distributors:Long-standing Ministry of Health relationships sustain tender participation for vendors with established Middle East distribution networks and post-market surveillance capabilities.
- Direct Sales:Manufacturer-led contracting with hospital procurement committees enables multi-year framework agreements with integrated service provisions.
- Specialty Stores:Diabetes-focused retail channels in Muscat serve patient segments seeking device upgrade consultations.
- Online Retail:E-commerce platforms target convenience-oriented home care users with consumable replenishment and accessory purchases.
Primary volume channel: Medical Supply Distributors. Gaining share fastest: Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical feedstock availability from Oman's Sohar Industrial Port anchors device manufacturing supply chains serving the Sultanate's diabetes care market. The Ministry of Health's procurement centralization concentrates demand within Muscat Governorate while peripheral governorates remain underpenetrated. Regional distribution networks must navigate varied infrastructure maturity across Oman's eleven governorates.
Muscat Governorate
Royal Hospital and Sultan Qaboos University Hospital drive institutional demand for connected glucose monitors through pilot remote monitoring programs. The Ministry of Health's IEC 62304 compliance requirements filter device registration through centralized Muscat-based regulatory review. Specialist diabetes clinics cluster in the capital region, creating economies of scale for device deployment and patient education programs.
Al Batinah Governorate
Home care demand for self-monitoring blood glucose systems exceeds connected device penetration due to sparse specialist clinic infrastructure. The Ministry of Health's regional health directorates extend procurement frameworks from Muscat, though delivery timelines lag for remote CGM sensor replenishment. Sohar Industrial Port's logistics hub supports medical supply distributor warehousing for northern governorate coverage.
Dhofar Governorate
Seasonal population fluctuations between Salalah's coastal urban center and interior rural communities complicate continuous glucose monitoring supply chain planning. The Ministry of Health's telemedicine infrastructure investments target Salalah's tertiary care facilities for hub-and-spoke diabetes management models. Port of Salalah connectivity enables direct sensor import routes bypassing Muscat distribution intermediaries.
Ad Dakhiliyah Governorate
Nizwa's regional hospital anchors diabetes care referral patterns for mountainous interior communities with limited CGM technician availability. The Ministry of Health's framework agreements with medical supply distributors prioritize test strip volume commitments over connected device pilots in this governorate. Road infrastructure constraints extend procurement lead times for temperature-sensitive sensor shipments.
Ash Sharqiyah Governorate
Sur's fishing and maritime industrial base generates occupational health screening demand for basic blood glucose meters through employer-sponsored programs. The Ministry of Health's public health campaigns target this governorate for diabetes prevention device subsidies. Regional pharmacy networks serve uninsured patient segments outside hospital procurement channels with economy-tier self-monitoring alternatives.
Oman Diabetes Care Devices Market Competitive Landscape
Strategic partnerships dominate the current landscape as device manufacturers align with medical supply distributors possessing established Ministry of Health tender relationships. The vendor base concentrates around multinational diabetes care specialists with existing Middle East distribution networks, compressing opportunities for new entrants lacking post-market surveillance infrastructure. Three archetypes anchor competitive positioning: integrated pump-CGM ecosystem providers, test strip and sensor volume suppliers, and connected platform specialists pursuing telehealth reimbursement eligibility. Geographic expansion into underpenetrated governorates and technology licensing for local software adaptation represent the primary competitive vectors.
Among North American-headquartered multinationals, Abbott Diabetes Care, Medtronic PLC, and Dexcom Inc. exemplify divergent strategic archetypes within the connected device segment. Abbott Diabetes Care occupies a position anchored by hospital tender penetration through its FreeStyle portfolio. Medtronic PLC represents the integrated ecosystem approach combining insulin delivery with continuous glucose monitoring. Dexcom Inc. sits within the pure-play CGM specialization tier targeting clinician demand for real-time glycemic data. European competitors including Roche Diabetes Care and Novo Nordisk A/S leverage long-standing relationships with Ministry of Health distribution channels, while Ascensia Diabetes Care and Lifescan concentrate test strip volume plays. Insulet Corporation and Eli Lilly and Company anchor alternative delivery mechanism positions within the broader competitive set.
| Leading Market Players |
|---|
| Abbott Diabetes Care |
| Medtronic PLC |
| Roche Diabetes Care |
| Novo Nordisk A/S |
| Lifescan |
| Ascensia Diabetes Care |
| Dexcom Inc. |
| Insulet Corporation |
| Eli Lilly and Company |
| Others |
Value Network & Pricing Analysis
Continuous glucose monitoring platform migration from hospital to home settings simultaneously compresses per-test economics and concentrates procurement leverage within Ministry of Health framework agreements. IEC 62304 software lifecycle compliance requirements filter vendor participation, elevating certification costs while bundling calibration and technical support into multi-year tenders.
Pricing Analysis
Service bundling separates connected glucose monitors with integrated calibration support from unbundled self-monitoring alternatives sold through retail channels. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales infrastructure depth. Price differentiation hinges on IEC 62304 documentation completeness and local biomedical engineering coverage. Cost compression in economy-tier blood glucose meters intensifies as uninsured patient segments dominate pharmacy purchases. Home care users in Muscat Governorate show lowest price sensitivity due to reimbursement coverage, while rural governorates prioritize unbundled test strip affordability.
Supply Chain Analysis
Sensor refurbishment and device calibration return flows concentrate through Medtronic's and Abbott's regional service centers in Dubai and Riyadh. Manufacturing draws from Ireland, Malaysia, and the United States for electrochemical sensor substrates and Bluetooth-enabled transmitter assemblies. Raw material dependencies include palladium-based electrode coatings, medical-grade adhesives, and lithium coin cell batteries. Single-source vulnerability runs through concentrated CGM sensor fabrication in Southeast Asian contract facilities. Distribution runs through medical supply distributors with established Ministry of Health tender relationships, bypassing direct manufacturer-to-hospital contracting outside Muscat's tertiary facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into consumable sensor production represents the decisive competitive lever as procurement committees consolidate multi-year framework agreements and prioritize supply security over spot-price optimization.
For Market Incumbents: Cement tender lock-in through exclusive calibration service provisioning and biomedical engineering training partnerships with Royal Hospital and Sultan Qaboos University Hospital. Threat substitution from low-cost Asian sensor manufacturers demands backward integration into adhesive substrate formulation. Capacity addition in Jebel Ali Free Zone reduces shipping volatility exposure for CGM sensor replenishment cycles. For New Entrants and Emerging Players: Medical supply distributors with dormant Ministry of Health relationships offer the fastest channel access without multi-year tender qualification timelines. Dhofar Governorate's seasonal population flows and underpenetrated home care infrastructure present the most penetrable geography. Direct-to-clinic software companion development bypasses hospital procurement committee concentration. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated pump-CGM ecosystem providers seeking regional software adaptation capabilities. Long-term viability favors platforms with IEC 62304 documentation and existing Middle East post-market surveillance infrastructure. Watch Ministry of Health telehealth reimbursement rule finalization as the definitive demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| IEC 62304 Compliance Investment | Software lifecycle documentation unlocks Ministry of Health tender eligibility and reimbursement access. |
| Hospital System Partnership | Royal Hospital pilot programs establish reference sites for remote monitoring protocol expansion. |
| Biomedical Engineering Training Program | Local calibration capability addresses talent scarcity and reduces device downtime in regional facilities. |
| Software Companion Development | Cloud analytics integration with hospital information systems enables real-time glycemic data sharing. |
| Reimbursement Strategy | Telehealth protocol alignment with Ministry of Health expands addressable patient pool beyond insured Muscat populations. |
Research Methodology
Independent corroboration across hospital procurement committee interviews, medical supply distributor operational reviews, and regulatory affairs consultations underwrites the qualitative findings. Primary fieldwork engaged biomedical engineers at Ministry of Health facilities, GPO contracts managers, diabetes clinic endocrinologists, and pharmaceutical regulatory specialists. Secondary validation drew from device registration databases, tender announcement archives, IEC 62304 certification registries, and customs import records. Bottom-up patient population modeling and top-down healthcare expenditure triangulation anchored market sizing.
Comparable-period anchoring to historical procurement cycles and installed base transitions shaped the projection horizon. Segmentation dimensions modeled include product type, technology tier, end-user setting, and distribution channel, with additional stratification by governorate infrastructure maturity and reimbursement eligibility. CAGRs were derived from regression analysis of tender volume trends and patient population growth curves. Forecast inputs incorporated Ministry of Health telehealth infrastructure deployment timelines and evolving device registration protocol stringency.
Several conditions sit outside the modeled scope, including currency fluctuation severity, shipping route disruptions, and unannounced regulatory enforcement shifts. Forecasts reflect documented assumptions about procurement centralization continuity and reimbursement rule evolution pace. Material deviation in Ministry of Health telehealth protocol finalization or IEC 62304 compliance timeline extension warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Diabetic Footwear Market
Diabetes Care
Germany Insulin Infusion Pump Market
Diabetes Care
Insulin Patch Pumps Market
Diabetes Care
Hyperinsulinemia Hypoglycaemia Treatment Market
Diabetes Care
Asia Pacific Blood Glucose Test Strip Market
Diabetes Care
Middle East and Africa Continuous Glucose Monitoring Market
Diabetes Care
South Africa Oral Antidiabetic Drug Market
Diabetes Care
Italy Continuous Glucose Monitoring Devices Market
Diabetes Care
Point of Care Glucose Testing Market
Diabetes Care
Vietnam Diabetes Care Devices Market
Diabetes Care
Continuous Glucose Monitoring in Philippines Market
Diabetes Care
Russia Diabetes Care Devices Market
Diabetes Care
Global Type 1 Diabetes (T1D) Market
Diabetes Care
Artificial Intelligence in Diabetes Management Market
Diabetes Care
Diabetic Ketoacidosis Treatment Market
Diabetes Care
Global Diabetes Pen Market