
 Partial Ossicular Replacement Prosthesis Market | 2026-2036
Partial Ossicular Replacement Prosthesis Market Size, Share, and Industry Trends Forecast 2026-2036
Partial Ossicular Replacement Prosthesis Market Intelligence
The modularization of prosthesis components is consolidating buyer preference around adaptable surgical kits, allowing surgeons greater intraoperative flexibility. This shift favors suppliers with robust R&D and broad product portfolios. Stryker Corporation leverages its extensive distribution network to offer these configurable systems to large hospital groups. Heinz Kurz GmbH Medizintechnik specializes in high-precision titanium and gold prostheses, competing on material science and clinical outcomes.
A Partial Ossicular Replacement Prosthesis is a biocompatible implant designed to bridge the gap between the tympanic membrane and the stapes head. These devices, often made from titanium with shaft diameters between 0.2 mm and 0.8 mm, restore the sound conduction mechanism of the middle ear. Titanium-based prostheses lead the product type segment due to their superior biocompatibility and acoustic performance. Demand from ENT clinics for treating chronic otitis media constitutes the largest application, representing a mature but stable volume base.
Market access is governed by stringent medical device regulations, including FDA premarket approval in the United States and CE marking under the Medical Device Regulation (MDR) in Europe. These frameworks mandate extensive clinical data on biocompatibility and long-term efficacy, shaping product development cycles. Consequently, material innovation and the validation of new composite prostheses will determine future competitive differentiation for manufacturers.
Market Dynamics
The convergence of material science and additive manufacturing is the central force shaping the market. This allows for the creation of patient-specific implants, shifting competitive differentiation from standardized mass production toward personalized, high-performance solutions for complex ossicular chain reconstructions.
Growth Catalysts
- 3D Printing Adoption:The use of additive manufacturing technologies to create patient-specific titanium implants improves surgical outcomes and fit, stimulating demand from advanced surgical centers.
- Aging Demographics:An increasing prevalence of age-related hearing loss and chronic middle ear conditions in developed nations, such as Germany and Japan, expands the addressable patient population.
- ENT Clinic Procedure Volume:A stable and mature volume of procedures for treating chronic otitis media within specialized Ear, Nose, and Throat (ENT) clinics provides a consistent demand base for prostheses.
Market Restraints
- High Material Costs:The significant cost of medical-grade titanium and gold, the primary materials for high-performance prostheses, can limit adoption in cost-sensitive healthcare systems.
- Regulatory Scrutiny:Stringent clinical evidence requirements under frameworks like the EU's Medical Device Regulation (MDR) increase the time and expense of bringing new materials and designs to market.
- Surgical Skill Dependency:Successful outcomes are highly dependent on the specialized skills of otologic surgeons, and a limited pool of trained experts can constrain procedural growth in some regions.
Strategic Opportunities
- Bioabsorbable Materials:Research into novel composite and bioabsorbable materials offers a pathway to creating prostheses that support natural tissue regeneration and then degrade, eliminating the need for a permanent implant.
- Emerging Market Penetration:Expanding distribution and training programs in countries like Brazil and India, where healthcare spending is rising, presents an opportunity to address a large, underserved patient base.
- Smart Prostheses:Integrating micro-sensors into implants to monitor post-operative healing and middle ear pressure could create a new premium product tier focused on data-driven patient management.
Industry Challenges
- Reimbursement Complexity:Navigating disparate and often inadequate reimbursement codes for ossiculoplasty procedures across different national and private payer systems complicates market access and profitability.
- Long-Term Efficacy Data:Generating the extensive, multi-year clinical data required by regulators like the FDA to prove the long-term biocompatibility and acoustic stability of new devices is a major operational hurdle.
- Supply Chain Validation:Ensuring the quality and consistency of raw materials, such as titanium alloys, requires rigorous supplier validation and certification, adding complexity to the supply chain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Partial Ossicular Replacement Prosthesis Market |
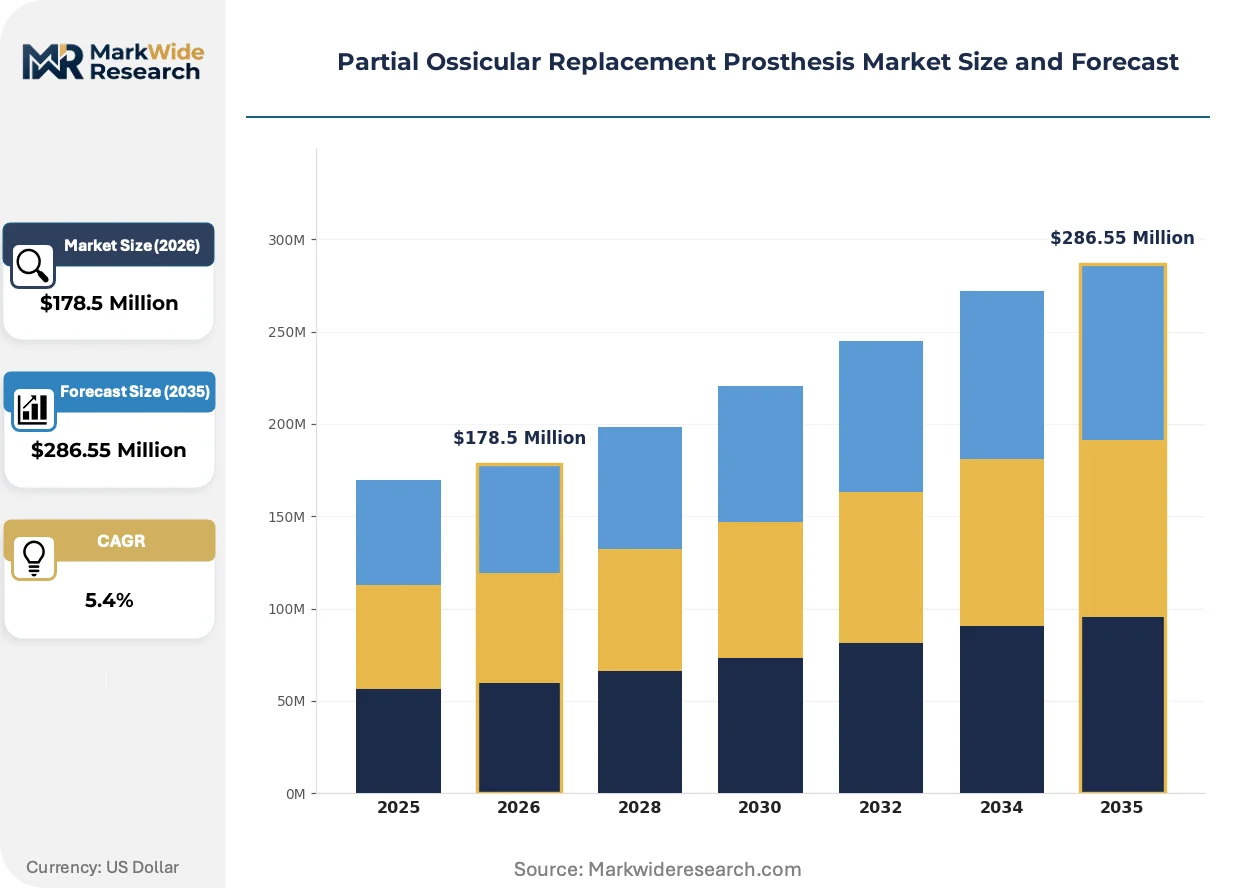
| Market Size in 2026 | $178.5 Million |
| Market Size in 2035 | $286.55 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Titanium, Hydroxyapatite, Ceramic, Polymer, Composite Application: Chronic Otitis Media, Trauma Repair, Ossicular Chain Reconstruction, Eustachian Tube Dysfunction End User: ENT Clinics, Specialized Audiology Centers, Tertiary Care Hospitals, Hearing Implant Centers Technology: 3D Printing, Laser Sintering, Mold Casting, Computer-Aided Design |
| Companies Covered | Stryker Corporation, Heinz Kurz GmbH Medizintechnik, Medtronic, Cochlear Limited, Spiggle & Theis, Olympus Corporation, Sonova, Karl Storz SE & Co. KG, Grace Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Partial Ossicular Replacement Prosthesis Market Strategic Shifts & Innovations
Precision and personalization are becoming the new competitive benchmarks in the prosthesis market. This evolution is driven by advancements in material processing and tightening regulatory demands for clinical evidence, pushing manufacturers toward more sophisticated and patient-adapted solutions.
Additive manufacturing enables the fabrication of customized titanium prostheses based on individual patient anatomy. Tertiary care hospitals are increasingly adopting this technology for complex revision surgeries and unique anatomical variations. This capability is consolidating the high-value segment of the market around suppliers with expertise in both medical imaging and 3D printing, reducing the one-size-fits-all approach of traditional implants.
Europe's Medical Device Regulation (MDR) is intensifying the focus on lifecycle management for medical devices. This framework requires manufacturers to provide more robust clinical data on long-term performance and biocompatibility. Consequently, companies producing both titanium and newer composite prostheses are investing heavily in post-market surveillance systems to maintain their CE marking and demonstrate sustained efficacy.
Surgical preferences are evolving toward modular prosthesis kits that offer greater intraoperative flexibility. This trend displaces the reliance on single, fixed-size implants by providing surgeons with a system of interchangeable components to better match the specific needs of a patient's anatomy discovered during surgery. This shift is most visible in the United States market, where large hospital networks favor systems that can streamline inventory and adapt to a wider range of clinical scenarios.
Partial Ossicular Replacement Prosthesis Market Segmentation
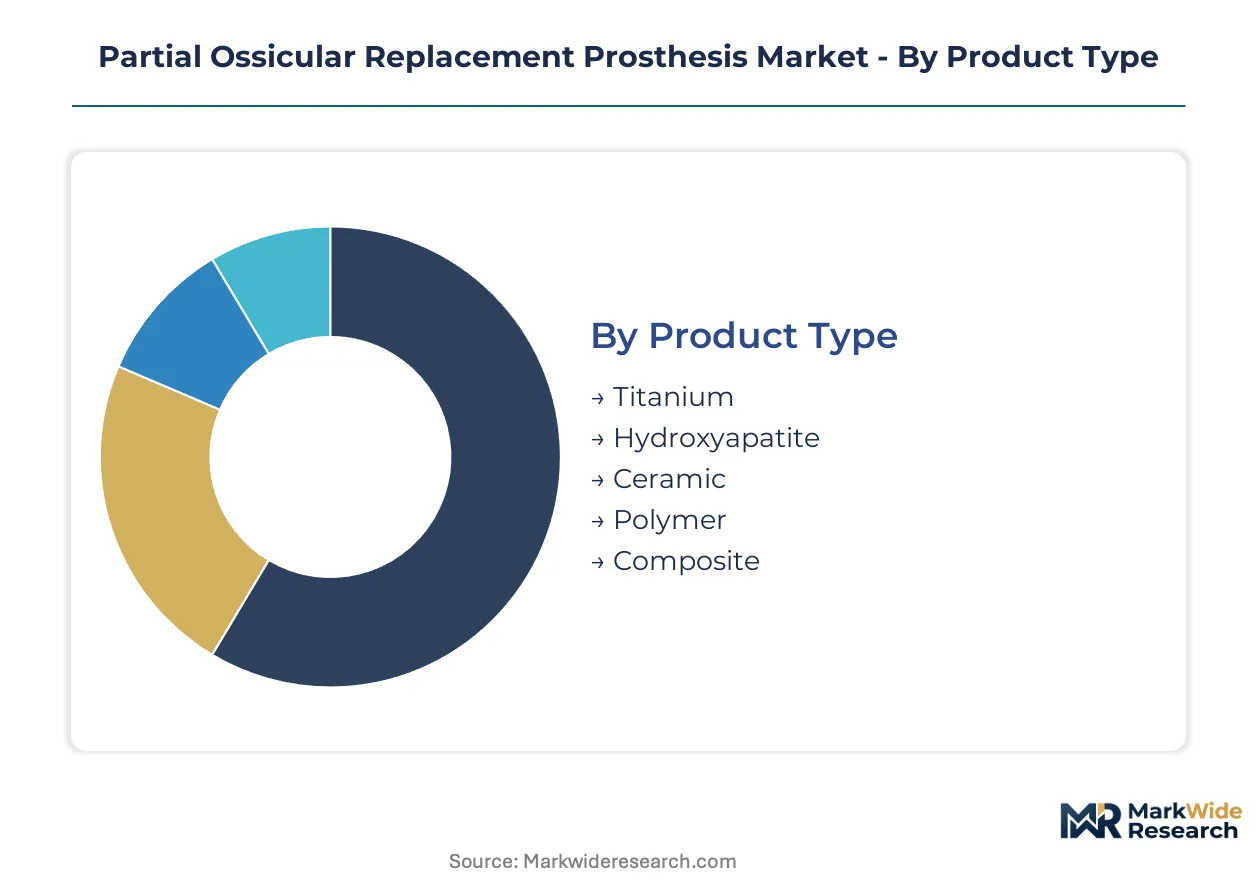
The Partial Ossicular Replacement Prosthesis market is highly stratified, reflecting diverse patient needs, material science advancements, and varied clinical settings. Understanding these segments is critical for manufacturers to align product development and distribution strategies with specific market demands and regulatory pathways.
Product Type:
Supply concentration in the Partial Ossicular Replacement Prosthesis market heavily favors materials offering superior biocompatibility and acoustic performance.
- Titanium:These prostheses are widely used due to their excellent biocompatibility, inertness, and superior acoustic transmission properties, making them a preferred choice for restoring middle ear function. Demand from ENT clinics for chronic otitis media procedures heavily utilizes titanium implants due to their established clinical efficacy.
- Composite:These devices integrate multiple materials to leverage combined benefits, such as enhanced flexibility, reduced weight, or improved tissue integration, aiming for superior long-term outcomes. Material innovation and the validation of new composite prostheses will determine future competitive differentiation in the market.
- Hydroxyapatite:Prostheses made from hydroxyapatite are valued for their osteoconductive properties, promoting bone ingrowth and integration with surrounding tissue.
- Ceramic:Ceramic prostheses offer high rigidity and biocompatibility, providing stable support for ossicular chain reconstruction in specific clinical scenarios.
- Polymer:Polymer-based implants offer flexibility and can be designed for specific biomechanical properties, though their long-term acoustic performance is still under evaluation.
Titanium absorbs the bulk of installed capacity; Composite is expanding most quickly.
Application:
The volume of procedures dictates the prominence of various applications for ossicular replacement prostheses.
- Chronic Otitis Media:This application represents a mature and stable volume base, with prostheses used to repair ossicular damage resulting from persistent middle ear inflammation and infection. Specialized ENT clinics consistently drive demand for these standard procedures.
- Ossicular Chain Reconstruction:These complex surgical procedures aim to restore the continuity of the ossicular chain following damage from trauma, disease, or congenital anomalies, often requiring patient-specific implants in tertiary care hospitals. The adoption of 3D printing technology for custom prostheses stimulates demand in this segment.
- Trauma Repair:Prostheses are utilized to reconstruct the middle ear ossicles following traumatic injuries, such as head trauma or direct ear canal impact.
- Eustachian Tube Dysfunction:While less common for direct prosthesis use, this application involves addressing underlying conditions that can lead to ossicular damage, sometimes requiring adjunctive procedures.
Chronic Otitis Media procedures command the largest volume base; Ossicular Chain Reconstruction exhibits the steepest expansion trajectory.
End User:
Customer type significantly influences the demand profile for advanced ossicular replacement prostheses.
- Tertiary Care Hospitals:These institutions handle complex ossicular chain reconstruction procedures, often requiring advanced imaging and patient-specific implant solutions, leveraging their specialized surgical expertise and infrastructure. The demand for customized 3D printed implants is concentrated here.
- ENT Clinics:These specialized clinics represent a stable demand base for ossicular prostheses, particularly for treating chronic otitis media and other common middle ear conditions. These clinics serve as primary points of care for initial diagnosis and treatment.
- Specialized Audiology Centers:These centers focus on comprehensive hearing diagnostics and rehabilitation, often collaborating with surgeons for implant selection and post-operative care.
- Hearing Implant Centers:These facilities specialize in various hearing solutions, including ossicular prostheses, catering to patients requiring advanced surgical interventions for hearing restoration.
Tertiary Care Hospitals drive the highest value purchases; Specialized Audiology Centers are gaining share fastest.
Technology:
Innovation in manufacturing technologies is reshaping the competitive landscape for prosthesis production.
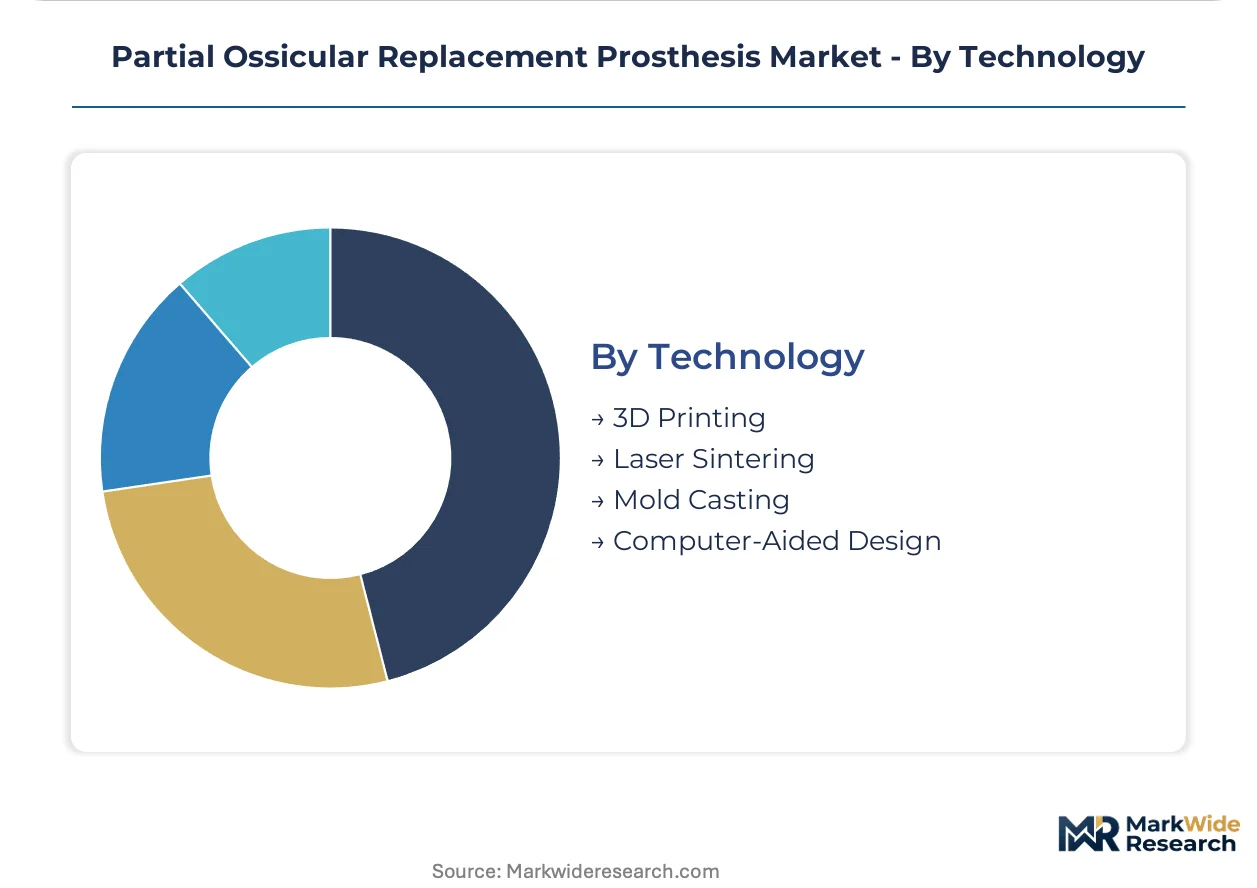
- 3D Printing:This additive manufacturing technology enables the creation of highly customized, patient-specific titanium implants with complex geometries, improving fit and surgical outcomes. Advanced surgical centers are increasingly adopting this technology for complex revision surgeries.
- Computer-Aided Design:CAD software is instrumental in designing precise and anatomically accurate prostheses, facilitating rapid prototyping and seamless integration with 3D printing processes. This technology underpins the development of personalized solutions.
- Laser Sintering:A specific form of 3D printing, laser sintering uses a laser to fuse powdered materials, often titanium, into a solid structure, offering high precision for medical implants.
- Mold Casting:This traditional manufacturing method involves pouring molten material into a mold to create prostheses, offering cost-effective production for standardized designs.
Mold Casting remains a foundational production method; 3D Printing represents the fastest-growing trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global landscape for partial ossicular replacement prostheses shows a distinct divide between advanced manufacturing hubs and regions with high procedural volumes. Production of high-precision implants often centralizes in developed economies with robust R&D capabilities. Consumption, however, expands across diverse markets driven by demographic shifts and evolving healthcare access.
United States
High procedural volumes and advanced healthcare infrastructure drive significant demand in the United States. FDA premarket approval dictates rigorous clinical data requirements for new devices entering this lucrative market. Medical technology clusters in states like Massachusetts and California foster innovation in patient-specific implant development.
Germany
Germany experiences substantial demand due to its aging demographics and high prevalence of middle ear conditions. CE marking under the Medical Device Regulation (MDR) sets stringent standards for device approval and post-market surveillance. Cities like Tuttlingen and regions such as Bavaria house specialized manufacturers focusing on high-precision surgical instruments and implants.
Japan
Japan's rapidly aging population fuels a consistent demand for ossicular prostheses, supported by high standards of medical care. PMDA approval processes emphasize long-term efficacy and biocompatibility for medical devices. Major metropolitan areas like Tokyo and Osaka are centers for advanced medical research and precision manufacturing of implants.
China
China presents a significant growth opportunity due to its vast patient population and increasing healthcare expenditure. NMPA approval is crucial for market access, focusing on safety and performance data for imported and domestic devices. Industrial zones in the Yangtze River Delta and innovation hubs in Beijing are developing capabilities for advanced medical device production.
Brazil
Brazil offers an emerging market for ossicular prostheses, driven by rising healthcare spending and efforts to expand access to specialized ENT procedures. ANVISA approval ensures medical device quality and safety for the Brazilian market. Major cities like São Paulo and Rio de Janeiro are central to the country's growing network of advanced surgical centers.
Partial Ossicular Replacement Prosthesis Market Key Industry Players
The competitive structure tilts toward specialized manufacturers and diversified medical technology giants. This market exhibits a blend of established consolidation among larger players and dynamic fragmentation among niche specialists. Key strategic archetypes include high-precision material specialists, broad-portfolio solution providers, and patient-specific implant innovators leveraging additive manufacturing. Companies frequently engage in strategic partnerships for technology integration and pursue portfolio diversification to address varied clinical needs and expand market reach.
On the premium-tier vector, Heinz Kurz GmbH Medizintechnik, a German-based specialist, exemplifies a focus on material science and high-precision titanium and gold prostheses. This company represents the archetype of a niche innovator emphasizing clinical outcomes and advanced material properties. Conversely, Stryker Corporation, a diversified medical technology firm, occupies a position as a broad-portfolio solution provider. Its extensive distribution network anchors its approach to offering configurable systems to large hospital groups. Medtronic, another global medical device giant, sits within the large-scale solution provider segment, focusing on comprehensive offerings across various surgical disciplines.
| Leading Market Players |
|---|
| Stryker Corporation |
| Heinz Kurz GmbH Medizintechnik |
| Medtronic |
| Cochlear Limited |
| Spiggle & Theis |
| Olympus Corporation |
| Sonova |
| Karl Storz SE & Co. KG |
| Grace Medical |
| Others |
Cost & Logistics Intelligence
Additive manufacturing technology fundamentally reshapes the cost economics and supply concentration for partial ossicular replacement prostheses. This transition from standardized production to patient-specific solutions introduces new cost drivers related to design, materials, and validation, influencing pricing power.
Pricing Analysis
Cost-down pressure on standard titanium prostheses accelerates because of increasing competition and established manufacturing processes. The dominant pricing model remains per-unit transactional, with a premium value-based pricing structure for highly customized, patient-specific implants. Price differentiation drivers include the level of customization for complex cases and the biocompatibility grade of the material, such as medical-grade titanium. Tertiary care hospitals, requiring advanced patient-specific solutions, exhibit lower price sensitivity compared to ENT clinics focused on high-volume standard procedures.
Supply Chain Analysis
Reverse logistics for explanted prostheses are minimal, focusing primarily on material disposal rather than refurbishment due to sterility and patient-specific design requirements. Geographic supply concentration for high-precision implants centers around Germany, the United States, and Japan, leveraging advanced manufacturing capabilities. Raw material dependencies include medical-grade titanium alloys and specialized composite materials. A structural supply chain risk involves single-source vulnerability for novel composite materials requiring specific regulatory approvals. Distribution runs through direct sales channels to large hospital networks and specialized medical device distributors serving ENT clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Partial Ossicular Replacement Prosthesis market functions as a cost-of-compliance story, where stringent regulations like the EU's Medical Device Regulation (MDR) create a significant barrier-to-entry moat for established, compliant players.
For Market Incumbents: Lock in long-term procurement agreements for medical-grade titanium and advanced composite materials to mitigate commodity price volatility. Invest in expanded clinical data generation to satisfy evolving regulatory requirements, particularly for long-term efficacy and biocompatibility. Develop modular prosthesis kits to offer greater intraoperative flexibility, defending against niche innovators with single-product offerings. Expand distribution networks in emerging markets like Brazil to leverage rising healthcare expenditure and address underserved patient populations.
For New Entrants and Emerging Players: Online platforms for surgical planning and patient-specific implant design offer a digital-channel route to collaborate directly with advanced surgical centers. Target the patient-specific implant segment, leveraging 3D printing capabilities for complex ossicular chain reconstructions. Focus on novel bioabsorbable materials that support natural tissue regeneration, offering a distinct value proposition in an underpenetrated segment. A go-to-market angle could involve direct-to-surgeon education and training programs highlighting superior fit and outcomes.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified medical technology giants seeking to expand their ENT portfolios or acquire advanced manufacturing capabilities. Long-term viability over a 5-10 year window favors companies with proprietary material science and robust regulatory compliance records. Target niche innovators specializing in 3D printed, patient-specific solutions or those developing novel composite prostheses. The signal to watch for inflection is successful clinical trial completion and subsequent regulatory approval for next-generation bioabsorbable or smart prostheses.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in 3D Printing R&D | Enhances capability for patient-specific implants, improving surgical outcomes and fit. |
| Expand Clinical Data Collection | Satisfies stringent FDA and MDR requirements, securing market access and competitive differentiation. |
| Develop Modular Prosthesis Kits | Offers surgeons greater intraoperative flexibility, consolidating buyer preference in large hospital groups. |
| Penetrate Emerging Markets | Addresses a large, underserved patient base in countries like Brazil with rising healthcare spending. |
| Research Bioabsorbable Materials | Creates prostheses that support natural tissue regeneration, eliminating the need for permanent implants. |
Research Approach
FDA filings, CE marking documentation, and peer-reviewed medical journal publications formed the secondary backbone for market sizing and trend identification. This was triangulated with primary interviews conducted with otologic surgeons, hospital procurement managers, medical device engineers, and regulatory affairs specialists. Bottom-up and top-down data validation refined market estimates.
Historical trendline analysis established foundational growth trajectories across the analysis window. The forecast framework modeled market expansion based on product type (titanium, composite), application (chronic otitis media, ossicular chain reconstruction), end-user (tertiary care hospitals, ENT clinics), and key geographies. Compound annual growth rates were derived from a blend of historical performance and projected shifts in technology adoption. Key forecast inputs included aging demographic trends and healthcare infrastructure development.
The model holds under current regulatory and technological conditions; deviation in material science breakthroughs or reimbursement policy shifts would alter projections. Forecasts reflect assumptions documented through extensive industry engagement and data analysis. Practitioners should monitor regulatory changes and advancements in additive manufacturing for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Russia Massage Equipment Market
Medical Devices
Europe Artificial Organs and Bionic Implants Market
Medical Devices
Global Skin Grafting Device Market
Medical Devices
Male Artificial Urinary Sphincter Market
Medical Devices
Gastric Space-Occupying Devices Market
Medical Devices
Cryoablation Devices Market
Medical Devices
North America Electroencephalography Devices Market
Medical Devices
Global Medical Sensor Market
Medical Devices
Occlusion Microcatheter Market
Medical Devices
Directed Energy Based Surgical Systems Market
Medical Devices
Tissue Embedding Center Market
Medical Devices
Contact Lens Lubricant Market
Medical Devices
Italy Aesthetic Devices Market
Medical Devices
Appendage Management Market
Medical Devices
Medical Pendant Market
Medical Devices
Ovulation Microscope Market