
 BRICS Diabetes Drugs Market | 2026-2036
BRICS Diabetes Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
BRICS Diabetes Drugs Market Intelligence
The reliance on government-led bulk procurement tenders is narrowing the field of viable competitors in several BRICS nations. This environment favors companies with significant manufacturing scale and logistical prowess. Novo Nordisk A/S dominates the insulin segment with its established portfolio and brand recognition. Biocon Ltd leverages its biosimilar development capabilities, while Sanofi maintains a strong presence through its extensive distribution channels in Brazil and China.
BRICS diabetes drugs are pharmaceutical agents that regulate blood glucose levels in patients. These compounds function by various mechanisms, including stimulating pancreatic insulin secretion or improving cellular insulin sensitivity. While Biguanides remain the high-volume foundation for managing Type 2 Diabetes, newer drug classes are gaining traction. GLP-1 Receptor Agonists and SGLT2 Inhibitors represent the fastest-growing segments, driven by superior efficacy and cardiovascular benefits despite higher price points.
Market access within BRICS is governed by distinct national regulatory bodies. China's NMPA and India's CDSCO enforce rigorous approval processes, while Brazil's ANVISA oversees pricing and post-market surveillance. These regulations create a complex compliance matrix for multinational and domestic firms alike. Successfully navigating the varied reimbursement policies and public health priorities across these key markets will determine long-term commercial success.
Market Dynamics
The central dynamic shaping the BRICS diabetes drugs market is the tension between price-sensitive public procurement systems and clinical demand for high-efficacy, premium-priced therapies. This creates a bifurcated market structure, rewarding both large-scale generic producers and innovative biopharmaceutical firms.
Growth Catalysts
- Policy Incentives:India's Production Linked Incentive (PLI) scheme for pharmaceuticals is directly boosting domestic manufacturing capacity for both active pharmaceutical ingredients (APIs) and finished formulations, enhancing supply chain resilience.
- Urbanization and Diagnostics:Rising healthcare expenditure and improved diagnostic infrastructure in major urban clusters across China and India are accelerating patient identification and subsequent treatment initiation for Type 2 diabetes.
- Superior Clinical Outcomes:Newer drug classes, specifically GLP-1 Receptor Agonists and SGLT2 Inhibitors, are demonstrating significant cardiovascular and renal benefits beyond glycemic control, driving physician and patient preference despite their cost.
Market Restraints
- Pricing Pressure:Government-led bulk procurement programs, particularly in China and Brazil, exert significant downward pressure on the prices of mature drugs like metformin and older insulins, compressing margins for suppliers.
- Complex Regulatory Pathways:Navigating the distinct and rigorous approval processes of national bodies like China's NMPA, India's CDSCO, and Brazil's ANVISA creates substantial compliance costs and extends time-to-market.
- Reimbursement Hurdles:Limited public reimbursement for newer, high-cost therapies in several BRICS nations restricts patient access and confines their use primarily to the affluent population or private insurance markets.
Strategic Opportunities
- Digital Health Integration:Combining diabetes medications with digital health platforms, such as mobile apps for adherence tracking and continuous glucose monitoring (CGM) data, offers a path to value-added services and improved patient outcomes.
- Biosimilar Expansion:The expiration of patents for first-generation biologic drugs, including certain insulins and GLP-1 agonists, creates a significant opportunity for biosimilar developers in markets like Brazil and South Africa.
- Rural Market Penetration:Developing low-cost formulations and strengthening distribution networks to reach under-served rural populations in India and Brazil represents a long-term volume growth opportunity.
Industry Challenges
- Cold Chain Logistics:Maintaining the integrity of temperature-sensitive biologics like insulin and GLP-1 agonists across vast and climatically diverse territories in BRICS nations presents a significant logistical and cost challenge.
- Intellectual Property Disputes:The push for local manufacturing and biosimilar entry, encouraged by national industrial policies, is leading to increased intellectual property conflicts and patent litigation with originator companies.
- Counterfeit Drug Proliferation:Weak enforcement in parts of the supply chain allows counterfeit diabetes drugs to enter the market, posing a severe risk to patient safety and eroding brand trust.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | BRICS Diabetes Drugs Market |
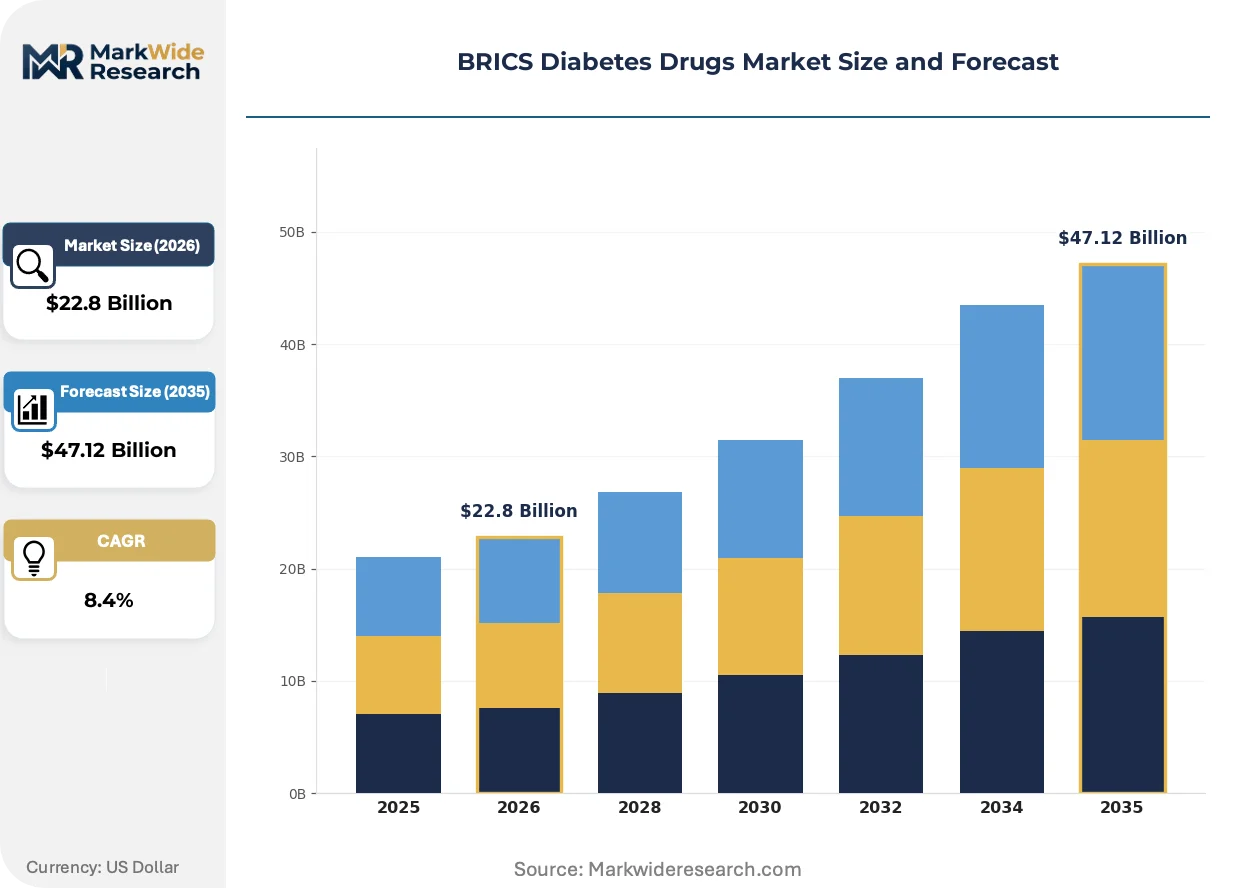
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $47.12 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin, Biguanides, Sulfonylureas, DPP-4 Inhibitors, GLP-1 Receptor Agonists, SGLT2 Inhibitors Application: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Prediabetes, Diabetic Ketoacidosis, Hyperglycemia Management End User: Hospitals, Diabetes Clinics, Ambulatory Care Centers, Diagnostic Laboratories, Home Care Providers, Specialized Pharmacies Distribution Channel: Retail Pharmacies, Hospital Pharmacies, Online Pharmacies, Wholesale Distributors, Direct Sales, Government Supply |
| Companies Covered | Merck & Co. Inc., Biocon Ltd, Novo Nordisk A/S, Dr. Reddy's Laboratories Ltd, Sun Pharma Industries Ltd, Sanofi, Abbott Laboratories, Boehringer Ingelheim, Eli Lilly and Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
BRICS Diabetes Drugs Market Strategic Shifts & Innovations
The market is undergoing a fundamental shift, moving from a singular focus on glycemic control to a more holistic approach that values cardiovascular and renal protection. This evolution favors newer therapeutic classes, even as health systems grapple with their associated costs and access challenges.
Advanced drug delivery systems provide a key avenue for product differentiation. Patient preference and clinical demand are migrating from traditional vials and syringes to user-friendly formats like pre-filled insulin pens and auto-injectors for GLP-1 agonists. This trend is most pronounced in urban centers with higher disposable incomes, where convenience and dosing accuracy are prioritized by patients and physicians.
China's national Volume-Based Procurement (VBP) program is a powerful regulatory force altering market competition for mature pharmaceuticals. The policy consolidates demand to secure major price reductions on off-patent drugs, including foundational diabetes treatments like metformin. This forces suppliers to compete aggressively on cost and manufacturing efficiency, impacting the oral antidiabetics segment most acutely and spurring a strategic pivot toward innovation.
A notable behavioral shift is occurring as cardiologists and nephrologists become more involved in prescribing diabetes medications. This is driven by compelling clinical trial data demonstrating the cardio-renal protective benefits of SGLT2 inhibitors and GLP-1 receptor agonists. This prescribing pattern is most evident within the private healthcare systems of Brazil and India, where specialist physicians can more readily specify these advanced, outcome-focused therapies.
BRICS Diabetes Drugs Market Segmentation
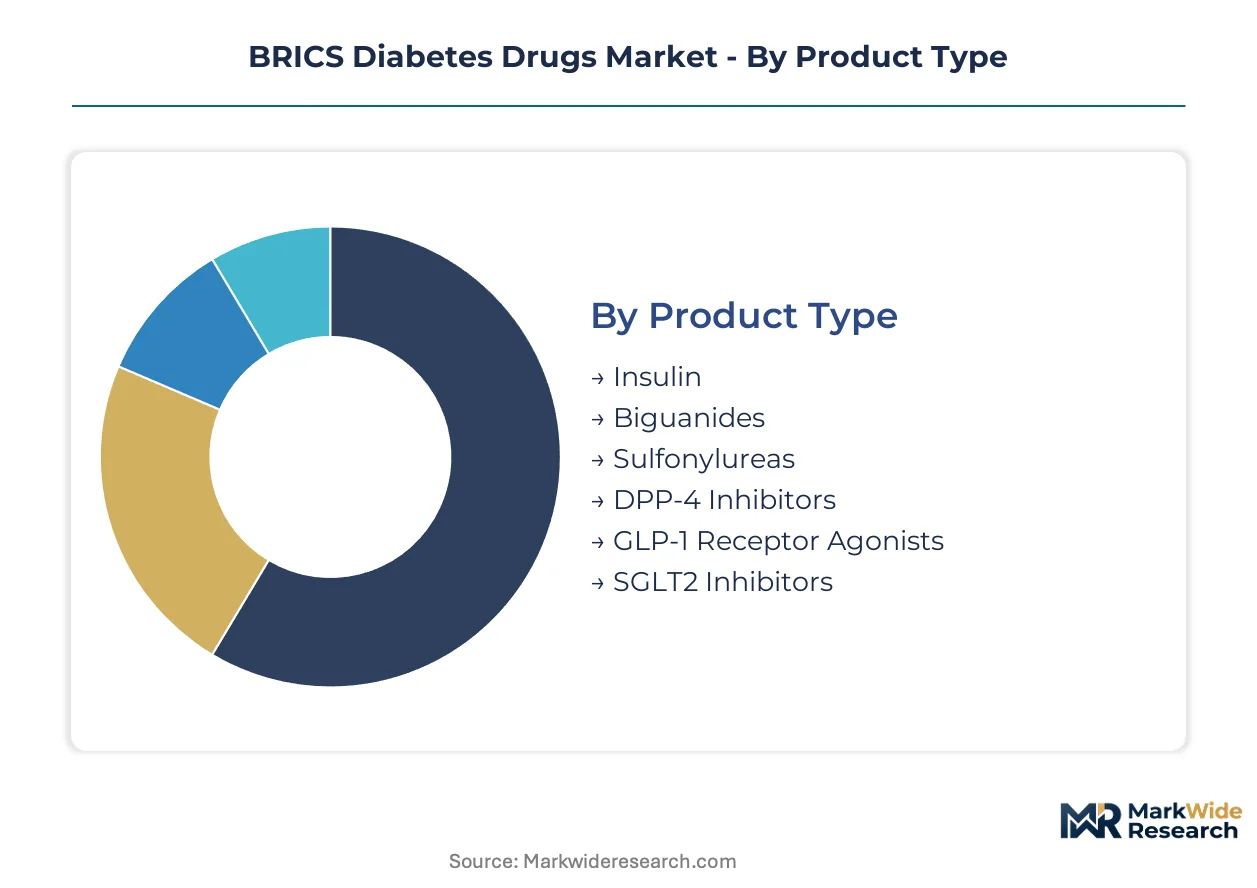
The BRICS diabetes drugs market segmentation provides a granular view of therapeutic approaches and patient care pathways. Understanding these distinct segments helps manufacturers and healthcare providers tailor strategies for drug development, distribution, and patient access across diverse economic and regulatory landscapes.
Product Type:
The use-case spectrum for diabetes drugs ranges from foundational glucose control to advanced multi-benefit therapies.
- Insulin:This essential hormone regulates carbohydrate and fat metabolism, enabling glucose uptake by cells. Demand concentrates in major urban centers of China and India, driven by increasing Type 1 diabetes diagnoses and advanced Type 2 cases requiring intensive management.
- GLP-1 Receptor Agonists:These injectable drugs mimic natural incretins, stimulating insulin release and slowing gastric emptying. Rapid adoption occurs within private healthcare systems in Brazil, driven by superior glycemic control and demonstrated cardiovascular benefits.
- Biguanides:Metformin, the primary drug in this class, reduces glucose production by the liver and improves insulin sensitivity.
- Sulfonylureas:These oral medications stimulate insulin secretion from pancreatic beta cells.
- DPP-4 Inhibitors:These drugs enhance the body's natural ability to lower elevated glucose levels.
- SGLT2 Inhibitors:These oral therapies reduce glucose reabsorption in the kidneys, promoting its excretion.
Established volume favors Biguanides; emerging adoption favors GLP-1 Receptor Agonists.
Application:
The volume of patient populations dictates the focus for various diabetes drug applications.
- Type 2 Diabetes:This chronic condition results from insulin resistance or insufficient insulin production, requiring long-term glucose management. High prevalence in India and China drives the largest drug volumes, particularly for oral antidiabetics and newer injectables.
- Type 1 Diabetes:An autoimmune condition where the pancreas produces little to no insulin, necessitating lifelong insulin therapy. Brazil's public health system provides essential insulin access, supporting a consistent demand for these critical medications.
- Gestational Diabetes:This condition develops during pregnancy, often requiring temporary insulin or oral medication to manage blood glucose.
- Prediabetes:Characterized by elevated blood glucose levels not yet high enough for a diabetes diagnosis, it often involves lifestyle interventions.
- Diabetic Ketoacidosis:A serious complication of diabetes, requiring immediate medical intervention, often with intravenous insulin.
- Hyperglycemia Management:Broader management of high blood sugar levels in various clinical settings.
Extensive demand for Type 2 Diabetes treatments expands most quickly, while Type 1 Diabetes treatments maintain critical, stable demand.
End User:
Customer type defines the procurement and delivery models for diabetes drugs across BRICS nations.
- Hospitals:These institutions provide acute care and manage complex diabetes cases, including initial diagnosis and stabilization. Procurement through bulk tenders in China and Brazil drives significant volumes of both insulins and oral antidiabetics for inpatient and outpatient dispensing.
- Diabetes Clinics:Specialized facilities offering comprehensive diabetes management, education, and follow-up care. These clinics in India increasingly prescribe advanced therapies like GLP-1 Receptor Agonists due to specialist physician influence and patient preference.
- Ambulatory Care Centers:These outpatient facilities provide routine check-ups and medication management for stable diabetes patients.
- Diagnostic Laboratories:These facilities play a crucial role in screening, diagnosis, and monitoring of diabetes, influencing treatment initiation.
- Home Care Providers:Professionals assisting patients with medication administration and monitoring in their homes.
- Specialized Pharmacies:Pharmacies focusing on chronic disease management, offering counseling and specific diabetes medications.
Hospitals represent the foundational volume segment, with Diabetes Clinics gaining share fastest for specialized care.
Distribution Channel:
Supply concentration shapes the accessibility and pricing of diabetes drugs in BRICS markets.
- Retail Pharmacies:These provide direct patient access to prescribed and over-the-counter diabetes medications. Extensive networks in India and Brazil ensure broad geographic reach, particularly for established oral antidiabetics and older insulin formulations.
- Hospital Pharmacies:Integrated within hospital systems, these pharmacies dispense medications for inpatient use and discharge. They are crucial for managing acute diabetes complications and initiating new therapies under physician supervision.
- Online Pharmacies:Digital platforms offering convenient home delivery of diabetes medications, gaining traction in urban areas.
- Wholesale Distributors:These intermediaries manage large-scale logistics, connecting manufacturers to various healthcare providers and pharmacies.
- Direct Sales:Manufacturers selling directly to large institutional buyers or government programs.
- Government Supply:Centralized procurement and distribution by national health ministries for public health programs.
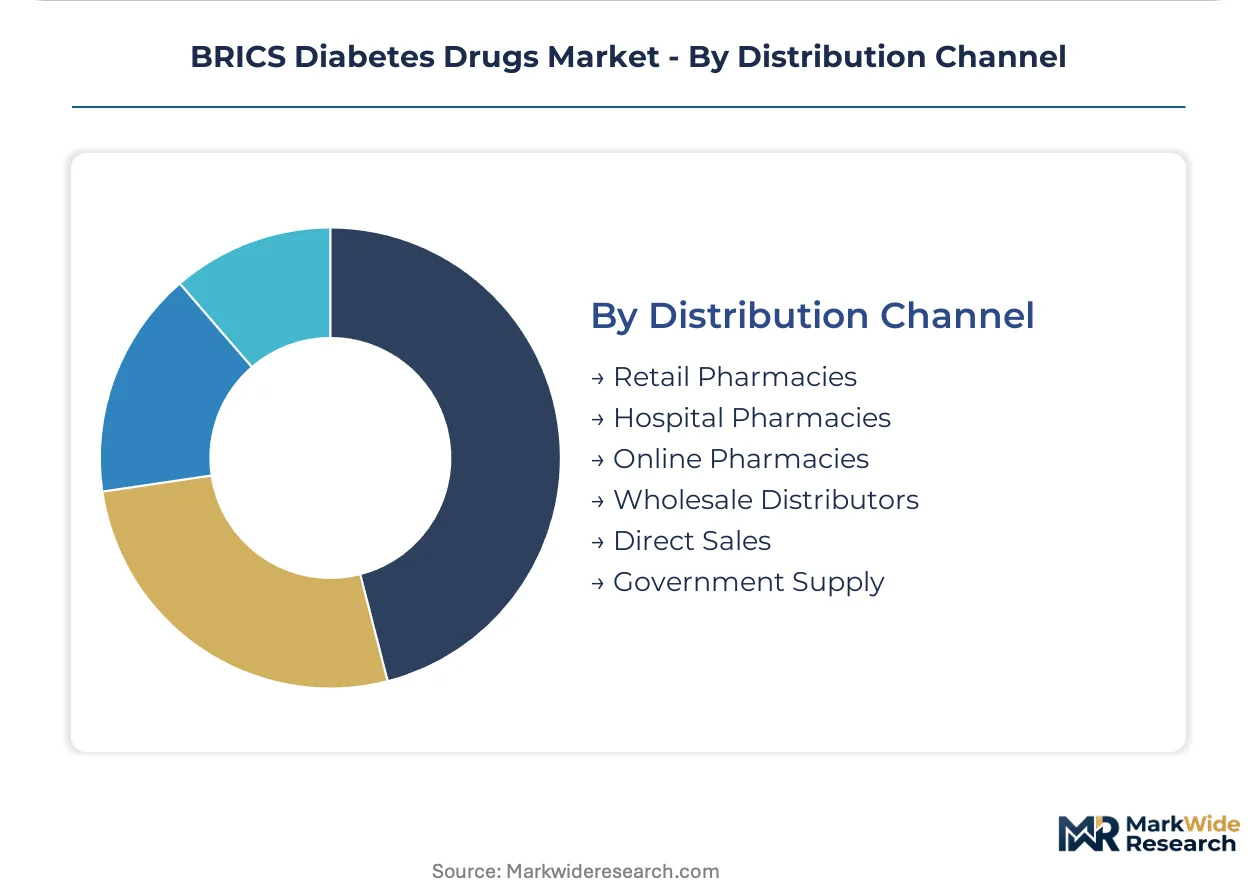
Retail Pharmacies dominate patient access, while Government Supply channels influence pricing significantly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Production Linked Incentive (PLI) scheme for pharmaceuticals is directly boosting domestic manufacturing capacity for both active pharmaceutical ingredients and finished formulations. This policy support, combined with expanding treatment protocols, shapes regional market dynamics. Urbanization and improved diagnostics further accelerate patient identification across BRICS nations.
India
High prevalence of Type 2 Diabetes and improving diagnostic access drive significant demand for diabetes drugs. India's CDSCO enforces rigorous approval processes, while the PLI scheme supports domestic API and formulation manufacturing. Major urban centers like Delhi-NCR and Mumbai are seeing increased treatment initiation for various diabetes types.
China
China's large patient population for Type 2 Diabetes and rising healthcare spending fuel substantial market expansion. The NMPA governs drug approvals, and the national Volume-Based Procurement (VBP) program drives price reductions for mature drugs. Urban clusters in the Yangtze River Delta concentrate demand for advanced therapies and specialized care.
Brazil
Brazil's consistent demand for insulin, particularly for Type 1 Diabetes, is supported by its public health system. ANVISA oversees pricing and post-market surveillance. Rapid adoption of GLP-1 Receptor Agonists occurs within private healthcare systems, driven by specialist physician influence in São Paulo and Rio de Janeiro.
South Africa
Expanding treatment protocols for Type 2 Diabetes contribute to the growing demand for diabetes drugs in South Africa. The country's national pharmaceutical regulator manages market access and reimbursement policies. Major metropolitan areas like Johannesburg and Cape Town show higher patient identification rates and adoption of newer therapies.
BRICS Diabetes Drugs Market Key Industry Players
Channel-controlling players compete with product-specialist players, creating a bifurcated market structure. The BRICS diabetes drugs market exhibits characteristics of both consolidation for foundational therapies and fragmentation for innovative segments. Strategic archetypes include large multinational pharmaceutical companies, domestic generic manufacturers, and biosimilar developers. Competitive moves involve capacity expansion for generics and portfolio diversification into newer drug classes.
Within the multinational pharmaceutical tier, Novo Nordisk A/S exemplifies dominance in the insulin segment with its established portfolio. Sanofi maintains a strong presence through extensive distribution channels, particularly in Brazil and China. Biocon Ltd represents the biosimilar development archetype, leveraging its capabilities for cost-effective alternatives.
| Leading Market Players |
|---|
| Merck & Co. Inc. |
| Biocon Ltd |
| Novo Nordisk A/S |
| Dr. Reddy's Laboratories Ltd |
| Sun Pharma Industries Ltd |
| Sanofi |
| Abbott Laboratories |
| Boehringer Ingelheim |
| Eli Lilly and Company |
| Others |
Cost & Logistics Intelligence
India's expanding domestic manufacturing capacity, driven by the PLI scheme, influences supplier behavior and pricing posture for foundational diabetes drugs. This increased local production impacts the competitive dynamics across BRICS nations.
Pricing Analysis
Government-led bulk procurement creates the primary spread between mature, off-patent drugs and innovative therapies. Contract-based long-term offtake models dominate for high-volume generics like metformin. Brand premium and clinical efficacy differentiate newer drug classes, particularly GLP-1 Receptor Agonists. Pricing pressure stems from China's Volume-Based Procurement program, compressing margins for established oral antidiabetics. Public health systems represent the most price-sensitive buyers, while private healthcare patients demonstrate lower sensitivity for advanced, outcome-focused treatments.
Supply Chain Analysis
Cold chain logistics for temperature-sensitive biologics like insulin represent a significant structural risk across BRICS territories. Geographic supply concentration for active pharmaceutical ingredients (APIs) centers on India and China. Diabetes drug manufacturing relies heavily on chemical precursors and specialized fermentation technologies. Retail pharmacies form the dominant downstream distribution model, ensuring broad patient access for many medications. Hospital pharmacies manage acute care and initial dispensing of complex therapies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The BRICS diabetes drugs market is a high-growth disruption, driven by regulatory pushes for domestic manufacturing and novel therapeutic advancements.
For Market Incumbents: Insulate established patent portfolios through strategic litigation and by diversifying into next-generation drug delivery systems. Expand manufacturing capacity in key BRICS nations to meet local demand and leverage policy incentives like India's PLI scheme. Navigate price erosion from government procurement programs by focusing R&D on high-efficacy, premium-priced therapies. The threat of biosimilar entry and volume-based procurement necessitates continuous innovation.
For New Entrants and Emerging Players: Rural market underpenetration in India and Brazil offers significant white-space opportunities for accessible diabetes treatments. Target the development of low-cost formulations and biosimilars for off-patent biologics to address unmet needs. Integrate digital health platforms with medication delivery to offer value-added services, enhancing patient adherence and outcomes. A go-to-market angle focusing on affordability and patient support can differentiate new players.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across advanced therapy development and specialized manufacturing capabilities within the BRICS region. Identify acquisition targets among biosimilar developers with strong R&D pipelines or digital health companies offering integrated diabetes management solutions. Regulatory approvals for novel drug mechanisms, particularly those with cardio-renal benefits, serve as a critical signal to watch for long-term viability in this market.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates market entry for novel GLP-1 and SGLT2 therapies across BRICS nations. |
| Regulatory Approval Pathway | Streamlines compliance with NMPA, CDSCO, and ANVISA requirements for new drugs. |
| Manufacturing Scale-Up | Enhances local production capacity, capitalizing on India's PLI scheme and regional demand. |
| Biosimilar Development | Addresses pricing pressure and expands access to cost-effective biologic treatments in Brazil. |
| Digital Health Integration | Improves patient adherence and provides value-added services for diabetes management in urban centers. |
Research Approach
A standing panel of pharmaceutical executives, regulatory affairs specialists, hospital procurement managers, and diabetes clinic physicians provided ongoing calibration for this analysis. This primary research was rigorously validated against secondary sources including NMPA filings, CDSCO guidelines, ANVISA reports, and World Health Organization diabetes statistics. The methodology incorporated both bottom-up market sizing and top-down validation.
Scenario-bracketing framed the analytical framework across the modeling period, accounting for diverse market conditions. Segmentation dimensions included product type, application, end-user, distribution channel, and regional regulatory frameworks. Compound annual growth rates were derived from historical data trends and projected market expansion factors. Key industry-specific forecast inputs included disease prevalence rates and healthcare expenditure patterns.
Practitioners should monitor shifts in government procurement policies and new drug class approvals for early signals of market evolution. Forecasts reflect assumptions regarding regulatory stability and technological advancements. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Brazil Continuous Glucose Monitoring Market
Diabetes Care
Type 2 Diabetes Market
Diabetes Care
Brazil Blood Glucose Monitoring Market
Diabetes Care
North America Continuous Glucose Monitoring Market
Diabetes Care
North America Insulin Infusion Pumps Market
Diabetes Care
Internet of Things for Diabetes Market
Diabetes Care
Japan Insulin Drugs and Delivery Devices Market
Diabetes Care
SGLT2 Inhibitors Treatment Market
Diabetes Care
OTC Glucose Monitors Market
Diabetes Care
Latin America Insulin Infusion Pump Market
Diabetes Care
Diabetes Injection Pens Market
Diabetes Care
Vietnam Oral Anti-Diabetic Drug Market
Diabetes Care
Europe Diabetes Care Devices Market
Diabetes Care
Insulin Resistance Market
Diabetes Care
Europe Insulin Infusion Pumps Market
Diabetes Care
Glycated Albumin Market