
 Global Diabetic Ulcers Treatment Market | 2026-2036
Global Diabetic Ulcers Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Diabetic Ulcers Treatment Market Foresight
The gap between advanced biologics and standard dressings is expanding as reimbursement thresholds harden and clinical evidence requirements intensify. Smith & Nephew leverages its integrated wound care portfolio to sustain premium positioning across hospital and home settings. Mölnlycke Health Care AB anchors Nordic supply chains while competing aggressively in antimicrobial silver segments. ConvaTec Group differentiates through ostomy and wound convergence, occupying strong positions in community nursing channels.
Diabetic ulcers treatment encompasses therapeutic interventions for lower extremity wounds arising from peripheral neuropathy and vascular insufficiency, typically involving debridement, moisture-balanced dressings, bioactive agents, and negative pressure systems designed to reduce bacterial load and accelerate granulation tissue formation. Advanced dressings and skin substitutes command the deepest margin pools as hospitals seek reduced dressing change frequency and faster closure times. Negative pressure therapy leads treatment technology adoption in inpatient settings, while home care providers increasingly access portable electrical stimulation devices. Growth factors remain concentrated in specialty clinics due to handling complexity and cold chain requirements.
FDA clearance pathways for combination products and the EU MDR's tightened clinical evidence standards shape competitive access across both markets, with EMA post-market surveillance obligations extending compliance costs for biologic dressings. The WHO's diabetic foot care guidelines and ISO 13485 quality management requirements further filter vendor participation in institutional procurement. Stakeholders must monitor evolving CMS bundled payment models and EMA guidance on regenerative medicine to anticipate which product categories will retain favorable reimbursement positioning.
Market Dynamics
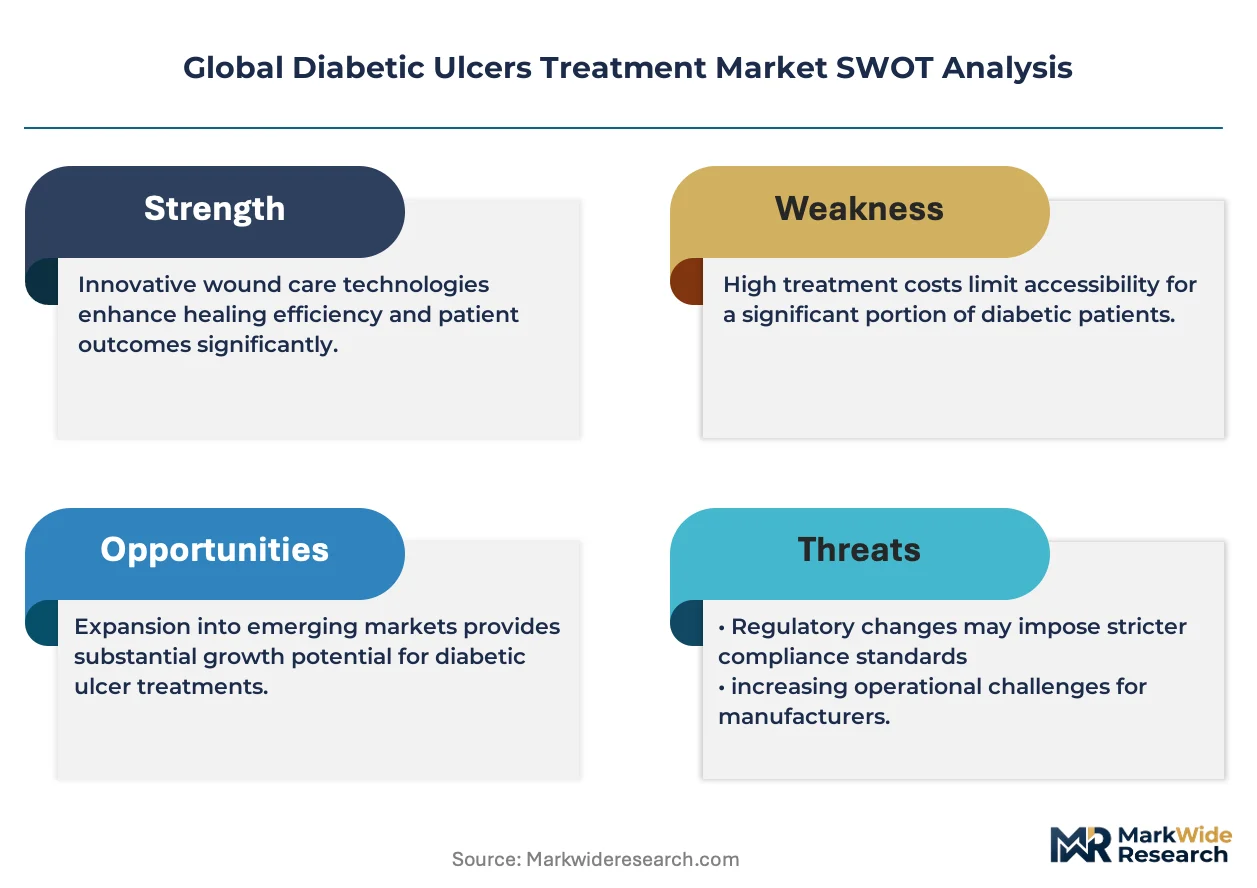
Reimbursement compression from CMS bundled payments is forcing product category consolidation as hospitals prioritize demonstrable cost-per-closure over brand loyalty in advanced wound care procurement decisions.
Growth Catalysts
- EU MDR clinical evidence mandates:Germany's specialty clinics now require bioengineered skin substitutes with robust safety dossiers, accelerating substitution away from conventional dressings in acute care settings.
- Home care channel expansion:Portable negative pressure systems enable wound management outside institutional settings, with durable medical equipment suppliers building dedicated diabetic foot programs.
- Peripheral neuropathy prevalence:Aging populations in Japan and Italy drive incident case volumes that outpace general population growth, concentrating demand in vascular surgery and podiatry practices.
Market Restraints
- Biologic cold chain costs:Growth factor therapies require continuous refrigeration from manufacture through application, limiting distribution to tertiary medical centers with validated logistics infrastructure.
- Silver price volatility:Antimicrobial dressing margins compress when precious metal markets spike, forcing manufacturers to absorb input cost swings or reformulate active agent concentrations.
- EMA post-market surveillance obligations:Extended pharmacovigilance reporting for combination products extends compliance timelines and diverts regulatory affairs resources from pipeline advancement.
Strategic Opportunities
- Brazil's SUS expansion:ANVISA's streamlined pathway for Class III medical devices opens access to public hospital procurement for collagen-based matrices previously restricted to private pay.
- Electrical stimulation convergence:Integration of biofeedback sensors with portable stimulation units creates remote monitoring capabilities that align with telehealth reimbursement codes in select US states.
- India's PLI scheme for medical devices:Domestic manufacturing incentives reduce landed cost for advanced dressings, enabling price-competitive positioning against imported legacy products in tier-2 cities.
Industry Challenges
- Wound care specialist shortages:Certified diabetic foot nurses remain concentrated in metropolitan academic centers, constraining protocol adoption in community hospitals and rural clinics.
- Legacy EHR integration:Digital wound measurement tools face interoperability barriers with established hospital information systems, delaying real-world evidence collection for payer negotiations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Diabetic Ulcers Treatment Market |
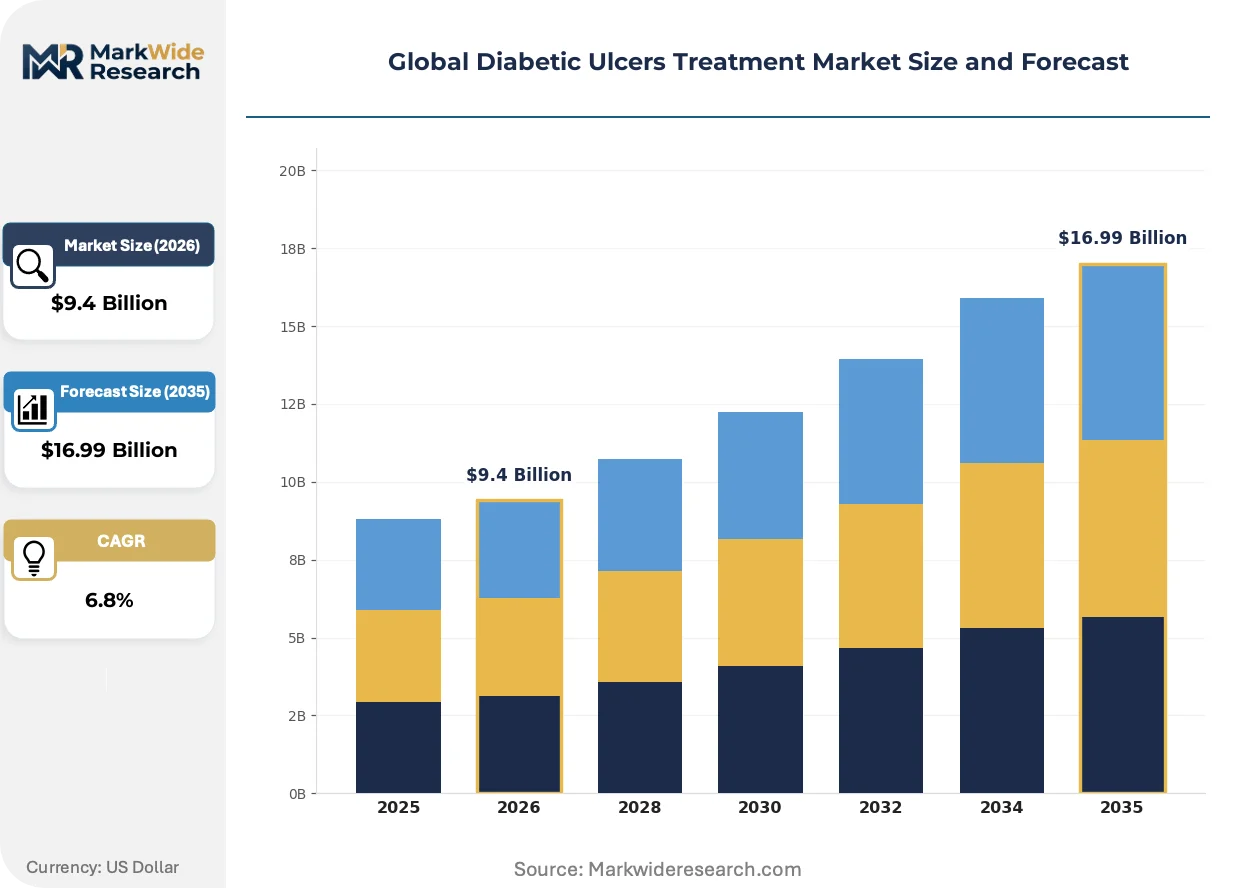
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $16.99 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Advanced Dressings, Wound Care Devices, Topical Agents, Debridement Products, Growth Factors, Skin Substitutes Application: Neuropathic Ulcers, Ischemic Ulcers, Mixed Ulcers, Pressure Ulcers, Post-Surgical Wounds, Venous Leg Ulcers End User: Specialty Clinics, Home Care Providers, Ambulatory Surgical Centers, Rehabilitation Centers, Nursing Facilities, Long-term Care Settings Treatment Technology: Negative Pressure Therapy, Hyperbaric Oxygen Therapy, Electrical Stimulation, Ultrasound Therapy, Laser Therapy, Cryotherapy |
| Companies Covered | Smith & Nephew, 3M Healthcare, ConvaTec Group, B. Braun Melsungen AG, Mölnlycke Health Care AB, Coloplast, Organogenesis, Integra LifeSciences, Medline Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Diabetic Ulcers Treatment Market Shifts & Advancements
Technology convergence between biologics and digital monitoring is compressing the traditional separation between acute intervention and longitudinal wound tracking, with regulatory frameworks racing to accommodate hybrid product classifications.
Smart dressings incorporating pH-responsive dyes and wireless moisture sensors are unifying diagnostic and therapeutic functions in single-application platforms. Hospital wound care centers in the Netherlands and Sweden pilot these systems to reduce nursing assessment frequency. The technology is unifying previously separate budget lines for diagnostics and dressings into consolidated per-patient contracts.
FDA's evolving guidance on combination products is creating distinct approval pathways for drug-device biologic hybrids, with the Center for Devices and Radiological Health asserting primary jurisdiction over antimicrobial matrices containing sustained-release agents. Wound care manufacturers with established 510(k) track records face steeper evidentiary requirements than pure pharmaceutical entrants, reshaping competitive access timelines.
Institutional procurement teams now demand outcome guarantees tied to healing velocity benchmarks, replacing traditional unit-price negotiations with risk-sharing arrangements. Group purchasing organizations in the US hospital sector pilot these models for negative pressure therapy rentals. The shift is most visible in integrated delivery networks with captive home health agencies capable of capturing full episode savings.
Global Diabetic Ulcers Treatment Market Segmentation
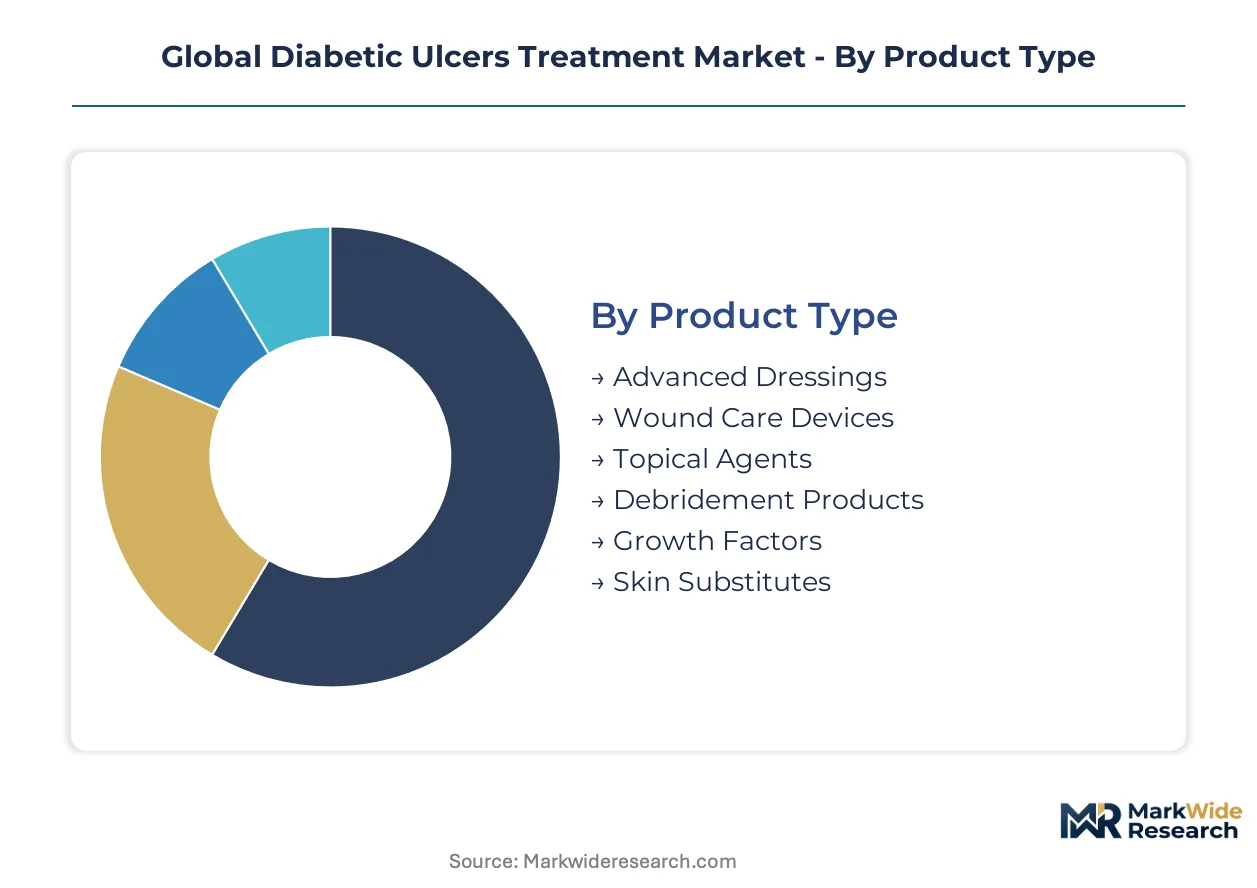
Product differentiation in diabetic ulcer care follows wound severity gradients and reimbursement tiers rather than uniform clinical protocols. Segmentation reveals where capital investment concentrates versus where commoditization pressures dominate procurement decisions.
Product Type:
Material science sophistication separates segments with cold-chain requirements from shelf-stable alternatives that community nursing can deploy without specialized infrastructure.
- Advanced Dressings:Hydrogels, hydrocolloids, and alginates incorporate moisture-balancing polymers that reduce maceration risk in exuding wounds. Demand clusters in Germany's outpatient wound centers where EU MDR compliance costs filter out commodity suppliers.
- Wound Care Devices:Negative pressure units and portable electrical stimulation systems require durable medical equipment certification and technician training for home deployment. The United States dominates volume as CMS reimbursement codes for outpatient wound care expand device rental coverage.
- Topical Agents:Antimicrobial creams and enzymatic debriders serve as first-line interventions in resource-constrained settings across India's tier-2 hospital networks.
- Debridement Products:Autolytic and enzymatic formulations accelerate necrotic tissue removal in Japan's vascular surgery departments.
- Growth Factors:Recombinant human platelet-derived growth factor therapies demand continuous refrigeration from manufacture through application, restricting distribution to tertiary medical centers with validated cold-chain logistics in Saudi Arabia's MOHAP-regulated facilities.
- Skin Substitutes:Bioengineered matrices derived from neonatal fibroblasts or collagen scaffolds command premium pricing in Brazil's private hospital sector where ANVISA's Class III pathway enables differentiated positioning.
Mature deployment sits with Advanced Dressings. Newer deployment is concentrated in Skin Substitutes.
Application:
Pathophysiology determines technology selection, with neuropathic versus ischemic etiologies requiring fundamentally different vascular assessment protocols before intervention.
- Neuropathic Ulcers:Plantar surface lesions arising from diabetic peripheral neuropathy constitute the dominant application volume, driving demand for pressure-offloading devices combined with moisture-balanced dressings in Italy's podiatry practices.
- Ischemic Ulcers:Arterial insufficiency wounds require revascularization coordination before topical therapy can succeed, concentrating treatment in Sweden's vascular surgery wards with integrated wound care protocols.
- Mixed Ulcers:Combined neuropathic-ischemic etiologies complicate treatment algorithms and extend healing timelines in Netherlands' academic medical centers.
- Pressure Ulcers:Facility-acquired lesions drive prevention technology investment in Japan's long-term care insurance reimbursement framework.
- Post-Surgical Wounds:Incisional complications from diabetic foot amputations create demand for negative pressure therapy in Germany's inpatient surgical units.
- Venous Leg Ulcers:Though distinct from diabetic etiology, compression therapy convergence creates procurement bundling opportunities in United Kingdom community nursing contracts.
Volume leadership belongs to Neuropathic Ulcers. Complexity premiums attach to Mixed Ulcers.
End User:
Site-of-care migration from inpatient to community settings reconfigures product form factors and service bundling requirements across the delivery spectrum.
- Specialty Clinics:Germany's diabetic foot centers under EU MDR requirements now mandate bioengineered skin substitutes with complete safety dossiers, displacing conventional dressings in acute referral pathways.
- Home Care Providers:Portable negative pressure systems and telehealth-integrated electrical stimulation units enable wound management outside institutional walls, with durable medical equipment suppliers in the United States building dedicated diabetic foot programs around CMS reimbursement expansion.
- Ambulatory Surgical Centers:Same-day debridement and grafting procedures concentrate in Brazil's private pay networks.
- Rehabilitation Centers:Post-amputation wound care integrates with prosthetic fitting schedules in Japan's geriatric facilities.
- Nursing Facilities:Pressure ulcer prevention protocols drive antimicrobial dressing consumption in Italy's residential care homes.
- Long-term Care Settings:Chronic wound management programs in Sweden's municipal eldercare systems prioritize cost-per-closure metrics over brand loyalty.
Reimbursement stability favors Specialty Clinics. Regulatory flexibility is expanding fastest in Home Care Providers.
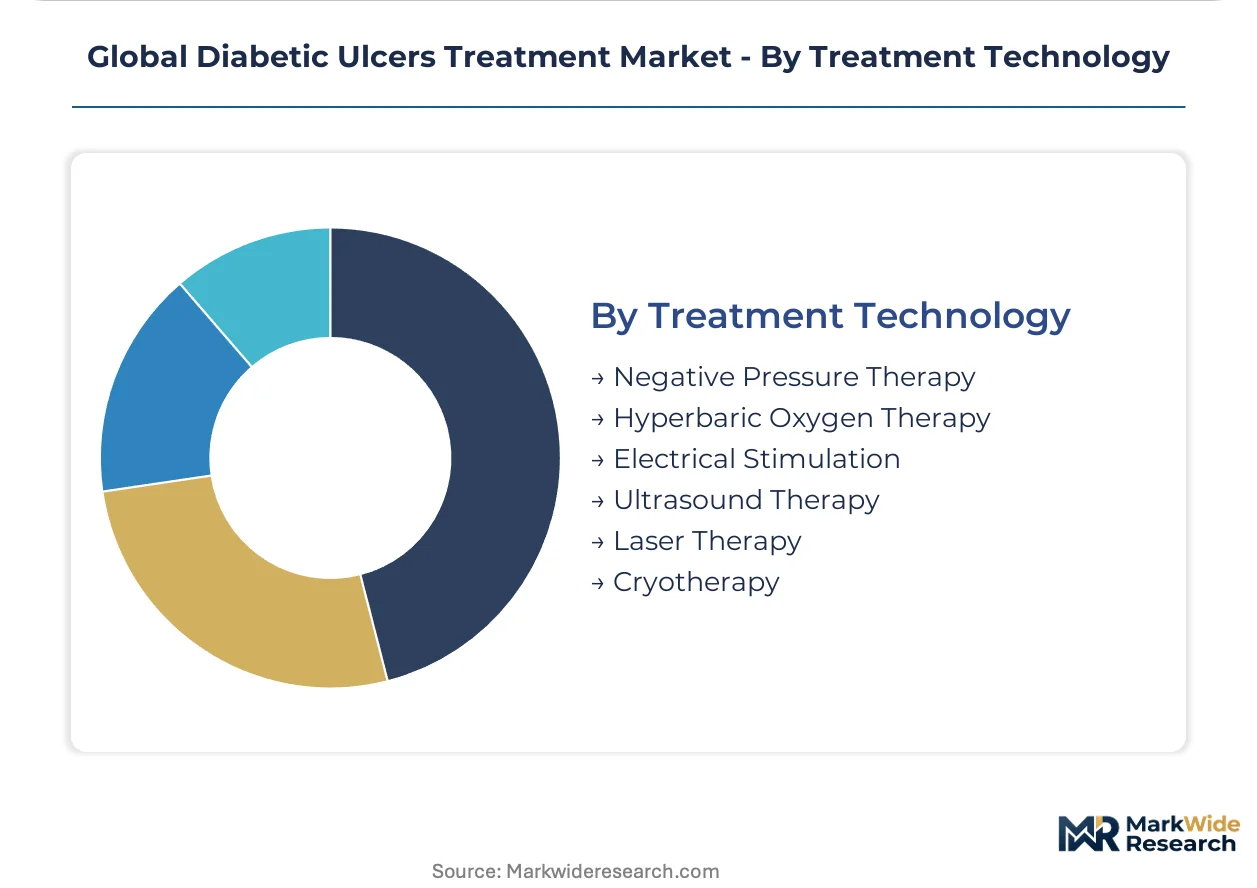
Treatment Technology:
Energy-based modalities compete with biologic interventions for capital allocation in wound care center equipment budgets.
- Negative Pressure Therapy:Vacuum-assisted closure systems reduce edema and bacterial load through controlled suction, dominating inpatient adoption in United States hospitals while portable variants penetrate home care through durable medical equipment channels.
- Hyperbaric Oxygen Therapy:Pressurized chamber treatments for ischemic wounds require substantial facility investment, limiting deployment to Germany's specialized wound centers and select United States hospital-based programs.
- Electrical Stimulation:Biofeedback-integrated portable units enable remote monitoring capabilities that align with telehealth reimbursement codes in select United States state Medicaid programs.
- Ultrasound Therapy:Low-frequency acoustic energy accelerates granulation tissue formation in Japan's outpatient vascular clinics.
- Laser Therapy:Photobiomodulation devices for chronic wound biostimulation gain traction in Brazil's aesthetic medicine crossover applications.
- Cryotherapy:Controlled cooling for wound bed preparation remains niche in Netherlands experimental protocols.
Capital intensity peaks with Hyperbaric Oxygen Therapy. Adoption velocity is steepest in Electrical Stimulation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's medical technology corridor anchors advanced wound care development through proximity to Massachusetts General Hospital's limb salvage program and the FDA's Center for Devices and Radiological Health in nearby Silver Spring.
United States
CMS bundled payment models for diabetic foot care drive hospital procurement consolidation toward demonstrable cost-per-closure metrics. The FDA's combination product guidance creates distinct approval pathways for drug-device biologic hybrids. Texas Medical Center in Houston concentrates negative pressure therapy adoption through its captive home health networks.
Germany
EU MDR clinical evidence mandates now require bioengineered skin substitutes with complete safety dossiers in acute care settings. The country's national pharmaceutical regulator enforces extended pharmacovigilance reporting for combination products. Heidelberg's university hospital network anchors specialty clinic concentration for complex neuropathic cases.
Japan
Aging demographics expand incident diabetic foot ulcer volumes beyond general population growth curves. METI's medical device reimbursement frameworks prioritize portable electrical stimulation units for home care deployment. Osaka's Kansai region concentrates vascular surgery wards with integrated wound management protocols.
Brazil
ANVISA's streamlined pathway for Class III medical devices opens public hospital procurement to collagen-based matrices previously restricted to private pay. The national health regulator's convergence with SUS expansion programs reduces import dependency. São Paulo's private hospital sector commands premium positioning for bioengineered skin substitutes.
India
PLI scheme incentives for domestic medical device manufacturing reduce landed costs for advanced dressings in tier-2 cities. CDSCO's accelerated approval pathways for wound care products enable faster market entry. Gujarat's pharmaceutical manufacturing belt concentrates production capacity for antimicrobial silver dressings.
Global Diabetic Ulcers Treatment Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology sophistication tiers, with integrated wound care portfolios commanding pricing power against single-product suppliers. The vendor base organizes around three strategic archetypes: diversified medical technology conglomerates with hospital channel dominance, specialized wound care pure-plays with biologic expertise, and regional fabricators competing on cost in standard dressing segments. Consolidation pressure intensifies as group purchasing organizations demand outcome guarantees tied to healing velocity benchmarks rather than unit-price negotiations.
Among diversified medical technology conglomerates, Smith & Nephew and 3M Healthcare exemplify the integrated portfolio approach spanning advanced dressings through negative pressure systems. ConvaTec Group occupies a position within the specialized wound care tier, representing the convergence strategy between ostomy and wound management that community nursing channels favor. Mölnlycke Health Care AB anchors the Nordic supply chain concentration while competing in antimicrobial segments where silver price volatility compresses margins.
| Leading Market Players |
|---|
| Smith & Nephew |
| 3M Healthcare |
| ConvaTec Group |
| B. Braun Melsungen AG |
| Mölnlycke Health Care AB |
| Coloplast |
| Organogenesis |
| Integra LifeSciences |
| Medline Industries |
| Others |
Supply & Pricing Matrix
Portable negative pressure system miniaturization compresses manufacturing cost curves while concentrating component sourcing among FDA-registered contract manufacturers in Minnesota and Massachusetts. This technological shift simultaneously enables home care pricing tiers previously unreachable and deepens dependency on specialized electronics supply chains with limited secondary qualification options.
Pricing Analysis
Value-based contracts tied to healing velocity benchmarks anchor pricing for bioengineered skin substitutes in Germany's EU MDR-compliant specialty clinics. Three-tier pricing structure across premium, standard, and economy levels separates cold-chain growth factors from shelf-stable advanced dressings and commodity gauze alternatives. Cost compression in silver antimicrobial segments intensifies when precious metal markets spike, forcing reformulation or margin absorption. Community nursing providers exhibit highest price sensitivity, while academic medical centers prioritize clinical outcomes over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from US hospital group purchasing organizations mandate qualified secondary suppliers for negative pressure pumps and bioengineered matrices, extending vendor onboarding timelines. Manufacturing concentrates in the United States, Germany, and Sweden for high-margin biologics, with India's PLI scheme expanding tier-2 city production of advanced dressings. Supply chains draw from collagen processors, medical-grade silicone foundries, and silver nanoparticle refiners. Single-source vulnerability concentrates in neonatal fibroblast cell lines for skin substitutes. Distribution runs through durable medical equipment suppliers, hospital GPOs, and specialty clinic direct contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into cold-chain logistics and captive home health networks determines margin sustainability as reimbursement bundles harden. Players securing upstream control over biologic raw materials and downstream patient monitoring data capture full episode economics.
For Market Incumbents: Deepen backward integration into collagen harvesting and cell culture media production to insulate margins from biologic input volatility. Lock in exclusive GPO contracts with outcome guarantees that emerging competitors cannot match. Prioritize FDA 510(k) pathway expertise as combination product guidance tightens evidentiary requirements for antimicrobial matrices. For New Entrants and Emerging Players: Capture Brazil's SUS expansion corridor where ANVISA's streamlined Class III pathway reduces incumbent regulatory moats. Target India's tier-2 hospital networks with domestically manufactured advanced dressings enabled by PLI scheme incentives. Lead with telehealth-integrated electrical stimulation units aligned with emerging state Medicaid reimbursement codes. For Investors and Strategic Acquirers: Re-rating potential sits with specialized wound care pure-plays possessing EU MDR Master File dossiers given Germany's acute care substitution mandate. Long-term viability hinges on recurring revenue streams from disposable dressing components rather than capital equipment sales. Monitor CMS bundled payment expansion into additional diabetic foot diagnosis codes as inflection signal for home care channel acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evidence dossiers enable German specialty clinic access and displace conventional dressings. |
| Hospital System Partnership | Integrated delivery networks with captive home health agencies capture full episode savings under bundled payments. |
| Backward Integration into Biologics | In-house collagen scaffold production reduces dependency on volatile raw material suppliers and secures margin. |
| Software Companion Development | Biofeedback-integrated electrical stimulation aligns with telehealth reimbursement expansion in select US states. |
| Reimbursement Strategy | CMS outpatient wound care code optimization determines portable negative pressure rental coverage expansion. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with wound care clinicians, hospital purchasing committee members, biomedical engineers, and GPO contracts managers combined with secondary validation from FDA 510(k) databases, EMA submission dossiers, CMS Medicare reimbursement files, and hospital procurement databases. Bottom-up demand modeling across product categories triangulated against top-down market sizing from regulatory approval trends.
Data-stream reconciliation between volume-based shipment tracking and value-based pricing surveys informed the analytical framework across the analysis window. Segmentation dimensions modeled include product type sophistication tiers, wound severity application gradients, end-user site-of-care migration patterns, and regional regulatory cluster variations. CAGRs derived from fitted growth curves incorporating incident case volume projections, reimbursement policy phase-ins, and technology substitution elasticities. Forecast inputs incorporated EU MDR compliance cost trajectories and CMS bundled payment expansion schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to silver commodity price cycles, cold-chain logistics infrastructure buildout rates, and wound care specialist training program expansion. Deviation in CMS bundled payment geographic rollout timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Antidiabetics Market
Diabetes Care
New Zealand Insulin Drugs and Devices Market
Diabetes Care
Internet of Things for Diabetes Market
Diabetes Care
South Africa Oral Antidiabetic Drug Market
Diabetes Care
Vietnam Insulin Drug and Delivery Device Market
Diabetes Care
South Korea Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Spain Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Diabetes Monitors Market
Diabetes Care
BRICS Diabetes Treatment and Prevention Market
Diabetes Care
New Zealand Continuous Glucose Monitoring Devices Market
Diabetes Care
Global Proliferative Diabetic Retinopathy Market
Diabetes Care
United Kingdom Continuous Glucose Monitoring Market
Diabetes Care
United Kingdom Blood Glucose Monitoring Market
Diabetes Care
Pet Diabetes Care Devices Market
Diabetes Care
France Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Diabetic Shoes Market