
 Asia Pacific Diabetes Drug Market | 2026-2036
Asia Pacific Diabetes Drug Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Diabetes Drug Market Insights
Hospital procurement of diabetes therapies is shifting toward outpatient and home-based models across Southeast Asian markets. Novo Nordisk A/S anchors its regional position through deep insulin specialization and manufacturing scale in China. Sanofi competes via established GLP-1 receptor agonist portfolios and channel control across urban hospital networks. Eli Lilly and Company differentiates through intensified R&D investment in next-generation peptide therapies for Type 2 diabetes management.
Diabetes drugs comprise synthetic and biological active pharmaceutical ingredients formulated to regulate blood glucose through insulin supplementation, incretin pathway modulation, or renal glucose excretion inhibition, with molecular weights ranging from small-molecule DPP-4 inhibitors under 500 Da to biologic insulin analogs exceeding 5,800 Da. SGLT-2 inhibitors command expanding prescription volumes among cardiometabolic specialists due to demonstrated renal and cardiovascular protective effects beyond glycemic control. Oral administration routes retain dominant volume share across India and Southeast Asia where injection infrastructure remains limited, while subcutaneous delivery leads value generation through premium biologic pricing in Japan, South Korea, and urban China.
China's NMPA accelerates biosimilar insulin approvals through streamlined review pathways, while India's CDSCO enforces tightened bioequivalence standards for oral hypoglycemic generics under revised Schedule Y provisions. Japan's PMDA maintains distinct pharmacovigilance requirements for GLP-1 receptor agonists that shape product labeling and physician training investments. Stakeholders must monitor regulatory divergence across national approval frameworks when allocating clinical trial resources and manufacturing capacity across the region.
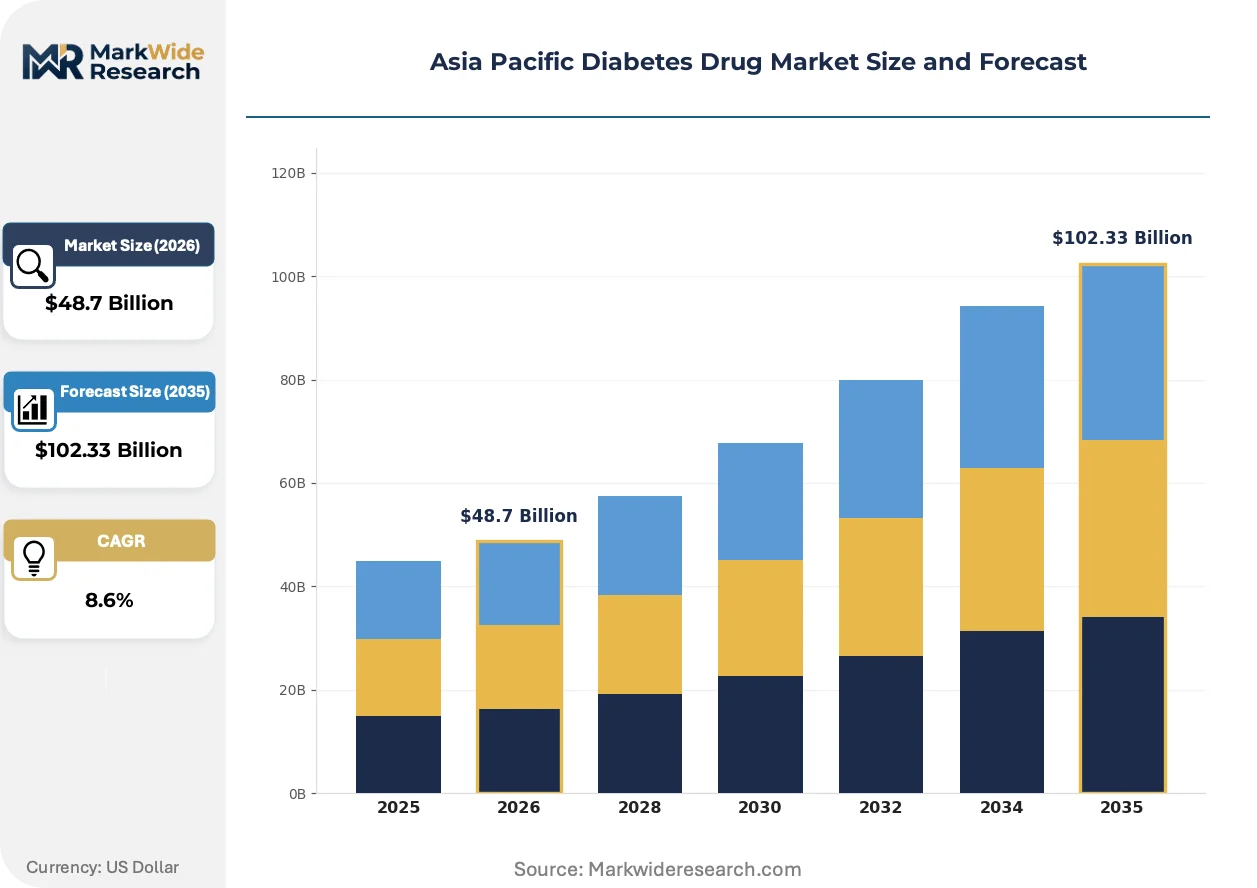
Market Dynamics
China's NMPA biosimilar insulin approval acceleration is compressing development timelines and forcing multinational incumbents to defend pricing power through formulation differentiation rather than patent exclusivity alone. This regulatory velocity is redrawing competitive boundaries across the region.
Growth Catalysts
- India's PLI scheme for pharmaceutical manufacturing:Domestic production incentives are attracting contract manufacturing investment from global insulin suppliers seeking cost-competitive export bases.
- Cardiometabolic specialist prescribing:SGLT-2 inhibitor demand from nephrologists and cardiologists is expanding beyond endocrinology into integrated diabetes-heart-kidney care protocols.
- Home-based delivery infrastructure:Cold chain logistics investment across Southeast Asia is enabling subcutaneous biologic distribution outside hospital settings.
Market Restraints
- Active pharmaceutical ingredient concentration:Peptide and insulin API production clusters heavily in China and South Korea, creating single-source vulnerability for regional formulators.
- Japan's PMDA pharmacovigilance requirements:Extended GLP-1 receptor agonist safety monitoring mandates delay product launches and inflate post-market surveillance costs.
- Oral hypoglycemic generic substitution:India's CDSCO bioequivalence enforcement has intensified price competition in metformin and DPP-4 inhibitor categories.
Strategic Opportunities
- Indonesia's underpenetrated GLP-1 market:Southeast Asia's largest population offers whitespace for incretin therapy expansion as diagnosis rates improve.
- Dual-hormone artificial pancreas systems:Convergence of continuous glucose monitoring with automated insulin-glucagon delivery is opening premium device-drug combination categories.
- Thailand's universal coverage expansion:National health insurance reimbursement broadening for insulin analogs is unlocking volume growth in previously cash-pay segments.
Industry Challenges
- Biologics manufacturing talent scarcity:Cell culture and purification expertise for insulin analog production remains concentrated in Japan and South Korea, constraining capacity buildout elsewhere.
- Multi-jurisdiction trial coordination:Divergent NMPA, PMDA, and CDSCO clinical data requirements fragment development programs and extend registration timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Diabetes Drug Market |
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $102.33 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin, GLP-1 Receptor Agonists, DPP-4 Inhibitors, SGLT-2 Inhibitors Administration Route: Oral, Subcutaneous, Intravenous, Inhalation Therapy Area: Type 1 Diabetes, Type 2 Diabetes, Prediabetes, Gestational Diabetes End User: Hospitals, Clinics, Home Care, Pharmacies |
| Companies Covered | Novo Nordisk A/S, Sanofi, Eli Lilly and Company, AstraZeneca, Boehringer Ingelheim, Takeda Pharmaceutical, Merck & Co., Biocon, Bayer AG, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Diabetes Drug Market Trends and Innovations
Peptide engineering and connected delivery devices are converging to redefine therapeutic efficacy benchmarks and patient adherence measurement across Asia Pacific diabetes care. These innovations are compressing the gap between clinical trial endpoints and real-world glycemic outcomes.
Once-weekly basal insulin analogs are unifying glucose control and dosing convenience into single therapeutic propositions. Cardiometabolic specialists in Japan and urban China are adopting these extended-duration formulations faster than traditional twice-daily regimens. The technology is unifying hospital and home administration protocols by reducing hypoglycemia risk and nursing dependency.
China's NMPA streamlined biosimilar review pathways are compressing insulin analog approval timelines from five years toward eighteen months. Domestic manufacturers in Jiangsu and Shandong provinces are exploiting this regulatory velocity to capture municipal hospital procurement contracts. The policy shift most affects rapid-acting insulin segments where reference product patents have lapsed.
Specialist-led prescribing is displacing general practitioner dominance in Type 2 diabetes initiation across South Korea and Taiwan. Endocrinology networks are consolidating patient flows through dedicated diabetes centers that bundle diagnostics, drug dispensing, and complication screening. This channel concentration is most visible in Seoul and Taipei metropolitan areas where vertical integration of care delivery is accelerating.
Asia Pacific Diabetes Drug Market Segmentation
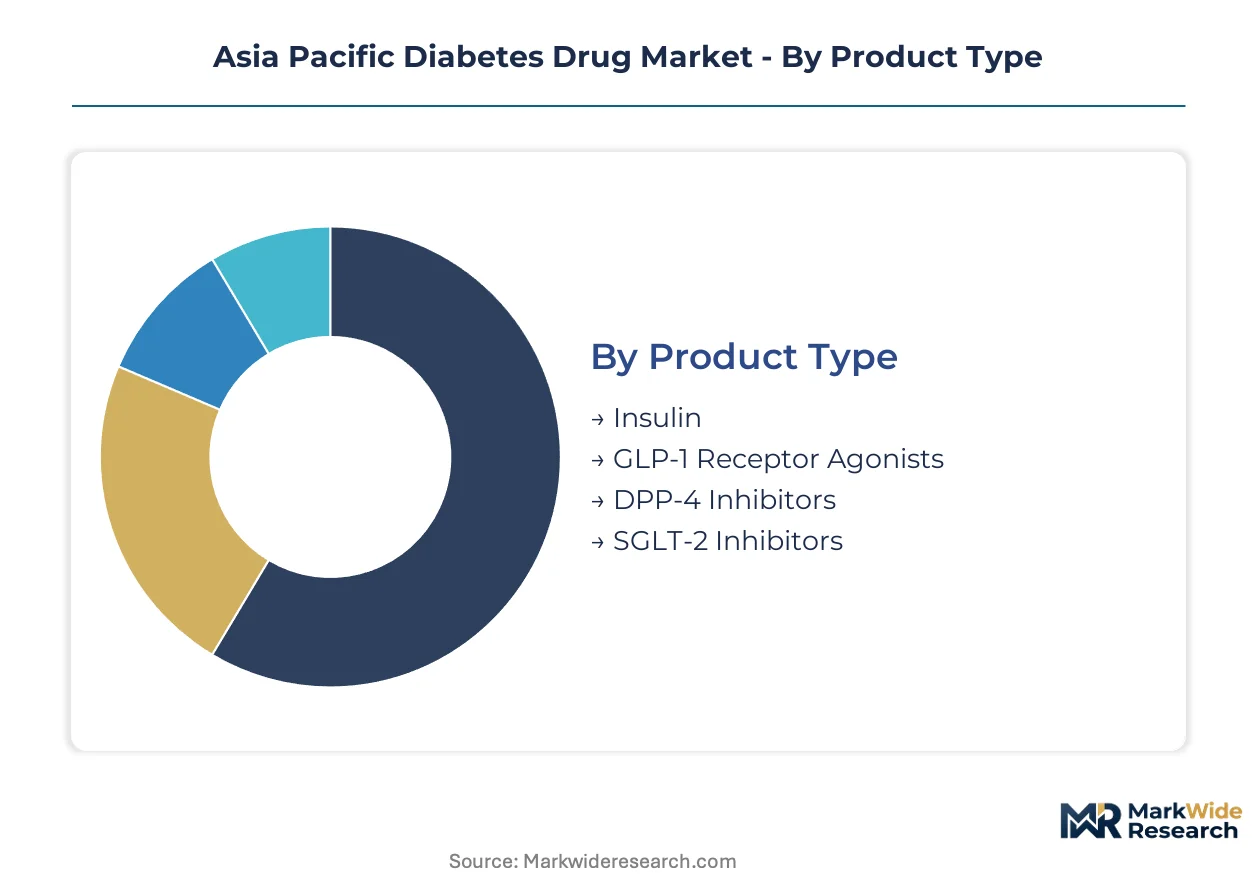
Segmentation in the Asia Pacific diabetes drug market reveals how formulation chemistry, delivery mechanics, and care setting economics create distinct competitive arenas. Manufacturers must align R&D investment and distribution infrastructure against these fracture lines to capture value.
Product Type:
API manufacturing clusters heavily in China's Jiangsu and Shandong provinces for insulin analogs, while peptide synthesis for GLP-1 therapies concentrates in South Korean contract manufacturing organizations.
- Insulin:Recombinant human and analog formulations manufactured through microbial or mammalian cell culture, with molecular weights spanning 5,800 to 6,000 Da. Demand concentrates in China's tier-1 and tier-2 municipal hospitals where NMPA biosimilar approvals have compressed pricing power for originator products.
- GLP-1 Receptor Agonists:Synthetic peptide therapies mimicking endogenous incretin hormones, administered via subcutaneous injection or oral formulations. Japan's PMDA pharmacovigilance requirements for this class delay launches but protect premium positioning in cardiometabolic specialist channels.
- DPP-4 Inhibitors:Small-molecule oral agents under 500 Da enabling once-daily dosing convenience.
- SGLT-2 Inhibitors:Oral small molecules driving prescription expansion beyond endocrinology into nephrology and cardiology practices across South Korea and urban China.
Today's leader: Insulin. Tomorrow's challenger: GLP-1 Receptor Agonists.
Administration Route:
Delivery modality selection directly determines cold chain infrastructure requirements, nursing dependency, and patient adherence economics across the region's heterogeneous healthcare systems.
- Oral:Small-molecule tablets and capsules requiring no refrigeration, dominating volume share in India and Southeast Asia where injection infrastructure remains limited. India's CDSCO bioequivalence enforcement under Schedule Y provisions intensifies price competition in metformin and DPP-4 categories.
- Subcutaneous:Prefilled pen and autoinjector systems for insulin and GLP-1 therapies, generating premium value in Japan, South Korea, and urban China through biologic pricing and reduced hypoglycemia risk with once-weekly basal analogs.
- Intravenous:Hospital-confused insulin infusions for acute hyperglycemic crises.
- Inhalation:Dry powder and liquid aerosol formulations offering needle-free alternatives with limited regional penetration.
Oral administration commands volume dominance. Subcutaneous delivery captures value concentration.
Therapy Area:
Disease stage progression and pathophysiology heterogeneity fragment prescribing patterns between insulin-dependent and insulin-resistant patient populations.
- Type 2 Diabetes:Progressive insulin resistance and beta-cell dysfunction affecting the vast majority of regional patients, driving demand for oral hypoglycemics, GLP-1 agonists, and eventual insulin supplementation. Specialist-led prescribing in Seoul and Taipei metropolitan diabetes centers is consolidating patient flows through vertically integrated care delivery.
- Type 1 Diabetes:Autoimmune beta-cell destruction requiring lifelong insulin replacement, with demand concentrated in pediatric and young adult populations across Japan and Australia's TGA-regulated markets.
- Prediabetes:Impaired glucose tolerance preceding diagnostic thresholds, with limited pharmacological intervention.
- Gestational Diabetes:Glucose intolerance during pregnancy requiring short-term glycemic management protocols.
Type 2 Diabetes generates absolute revenue concentration. Type 1 Diabetes sustains insulin manufacturing scale.
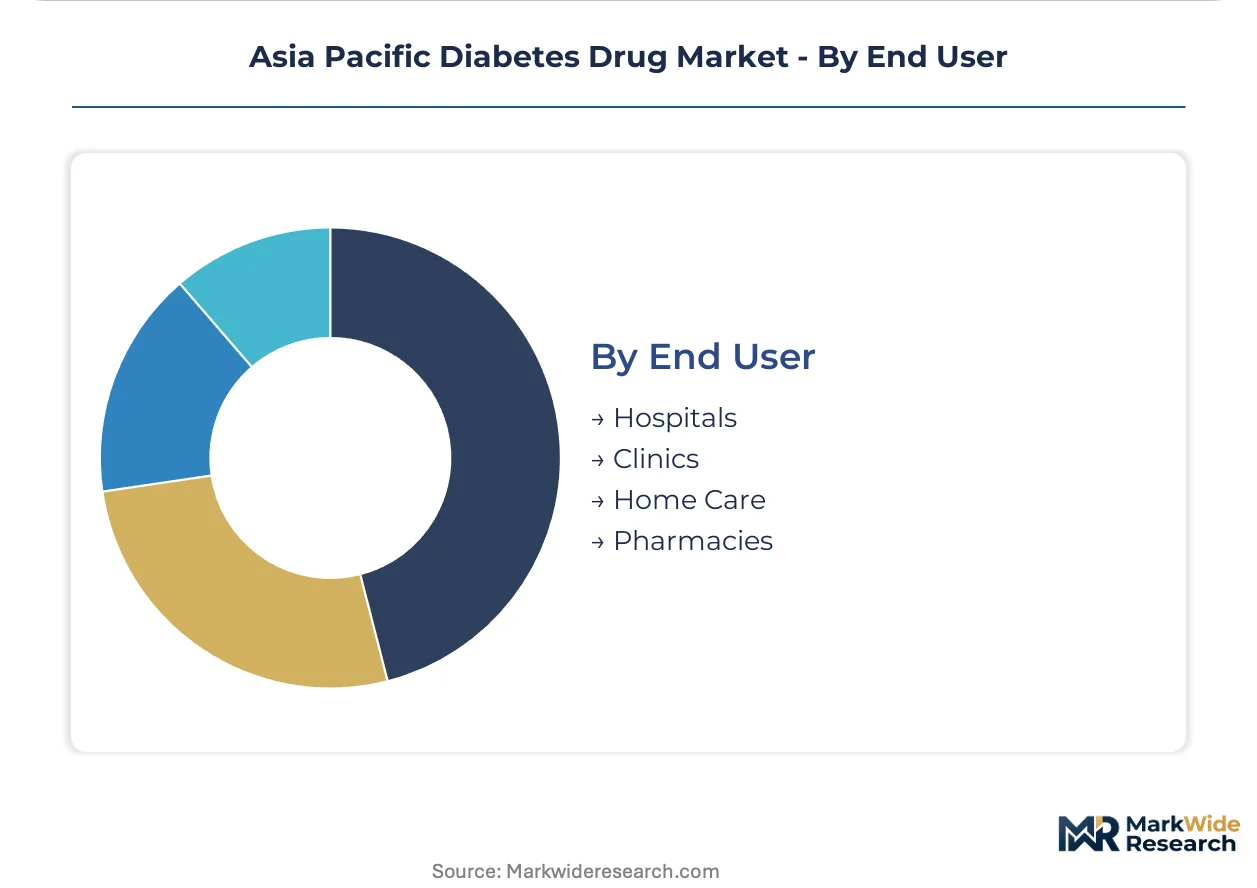
End User:
Care setting migration from institutional to ambulatory and home-based delivery is reshaping procurement relationships and reimbursement pathways across Southeast Asia.
- Hospitals:Acute care institutions managing diabetic ketoacidosis, perioperative glycemic control, and complication screening. China's municipal hospital procurement contracts are increasingly contested by domestic biosimilar manufacturers exploiting NMPA streamlined review pathways.
- Home Care:Patient-administered therapy outside institutional settings, enabled by cold chain logistics investment across Southeast Asia and Thailand's universal coverage expansion for insulin analog reimbursement.
- Clinics:Outpatient facilities bridging hospital and community care.
- Pharmacies:Retail dispensing channels with growing direct patient access in India's PLI-incentivized domestic manufacturing environment.
Hospitals retain high-acuity concentration. Home Care is gaining the fastest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redrawing manufacturing footprints across Asia Pacific as cost-of-compliance gaps between national frameworks accelerate contract manufacturing migration and domestic production incentives.
China
NMPA's streamlined biosimilar insulin pathways are compressing approval timelines from five years toward eighteen months. Jiangsu and Shandong provinces host expanding API manufacturing clusters where domestic manufacturers capture municipal hospital procurement contracts. The regulatory velocity most affects rapid-acting insulin segments where reference product patents have lapsed.
India
CDSCO's tightened bioequivalence standards under Schedule Y provisions intensify price competition in metformin and DPP-4 inhibitor categories. The PLI scheme for pharmaceutical manufacturing attracts contract manufacturing investment from global insulin suppliers seeking cost-competitive export bases. Domestic production capacity concentrates in Maharashtra and Gujarat for oral hypoglycemic formulation.
Japan
PMDA's extended GLP-1 receptor agonist safety monitoring mandates delay product launches and inflate post-market surveillance costs. Cardiometabolic specialists in Tokyo and Osaka metropolitan areas adopt once-weekly basal insulin analogs faster than traditional twice-daily regimens. The pharmacovigilance requirements protect premium positioning in specialist-led prescribing channels.
South Korea
MFDS regulatory frameworks support peptide synthesis concentration for GLP-1 therapies in contract manufacturing organizations. Seoul Capital Area endocrinology networks consolidate patient flows through dedicated diabetes centers bundling diagnostics and drug dispensing. Biologics manufacturing expertise for insulin analog production remains concentrated here, constraining capacity buildout elsewhere.
Thailand
National health insurance reimbursement broadening for insulin analogs unlocks volume growth in previously cash-pay segments. Cold chain logistics investment across Southeast Asia enables subcutaneous biologic distribution outside hospital settings. Bangkok metropolitan procurement is shifting toward outpatient and home-based delivery models.
Asia Pacific Diabetes Drug Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with multinational incumbents defending pricing power through formulation differentiation while domestic biosimilar producers exploit regulatory velocity. The market structure concentrates around insulin and incretin therapy specialists with deep manufacturing scale. Three archetypes dominate: originator biologic specialists, biosimilar challengers, and diversified pharmaceutical conglomerates. Competitive moves center on M&A for peptide engineering capabilities and capacity expansion in cold chain-enabled distribution.
Within the originator biologic tier, Novo Nordisk A/S and Sanofi occupy positions anchored by insulin specialization and GLP-1 receptor agonist portfolios respectively. Eli Lilly and Company exemplifies the R&D-intensive archetype through next-generation peptide therapy investment. These three entities represent distinct competitive vectors: manufacturing scale, channel control, and clinical innovation.
| Leading Market Players |
|---|
| Novo Nordisk A/S |
| Sanofi |
| Eli Lilly and Company |
| AstraZeneca |
| Boehringer Ingelheim |
| Takeda Pharmaceutical |
| Merck & Co. |
| Biocon |
| Bayer AG |
| Others |
Pricing and Supply Chain Analysis
Captive API production in China's Jiangsu and Shandong provinces anchors supply positioning for insulin analogs while simultaneously defending pricing power against biosimilar entrants. This backward integration into fermentation and purification capacity allows domestic manufacturers to undercut originator products in municipal hospital procurement without sacrificing margin structure.
Pricing Analysis
Distributor margins in Southeast Asian markets compress as cold chain logistics investment intensifies competition for subcutaneous biologic delivery contracts. Pricing stratifies across premium, standard, and economy tiers where originator insulin analogs command specialist channel premiums, while India's CDSCO bioequivalence enforcement drives cost compression in oral hypoglycemic generics. Cardiometabolic specialists in Japan and urban China exhibit lowest price sensitivity due to PMDA pharmacovigilance requirements that protect premium positioning, whereas India's retail pharmacy channels face acute price sensitivity from cash-pay patients.
Supply Chain Analysis
Returns and temperature excursion management for insulin products create reverse-logistics complexity that favors manufacturers with integrated cold chain networks over third-party distributors. API synthesis draws from China, South Korea, and India, with peptide manufacturing for GLP-1 therapies concentrated in South Korean contract manufacturing organizations. Single-source vulnerability persists in mammalian cell culture media and chromatography resins sourced from Japanese and German suppliers. Distribution runs through hospital procurement consortia in China, specialist clinic networks in South Korea, and pharmacy retail chains in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific diabetes drug market functions as a stable compounder where chronic disease prevalence and aging demographics generate predictable demand expansion regardless of macroeconomic cycles.
For Market Incumbents: Anticipate NMPA biosimilar acceleration by deepening formulation differentiation around once-weekly basal analogs and connected delivery devices rather than defending patent exclusivity alone. Secure backward integration into peptide synthesis capacity in South Korea to offset API concentration risk in Chinese manufacturing clusters. Prioritize cardiometabolic specialist channel control in Japan and urban China where PMDA pharmacovigilance requirements sustain premium positioning. For New Entrants and Emerging Players: The gap between premium GLP-1 pricing and economy insulin tiers offers whitespace for mid-market oral incretin formulations targeting Southeast Asia's diagnosis-improvement trajectory. Indonesia's underpenetrated GLP-1 market presents the most penetrable geography, with Thailand's universal coverage expansion for insulin analogs providing a parallel volume opportunity. Pursue contract manufacturing partnerships with India's PLI-incentivized domestic producers to establish cost-competitive export bases for regional hospital procurement. For Investors and Strategic Acquirers: Roll-up economics work for peptide engineering specialists because biologics manufacturing talent scarcity in cell culture and purification expertise constrains organic capacity buildout across the region. Five-to-ten-year viability hinges on positioning for dual-hormone artificial pancreas convergence. Target acquisition candidates with GLP-1 oral formulation capabilities or continuous glucose monitoring integration expertise. Monitor NMPA biosimilar approval velocity as an inflection indicator for pricing power compression timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Expands insulin analog capacity in Jiangsu province to capture NMPA-accelerated municipal hospital contracts. |
| Regulatory Approval Pathway | Streamlines PMDA pharmacovigilance compliance for GLP-1 launches in Tokyo-Osaka cardiometabolic corridors. |
| Pipeline Diversification | Adds once-weekly basal insulin candidates to reduce hypoglycemia risk in home-based delivery settings. |
| Strategic Partnership | Links continuous glucose monitoring platforms with automated insulin delivery for premium device-drug combinations. |
| Geographic Expansion | Establishes cold chain distribution nodes across Southeast Asia to enable subcutaneous biologic home administration. |
Research Methodology
Coverage spans China, India, Japan, South Korea, and Southeast Asian markets, with primary inputs from each geography combined with secondary validation. Drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists provided qualitative intelligence on prescribing patterns and reimbursement dynamics. Secondary sources include NMPA filings, PMDA submissions, ClinicalTrials.gov records, and hospital formulary databases. Bottom-up patient population modeling and top-down pharmaceutical revenue triangulation generated convergent estimates.
Granularity extends to product type, administration route, therapy area, and end user, with additional modeling of regional regulatory cluster effects on approval timelines and pricing power. CAGRs were derived from segment-level volume and value trajectories across the projection horizon, incorporating treatment line progression patterns and biosimilar penetration curves as diabetes-specific forecast inputs.
Caveats apply where NMPA regulatory velocity shifts, PMDA pharmacovigilance requirement changes, or API supply disruptions could materially shift the outlook. Practitioners should monitor CDSCO bioequivalence enforcement intensity and Thailand universal coverage reimbursement breadth for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Asia Pacific Continuous Glucose Monitoring (CGM) Market
Diabetes Care
Insulin Pen Needles Market
Diabetes Care
Wearable Glucometers Market
Diabetes Care
Insulin Patch Pumps Market
Diabetes Care
Global Smart Insulin Pens Market
Diabetes Care
United Kingdom Continuous Glucose Monitoring Market
Diabetes Care
France Insulin Infusion Pump Market
Diabetes Care
South Africa Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Latin America Oral Anti-Diabetic Drug Market
Diabetes Care
India Self-Monitoring Blood Glucose Devices Market
Diabetes Care
SGLT2 Inhibitors Treatment Market
Diabetes Care
South Africa Continuous Glucose Monitoring Market
Diabetes Care
Mexico Diabetes Medication Market
Diabetes Care
United Kingdom Blood Glucose Monitoring Market
Diabetes Care
Diabetic Pen Cap Market
Diabetes Care
Global Diabetes Pen Market