
 Germany Digital Diabetes Management Market | 2026-2036
Germany Digital Diabetes Management Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Digital Diabetes Management Market Insights
Specialist diabetes practices are redrawing procurement priorities for digital diabetes management platforms across Germany. Abbott Laboratories leverages its FreeStyle Libre ecosystem to anchor hospital-to-home continuity in glucose data flows. Medtronic competes through closed-loop insulin delivery algorithms that sustain reimbursement conversations with German sickness funds. Dexcom specializes in real-time continuous glucose monitoring APIs that integrate with electronic health record systems deployed by university hospitals in Berlin and Munich.
Germany digital diabetes management encompasses connected hardware, algorithmic software, and cloud infrastructure that capture, transmit, and analyze glycemic data for therapeutic decision support. Wearable devices incorporate electrochemical sensors measuring interstitial glucose concentrations at five-minute intervals, transmitting encrypted readings via Bluetooth Low Energy to mobile applications. Cloud-based delivery models capture the fastest expansion as German healthcare providers seek scalable infrastructure for multi-site diabetes networks, while integrated systems command premium positioning through their ability to synchronize patient-generated data with clinical workflow platforms. Subscription-based pricing for software solutions is maturing as payers demand outcome-linked contracts rather than per-seat licensing.
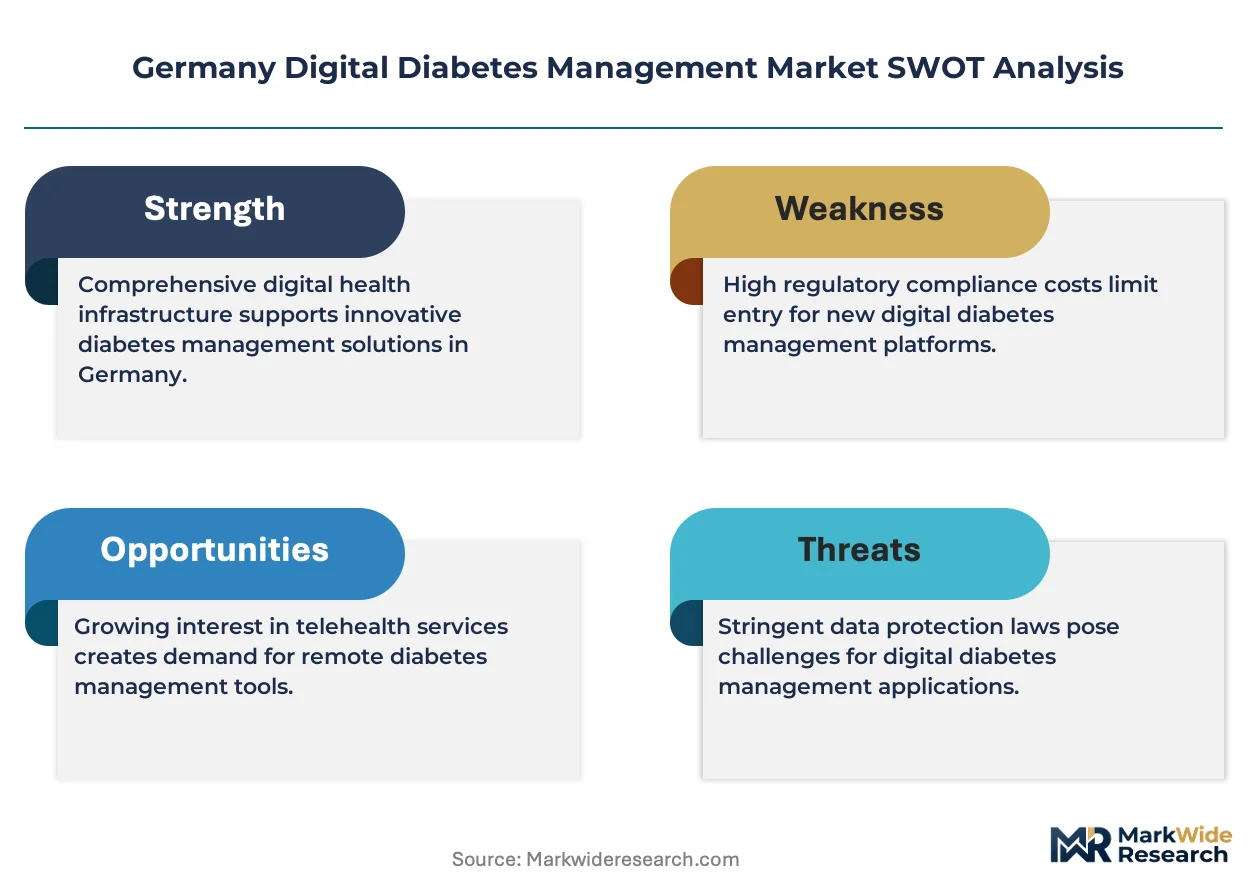
Germany's Federal Institute for Drugs and Medical Devices (BfArM) regulates digital health applications under the DiGA fast-track approval pathway, while the German Social Code (SGB V) mandates statutory health insurance reimbursement for approved solutions. The EU Medical Device Regulation (MDR) imposes clinical evidence requirements that shape product development timelines and market access strategies for device-software combinations. Stakeholders must monitor how forthcoming BfArM guidance on artificial intelligence-enabled diagnostic features reclassifies risk categories for algorithm-driven insulin dosing recommendations.
Market Dynamics
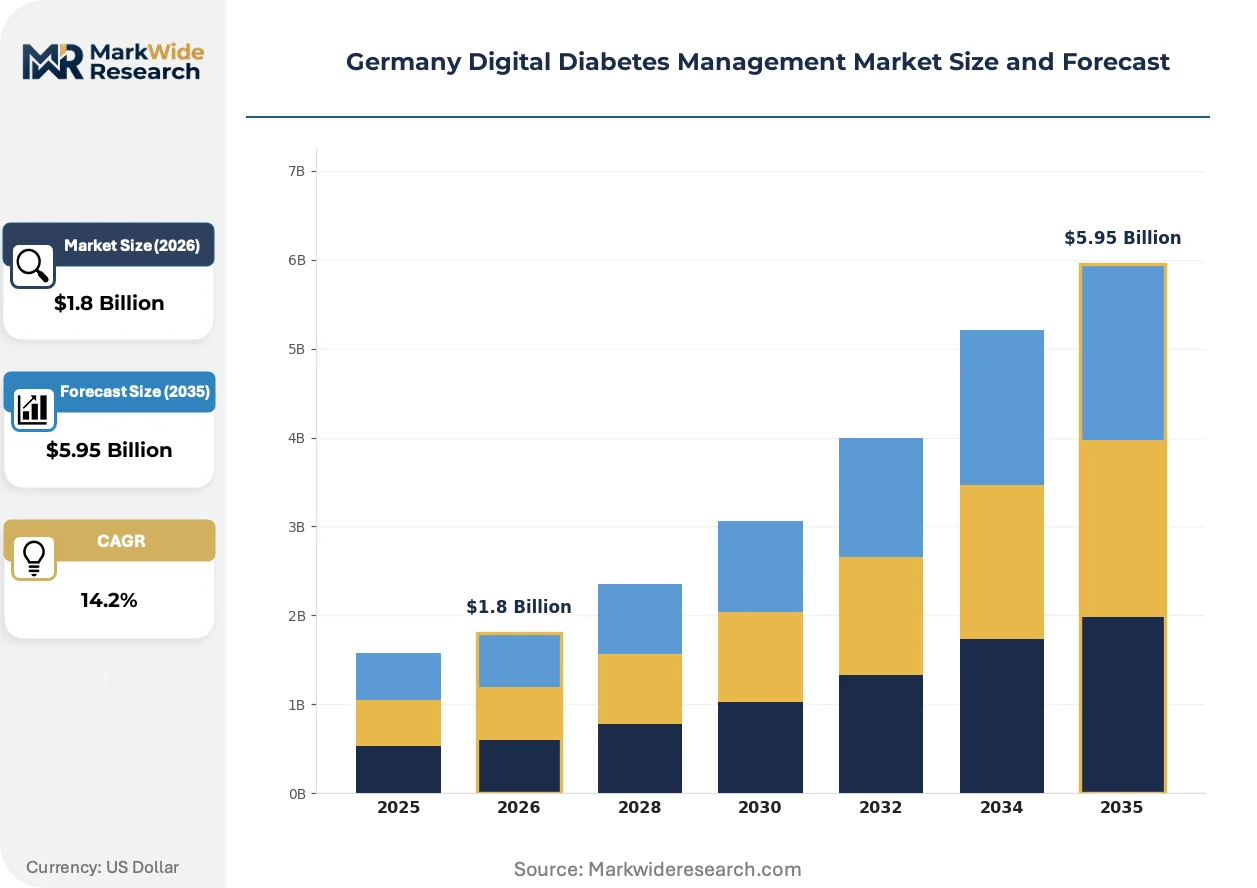
Reimbursement pathways under Germany's Digital Healthcare Act are compressing commercialization timelines for algorithmic diabetes solutions, forcing developers to restructure clinical evidence packages around DiGA fast-track requirements rather than traditional medical device pathways.
Growth Catalysts
- DiGA Fast-Track:BfArM's accelerated approval pathway for digital health applications reduces time-to-reimbursement from 18 months to 90 days for qualifying glucose management software.
- Integrated Care Contracts:North Rhine-Westphalia's disease management programs create bundled procurement opportunities for connected monitoring platforms across hospital networks.
- Bluetooth Low Energy:Standardized wireless protocols enable seamless transmission of interstitial glucose readings to electronic health record systems without proprietary gateway hardware.
Market Restraints
- Electrochemical Sensor Materials:Platinum and palladium price volatility in sensor electrodes compresses hardware margins for wearable glucose monitors.
- EU MDR Compliance Burden:Clinical evidence requirements for Class IIb device-software combinations extend development cycles by 14-22 months.
- Statutory Insurance Reimbursement Caps:German Social Code SGB V fixes maximum reimbursable amounts for digital diabetes applications regardless of feature differentiation.
Strategic Opportunities
- Bavaria University Hospital Networks:Munich and Berlin academic medical centers seek API-integrated continuous glucose monitoring for research cohorts and precision medicine initiatives.
- AI-Enabled Insulin Dosing:Machine learning algorithms for predictive hypoglycemia alerts await BfArM risk classification guidance, creating first-mover advantages for compliant submissions.
- Pharmacy Distribution Channels:DiGA prescription-to-dispensing workflows enable direct-to-patient fulfillment models bypassing traditional medical device distributor markups.
Industry Challenges
- Data Interoperability Engineering:HL7 FHIR integration with legacy hospital information systems requires specialized health IT talent scarce in German labor markets.
- Cybersecurity Certification:BSI technical guidelines for networked medical devices mandate penetration testing protocols that add 4-6 months to product release schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Digital Diabetes Management Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Apps, Wearable Devices, Software Solutions, Glucometers Delivery Model: On-Premise, Cloud-Based, Hybrid, Subscription-Based End User: Patients, Healthcare Providers, Caregivers, Payers Integration Level: Standalone Solutions, Integrated Systems, API-Enabled, Dashboard Interfaces |
| Companies Covered | Abbott Laboratories, Medtronic, F. Hoffmann-La Roche Ltd., Bayer AG, Dexcom, Inc., Sanofi, Insulet Corporation, Ascensia Diabetes Care Holdings AG, B. Braun Melsungen AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Digital Diabetes Management Market Trends and Innovations
Algorithmic decision support is displacing passive glucose logging across German diabetes care pathways, with software-enabled therapeutic recommendations now qualifying for statutory reimbursement independent of hardware bundling.
Continuous glucose monitoring hardware is bifurcating into hospital-calibrated precision tiers and consumer-grade wellness variants. Specialist diabetes practices in Hamburg and Frankfurt adopt clinical-grade sensors with ±5% MARD accuracy for therapeutic insulin adjustments. This split is compressing addressable markets for mid-accuracy devices while expanding premium positioning for FDA-equivalent performance tiers validated under EU MDR.
BfArM's forthcoming artificial intelligence guidance reclassifies risk categories for algorithm-driven dosing recommendations. Developers must submit prospective clinical trials for adaptive insulin delivery systems previously cleared as decision-support tools. Endocrinology practices in Baden-Württemberg delay procurement commitments pending clarity on whether machine learning features trigger Class III medical device obligations.
Hospital outpatient clinics unbundle glucose data management from device procurement, subscribing to cloud analytics platforms independent of sensor manufacturer. Procurement teams in North Rhine-Westphalia negotiate enterprise software licenses covering multi-vendor device fleets. This purchasing pattern concentrates vendor selection authority within hospital IT departments rather than individual diabetes specialists.
Germany Digital Diabetes Management Market Segmentation
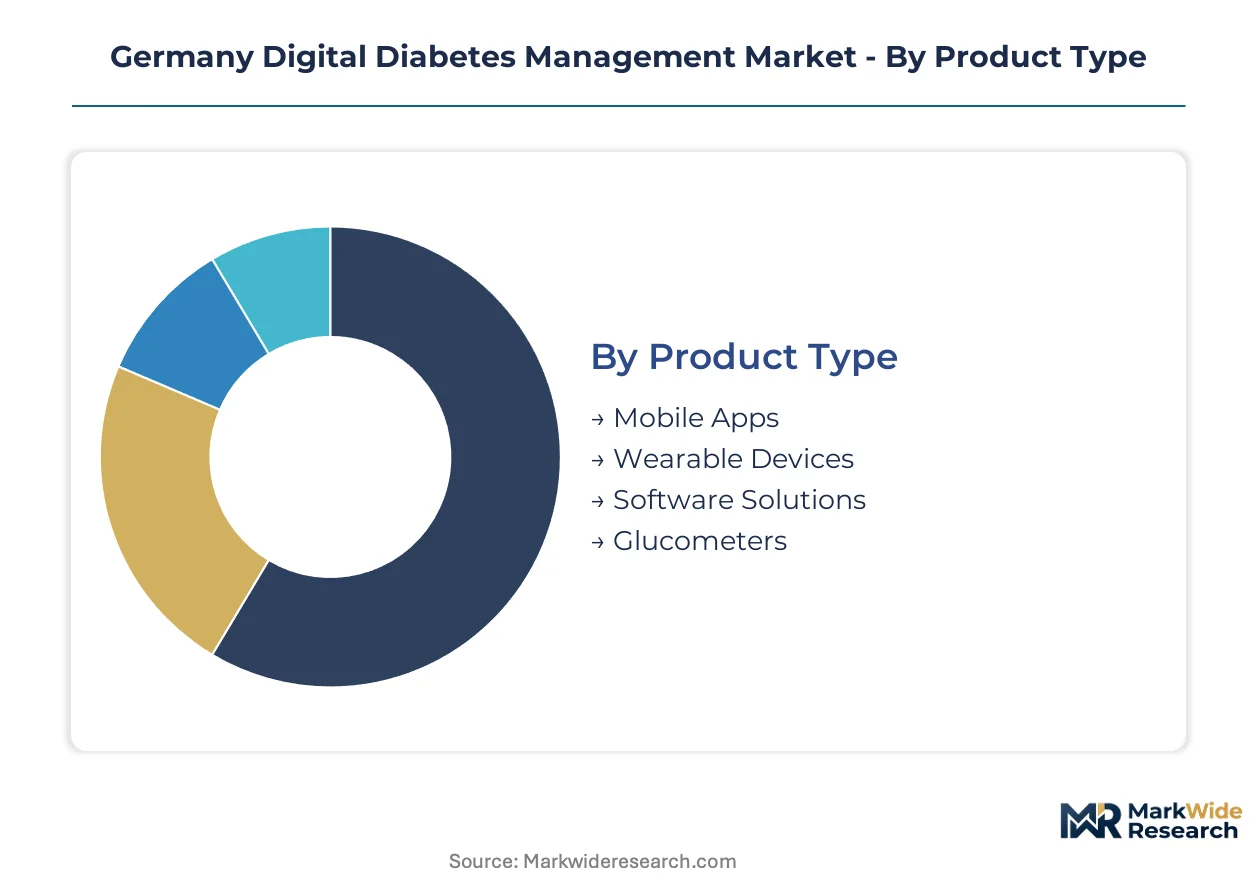
Segmentation in Germany's digital diabetes management market reveals how reimbursement pathways and procurement authority reshape competitive boundaries. BfArM's DiGA fast-track approval stratifies product categories by evidence requirements, while hospital IT departments increasingly control vendor selection across integration tiers.
Product Type:
Wearable devices face intensifying substitution pressure from smartphone-integrated solutions as electrochemical sensor costs fluctuate and software-only DiGA approvals accelerate.
- Mobile Apps:Smartphone-based glucose logging and insulin dosing calculators leverage device cameras for meal carbohydrate estimation. North Rhine-Westphalia's integrated care contracts prioritize DiGA-approved apps for remote patient monitoring in diabetes disease management programs, though BfArM reimbursement caps limit premium pricing.
- Wearable Devices:Electrochemical sensors measuring interstitial glucose at five-minute intervals transmit encrypted readings via Bluetooth Low Energy. Hamburg and Frankfurt specialist practices drive demand for clinical-grade sensors with ±5% MARD accuracy, while consumer wellness variants lose procurement traction.
- Software Solutions:Cloud analytics platforms aggregate multi-vendor glucose data for population health dashboards.
- Glucometers:Traditional fingerstick meters with Bluetooth connectivity bridge legacy patients into digital workflows.
Wearable devices anchor the volume base while mobile apps gain share at the steepest rate.
Delivery Model:
Cost tier differentiation separates enterprise hospital deployments from individual practitioner subscriptions, with cloud infrastructure commanding premium positioning through scalability guarantees.
- Cloud-Based:Scalable infrastructure captures the fastest expansion as German healthcare providers build multi-site diabetes networks. Munich and Berlin university hospitals prioritize cloud analytics for research cohorts requiring centralized data lakes and API access for precision medicine initiatives.
- Subscription-Based:Outcome-linked contracts replace per-seat licensing as German sickness funds demand performance guarantees. Procurement teams in North Rhine-Westphalia negotiate enterprise software licenses covering multi-vendor device fleets, concentrating vendor selection authority within hospital IT departments.
- On-Premise:Local server installations persist in data-sensitive academic medical centers.
- Hybrid:Mixed deployments balance edge computing with cloud backup for continuity assurance.
Cloud-based delivery anchors the volume base while subscription-based pricing climbs the fastest.
End User:
Procurement authority is shifting from individual prescribers to institutional buyers as integrated care contracts consolidate purchasing across hospital networks.
- Healthcare Providers:Hospital outpatient clinics and specialist diabetes practices drive platform adoption through integrated care contracts. Berlin and Munich academic medical centers seek API-integrated continuous glucose monitoring for electronic health record synchronization, creating bundled procurement opportunities.
- Payers:German statutory health insurance funds under SGB V mandate reimbursement for DiGA-approved solutions, fixing maximum reimbursable amounts regardless of feature differentiation and compressing margins for undifferentiated offerings.
- Patients:Direct-to-consumer channels expand through pharmacy DiGA dispensing workflows.
- Caregivers:Family monitoring features gain traction for pediatric and elderly diabetes populations.
Healthcare providers anchor the volume base while payers reshape competitive dynamics fastest through reimbursement policy.
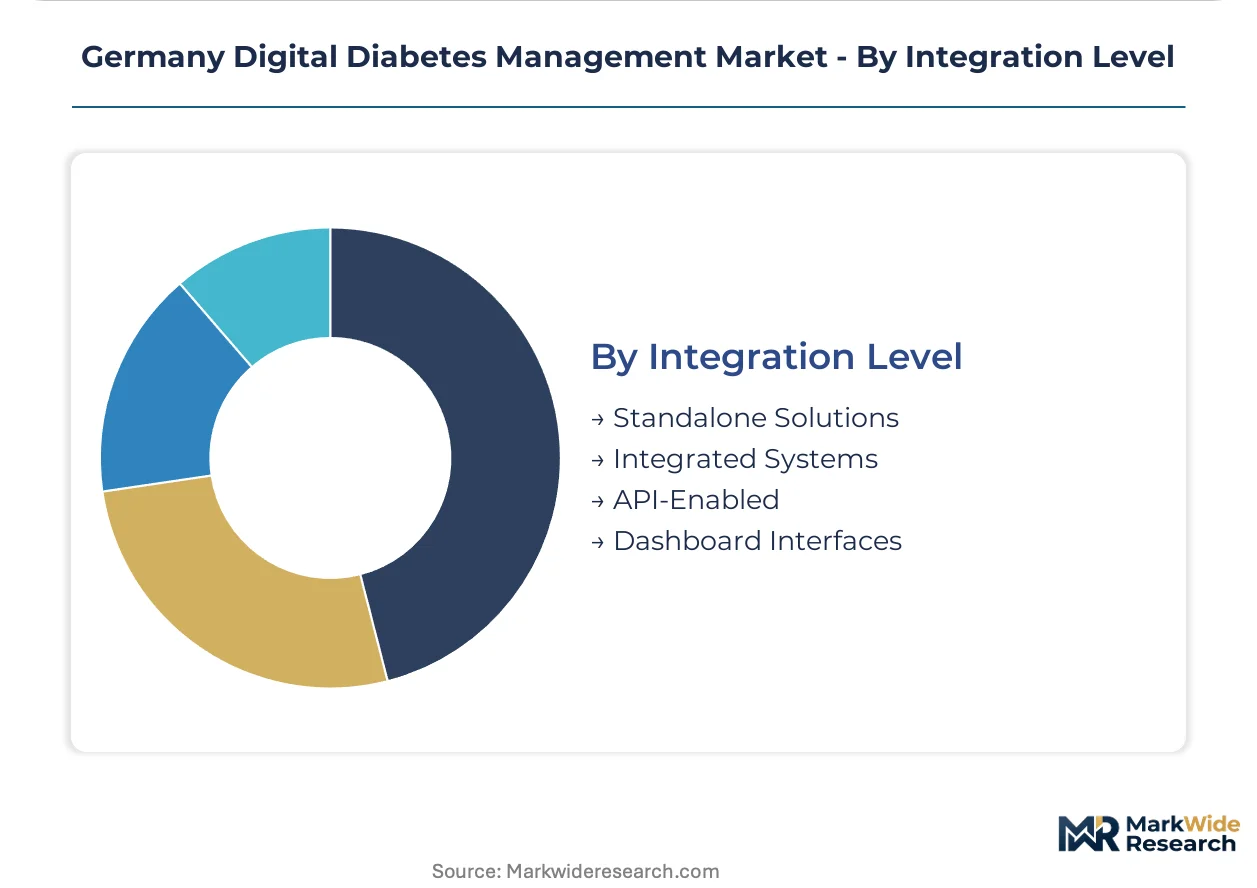
Integration Level:
Application maturity separates workflow-embedded solutions from isolated data capture tools, with HL7 FHIR compliance becoming a threshold requirement for hospital procurement.
- Integrated Systems:Synchronization with clinical workflow platforms commands premium positioning through patient-generated data integration. Baden-Württemberg endocrinology practices delay procurement commitments pending BfArM clarity on whether machine learning features trigger Class III medical device obligations.
- API-Enabled:Real-time continuous glucose monitoring APIs integrate with electronic health record systems deployed by university hospitals. BSI technical guidelines for networked medical devices mandate penetration testing protocols that add 4-6 months to product release schedules for API-connected platforms.
- Standalone Solutions:Single-function applications without EHR connectivity face exclusion from hospital procurement.
- Dashboard Interfaces:Visualization layers aggregate multi-source data for clinical decision support.
Integrated systems anchor the volume base while API-enabled platforms expand most quickly through interoperability mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr metropolitan rail network and Düsseldorf Airport cargo terminals anchor North Rhine-Westphalia's position as Germany's digital diabetes management logistics hub, connecting sensor manufacturing clusters to hospital procurement centers across the Benelux corridor.
North Rhine-Westphalia
Düsseldorf-based integrated care contracts bundle diabetes disease management programs across hospital networks, creating concentrated procurement demand for connected glucose monitoring platforms. The German Social Code SGB V reimbursement mandates under the Digital Healthcare Act accelerate DiGA prescribing workflows in this region. Cologne and Essen academic medical centers pilot API-integrated continuous glucose monitoring for multi-site data aggregation.
Bavaria
Munich university hospitals drive demand for cloud analytics platforms serving precision medicine research cohorts requiring centralized glucose data lakes. BfArM's fast-track DiGA approval pathway compresses commercialization timelines for algorithmic diabetes solutions submitted through Bavaria's regulatory consulting cluster. The Munich-Berlin corridor concentrates health IT talent for HL7 FHIR integration projects.
Baden-Württemberg
Stuttgart-area endocrinology practices delay procurement commitments pending BfArM guidance on AI-enabled insulin dosing risk classifications. The EU Medical Device Regulation imposes clinical evidence requirements that extend product development cycles for Class IIb device-software combinations in this manufacturing-intensive state. Mannheim hospital networks negotiate enterprise software licenses covering multi-vendor glucose sensor fleets.
Berlin-Brandenburg
Charité Universitätsmedizin Berlin anchors demand for real-time continuous glucose monitoring APIs synchronized with electronic health record systems. BSI technical guidelines for networked medical devices mandate penetration testing protocols that add certification delays for startups in the Adlershof technology park. Potsdam health IT clusters specialize in cybersecurity engineering for Bluetooth Low Energy medical data transmission.
Hamburg
Specialist diabetes practices in Hamburg's private healthcare sector drive demand for clinical-grade sensors with ±5% MARD accuracy for therapeutic insulin adjustments. The city's port infrastructure facilitates import logistics for electrochemical sensor materials facing platinum and palladium price volatility. Hamburg's health insurance fund headquarters influence national reimbursement negotiations for digital diabetes applications.
Germany Digital Diabetes Management Market Competitive Landscape
Concentration sits with diversified medical technology conglomerates and specialized continuous glucose monitoring developers. The vendor base stratifies across three tiers: established diagnostic platforms with hospital procurement relationships, insulin delivery specialists with closed-loop algorithm portfolios, and emerging software-only DiGA applicants. Strategic moves center on DiGA fast-track submissions restructuring clinical evidence packages, and cloud infrastructure partnerships enabling multi-site hospital network deployments.
Among diversified health technology conglomerates, Abbott Laboratories and Medtronic occupy positions anchoring hospital-to-home continuity and closed-loop insulin delivery respectively. Dexcom, Inc. represents the specialized continuous glucose monitoring archetype, with its API-first positioning aligned to university hospital interoperability mandates. These three companies exemplify the competitive vectors shaping procurement authority shifts from individual prescribers to institutional IT departments.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Medtronic |
| F. Hoffmann-La Roche Ltd. |
| Bayer AG |
| Dexcom, Inc. |
| Sanofi |
| Insulet Corporation |
| Ascensia Diabetes Care Holdings AG |
| B. Braun Melsungen AG |
| Others |
Pricing and Supply Chain Analysis
Ninety-day DiGA approval timelines compress inventory cycles for algorithmic diabetes software developers, concentrating pricing power with cloud infrastructure providers while squeezing hardware margins for electrochemical sensor manufacturers tethered to platinum and palladium spot markets.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates integrated hospital systems with API-enabled EHR synchronization from standalone glucose logging applications and basic wearable sensors. Certification grade under EU MDR and volume scale through North Rhine-Westphalia's integrated care contracts drive price differentiation, with BfArM DiGA approval commanding substantial premiums over non-reimbursed alternatives. Pricing pressure stems from SGB V statutory reimbursement caps that fix maximum reimbursable amounts regardless of feature sophistication. Hospital IT departments demonstrate lowest price sensitivity due to bundled procurement authority, while individual specialist practices face acute margin compression.
Supply Chain Analysis
Platinum group metal sourcing from South Africa and Russia anchors electrochemical sensor electrode production, creating single-source vulnerability for wearable glucose monitor manufacturers. Component dependencies extend to Bluetooth Low Energy chipsets from Taiwan, medical-grade polymers from Germany, and cloud server capacity from Irish and Dutch hyperscale facilities. Tariff exposure on Chinese-sourced sensor substrates intensifies supply chain risk as EU MDR compliance extends development cycles. Distribution runs through pharmacy DiGA dispensing workflows and hospital procurement committees rather than traditional medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized health IT talent for HL7 FHIR integration represents the binding constraint reshaping competitive outcomes, with hospitals unable to deploy multi-vendor glucose data platforms without scarce interoperability engineering capabilities.
For Market Incumbents: Shield installed base relationships in North Rhine-Westphalia's integrated care networks by accelerating backward integration into cloud analytics infrastructure, neutralizing substitution threats from software-only DiGA entrants. Prioritize BSI cybersecurity certification investment to close the 4-6 month penetration testing gap blocking API-connected platform releases. For New Entrants and Emerging Players: Lead with AI-enabled insulin dosing algorithms awaiting BfArM risk classification guidance, capturing first-mover positioning in Baden-Württemberg's delayed procurement pipeline. Bavaria's university hospital precision medicine initiatives offer the most penetrable geography for API-first continuous glucose monitoring platforms. Pursue direct pharmacy distribution partnerships to bypass incumbent medical device distributor markups. For Investors and Strategic Acquirers: Long-term, this sits as a reimbursement-regulation play because DiGA fast-track approval velocity and SGB V coverage expansion determine addressable market expansion more than technology differentiation. Target acquisition archetypes combining clinical-grade sensor hardware with cloud-native software stacks. Monitor BfArM artificial intelligence guidance publication as the critical inflection signal for algorithm-driven dosing risk reclassification.| Strategic Initiative | Industry Significance |
|---|---|
| DiGA Fast-Track Submission | BfArM's 90-day approval pathway accelerates statutory reimbursement access for algorithmic diabetes solutions. |
| HL7 FHIR Integration Development | Hospital IT departments mandate workflow-embedded glucose data synchronization for procurement eligibility. |
| Cloud Infrastructure Partnership | Multi-site diabetes networks in North Rhine-Westphalia require scalable analytics platforms for population health dashboards. |
| BSI Cybersecurity Certification | Networked medical device penetration testing protocols add mandatory lead times to product release schedules. |
| Pharmacy Distribution Channel | Prescription-to-dispensing workflows enable direct-to-patient fulfillment bypassing traditional distributor networks. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital purchasing committees, biomedical engineers, GPO contracts managers, and regulatory affairs specialists at BfArM and notified body organizations. Secondary validation drew from hospital procurement databases, GPO contracts, CMS Medicare data analogues, and EU MDR technical documentation filings. Bottom-up device shipment and software subscription data triangulated against top-down healthcare expenditure flows across the German statutory insurance system.
Across the analysis window, the forecasting framework modeled product type segmentation by reimbursement pathway, delivery model by scalability tier, end user by procurement authority concentration, and integration level by interoperability complexity. CAGRs derived from fitted growth curves applied to DiGA approval velocity and integrated care contract expansion trajectories. Algorithmic decision support penetration rates and cloud infrastructure adoption curves served as diabetes-specific forecast inputs.
Underlying assumptions cover BfArM regulatory guidance timelines and SGB V reimbursement stability, with deviation risk concentrated in EU MDR clinical evidence requirement evolution and electrochemical sensor material price volatility. Practitioners should keep alternative scenarios live as artificial intelligence risk classification guidance and statutory insurance coverage expansion negotiations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
APAC Insulin Infusion Pumps Market
Diabetes Care
Global Needle Free Diabetes Care Market
Diabetes Care
Global Smart Insulin Pens Market
Diabetes Care
Gestational Diabetes Market
Diabetes Care
Japan Insulin Drugs and Delivery Devices Market
Diabetes Care
North America Diabetes Care Devices Market
Diabetes Care
Continuous Glucose Monitoring in Philippines Market
Diabetes Care
Malaysia Diabetes Care Devices Market
Diabetes Care
France Continuous Glucose Monitoring Market
Diabetes Care
Type 2 Diabetes Mellitus Treatment Market
Diabetes Care
New Zealand Insulin Drugs and Devices Market
Diabetes Care
Global Diabetic Retinopathy Market
Diabetes Care
Global Diabetic Ulcers Treatment Market
Diabetes Care
Philippines Oral Anti-Diabetic Drug Market
Diabetes Care
France Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Self-Monitoring Blood Glucose Strips Market